
 India Satellite Connectivity Market | 2026-2036
India Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
India Satellite Connectivity Market Insights
Platform licensing revenue is fragmenting across low-earth orbit gateway operators and traditional geostationary incumbents. Bharti Airtel leverages its terrestrial fiber backbone to anchor hybrid satellite-terrestrial service bundles. OneWeb competes through dedicated polar gateway infrastructure deployed near the Arctic Circle. Nelco specializes in enterprise VSAT networks for oil and gas exploration clients.
India Satellite Connectivity encompasses radio frequency links between ground stations and orbiting spacecraft operating across C-band, Ku-band, Ka-band, and emerging Q/V-band spectra, with link budgets engineered for rain fade margins exceeding six decibels in tropical latitudes. Its primary commercial purpose is extending broadband coverage to regions where terrestrial fiber deployment remains economically unviable. LEO constellations represent the fastest-expanding technology segment as latency-sensitive enterprise applications displace legacy geostationary services. Government end users concentrate procurement around sovereign bandwidth requirements for border surveillance and disaster response coordination.
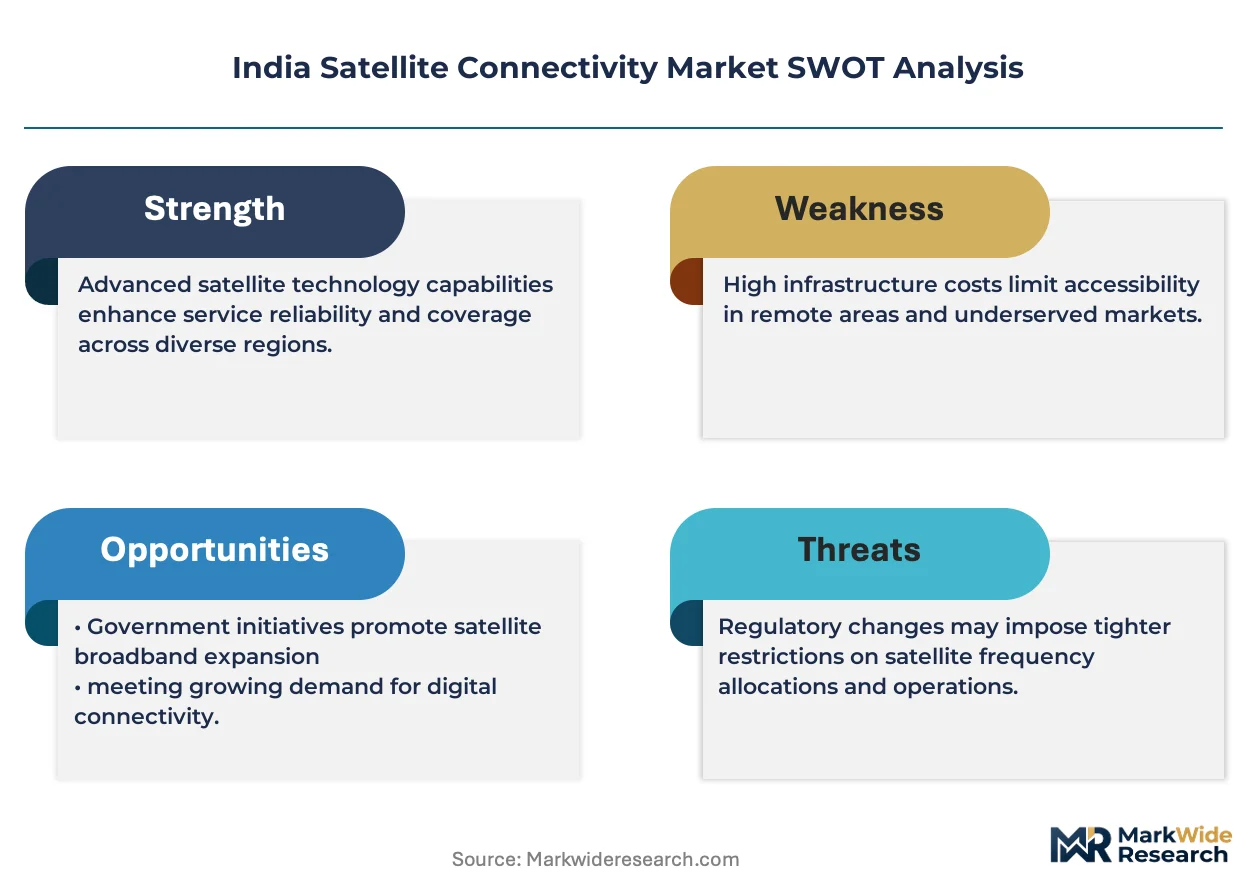
IN-SPACe, the Department of Telecommunications, and TRAI collectively govern spectrum allocation, landing rights, and foreign direct investment thresholds for satellite service providers. BIS technical standards for ground equipment interoperability create compliance barriers that favor domestic manufacturing partnerships. Stakeholders must monitor how the Telecommunications Act's satellite-specific licensing categories redefine competitive boundaries between Indian-owned and foreign-operated constellations.
Market Dynamics
LEO constellation deployment is compressing latency benchmarks and forcing incumbents to re-engineer ground infrastructure around hybrid orbital architectures. This orbital shift redistributes value from satellite manufacturing toward gateway real estate and spectrum coordination capabilities.
Growth Catalysts
- Defense bandwidth procurement:Border surveillance and disaster response coordination drive sovereign spectrum allocation through the Department of Telecommunications.
- GIFT City ground infrastructure:Gujarat's satellite gateway cluster attracts landing rights applications from multiple constellation operators seeking Indian market access.
- IN-SPACe licensing reforms:Streamlined foreign direct investment thresholds accelerate constellation service authorization timelines for non-Indian operators.
Market Restraints
- BIS interoperability mandates:Domestic manufacturing partnership requirements for ground equipment create compliance cost barriers for foreign gateway suppliers.
- Tropical rain fade engineering:Six-decibel link margin specifications for C-band and Ku-band installations inflate terminal hardware costs versus temperate-climate deployments.
- Geostationary spectrum legacy:Incumbent orbital slot holdings constrain Ka-band availability for LEO operators in high-demand Indian Ocean coverage arcs.
Strategic Opportunities
- Enterprise VSAT oil and gas:Offshore exploration platforms in the Arabian Sea and Bay of Bengal require dedicated maritime connectivity beyond terrestrial cellular reach.
- Telecommunications Act licensing categories:New satellite-specific service authorizations create definitional clarity for foreign-constellation versus Indian-owned operator competitive boundaries.
- Q/V-band spectrum pioneering:Next-generation frequency allocations enable terabit-scale throughput for data center interconnect applications in Hyderabad and Bengaluru.
Industry Challenges
- Gateway site acquisition:Clear-horizon real estate near population centers faces zoning conflicts with urban expansion and aviation approach corridors.
- RF engineer scarcity:Specialized talent for link budget optimization and interference coordination commands premium compensation in Bengaluru's aerospace labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Satellite Connectivity Market |
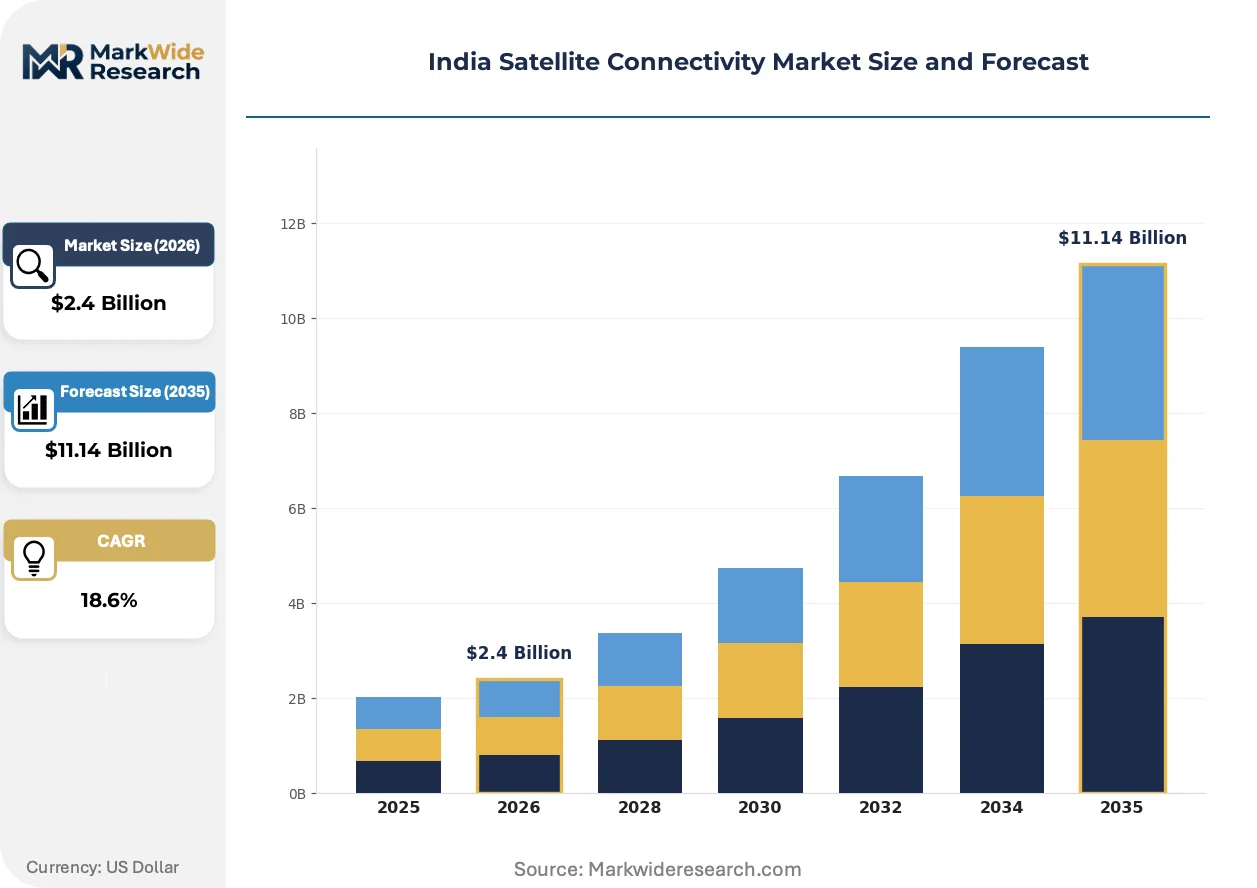
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.14 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Geostationary, LEO, MEO, HTS Application: Broadband, Broadcasting, Military, IoT End User: Telecom Operators, Government, Enterprises, Maritime Service Type: Internet Access, Emergency Services, Data Transmission, Remote Sensing |
| Companies Covered | Reliance Jio Infocomm, Bharti Airtel, Antrix Corporation, SES, Intelsat, Viasat, OneWeb, Nelco, Tata Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Satellite Connectivity Market Trends and Innovations
Software-defined payload architectures are decoupling hardware refresh cycles from service capability upgrades. This virtualization layer enables constellation operators to reconfigure coverage and capacity through orbital software pushes rather than spacecraft replacement.
Digital transparent processors aboard next-generation satellites are virtualizing traditional bent-pipe transponder economics. Indian defense procurement offices are piloting these payloads for dynamic bandwidth allocation across theater operations. The technology is virtualizing the historical trade-off between coverage footprint and power concentration.
TRAI's consultation on satellite-based broadband service authorization frameworks is redefining landing rights enforcement mechanisms. Foreign constellation operators must now demonstrate domestic gateway presence and spectrum coordination protocols before market entry approval. The policy shift most affects LEO operators seeking to bypass traditional geostationary partnership structures.
Enterprise buyers in Gujarat's petrochemical corridor are consolidating vendor relationships around integrated satellite-terrestrial managed service contracts. Long-term bandwidth commitments with guaranteed latency service-level agreements are displacing transactional megahertz-month purchasing. This consolidation pattern concentrates procurement leverage with integrated operators possessing both orbital assets and terrestrial fiber backhaul.
India Satellite Connectivity Market Segmentation
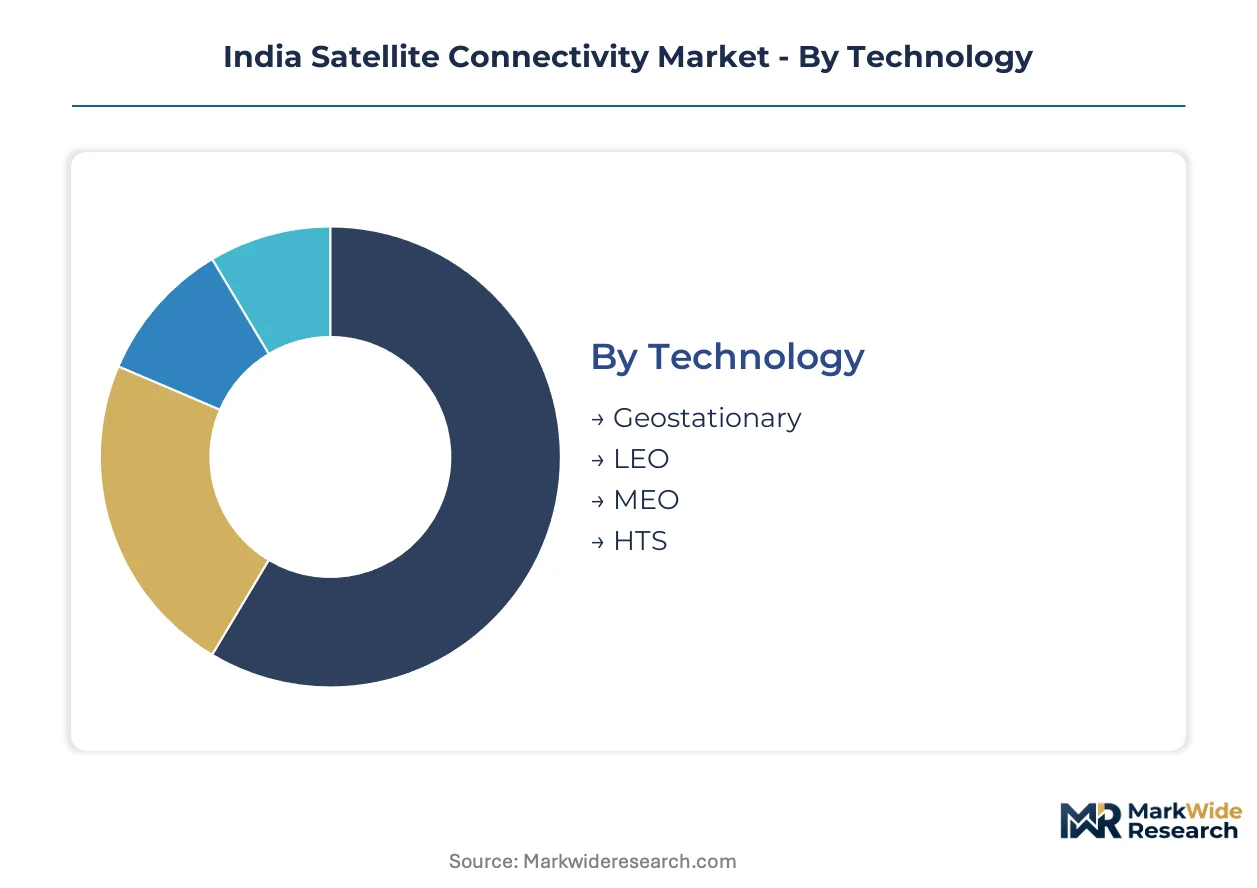
Segmentation reveals how orbital economics, spectrum allocation, and procurement authority reshape competitive boundaries across India's satellite connectivity landscape. Each dimension exposes distinct margin structures and regulatory exposure profiles for service providers.
Technology:
The use-case spectrum spans latency-tolerant broadcasting through millisecond-critical financial trading applications.
- LEO:Low-earth orbit constellations operate 500-2,000 kilometers altitude with 20-40 millisecond round-trip latency. Gujarat's GIFT City ground cluster anchors gateway infrastructure for polar-orbiting systems serving algorithmic trading platforms in Mumbai's financial district. Latency benchmarks compress competitive positioning against fiber routes through submarine cable chokepoints.
- HTS:High-throughput satellites deploy frequency reuse across multiple spot beams, concentrating power density for bandwidth-intensive applications. Ka-band HTS capacity targets enterprise VSAT networks in Rajasthan's mining corridors where terrestrial backhaul remains uneconomical. Spot beam economics enable per-megahertz pricing that undercuts traditional wide-beam transponder leases.
- Geostationary:Orbital slot holdings at 35,786 kilometers altitude leverage legacy C-band and Ku-band spectrum for broadcasting distribution networks.
- MEO:Medium-earth orbit systems bridge latency and coverage trade-offs for maritime connectivity in the Arabian Sea and Bay of Bengal.
The dominant share belongs to Geostationary, while LEO is closing the gap fastest.
Application:
Cost tier differentiation separates sovereign procurement from commercial bandwidth arbitrage.
- Broadband:Consumer and enterprise internet access extends connectivity to India's 600,000+ villages beyond fiber reach. TRAI's satellite-based broadband consultation reshapes landing rights enforcement for foreign constellation market entry. Rural distribution partnerships with telecom operators concentrate subscriber acquisition costs.
- Military:Defense bandwidth procurement operates through Department of Telecommunications sovereign spectrum allocation for border surveillance and disaster response. Digital transparent processors enable dynamic bandwidth reallocation across theater operations without spacecraft replacement. Procurement timelines extend 18-36 months with stringent BIS interoperability mandates.
- Broadcasting:Direct-to-home television distribution leverages Ku-band capacity for regional language content aggregation.
- IoT:Narrowband connectivity serves agricultural sensor networks and asset tracking across India's logistics corridors.
Military commands premium pricing tiers, whereas Broadband is expanding addressable market volume most aggressively.
End User:
Customer type determines contract structure, with sovereign procurement favoring long-term commitments against enterprise spot-market flexibility.
- Government:Central and state agencies procure dedicated bandwidth for disaster response coordination and rural telemedicine networks. IN-SPACe licensing reforms streamline foreign direct investment thresholds for constellation operators serving public sector requirements. Procurement concentrates through Department of Telecommunications spectrum coordination.
- Telecom Operators:Bharti Airtel and terrestrial carriers bundle satellite backhaul for last-mile connectivity in Northeastern states and island territories. Hybrid satellite-terrestrial service packages leverage existing fiber backbone investments for margin protection. Interconnection agreements with LEO gateway operators reshape wholesale pricing structures.
- Enterprises:Oil and gas exploration platforms in offshore blocks require dedicated maritime VSAT beyond cellular reach.
- Maritime:Shipping corridors through Indian Ocean coverage arcs demand continuous connectivity for vessel operations and crew welfare.
Government holds the largest committed bandwidth contracts, though Enterprises are diversifying vendor relationships fastest.
Service Type:
Margin structure varies with service criticality, from commodity internet access through specialized remote sensing analytics.
- Internet Access:Consumer and SME broadband subscriptions generate recurring revenue with high customer acquisition costs in rural markets. GIFT City gateway infrastructure enables competitive latency benchmarks for financial services clients. Pricing pressure from LEO constellation overcapacity threatens incumbent geostationary returns.
- Emergency Services:Disaster response coordination requires pre-positioned bandwidth reserves with guaranteed availability during terrestrial network failures. Department of Telecommunications mandates priority spectrum access for national emergency communication networks. Contract structures emphasize availability service-level agreements over throughput guarantees.
- Data Transmission:Enterprise backhaul and cloud interconnect services target data center corridors in Hyderabad and Bengaluru.
- Remote Sensing:Earth observation data serves agricultural monitoring, urban planning, and environmental compliance applications.
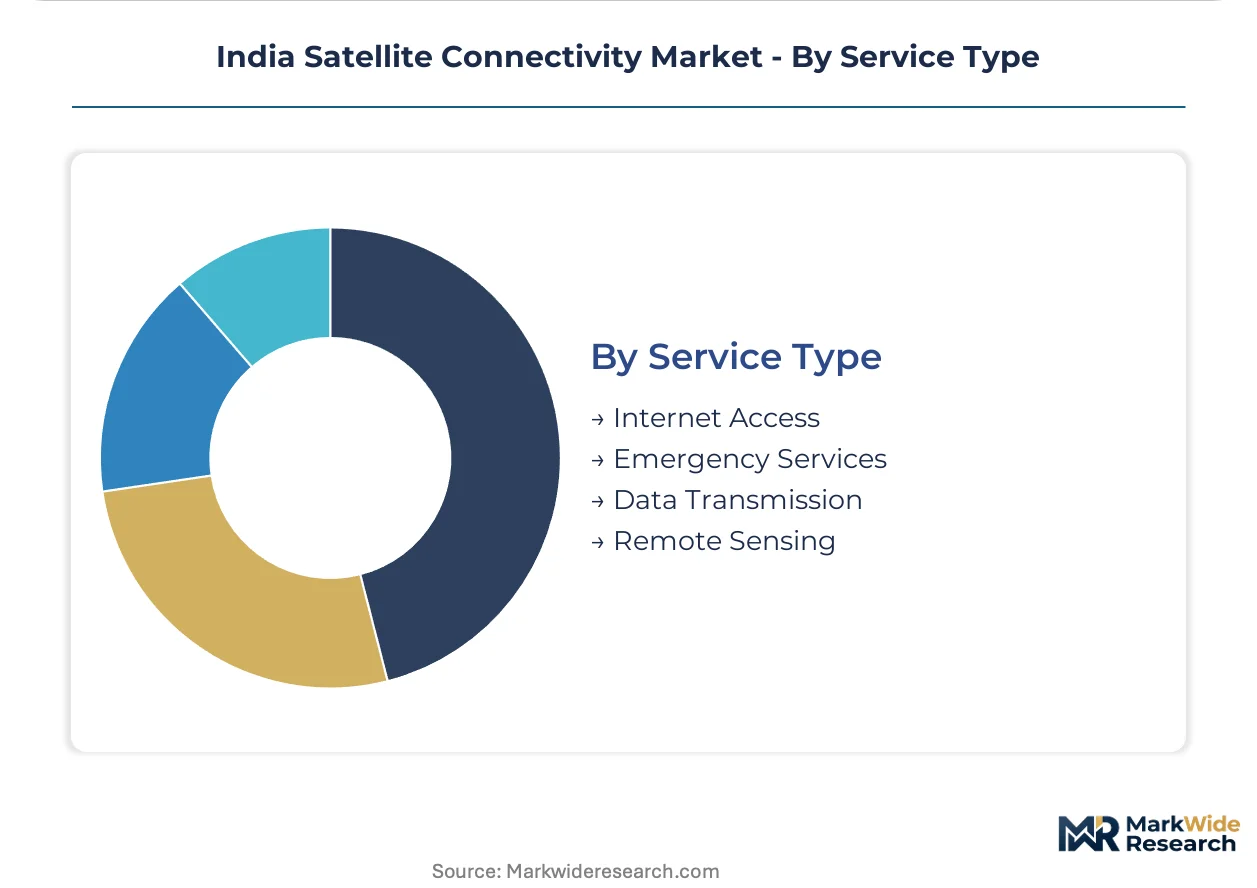
Internet Access captures the broadest subscriber base, while Emergency Services commands the highest per-megahertz premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Gujarat's financial corridor exhibit low price elasticity for latency-guaranteed services, while rural broadband subscribers in eastern states demand aggressive per-gigabyte discounts that compress reseller margins.
Gujarat
GIFT City's satellite gateway cluster anchors polar-orbiting LEO infrastructure for Mumbai's algorithmic trading platforms. TRAI's landing rights enforcement requires domestic gateway presence for foreign constellation market entry. Gandhinagar's aerospace engineering institutes feed RF specialist talent into ground station operations.
Maharashtra
Mumbai's financial services sector procures dedicated low-latency circuits for cross-exchange arbitrage systems. The Department of Telecommunications coordinates sovereign spectrum allocation for defense bandwidth requirements. Pune's defense electronics corridor houses BIS-certified ground equipment manufacturing partnerships.
Karnataka
Bengaluru's data center operators pilot Q/V-band interconnect for terabit-scale cloud backhaul. IN-SPACe licensing reforms streamline foreign direct investment thresholds for constellation operators. The city's aerospace labor market commands premium compensation for interference coordination specialists.
Tamil Nadu
Chennai's port infrastructure drives maritime VSAT demand for crew welfare and vessel operations. The Telecommunications Act's satellite-specific categories clarify competitive boundaries for Indian-owned versus foreign-operated systems. Sriperumbudur's electronics manufacturing zone produces BIS-compliant terminal hardware.
Telangana
Hyderabad's pharmaceutical and IT corridors require hybrid satellite-terrestrial disaster recovery networks. CDSCO's telemedicine mandates for rural clinical trials create sovereign bandwidth procurement channels. The city's satellite ground station real estate faces zoning conflicts with aviation approach corridors.
India Satellite Connectivity Market Competitive Landscape
Integrated telecom operators and specialized satellite service providers split the market between hybrid bundle dominance and niche vertical expertise. The structure concentrates around three archetypes: terrestrial carriers leveraging fiber backbone for satellite-terrestrial convergence, dedicated constellation operators with polar gateway assets, and enterprise VSAT specialists serving extractive industries. Competitive moves center on strategic partnerships for ground infrastructure sharing and portfolio diversification into managed service contracts with guaranteed latency service-level agreements.
Among India-based integrated carriers, Bharti Airtel and Reliance Jio Infocomm represent the terrestrial-fiber-anchored archetype, while Nelco occupies a position exemplifying enterprise VSAT specialization for maritime and energy verticals.
| Leading Market Players |
|---|
| Reliance Jio Infocomm |
| Bharti Airtel |
| Antrix Corporation |
| SES |
| Intelsat |
| Viasat |
| OneWeb |
| Nelco |
| Tata Communications |
| Others |
Pricing and Supply Chain Analysis
Gateway infrastructure overcapacity in Gujarat's GIFT City cluster compresses landing rights premiums while amplifying price competition among constellation operators seeking Indian market access. This utilization dynamic simultaneously pressures ground equipment suppliers to absorb BIS compliance costs and forces service providers toward long-term managed service contracts with guaranteed latency service-level agreements.
Pricing Analysis
Managed service contract renewals and extended bandwidth commitments generate lifetime value that exceeds initial terminal hardware sales by substantial multiples. Pricing stratifies across premium latency-guaranteed financial services tiers, standard enterprise VSAT packages, and economy rural broadband subscriptions. Cost compression in economy tiers intensifies because LEO constellation overcapacity enables aggressive per-gigabyte discounting. Rural subscribers exhibit highest price sensitivity, while Mumbai algorithmic trading platforms demonstrate near-zero elasticity for sub-30 millisecond circuit guarantees.
Supply Chain Analysis
Export control restrictions on RF amplifier components and phased array antenna technologies limit flows from US and European suppliers to Indian ground station manufacturers. Component sourcing draws from Taiwan for semiconductor payloads, South Korea for advanced antenna systems, and domestic Bengaluru facilities for BIS-certified terminal assembly. Single-source vulnerability concentrates in gallium nitride amplifier supply chains. Distribution runs through authorized system integrators possessing IN-SPACe licensing credentials and established relationships with Department of Telecommunications procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India Satellite Connectivity operates at a platform-economics inflection where interoperability mandates and gateway infrastructure sharing agreements reshape competitive boundaries between integrated telecom operators and specialized constellation providers.
For Market Incumbents: Insulate core enterprise relationships through exclusive terrestrial fiber backhaul integration that foreign LEO operators cannot replicate without Bharti Airtel-scale infrastructure investments. Deepen backward integration into BIS-certified terminal manufacturing through partnerships with Sriperumbudur electronics zones to neutralize compliance cost disadvantages against domestic competitors. Priority defensive lever rests on locking long-term spectrum coordination agreements with Department of Telecommunications before Telecommunications Act licensing categories fully mature. For New Entrants and Emerging Players: Establish a beachhead in maritime VSAT services for Arabian Sea oil exploration platforms where Nelco's incumbent position remains vulnerable to specialized low-latency offerings. Target Tamil Nadu port infrastructure and Telangana pharmaceutical corridor disaster recovery networks as white-space geographies with concentrated procurement authority and limited incumbent penetration. Go-to-market angle centers on guaranteed availability service-level agreements for emergency services bandwidth that legacy geostationary operators cannot match with bent-pipe transponder economics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated operators possessing both orbital capacity rights and terrestrial fiber backbone assets that enable hybrid service bundling. Long-term viability over the next decade hinges on spectrum portfolio depth and landing rights exclusivity rather than spacecraft manufacturing scale. Acquisition target archetype emphasizes gateway real estate holders in GIFT City with established IN-SPACe authorizations and Department of Telecommunications relationships. Signal to watch is TRAI's final satellite-based broadband authorization framework, which will clarify competitive boundaries between Indian-owned and foreign-operated constellations.| Strategic Initiative | Industry Significance |
|---|---|
| Gateway Infrastructure Sharing Agreement | Reduces capital intensity for LEO market entry while satisfying TRAI domestic presence mandates. |
| BIS Certification Investment | Unlocks defense procurement channels and creates compliance barriers against unqualified foreign suppliers. |
| Terrestrial Fiber Backhaul Integration | Enables hybrid latency guarantees that pure-satellite competitors cannot offer Mumbai financial clients. |
| Q/V-Band Spectrum Pioneering | Positions operators for terabit-scale data center interconnect demand from Hyderabad and Bengaluru cloud operators. |
| Managed Service Contract Consolidation | Captures long-term enterprise relationships with guaranteed service-level agreements displacing transactional purchasing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with constellation operators, gateway infrastructure providers, and Department of Telecommunications spectrum coordination officials, alongside secondary validation through TRAI consultation papers, IN-SPACe licensing records, and BIS technical standard disclosures. Primary stakeholders included ground station engineering directors, defense procurement officers, enterprise VSAT network managers, and satellite payload procurement leads at integrated telecom operators. Secondary sources encompassed spectrum allocation databases, foreign direct investment threshold notifications, customs records for ground equipment imports, and aerospace labor market compensation surveys. Bottom-up terminal deployment estimates and top-down addressable market sizing underwent cross-triangulation against disclosed gateway capacity figures.
Forecast inputs considered orbital slot holdings, LEO constellation deployment schedules, and spectrum coordination timelines across the projection horizon. Segmentation dimensions modeled include orbital altitude tier, application bandwidth requirement, end-user procurement authority, and service type criticality. CAGRs derived from compound growth trajectory analysis applied to disclosed gateway infrastructure investments and sovereign bandwidth procurement commitments. Industry-specific forecast inputs incorporated rain fade engineering specifications for tropical latitudes and Telecommunications Act licensing category implementation pace.
Sensitivities concentrate around IN-SPACe regulatory implementation pace, LEO constellation bankruptcy or consolidation events, and defense budget reallocation patterns. Forecasts reflect documented assumptions regarding spectrum availability and foreign direct investment threshold stability. Material shifts in TRAI satellite-based broadband authorization final rules or Department of Telecommunications sovereign spectrum reallocation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
South Korea Satellite Communication Market
Satellite
UAE Satellite Communication Market
Satellite
UK Satellite Connectivity Market
Satellite
Satellite Sensor Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Satellite Amplifier Market
Satellite
North America Satellite Launch Vehicle Market
Satellite
Satellite Connectivity Market
Satellite
North America Satellite Manufacturing Market
Satellite
Satellite Broadband Market
Satellite
Satellite Backhaul Market
Satellite
Global Dish Antennas Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
LEO and GEO Satellite Market
Satellite
Asia-Pacific Remote Sensing Satellites Market