
 LEO and GEO Satellite Market | 2026-2036
LEO and GEO Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
LEO and GEO Satellite Market Foresight
Satellite service distribution through legacy geostationary capacity brokers is rewriting as direct-to-device operators and cloud-integrated ground segment providers capture end-user relationships. SpaceX leverages its Starship launch cadence and Starlink subscriber base to sustain vertical control from manufacturing to consumer billing. Lockheed Martin Corporation anchors classified government demand through hardened GEO payloads and protected tactical waveform development. Airbus Defence and Space competes across European institutional programs and export markets with dual-use Earth observation platforms.
LEO and GEO satellites are spacecraft positioned in low Earth orbit or geostationary orbit, distinguished by altitude—LEO typically operates below 2,000 kilometers with orbital periods under 128 minutes, while GEO maintains fixed positions at 35,786 kilometers with zero relative ground track motion—serving functions from broadband relay to persistent weather surveillance. Satellite Type segments show LEO constellations capturing the bulk of new capital deployment as megaconstellation architectures drive manufacturing scale, while GEO retains premium pricing for broadcast and government applications requiring stationary coverage footprints. End User demand tilts toward Commercial and Military segments, where private equity-backed constellation ventures and classified resilient-space programs are expanding procurement bandwidth beyond traditional government channels.
The FCC regulates spectrum allocation and orbital debris mitigation for U.S.-registered operators, while the EU Space Programme and ESA framework shape European procurement through the IRIS² secure connectivity constellation and Copernicus expansion. China's MIIT and GB standards govern domestic satellite manufacturing and launch licensing, constraining foreign participation in its rapidly growing Beidou and Guowang ecosystem. Stakeholders must monitor evolving debris-remediation mandates and spectrum reallocation proceedings that could alter constellation economics and market access conditions.
Market Dynamics
Starship's launch cost compression is collapsing the economics of megaconstellation deployment, forcing legacy GEO operators to defend stationary-orbit premiums through hardened government payloads while LEO broadband scales toward direct-to-device ubiquity.
Growth Catalysts
- Streamlined FCC Licensing:The FCC's accelerated approval timelines for non-geostationary orbit systems compress deployment schedules for constellation operators seeking rapid spectrum access.
- NATO Secure Communications Procurement:Defense agencies across member states are expanding classified satellite bandwidth contracts, anchoring demand for protected tactical waveforms and resilient space architectures.
- Cloud-Integrated Ground Segments:Ground station virtualization is digitizing satellite service delivery, enabling direct relationships between constellation operators and end-users without legacy capacity broker intermediation.
Market Restraints
- Rare Earth Magnet Supply Concentration:Permanent magnet dependencies for electric propulsion systems concentrate in Asian processing corridors, exposing constellation manufacturers to input volatility and geopolitical disruption.
- Orbital Debris Mitigation Mandates:FCC and ESA post-mission disposal requirements impose structural cost burdens on small satellite operators with limited propulsion budgets.
- Optical Inter-Satellite Link Complexity:Laser crosslink thermal management and pointing-acquisition-tracking precision create technical barriers for second-tier constellation architects.
Strategic Opportunities
- EU IRIS² Secure Connectivity Constellation:The European Union's sovereign broadband infrastructure program creates procurement white space for dual-use platforms combining commercial and government service models.
- Direct-to-Device Integration:Unmodified smartphone connectivity via LEO constellations opens addressable markets in remote maritime, aviation, and emergency response verticals previously unreachable by terrestrial infrastructure.
- India's SpaceCom Policy Liberalization:The Indian Space Research Organisation's phased private sector participation reforms enable foreign constellation operators to establish gateway earth stations and spectrum partnerships.
Industry Challenges
- Orbital Mechanics Talent Scarcity:Constellation design and station-keeping optimization require specialized astrodynamics expertise that outpaces university pipeline output.
- ITU Coordination Timeline Compression:International Telecommunication Union spectrum filing and coordination procedures create procedural bottlenecks that delay commercial service activation.
- Legacy GEO Integration Friction:Hybrid networks combining geostationary and low Earth orbit assets face waveform interoperability and handover complexity that degrades user experience during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LEO and GEO Satellite Market |
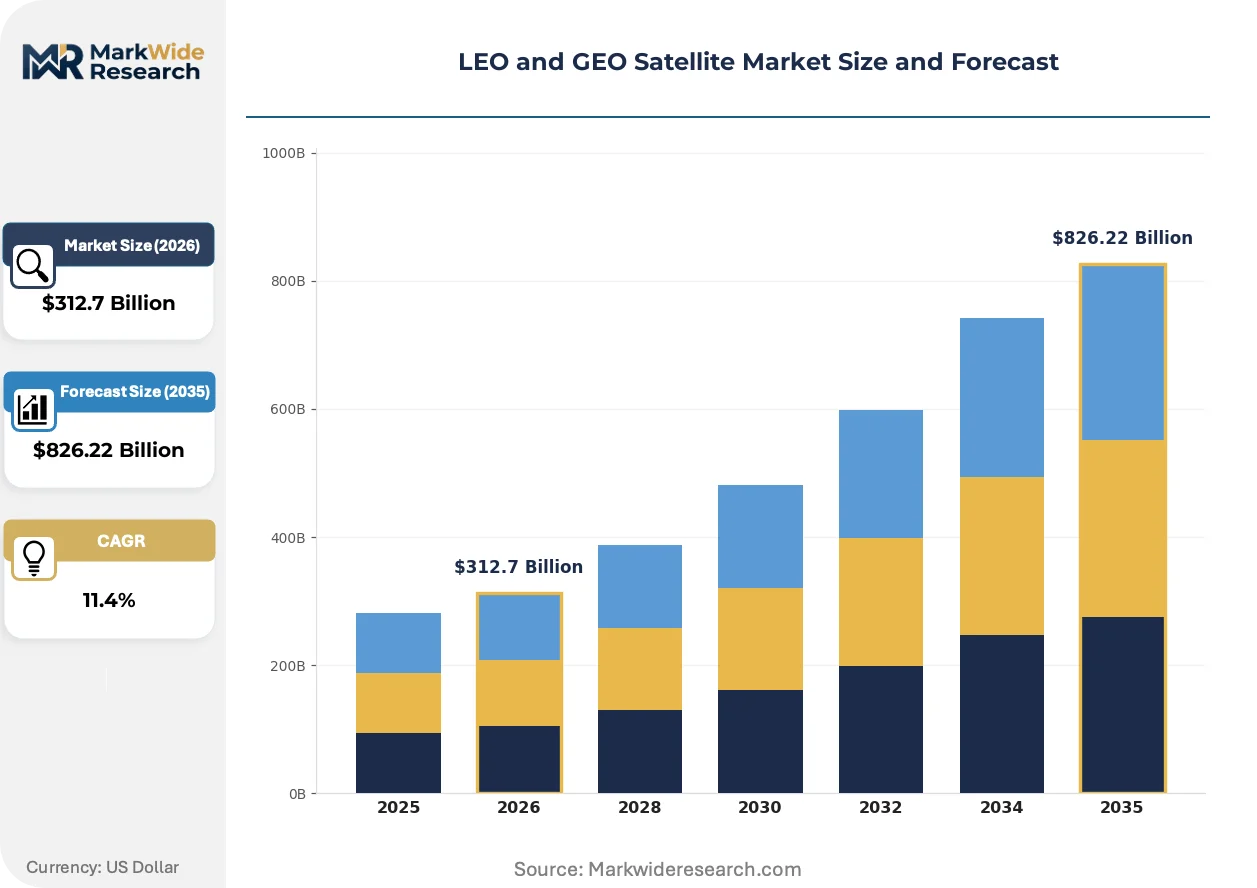
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Satellite Type: LEO, GEO, MEO, HEO End User: Government, Commercial, Military, Academic Application: Telecommunications, Earth Observation, Navigation, Remote Sensing Deployment Model: Launch Services, Ground Segment, Satellite Manufacturing, Operations |
| Companies Covered | Northrop Grumman, OneWeb, SpaceX, Maxar Technologies, Planet Labs PBC, Lockheed Martin Corporation, L3Harris Technologies, China Aerospace Science and Technology Corporation, Airbus Defence and Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LEO and GEO Satellite Market Shifts & Advancements
Software-defined payload architectures are displacing hardware-fixed satellite designs, enabling orbital reconfiguration that extends asset utility across shifting market demands without replacement launches.
Digital beamforming and onboard processing is digitizing satellite communications infrastructure, allowing operators to reallocate capacity dynamically across coverage footprints. Military and maritime end-users are adopting these flexible payloads fastest, compressing procurement cycles for dedicated regional beams. This technology is digitizing how spectrum utility gets priced and traded, shifting value capture toward operators with real-time orchestration capabilities.
The EU Space Programme's debris remediation mandates and the FCC's updated orbital collision probability thresholds are tightening post-mission disposal requirements for all registered operators. Industrial consequences include mandatory propulsion reserves and design-for-demise material selections that add mass and complexity to small satellite platforms. LEO constellation ventures with high satellite counts face disproportionate compliance exposure, driving investment into autonomous deorbit systems and active debris removal partnerships.
Service unbundling is fragmenting traditional satellite operator business models as hyperscale cloud providers integrate ground segment functions and sell capacity as utility compute. Channel relationships that once ran through national distributors and maritime integrators now compress toward API-driven direct provisioning. This pattern concentrates in United States and European enterprise markets where procurement functions possess technical sophistication to manage multi-orbit service orchestration internally.
LEO and GEO Satellite Market Segmentation
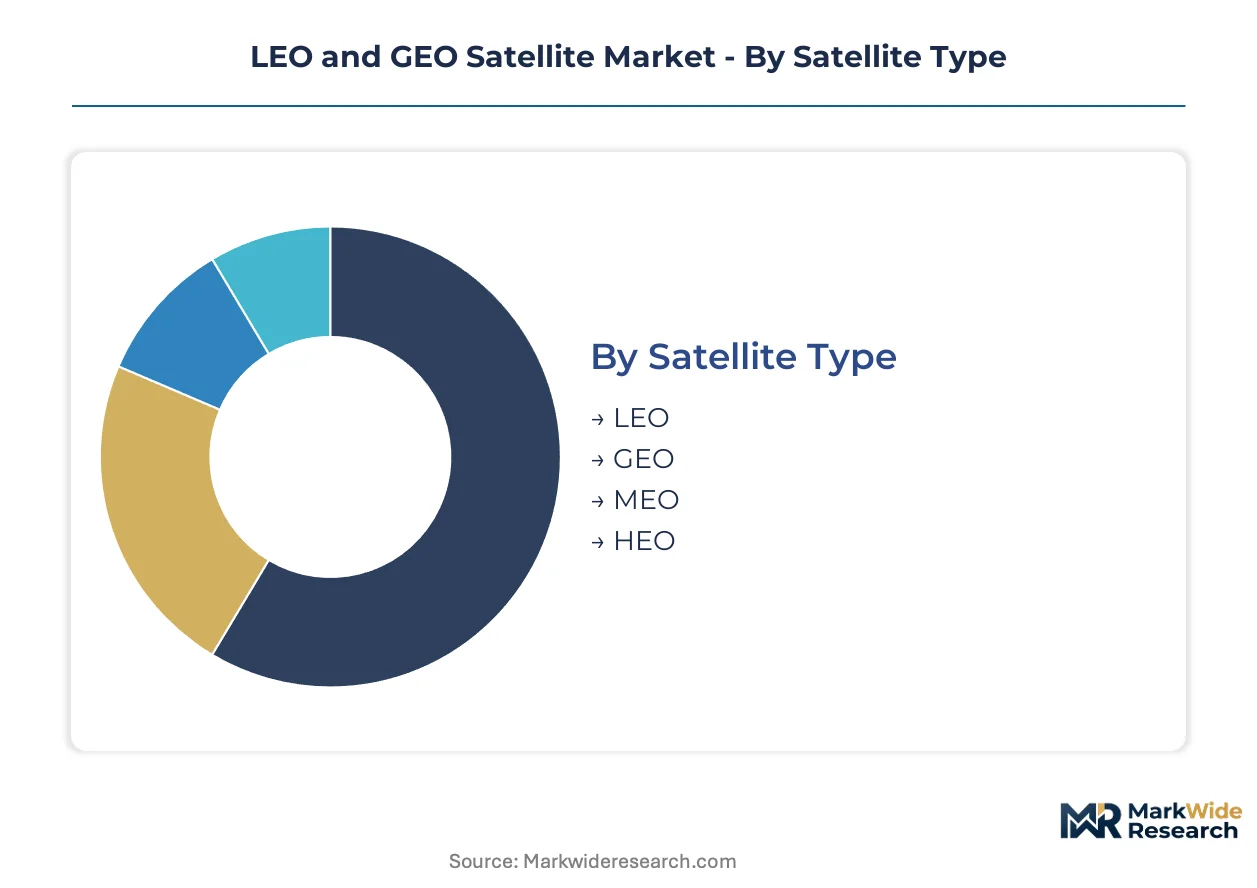
LEO and GEO satellite architectures diverge across orbital mechanics, end-use security requirements, and deployment economics, creating distinct procurement channels and margin structures. Segmentation clarity enables constellation operators to match payload specifications against regulatory constraints and customer mission profiles.
Satellite Type:
Mature geostationary platforms anchor broadcast and government markets while emerging low Earth orbit constellations redefine broadband economics through manufacturing scale.
- LEO:Satellites operate below 2,000 kilometers with orbital periods under 128 minutes, enabling low-latency broadband relay. Demand concentrates in United States commercial and military segments where Space Force resilient-space programs and rural broadband subsidies accelerate procurement.
- GEO:Fixed-position spacecraft at 35,786 kilometers maintain zero relative ground track motion for persistent coverage. European institutional programs and NATO secure communications anchor demand for hardened payloads with protected tactical waveforms.
- MEO:Medium Earth orbit assets bridge latency and coverage trade-offs for navigation constellations and specialized relay applications.
- HEO:Highly elliptical orbits deliver extended dwell time over high-latitude regions for Arctic communications and surveillance missions.
GEO retains volume leadership in government premium contracts; LEO holds the steepest expansion curve.
End User:
Customer type stratification separates classified procurement with hardened security requirements from commercial ventures pursuing subscriber scale.
- Commercial:Private equity-backed constellation ventures and maritime integrators drive procurement bandwidth for broadband and Earth observation services. Cloud-integrated ground segments enable direct API-driven provisioning without legacy capacity broker intermediation.
- Military:Classified resilient-space programs across NATO member states demand protected tactical waveforms and anti-jam payloads. United States Space Force contracts anchor procurement volume with multi-year bandwidth commitments.
- Government:Civilian agencies procure weather monitoring and environmental sensing through institutional frameworks like EU Copernicus expansion.
- Academic:University-led CubeSat missions and technology demonstration programs access rideshare launch opportunities for research payloads.
Commercial segments expand most quickly through direct-to-device integration; military procurement sustains premium pricing.
Application:
Functional use cases span communications infrastructure, environmental monitoring, and positioning services with diverging technical specifications.
- Telecommunications:Broadband relay and direct-to-device connectivity dominate capital deployment. FCC streamlined licensing for non-geostationary orbit systems compresses deployment timelines for constellation operators seeking rapid spectrum access.
- Earth Observation:Dual-use platforms combine commercial imagery sales with government reconnaissance contracts. Airbus Defence and Space competes across European institutional programs with synthetic aperture radar and optical payloads.
- Navigation:Precision timing and positioning services leverage MEO and GEO constellations for aviation and maritime safety applications.
- Remote Sensing:Hyperspectral and radar instruments support agriculture, mining, and disaster response with revisit-driven data products.
Telecommunications captures the largest capital deployment; Earth Observation climbs the fastest on dual-use demand.
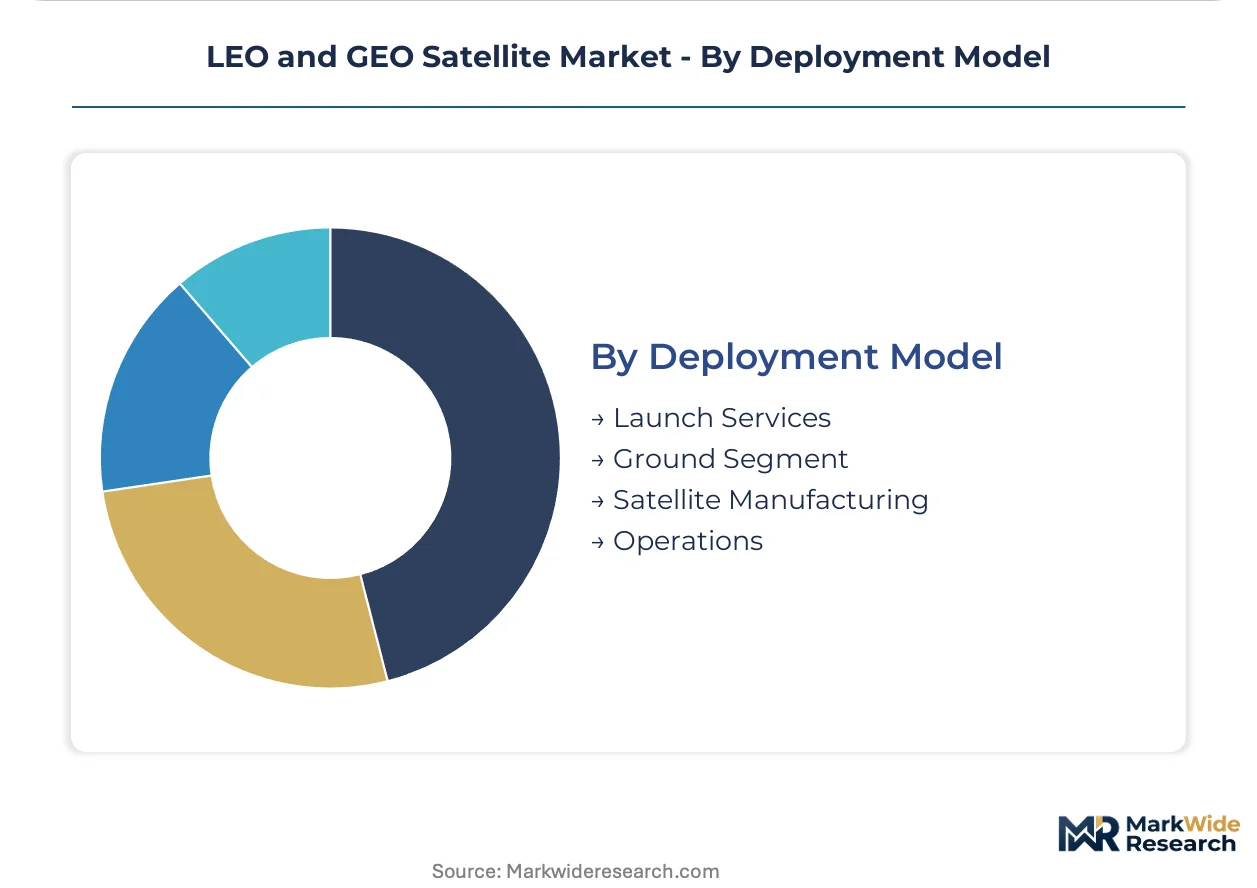
Deployment Model:
Value chain positioning determines margin capture between manufacturing, launch, ground infrastructure, and ongoing operations.
- Satellite Manufacturing:Megaconstellation architectures drive production scale for small satellite platforms with standardized bus designs. Software-defined payload architectures displace hardware-fixed designs, enabling orbital reconfiguration without replacement launches.
- Launch Services:Starship's cost compression collapses per-kilogram economics for constellation deployment. United States launch cadence advantages channel investment toward domestic operators with vertical integration from manufacturing to launch.
- Ground Segment:Virtualized ground station networks digitize service delivery. Cloud providers integrate ground segment functions and sell capacity as utility compute, fragmenting traditional operator business models.
- Operations:Constellation management and end-of-life disposal face tightening FCC and ESA debris remediation mandates with mandatory propulsion reserves.
Operations absorbs expanding regulatory compliance costs; ground segment virtualization gains share fastest through hyperscale cloud integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States procurement channels while European institutional programs defend premium margins through sovereign capability requirements. Demand asymmetry reflects divergent regulatory frameworks and defense spending trajectories across Atlantic markets.
United States
Space Force resilient-space contracts and FCC streamlined licensing for non-geostationary orbit systems channel investment toward LEO broadband and geostationary weather monitoring assets. The FCC's orbital debris mitigation mandates impose structural cost burdens on small satellite operators with limited propulsion budgets. Greater Los Angeles and Denver-Boulder corridors host constellation design and ground segment virtualization clusters.
China
MIIT and GB standards govern domestic satellite manufacturing and launch licensing for the Beidou navigation and Guowang broadband ecosystems. The country's national space regulator constrains foreign participation while accelerating captive constellation deployment. Beijing-Tianjin-Hebei and Yangtze River Delta regions concentrate state-owned prime contractors and commercial launch vehicle ventures.
Germany
ESA framework procurement and EU Space Programme debris remediation mandates shape European satellite manufacturing requirements. The EU IRIS² secure connectivity constellation creates procurement white space for dual-use platforms combining commercial and government service models. Munich and Bremen industrial clusters anchor Airbus Defence and Space production and optical payload development.
United Kingdom
OneWeb's constellation operations and UK Space Agency funding programs drive LEO broadband procurement bandwidth beyond traditional government channels. The country's national communications regulator oversees spectrum coordination for non-geostationary systems under ITU procedures. Harwell Space Cluster and Scottish launch sites concentrate satellite manufacturing and vertical launch capability development.
France
CNES institutional programs and EU Copernicus expansion anchor demand for Earth observation platforms with synthetic aperture radar and optical instruments. The EU AI Act and CSRD frameworks increasingly shape payload software certification and supply chain disclosure requirements. Toulouse and Paris-Saclay corridors host Airbus Defence and Space headquarters and optical inter-satellite link research facilities.
LEO and GEO Satellite Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower margin capture. The vendor base stratifies between vertically integrated constellation operators and modular payload suppliers serving multiple primes. Three archetypes dominate: launch-integrated megaconstellation ventures, hardened government payload specialists, and dual-use Earth observation platform vendors. Competitive moves concentrate on strategic partnerships for ground segment virtualization and manufacturing scale expansion for small satellite production lines.
Among United States-based integrators, SpaceX and Lockheed Martin Corporation occupy distinct tier positions—one representing launch-cadence-driven constellation scale, the other anchoring classified government demand through protected tactical waveform development. Airbus Defence and Space exemplifies the European dual-use archetype competing across institutional programs and export markets. These three entities illustrate how geographic regulatory alignment and end-user security requirements partition competitive positioning across Atlantic markets.
| Leading Market Players |
|---|
| Northrop Grumman |
| OneWeb |
| SpaceX |
| Maxar Technologies |
| Planet Labs PBC |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| China Aerospace Science and Technology Corporation |
| Airbus Defence and Space |
| Others |
Supply & Pricing Matrix
Long Beach to Shanghai maritime corridors carry satellite component shipments where container rate volatility feeds directly into LEO constellation manufacturing economics and downstream subscription pricing tiers. Supply concentration in Asian rare earth processing nodes compresses margins for electric propulsion manufacturers while enabling premium capture for hardened GEO payload specialists with captive magnet sourcing.
Pricing Analysis
The customization-premium spread separates standard small satellite bus pricing from configured-to-order government payloads with protected tactical waveforms. Subscription-based capacity pricing dominates commercial LEO broadband while project-based contracting anchors classified military procurement. Price differentiation rests on ITAR certification tier and launch integration bundling. Cost compression in Starship launch services is intensifying price competition among second-tier constellation operators. Maritime integrators show highest price sensitivity; NATO defense agencies demonstrate lowest.
Supply Chain Analysis
Upstream feedstock for satellite manufacturing draws from gallium arsenide wafer production concentrated in Japan and Taiwan, rare earth magnet processing in China, and carbon fiber composites from the United States and Germany. Permanent magnet dependencies for electric propulsion systems create single-source vulnerability exposure. Distribution runs through vertically integrated primes with in-house launch capabilities and modular component suppliers serving multiple constellation architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale cloud providers and national defense procurement offices, fragmenting traditional capacity broker intermediation and compressing channel margins across the value chain.
For Market Incumbents: Build regulatory moat through accelerated ITU spectrum filings and FCC debris remediation certification ahead of tightening mandates. Incumbents should deepen backward integration into optical inter-satellite link manufacturing to defend against emerging photonics specialists. Channel control through ground segment virtualization investments protects against cloud provider disintermediation. For New Entrants and Emerging Players: Dual-use Earth observation platforms for European institutional programs represent the most penetrable entry point given IRIS² procurement white space and Copernicus expansion bandwidth. India's liberalized SpaceCom policy enables foreign gateway establishment with reduced regulatory friction. Go-to-market positioning through API-driven direct provisioning bypasses legacy maritime integrator relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined payload architects with orbital reconfiguration capabilities over hardware-fixed legacy designs. Long-term viability across the projection horizon rests on autonomous deorbit system readiness and active debris removal partnerships. Acquisition targets with ITU coordination precedence and cleared spectrum filings offer defensible positioning. The signal to watch is FCC licensing queue compression indicating regulatory bandwidth constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Development | Orbital reconfiguration extends asset utility across shifting NATO secure communications requirements without replacement launches. |
| Optical Inter-Satellite Link Integration | Laser crosslink deployment enables direct-to-device connectivity for maritime and aviation verticals previously unreachable. |
| Ground Segment Virtualization Partnership | Cloud provider integration fragments traditional capacity broker business models and captures end-user relationships directly. |
| Active Debris Removal Collaboration | FCC and ESA disposal mandates drive investment into autonomous deorbit systems for high-count LEO constellations. |
| Dual-Use Platform Certification | IRIS² and Copernicus qualification opens procurement channels across European institutional programs and export markets. |
Research Methodology
The analysis maps LEO constellation architectures, GEO payload specializations, ground segment virtualization platforms, and launch service providers, each validated through constellation design engineers, defense procurement officers, satellite component manufacturing leads, and regulatory affairs specialists at spectrum allocation bodies. Primary interview intelligence combined with secondary validation from FCC licensing databases, ESA procurement records, ITU satellite network filings, and operator capex disclosures. Bottom-up unit economics modeling and top-down market sizing triangulation anchored volume estimates.
Assumptions held fixed include Starship launch cadence realization, FCC streamlined licensing timeline maintenance, and NATO secure communications budget trajectory. Variables tested across sensitivity scenarios included rare earth magnet supply disruption probability and ITU coordination queue duration. Segmentation dimensions modeled encompass orbital altitude tier, end-user security classification, payload software architecture, and regional regulatory cluster. CAGRs derived from installed base growth and replacement cycle dynamics. Forecast inputs incorporated debris remediation compliance cost curves and direct-to-device addressable market penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations cycles or launch vehicle capital availability would shift the trajectory. Forecasts reflect documented assumptions about spectrum allocation priority and debris mitigation technology readiness. Cross-checking against ESA and FCC regulatory filing velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Satellite Link Emulator Market
Satellite
M2M Satellite Communication Market
Satellite
Satellite Connectivity Market
Satellite
France Satellite Connectivity Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
Satellite Services Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
India Satellite Connectivity Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
Europe Military Satellite Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
Japan Satellite Connectivity Market
Satellite
Satellite Imaging Market