
 High Purity Gas Market | 2026-2036
High Purity Gas Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Gas Market Intelligence
Helium is decoupling from conventional natural gas extraction economics as LNG boil-off recovery and closed-loop recycling gain scale. Linde Plc leverages its Qatari helium stewardship and U.S. BLM pipeline access to sustain supply security for MRI and aerospace customers. Air Products and Chemicals, Inc. anchors North American hydrogen infrastructure through Gulf Coast blue hydrogen hubs, while Iwatani Corporation dominates Asia-Pacific helium distribution through captive Japanese liquefaction capacity.
High purity gas denotes mixtures or single-species gases refined to impurity levels below one part per billion, typically achieved through pressure swing adsorption, cryogenic distillation, or catalytic purification followed by point-of-use filtration. Electronic-grade nitrogen and argon serve as inert atmospheres for photolithography and etch processes, where particulate contamination above 0.1 micron destroys wafer yield. Semiconductor-grade helium leads value pools due to irreplaceable thermal conductivity in cryogenic wafer cooling, while pharmaceutical production applications for medical-grade oxygen and nitrogen expand with sterile fill-finish capacity buildouts. Ultra high purity hydrogen remains the fastest-growing grade category, driven by epitaxy and annealing steps in compound semiconductor manufacturing.
FDA medical gas cGMP requirements and EPA hazardous air pollutant standards shape U.S. product certification and plant siting, while REACH and the EU F-Gas Regulation govern European import quotas and mandatory reclamation rates for fluorinated and noble gases. China's SAMR enforces GB standards for electronic materials that foreign suppliers must meet to qualify for domestic fab projects. Stakeholders must monitor how regional carbon border adjustments and semiconductor subsidy local-content rules redirect supply chain investment toward captive on-site gas generation versus merchant bulk delivery.
Market Dynamics
Semiconductor localization mandates are forcing gas suppliers to build captive on-site generation plants adjacent to advanced logic fabs, displacing traditional merchant bulk delivery economics.
Growth Catalysts
- EU F-Gas Regulation:Mandatory fluorinated gas recovery quotas are retrofitting reclamation infrastructure across European production sites, creating sustained equipment upgrade cycles.
- Compound semiconductor epitaxy:Gallium nitride and silicon carbide wafer fabrication is consuming ultra high purity hydrogen at volumes that justify dedicated pipeline investments.
- South Korean fab clustering:Samsung and SK Hynix concentration in Pyeongtaek and Yongin is anchoring regional helium and nitrogen supply security investments.
Market Restraints
- Helium feedstock concentration:Qatari LNG extraction and U.S. BLM reserve dependence creates single-source vulnerability for cryogenic cooling applications.
- Blue hydrogen cost structure:Steam methane reforming with carbon capture requires sustained natural gas price stability to compete against unabated gray hydrogen.
- EPA hazardous air pollutant standards:Stringent emissions thresholds for perfluorinated compounds limit fluorinated gas production capacity expansion in U.S. coastal zones.
Strategic Opportunities
- India PLI scheme:Semiconductor manufacturing incentives are attracting on-site gas generation investments for greenfield fabs in Gujarat and Karnataka.
- LNG boil-off helium recovery:Closed-loop capture systems at liquefaction terminals are unlocking stranded helium without new natural gas field development.
- Medical-grade oxygen sterile fill-finish:Biologics manufacturing expansion is creating demand for pharmaceutical nitrogen and oxygen with FDA cGMP certification.
Industry Challenges
- Cryogenic system technician scarcity:Specialized expertise in helium liquefaction and distribution is concentrating among aging workforces in Japan and Germany.
- GB standards compliance timelines:Foreign suppliers face extended qualification periods under China's SAMR electronic materials certification for domestic fab projects.
- Legacy bulk delivery contract structures:Long-term take-or-pay agreements with industrial gas majors resist flexible pricing adjustments during semiconductor demand cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Gas Market |
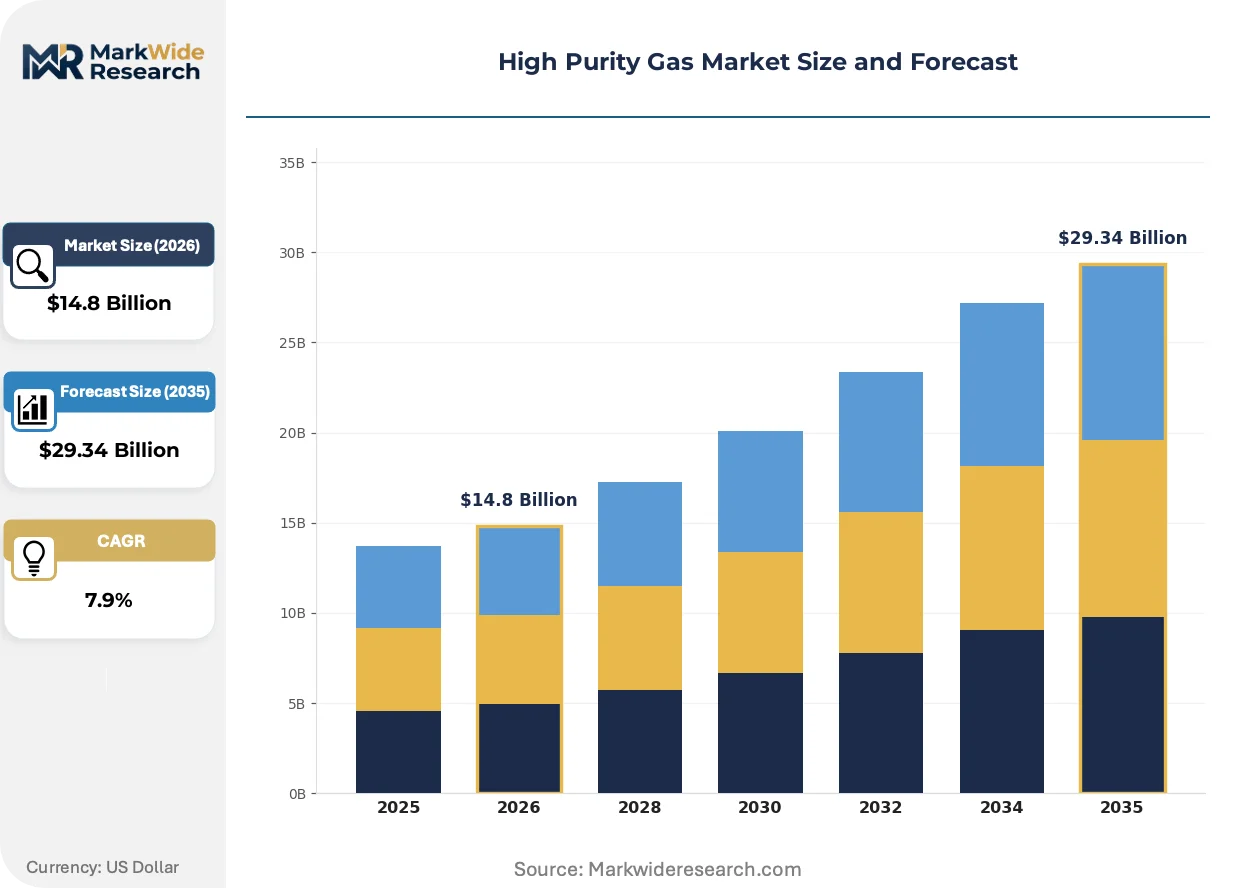
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $29.34 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen, Nitrogen, Argon, Helium, Hydrogen, Carbon Dioxide Grade: Electronic Grade, Semiconductor Grade, Ultra High Purity, Medical Grade, Food Grade Application: Semiconductor Fabrication, Pharmaceutical Production, Chemical Synthesis, Food Processing, Laser Technology End User: Research Laboratories, Electronics Manufacturers, Pharmaceutical Companies, Food & Beverage Processors |
| Companies Covered | Messer SE & Co. KGaA, Iwatani Corporation, Linde Plc, Advanced Specialty Gases, Matheson Tri-Gas Inc., Air Liquide, Nippon Sanso Holdings Corporation, Resonac Holdings Corporation, Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Gas Market Strategic Shifts & Innovations
Point-of-use gas purification is compressing supply chain tiers as fabs internalize impurity control previously outsourced to merchant suppliers.
Membrane-based nitrogen generation is expanding into advanced packaging facilities seeking independence from liquid nitrogen tanker deliveries. OSATs in Malaysia and Vietnam are adopting pressure swing adsorption units to buffer against regional merchant supply disruptions. This distributed architecture is compressing traditional bulk gas logistics margins while elevating on-site equipment service contracts.
China's dual carbon goals are tightening bulk gas recovery mandates through MEE enforcement of industrial emissions intensity targets. Producers must retrofit catalytic destruction and cryogenic capture systems or face production quota restrictions. Compound semiconductor manufacturers in Jiangsu and Shaanxi are most affected, accelerating closed-loop helium recycling investments.
Take-or-pay contract structures are fragmenting as foundries negotiate variable-volume agreements indexed to wafer starts rather than fixed minimum offtake. Merchant gas suppliers in Taiwan and Singapore are accepting performance-linked pricing to defend fab relationships against captive on-site generation. This behavioral shift is most visible among advanced logic producers with volatile product mix transitions.
High Purity Gas Market Segmentation
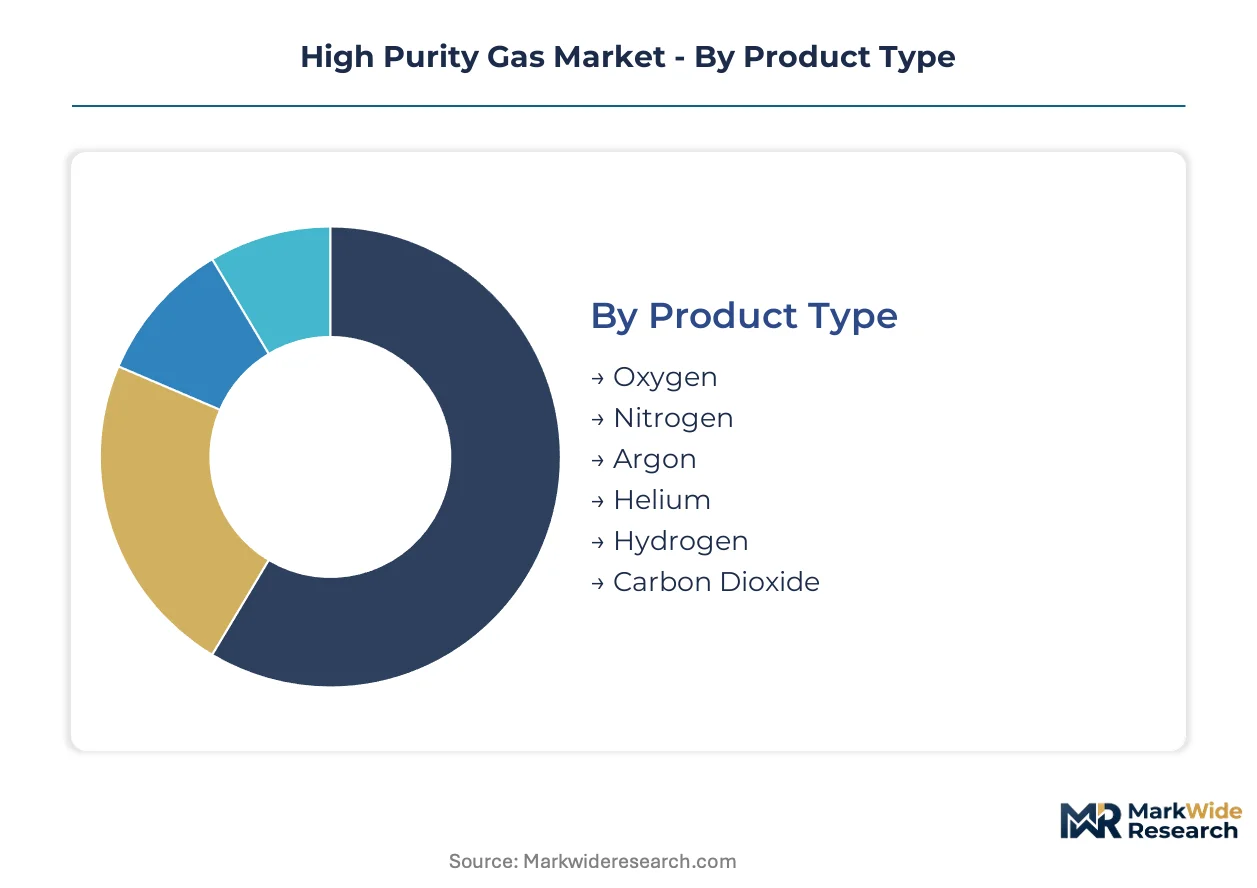
Segmentation in high purity gases separates captive on-site generation from merchant bulk delivery, each commanding distinct capital intensity and contract structures. Product type and grade classifications determine purification thresholds that lock suppliers into specific end-use qualifications.
Product Type:
Standalone bulk gases dominate merchant supply chains, while embedded point-of-use purification systems are displacing tanker deliveries in advanced fabs.
- Nitrogen:Cryogenic distillation yields purity levels exceeding 99.9999% for photolithography inert atmospheres. Samsung and SK Hynix fabs in South Korea consume the largest merchant volumes, though membrane generation is eroding tanker economics at packaging facilities.
- Helium:Extracted from Qatari LNG streams and U.S. BLM reserves, this irreplaceable coolant for cryogenic wafer processing faces structural supply concentration. Closed-loop recycling investments are accelerating as semiconductor manufacturers seek insulation from feedstock volatility.
- Hydrogen:Steam methane reforming with carbon capture supplies blue hydrogen for gallium nitride epitaxy.
- Argon:Steel industry off-gas purification feeds semiconductor etch processes.
- Oxygen:Medical-grade specifications require FDA cGMP certification for sterile fill-finish operations.
- Carbon Dioxide:Food-grade applications in beverage carbonation and modified atmosphere packaging.
Nitrogen leads volumes today; helium is gaining share fastest in value terms.
Grade:
Cost tiers stratify sharply, with certification overhead separating premium electronic grades from commoditized industrial specifications.
- Electronic Grade:Impurity thresholds below one part per billion achieved through pressure swing adsorption and catalytic purification. EU F-Gas Regulation mandates are tightening recovery requirements for fluorinated electronic gases, forcing retrofit investments at German and French production sites.
- Semiconductor Grade:Dedicated supply chains exclude cross-contamination risks from industrial gas networks. Taiwan and Singapore foundries negotiate wafer-start-indexed contracts rather than fixed minimum offtake, fragmenting traditional take-or-pay structures.
- Ultra High Purity:Compound semiconductor epitaxy for silicon carbide power devices demands hydrogen purity exceeding 99.99999%.
- Medical Grade:FDA and EMA cGMP compliance extends batch documentation through fill-finish operations.
- Food Grade:Modified atmosphere packaging and beverage carbonation specifications under EFSA and national food safety frameworks.
Electronic grade dominates current revenue; ultra high purity is expanding most quickly.
Application:
Application concentration tracks semiconductor capital expenditure cycles, with volatility highest in leading-edge logic and memory fabrication.
- Semiconductor Fabrication:Photolithography, etch, and deposition processes consume electronic-grade nitrogen, argon, and helium in ratios tied to process node complexity. Pyeongtaek and Yongin clustering in South Korea anchors regional supply security investments by Linde and Air Products.
- Pharmaceutical Production:Sterile fill-finish operations for biologics require medical-grade nitrogen and oxygen with full batch traceability. India's CDSCO is aligning with FDA cGMP standards to attract contract manufacturing investment.
- Chemical Synthesis:High purity hydrogen feeds ammonia and methanol production with carbon intensity disclosures under EU Green Deal requirements.
- Food Processing:Modified atmosphere packaging extends shelf life for premium protein exports.
- Laser Technology:Excimer and CO2 laser gain media specify ultra high purity gas mixtures.
Semiconductor fabrication commands the largest value pool; pharmaceutical production is climbing the fastest.
End User:
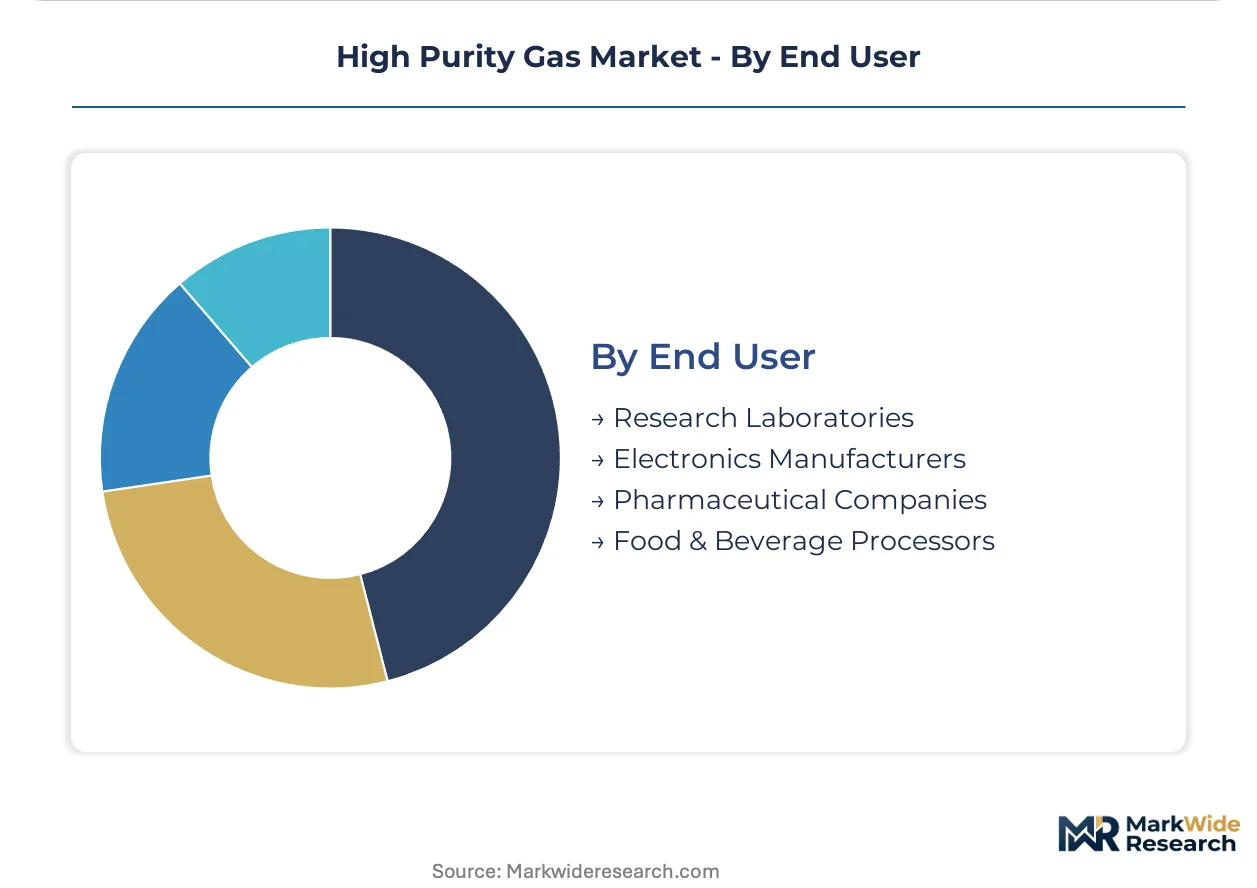
Customer type determines contract structure, with research laboratories accepting spot pricing while electronics manufacturers negotiate decade-long supply agreements.
- Electronics Manufacturers:Samsung, SK Hynix, and TSMC anchor demand through captive on-site plants or dedicated pipeline investments. China's SAMR GB standards compliance timelines extend foreign supplier qualification periods for domestic fab projects.
- Pharmaceutical Companies:Sterile manufacturing capacity buildouts in India and Southeast Asia are attracting medical-grade gas infrastructure investment under PLI scheme incentives.
- Research Laboratories:Helium for cryogenic cooling in MRI and basic science faces allocation constraints from concentrated Qatari and U.S. supply.
- Food & Beverage Processors:Carbon dioxide and nitrogen volumes track packaged goods consumption with lower purity thresholds than electronic applications.
Electronics manufacturers absorb the largest volumes today; pharmaceutical companies are expanding procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyeongtaek and Yongin anchor the densest concentration of advanced logic and memory fabrication globally, driving helium and nitrogen supply security investments across East Asia.
United States
EPA hazardous air pollutant standards constrain perfluorinated compound production capacity in coastal zones, while Gulf Coast blue hydrogen hubs anchor North American ultra high purity hydrogen supply. Samsung's Taylor, Texas fab complex is attracting captive on-site nitrogen generation investments.
South Korea
Samsung and SK Hynix fabs in Pyeongtaek and Yongin consume the world's largest merchant volumes of electronic-grade nitrogen and helium. MFDS pharmaceutical regulations are tightening medical-grade gas certification requirements for sterile fill-finish exports. The Seoul Capital Area is witnessing foundries negotiate wafer-start-indexed contracts rather than fixed minimum offtake.
China
Dual carbon goals enforced through MEE emissions intensity targets are retrofitting catalytic destruction and cryogenic capture systems at Jiangsu and Shaanxi compound semiconductor facilities. SAMR GB standards compliance timelines extend foreign supplier qualification periods for domestic fab projects. Yangtze River Delta clustering is accelerating closed-loop helium recycling investments.
Germany
EU F-Gas Regulation mandatory recovery quotas are retrofitting reclamation infrastructure at production sites in Baden-Württemberg and Bavaria. ECHA REACH compliance governs import quotas for fluorinated and noble gases used in automotive sensor manufacturing. The Rhine-Main industrial corridor is consolidating pressure swing adsorption expertise among specialized equipment vendors.
Japan
METI industrial policy supports captive liquefaction capacity for helium distribution across Asia-Pacific semiconductor markets. JIS standards certification creates qualification barriers for foreign medical-grade gas suppliers seeking pharmaceutical manufacturing partnerships. Kyushu's advanced materials cluster is integrating point-of-use purification systems for compound semiconductor epitaxy.
High Purity Gas Market Key Industry Players
Global majors compete with regional champions across supply security and localization service capabilities, producing a tiered structure where integrated gas majors hold bulk infrastructure advantages while national champions dominate captive on-site generation. European and Japanese specialists concentrate cryogenic system expertise, while Gulf-based players leverage feedstock access. Three archetypes predominate: integrated global majors with pipeline networks, regional champions with government-backed localization mandates, and specialized purifiers serving point-of-use applications. Competitive moves center on captive plant construction adjacent to advanced fabs and closed-loop recycling technology licensing.
Within the integrated major tier, Linde Plc and Air Products and Chemicals, Inc. exemplify archetypes differentiated by regional infrastructure density and hydrogen hub positioning. Iwatani Corporation occupies a distinct position as a regional champion with Asia-Pacific helium distribution anchored in Japanese liquefaction capacity. These three represent the spectrum from global pipeline networks to national feedstock stewardship.
| Leading Market Players |
|---|
| Messer SE & Co. KGaA |
| Iwatani Corporation |
| Linde Plc |
| Advanced Specialty Gases |
| Matheson Tri-Gas Inc. |
| Air Liquide |
| Nippon Sanso Holdings Corporation |
| Resonac Holdings Corporation |
| Air Products and Chemicals, Inc. |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers in Qatar and state-controlled reserves in the United States anchor feedstock ownership patterns that transmit directly into contract pricing discipline and supply security premiums for semiconductor buyers. This ownership concentration elevates take-or-pay structures for helium and nitrogen while compressing margins for merchant distributors caught between fixed input costs and wafer-start-indexed customer demands.
Pricing Analysis
Input-cost pass-through from Qatari LNG extraction and U.S. BLM reserve stewardship governs helium contract structures, with long-term offtake agreements indexing to feedstock availability rather than spot commodity benchmarks. Price differentiation rests on certification grade—electronic-grade nitrogen commands premiums over industrial specifications due to SAMR GB standards compliance overhead in China—and volume scale, where Samsung and SK Hynix leverage fab clustering for dedicated pipeline economics. Cost compression in merchant bulk delivery is intensifying because membrane-based nitrogen generation at OSAT facilities displaces tanker volumes. Packaging subcontractors in Malaysia and Vietnam exhibit highest price sensitivity, while advanced logic foundries in South Korea and Taiwan accept performance-linked premiums for supply security.
Supply Chain Analysis
Direct-to-fab pipeline networks handle hyperscale demand from Samsung, SK Hynix, and TSMC, while merchant tanker deliveries serve smaller packaging and pharmaceutical accounts. Geographic supply concentrates in Qatar for helium extraction, the United States for BLM reserve access and Gulf Coast hydrogen production, and Japan for Asia-Pacific liquefaction capacity. Raw material dependencies include natural gas feedstocks for helium extraction, steel industry off-gas for argon purification, and methane feedstock for blue hydrogen production. Single-source vulnerability from Qatari LNG concentration creates structural supply risk for cryogenic cooling applications. Distribution runs through integrated global majors with pipeline infrastructure, regional champions with government-backed localization mandates, and specialized point-of-use purifiers serving compound semiconductor epitaxy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high purity gas market reads as a late-cycle quality story where semiconductor localization mandates and EU F-Gas Regulation recovery quotas shift procurement toward premium electronic-grade specifications with full batch traceability and closed-loop recycling infrastructure.
For Market Incumbents: Extend captive on-site generation footprints adjacent to advanced logic fabs in Pyeongtaek, Yongin, and Taylor, Texas to defend against membrane-based nitrogen displacement at packaging facilities. Deepen backward integration into helium liquefaction capacity through Japanese or Qatari partnerships, as feedstock concentration threatens supply security premiums. Lock in wafer-start-indexed contract structures with performance-linked pricing to retain foundry relationships against emerging point-of-use purification specialists. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for reclamation equipment specialists to retrofit catalytic destruction and cryogenic capture systems at fluorinated gas production sites. Target India's PLI scheme semiconductor incentives for greenfield captive nitrogen generation investments in Gujarat and Karnataka, where merchant infrastructure remains underdeveloped. Lead with FDA cGMP certification capabilities for medical-grade oxygen and nitrogen to penetrate sterile fill-finish capacity buildouts in Southeast Asian biologics manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among regional point-of-use purification specialists with compound semiconductor epitaxy expertise in Japan and Germany, where cryogenic system technician scarcity creates defensive moats. Long-term viability favors acquisition targets with closed-loop helium recycling technology and SAMR GB standards qualification timelines already completed for Chinese domestic fab projects. Watch for inflection in take-or-pay contract fragmentation rates among Taiwan and Singapore foundries as a signal of merchant supplier pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive On-Site Generation Buildout | Samsung's Taylor fab anchors regional nitrogen supply security investments in Texas. |
| Helium Closed-Loop Recycling Licensing | Yangtze River Delta compound semiconductor facilities accelerate MEE-mandated retrofit cycles. |
| Backward Integration into Liquefaction | Iwatani's Japanese capacity secures Asia-Pacific distribution dominance against Qatari supply volatility. |
| Medical-Grade cGMP Certification Investment | India's CDSCO alignment with FDA standards attracts sterile fill-finish gas infrastructure under PLI incentives. |
| Wafer-Start-Indexed Contract Structuring | Taiwan foundries negotiate performance-linked pricing to balance volatile product mix transitions. |
Research Approach
Coverage spans East Asia, North America, and Europe, with primary inputs from each region combining interviews with fab procurement managers, gas supplier technical directors, and pharmaceutical manufacturing executives alongside secondary validation through SEC filings, customs and trade data, and SAMR certification databases. Bottom-up modeling of captive on-site generation capacity and merchant bulk delivery volumes triangulates against top-down semiconductor capital expenditure forecasts and pharmaceutical sterile manufacturing buildout tracking.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon, with segmentation dimensions including product type, grade tier, application concentration, and end-user contract structure. CAGRs derive from fitted growth curves against historical fab equipment spend correlations and pharmaceutical capacity utilization rates, incorporating EU F-Gas Regulation enforcement timelines and China's dual carbon goals as policy-driven inflection inputs.
Revisions become necessary when semiconductor demand cycles shift foundry utilization rates, helium reserve depletion accelerates beyond replacement rates, or regional carbon border adjustments redirect supply chain investment toward captive generation versus merchant delivery. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Food-Grade Gases Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Welding Gas Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Oxygen Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Industrial Hydrogen Market