
 Acetylene Gas Market | 2026-2036
Acetylene Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylene Gas Market Intelligence
Aftermarket cylinder refurbishment and requalification services is reconfiguring margin pools away from virgin gas production toward lifecycle asset management. BASF SE leverages its integrated petrochemical complexes to sustain captive acetylene supply for downstream chemical synthesis. Linde plc anchors its position through dense filling station networks and bulk delivery infrastructure across industrial clusters. Air Liquide competes by controlling cylinder fleet logistics and long-term gas supply contracts with automotive OEMs.
Acetylene is a hydrocarbon gas with the chemical formula C₂H₂, produced primarily through the calcium carbide reaction with water or via hydrocarbon cracking, yielding a colorless gas with a distinctive garlic-like odor and a flame temperature exceeding 3,100°C when combusted with oxygen. This extreme thermal output makes it indispensable for oxy-acetylene welding and precision metal cutting in heavy fabrication. Pure acetylene dominates product type revenue due to its direct use in high-heat industrial processes, while stabilized acetylene formulations are gaining traction where transport safety regulations have tightened. The welding application segment leads volume consumption across manufacturing end users, though chemical synthesis applications for vinyl chloride and acetic acid production carry substantially higher per-unit margins.
OSHA mandates workplace exposure limits and cylinder handling protocols that shape operational compliance costs for acetylene distributors and end users across the United States. The EPA monitors air emissions from carbide-based production facilities, pushing operators toward cleaner cracking technologies or emission capture systems. China's SAMR enforces GB cylinder standards that dictate manufacturing specifications for the domestic market and influence export certification requirements. Stakeholders must monitor how evolving carbon accounting rules and regional decarbonization timelines reshape the cost competitiveness of carbide-derived versus petrochemical-derived acetylene pathways.
Market Dynamics
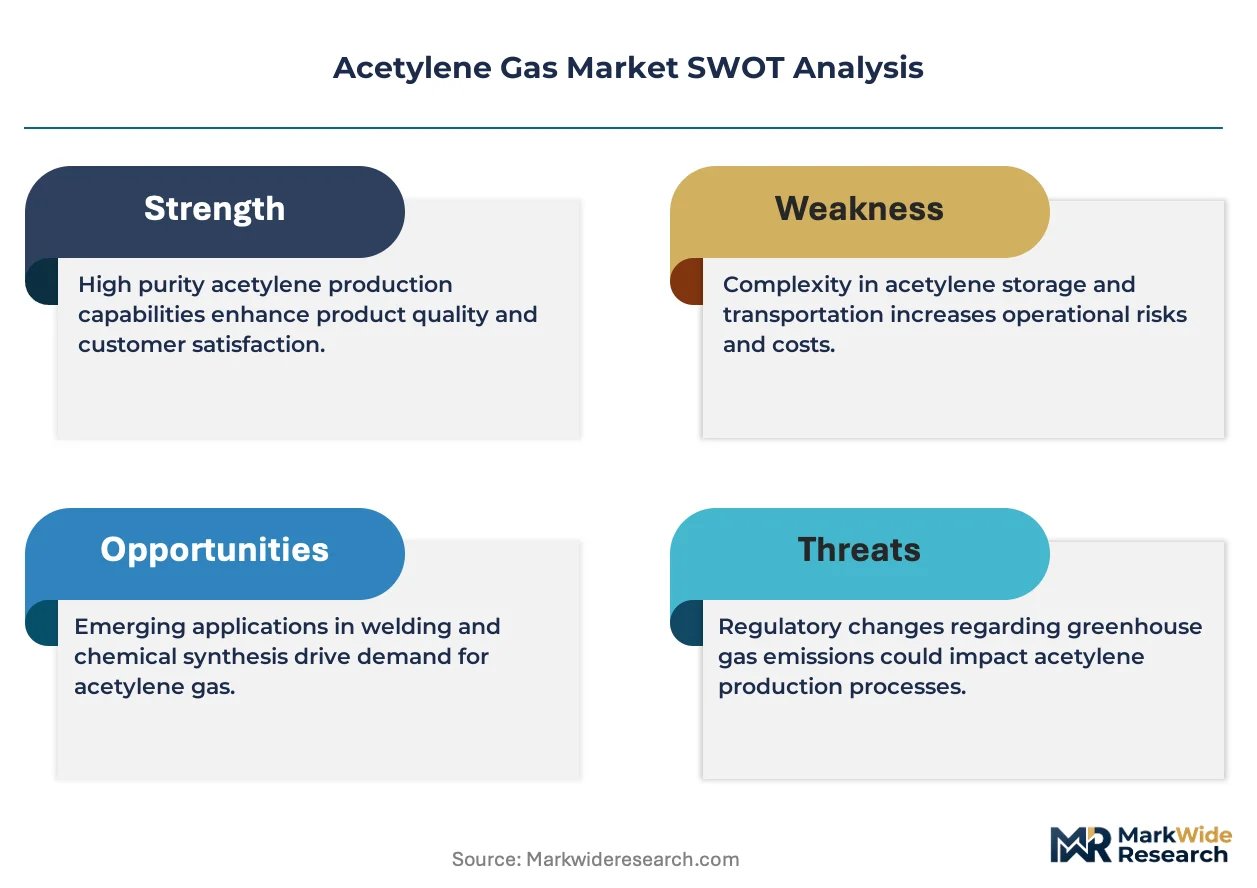
Carbide-derived acetylene production is losing cost competitiveness against petrochemical cracking routes as carbon accounting rules tighten across industrial clusters, forcing incumbent producers to reconfigure feedstock strategies or absorb margin compression.
Growth Catalysts
- Metal fabrication expansion:India's western industrial corridor around Gujarat and Maharashtra is scaling oxy-acetylene cutting capacity for shipbuilding and heavy equipment manufacturing.
- GB standards alignment:China's SAMR enforcement of stricter cylinder safety specifications is accelerating fleet replacement cycles and aftermarket refurbishment demand.
- Captive chemical synthesis:Downstream vinyl chloride and acetic acid producers are securing long-term acetylene offtake to insulate against feedstock volatility.
Market Restraints
- Calcium carbide input volatility:Electricity-intensive carbide production exposes margins to power tariff fluctuations in coal-dependent grids.
- Substitution by plasma cutting:High-precision fabrication shops are adopting plasma arc systems for thinner gauge metals, compressing addressable demand in light manufacturing.
- Transport safety compliance:Stabilized acetylene formulations require specialized cylinder metallurgy and handling protocols that inflate distribution costs.
Strategic Opportunities
- Cylinder lifecycle services:Third-party requalification and refurbishment providers are capturing margin pools previously held by virgin gas producers.
- Dual carbon pathway positioning:Petrochemical cracking routes align with China's dual carbon goals and EU carbon border adjustments, opening premium pricing for low-carbon acetylene certification.
- Automotive OEM contracts:Long-term supply agreements with electric vehicle battery enclosure fabricators are securing volume commitments for precision welding applications.
Industry Challenges
- Specialized welder certification gaps:Oxy-acetylene proficiency requirements exceed available training pipeline capacity in expanding industrial corridors.
- Carbide-to-cracking conversion capex:Retooling production assets demands substantial capital outlay with extended payback periods under uncertain carbon pricing trajectories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylene Gas Market |
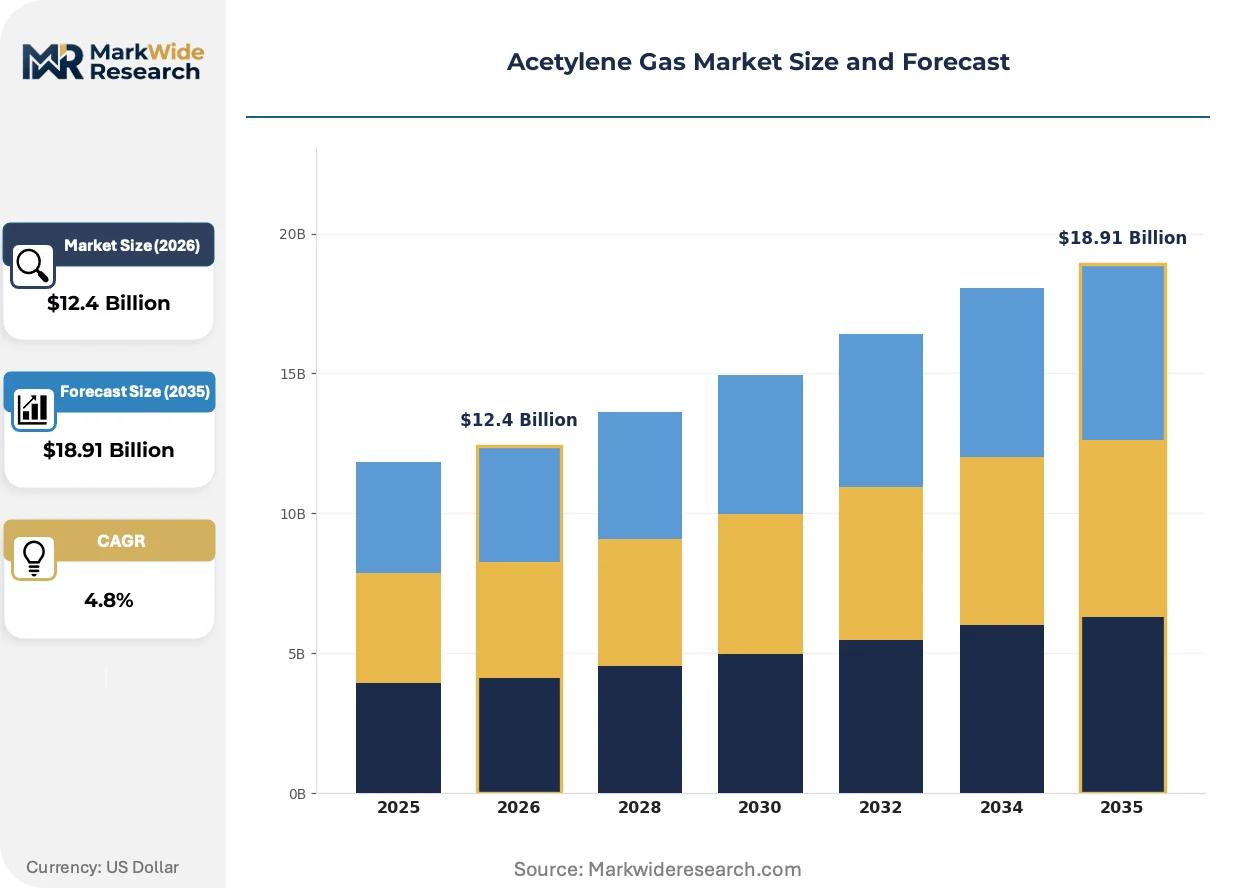
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Acetylene, Stabilized Acetylene, Mixed Acetylene, Acetylene Cylinders Application: Welding, Cutting, Chemical Synthesis, Lighting End User: Manufacturing, Automotive, Construction, Chemical Industry Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | BASF SE, Toho Acetylene, Linde plc, Sichuan Vinylon, Koatsu Gas Kogyo, Air Liquide, Gulf Cryo, Jinhong Gas, Airgas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylene Gas Market Strategic Shifts & Innovations
Production technology and regulatory compliance frameworks are diverging sharply between legacy carbide routes and emerging petrochemical pathways, fragmenting competitive strategies across supplier tiers.
Plasma-assisted acetylene cracking is migrating from pilot installations to commercial-scale deployment in integrated petrochemical complexes. Refinery operators with access to low-cost ethylene feedstock are adopting this technology to bypass carbide entirely. The shift is compressing the addressable market for traditional calcium carbide producers in regions with abundant natural gas liquids.
REACH registration requirements for acetylene derivatives are tightening substance documentation and supply chain traceability obligations across European chemical manufacturers. ECHA enforcement is extending compliance burdens to importers and downstream formulators. Vinyl chloride monomer producers are responding by consolidating supplier bases and demanding certified low-impurity acetylene grades.
Buyer consolidation among heavy fabrication contractors is compressing procurement cycles and unbundling cylinder logistics from gas supply contracts. Large metalworking conglomerates are negotiating direct bulk delivery arrangements, bypassing traditional distributor networks. This pattern is most pronounced in China's coastal manufacturing zones and India's western industrial belt.
Acetylene Gas Market Segmentation
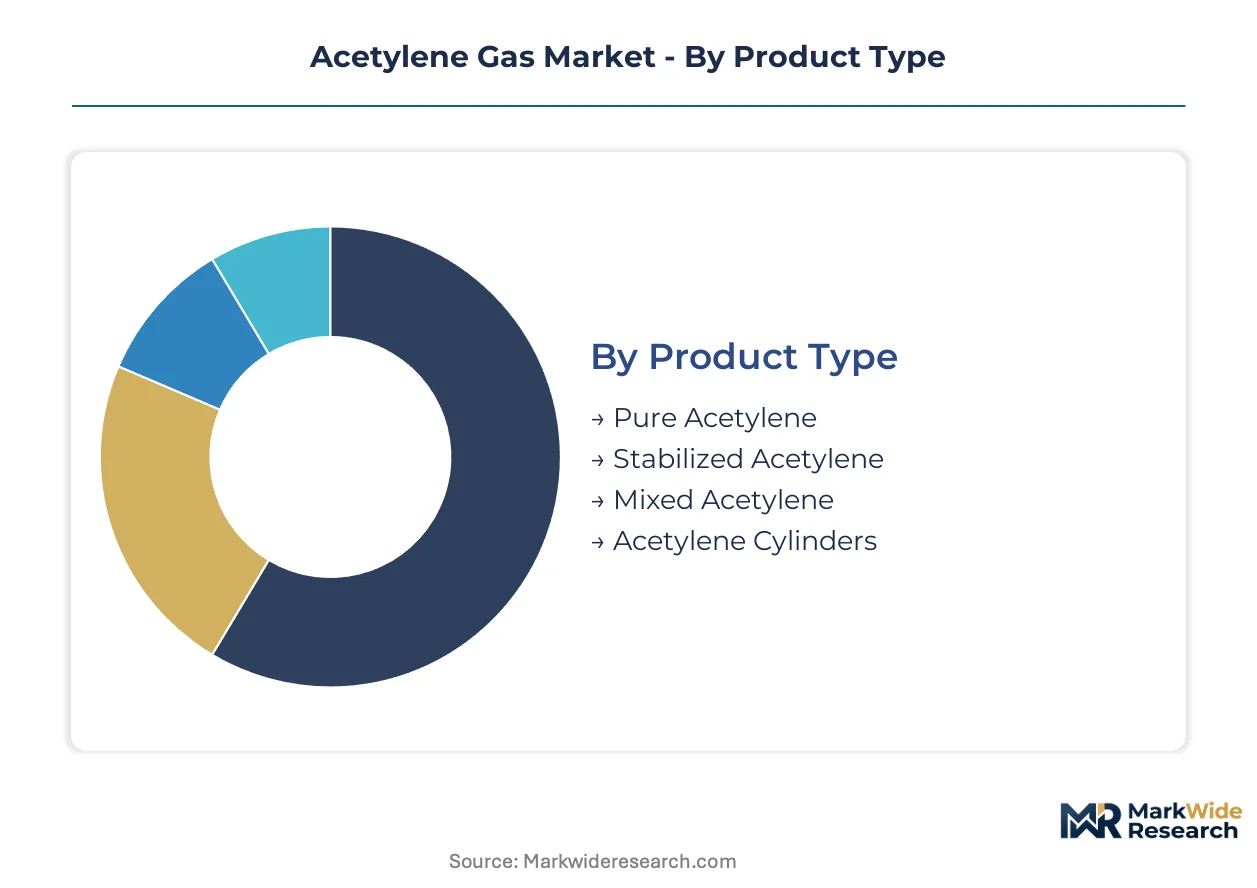
Acetylene gas segmentation reflects divergent purity requirements across metal fabrication versus chemical synthesis end uses. Each dimension shapes procurement patterns, cylinder specifications, and margin structures differently.
Product Type:
Mature formulations dominate established fabrication workflows, while emerging stabilized variants address tightening transport safety mandates.
- Pure Acetylene:Contains 98% minimum C₂H₂ content with minimal additives, delivering flame temperatures exceeding 3,100°C for oxy-acetylene welding. Demand concentrates in India's western industrial corridor around Gujarat and Maharashtra, where shipbuilding and heavy equipment fabricators prioritize thermal output over handling convenience.
- Stabilized Acetylene:Incorporates acetone or dimethylformamide as a solvent medium to prevent decomposition under pressure, enabling safer cylinder transport. China's SAMR enforcement of stricter GB cylinder standards is accelerating adoption among distributors serving dispersed construction sites.
- Mixed Acetylene:Blends with inert gases for specialized flame chemistry in brazing applications.
- Acetylene Cylinders:Porous mass storage vessels requiring periodic requalification under OSHA and GB protocols.
Pure Acetylene handles the majority of throughput; Stabilized Acetylene is climbing the fastest on share.
Application:
Volume concentration diverges sharply between high-throughput metalworking and margin-rich chemical conversion.
- Welding:Oxy-acetylene fusion joining of ferrous and non-ferrous metals in fabrication shops. India's expanding metalworking capacity in Gujarat's shipyards and Maharashtra's automotive component clusters sustains bulk consumption.
- Chemical Synthesis:Feedstock for vinyl chloride monomer and acetic acid production. BASF SE and integrated petrochemical operators capture substantially higher per-unit margins through captive acetylene conversion.
- Cutting:Precision severance of thick steel plate using oxidizing flame chemistry.
- Lighting:Historic carbide lamp applications now limited to specialized mining and caving equipment.
Welding commands the largest volume position; Chemical Synthesis delivers the steepest margin expansion.
End User:
Customer scale determines contract structure, with bulk industrial offtake contrasting fragmented construction procurement.
- Manufacturing:Metal fabrication workshops and machinery producers across China's coastal manufacturing zones and India's western belt. Procurement is shifting toward direct bulk delivery arrangements that bypass traditional distributor networks.
- Automotive:OEM and tier supplier welding operations for chassis and battery enclosure fabrication. Long-term supply agreements with electric vehicle producers are securing volume commitments for precision welding applications.
- Construction:On-site cutting and joining for structural steel erection.
- Chemical Industry:Downstream vinyl chloride and acetic acid producers securing feedstock against volatility.
Manufacturing absorbs the dominant share of cylinder movements; Automotive contracts are expanding most quickly.
Distribution Channel:
Channel selection reflects customer scale, geographic dispersion, and cylinder fleet ownership economics.
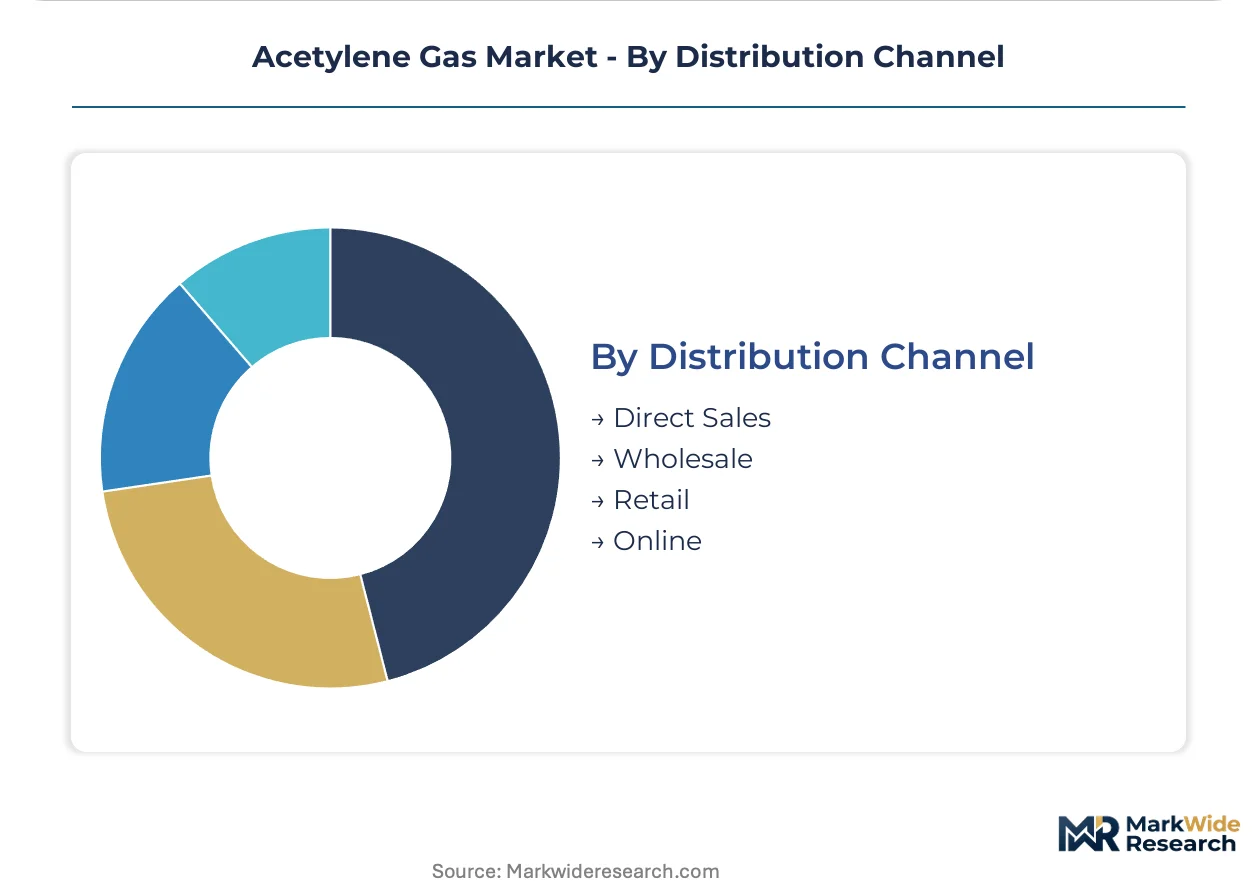
- Direct Sales:Bulk delivery contracts with heavy fabrication conglomerates and chemical producers. Large metalworking contractors in China's coastal zones negotiate unbundled gas supply separate from cylinder logistics.
- Wholesale:Intermediate supply to regional gas distributors and independent welding equipment dealers.
- Retail:Small-volume cylinder exchange for job shops and maintenance contractors.
- Online:Emerging platform-based procurement for standardized cylinder specifications and requalification scheduling.
Direct Sales captures the bulk of value throughput; Online channels are gaining share fastest among small and mid-scale fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies. China and India prioritize metal fabrication throughput, while Germany and the United States emphasize chemical synthesis and captive industrial gas supply. Japan maintains balanced demand across welding applications and precision manufacturing.
China
Shipbuilding yards in Jiangsu and Zhejiang provinces drive bulk acetylene consumption for oxy-acetylene cutting of thick steel plate. SAMR enforcement of stricter GB cylinder standards is accelerating fleet replacement cycles among regional distributors. The Yangtze River Delta industrial corridor around Shanghai hosts dense networks of filling stations serving dispersed construction sites.
India
Gujarat's shipbuilding clusters and Maharashtra's automotive component manufacturers sustain concentrated welding demand. BIS certification requirements for industrial gas cylinders are tightening purity specifications for domestic producers. The western industrial corridor from Ahmedabad to Pune represents the fastest-expanding acetylene consumption zone in South Asia.
Germany
Integrated chemical complexes along the Rhine corridor consume acetylene for vinyl chloride and acetic acid synthesis. ECHA enforcement of REACH registration requirements is extending compliance burdens to downstream formulators. The BASF Ludwigshafen complex anchors captive acetylene production for internal chemical conversion.
United States
Heavy fabrication contractors in Texas and Louisiana rely on bulk acetylene delivery for petrochemical infrastructure construction. OSHA workplace exposure limits and cylinder handling protocols shape operational compliance costs for regional distributors. The Gulf Coast industrial belt concentrates demand among shipyard and offshore platform fabricators.
Japan
Precision machinery producers in Aichi Prefecture and Osaka Prefecture maintain steady acetylene consumption for high-temperature welding applications. METI industrial safety standards govern cylinder requalification intervals and transport protocols. The Chubu and Kansai manufacturing belts represent mature, replacement-driven demand centers.
Acetylene Gas Market Key Industry Players
Capability concentration sits with integrated petrochemical operators; scale advantage sits with global industrial gas distributors. The market structures around three tiers: multinational gas majors with dense logistics networks, regional specialists with captive chemical synthesis capacity, and national distributors serving fragmented fabrication end users. Dominant competitive moves include backward integration into cracking technology and consolidation of cylinder fleet ownership.
Among integrated chemical operators, BASF SE and Sichuan Vinylon exemplify the captive-production archetype, converting acetylene internally for downstream chemical synthesis. Linde plc and Air Liquide occupy positions as global gas majors, competing through bulk delivery infrastructure and long-term supply contracts. These four companies represent the primary competitive anchors across distinct strategic vectors.
| Leading Market Players |
|---|
| BASF SE |
| Toho Acetylene |
| Linde plc |
| Sichuan Vinylon |
| Koatsu Gas Kogyo |
| Air Liquide |
| Gulf Cryo |
| Jinhong Gas |
| Airgas |
| Others |
Cost & Logistics Intelligence
Calcium carbide input volatility determines both pricing tier spreads and supply chain shape, as electricity-intensive production in coal-dependent grids forces producers to choose between absorbing margin compression or passing through power tariff fluctuations to fabrication end users.
Pricing Analysis
Long-term offtake contracts dominate chemical synthesis procurement, with vinyl chloride producers locking in captive supply to insulate against feedstock volatility. Spot pricing prevails among construction contractors and job shops with fragmented demand. Price differentiation rests on purity certification and volume scale, with automotive OEM contracts commanding premium positioning for precision welding grades. Cost compression in the construction tier is intensifying because plasma cutting substitution erodes addressable demand for light-gauge applications. Small-scale fabricators exhibit highest price sensitivity, while integrated chemical operators demonstrate lowest sensitivity due to captive conversion economics.
Supply Chain Analysis
Tariff exposure between China and downstream export markets dominates supply chain risk calculus for carbide-derived acetylene producers. Production concentrates in China, India, and Germany, with the Yangtze River Delta and Gujarat-Maharashtra corridor anchoring Asian supply. Raw material dependencies draw from metallurgical-grade lime, petroleum coke, and electricity access for carbide production. Single-source vulnerability characterizes the calcium carbide feedstock layer, where regional power grid configurations dictate production economics. Distribution runs through dense filling station networks and bulk delivery infrastructure serving industrial clusters, with cylinder fleet logistics increasingly unbundled from gas supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acetylene gas market sits at a cyclical recovery phase driven by metal fabrication capacity expansion in India's western industrial corridor, where shipbuilding and automotive component demand is rebounding from prior contraction.
For Market Incumbents: Entrench position through backward integration into petrochemical cracking routes that align with tightening carbon accounting rules, while consolidating cylinder fleet ownership to capture lifecycle services margin pools previously held by third-party refurbishers. Plasma cutting substitution in light manufacturing represents the core technology threat requiring defensive positioning.
For New Entrants and Emerging Players: Pursue aftermarket cylinder requalification and refurbishment services in China's coastal manufacturing zones, where SAMR enforcement of stricter GB standards accelerates fleet replacement cycles. The online channel for small-scale fabricator procurement offers the most penetrable entry vector, with platform-based requalification scheduling as the differentiated go-to-market angle.
For Investors and Strategic Acquirers: The market sits at an early expansion phase that favors asset-heavy cylinder fleet operators with established logistics density. Long-term viability over the coming decade hinges on dual carbon pathway positioning capability. The signal to watch is regional carbon border adjustment implementation timelines, which will determine cost competitiveness between carbide-derived and petrochemical-derived production routes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracking Technology | Petrochemical cracking routes align with China's dual carbon goals and EU carbon border adjustments. |
| Cylinder Fleet Consolidation | Capturing lifecycle services margin pools requires dense filling station networks across industrial clusters. |
| Long-term Supply Agreement | Automotive OEM contracts for electric vehicle battery enclosure fabrication secure volume commitments. |
| Joint Venture | Partnerships with refinery operators enable plasma-assisted acetylene cracking deployment at commercial scale. |
| Green Manufacturing Transition | Low-carbon acetylene certification opens premium pricing in jurisdictions with carbon accounting mandates. |
Research Approach
A standing panel of plant managers at calcium carbide facilities, procurement leads at downstream chemical producers, distribution channel partners, and technical R&D directors provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and national industrial gas association publications. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic indicators to ensure consistency.
Scenario bracketing anchored the forecast framework across the projection horizon, with modeling segmented by product type, application, end user, and regional production hub. CAGRs derived from trend extrapolation adjusted for identified inflection drivers including regulatory compliance cost trajectories and technology substitution patterns. Feedstock cost volatility and carbon pricing mechanism adoption served as primary industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity tariffs, coal price trajectories, or regional carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions about technology adoption rates and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
High Purity Gas Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Global Argon Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Krypton Gas Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Xenon Gas Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Food-Grade Gases Market