
 Welding Shielding Gas Market | 2026-2036
Welding Shielding Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Shielding Gas Market Intelligence
Modular cylinder-plus-regulator bundling is recalibrating procurement patterns among mid-sized metal fabricators. Linde PLC leverages captive air separation capacity across European industrial corridors. Air Liquide SA anchors its position through on-site gas generation contracts with automotive stamping plants. Messer Group GmbH differentiates via specialized helium-argon blends for precision aerospace welding.
Welding shielding gas comprises inert or semi-inert gas mixtures—typically argon, carbon dioxide, helium, or oxygen blends—delivered at flow rates between 10–40 L/min to displace atmospheric contaminants during arc welding processes. The gas prevents oxidation and porosity in the weld pool, ensuring structural integrity in critical joints across transportation and infrastructure applications. Argon-based blends command the largest volume share in metal fabrication, while helium segments carry premium margins due to supply constraints and aerospace certification requirements. Automotive application demand is expanding fastest, driven by aluminum-intensive vehicle platforms and resistance to atmospheric contamination in robotic welding cells.
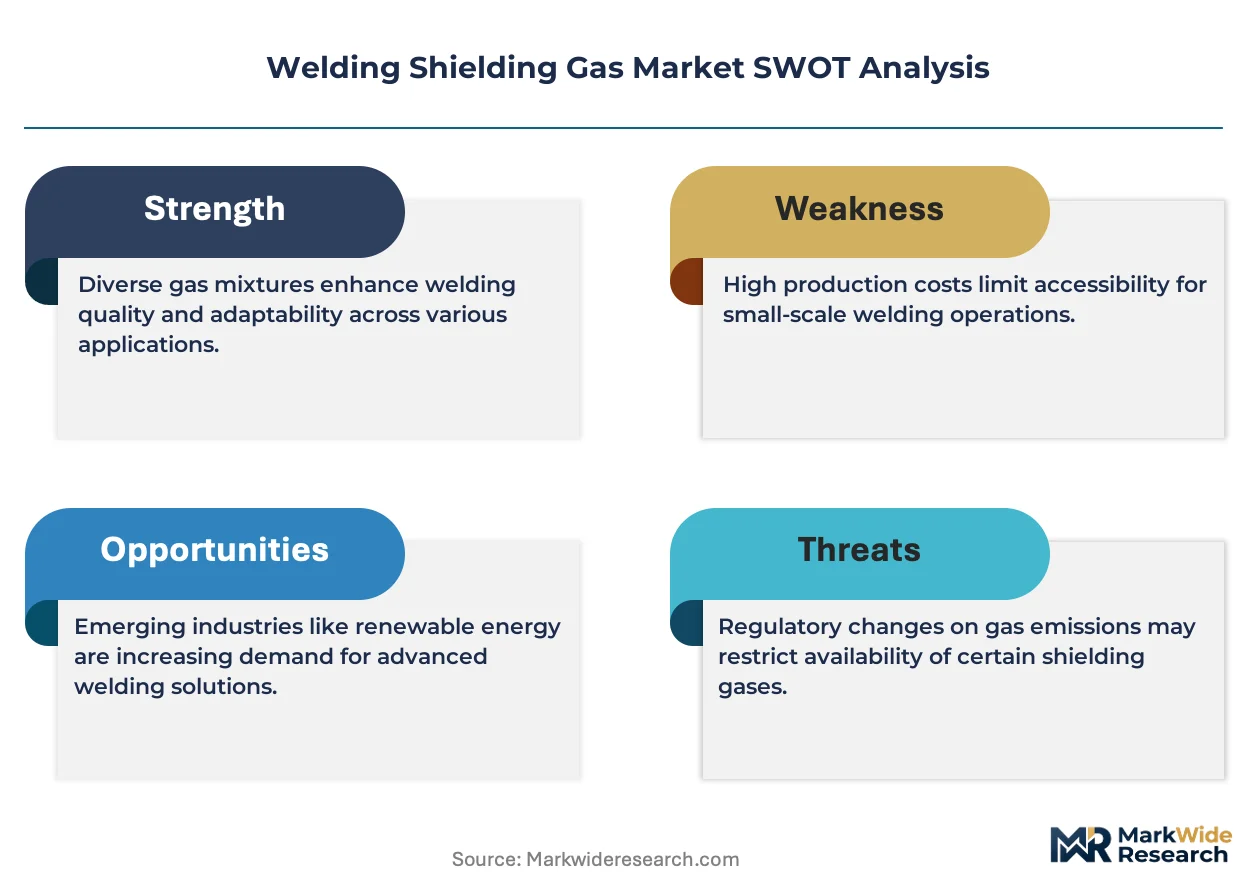
FDA oversight of medical-grade gas purity, EPA industrial emissions thresholds, and China's MEE enforcement of dual carbon goals collectively elevate barrier-to-entry for new shielding gas suppliers. REACH registration requirements in Europe and GB standard compliance in China add formulation and testing costs that favor scaled producers with dedicated regulatory affairs teams. Stakeholders must monitor helium supply diversification efforts and carbon dioxide capture regulations as these dynamics will determine regional cost structures and blend availability.
Market Dynamics
Automotive OEMs are accelerating aluminum chassis adoption, forcing shielding gas suppliers to recalibrate blend formulations and delivery infrastructure around robotic welding cells and inert atmosphere requirements.
Growth Catalysts
- EPA Industrial Emissions Thresholds:Stricter EPA thresholds on industrial emissions are compelling metal fabricators to upgrade to high-purity argon blends that minimize atmospheric contamination and reduce rework rates.
- Aluminum-Intensive Vehicle Platforms:Automotive stamping plants are expanding TIG and MIG welding operations for lightweight chassis, generating concentrated demand for precision argon-helium mixtures.
- Shanghai Manufacturing Cluster:East Asian fabrication hubs around Shanghai are consolidating procurement volumes, creating economies of scale for on-site gas generation contracts.
Market Restraints
- Helium Supply Concentration:Helium extraction concentrates in natural gas fields across the US and Qatar, exposing aerospace-grade blend pricing to geopolitical supply disruptions.
- REACH Registration Burden:ECHA registration requirements for novel gas formulations impose testing costs that disadvantage smaller blenders lacking dedicated regulatory affairs teams.
- Carbon Dioxide Capture Regulations:Emerging CO2 capture mandates in industrial corridors are constraining feedstock availability for CO2-argon blends used in heavy fabrication.
Strategic Opportunities
- India's PLI Scheme for Manufacturing:India's production-linked incentive scheme for automotive and electronics manufacturing is opening greenfield demand for shielding gas infrastructure.
- Hydrogen-Argon Blend Development:Converging hydrogen fuel cell research with welding metallurgy is creating pathways for reduced-porosity blends in high-strength steel applications.
- Modular Cylinder-Plus-Regulator Bundling:Mid-sized fabricators are adopting bundled procurement models that integrate equipment leasing with gas supply, displacing traditional cylinder exchange programs.
Industry Challenges
- Welding Engineer Talent Scarcity:Specialized expertise in robotic welding cell calibration and gas flow optimization remains concentrated among aging technician cohorts in mature industrial economies.
- ISO 14175 Certification Timelines:Extended validation periods for new gas mixture classifications under ISO 14175 are delaying commercialization of customized blends for exotic alloy welding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Shielding Gas Market |
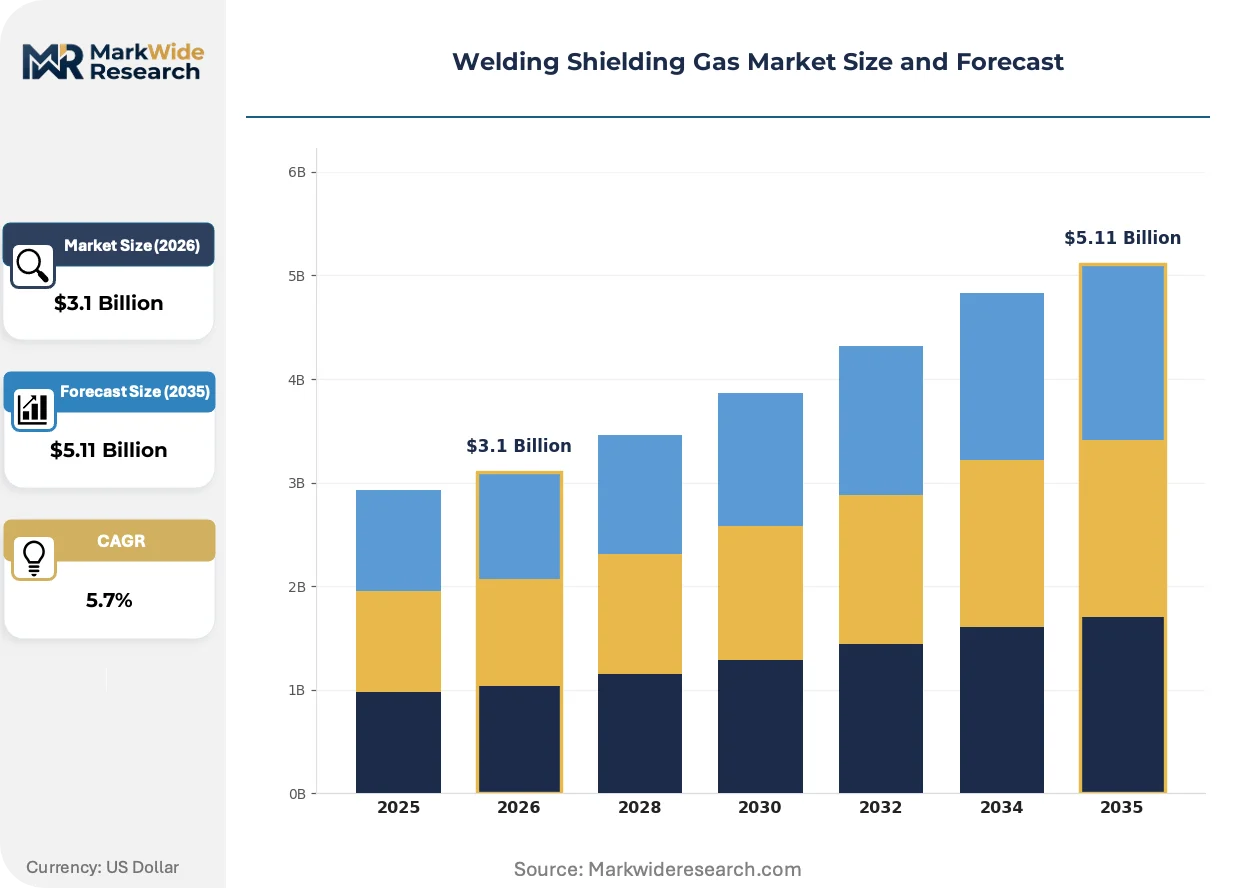
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Gas Type: Argon, Carbon Dioxide, Helium, Oxygen Application: Metal Fabrication, Automotive, Aerospace, Construction End User: Manufacturers, Contractors, Repair Shops, Educational Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Praxair Inc., Iwatani Corporation, Air Products and Chemicals Inc., Messer Group GmbH, Gulf Cryo, Linde PLC, Taiyo Nippon Sanso Corporation, SIG Gases Berhad, Air Liquide SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Shielding Gas Market Strategic Shifts & Innovations
Digital flow control systems and predictive gas monitoring are compressing waste rates and reshaping how fabricators manage consumable costs across high-volume production lines.
Smart regulator technology with embedded IoT sensors is consolidating real-time consumption tracking and automated replenishment scheduling. Tier-one automotive suppliers are deploying these systems across multi-robot welding cells to eliminate manual flow adjustments. The technology is consolidating supplier-customer relationships around data-integrated service contracts rather than commodity gas transactions.
China's GB standards on industrial emissions are mandating purity thresholds that disqualify legacy gas sourcing arrangements. MEE enforcement of dual carbon goals is accelerating facility upgrades in Guangzhou and Shenzhen manufacturing corridors. High-purity argon segments face the steepest compliance costs, pushing blenders toward captive air separation investments.
Metal fabricators are unbundling after-sales service from equipment purchase agreements, treating gas supply and maintenance as separate procurement categories. Mid-sized stamping plants in the US Midwest are driving this shift, negotiating shorter-term gas contracts with flexible volume commitments. The pattern is most visible among automotive tier suppliers managing volatile production schedules.
Welding Shielding Gas Market Segmentation
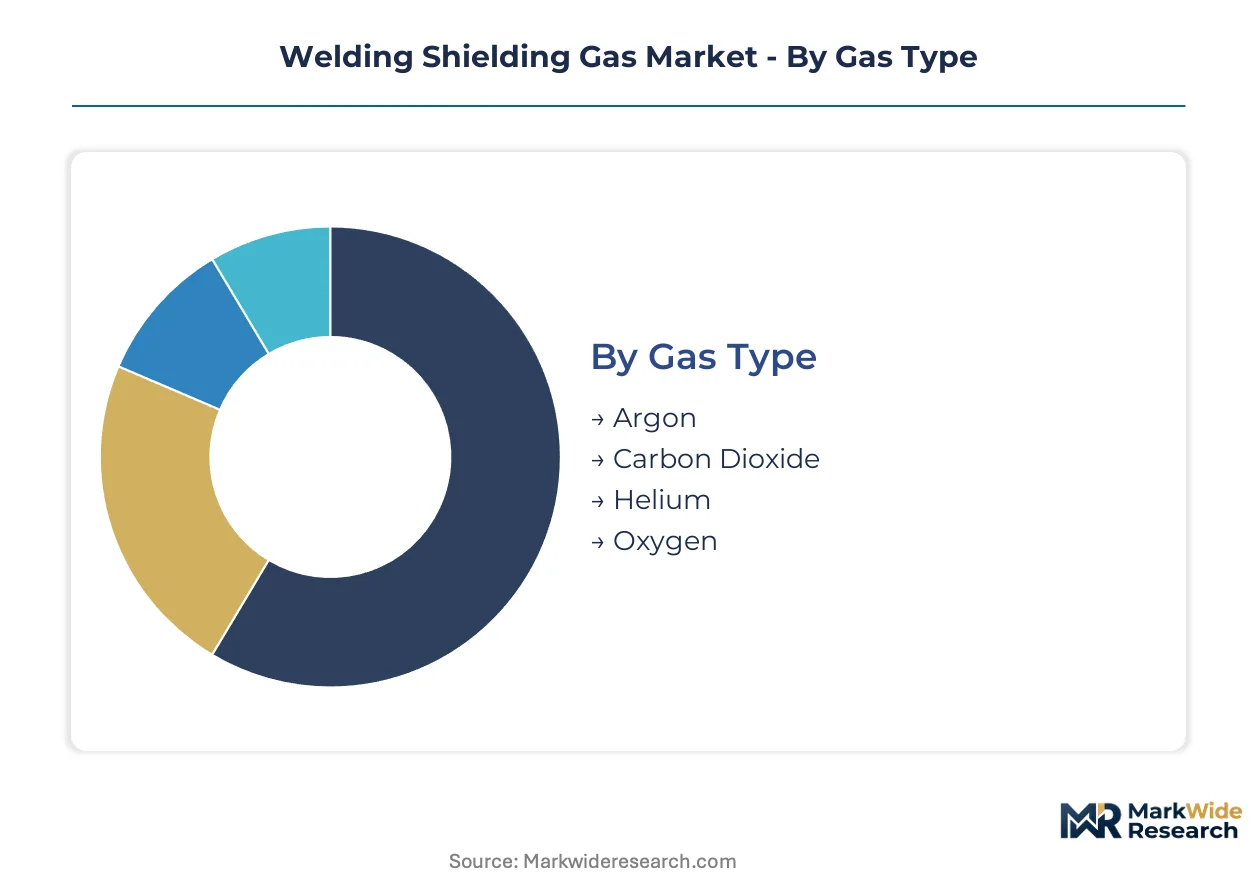
Shielding gas procurement patterns diverge sharply across end-use applications, with automotive stamping plants demanding high-volume on-site generation while repair shops prioritize portable cylinder logistics. Blend specifications and delivery infrastructure must align precisely with each segment's operational scale and purity requirements.
Gas Type:
Supply concentration in air separation infrastructure favors argon-dominant blends, while helium sourcing constraints create tiered availability across industrial corridors.
- Argon:Inert monatomic gas forms the backbone of TIG and MIG welding applications, typically blended with carbon dioxide or oxygen to optimize arc stability and penetration characteristics. Metal fabrication clusters around Shanghai and Guangzhou anchor concentrated demand, driven by GB standard purity mandates and robotic welding cell expansion. Argon absorbs the bulk of installed capacity; helium is expanding most quickly.
- Carbon Dioxide:Reactive gas component enhances weld penetration in short-circuit transfer modes for heavy steel fabrication, though emerging CO2 capture regulations in industrial corridors are constraining feedstock availability for blenders. Construction sector procurement in the US Midwest favors CO2-argon mixtures for structural welding cost efficiency.
- Helium:Low-density inert gas enables higher heat input for exotic alloy and aerospace-grade welding, with supply concentrating in natural gas fields across the US and Qatar exposing pricing to geopolitical disruption.
- Oxygen:Minor reactive addition to argon blends stabilizes the arc and improves wetting behavior in spray transfer applications, common in high-speed automotive production lines.
Argon-based formulations command the largest production volumes; helium segments carry the steepest supply risk premiums.
Application:
Cost tier differentiation separates commodity fabrication from certified aerospace welding, with purity grades and documentation requirements driving margin stratification.
- Automotive:OEM stamping plants are accelerating aluminum-intensive chassis adoption, forcing recalibration of blend formulations around robotic welding cells and inert atmosphere requirements. EPA industrial emissions thresholds compel high-purity argon blends that minimize rework rates. Automotive applications absorb the bulk of precision blend demand; aerospace is climbing the fastest.
- Metal Fabrication:General-purpose job shops drive volume consumption of standard argon-CO2 mixtures for carbon steel welding, with procurement consolidating around modular cylinder-plus-regulator bundling.
- Aerospace:Precision welding of titanium and nickel superalloys demands helium-argon blends with full lot traceability and aerospace certification, limiting qualified supplier pools.
- Construction:Infrastructure welding prioritizes cost-efficient CO2-enriched blends for field applications, with contractors favoring portable cylinder exchange programs over on-site generation.
Metal fabrication anchors volume consumption; aerospace commands the highest purity premiums.
End User:
Customer type determines contract structure, with manufacturers locking in long-term on-site generation while repair shops favor transactional spot purchasing.
- Manufacturers:Tier-one automotive suppliers and metal fabricators negotiate integrated service contracts combining gas supply with predictive monitoring systems, displacing traditional cylinder exchange models.
- Contractors:Construction and field service welding operations prioritize logistics flexibility, sourcing through distributor networks with rapid cylinder turnaround.
- Repair Shops:Small-scale maintenance welding drives fragmented demand for portable cylinder sizes, with procurement sensitivity to equipment leasing bundling.
- Educational Institutions:Vocational training programs require standardized blend specifications for curriculum consistency, often sourcing through regional distributor consortia.
Manufacturers concentrate procurement volumes; educational institutions represent the most price-elastic demand segment.
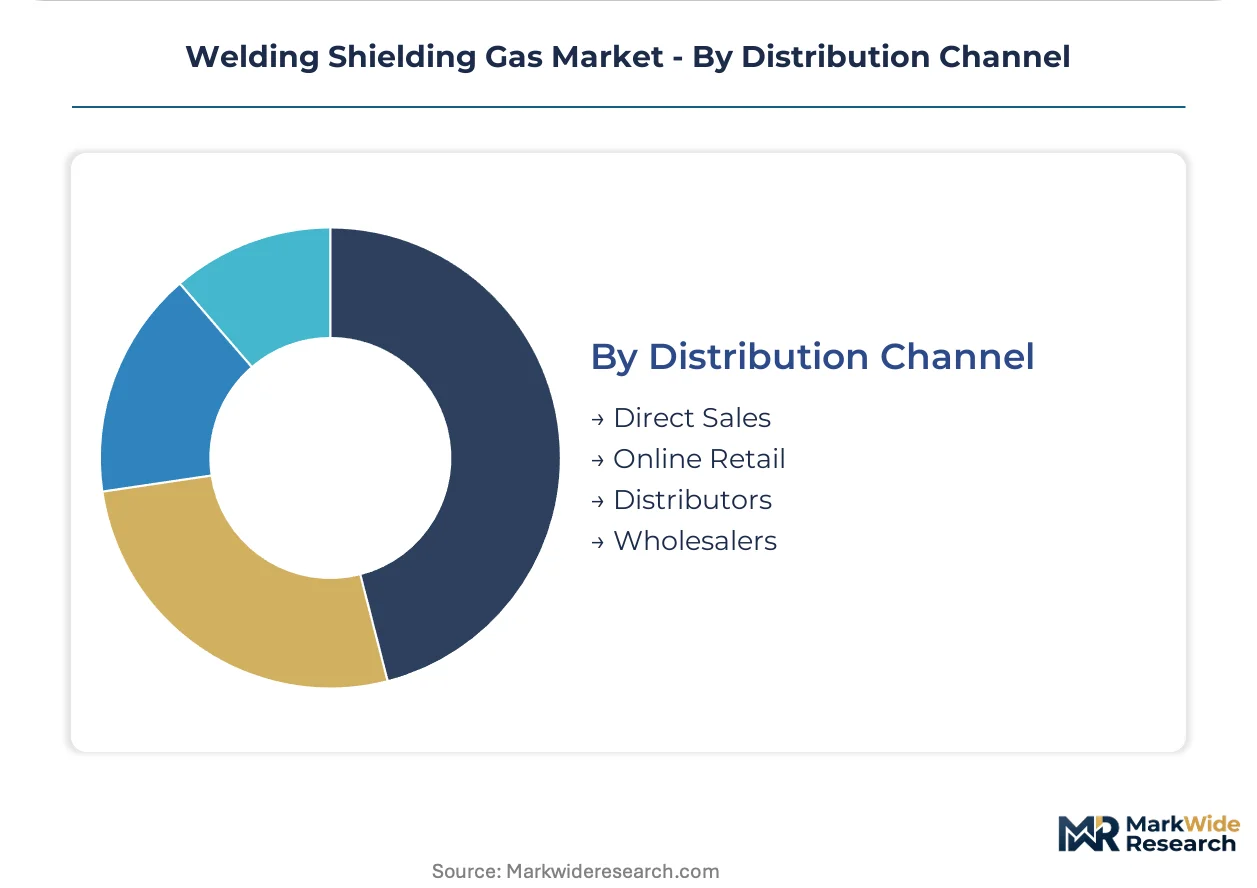
Distribution Channel:
Volume scale and geographic concentration dictate channel selection, with direct sales dominating high-throughput manufacturing corridors.
- Direct Sales:On-site gas generation contracts and bulk liquid supply agreements serve high-volume automotive and aerospace manufacturing facilities, embedding suppliers deeply in customer operations.
- Distributors:Regional gas distributors manage cylinder logistics and local inventory for mid-sized fabricators, bridging the gap between producer scale and fragmented demand.
- Online Retail:E-commerce platforms are gaining traction for standardized cylinder sizes and regulator accessories among small repair shops and hobbyist segments.
- Wholesalers:Bulk blenders and independent gas wholesalers supply private-label products to smaller distributors, particularly in emerging manufacturing corridors.
Direct sales absorb the bulk of revenue value; online retail is gaining share fastest among non-contract customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in industrial corridors with captive air separation infrastructure, while consumption clusters around automotive stamping plants and aerospace fabrication facilities. The divergence between gas production basins and manufacturing demand centers shapes regional trade flows and on-site generation investment patterns.
United States
Automotive OEMs in Michigan and Ohio are expanding aluminum chassis welding operations, driving concentrated demand for argon-helium precision blends. EPA industrial emissions thresholds compel fabricators to upgrade purity specifications and reduce rework rates. Gulf Coast helium extraction from natural gas fields anchors supply for aerospace-grade applications, though geopolitical exposure to Qatar concentrates pricing risk.
Germany
Automotive stamping plants in Bavaria and Baden-Württemberg anchor European demand for robotic welding cell integration. ECHA REACH registration requirements impose formulation testing costs that favor scaled producers with dedicated regulatory affairs capabilities. The Ruhr industrial corridor maintains legacy CO2-argon blend demand for heavy steel fabrication, though emerging carbon capture regulations constrain feedstock availability.
China
Shanghai and Guangzhou manufacturing clusters are consolidating procurement volumes for high-purity argon segments. MEE enforcement of dual carbon goals and GB standards on industrial emissions mandate purity thresholds that disqualify legacy gas sourcing arrangements. Yangtze River Delta fabricators are accelerating facility upgrades toward captive air separation investments to meet tightening compliance costs.
Japan
Precision welding of titanium and nickel superalloys in Nagoya and Osaka aerospace corridors sustains premium helium-argon blend demand. METI industrial policy supports hydrogen-argon blend research for reduced-porosity applications in high-strength steel. Chubu region suppliers face extended ISO 14175 certification timelines that delay commercialization of customized exotic alloy formulations.
India
Tamil Nadu and Maharashtra automotive hubs are absorbing new shielding gas infrastructure under the PLI scheme for manufacturing. BIS standards on industrial gas purity are elevating barrier-to-entry for blenders lacking scaled testing capabilities. Gujarat fabrication clusters are negotiating modular cylinder-plus-regulator bundling contracts that displace traditional cylinder exchange programs.
Welding Shielding Gas Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated air separation infrastructure favors scaled producers with captive production assets, while regional blenders occupy fragmented mid-market segments. Three archetypes dominate: integrated industrial gas majors with global distribution networks, regional specialists in helium-argon precision blends, and equipment-integrated service providers bundling gas supply with predictive monitoring systems. Competitive intensity centers on M&A consolidation of regional distributors and backward integration into air separation capacity.
Within the integrated major tier, Linde PLC and Air Liquide SA exemplify scale-driven positions anchored in European industrial corridors. Messer Group GmbH occupies a specialized position among German-origin industrial gas suppliers. Taiyo Nippon Sanso Corporation represents Japanese-based precision blend capabilities for aerospace certification requirements.
| Leading Market Players |
|---|
| Praxair Inc. |
| Iwatani Corporation |
| Air Products and Chemicals Inc. |
| Messer Group GmbH |
| Gulf Cryo |
| Linde PLC |
| Taiyo Nippon Sanso Corporation |
| SIG Gases Berhad |
| Air Liquide SA |
| Others |
Cost & Logistics Intelligence
China's MEE enforcement of dual carbon goals gates qualified supply access and premium-tier pricing for high-purity argon segments, forcing blenders toward captive air separation investments or exclusion from Shanghai and Guangzhou manufacturing corridors. This environmental mandate stratifies the market between compliant producers capturing automotive OEM contracts and legacy suppliers relegated to construction-grade CO2-argon spot sales.
Pricing Analysis
Margin tightening in helium-argon precision blends reflects geopolitical supply concentration across US and Qatar natural gas fields. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified helium blends from automotive-grade argon mixtures and construction CO2-enriched commodities. Price differentiation hinges on ISO 14175 certification status and captive air separation integration. Cost-down pressure on standard-grade blends accelerates because mid-sized fabricators are unbundling equipment leases from gas supply contracts. Repair shops exhibit highest price sensitivity; aerospace tier-one suppliers demonstrate least elasticity due to lot traceability requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through on-site gas generation contracts, while regional distributors manage fragmented cylinder logistics for job shops. Geographic supply concentrates in China, the United States, and Germany where air separation infrastructure clusters around industrial corridors. Raw material dependencies center on atmospheric argon extraction, natural gas field helium recovery, and industrial CO2 capture feedstocks. Supply chain risk crystallizes in single-source helium vulnerability to Qatar export disruptions. Distribution runs through bulk liquid tanker networks for manufacturers and cylinder exchange pools for field contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around scaled producers with captive air separation assets, as REACH registration burdens and GB standard compliance costs force smaller blenders toward exit or acquisition. Regulatory fixed costs are the primary pressure eliminating sub-scale competitors.
For Market Incumbents: Anchor market position through backward integration into Yangtze River Delta air separation capacity, securing feedstock autonomy against MEE purity mandates. Deepen robotic welding cell service contracts with predictive monitoring bundling to lock in automotive OEM volumes. Counter emerging modular cylinder-plus-regulator entrants by embedding equipment leasing within long-term gas supply agreements. Threat response requires neutralizing price-transparent procurement platforms before they gain tier-two supplier traction. For New Entrants and Emerging Players: Enter via India's PLI scheme automotive corridors in Tamil Nadu and Maharashtra, where greenfield shielding gas infrastructure demand outpaces established supplier coverage. Target mid-sized metal fabricators adopting unbundled procurement models, offering flexible volume commitments absent from incumbent direct-sales structures. Penetrate through hydrogen-argon blend development partnerships with METI-funded research programs, leapfrogging ISO 14175 certification timelines via collaborative validation. Go-to-market angle rests on specialty alloy expertise rather than commodity argon scale. For Investors and Strategic Acquirers: Captive air separation announcements in East Asian manufacturing clusters are the leading indicator that regional supply autonomy is becoming the decisive competitive moat. Frame long-term viability around five-to-ten year consolidation windows where regulatory fixed costs compound disadvantage for non-integrated blenders. Acquisition target archetype: regional distributors with established automotive tier-two relationships and pending GB standard compliance investments. Signal to watch: BIS standard enforcement timelines in Gujarat and Maharashtra fabrication corridors triggering forced seller dynamics among sub-scale Indian blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Air Separation Investment | Yangtze River Delta facility upgrades secure MEE-compliant argon supply for automotive OEM contracts. |
| Helium Supply Diversification Partnership | Qatar-US dual sourcing reduces aerospace blend pricing exposure to geopolitical disruption. |
| Smart Regulator IoT Integration | Embedded consumption tracking locks tier-one suppliers into data-integrated service contracts. |
| India PLI Corridor Infrastructure Buildout | Tamil Nadu on-site generation contracts capture automotive manufacturing incentive flow. |
| Hydrogen-Argon Blend R&D Collaboration | METI-funded research programs accelerate reduced-porosity certification for high-strength steel. |
Research Approach
Independent corroboration across welding engineer interviews, automotive procurement leads, and industrial gas distributor executives underwrites the qualitative findings. Primary fieldwork engaged plant managers at Shanghai and Guangzhou stamping facilities, technical R&D directors at European air separation majors, and aftermarket service heads at regional cylinder logistics providers. Secondary validation drew from EPA industrial emissions filings, ECHA REACH registration databases, China MEE enforcement bulletins, and SEC 10-K disclosures from listed industrial gas conglomerates. Bottom-up demand modeling across automotive, aerospace, and fabrication end-uses triangulates against top-down supply capacity assessments from air separation infrastructure databases.
Comparable-period anchoring to historical argon demand cycles and helium supply disruption events structured the projection horizon. Segmentation dimensions modeled include gas type purity grade, application certification tier, end-user contract structure, and regional regulatory cluster. CAGRs derive from slope-intercept fitting against normalized industrial production indices and automotive platform aluminum content trajectories. Industry-specific forecast inputs incorporate robotic welding cell deployment rates and GB standard compliance cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended ISO 14175 certification delays or abrupt helium export quota restrictions. Forecasts reflect assumptions regarding MEE enforcement consistency, PLI scheme disbursement timelines, and automotive aluminum chassis adoption trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Oxygen Market
Industrial Gases
Helium Market
Industrial Gases
Global Helium Gas Market
Industrial Gases
Syngas Market
Industrial Gases
North America Syngas Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Xenon Gas Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
Krypton Gas Market