
 Nitrogen Gas Market | 2026-2036
Nitrogen Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrogen Gas Market Analytics
High-purity nitrogen specifications above 99.999% is unwinding legacy supply arrangements across semiconductor and pharmaceutical end uses. Linde plc leverages captive air separation units near major electronics hubs to sustain volume commitments. Air Liquide anchors European medical and industrial demand through pipeline networks and regional production assets. Yingde Gases dominates domestic supply in China with extensive on-site generation contracts.
Nitrogen gas is a colorless, odorless, diatomic element comprising 78% of atmospheric composition, typically recovered through cryogenic air separation or pressure swing adsorption to achieve purity grades from industrial 99% to ultra-high-purity 99.9999% for semiconductor applications; it functions primarily as an inert blanketing, purging, and atmosphere-control medium across manufacturing processes. Liquid nitrogen within the product type dimension leads total volume due to its density advantage for transport and storage, though on-site generation within the delivery mode dimension captures the fastest expansion as industrial users seek supply security and cost predictability. Electronics manufacturing within the application dimension concentrates the highest-margin demand as fabs require continuous ultra-high-purity flows with zero tolerance for contamination.
The U.S. OSHA and EPA frameworks govern workplace exposure limits and emissions from air separation facilities, while the EU REACH and F-Gas Regulation shape equipment and handling standards for industrial gas systems in Europe; China's GB standards and MEE directives enforce local purity certification and environmental compliance for production facilities. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs and certification requirements increasingly determine supplier selection and facility siting decisions.
Market Dynamics
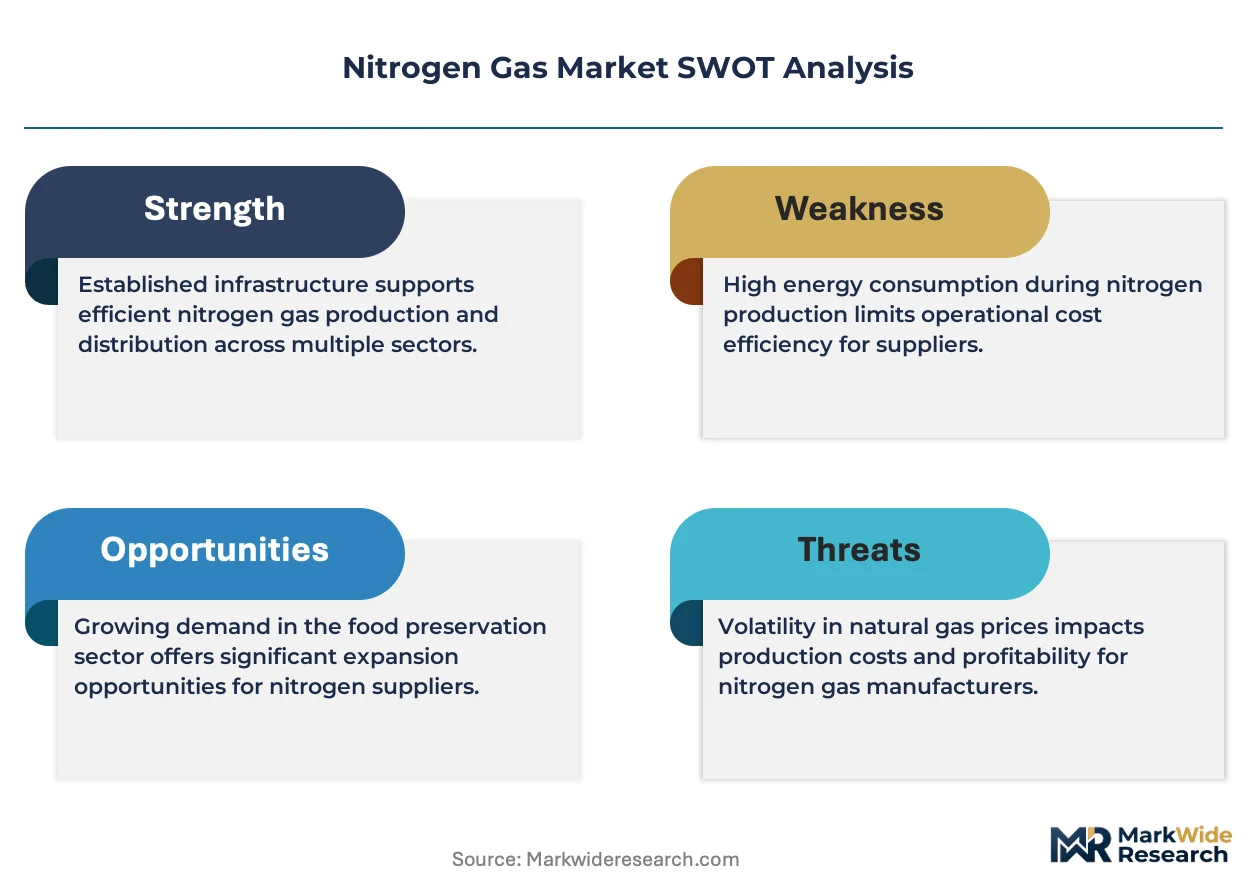
The nitrogen gas market pivots on tightening purity specifications for semiconductor lithography, which compresses legacy supply arrangements and accelerates on-site generation adoption among electronics manufacturers seeking contamination control.
Growth Catalysts
- OSHA workplace exposure standards:The U.S. OSHA tightened industrial gas handling protocols, pushing chemical processors toward closed-loop nitrogen systems with real-time monitoring.
- Semiconductor lithography expansion:Taiwan and South Korea electronics fabs now consume ultra-high-purity nitrogen at volumes that justify dedicated air separation units adjacent to production lines.
- Pressure swing adsorption:Modular PSA technology enables mid-scale manufacturers to bypass liquid nitrogen logistics through containerized on-site generation with sub-99.999% purity adequacy.
Market Restraints
- Cryogenic energy intensity:Air separation units consume electricity equivalent to 30-40% of operating costs, exposing producers to grid price volatility in Germany and Texas.
- Chinese supply concentration:Yingde Gases controls pipeline networks across the Yangtze River Delta, creating single-source dependency risks for chemical manufacturers in Jiangsu and Zhejiang provinces.
- Liquid nitrogen transport limits:Boil-off losses of 0.5-2% daily constrain distribution radius to 300 kilometers, fragmenting supply economics for remote industrial clusters.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightening GMP standards for sterile packaging creates first-mover advantage for nitrogen suppliers establishing on-site generation at Hyderabad and Ahmedabad API hubs.
- Hydrogen economy interface:Ammonia cracking and hydrogen liquefaction require nitrogen blanketing at scale, opening adjacent demand from European electrolyzer installations.
- Carbon capture integration:The EU F-Gas Regulation incentivizes nitrogen-driven inerting systems that displace fluorinated gases in cold chain applications.
Industry Challenges
- Cryogenic technician scarcity:Specialized certification for liquid nitrogen handling exceeds available training pipeline capacity in Vietnam and Indonesia expansion markets.
- Legacy system integration:Chemical plants with 1990s-era nitrogen distribution infrastructure face 18-24 month retrofit timelines to achieve semiconductor-grade purity compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogen Gas Market |
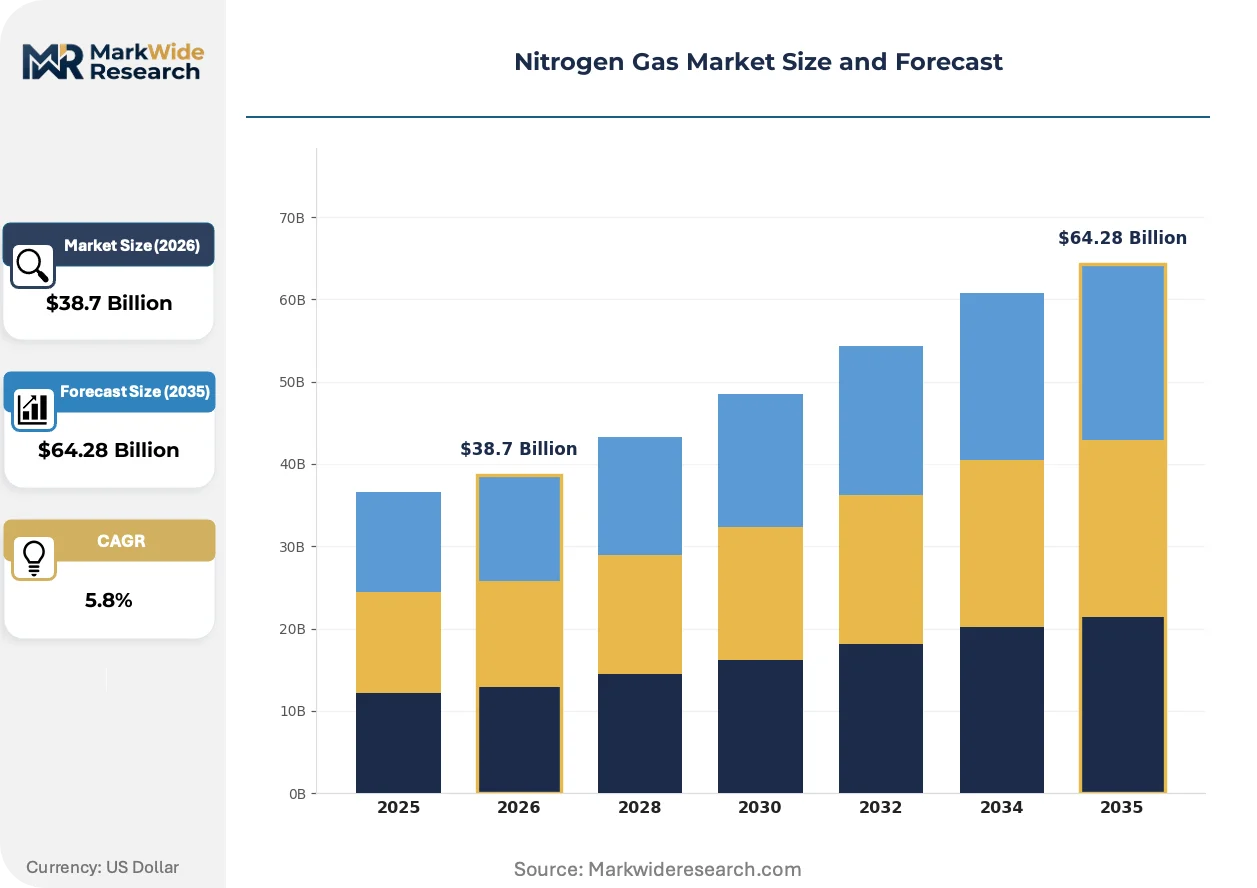
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Nitrogen, Liquid Nitrogen, Medical Nitrogen, Nitrogen Generators Application: Food Preservation, Pharmaceuticals, Electronics Manufacturing, Chemical Processing End User: Healthcare, Automotive, Electronics, Food & Beverage Delivery Mode: Bulk Supply, Cylinder Supply, On-site Generation, Pipeline Delivery |
| Companies Covered | Messer Group, Axcel Gases, Linde plc, Gulfcryo, Ellenbarrie Industrial Gases, Air Products and Chemicals, Inc., Taiyo Nippon Sanso, Yingde Gases, Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogen Gas Market Evolving Landscape
Membrane separation technology is compressing the economics of mid-purity nitrogen supply, while regulatory fragmentation across jurisdictions forces suppliers to maintain multiple certification portfolios.
Membrane nitrogen generators using hollow-fiber polymeric modules are supplanting small-scale cryogenic plants for applications requiring 95-99.5% purity. Food packaging operations in Brazil and Southeast Asia adopt these systems for their 40% lower capital footprint and absence of hazardous liquid handling. The shift enables regional nitrogen autonomy for manufacturers previously dependent on distant air separation facilities.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants mandates nitrogen-based cooling alternatives in pharmaceutical cold chains and semiconductor process cooling. Equipment manufacturers in Germany and France now bundle nitrogen generation with temperature-controlled logistics systems. Medical gas distributors respond by acquiring PSA technology capabilities to maintain service contracts.
Electronics manufacturers now specify outcome-based nitrogen supply agreements tied to uptime guarantees rather than volume commitments. Taiwan Semiconductor Manufacturing and Samsung Foundry negotiate contracts where suppliers bear downtime penalties for purity excursions. This transfers operational risk to Linde and Air Liquide while locking in decade-long facility adjacency requirements.
Nitrogen Gas Market Segmentation
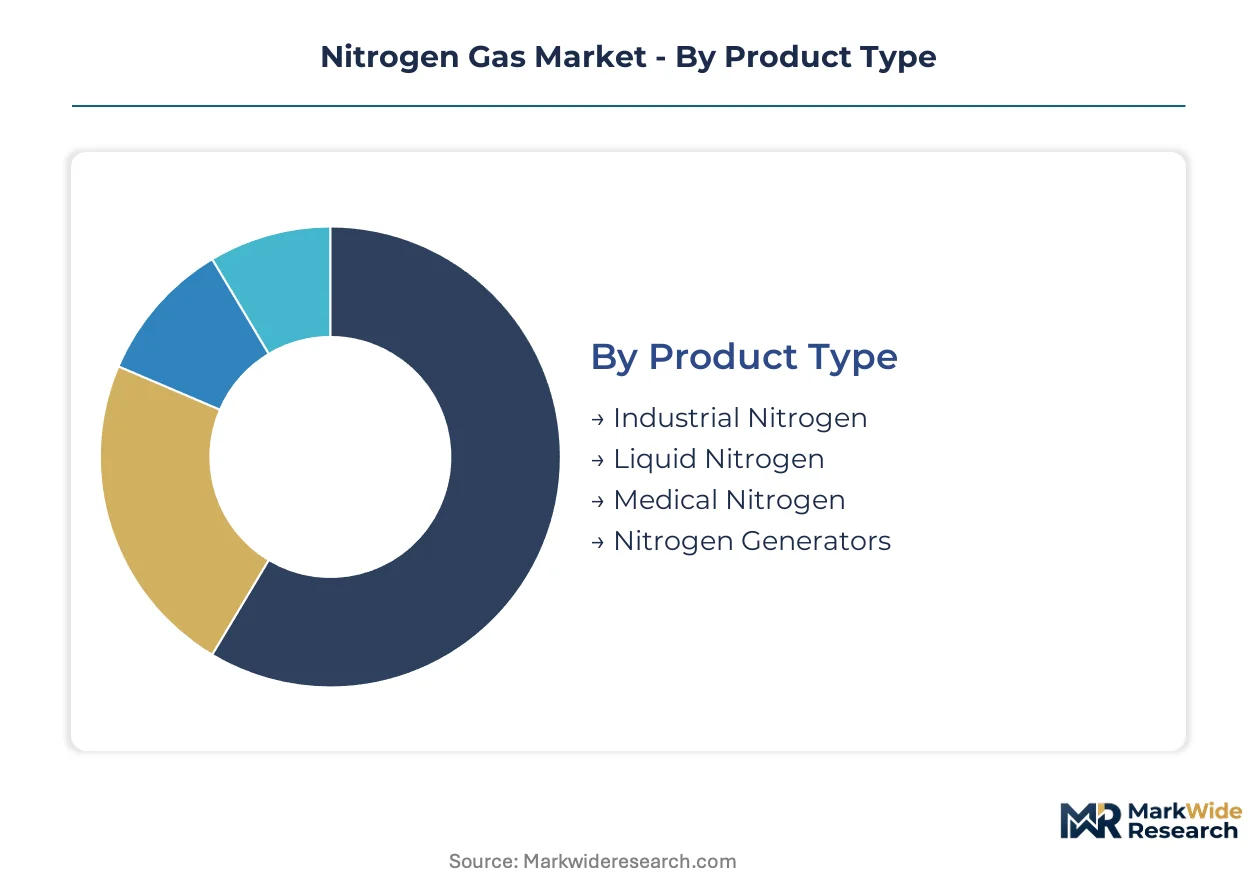
Nitrogen gas segmentation reveals how purity grades and delivery logistics fragment competitive positioning across end uses. Electronics manufacturers impose specification premiums that reshape supply economics for adjacent segments.
Product Type:
Membrane and PSA technologies are displacing cryogenic supply in mid-purity segments below 99.9%, compressing margins for traditional air separation products.
- Liquid Nitrogen:Cryogenic liquid at -196°C enables dense storage and long-haul distribution to remote industrial clusters. Taiwan and South Korea electronics fabs consume liquid nitrogen for wafer processing where pipeline infrastructure remains unavailable, though boil-off losses constrain radius economics.
- Industrial Nitrogen:Compressed gas at 95-99.5% purity serves chemical blanketing and metal heat treatment. China's Yangtze River Delta chemical manufacturers anchor demand through bulk supply contracts with Yingde Gases pipeline networks.
- Medical Nitrogen:USP-grade specification for respiratory therapy and surgical tools in hospital settings.
- Nitrogen Generators:Modular PSA and membrane systems enable food packaging autonomy in Brazil and Southeast Asia manufacturing.
Liquid nitrogen anchors the volume base while nitrogen generators gain share at the steepest rate.
Application:
Margin concentration varies sharply by contamination tolerance, with semiconductor lithography commanding tenfold purity premiums over food packaging.
- Electronics Manufacturing:Ultra-high-purity 99.9999% nitrogen eliminates particulate contamination during photolithography and wafer transport. Samsung Foundry and TSMC negotiate outcome-based contracts with uptime penalties, forcing suppliers into captive air separation adjacency.
- Food Preservation:Modified atmosphere packaging displaces oxygen to extend shelf life in meat and snack products. Brazilian protein processors adopt membrane generators to bypass liquid nitrogen logistics costs.
- Pharmaceuticals:Sterile manufacturing and API storage under inert atmosphere per CDSCO and FDA GMP standards.
- Chemical Processing:Reactor blanketing and catalyst regeneration in petrochemical and specialty chemical production.
Chemical processing anchors the volume base while electronics manufacturing expands most quickly.
End User:
Customer procurement sophistication ranges from volume-driven commodity purchasing to specification-locked technical partnerships.
- Electronics:Foundry operators specify purity certificates with ppb contaminant thresholds and zero-tolerance downtime clauses. Supply agreements now span 10-15 years with facility co-location requirements.
- Healthcare:Hospital systems and home care providers source medical nitrogen through FDA-regulated gas distributors with batch traceability requirements.
- Automotive:Tire inflation and heat treatment applications in manufacturing plants.
- Food & Beverage:Breweries and packaging lines using nitrogen for dispensing and modified atmosphere applications.
Food and beverage anchors the volume base while electronics climbs the fastest.
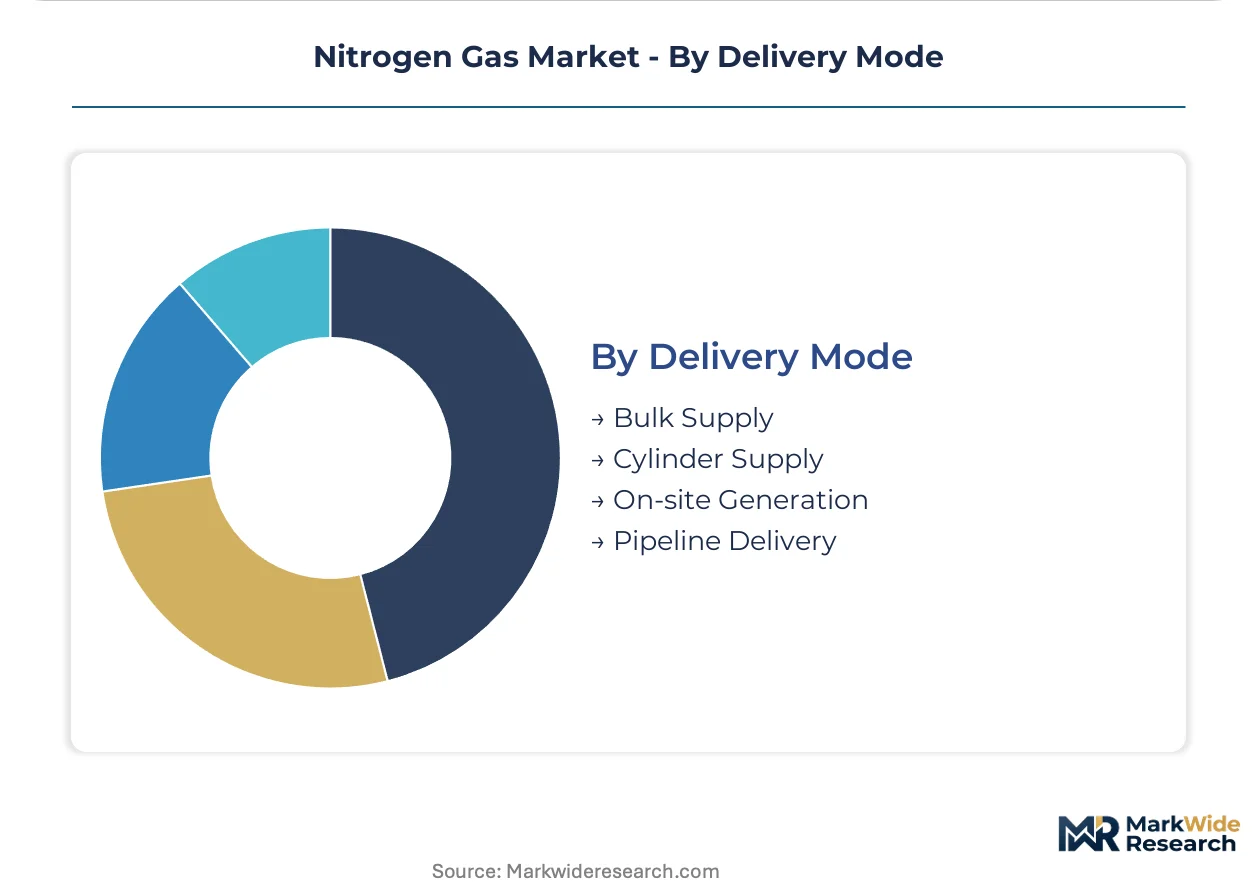
Delivery Mode:
Supply security concerns are rebalancing procurement toward captive production, particularly where grid electricity stabilizes operating cost predictability.
- On-site Generation:Dedicated air separation units or PSA systems eliminate logistics risk for high-volume continuous consumers. Linde and Air Liquide construct captive ASUs adjacent to major electronics hubs to lock in decade-long contracts.
- Pipeline Delivery:Dense industrial clusters in Germany's Ruhr region and China's Yangtze Delta access nitrogen through buried distribution networks with take-or-pay structures.
- Bulk Supply:Liquid nitrogen tanker delivery to mid-scale consumers without pipeline access.
- Cylinder Supply:High-pressure gas cylinders for laboratory and small industrial users with intermittent demand patterns.
Bulk supply anchors the volume base while on-site generation captures the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air separation capacity clusters near major electronics and chemical manufacturing hubs, with pipeline networks and on-site generation systems determining competitive access. National regulatory frameworks for industrial gas purity and workplace exposure reshape facility siting decisions across major producing regions.
China
Yingde Gases operates extensive pipeline networks across the Yangtze River Delta chemical corridor, serving Jiangsu and Zhejiang province manufacturers. MEE directives enforce local purity certification and emissions controls for air separation facilities. Shanghai and Suzhou electronics fabs drive ultra-high-purity nitrogen demand for semiconductor lithography operations.
United States
OSHA workplace exposure standards push chemical processors toward closed-loop nitrogen systems with real-time monitoring capabilities. The EPA governs emissions from cryogenic air separation units in Texas and Louisiana industrial corridors. Houston and Gulf Coast petrochemical clusters anchor bulk liquid nitrogen consumption for reactor blanketing applications.
Germany
The EU F-Gas Regulation mandates nitrogen-driven inerting systems that displace fluorinated gases in pharmaceutical cold chain applications. REACH compliance shapes equipment standards for industrial gas handling across the Ruhr industrial region. BASF and Bayer manufacturing sites in Ludwigshafen and Leverkusen access nitrogen through buried pipeline distribution networks.
South Korea
Samsung Foundry and SK Hynix fabs consume ultra-high-purity nitrogen volumes justifying dedicated air separation unit adjacency. MFDS pharmaceutical regulations drive sterile manufacturing atmosphere requirements for domestic API producers. Pyeongtaek and Yongin electronics clusters concentrate the highest-specification nitrogen demand in East Asia.
India
CDSCO tightening of GMP standards for sterile packaging creates demand for on-site nitrogen generation at Hyderabad and Ahmedabad API hubs. The PLI scheme for electronics manufacturing attracts nitrogen suppliers to establish captive production near semiconductor assembly facilities. Maharashtra chemical manufacturers in Mumbai-Pune corridor represent the largest industrial gas volume base.
Nitrogen Gas Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with ultra-high-purity specialists commanding specification premiums while scale operators compete on delivered cost per cubic meter. The market structure consolidates around three tiers: integrated industrial gas majors with pipeline networks, regional specialists with on-site generation expertise, and equipment fabricators supplying modular PSA systems. Two dominant competitive moves define current positioning: facility co-location contracts with decade-long duration, and backward integration into air separation unit manufacturing to reduce equipment procurement costs.
Within the integrated major tier, Linde plc and Air Liquide exemplify the pipeline-network archetype with captive production assets near electronics hubs. Yingde Gases occupies a position as the dominant domestic supplier in China through extensive on-site generation contracting. Among specialized regional operators, Messer Group represents the mid-scale European model with focused industrial cluster coverage. Taiyo Nippon Sanso anchors Japanese ultra-high-purity supply relationships with domestic semiconductor manufacturers.
| Leading Market Players |
|---|
| Messer Group |
| Axcel Gases |
| Linde plc |
| Gulfcryo |
| Ellenbarrie Industrial Gases |
| Air Products and Chemicals, Inc. |
| Taiyo Nippon Sanso |
| Yingde Gases |
| Air Liquide |
| Others |
Value Network & Pricing Analysis
Air separation unit utilization rates above 85% create margin leverage for pipeline-connected producers while forcing spot-market buyers into premium liquid nitrogen sourcing. Scale concentration in China's Yangtze River Delta and Germany's Ruhr region establishes regional price floors that remote industrial clusters cannot match without captive generation investment.
Pricing Analysis
OSHA workplace exposure standards dictate the pricing tier structure across the nitrogen gas market. Three-tier pricing separates ultra-high-purity semiconductor-grade supply from standard industrial and economy PSA-generated tiers. Price differentiation centers on certification grade and volume commitment duration, with electronics manufacturers locking decade-long contracts at fixed rates. Cost compression in industrial-grade supply is intensifying because membrane technology erodes cryogenic plant economics. Food packaging operations demonstrate highest price sensitivity, while semiconductor fabs accept premiums for zero-tolerance uptime guarantees.
Supply Chain Analysis
Liquid nitrogen boil-off losses of 0.5-2% daily compress inventory cycles and constrain distribution radius economics. Geographic supply concentration centers on China, Germany, and South Korea, where pipeline networks and captive air separation units cluster near electronics and chemical manufacturing hubs. Raw material input draws from atmospheric air separation, electricity grids, and specialized filtration membranes for PSA systems. Single-source vulnerability risks emerge where Yingde Gases controls pipeline networks across Jiangsu and Zhejiang provinces. Distribution runs through buried pipeline networks in dense industrial clusters, with bulk tanker delivery serving mid-scale remote consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as purity specification divergence between semiconductor and industrial applications creates distinct supply niches. Demand-side shift toward outcome-based contracts transfers operational risk to suppliers while opening specialized service provider positions.
For Market Incumbents: Compound pipeline network density in electronics manufacturing corridors to lock in decade-long facility co-location agreements. Threat from modular PSA technology eroding mid-purity margins demands backward integration into membrane and adsorption equipment manufacturing. Priority lever rests on acquiring certification capabilities for multiple regulatory jurisdictions to reduce compliance friction for multinational electronics customers. For New Entrants and Emerging Players: Lead with on-site generation contracting in India's pharmaceutical API hubs, where CDSCO tightening of GMP standards outpaces established supplier response capacity. Most penetrable segment sits in mid-scale food packaging operations across Brazil and Southeast Asia, where membrane generator economics bypass liquid nitrogen logistics. Go-to-market angle emphasizes containerized deployment with local maintenance partnerships rather than capital-heavy air separation construction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment fabricators with PSA and membrane capabilities over pure-play gas distributors. Long-term viability across the analysis window hinges on regulatory divergence between OSHA, REACH, and MEE frameworks creating compliance service demand. Acquisition target archetype: regional specialists with on-site generation expertise in underpenetrated pharmaceutical manufacturing clusters. Signal to watch: electronics manufacturer contract structures shifting from volume commitments to uptime guarantee penalties.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Air Separation Unit Construction | Linde and Air Liquide anchor decade-long electronics contracts through facility adjacency in Taiwan and South Korea. |
| Membrane Technology Acquisition | Equipment fabricators capture mid-purity food packaging demand with 40% lower capital footprint than cryogenic plants. |
| Multi-Jurisdiction Certification Investment | Suppliers reduce compliance friction for multinational semiconductor manufacturers operating across OSHA, REACH, and MEE frameworks. |
| Pipeline Network Expansion | Yingde Gases reinforces single-source positioning across China's Yangtze River Delta chemical corridor. |
| Outcome-Based Contract Structuring | TSMC and Samsung Foundry transfer purity excursion risk to suppliers through uptime penalty clauses. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this nitrogen gas market analysis. Primary fieldwork engaged air separation plant managers, electronics procurement leads at foundry operators, pharmaceutical GMP compliance officers, and industrial gas distribution channel partners. Secondary sources incorporated EPA and OSHA regulatory databases, EU F-Gas Regulation implementation reports, MEE emissions directives, customs trade data for cryogenic equipment imports, and SEC filings from listed industrial gas majors. Bottom-up capacity utilization modeling triangulated against top-down electronics fabrication expansion forecasts.
Sensitivity analysis tested forecast robustness across electricity price volatility scenarios and semiconductor capital expenditure cycles. The analytical framework segmented volume and value projections by purity grade tier, delivery mode configuration, end-use industry concentration, and regional regulatory cluster. CAGRs derived from weighted average of capacity expansion pipelines, announced fab construction timelines, and historical elasticity between industrial production indices and nitrogen consumption intensity. Industry-specific inputs included cryogenic energy intensity coefficients and boil-off loss rates for liquid nitrogen logistics economics.
The analysis sits within stated boundaries; outcomes outside sustained electronics manufacturing expansion or stable grid electricity pricing would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution rates. Specific risks that could revise projections include abrupt OSHA workplace standard changes, MEE emissions directive tightening, or breakthrough membrane efficiency gains displacing cryogenic supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
3D Printing Gases Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Xenon Gas Market
Industrial Gases
Gas Processing Market
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
Krypton-85 Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Europe Syngas Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Global Argon Market