
 High Performance Plastics Market | 2026-2036
High Performance Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Plastics Market Intelligence
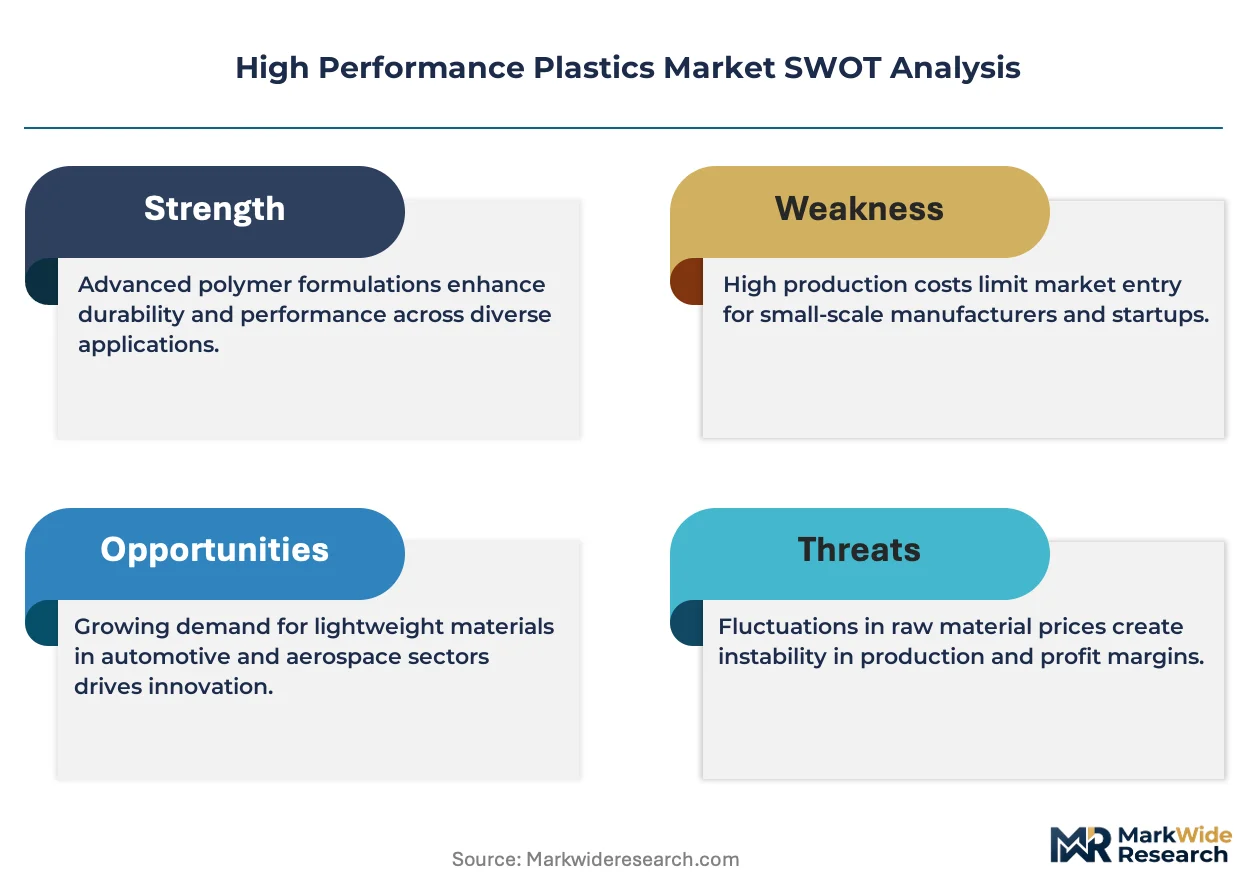
Advanced polymer formulation is rewriting how engineers specify materials for extreme-service environments. BASF SE leverages its integrated polyamide and polyaryletherketone portfolio to anchor supply relationships with tier-one automotive suppliers. DuPont sustains technology leadership in fluoropolymer and high-performance polyimide films through intensive R&D spending on thermal stability. Solvay dominates the polyphenylene sulfide segment with vertical control over key raw material streams.
High performance plastics are thermally stable, chemically resistant polymer systems engineered for continuous service above 150°C, with mechanical properties retained under load, corrosion, or electrical stress. These materials serve critical functions in aerospace turbine housings, semiconductor process equipment, implantable medical devices, and EV battery modules where commodity polymers fail. Polyether ether ketone leads in revenue contribution due to its unmatched strength-to-weight ratio in structural aerospace and oilfield components, while polyphenylene sulfide posts the fastest application growth in EV thermal management and electrical connectors. Polytetrafluoroethylene occupies a mature, high-margin niche in chemical processing linings and medical tubing where purity standards command premium pricing.
REACH in Europe and EPA regulations in the United States restrict perfluorinated compound emissions and mandate full material disclosure, compelling resin producers to certify halogen-free grades and validate recyclability pathways. The FDA and EMA medical device frameworks demand biocompatibility testing that only specialized polyether ether ketone and polyimide formulations satisfy, creating a barrier against unqualified entrants. Stakeholders must monitor how the EU Green Deal's polymer recycling mandates and evolving automotive emissions rules in Japan and China redirect formulation roadmaps before committing capital to new capacity.
Market Dynamics
REACH disclosure mandates and EPA emissions caps are compressing formulation freedom, forcing resin producers to requalify halogen-free grades while aerospace OEMs accelerate polyphenylene sulfide adoption for thermal management.
Growth Catalysts
- EV battery thermal management:Polyphenylene sulfide demand accelerates as cell manufacturers specify flame-retardant housings and coolant manifolds for 800-volt architectures.
- REACH Article 33:Full material disclosure requirements in Europe push converters toward certified supply chains with validated recyclability documentation.
- Aerospace lightweighting:Polyether ether ketone substitution for metal brackets and ducting in next-generation narrowbody programs reduces fuel burn per seat-mile.
Market Restraints
- Fluoropolymer feedstock volatility:Tetrafluoroethylene monomer supply concentrates among three global producers, exposing compounders to price spikes and allocation risk.
- Perfluorinated compound restrictions:EPA PFAS enforcement actions and state-level prohibitions in Minnesota and Maine threaten PTFE medical tubing and chemical processing liner markets.
- Polyimide film processing limits:Continuous cast film widths below 1500mm constrain large-format flexible circuit designs for advanced packaging substrates.
Strategic Opportunities
- India automotive electronics:PLI scheme incentives for semiconductor and EV component manufacturing create first-mover openings for polyetherimide connector housings.
- EU Green Deal recycling mandates:Mechanical and chemical recycling infrastructure investments favor suppliers with validated closed-loop polyamide and PEEK recovery processes.
- Medical device miniaturization:Micro-molding grade PEEK for implantable neuromodulation devices opens premium pricing tiers beyond orthopedic trauma plates.
Industry Challenges
- Polymer rheology expertise gap:Fewer than twelve compounders globally maintain in-house capability to model shear heating in thin-wall PEEK injection molding.
- FDA 510(k) biocompatibility timelines:New resin grades require 18-24 month validation cycles for permanent implant contact applications, freezing formulation innovation.
- Multi-material bonding protocols:Adhesion between PEEK and titanium in spinal fusion cages demands plasma surface activation equipment that mid-tier device manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Plastics Market |
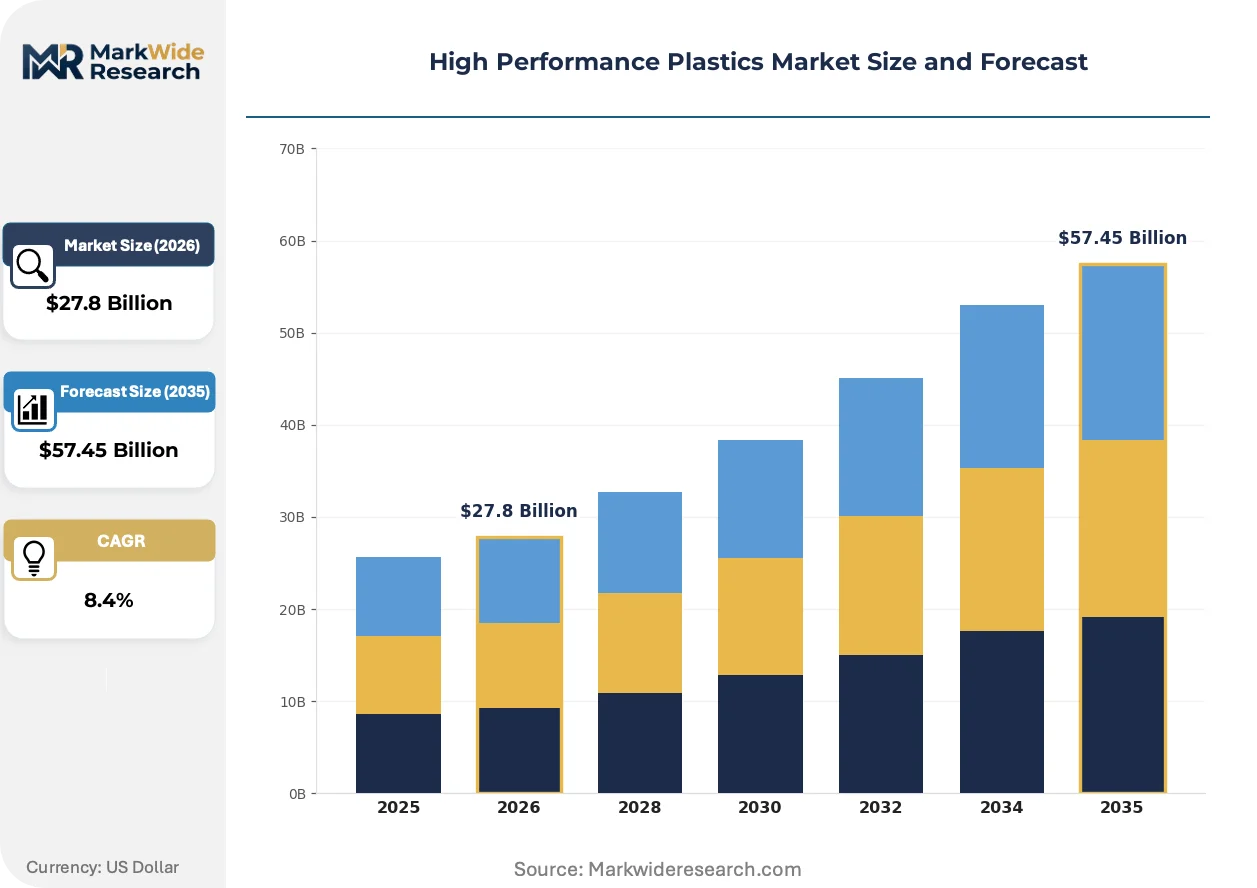
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $57.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether Ether Ketone, Polyphenylene Sulfide, Polytetrafluoroethylene, Polyimide Application: Aerospace, Automotive Components, Electrical Insulation, Medical Devices End User: Electronics, Healthcare, Transportation, Industrial Equipment Technology: Additive Manufacturing, Extrusion, Injection Molding, Compression Molding |
| Companies Covered | BASF SE, DuPont, Solvay, SABIC, Celanese Corporation, Arkema, Evonik Industries, Dow Inc., Victrex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Plastics Market Strategic Shifts & Innovations
Digital thread integration across resin specification, processing simulation, and part performance tracking is compressing development cycles and exposing legacy qualification protocols as bottlenecks.
Machine learning-enabled rheology modeling is digitizing how compounders predict shear heating and crystallization kinetics in thin-wall PEEK injection molding. Tier-one automotive suppliers deploy these tools to reduce tooling iterations from twelve to three. The compression in development timelines is digitizing competitive advantage toward firms with captive simulation capabilities.
F-Gas Regulation phase-down schedules in Europe restrict hydrofluorocarbon blowing agents used in polyimide foam insulation for aerospace applications. Manufacturers pivot toward water-blown and hydrocarbon alternatives with modified thermal conductivity profiles. The regulation most severely impacts French and German aerostructure suppliers serving Airbus narrowbody programs.
Buyers increasingly specify resin grades against ISO 10993 biocompatibility tiers rather than relying on supplier marketing claims. Large medical device OEMs in Massachusetts and Minnesota now mandate batch-level extractables testing data before qualifying new PEEK sources. This certification-driven preference shift concentrates procurement among compounders with captive analytical laboratories.
High Performance Plastics Market Segmentation
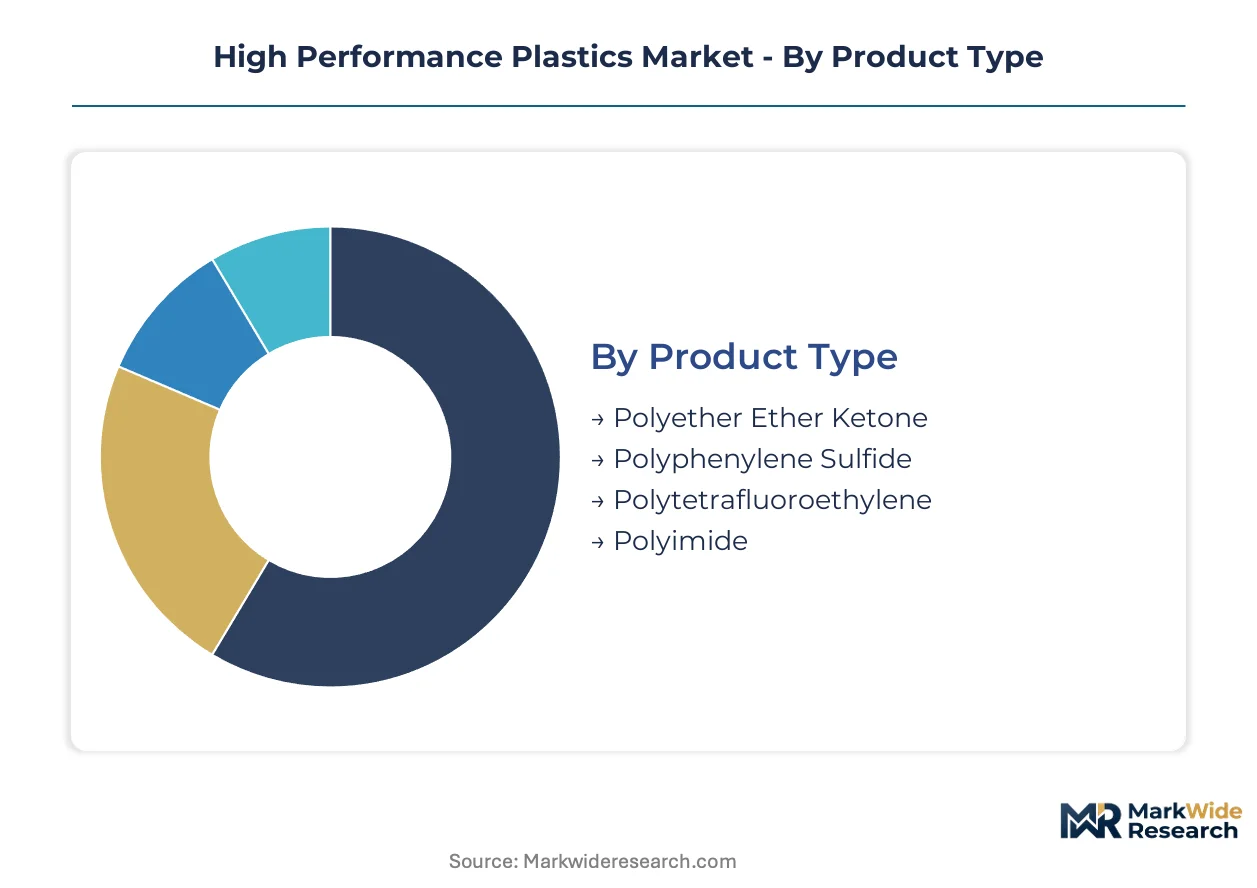
Segmentation in high performance plastics determines specification pathways, processing investments, and regulatory compliance burdens. Engineers select polymer families based on thermal ceiling requirements, while converters align technology choices with part complexity and volume economics.
Product Type:
Cost tier stratification separates premium aromatic polymers from commoditized fluoropolymers, with pricing power concentrated in medical-certified and aerospace-qualified grades.
- Polyether Ether Ketone:Semi-crystalline aromatic polyketone with continuous service temperature reaching 260°C and excellent fatigue resistance. Demand concentrates in spinal implant manufacturers in Massachusetts and aircraft bracket suppliers serving Airbus and Boeing narrowbody programs, where metal substitution drives specification. PEEK holds installed capacity. Polyphenylene Sulfide is rotating up the share rankings.
- Polyphenylene Sulfide:High-heat semicrystalline polymer with inherent flame retardancy and dimensional stability under thermal cycling. EV battery module producers in Germany and South Korea specify PPS for coolant manifolds and cell housings in 800-volt architectures, though REACH Article 33 disclosure requirements complicate raw material sourcing.
- Polytetrafluoroethylene:Fully fluorinated polymer with the lowest coefficient of friction among engineered plastics and exceptional chemical inertness. Chemical processing liner fabricators and medical tubing extruders in the United States face EPA PFAS enforcement pressure and state-level prohibitions in Minnesota and Maine.
- Polyimide:Aromatic heterocyclic polymer maintaining mechanical properties from cryogenic to 300°C service environments. Flexible circuit substrate manufacturers and aerospace insulation suppliers specify Kapton-type films despite F-Gas Regulation restrictions on blowing agents in the European Union.
PEEK commands premium pricing in implantable medical devices. PPS gains share fastest in EV thermal management applications.
Application:
Application segmentation tracks load-bearing requirements, regulatory exposure, and surface finish specifications across extreme-service environments.
- Aerospace:Structural brackets, ducting, and interior components where FAA fire-smoke-toxicity standards apply. Polyether ether ketone substitution for aluminum and titanium accelerates in next-generation narrowbody programs at Airbus and Boeing, with fuel burn reduction per seat-mile as the primary driver. Aerospace holds installed capacity. Medical Devices is rotating up the share rankings.
- Automotive Components:Under-hood thermal management parts, electrical connectors, and bearing surfaces. PPS demand from EV battery manufacturers in Germany and China outpaces traditional internal combustion applications, though supply chain qualification timelines extend 18-24 months for safety-critical parts.
- Electrical Insulation:Wire coatings, motor slot liners, and capacitor films requiring dielectric stability across temperature and humidity extremes. Polyimide film suppliers face width constraints below 1500mm that limit large-format flexible circuit designs for advanced semiconductor packaging substrates.
- Medical Devices:Permanent implants, surgical instruments, and drug delivery components requiring ISO 10993 biocompatibility certification. FDA 510(k) validation cycles and batch-level extractables testing requirements concentrate procurement among compounders with captive analytical laboratories in Massachusetts and Minnesota.
Medical Devices commands the steepest pricing premiums. Automotive Components climbs fastest in volume terms.
End User:
Customer type segmentation reflects divergent technical requirements, procurement scale, and regulatory sophistication across industrial verticals.
- Electronics:Semiconductor process equipment, flexible circuits, and connector housings requiring precision dimensional tolerance. Polyetherimide grades for high-speed connector applications in India's PLI-supported semiconductor packaging sector attract first-mover investment, though domestic compounding capability remains limited.
- Healthcare:Implantable devices, surgical tools, and diagnostic equipment with permanent patient contact. PEEK spinal fusion cages and neuromodulation device housings command premium micro-molding grades, with plasma surface activation protocols for titanium bonding creating capability barriers for mid-tier manufacturers.
- Transportation:Aerospace OEMs, automotive tier suppliers, and rail interior fabricators. Lightweighting mandates from airlines and emissions regulations in Japan and China redirect formulation roadmaps toward recycled-content and bio-based polyamide grades.
- Industrial Equipment:Chemical processing, oilfield, and food machinery requiring corrosion resistance and FDA compliance. PTFE-lined vessels and PEEK seals in downhole drilling tools face feedstock volatility concentrated among three global tetrafluoroethylene monomer producers.
Healthcare sustains the highest margin structure. Electronics expands most quickly in emerging manufacturing clusters.
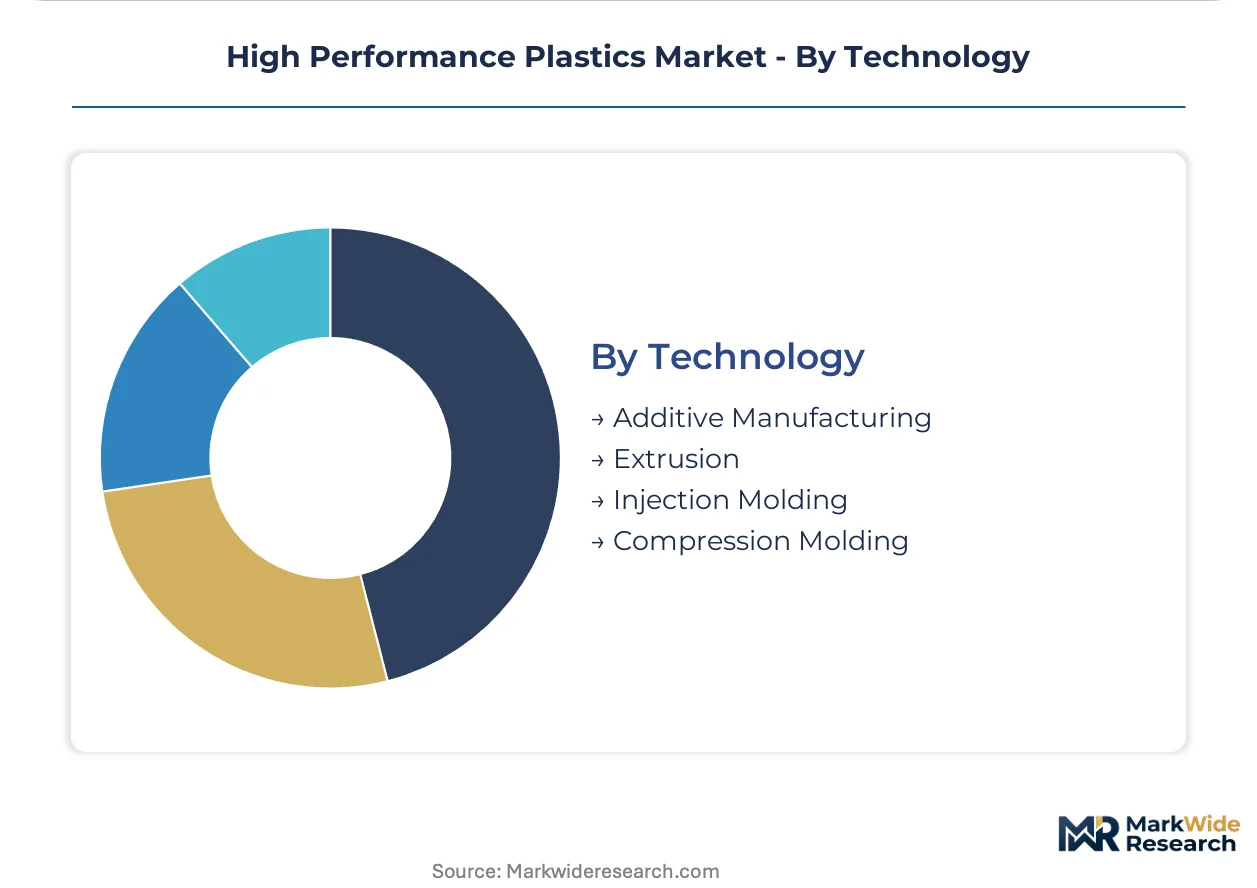
Technology:
Processing technology segmentation governs capital intensity, part complexity limits, and development cycle duration for new applications.
- Additive Manufacturing:Laser sintering and fused filament fabrication of PEEK and PPS for patient-specific implants and low-volume aerospace brackets. Machine learning-enabled rheology modeling reduces tooling iterations from twelve to three at tier-one automotive suppliers deploying these tools for prototype validation.
- Extrusion:Continuous profile production for tubing, film, and stock shapes. Polyimide film cast width limitations below 1500mm constrain substrate suppliers serving advanced flexible circuit packaging, while water-blown and hydrocarbon alternatives replace restricted hydrofluorocarbon blowing agents under F-Gas Regulation phase-down schedules.
- Injection Molding:High-volume production of complex geometries with tight dimensional tolerances. Fewer than twelve compounders globally maintain in-house capability to model shear heating in thin-wall PEEK injection molding, digitizing competitive advantage toward firms with captive simulation capabilities.
- Compression Molding:Large-format parts and high-fill composites where fiber orientation control dominates performance. Aerospace ducting and industrial bearing producers favor this route for PEEK and PTFE compounds with carbon or glass reinforcement, though cycle times limit economic viability below medium volumes.
Injection Molding holds installed capacity. Additive Manufacturing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and medical device manufacturers concentrate procurement authority in Germany, the United States, and China, with EV battery suppliers and aerospace tier-ones driving specification intensity.
United States
Medical device OEMs in Massachusetts and Minnesota mandate batch-level extractables testing for PEEK implant grades, tightening supplier qualification. FDA 510(k) timelines extend 18-24 months for permanent implant applications. Boston and Minneapolis-St. Paul anchor spinal fusion cage and neuromodulation device manufacturing clusters.
Germany
EV battery manufacturers specify PPS coolant manifolds for 800-volt architectures, accelerating thermal management polymer demand. REACH Article 33 disclosure requirements push converters toward certified halogen-free supply chains. BASF SE and Evonik Industries anchor polymer innovation clusters in Ludwigshafen and Marl.
China
Semiconductor packaging substrate producers seek polyimide films for advanced flexible circuits, constrained by cast width limitations below 1500mm. Dual carbon goals redirect formulation roadmaps toward recycled-content polyamide grades. Yangtze River Delta electronics manufacturing clusters drive connector housing demand for polyetherimide grades.
Japan
Aerospace insulation suppliers pivot from hydrofluorocarbon blowing agents under F-Gas Regulation phase-down schedules, adopting water-blown alternatives. METI automotive emissions rules redirect lightweighting investments toward PEEK bracket substitution. Nagoya and Tokyo aerostructure clusters serve Boeing and Airbus narrowbody programs.
South Korea
EV cell manufacturers in Gyeonggi Province specify flame-retardant PPS cell housings for next-generation battery architectures. MFDS medical device frameworks create parallel biocompatibility certification requirements for implantable grades. Busan-Ulsan chemical processing clusters demand PTFE-lined vessels despite feedstock volatility.
High Performance Plastics Market Key Industry Players
Channel-controlling players compete with product-specialist players across formulation tiers, creating a tiered structure where integrated resin producers hold pricing power in medical-certified grades while regional compounders serve industrial volume segments. Three archetypes dominate: integrated chemical conglomerates with captive monomer supply, specialized high-performance polymer pure-plays, and regional compounding houses with formulation flexibility. Capacity expansion and strategic partnerships represent the dominant competitive moves, with firms securing backward integration into key raw material streams or partnering with medical device OEMs for co-development of implantable grades.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries exemplify players with polymer innovation clusters in Germany, while DuPont occupies a position among North American-based material science specialists with intensive R&D footprints. Solvay anchors the European polyphenylene sulfide segment through upstream control over key raw material streams. These three companies represent distinct strategic postures: German integrated production, North American technology licensing, and European vertical specialization.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| Solvay |
| SABIC |
| Celanese Corporation |
| Arkema |
| Evonik Industries |
| Dow Inc. |
| Victrex |
| Others |
Cost & Logistics Intelligence
Undercapacity in European PPS resin production is driving BASF SE and Evonik Industries toward allocation-based contracting, while buyers absorb premium pricing for REACH-certified halogen-free grades. This utilization squeeze concentrates pricing power among integrated producers with captive monomer supply, forcing compounders without backward integration into cost-plus pass-through arrangements indexed to tetrafluoroethylene volatility.
Pricing Analysis
Cost-plus contracts with tetrafluoroethylene monomer indexation dominate PTFE and fluoropolymer transactions, insulating compounders from feedstock spikes but exposing OEMs to margin compression. Three-tier pricing structure across medical-certified, aerospace-qualified, and industrial-standard grades separates PEEK spinal implant suppliers from automotive connector producers. Pricing pressure stems from EPA PFAS enforcement actions constraining PTFE medical tubing demand, with Massachusetts device OEMs exhibiting highest price sensitivity due to batch-level extractables testing mandates.
Supply Chain Analysis
Contract manufacturing concentrates among German automotive tier suppliers and Massachusetts medical device foundries with captive PEEK compounding lines. Raw material sourcing draws from Chinese para-xylene streams, German caprolactam clusters, and Japanese fluoromonomer producers. Single-source vulnerability in tetrafluoroethylene monomer—controlled by three global producers—exposes PTFE fabricators to allocation risk. Distribution runs through authorized distributor networks for medical grades and direct mill relationships for industrial volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where FDA 510(k) and REACH Article 33 compliance create regulatory entrenchment against unqualified entrants. Switching costs for qualified medical-grade PEEK supply chains exceed eighteen months, locking in incumbent positions.
For Market Incumbents: Insulate medical-grade pricing power through captive plasma surface activation capability for PEEK-titanium bonding protocols, neutralizing mid-tier device manufacturer competition. Accelerate backward integration into para-xylene and fluoromonomer streams to secure supply against Korean EV battery manufacturer demand surges. Prioritize ISO 10993 batch-level extractables testing infrastructure as the primary capability barrier. For New Entrants and Emerging Players: India's PLI-supported semiconductor packaging sector represents the most penetrable entry point for polyetherimide connector housing qualification, given limited domestic compounding capability and first-mover incentive windows. Water-blown polyimide foam insulation for Japanese aerospace applications offers secondary white-space as F-Gas Regulation phase-down displaces incumbent hydrofluorocarbon processes. Lead with machine learning-enabled rheology modeling services to reduce tier-one automotive supplier tooling iterations. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because medical device biocompatibility certification timelines and REACH disclosure mandates compound incumbent advantages across multiple product generations. Acquisition targets should display captive analytical laboratories with ISO 17025 accreditation and established FDA Master File documentation. Monitor EPA PFAS enforcement intensity and EU Green Deal polymer recycling mandate implementation as inflection signals for fluoropolymer versus bio-based polyamide demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoromonomer Supply | Captive tetrafluoroethylene production insulates Solvay and DuPont from allocation risk in medical tubing markets. |
| Medical Device Co-Development Partnerships | FDA 510(k) shared validation with Massachusetts OEMs compresses eighteen-month qualification timelines for implantable PEEK grades. |
| Machine Learning Rheology Platform Deployment | Shear heating prediction capabilities digitize competitive advantage for tier-one automotive suppliers in thin-wall molding. |
| EU Green Deal Recycling Infrastructure Investment | Closed-loop polyamide and PEEK recovery processes secure preferred supplier status under evolving circular economy mandates. |
| India PLI Semiconductor Packaging Entry | Polyetherimide connector housing qualification captures first-mover positioning in government-incentivized electronics manufacturing clusters. |
Research Approach
Desk research of customs trade databases, SEC 10-K resin segment disclosures, and ECHA REACH registration dossiers preceded structured interviews with PEEK compounding plant managers, medical device procurement directors at Massachusetts OEMs, automotive tier supplier material engineers, and aerospace qualification specialists at Airbus and Boeing tier-ones. Bottom-up volume estimates from polymer grade production capacities were triangulated against top-down demand models built from EV battery architecture specifications and implantable device shipment data.
Assumptions held fixed include current EPA PFAS enforcement intensity, REACH Article 33 disclosure requirement scope, and F-Gas Regulation phase-down schedules, while variables included EV 800-volt architecture adoption rates across German and Chinese OEMs and medical device miniaturization trends in neuromodulation applications. Segmentation modeling spanned product type crystallinity classes, application thermal load requirements, end-user regulatory sophistication tiers, and regional automotive emissions framework clusters. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements.
Practitioners should monitor EPA PFAS rulemaking dockets, EU Green Deal polymer recycling mandate implementation timelines, and Japanese METI automotive lightweighting subsidy adjustments for early signals of formulation roadmap redirection. Quarterly review of tetrafluoroethylene monomer producer allocation announcements and FDA 510(k) PEEK implant submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
High Performance Epoxy Market
Performance Chemicals
Global Oilfield Production Chemicals Market
Performance Chemicals
Global High Performance Polyamides Market
Performance Chemicals
Chemical Feed Systems Market
Performance Chemicals
Asia-Pacific Hydrogen Peroxide Market
Performance Chemicals
Global Reflective Materials Market
Performance Chemicals
Global High Performance Polymers Market
Performance Chemicals
Mecoprop Market