
 High Purity Gas/Ultra-High Purity Gas/Pure Gas Market | 2026-2036
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market Foresight
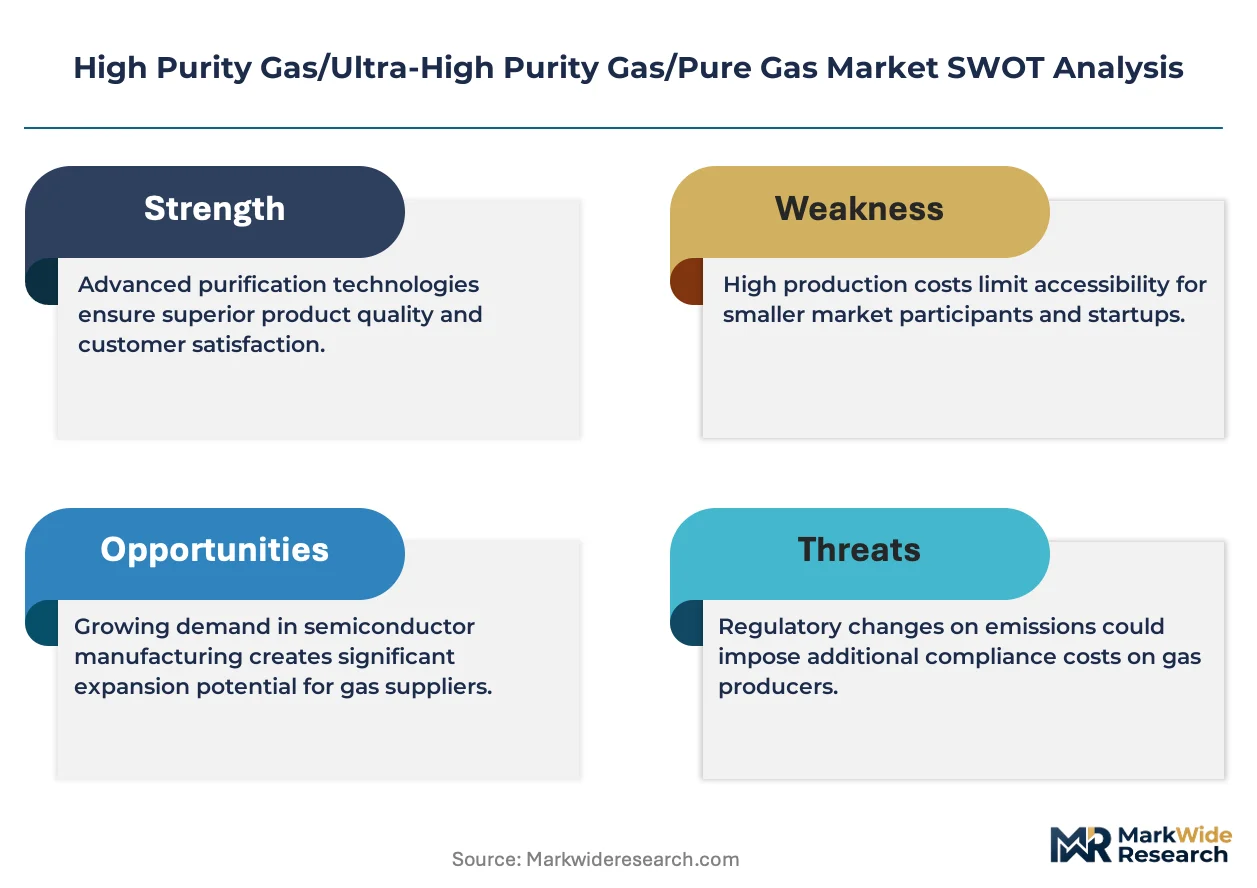
Bulk-to-micro-bulk packaging is shifting procurement economics for mid-volume electronics fabs. Linde plc leverages captive helium extraction from Wyoming's Riley Ridge field to sustain North American supply security. Air Liquide anchors European demand through its pipeline networks serving ASML's lithography ecosystem in the Netherlands. Taiyo Nippon Sanso Corporation differentiates via ultra-high purity fluorine technology for advanced node etching.
High purity gas, ultra-high purity gas, and pure gas denote gases refined to contaminant levels below one part per billion, with ultra-high purity grades typically achieving 99.9999% or higher mole fraction through cryogenic distillation, pressure swing adsorption, and catalytic purification trains. These gases function as process enablers in semiconductor lithography, pharmaceutical sterilization, and aerospace propulsion where trace impurities destroy yield or compromise safety. Helium commands structural premium pricing due to constrained geological sourcing and US Federal Helium Reserve drawdown policies. Nitrogen volumes dominate tonnage flows because every wafer fab consumes thousands of tons annually for inerting and purging. Argon competes aggressively in metal inert gas welding and titanium processing, though semiconductor-grade argon carries tighter specification premiums.
The EPA regulates fluorinated greenhouse gas emissions under the American Innovation and Manufacturing Act, compelling gas suppliers to document destruction efficiencies and transition to lower-GWP alternatives. FDA enforces current Good Manufacturing Practice standards that mandate nitrogen and oxygen purity certificates for pharmaceutical aseptic processing, effectively raising compliance costs for uncertified regional blenders. OSHA's confined space and hazard communication rules shape cylinder handling protocols across the industrial gas supply chain. Stakeholders must monitor how the Department of Energy's critical minerals list revisions affect helium's strategic reserve classification and trade policy treatment.
Market Dynamics
Semiconductor node shrinkage below 3nm is forcing gas suppliers to certify impurity thresholds at parts-per-trillion levels, compressing qualification timelines and concentrating procurement among vertically integrated producers with captive purification assets.
Growth Catalysts
- Advanced lithography expansion:EUV scanner deployment in South Korea's Pyeongtaek corridor is pulling ultra-high purity nitrogen and helium volumes upward as Samsung and SK Hynix commission new wafer fabs.
- F-Gas Regulation phase-down:The European Union's fluorinated gas restrictions are compelling etchant gas producers to reformulate blends with lower global warming potential, creating certified product premiums.
- Pipeline infrastructure density:Netherlands-based pipeline networks serving ASML's lithography ecosystem enable just-in-time argon and nitrogen delivery that bulk cylinder supply cannot match.
Market Restraints
- Helium geological scarcity:Wyoming's Riley Ridge field and Qatar's North Dome represent the only significant new sources, concentrating supply security risk among three national reserve holders.
- Cryogenic distillation capex intensity:Ultra-high purity production requires billion-dollar air separation units with decade-long depreciation schedules, freezing out regional blenders.
- EPA fluorinated gas documentation:The American Innovation and Manufacturing Act mandates destruction efficiency certificates that add six-month compliance timelines to new product introductions.
Strategic Opportunities
- Micro-bulk packaging penetration:Mid-volume electronics fabs in Vietnam and Malaysia are converting from cylinder exchange to on-site micro-bulk tanks, opening distribution channel innovation.
- Pharmaceutical aseptic processing:FDA current Good Manufacturing Practice standards for nitrogen and oxygen purity certificates raise compliance barriers that favor certified multinational suppliers over uncertified regional competitors.
- Fluorine technology convergence:Ultra-high purity fluorine for advanced node etching is absorbing adjacent chemistries as chipmakers consolidate gas portfolios to reduce contamination vectors.
Industry Challenges
- Cryogenic engineering talent scarcity:Pressure swing adsorption and catalytic purification train operation requires specialized technicians that vocational pipelines in the US and Germany cannot currently supply.
- Multi-jurisdiction certification lag:Simultaneous EPA, FDA, and EMA qualification for a single ultra-high purity gas grade extends time-to-revenue by 18-24 months.
- Legacy cylinder fleet incompatibility:Parts-per-trillion purity specifications require electropolished stainless steel and specialized valve materials that existing logistics networks cannot accommodate without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Gas/Ultra-High Purity Gas/Pure Gas Market |
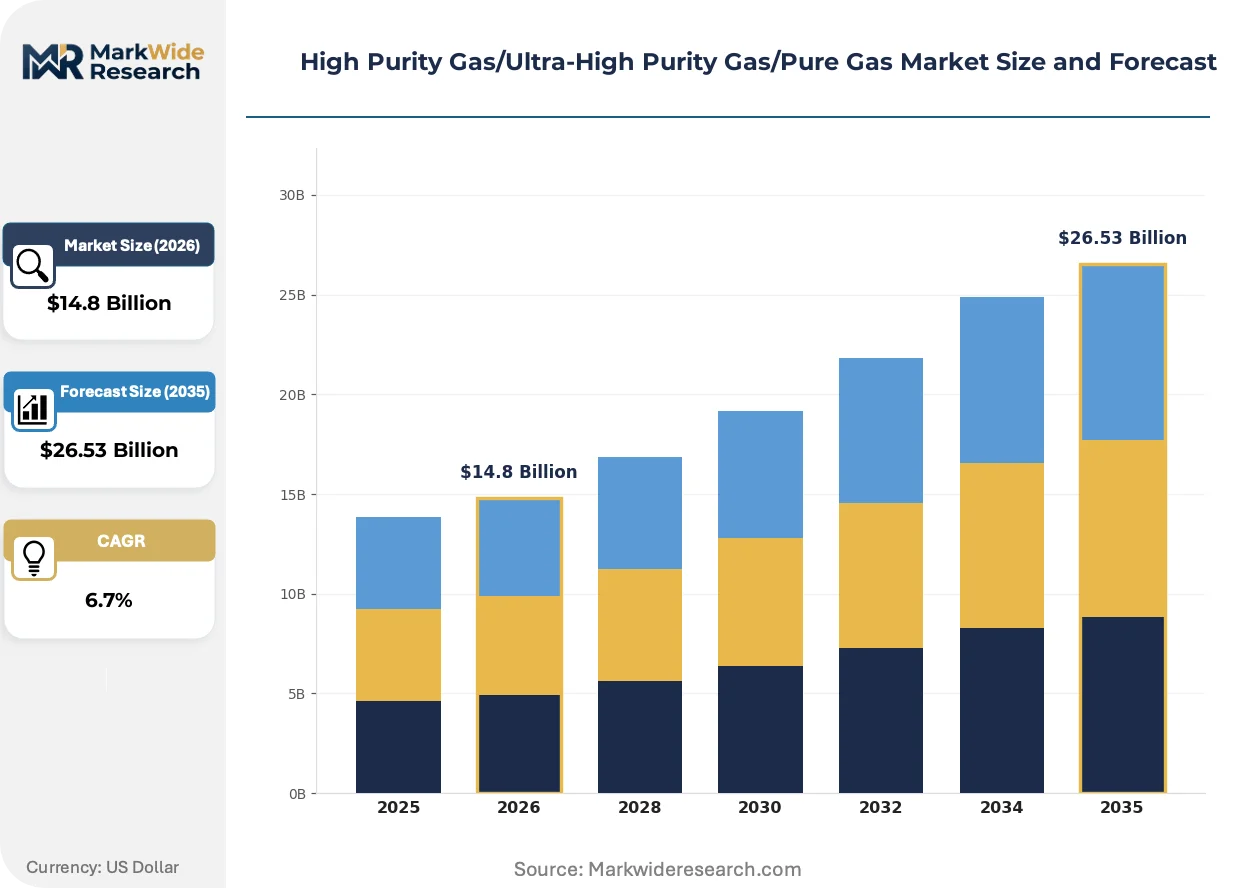
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helium, Hydrogen, Nitrogen, Argon Grade: Ultra-High Purity, High Purity, Semi-Pure, Standard End Use Industry: Electronics, Pharmaceuticals, Aerospace, Chemical Processing Distribution Channel: Direct Sales, Distributors, Online Retail, Gas Suppliers |
| Companies Covered | Iwatani Corporation, Matheson Tri-Gas, Linde plc, Airgas, Advanced Specialty Gases, Air Liquide, Messer Group, Taiyo Nippon Sanso Corporation, Air Products and Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market Shifts & Advancements
Gas supply architecture is bifurcating between pipeline-integrated megafabs and distributed micro-bulk nodes, with purification technology and packaging format selection increasingly determining competitive access rather than commodity chemistry alone.
Point-of-use gas abatement systems is absorbing capital allocation from traditional centralized scrubbing as 3nm fab operators demand real-time destruction of hazardous exhaust at the tool level. ASML's lithography customers in the Netherlands are specifying these systems as mandatory for new equipment purchases. The technology is compressing facility-scale environmental compliance into modular, replaceable units.
REACH and the EU F-Gas Regulation are forcing reformulation of nitrogen trifluoride and sulfur hexafluoride etchants ahead of scheduled phase-down milestones. German chemical suppliers are accelerating low-global-warming-potential alternative development to defend existing semiconductor customer relationships. The regulatory pressure is most acute in etchant blends where destruction efficiency documentation determines market access.
Long-term take-or-pay contracts with indexed helium pricing are displacing spot market exposure for major semiconductor fabs. Buyers in South Korea's Yongin corridor are locking in 10-year supply agreements with Qatar and US producers to hedge against Federal Helium Reserve volatility. This contractual shift is visible wherever wafer fabrication capacity expansion outpaces regional gas infrastructure development.
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market Segmentation
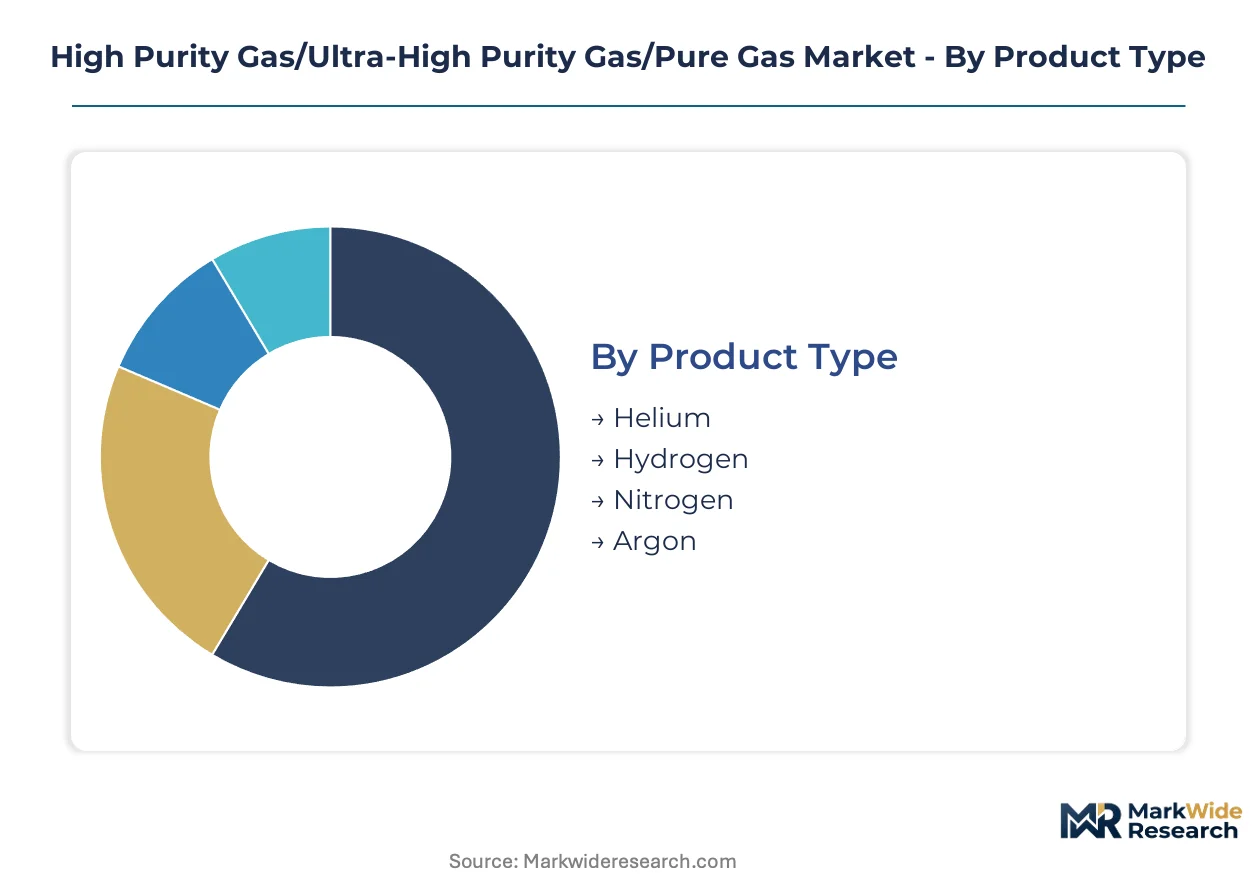
Gas purity specifications and delivery mechanisms determine procurement economics across semiconductor, pharmaceutical, and aerospace applications. Segmentation reveals how technical requirements fragment supply chains and concentrate margin capture among certified producers with captive purification infrastructure.
Product Type:
Technical differentiation centers on molecular weight, sourcing geology, and purification train complexity rather than commodity chemistry alone.
- Helium:Extracted from Wyoming's Riley Ridge field and Qatar's North Dome, this gas achieves 99.9999% purity through cryogenic separation. Semiconductor fabs in South Korea's Yongin corridor lock in decade-long indexed contracts to hedge Federal Helium Reserve volatility.
- Nitrogen:Generated via billion-dollar air separation units consuming thousands of tons annually per wafer fab for inerting and purging. Pipeline networks serving ASML's lithography ecosystem in the Netherlands enable just-in-time delivery that cylinder supply cannot match.
- Hydrogen:Serves fuel cell testing and polysilicon reduction with purity thresholds tightening for advanced semiconductor applications.
- Argon:Competes in metal inert gas welding and titanium processing, though semiconductor-grade specifications command substantial specification premiums over industrial grades.
Nitrogen leads on scale; helium leads on momentum.
Grade:
Certification tiers stratify pricing power and customer switching costs across end-use verticals.
- Ultra-High Purity:Achieves 99.9999% or higher mole fraction through pressure swing adsorption and catalytic purification trains. Parts-per-trillion impurity thresholds compress qualification timelines to 18-24 months for EPA, FDA, and EMA simultaneous approval.
- High Purity:Contaminant levels below one part per billion satisfy pharmaceutical aseptic processing under FDA current Good Manufacturing Practice standards, raising compliance barriers against uncertified regional blenders.
- Semi-Pure:Targets chemical processing and industrial applications where cost sensitivity outweighs specification stringency.
- Standard:Serves legacy manufacturing with minimal purification overhead and commodity pricing dynamics.
Ultra-High Purity captures margin concentration; High Purity captures volume depth.
End Use Industry:
Application-specific contamination vectors dictate gas portfolio composition and point-of-use abatement requirements.
- Electronics:EUV lithography deployment in South Korea's Pyeongtaek corridor pulls ultra-high purity nitrogen and helium volumes upward as Samsung and SK Hynix commission 3nm wafer fabs.
- Pharmaceuticals:FDA-mandated nitrogen and oxygen purity certificates for aseptic processing favor certified multinational suppliers over regional competitors lacking documentation infrastructure.
- Aerospace:Propulsion systems require trace-impurity control where contamination destroys yield or compromises crew safety.
- Chemical Processing:Serves reformulated etchant blends responding to EPA fluorinated gas restrictions under the American Innovation and Manufacturing Act.
Electronics commands specification intensity; pharmaceuticals commands regulatory stickiness.
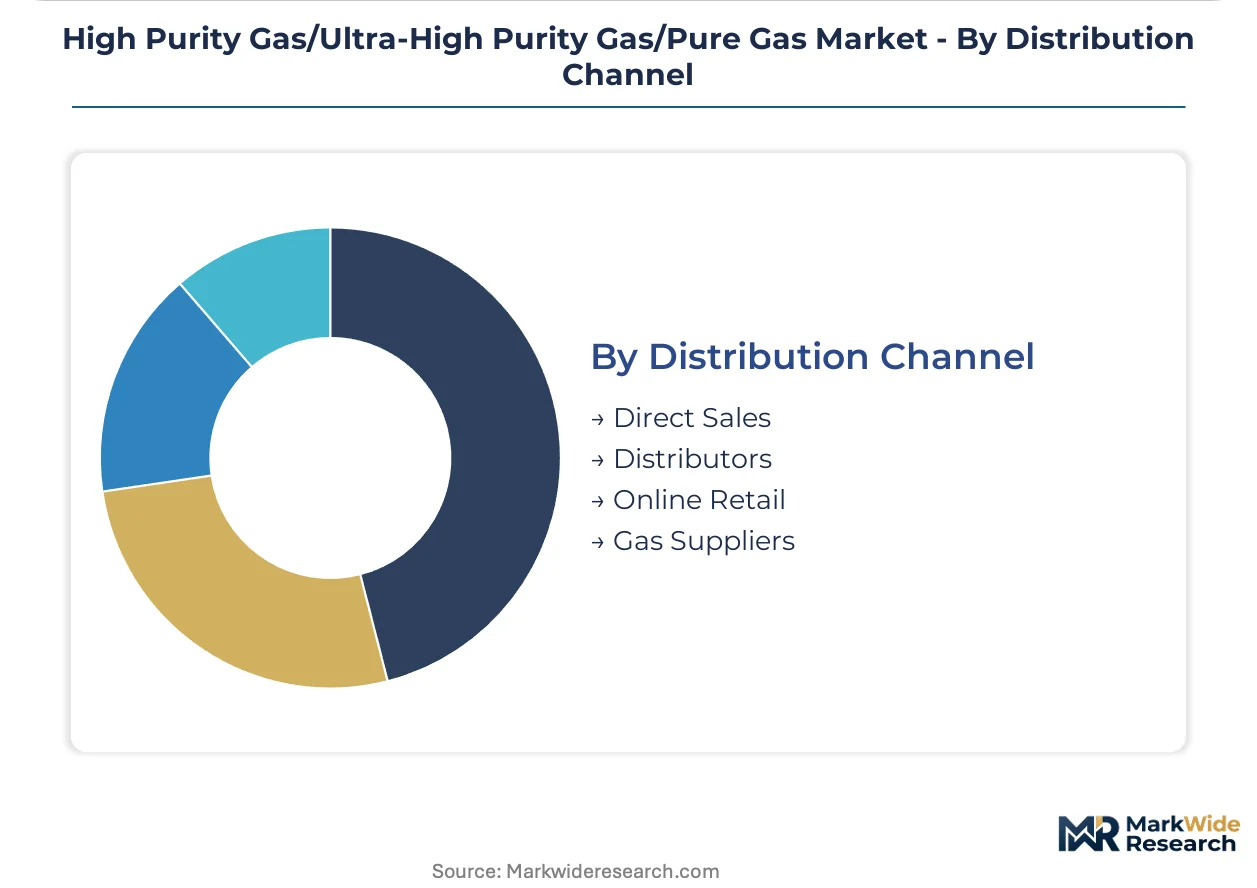
Distribution Channel:
Packaging format selection increasingly determines competitive access rather than gas chemistry alone.
- Direct Sales:Long-term take-or-pay contracts with indexed helium pricing displace spot market exposure for major semiconductor fabs hedging supply security risk.
- Distributors:Micro-bulk tank conversions among mid-volume electronics fabs in Vietnam and Malaysia open channel innovation away from cylinder exchange models.
- Online Retail:Serves fragmented research and development procurement with standard-grade specifications and minimal technical support.
- Gas Suppliers:Vertically integrated producers with captive purification assets concentrate procurement among pipeline-integrated megafabs requiring just-in-time delivery.
Direct Sales anchors contract value; Distributors anchors geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial gas purification industry traces its commercial origins to Germany's development of cryogenic air separation in the early twentieth century, with BASF and Linde establishing the technical foundations that now underpin semiconductor-grade production worldwide.
United States
Wyoming's Riley Ridge field supplies captive helium extraction for North American semiconductor security. The EPA's American Innovation and Manufacturing Act mandates destruction efficiency certificates for fluorinated etchant gases, extending new product qualification timelines. Samsung's Austin fab expansion and Intel's Arizona manufacturing investments are pulling ultra-high purity nitrogen and argon volumes upward.
South Korea
EUV lithography deployment in the Pyeongtaek-Yongin corridor drives demand for parts-per-trillion purity helium and nitrogen. The country's national environmental regulator enforces fluorinated gas phase-down schedules aligned with EU F-Gas Regulation benchmarks. Samsung and SK Hynix are commissioning 3nm wafer fabs that lock in decade-long indexed helium contracts with Qatar and US producers.
Netherlands
ASML's lithography ecosystem anchors European ultra-high purity gas demand through dense pipeline networks serving just-in-time delivery requirements. ECHA's REACH framework governs etchant gas reformulation with lower global warming potential alternatives. The Eindhoven region concentrates purification infrastructure that cylinder supply cannot economically match.
Japan
Advanced node etching applications absorb ultra-high purity fluorine technology from domestic suppliers. METI's critical materials policies shape helium strategic reserve classification and trade treatment. The Chubu region around Nagoya hosts specialized catalytic purification train operations for semiconductor process gases.
China
Domestic wafer fab construction is accelerating demand for captive air separation unit deployment. The Ministry of Ecology and Environment enforces dual carbon goals that constrain fluorinated gas emissions intensity. Yangtze River Delta clusters in Shanghai and Jiangsu province are importing purification technology through joint ventures with European and Japanese partners.
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and captive purification infrastructure ownership. The market structure concentrates procurement among vertically integrated producers with billion-dollar air separation assets, while regional blenders compete on semi-pure and standard grades. Three archetypes dominate: pipeline-integrated megafab suppliers, micro-bulk distribution innovators, and fluorine technology specialists. Competitive moves center on long-term take-or-pay contract anchoring and point-of-use abatement system integration.
Within the pipeline-integrated tier, Linde plc and Air Liquide exemplify scale-driven positioning through captive helium extraction and European pipeline network density. Taiyo Nippon Sanso Corporation occupies a specialist position in ultra-high purity fluorine technology for advanced node etching applications. These three entities represent contrasting strategic anchors: resource-backed vertical control, continental infrastructure dominance, and process-specific technical differentiation.
| Leading Market Players |
|---|
| Iwatani Corporation |
| Matheson Tri-Gas |
| Linde plc |
| Airgas |
| Advanced Specialty Gases |
| Air Liquide |
| Messer Group |
| Taiyo Nippon Sanso Corporation |
| Air Products and Chemicals |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in Qatar and Wyoming anchor helium supply security through indexed long-term contracts, compressing spot market liquidity and forcing price discipline onto semiconductor fabs hedging Federal Helium Reserve volatility. This ownership pattern concentrates pricing power upstream while downstream buyers absorb pass-through clauses for cryogenic distillation energy costs.
Pricing Analysis
Long-term take-or-pay contracts with indexed helium pricing dominate procurement for semiconductor-grade gases, separating ultra-high purity premiums from industrial-grade commodity benchmarks. Price differentiation rests on certification grade and captive purification infrastructure ownership, with EPA destruction efficiency documentation adding compliance premiums to fluorinated etchants. Pricing pressure stems from billion-dollar air separation unit capex intensity freezing out regional blenders. Mid-volume electronics fabs in Vietnam and Malaysia exhibit highest price sensitivity, while 3nm node fabs in South Korea's Yongin corridor accept premium terms for supply security.
Supply Chain Analysis
Parts-per-trillion impurity thresholds enforce 18-24 month EPA, FDA, and EMA qualification timelines that gate market access among certified producers. Supply concentrates in Qatar, Wyoming, and the Netherlands, with helium extraction tethered to Riley Ridge field geology and North Dome reserves. Raw material dependencies span cryogenic separation equipment, catalytic purification media, and electropolished stainless steel cylinder fleets. Single-source vulnerability runs through helium geological scarcity, with only three national reserve holders controlling new production. Distribution runs through pipeline-integrated megafabs for just-in-time nitrogen delivery, while micro-bulk tanks serve distributed electronics manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as semiconductor node shrinkage below 3nm forces parts-per-trillion certification standards that only vertically integrated producers with captive purification assets can satisfy.
For Market Incumbents: Acquire captive helium extraction rights or long-term offtake positions to defend against Federal Helium Reserve volatility and Qatar supply concentration. Secure cryogenic engineering talent pipelines through German and US vocational partnerships to address technician scarcity threatening purification train operations. Backward integration into electropolished stainless steel cylinder manufacturing mitigates legacy fleet incompatibility risks for parts-per-trillion specifications. For New Entrants and Emerging Players: Capture micro-bulk distribution nodes in Vietnam and Malaysia where mid-volume electronics fabs are converting from cylinder exchange models. Target pharmaceutical aseptic processing segments where FDA current Good Manufacturing Practice certificate barriers favor new certified entrants over uncertified regional blenders. A go-to-market angle anchored on point-of-use abatement system integration with ASML lithography equipment purchases bypasses pipeline infrastructure disadvantages. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders lacking EPA fluorinated gas documentation infrastructure but possessing semi-pure grade customer relationships convertible to certified portfolios. The five-to-ten year viability window favors acquisition of catalytic purification train operators with existing EMA qualification pathways. The signal to watch is South Korean national environmental regulator alignment with EU F-Gas Regulation phase-down schedules, which would accelerate etchant gas reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Helium Extraction | Wyoming's Riley Ridge field captive supply secures North American semiconductor fab demand against reserve volatility. |
| Micro-Bulk Tank Distribution Expansion | Vietnam and Malaysia mid-volume fab conversions from cylinder exchange open channel innovation opportunities. |
| Catalytic Purification Train Certification | EPA, FDA, and EMA simultaneous qualification compresses 18-24 month timelines that gate ultra-high purity market access. |
| Point-of-Use Abatement System Integration | ASML lithography equipment mandates in the Netherlands absorb capital allocation from centralized scrubbing infrastructure. |
| Long-Term Take-or-Pay Contract Anchoring | Samsung and SK Hynix decade-long indexed helium agreements in South Korea's Yongin corridor displace spot market exposure. |
Research Methodology
Bottom-up electronics and pharmaceutical end-use modeling reconciled against top-down helium extraction and air separation unit capacity tracking forms the analytical core of this study. Primary interviews with semiconductor fab procurement directors, gas supplier technical R&D leads, pharmaceutical aseptic processing managers, and EPA regulatory compliance officers combined with secondary validation from SEC 10-K filings, customs and trade data, FDA current Good Manufacturing Practice certificates, and EMA qualification databases. Triangulation between demand-side consumption metrics and supply-side infrastructure investments ensures statistical integrity.
Input-output matrices map gas purity grade specifications to end-use contamination vectors across the projection horizon, with segmentation dimensions spanning product type, certification tier, end-use industry, and distribution channel. CAGRs derive from fitted trend extrapolation against named capacity additions and regulatory phase-down schedules. Forecast inputs include EUV lithography deployment timelines in South Korea's Pyeongtaek corridor, EPA American Innovation and Manufacturing Act destruction efficiency documentation requirements, and helium reserve drawdown policies affecting indexed contract pricing.
Semiconductor fab construction delays, EPA fluorinated gas regulation enforcement intensity, and helium geological reserve reclassification are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about qualification timeline compression and pipeline infrastructure density thresholds. A model refresh is warranted upon material change in South Korean national environmental regulator alignment with EU F-Gas Regulation benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Krypton Gas Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Syngas Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Gas Processing Market
Industrial Gases
Global Sulfur Dioxide Market