
 Industrial Gases for Metals and Metal Fabrication Market | 2026-2036
Industrial Gases for Metals and Metal Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gases for Metals and Metal Fabrication Market Foresight
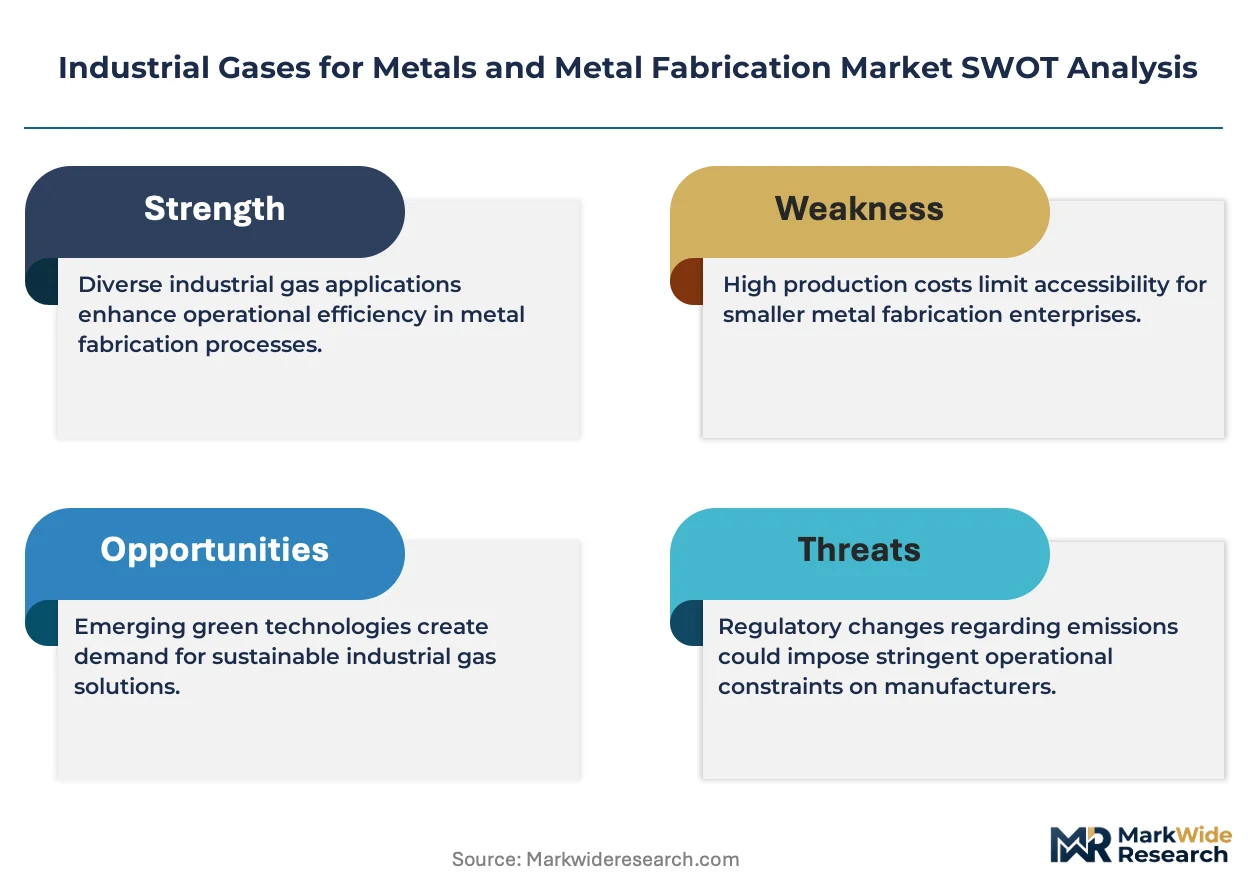
Project finance for on-site air separation units is rewriting competitive entry barriers across metal fabrication corridors. Linde plc leverages captive production models to anchor long-term supply contracts at integrated steel complexes. Air Liquide sustains R&D intensity in cryogenic gas separation, while Messer Group specializes in regional bulk distribution networks that compete on logistics density rather than technology parity.
Industrial gases for metals and metal fabrication encompass oxygen, nitrogen, argon, and carbon dioxide supplied in compressed, liquid, or on-site generated forms with purity grades ranging from industrial standard to ultra-high purity for specialty alloys. These gases enable oxidation control, inert atmosphere protection, and precise thermal management across melting, welding, cutting, and heat treatment operations. Welding applications dominate volume consumption due to structural steel and automotive chassis fabrication demand, while heat treatment commands premium pricing through nitrogen-based controlled atmosphere systems. Cryogenic cooling technology is expanding fastest as superalloy producers adopt deep-freeze stress relief protocols for aerospace turbine components.
EPA emissions standards for steel mill combustion processes and OSHA confined-space rules for gas handling operations shape equipment specifications and worker training mandates across United States fabrication facilities. REACH chemical registration requirements in Europe constrain argon supply chain documentation burdens, while China's GB standards for industrial gas purity grades determine import eligibility for foreign producers. Stakeholders must monitor evolving carbon border adjustment mechanisms that will restructure cost competitiveness between regional gas production hubs and long-haul liquid supply routes.
Market Dynamics
On-site gas generation technology is compressing traditional bulk liquid supply chains as integrated steel mills and automotive stamping plants prioritize energy security over delivered convenience.
Growth Catalysts
- China's dual carbon goals:National decarbonization mandates are accelerating oxyfuel-based furnace retrofits across steel complexes, pulling oxygen demand toward captive production models.
- Aerospace-grade titanium welding:Precision fabrication standards in Germany and Japan are tightening argon purity specifications for defense and commercial aviation supply chains.
- Deep-freeze stress relief protocols:Superalloy producers are adopting cryogenic cooling technology for aerospace turbine components, expanding nitrogen consumption in heat treatment applications.
Market Restraints
- Electric arc furnace substitution:Scrap-based steelmaking reduces oxygen intensity per ton versus blast furnace routes, constraining volume growth in mature markets.
- European REACH documentation:Chemical registration requirements impose compliance burdens on argon supply chains, elevating administrative costs for importers.
- Cryogenic energy penalties:Air separation unit electricity consumption concentrates operational cost exposure in regions with volatile power pricing.
Strategic Opportunities
- India's steel expansion corridor:Greenfield integrated complexes in Odisha and Jharkhand present captive gas production deployment opportunities without legacy infrastructure displacement.
- Controlled atmosphere brazing:Hydrogen-nitrogen mixtures are penetrating automotive heat exchanger manufacturing, opening premium pricing tiers for specialty gas blends.
- Carbon border adjustment mechanisms:Emerging EU trade rules will restructure cost competitiveness between regional production hubs and long-haul liquid supply routes.
Industry Challenges
- Cryogenic system commissioning:Air separation unit startup requires specialized technician teams, creating bottlenecks in rapid deployment timelines.
- Legacy bulk tank integration:On-site generation retrofits must interface with existing liquid storage infrastructure, complicating engineering specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gases for Metals and Metal Fabrication Market |
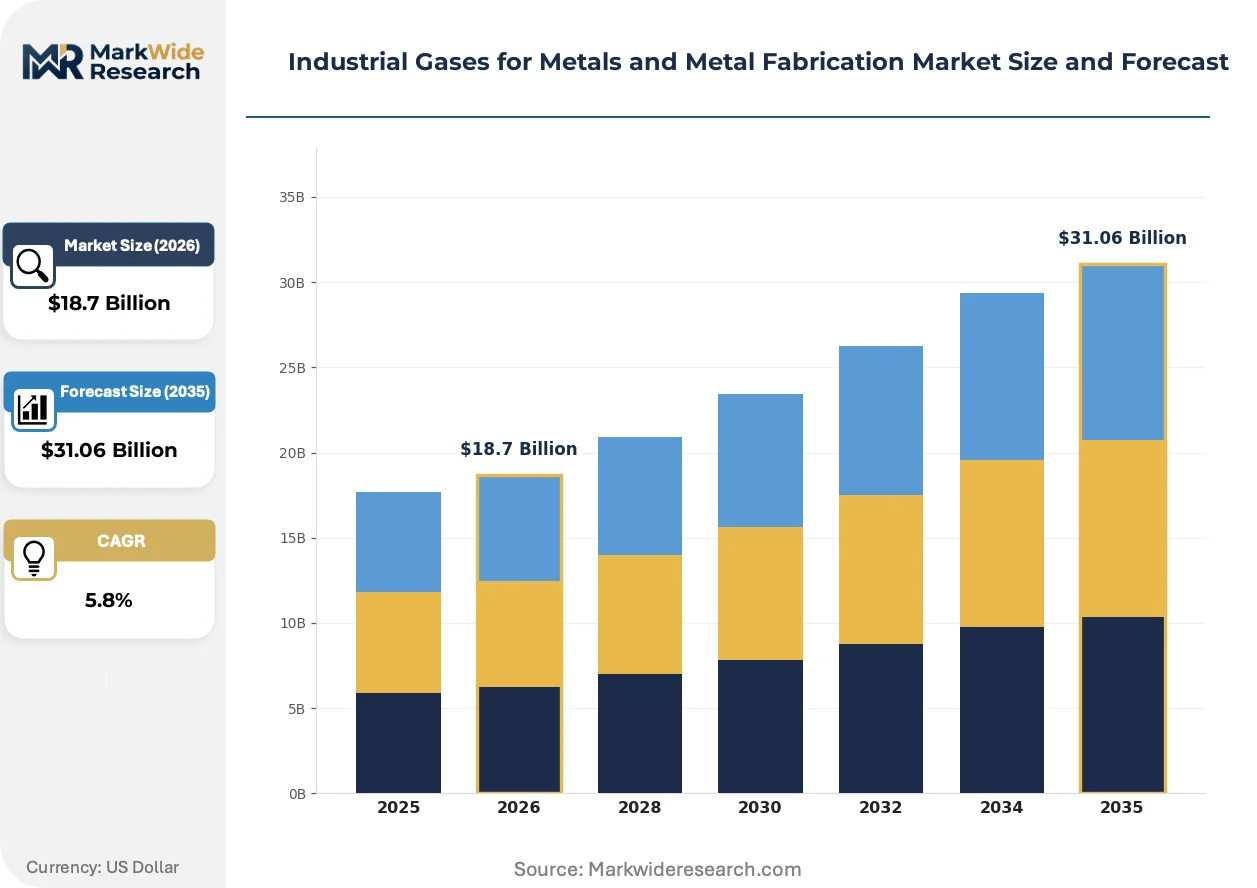
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Welding, Cutting, Heat Treatment, Metal Fabrication Product Type: Oxygen, Nitrogen, Argon, Carbon Dioxide End User: Aerospace, Automotive, Construction, Electronics Technology: Gas Separation, Cryogenic Cooling, Membrane Separation, Chemical Reaction |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Messer Group, Taiyo Nippon Sanso Corporation, Iwatani Corporation, Airgas, Praxair, nexAir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gases for Metals and Metal Fabrication Market Shifts & Advancements
Gas supply architectures are fragmenting between centralized mega-plants and distributed generation nodes as energy security concerns override pure cost optimization.
Membrane and pressure swing adsorption systems are hybridizing with traditional cryogenic separation, enabling smaller-scale nitrogen and oxygen production at automotive stamping plants. Tier-one suppliers in Michigan and Ontario are deploying these units to buffer against delivered supply disruptions. The technology is compressing minimum efficient scale thresholds, allowing mid-volume fabricators to justify captive production.
EPA emissions standards for steel mill combustion processes are tightening particulate and NOx limits, forcing oxygen enrichment upgrades across US integrated complexes. Fabricators must retrofit burner systems or face production curtailments. The regulatory pressure concentrates in Great Lakes steel corridors where aging blast furnace fleets dominate capacity.
Take-or-pay contract structures are losing ground to variable-volume agreements as automotive OEMs demand flexibility amid production schedule volatility. Gas distributors are unbundling equipment leases from molecule supply, shifting revenue toward service fees. This restructuring is most visible in North American automotive supply chains where just-in-time metal fabrication tolerates minimal inventory buffers.
Industrial Gases for Metals and Metal Fabrication Market Segmentation
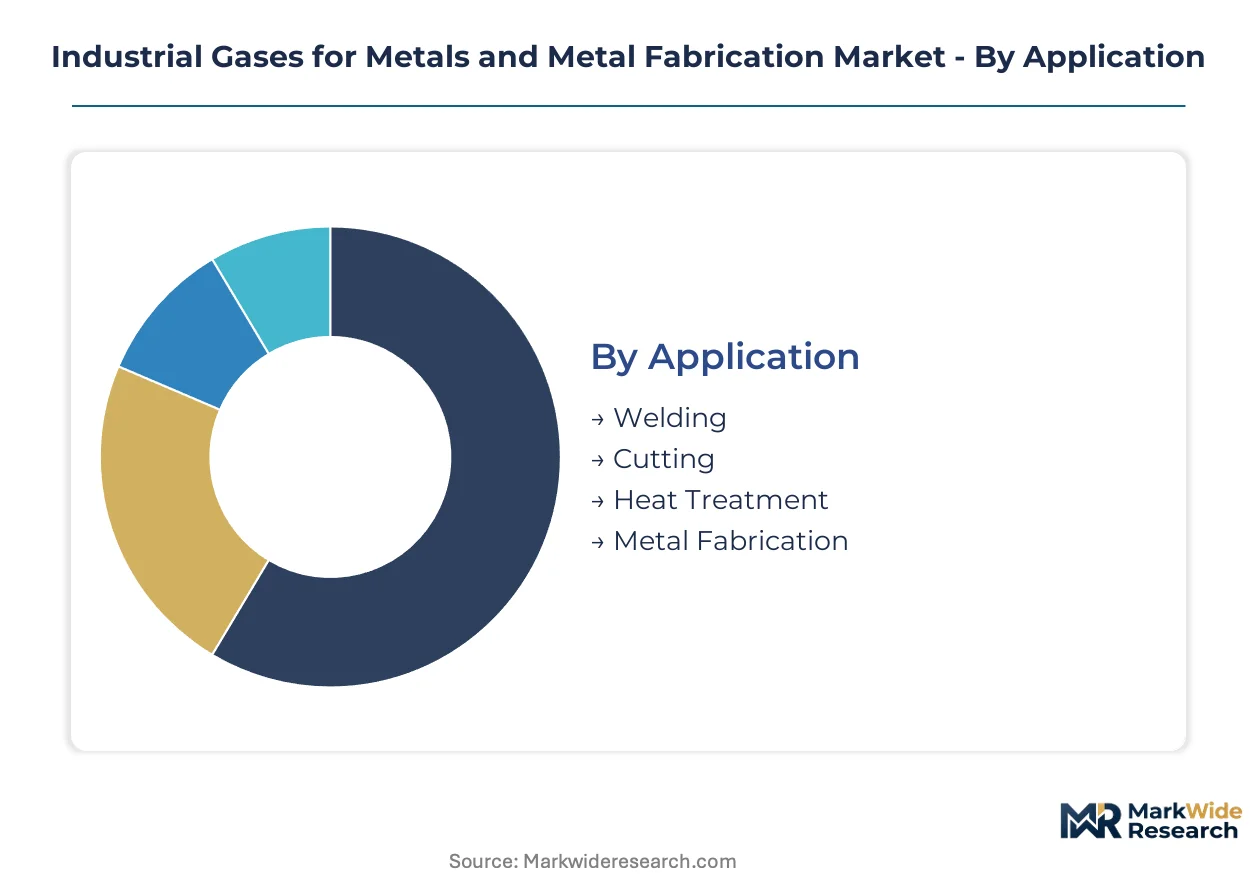
Industrial gas deployment across metals and fabrication follows distinct technical and commercial logics. Each segmentation dimension reveals how supply configurations, purity requirements, and process integration vary by end-use intensity.
Application:
The use-case spectrum spans oxidation control, thermal cutting, metallurgical transformation, and structural assembly across metalworking value chains.
- Welding:Shielding gas mixtures protect molten metal pools from atmospheric contamination during arc and laser processes. Automotive chassis fabrication in Michigan and Ontario consumes bulk argon-CO2 blends under just-in-time supply contracts.
- Cutting:High-velocity oxygen jets enable precision severing of thick steel plate. Shipyards in South Korea and Japan specify ultra-high purity oxygen for plasma cutting of marine-grade alloys.
- Heat Treatment:Controlled atmosphere furnaces use nitrogen-based systems for surface hardening and stress relief. Aerospace turbine component producers in Germany adopt deep-freeze protocols requiring cryogenic nitrogen.
- Metal Fabrication:General forming and finishing operations consume mixed gas portfolios for surface preparation and coating adhesion. Job shops across India's industrial corridors source through distributed bulk networks.
The dominant share belongs to Welding, while Heat Treatment is closing the gap fastest.
Product Type:
Cost tiers separate commodity industrial gases from specialty grades commanding purity premiums.
- Oxygen:Oxyfuel combustion and basic oxygen furnace steelmaking drive volume consumption. China's steel mills under dual carbon mandates are retrofitting blast furnaces with oxygen enrichment systems.
- Nitrogen:Inert atmosphere protection dominates heat treatment and electronics manufacturing. Cryogenic liquid nitrogen serves superalloy stress relief for aerospace turbine producers.
- Argon:Dense inert shielding properties suit precision welding of reactive metals. Aerospace-grade titanium fabrication in Japan and Germany tightens purity specifications beyond standard industrial grades.
- Carbon Dioxide:Active gas component in MAG welding and cooling applications. Automotive stamping plants blend CO2 with argon for cost-optimized shielding mixtures.
Oxygen retains volume leadership, though Argon climbs fastest on purity-driven pricing expansion.
End User:
Customer type determines contract structure, from spot bulk purchases to captive on-site generation.
- Aerospace:Precision welding and heat treatment of titanium and superalloys demand ultra-high purity argon and nitrogen. Tier-one suppliers face tightening certification requirements from airframe OEMs.
- Automotive:High-volume welding of chassis and body-in-white structures consumes bulk shielding gases. OEMs are shifting from take-or-pay contracts toward variable-volume agreements.
- Construction:Structural steel fabrication relies on standard-grade oxygen and acetylene cutting. Infrastructure stimulus in India is pulling demand toward oxyfuel-based plate processing.
- Electronics:Semiconductor and display manufacturing requires ultra-high purity nitrogen for cleanroom environments. fabs in South Korea and Taiwan specify sub-ppb contamination limits.
Automotive anchors current demand, with Electronics expanding most quickly on purity premiums.
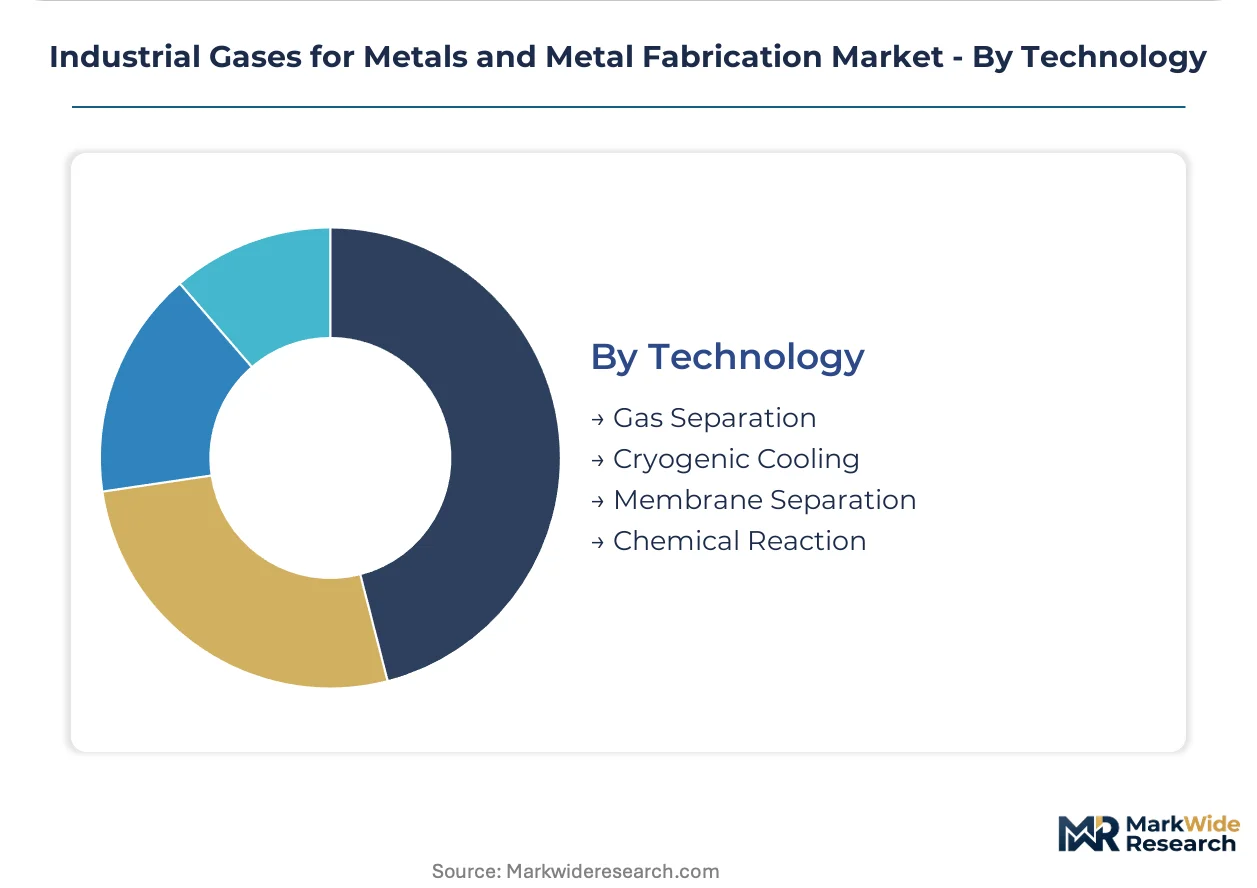
Technology:
Supply concentration varies by process maturity and minimum efficient scale thresholds.
- Gas Separation:Cryogenic air separation units produce bulk oxygen, nitrogen, and argon at mega-scale. Integrated steel complexes in China and India favor captive ASU deployment.
- Cryogenic Cooling:Deep-temperature nitrogen systems enable stress relief and shrink-fit assembly. Aerospace turbine producers adopt these protocols for nickel-based superalloys.
- Membrane Separation:Polymer membrane systems generate on-site nitrogen at smaller scale. Automotive stamping plants in North America deploy these for supply security.
- Chemical Reaction:Partial oxidation and steam methane reforming produce syngas-derived hydrogen for specialized heat treatment. Controlled atmosphere brazing of automotive heat exchangers drives niche adoption.
Gas Separation commands installed capacity, though Membrane Separation gains share fastest on distributed deployment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for industrial gases in metals fabrication tilt toward regional self-sufficiency as energy security concerns override delivered-liquid economics. Captive air separation unit deployment is compressing cross-border liquid nitrogen and oxygen trade volumes. Countries with integrated steel complexes and automotive stamping corridors are prioritizing on-site generation over import dependency.
China
Blast furnace oxygen enrichment retrofits under dual carbon goals are pulling demand toward mega-scale captive ASUs at steel complexes in Hebei and Jiangsu provinces. GB standards for industrial gas purity grades determine import eligibility, constraining foreign supplier participation. Baowu Steel's Zhongwei complex anchors the largest on-site oxygen deployment in the Asian steel corridor.
United States
EPA emissions standards for steel mill combustion are forcing oxygen system upgrades across Great Lakes blast furnace fleets. OSHA confined-space rules for gas handling shape worker training mandates at fabrication facilities in Michigan and Indiana. Detroit-area automotive stamping plants are deploying membrane nitrogen systems to buffer against supply disruptions.
Germany
Aerospace-grade argon demand for titanium welding concentrates in precision fabrication clusters under tightening DIN certification requirements. REACH chemical registration burdens elevate administrative costs for argon importers serving the Ruhr industrial basin. Hamburg and Bremen port complexes handle cryogenic liquid imports for distribution across Central European metalworking corridors.
India
Greenfield integrated steel complexes in Odisha and Jharkhand present captive gas production opportunities without legacy infrastructure displacement. PLI scheme incentives for specialty steel production are accelerating oxyfuel furnace adoption at new mills. Kalinganagar and Rourkela industrial zones anchor the fastest-expanding oxygen demand corridor in South Asia.
Japan
Precision welding standards for defense and commercial aviation supply chains tighten argon purity specifications beyond standard industrial grades. METI industrial gas quality guidelines constrain import sourcing for aerospace-tier fabricators. Nagoya and Osaka industrial corridors concentrate titanium fabrication capacity requiring ultra-high purity shielding gases.
Industrial Gases for Metals and Metal Fabrication Market Competitive Landscape
On the supply side, the industry is consolidating around integrated gas majors with captive production capabilities and regional specialists competing on logistics density. Three strategic archetypes dominate: global majors with ASU technology platforms, regional bulk distributors with tanker fleet networks, and on-site generation specialists with membrane and PSA system portfolios. Competitive moves center on long-term take-or-pay contract anchoring at integrated steel complexes and unbundled equipment lease models for automotive supply chains.
Among the global majors, Linde plc and Air Liquide exemplify the integrated technology-and-supply archetype, while Messer Group occupies a position representing regional logistics-intensive competition. These three anchors illustrate how competitive positioning fragments between technology-driven captive production and distribution-density bulk supply. Smaller specialists in on-site generation systems sit within a separate tier serving mid-volume fabricators seeking supply security over delivered-liquid convenience.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals |
| Messer Group |
| Taiyo Nippon Sanso Corporation |
| Iwatani Corporation |
| Airgas |
| Praxair |
| nexAir |
| Others |
Supply & Pricing Matrix
Single-source dependency on cryogenic air separation unit technology concentrates pricing power among integrated gas majors while simultaneously tethering supply chain resilience to electricity grid stability in steel corridor geographies. This structural concentration determines both the spread between premium ultra-high purity grades and commodity industrial tiers, and the geographic clustering of captive production investments versus distributed bulk distribution networks.
Pricing Analysis
Industrial OEM buyers anchor contract structures around long-term take-or-pay agreements with embedded volume floors and electricity pass-through clauses. Pricing stratifies across aerospace-grade argon, automotive bulk blends, and standard industrial oxygen tiers, with purity certification levels and captive versus delivered supply models as the primary differentiation drivers. Cost compression in commodity oxygen is intensifying as Chinese steel mills accelerate captive ASU deployment under dual carbon mandates. Automotive stamping plants exhibit highest price sensitivity due to just-in-time inventory constraints, while aerospace fabricators tolerate premium pricing for certified ultra-high purity grades.
Supply Chain Analysis
Export control regimes on cryogenic heat exchanger and distillation column technology constrain ASU equipment flows to certain steel-producing jurisdictions, compressing supply chain optionality for greenfield projects. Geographic concentration centers on China, the United States, and Germany for mega-scale air separation capacity, with India and Japan as secondary hubs. Raw material dependencies draw from specialized aluminum alloy cold boxes, molecular sieve adsorbents, and precision compressor systems. Single-source vulnerability concentrates in cryogenic equipment engineering expertise. Distribution runs through regional bulk liquid tanker fleets for mid-volume fabricators and direct pipeline connections for integrated steel complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from on-site membrane and pressure swing adsorption systems that displace traditional bulk liquid supply in automotive and mid-volume fabrication segments.
For Market Incumbents: Harden contract anchoring at integrated steel complexes through bundled equipment lease and molecule supply agreements that raise switching costs for oxygen-intensive blast furnace operators. Deepen backward integration into cryogenic equipment manufacturing to capture margin pools currently flowing to specialized engineering houses. Priority investment in modular ASU designs that retrofit legacy bulk tank infrastructure without production disruption. For New Entrants and Emerging Players: India's Odisha and Jharkhand steel expansion corridors present underpenetrated white space for captive gas production deployment without incumbent legacy infrastructure displacement. Membrane nitrogen systems for North American automotive stamping plants offer the most penetrable entry point, competing on supply security rather than unit cost parity. Go-to-market angle: unbundled equipment-as-a-service models that separate capital expenditure from molecule procurement decisions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional bulk distributors with dense tanker fleet networks and established logistics infrastructure over pure technology plays. Long-term viability rests on exposure to steel decarbonization capital cycles and aerospace precision fabrication certification requirements. Acquisition target archetype: mid-scale membrane and PSA system specialists with automotive OEM relationships. Signal to watch: carbon border adjustment mechanism implementation timelines that restructure cost competitiveness between regional production hubs and long-haul liquid supply routes.| Strategic Initiative | Industry Significance |
|---|---|
| Captive ASU Deployment at Integrated Steel Complexes | Baowu Steel's Zhongwei complex anchors the largest on-site oxygen installation in the Asian steel corridor. |
| Membrane Nitrogen System Rollout | Michigan and Ontario automotive stamping plants deploy these units to buffer against delivered supply disruptions. |
| Ultra-High Purity Argon Certification Investment | German and Japanese aerospace fabricators face tightening DIN and METI quality guidelines for titanium welding. |
| Backward Integration into Cryogenic Equipment | Air Liquide sustains R&D intensity in cryogenic gas separation to capture engineering margin pools. |
| Unbundled Equipment Lease Restructuring | North American automotive OEMs shift from take-or-pay contracts toward variable-volume service fee models. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings from integrated gas majors, and national steel production statistics preceded structured interviews with plant managers at blast furnace complexes, procurement leads at automotive OEMs, and technical R&D directors at air separation equipment manufacturers. Primary fieldwork combined with secondary validation from EPA emissions filings, ECHA REACH registration databases, and China's GB standards documentation enabled bottom-up and top-down triangulation across volume and value estimates.
Assumptions held fixed include continuation of China's dual carbon policy trajectory, EPA emissions standard enforcement timelines, and REACH chemical registration documentation burdens for argon importers. Variable conditions across the analysis window encompass electricity price volatility in steel corridor geographies, carbon border adjustment mechanism implementation schedules, and automotive production schedule volatility. Segmentation dimensions modeled include application intensity, product purity grade, end-user contract structure, and technology deployment scale. CAGRs were derived from production capacity expansion announcements, steel mill retrofit timelines, and aerospace certification pipeline data.
Practitioners should monitor captive ASU commissioning delays, cryogenic electricity cost spikes, and carbon border adjustment mechanism final rules for early signals of forecast deviation. Forecasts reflect assumptions about regulatory enforcement continuity and technology substitution rates. Material shifts in national decarbonization policy stringency or breakthrough membrane system cost reductions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Krypton-85 Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Food-Grade Gases Market