
 High Purity Lead Market | 2026-2036
High Purity Lead Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Lead Market Outlook
Specialty metal distribution is fragmenting as battery-grade and electronic-grade buyers split procurement channels by purity certification. Nuclear Lead Company dominates shielding-grade supply through captive smelter partnerships in North America. Pure Lead Innovations leverages laboratory-grade refining to anchor European electronics demand. Stargen Solutions competes on ISO-certified powder production for Asian chemical processors.
High purity lead denotes refined metal exceeding 99.99% purity, achieved through electrolytic refining or vacuum distillation to remove bismuth, silver, and antimony traces for critical applications. Battery-grade material commands the largest volume share as lithium-ion anode current collectors and stationary storage terminals expand, while electronic-grade ingots capture premium margins from semiconductor packaging and radiation shielding in nuclear medicine equipment. Powder and wire forms are outpacing traditional ingot demand in additive manufacturing and precision electronics.
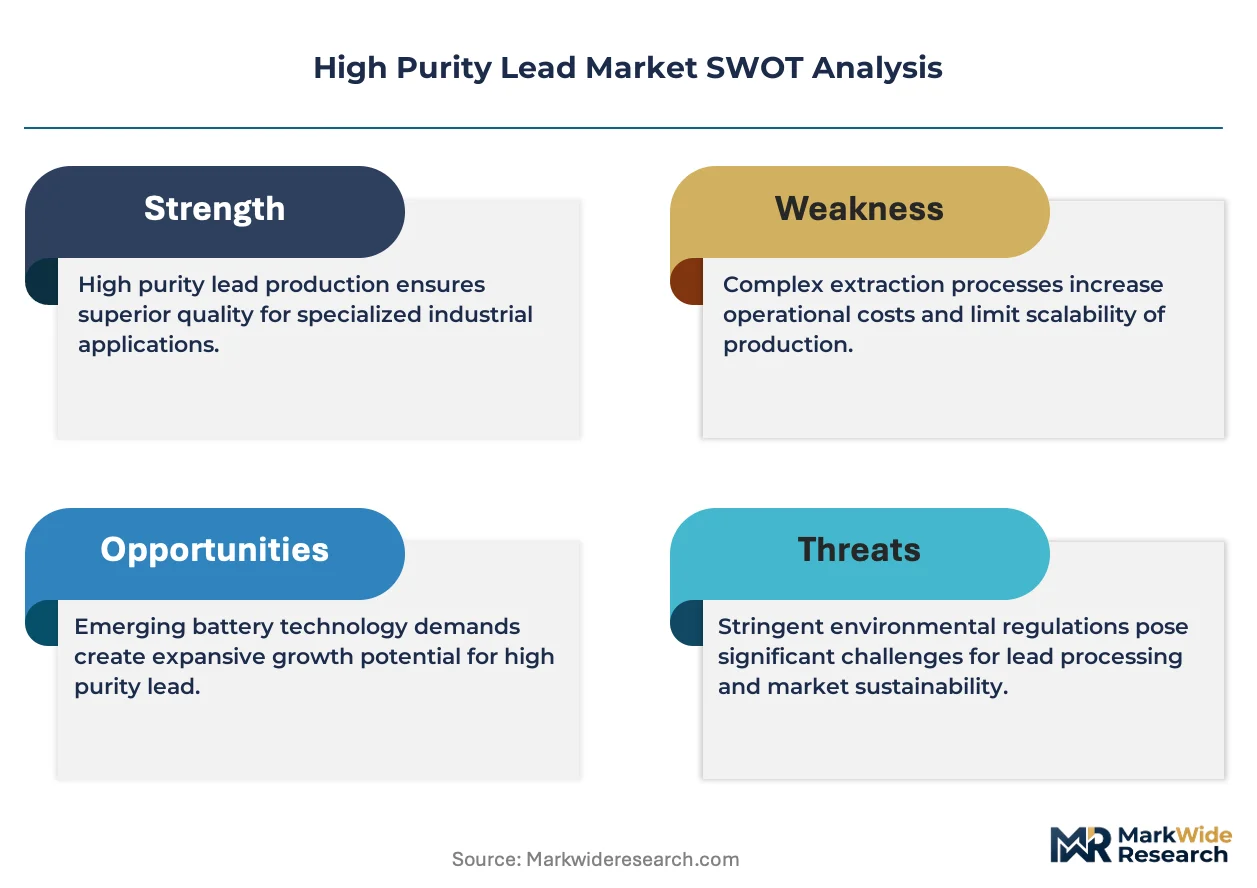
EPA hazardous waste rules and OSHA lead exposure limits govern US smelter emissions and workplace protocols, while REACH and RoHS in Europe restrict certain alloy additives in consumer-facing applications. China's NMPA and GB standards enforce stricter electronic-grade import thresholds. Stakeholders must monitor regulatory divergence between jurisdictions to align refining investments with divergent certification requirements.
Market Dynamics
China's NMPA and GB standards are tightening electronic-grade purity thresholds, forcing importers to retool refining capabilities or exit certification-heavy segments entirely.
Growth Catalysts
- Reactor construction:Nuclear facilities across China, France, and the United Arab Emirates are expanding radiation shielding procurement as fission plant buildouts accelerate.
- RoHS and REACH alignment:European electronics manufacturers are substituting legacy alloys with high-purity lead to meet restricted substance mandates in semiconductor packaging.
- Battery-grade powder demand:Lithium-ion anode current collectors in South Korean cathode production are absorbing rising volumes of 99.99%+ refined material.
Market Restraints
- Crude lead price volatility:Primary smelter feedstock costs fluctuate with LME pricing, compressing margins for electrolytic refiners dependent on spot market sourcing.
- Smelter concentration:Captive North American refining partnerships limit third-party access to shielding-grade certification channels.
- Bismuth removal limits:Vacuum distillation throughput caps prevent rapid scaling of 6N+ purity output for laboratory applications.
Strategic Opportunities
- Indian electronics manufacturing:BIS certification requirements for imported electronic-grade materials create first-mover advantages for compliant refiners establishing local assay partnerships.
- Additive manufacturing wire:Precision electronics producers in Japan are qualifying high-purity lead wire for 3D-printed shielding components in medical imaging equipment.
- EU Green Deal smelter incentives:Carbon capture retrofits at European electrolytic facilities qualify for transitional funding, lowering capital barriers to capacity expansion.
Industry Challenges
- Assay technician scarcity:ICP-MS and glow discharge mass spectrometry expertise is concentrated among retiring specialists at German and Japanese certification laboratories.
- Multi-jurisdiction certification timelines:Simultaneous NMPA, REACH, and FDA material master file approvals extend product launch cycles by 18-24 months for nuclear medicine shielding suppliers.
- Legacy alloy integration:Semiconductor packaging lines running antimonial lead solder require complete flux and temperature profile revalidation when switching to high-purity alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Lead Market |
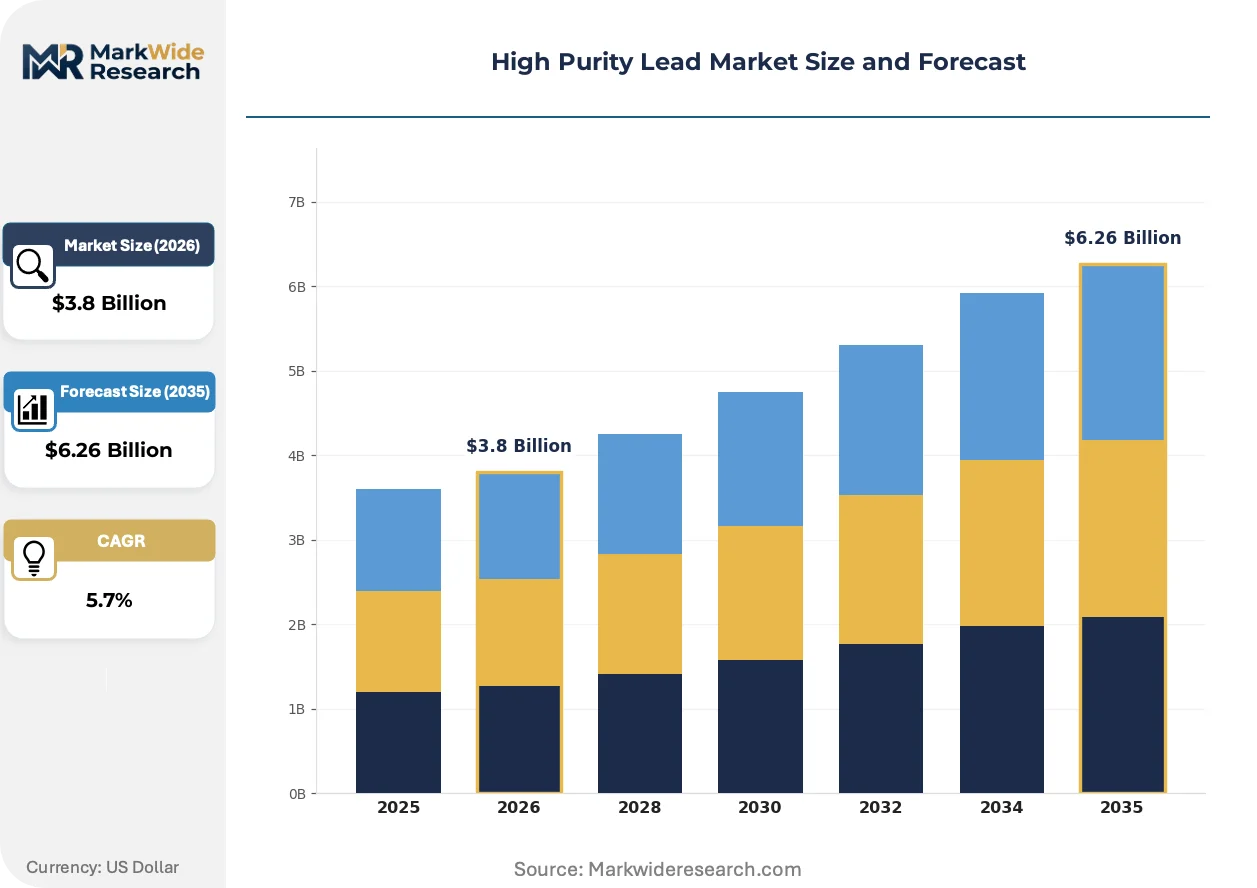
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Grade: Industrial Grade, Electronic Grade, Battery Grade, Chemical Grade Form: Ingot, Powder, Sheet, Wire, Pellet Application: Batteries, Radiation Shielding, Electronics Manufacturing, Chemical Processing End User Industry: Energy Storage, Consumer Electronics, Nuclear Facilities, Chemical Manufacturers |
| Companies Covered | Stargen Solutions, Pure Lead Innovations, Nuclear Lead Company, Lead Refining Corp, Clean Lead Systems, Advanced Lead Technologies, Lead Pure Solutions, Lead Recycling Industries, Lead Masters International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Lead Market Strategic Shifts
Refining automation and real-time purity monitoring are compressing batch-to-batch variation, while regulatory divergence between Asian and European certification regimes is fragmenting supplier qualification pathways.
Electrolytic refining control systems are digitizing cell voltage and electrolyte composition adjustments through AI-driven feedback loops. Japanese semiconductor packaging operations are deploying these systems to maintain 5N purity consistency across 10,000+ hour production runs. This capability is digitizing quality assurance documentation for FDA and PMDA material master file submissions, collapsing certification preparation timelines.
REACH substance restriction updates are expanding controlled impurity lists for electronic-grade lead alloys used in consumer-facing devices. German and French electronics assemblers are reformulating solder compositions to preempt anticipated antimony and cadmium threshold reductions. Battery-grade suppliers serving stationary storage terminals face lighter compliance burdens, creating a two-tier regulatory exposure landscape.
Buyers are consolidating vendor panels around dual-certified refiners capable of supplying both nuclear shielding and battery-grade material from shared smelter assets. South Korean cathode manufacturers and Japanese semiconductor packagers are conducting joint supplier audits to reduce qualification overhead. This concentration is most visible in East Asian manufacturing clusters, where procurement teams prioritize ISO-certified powder and ingot producers with multi-segment track records.
High Purity Lead Market Segmentation
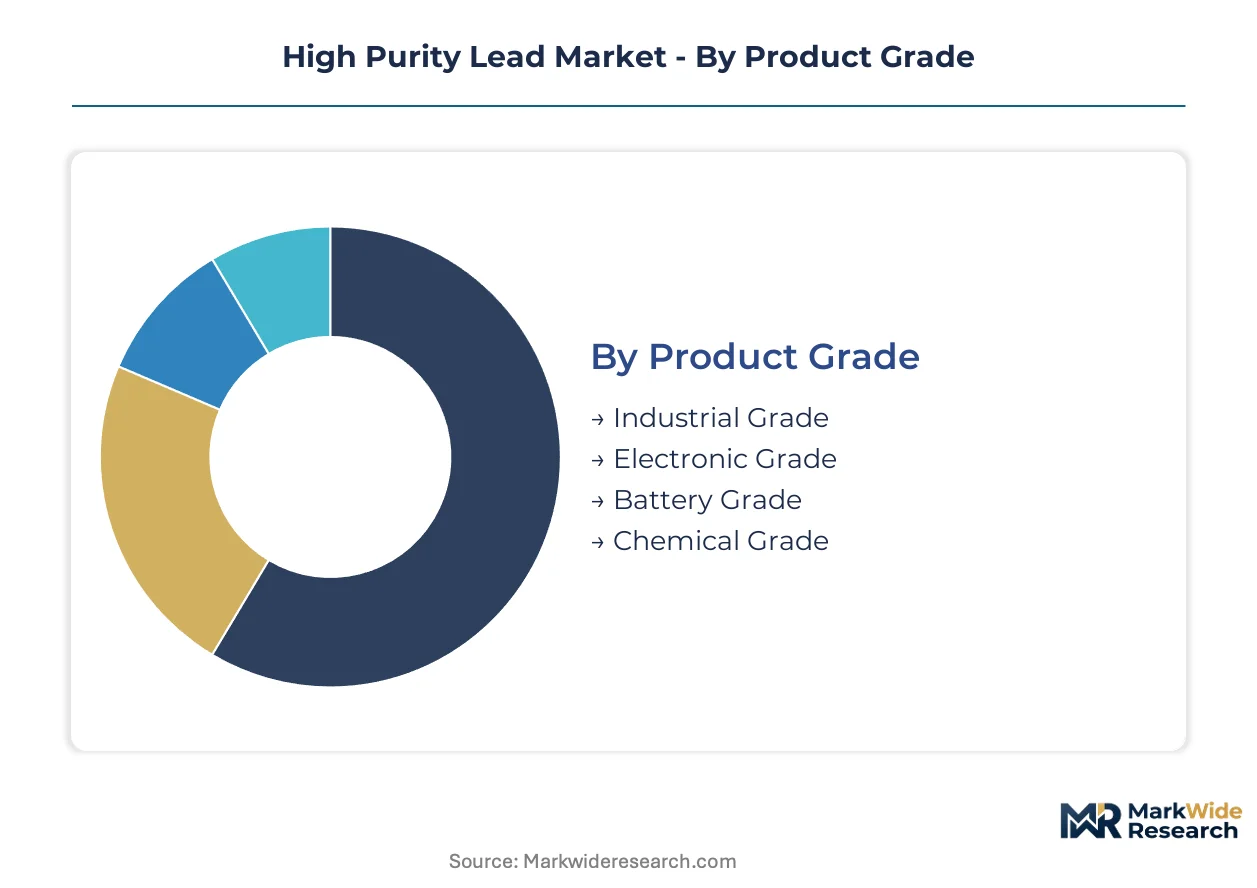
High purity lead serves radically different performance requirements across nuclear shielding, semiconductor packaging, and battery current collectors. Each segment demands distinct purity thresholds, certification regimes, and physical forms that reshape supplier economics and procurement patterns.
Product Grade:
Purity thresholds define the use-case spectrum from commodity industrial feedstock to laboratory-grade material.
- Industrial Grade:Refined metal meeting 99.9% purity specifications serves general manufacturing and alloying applications where trace element tolerance remains wider. Chinese smelters dominate this tier through cost-optimized electrolytic refining serving domestic construction and automotive battery terminals.
- Electronic Grade:Material exceeding 99.99% purity with controlled bismuth and silver content enables semiconductor packaging and precision soldering. Japanese semiconductor operations in Osaka and Kyoto clusters drive qualification timelines for 5N+ consistency across extended production runs.
- Battery Grade:99.99%+ refined lead optimized for lithium-ion anode current collectors and stationary storage terminals. South Korean cathode manufacturers in Gumi and Ochang industrial parks absorb rising volumes as energy storage buildouts accelerate.
- Chemical Grade:Ultra-high purity material for laboratory reagents and specialized catalyst precursors. Vacuum distillation throughput constraints limit scalable supply for 6N+ applications.
The dominant share belongs to Battery Grade, while Electronic Grade is closing the gap fastest.
Form:
Physical configuration determines downstream processing economics and automation compatibility.
- Ingot:Traditional cast blocks remain the standard unit for bulk shielding fabrication and alloying operations. Nuclear facilities in France and the United Arab Emirates specify ingot form for gamma radiation vault casting.
- Powder:Atomized and electrolytic powder enables additive manufacturing feedstock and chemical synthesis. ISO-certified powder producers serving Asian chemical processors command premium spreads over ingot equivalents.
- Sheet:Rolled plate for radiation shielding walls and medical imaging equipment housings. German and Japanese fabricators maintain dedicated rolling mills for nuclear medicine OEM supply chains.
- Wire:Precision-drawn filament for 3D-printed shielding components and microelectronic interconnects. Japanese medical imaging equipment producers are qualifying high-purity lead wire for additive manufacturing integration.
- Pellet:Granular form optimized for chemical vapor deposition and specialty alloy master batch production. Pellet demand concentrates in European catalyst manufacturing.
Ingot retains volume leadership, though Powder is expanding most quickly as additive manufacturing qualifications multiply.
Application:
End-use performance requirements fragment procurement channels by certification burden and purity threshold.
- Batteries:Lithium-ion anode current collectors and stationary storage terminals absorb the largest volume of 99.99%+ material. South Korean and Chinese cell manufacturers drive specification convergence around impurity limits for electrochemical stability.
- Radiation Shielding:Gamma and neutron attenuation in nuclear reactors, medical imaging, and particle physics facilities demands high density and corrosion resistance. Reactor construction in China, France, and the United Arab Emirates is accelerating shielding-grade procurement.
- Electronics Manufacturing:Semiconductor packaging, solder alloys, and precision interconnects require 5N+ purity with documented trace element profiles. REACH and RoHS alignment is forcing European assemblers to reformulate legacy antimonial compositions.
- Chemical Processing:Catalyst precursors, laboratory reagents, and specialty compound synthesis utilize ultra-high purity feedstock. Chemical Grade material in this channel faces lighter regulatory compliance burdens than consumer-facing electronics applications.
Batteries command the dominant application share, while Radiation Shielding is climbing the fastest as fission plant buildouts accelerate.
End User Industry:
Customer concentration patterns determine supplier qualification investments and contract structures.
- Energy Storage:Battery cell manufacturers and stationary storage integrators purchase the largest volumes of refined material. Procurement teams in South Korean manufacturing clusters prioritize dual-certified suppliers with multi-segment track records.
- Consumer Electronics:Smartphone, laptop, and wearable device assemblers specify solder and shielding materials. European electronics manufacturers are substituting legacy alloys to meet anticipated REACH substance restriction updates.
- Nuclear Facilities:Fission reactor operators and medical isotope producers require shielding-grade certification with full material traceability. Multi-jurisdiction approval timelines for NMPA, FDA, and PMDA master files extend supplier onboarding cycles.
- Chemical Manufacturers:Catalyst producers and specialty chemical synthesizers utilize high-purity lead for process chemistry. This segment faces lighter compliance burdens than consumer-facing electronics or nuclear medicine applications.
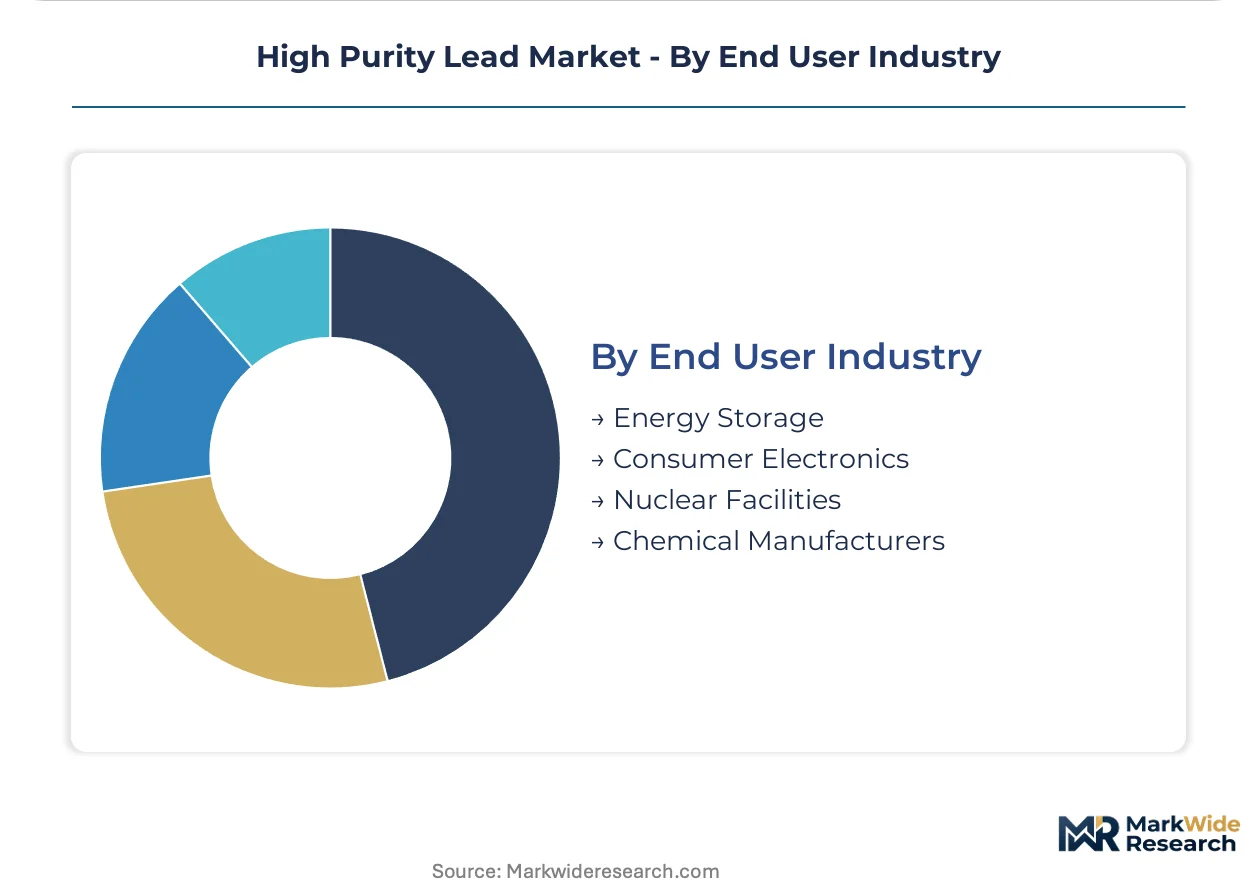
Energy Storage holds the dominant share, while Nuclear Facilities is gaining share fastest as reactor construction expands across multiple geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese refiners extract 15-20% price premiums on electronic-grade exports to European buyers, while North American shielding-grade contracts trade at narrower spreads due to captive smelter partnerships. This asymmetry reflects divergent certification burdens and reactor construction timelines across major demand centers.
China
Reactor construction in Fujian and Guangdong provinces is accelerating radiation shielding procurement from domestic smelters. NMPA and GB standards are tightening electronic-grade import thresholds, forcing foreign suppliers to retool refining capabilities or exit certification-heavy segments. Yangtze River Delta battery cathode manufacturers in Suzhou and Changzhou are absorbing rising volumes of 99.99%+ refined material for lithium-ion current collectors.
United States
Nuclear medicine equipment producers in Minnesota and Massachusetts are qualifying high-purity lead wire for additive manufacturing integration. EPA hazardous waste rules and OSHA lead exposure limits govern domestic smelter emissions and workplace protocols, compressing margins for electrolytic refiners dependent on spot market sourcing. Captive North American refining partnerships around the Great Lakes limit third-party access to shielding-grade certification channels.
Germany
Electronics assemblers in Bavaria and Baden-Württemberg are reformulating solder compositions to preempt anticipated REACH substance restriction updates. EU Green Deal smelter incentives for carbon capture retrofits at electrolytic facilities qualify for transitional funding, lowering capital barriers to capacity expansion. Frankfurt-area certification laboratories maintain concentrated ICP-MS and glow discharge mass spectrometry expertise for multi-jurisdiction approvals.
South Korea
Cathode manufacturers in Gumi and Ochang industrial parks are conducting joint supplier audits with Japanese semiconductor packagers to reduce qualification overhead. MFDS alignment with international material master file standards is streamlining nuclear medicine shielding approvals. Seoul-based procurement teams prioritize dual-certified refiners capable of supplying both battery-grade and electronic-grade material from shared assets.
Japan
Semiconductor packaging operations in Osaka and Kyoto clusters drive qualification timelines for 5N+ purity consistency across extended production runs. PMDA material master file submissions require digitized quality assurance documentation, collapsing certification preparation timelines for compliant suppliers. METI-funded refining automation programs are deploying AI-driven feedback loops for real-time purity monitoring in electrolytic cell operations.
High Purity Lead Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower certification scope but higher purity thresholds. The vendor base separates into three strategic tiers: captive smelter partnerships serving nuclear shielding, laboratory-grade refiners anchoring European electronics demand, and ISO-certified powder producers competing on Asian chemical processing contracts. Dominant competitive moves include backward integration into primary smelter feedstock and multi-jurisdiction certification stacking to extend product launch cycles.
Within the captive partnership tier, Nuclear Lead Company exemplifies North American shielding-grade concentration through smelter alliances. Pure Lead Innovations occupies a position among European laboratory-grade specialists leveraging vacuum distillation capabilities. Stargen Solutions represents the ISO-certified powder production archetype serving Asian chemical processors. These three anchors illustrate how geographic certification requirements fragment competitive positioning across reactor construction, semiconductor packaging, and battery cathode supply chains.
| Leading Market Players |
|---|
| Stargen Solutions |
| Pure Lead Innovations |
| Nuclear Lead Company |
| Lead Refining Corp |
| Clean Lead Systems |
| Advanced Lead Technologies |
| Lead Pure Solutions |
| Lead Recycling Industries |
| Lead Masters International |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Great Lakes captive smelter partnerships determines both the narrow pricing spreads in North American shielding-grade contracts and the regional supply chain's resistance to third-party entrants. Crude lead price volatility on the LME feeds directly into electrolytic refiner margins, compressing returns for spot-market-dependent producers while reinforcing the cost advantage of vertically integrated operators.
Pricing Analysis
The customization-premium spread separates standard ingot quotations from configured-to-order powder and wire specifications. Battery-grade material operates on long-term offtake contracts anchored to LME benchmarks with volume-scale adjustments, while electronic-grade commands certification-level premiums reflecting NMPA and REACH compliance burdens. Cost compression in battery-grade tiers is intensifying as South Korean cathode manufacturers consolidate vendor panels around dual-certified suppliers. Semiconductor packaging operations show least price sensitivity due to 5N+ purity requirements and multi-jurisdiction master file investments.
Supply Chain Analysis
Tariff exposure between Chinese electronic-grade exporters and European buyers dominates supply chain risk calculations, with NMPA-aligned refiners extracting 15-20% premia over standard industrial material. Primary concentrate draws from Australian and Canadian mining operations, while electrolytic refining capacity concentrates in China, Germany, and Japan. Single-source vulnerability around ICP-MS assay expertise at Frankfurt and Osaka certification laboratories threatens qualification timelines for nuclear medicine shielding suppliers. Distribution runs through specialty metal distributors fragmenting procurement channels by purity certification tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where multi-jurisdiction certification timelines create switching costs that lock in qualified suppliers and resist price-based displacement.
For Market Incumbents: Build certification moats by stacking NMPA, FDA, and PMDA material master files simultaneously, extending product launch cycles for competitors by 18-24 months. Deepen backward integration into primary smelter feedstock around the Great Lakes to defend against LME volatility and secure shielding-grade allocation priority. Channel control through captive distributor partnerships limits third-party access to nuclear facility procurement channels. For New Entrants and Emerging Players: Pursue BIS certification partnerships in Indian electronics manufacturing clusters, where import requirements for electronic-grade materials create first-mover advantages for compliant assay operations. Target additive manufacturing wire qualifications with Japanese medical imaging equipment producers, a segment where 3D-printed shielding component demand outpaces established supply. Go-to-market leverage rests on METI-funded refining automation programs for real-time purity documentation. For Investors and Strategic Acquirers: The market sits at a reactor construction acceleration phase that favors shielding-grade specialists with captive smelter access and multi-jurisdiction approval track records. Long-term viability hinges on regulatory divergence between Asian and European certification regimes persisting through the analysis window. Acquisition archetype: electrolytic refiners with digitized quality assurance systems and existing ISO-certified powder production. Signal to watch: EU Green Deal smelter incentive uptake rates as carbon capture retrofit funding lowers European capacity expansion barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Stacking | Simultaneous NMPA, FDA, and PMDA filings collapse competitor launch timelines by 18-24 months. |
| Backward Integration into Primary Smelter Feedstock | Captive concentrate supply from Great Lakes partnerships insulates margins against LME volatility. |
| Refining Automation and Real-Time Purity Monitoring | AI-driven electrolytic cell control systems digitize documentation for FDA and PMDA submissions. |
| Carbon Capture Retrofit at European Facilities | EU Green Deal transitional funding lowers capital barriers to electrolytic capacity expansion. |
| Joint Supplier Audits with Downstream Partners | South Korean cathode manufacturers and Japanese semiconductor packagers reduce qualification overhead through shared audits. |
Study Parameters
Operator-level perspectives from electrolytic refinery plant managers, specialty metal procurement leads at South Korean cathode manufacturers, nuclear facility shielding engineers, and ICP-MS assay technicians at German certification laboratories anchored the qualitative base. Secondary validation drew from customs and trade data for high purity lead shipments, SEC filings from integrated smelter operators, NMPA and FDA material master file databases, and REACH substance restriction update notices. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario bracketing around reactor construction timelines, NMPA standard implementation pace, and EU Green Deal funding disbursement framed the projection horizon. The analytical model segmented by product grade tier, physical form, end-use application, and regional regulatory cluster, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements. Industry-specific inputs included lithium-ion anode current collector specifications, nuclear shielding density requirements, and semiconductor packaging solder composition reformulation timelines.
Sensitivities concentrate around crude lead price volatility, multi-jurisdiction certification timeline extensions, and assay technician retirement rates at concentrated certification laboratories. Forecasts reflect documented assumptions regarding reactor construction completion schedules and regulatory divergence persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Heat-Treated Steel Plates Market
Metals
Gold Smelting Market
Metals
Rubidium Market
Metals
Aluminum Fluoride Market
Metals
Rolled Steel Motor Market
Metals
Saudi Arabia Aluminum Market
Metals
Silver Nitrate Market
Metals
Nickel Sulfate Market
Metals
Global Bronze Market
Metals
Aluminum Flat Products Market
Metals
Global Tantalum Market
Metals
High Purity Boron Market
Metals
Monel Alloy Market
Metals
Aluminum Ingots Market
Metals
Metallic Rope Cords Market
Metals
High Purity Base Metals Market