
 Global Industrial Nitrogen Generator Market | 2026-2036
Global Industrial Nitrogen Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Nitrogen Generator Market Outlook
The capital-intensity gap between engineered-systems specialists and commoditized assemblers is bifurcating competitive returns in industrial nitrogen generation. Parker Hannifin Corp leverages its filtration heritage to dominate membrane technology integration for food packaging lines. Atlas Copco Group anchors its position through compressor-nitrogen bundling that sustains aftermarket revenue streams across European automotive plants.
Industrial nitrogen generators are systems that separate nitrogen from compressed air through pressure swing adsorption, membrane permeation, or cryogenic distillation, typically delivering 95% to 99.999% purity depending on the separation mechanism and end-use requirement. These units serve primarily to displace oxygen in manufacturing processes, prevent oxidation in metal heat treatment, and maintain inert atmospheres for electronics soldering operations. Pressure swing adsorption systems occupy the largest installed base owing to their reliability in continuous-flow chemical processing, while membrane generators are gaining ground in food packaging where moderate purity suffices and capital outlay must stay low. Cryogenic units retain margin concentration at the highest purity thresholds demanded by pharmaceutical aseptic filling and semiconductor wafer fabrication.
The US FDA enforces Current Good Manufacturing Practice standards that mandate nitrogen purity documentation in pharmaceutical packaging, directly elevating validation requirements for generator suppliers seeking drug-manufacturer contracts. The EU F-Gas Regulation and REACH framework indirectly boost nitrogen generator demand by restricting synthetic fluorinated gases historically used as protective atmospheres, redirecting process engineers toward inert gas alternatives. China GB standards and the National Medical Products Administration impose parallel purity and materials-of-construction rules that filter market access for imported equipment. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving semiconductor subsidy regimes in the United States, European Union, and China reshape the geographic economics of onsite versus delivered nitrogen.
Market Dynamics
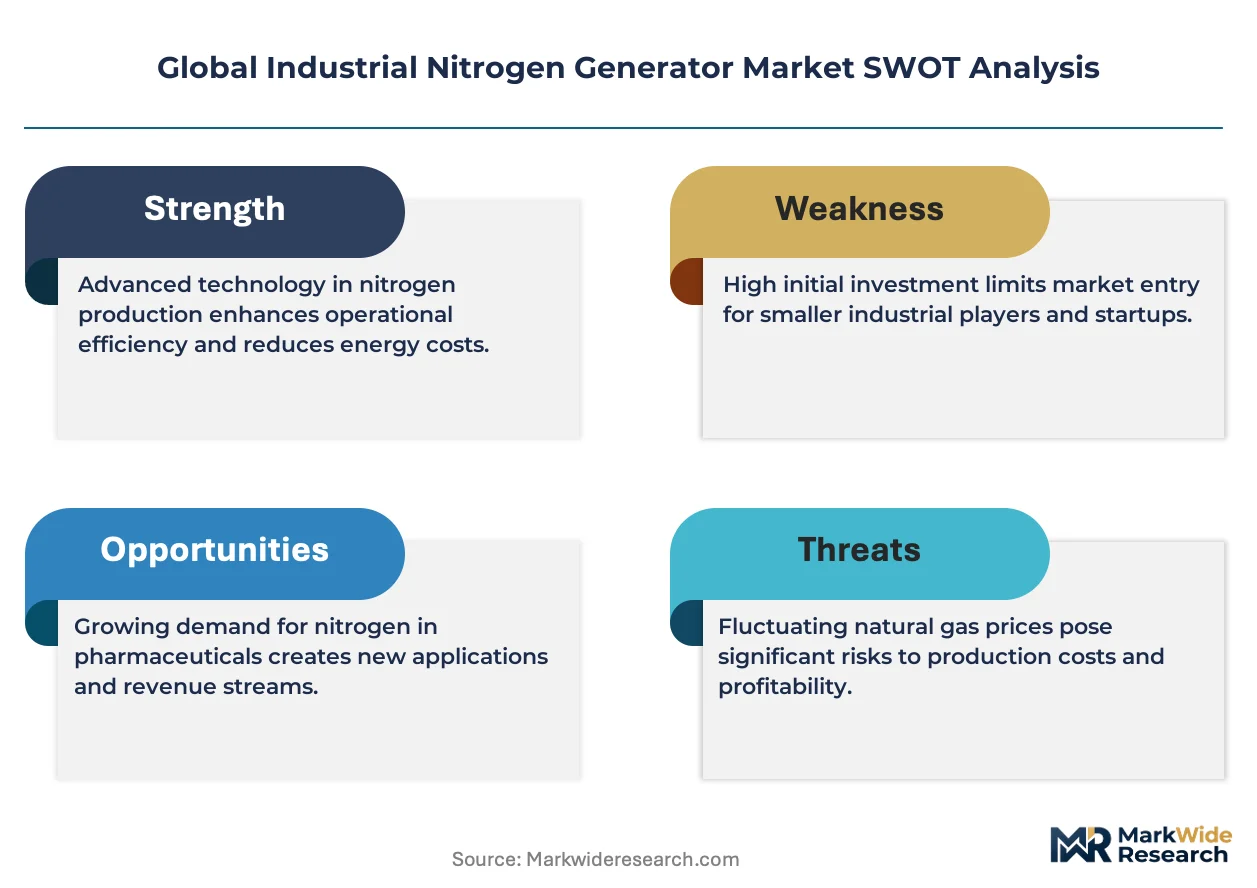
The industrial nitrogen generator market is bifurcating around capital efficiency thresholds, with membrane systems capturing food packaging volume while pressure swing adsorption retains chemical processing dominance where purity documentation carries regulatory weight.
Growth Catalysts
- EU F-Gas Regulation phase-down:Restrictions on synthetic fluorinated gases redirect process engineers toward inert nitrogen atmospheres in metal heat treatment and electronics soldering operations.
- Modified atmosphere packaging mandates:FDA and EFSA food safety requirements tighten oxygen displacement protocols across protein and snack packaging lines, accelerating onsite nitrogen adoption.
- Semiconductor fabrication cluster expansion:Wafer fabrication facilities in Taiwan, South Korea, and the United States require ultra-high purity nitrogen for cleanroom environments, sustaining cryogenic system demand.
Market Restraints
- Compressed air energy intensity:Nitrogen generation consumes 7-10 kWh per 100 cubic meters, exposing operators to electricity price volatility in Germany and industrial Chinese provinces.
- Zeolite molecular sieve supply concentration:Pressure swing adsorption systems depend on specialized adsorbent materials sourced primarily from Chinese and U.S. specialty chemical producers.
- Validation documentation burden:FDA Current Good Manufacturing Practice standards impose multi-month qualification timelines for pharmaceutical-grade nitrogen systems, extending sales cycles.
Strategic Opportunities
- India food processing infrastructure:FSSAI packaging regulations and cold chain expansion create first-mover advantage for membrane generator deployments in dairy and spice processing hubs.
- Carbon border adjustment alignment:EU CBAM implementation incentivizes European manufacturers to displace delivered liquid nitrogen with onsite generation to reduce transport emissions.
- IoT-enabled predictive maintenance:Remote monitoring integration with existing compressor networks allows aftermarket service bundling and uptime guarantees for automotive plant contracts.
Industry Challenges
- Cross-functional commissioning expertise:Integration of nitrogen generators with existing compressed air infrastructure requires rare combinations of pneumatic, electrical, and process safety competencies.
- Multi-jurisdiction certification stacking:Equipment destined for pharmaceutical export markets must simultaneously satisfy FDA, EMA, and NMPA documentation requirements, multiplying engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Nitrogen Generator Market |
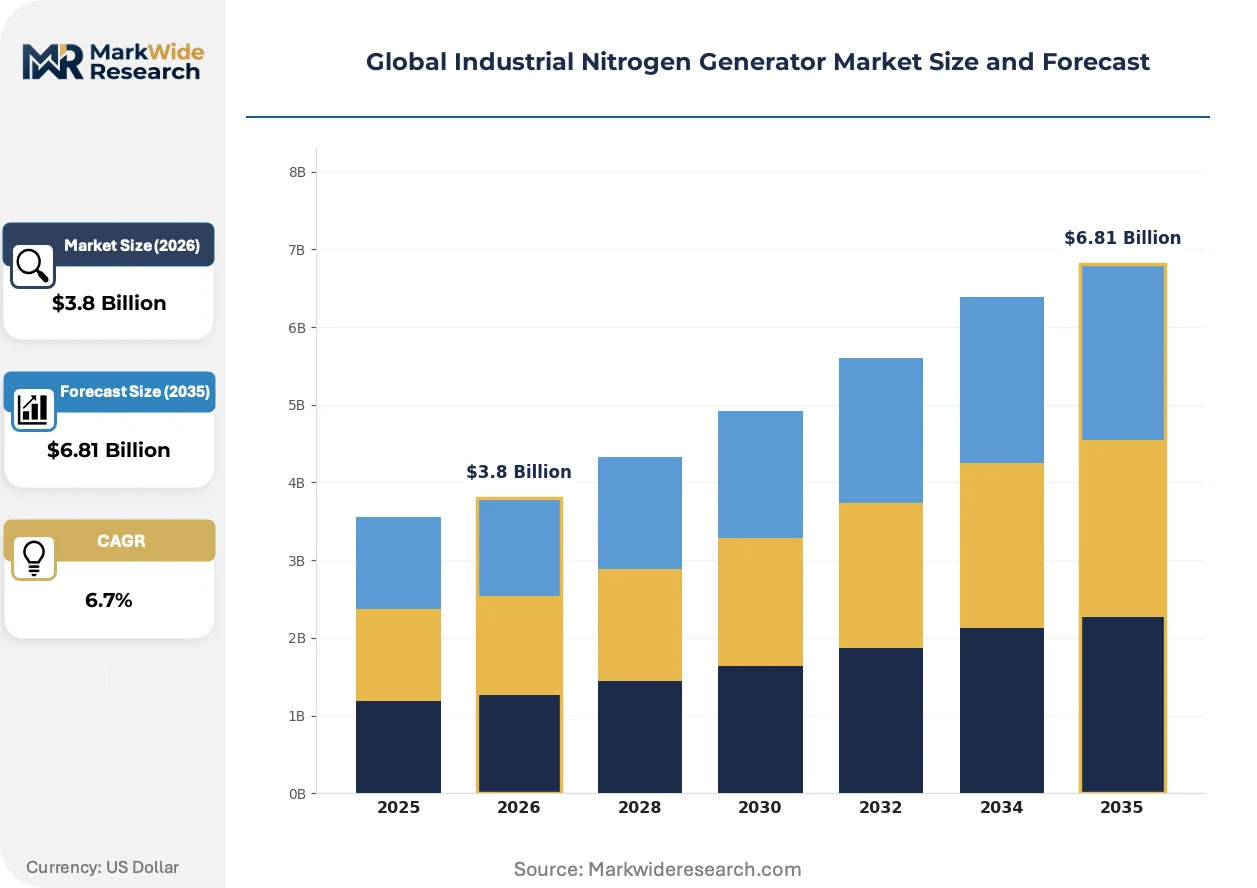
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane, Pressure Swing Adsorption, Cryogenic, Others Application: Food Packaging, Electronics Manufacturing, Metal Fabrication, Pharmaceuticals End User: Aerospace, Automotive, Chemical Processing, Oil & Gas Installation Type: Onsite, Portable, Stationary, Modular |
| Companies Covered | Parker Hannifin Corp, Air Products and Chemicals, Inc., Atlas Copco Group, Ingersoll Rand, Air Liquide, Linde PLC, Hitachi Industrial Equipment Systems Co., Ltd., Inmatec, Novair SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Nitrogen Generator Market Strategic Shifts
Membrane technology miniaturization and regulatory displacement of fluorinated gases are compressing system footprints while purity verification requirements reshape competitive positioning across end-use verticals.
Membrane separation technology is miniaturizing through hollow-fiber bundle density improvements and polymer chemistry advances. Food packaging lines in Southeast Asian seafood processing plants are adopting containerized membrane skids that occupy 40% less floor space than pressure swing adsorption equivalents. This footprint compression is miniaturizing deployment options for mid-scale bakeries and ready-meal facilities previously excluded from onsite generation economics.
REACH authorization procedures and the EU F-Gas Regulation are systematically restricting sulfur hexafluoride and perfluorocarbon use in magnesium die-casting and semiconductor etching operations. Metal foundries in Germany and electronics manufacturers in the Netherlands are retrofitting protective atmosphere systems to nitrogen-based alternatives. The regulatory pressure is most acute in automotive magnesium component supply chains, where Tier-1 suppliers face downstream OEM sustainability audits.
Buyer preference is consolidating around total-cost-of-ownership contracting rather than capital purchase models. European automotive plants and North American chemical processors are unbundling equipment procurement from long-term service agreements that guarantee purity, pressure, and availability metrics. This contracting evolution is most visible in German automotive clusters, where compressor-nitrogen bundling now dominates new facility specifications and aftermarket revenue capture determines vendor profitability.
Global Industrial Nitrogen Generator Market Segmentation
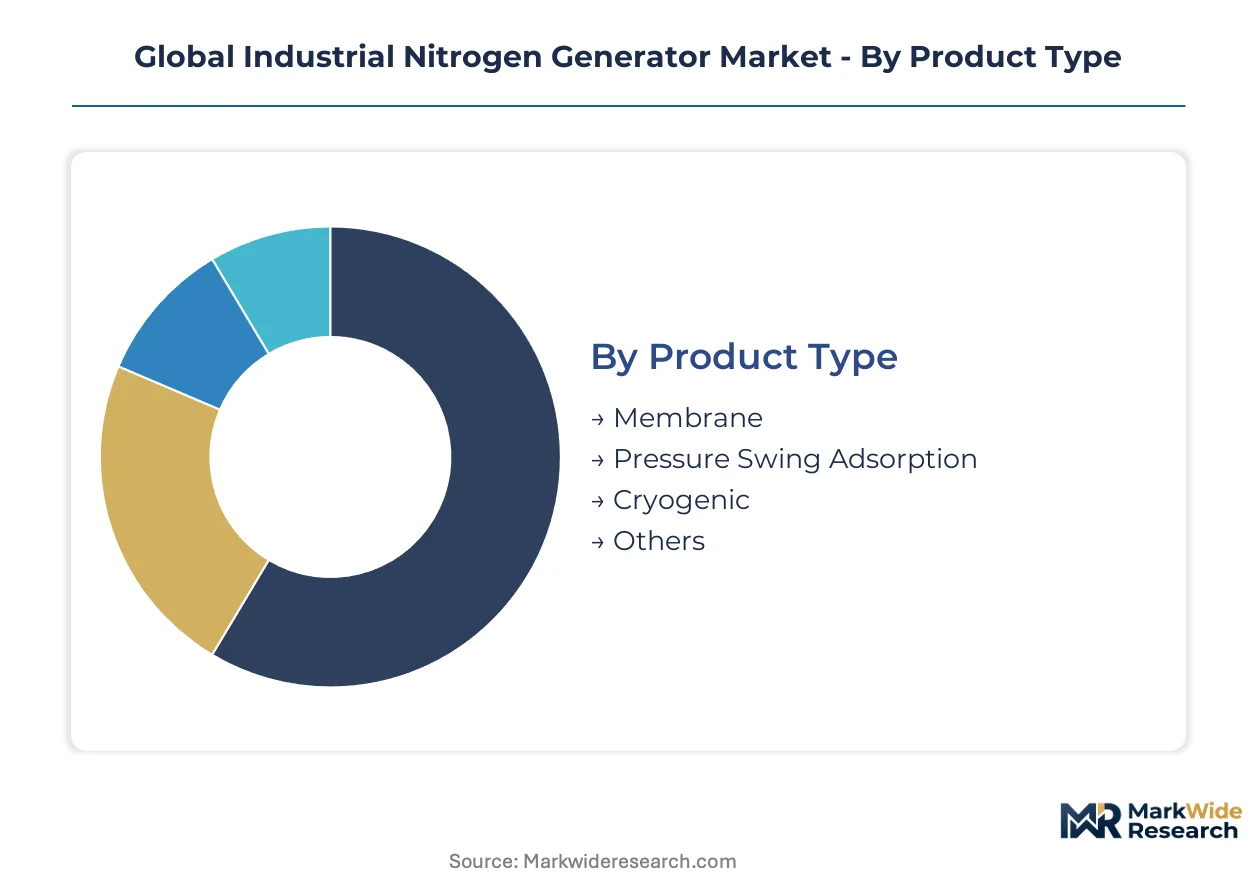
Industrial nitrogen generator procurement patterns diverge sharply across technology platforms and deployment contexts. Understanding these segment boundaries clarifies why membrane systems dominate Asian food packaging while pressure swing adsorption retains chemical processing loyalty.
Product Type:
Membrane systems concentrate in domestic food packaging markets. Cryogenic and pressure swing adsorption technologies anchor export-led pharmaceutical and semiconductor supply chains.
- Pressure Swing Adsorption:These systems force compressed air through zeolite molecular sieve beds that selectively adsorb oxygen, carbon dioxide, and water vapor under elevated pressure. Chemical processing clusters in Germany and the United States favor this technology for its reliability in continuous-flow operations where purity documentation carries regulatory weight under FDA Current Good Manufacturing Practice standards.
- Membrane:Hollow-fiber polymer bundles exploit differential gas permeation rates to separate nitrogen from oxygen without moving parts. Southeast Asian seafood processors and Chinese dairy packaging lines adopt these units for their lower capital outlay and reduced maintenance footprint where 95-99% purity suffices.
- Cryogenic:Distillation-based systems achieve 99.999%+ purity through fractional condensation at cryogenic temperatures. Semiconductor wafer fabrication facilities in Taiwan and South Korea require this grade for cleanroom inerting.
- Others:Emerging electrochemical and adsorption-enhanced separation technologies occupy niche R&D and pilot-scale deployments.
Pressure swing adsorption commands the established base. The steepest expansion runs through membrane technology.
Application:
Application selection tracks end-use purity thresholds and regulatory exposure. Food packaging tolerates moderate purity; pharmaceutical and electronics manufacturing demand documented ultra-high grades.
- Food Packaging:Modified atmosphere packaging displaces oxygen with nitrogen to extend shelf life in protein, snack, and ready-meal products. FDA and EFSA tightening of oxygen displacement protocols accelerates onsite adoption across Chinese and Indian processing hubs.
- Electronics Manufacturing:Wave soldering and reflow operations require inert atmospheres to prevent oxidation of solder joints. EU F-Gas Regulation restrictions on synthetic fluorinated gases redirect Dutch and German electronics manufacturers toward nitrogen-based alternatives.
- Metal Fabrication:Heat treatment and laser cutting operations use nitrogen to prevent oxidation and achieve clean cuts. Automotive magnesium component suppliers face downstream OEM sustainability audits driving atmosphere retrofits.
- Pharmaceuticals:Aseptic filling and API manufacturing demand 99.99%+ purity with full validation documentation under FDA, EMA, and NMPA requirements.
Food packaging anchors volume deployment. Electronics manufacturing presents the most demanding purity verification requirements.
End User:
End-user segmentation reflects capital intensity tolerance and integration complexity. Automotive and chemical processing favor bundled compressor-nitrogen contracts; aerospace prioritizes portability.
- Chemical Processing:Continuous-flow reactors and tank blanketing operations consume large nitrogen volumes with stringent availability guarantees. German and US Gulf Coast chemical clusters sustain pressure swing adsorption system demand.
- Automotive:Metal stamping, painting, and assembly operations use nitrogen for inerting and quality control. European automotive plants increasingly specify total-cost-of-ownership contracting with purity and uptime guarantees.
- Aerospace:Aircraft manufacturing and MRO operations require portable nitrogen sources for tire inflation, fuel tank inerting, and component testing. Military and commercial aviation specifications drive modular system adoption.
- Oil & Gas:Pipeline purging, tank blanketing, and enhanced oil recovery operations consume nitrogen in remote locations. Modular and portable deployments dominate offshore and shale field applications.
Chemical processing sustains the largest continuous-flow installations. Aerospace generates the most specialized portability requirements.
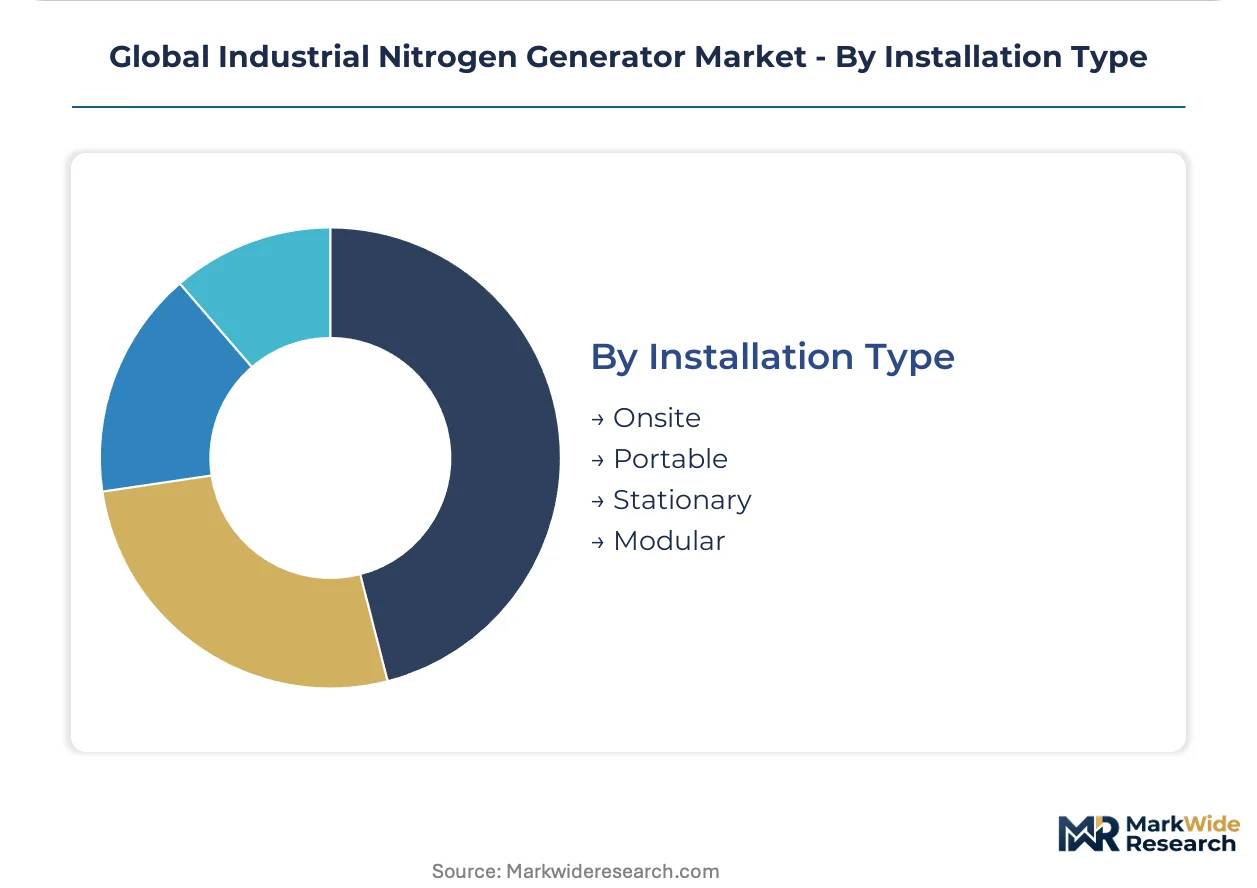
Installation Type:
Installation economics bifurcate around mobility needs and scale thresholds. Onsite generation displaces delivered liquid nitrogen where volume justifies capital investment; portable units serve intermittent or remote demand.
- Onsite:Permanently installed generators eliminate liquid nitrogen delivery logistics and reduce transport emissions. EU Carbon Border Adjustment Mechanism implementation incentivizes European manufacturers toward this model.
- Modular:Containerized skids enable rapid deployment and capacity scaling. Southeast Asian seafood processors and Indian dairy hubs adopt these for phased infrastructure expansion.
- Stationary:Fixed installations without mobility features dominate established chemical and pharmaceutical facilities with predictable demand profiles.
- Portable:Trailer-mounted or skid-mounted units serve construction, maintenance, and emergency response applications. Oil field services and shipyard operations favor this flexibility.
Onsite installations anchor the revenue base. Modular configurations are climbing the fastest as food processing infrastructure expands in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in membrane systems concentrates in German chemical clusters, while Chinese manufacturing hubs compete primarily on capital cost. This asymmetry shapes procurement patterns across food packaging and electronics verticals.
United States
Gulf Coast chemical processing and pharmaceutical manufacturing drive pressure swing adsorption demand. FDA Current Good Manufacturing Practice standards mandate nitrogen purity documentation for drug packaging lines. Houston and New Jersey pharmaceutical corridors sustain high-margin system deployments with multi-year service contracts.
Germany
Automotive magnesium component suppliers and metal heat treatment operations are retrofitting fluorinated gas systems. EU F-Gas Regulation phase-down redirects protective atmosphere investments toward nitrogen generators. Bavarian automotive clusters and Ruhr industrial zones anchor membrane and PSA system adoption with bundled compressor-nitrogen specifications.
China
Electronics manufacturing hubs and food packaging infrastructure expansion consume membrane and cryogenic units. GB standards and NMPA rules filter market access for imported pharmaceutical-grade equipment. Yangtze River Delta semiconductor fabrication and Pearl River Delta seafood processing drive divergent purity requirements across installation types.
India
Dairy processing and spice packaging infrastructure create first-mover opportunities for modular membrane deployments. FSSAI packaging regulations tighten oxygen displacement protocols for protein products. Maharashtra and Gujarat food processing hubs are adopting containerized skids for phased cold chain expansion.
South Korea
Wafer fabrication facilities require ultra-high purity nitrogen for cleanroom environments sustaining cryogenic system demand. MFDS pharmaceutical standards parallel FDA documentation requirements for aseptic filling operations. Gyeonggi-do semiconductor clusters and Busan industrial zones concentrate specialized generator procurement with availability guarantees.
Global Industrial Nitrogen Generator Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across purity segments. The market structure consolidates around engineered-systems specialists with validation capabilities and commoditized assemblers serving moderate-purity applications. Three archetypes dominate: filtration-heritage integrators, compressor-nitrogen bundlers, and industrial gas incumbents with cryogenic expertise. M&A activity targets regional membrane specialists, while capacity expansion concentrates in Asian manufacturing hubs serving food packaging volume.
Among filtration-heritage integrators, Parker Hannifin Corp exemplifies membrane technology positioning for food packaging lines. Atlas Copco Group and Ingersoll Rand occupy the compressor-nitrogen bundling archetype with aftermarket revenue capture across European automotive and North American chemical facilities. These three represent distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Parker Hannifin Corp |
| Air Products and Chemicals, Inc. |
| Atlas Copco Group |
| Ingersoll Rand |
| Air Liquide |
| Linde PLC |
| Hitachi Industrial Equipment Systems Co., Ltd. |
| Inmatec |
| Novair SAS |
| Others |
Value Chain & Pricing Dynamics
Zeolite molecular sieve substitution for imported adsorbent grades is compressing cost structures in pressure swing adsorption manufacturing while simultaneously shifting procurement geography toward domestic Chinese chemical producers and eroding the premium commanded by U.S. specialty material suppliers.
Pricing Analysis
Configured-to-order membrane systems for pharmaceutical-grade deployments command 40-60% premiums over standard food-packaging skids due to FDA validation documentation and materials-of-construction requirements. Contract-based long-term offtake agreements dominate European automotive and chemical processing procurement, bundling equipment with purity guarantees and aftermarket service. Price differentiation hinges on certification tier and geographic delivery cost, with German-manufactured PSA units carrying CE-marked premiums against Chinese membrane alternatives. Cost compression in standard-grade membrane systems is intensifying because of commoditized hollow-fiber bundle supply from Yangtze River Delta producers. Food packaging operators exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for cryogenic purity documentation.
Supply Chain Analysis
Strategic stockpiling of zeolite molecular sieves and hollow-fiber polymer membranes distinguishes European and North American system integrators from just-in-time dependent assemblers in emerging markets. Manufacturing concentrates in China, Germany, and the United States, with membrane bundle production anchored in Chinese chemical clusters and precision valve assemblies sourced from German pneumatic specialists. Raw material dependencies include specialized adsorbent materials, high-performance polymer resins, and precision compressor components. Single-source vulnerability runs through Chinese zeolite supply concentration for PSA systems. Distribution runs through direct OEM relationships for large chemical and automotive accounts, with regional distributors serving fragmented food packaging demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial nitrogen generation is approaching a platform-economics inflection where compressor-nitrogen bundling and IoT-enabled predictive maintenance create ecosystem lock-in comparable to industrial automation platforms.
For Market Incumbents: Secure aftermarket revenue capture through predictive maintenance platform integration with existing compressed air infrastructure, defending against modular membrane specialists eroding food packaging share. Anchor position in pharmaceutical validation documentation where FDA, EMA, and NMPA multi-jurisdiction requirements create insurmountable qualification barriers for new entrants. Prioritize backward integration into zeolite molecular sieve supply to mitigate Chinese supply concentration risk.
For New Entrants and Emerging Players: Differentiate on containerized modular deployment for Indian dairy and Southeast Asian seafood processing hubs where phased infrastructure expansion favors rapid-install membrane skids over permanent PSA installations. Target FSSAI-regulated Indian food packaging as the most penetrable geography given nascent cold chain development and limited incumbent bundling relationships. Pursue channel partnerships with regional compressor distributors to bypass direct OEM sales force requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward engineered-systems specialists with validated pharmaceutical-grade capabilities and installed base density in German automotive clusters, where total-cost-of-ownership contracting sustains recurring revenue visibility across decade-long horizons. Monitor EU Carbon Border Adjustment Mechanism implementation trajectory as the critical signal for onsite generation displacement of delivered liquid nitrogen in European manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adsorbent Materials | Captive zeolite supply secures PSA system margins against Chinese export restriction risk. |
| IoT-Enabled Predictive Maintenance Platform | Remote compressor monitoring locks in automotive plant aftermarket contracts with uptime guarantees. |
| Pharmaceutical Validation Documentation Investment | FDA Current Good Manufacturing Practice compliance creates insurmoentable qualification barriers for drug-manufacturer contracts. |
| Modular Containerized System Development | Footprint compression opens mid-scale bakery and ready-meal facilities previously excluded from onsite economics. |
| Compressor-Nitrogen Bundling Specification | European automotive cluster procurement now mandates integrated compressed air and nitrogen generation from single vendors. |
Study Parameters
The analysis maps membrane, pressure swing adsorption, cryogenic, and emerging electrochemical separation technologies, each validated through plant engineers at chemical processing facilities, procurement leads at automotive OEMs, aftermarket service heads at compressor distributors, and regulatory affairs specialists at pharmaceutical manufacturers. Primary interview findings triangulate against customs and trade data for nitrogen generator equipment, SEC filings from publicly traded industrial gas and equipment companies, chemical industry association reports, and pharmaceutical facility inspection databases from FDA and EMA. Bottom-up installation counts by end-use vertical reconcile with top-down industrial gas market sizing.
Consistency checks against external benchmarks validate projection outputs against disclosed capital expenditure patterns at semiconductor fabrication facilities, automotive plant expansion announcements, and food processing infrastructure investment programs across emerging markets. The analytical framework segments by technology platform, application purity threshold, end-user capital intensity tolerance, and installation mobility requirements across the projection horizon. CAGRs derive from regression analysis of historical equipment shipments against industrial production indices and regulatory implementation timelines. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and FDA purity documentation requirement evolution.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor capital expenditure cycles and stable electricity pricing in German industrial zones would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement continuity and zeolite supply chain stability. Revision becomes warranted when carbon border adjustment mechanism coverage expansion or Chinese adsorbent export restriction severity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Welding Gas Market
Industrial Gases
High Purity Gas Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Argon Gas Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Global Argon Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Krypton Gas Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
United States Industrial Gases Market