
 United States Industrial Gases Market | 2026-2036
United States Industrial Gases Market Size, Share, and Industry Trends Forecast 2026-2036
United States Industrial Gases Market Intelligence
Aftermarket service revenue is reconfiguring margin capture across the United States industrial gases landscape. Linde plc leverages its extensive on-site plant network to lock in multi-decade hydrogen supply contracts with Gulf Coast refiners. Air Products and Chemicals, Inc. anchors its position through backward integration into electrolyzer manufacturing for low-carbon hydrogen projects. Messer North America, Inc. specializes in regional bulk gas distribution, competing on logistics density rather than global scale.
Industrial gases comprise purified or synthesized atmospheric and process gases produced through cryogenic air separation, pressure swing adsorption, or steam methane reforming, with purity grades typically exceeding 99.5% for semiconductor and healthcare applications. These gases serve as feedstocks, inerting agents, oxidizers, or coolants across continuous-process industries. Oxygen commands the largest product volume given its irreplaceable role in steelmaking and medical therapy, while carbon dioxide growth tracks food and beverage carbonation and enhanced oil recovery demand. Electronics-grade nitrogen represents the fastest-expanding purity segment as domestic semiconductor fabrication capacity expands.
EPA emissions standards under the Clean Air Act shape hydrogen demand from refiners seeking sulfur reduction compliance, while OSHA workplace exposure limits govern cylinder handling protocols and drive automation investment. FDA Current Good Manufacturing Practice requirements enforce medical gas purity certifications that constrain supplier qualification. Stakeholders must monitor how IRA hydrogen production tax credits restructure the economics of on-site versus merchant supply models.
Market Dynamics
EPA sulfur reduction mandates are compressing hydrogen supply timelines for Gulf Coast refiners, forcing procurement toward captive on-site generation rather than merchant bulk deliveries. This regulatory pressure is restructuring contract tenures and capital deployment patterns across the value chain.
Growth Catalysts
- IRA Hydrogen Production Tax Credits:The Inflation Reduction Act's PTC tiering subsidizes low-carbon hydrogen production, accelerating electrolyzer deployment at Texas and Louisiana refineries.
- Semiconductor Fabrication Reshoring:CHIPS Act incentives are expanding domestic chip manufacturing, pulling electronics-grade nitrogen and argon demand from Arizona and Ohio fabs.
- Carbon Capture Utilization:Enhanced oil recovery operations in the Permian Basin are absorbing industrial CO2 volumes, creating offtake certainty for ammonia and ethanol plant capture projects.
Market Restraints
- Natural Gas Feedstock Volatility:Steam methane reforming economics swing with Henry Hub pricing, compressing hydrogen margin visibility for merchant suppliers.
- Cryogenic Distribution Infrastructure Concentration:Bulk liquid oxygen and nitrogen supply clusters around Gulf Coast pipeline corridors, creating geographic supply risk for inland manufacturers.
- Electrolyzer Capital Intensity:Green hydrogen projects face 3-5 year commissioning timelines and grid interconnection queues, delaying low-carbon supply scale-up.
Strategic Opportunities
- Appalachian Shale Gas Proximity:Pennsylvania and Ohio offer stranded gas monetization through small-scale hydrogen and syngas production for regional steel and chemical offtake.
- Medical Gas Home Delivery Networks:Post-acute respiratory therapy is shifting from hospital to home settings, opening last-mile distribution white space for portable oxygen concentrator services.
- Food Processing Cryogenic Freezing:CO2 and nitrogen demand from protein processing plants is accelerating as individual quick freezing replaces mechanical cold storage in poultry and seafood operations.
Industry Challenges
- Cryogenic Equipment Technician Scarcity:Pipeline maintenance and cold box repair require specialized welding and vacuum insulation expertise that outpaces vocational training output.
- Medical Gas cGMP Certification Timelines:FDA Current Good Manufacturing Practice validation for new ASU plants extends 18-24 months, constraining capacity response to hospital supply shortages.
- Legacy SCADA Integration Complexity:Remote monitoring upgrades for distributed air separation units must interface with decades-old control architectures, inflating automation project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Industrial Gases Market |
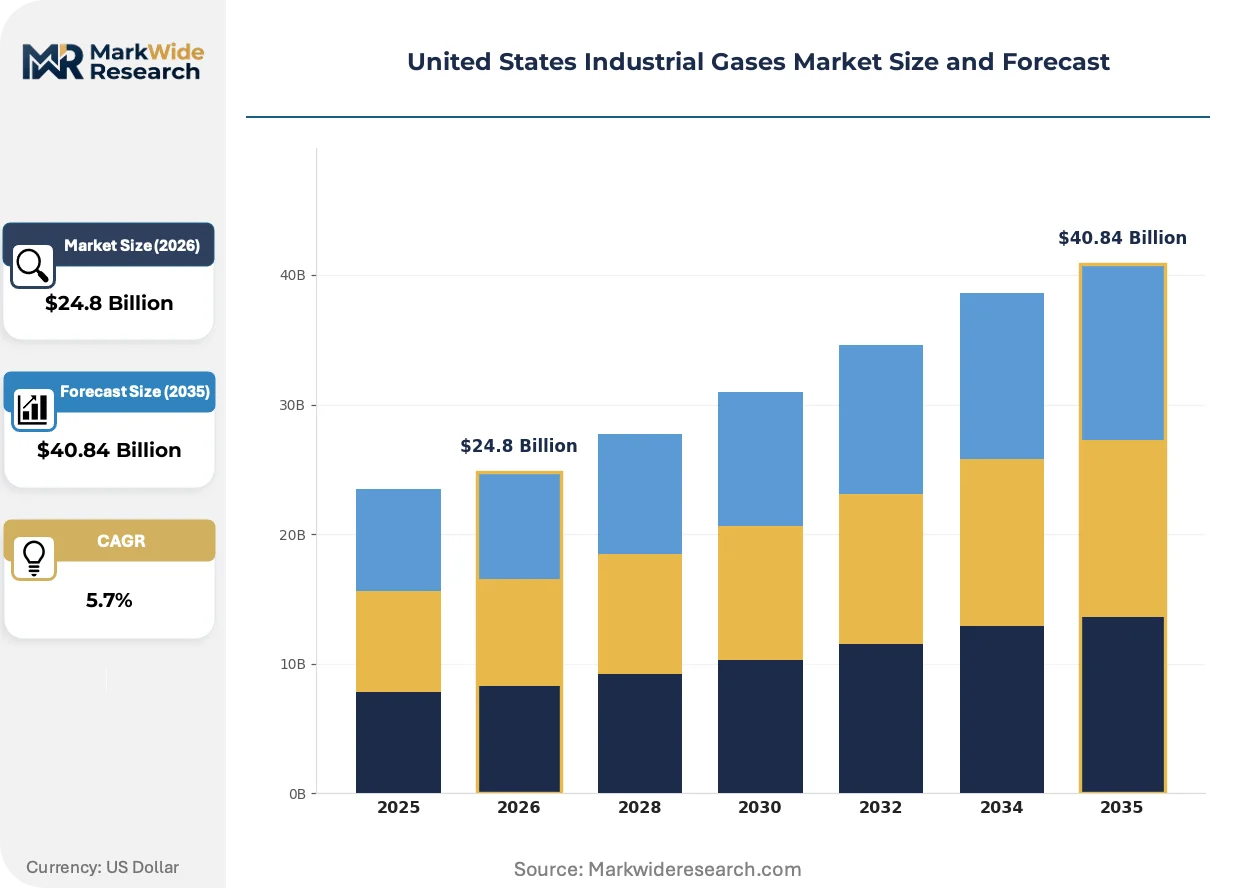
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen, Nitrogen, Argon, Carbon Dioxide Application: Chemical Processing, Metal Fabrication, Food & Beverage, Electronics End User: Manufacturing, Healthcare, Power Generation, Aerospace Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Linde plc, Air Products and Chemicals, Inc., Air Liquide, Messer North America, Inc., Matheson Tri-Gas, Inc., BASF SE, Universal Industrial Gases, Inc., Iwatani Corporation, AIR WATER INC., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Industrial Gases Market Strategic Shifts & Innovations
Digital twin deployment is compressing plant commissioning schedules and enabling predictive maintenance across cryogenic air separation networks. These virtualized systems are redefining how operators manage energy intensity and reliability.
Digital twin platforms are virtualizing the design and operational optimization of multi-train ASU facilities. Refiners and chemical producers are adopting these simulations during front-end engineering to compress startup timelines. The technology is virtualizing traditional commissioning workflows, reducing field rework and accelerating time-to-first-gas.
The EPA's Renewable Fuel Standard and state-level low-carbon fuel standards are mandating lifecycle emissions accounting for transportation fuels. This regulatory stack is forcing hydrogen suppliers to document carbon intensity scores through certified pathways. California's LCFS and the federal RFS together are reshaping Gulf Coast hydrogen procurement specifications toward certified low-carbon supply.
Refiners are consolidating hydrogen offtake through 15-20 year take-or-pay contracts with on-site plant operators, displacing spot merchant purchases. This contractual compression locks in volume certainty for producers while transferring price risk to buyers. The shift is most pronounced in Texas and Louisiana, where sulfur reduction compliance deadlines are tightening.
United States Industrial Gases Market Segmentation
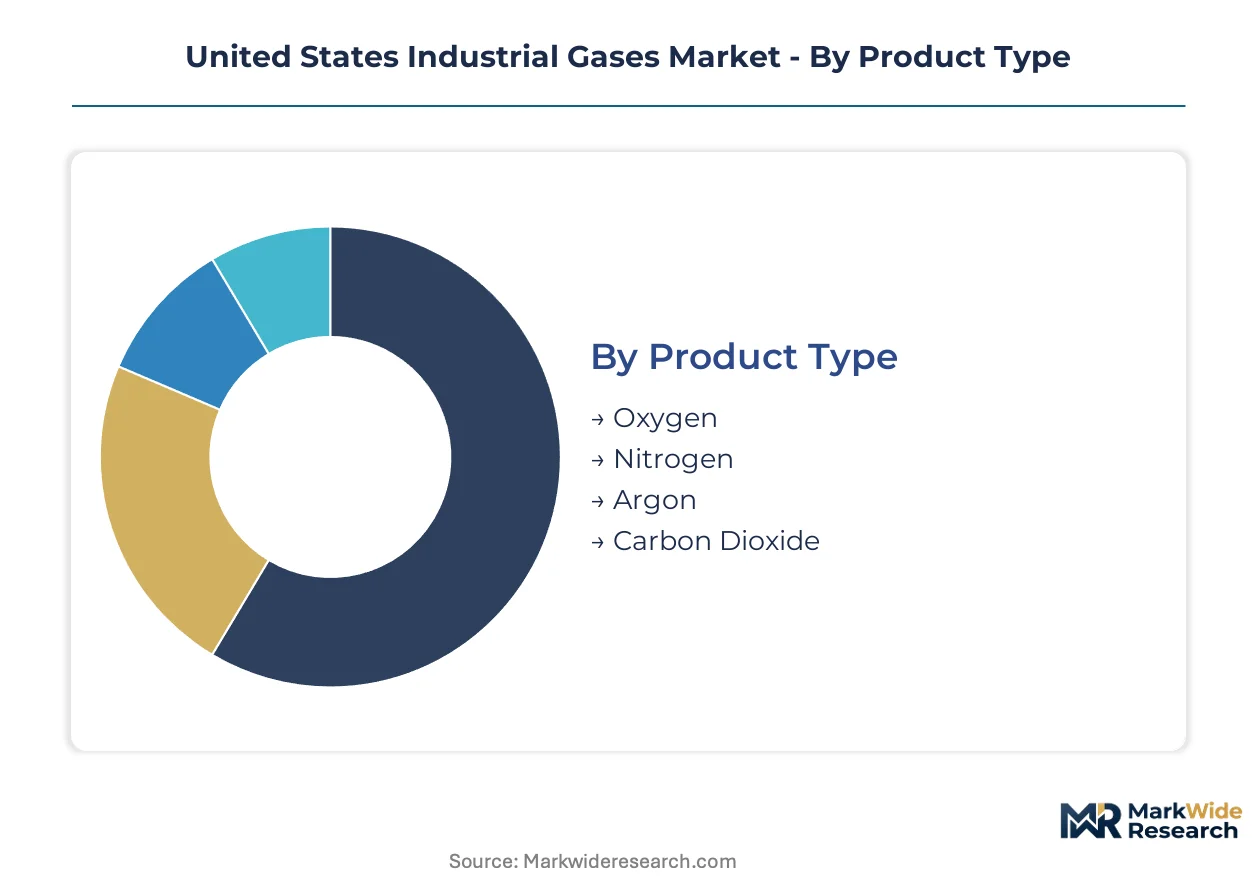
Industrial gases serve radically different performance requirements across steel mills, semiconductor fabs, and hospital wards. Segmentation reveals how supply chain configuration, purity specifications, and delivery modes diverge by end-use intensity. Understanding these splits exposes where margin concentrates and where volume growth is accelerating.
Product Type:
The use-case spectrum spans oxidizers for combustion control, inerting agents for semiconductor fabrication, and refrigerants for food preservation — each demanding distinct production and distribution infrastructure.
- Oxygen:Produced via cryogenic air separation or pressure swing adsorption with purity grades from 90% for steelmaking to 99.5%+ for medical therapy. Steel mills in Indiana and Ohio consume the largest volumes, with EPA emissions rules tightening sulfur reduction requirements that pull additional oxygen demand into refinery hydrotreaters.
- Nitrogen:Electronics-grade nitrogen at 99.9999% purity serves as inerting blanket and carrier gas in Arizona and Texas semiconductor fabs reshoring under CHIPS Act incentives. The segment's purity tiering creates the steepest price differentiation across the product matrix.
- Argon:Welding shield gas and semiconductor crystal growth applications dominate offtake, with specialty steel producers in Pennsylvania representing concentrated regional demand.
- Carbon Dioxide:Food-grade CO2 for beverage carbonation and dry ice production tracks population density, while industrial grades serve Permian Basin enhanced oil recovery operations.
Established volume favors oxygen; emerging adoption favors nitrogen.
Application:
Cost tier stratification separates continuous-process industrial demand from batch-mode specialty consumption, with electronics commanding premium pricing per unit volume.
- Chemical Processing:Hydrogen, oxygen, and nitrogen feedstocks for ammonia, methanol, and refinery hydrotreating operations. Gulf Coast petrochemical corridors in Texas and Louisiana concentrate demand around on-site generation contracts rather than merchant delivery.
- Metal Fabrication:Oxygen-fuel cutting and argon-shielded welding drive bulk consumption across automotive stamping plants and structural steel operations in the Midwest.
- Food & Beverage:Modified atmosphere packaging, cryogenic freezing, and carbonation require food-grade certifications that constrain supplier qualification to a narrower vendor base.
- Electronics:Ultra-high-purity nitrogen, argon, and helium for semiconductor lithography and display manufacturing commands the highest margin per cubic meter, with Arizona fabs expanding fastest.
Process intensity anchors chemical processing; margin density elevates electronics.
End User:
Customer type determines contract structure, with healthcare requiring FDA-validated supply chains and manufacturing favoring long-term take-or-pay arrangements.
- Manufacturing:Steel, automotive, and chemical plants consume industrial gases as production inputs, with procurement consolidating around 10-20 year on-site agreements that transfer price risk to buyers.
- Healthcare:FDA Current Good Manufacturing Practice requirements enforce medical oxygen and nitrous oxide purity certifications, with home respiratory therapy expanding last-mile distribution requirements.
- Power Generation:Hydrogen for generator cooling and carbon capture solvent regeneration represents emerging demand from utilities decarbonizing baseload capacity.
- Aerospace:Launch vehicle propellant loading and ground support equipment drives specialized helium and nitrogen requirements concentrated in Florida and California launch facilities.
Contract duration favors manufacturing; regulatory complexity favors healthcare.
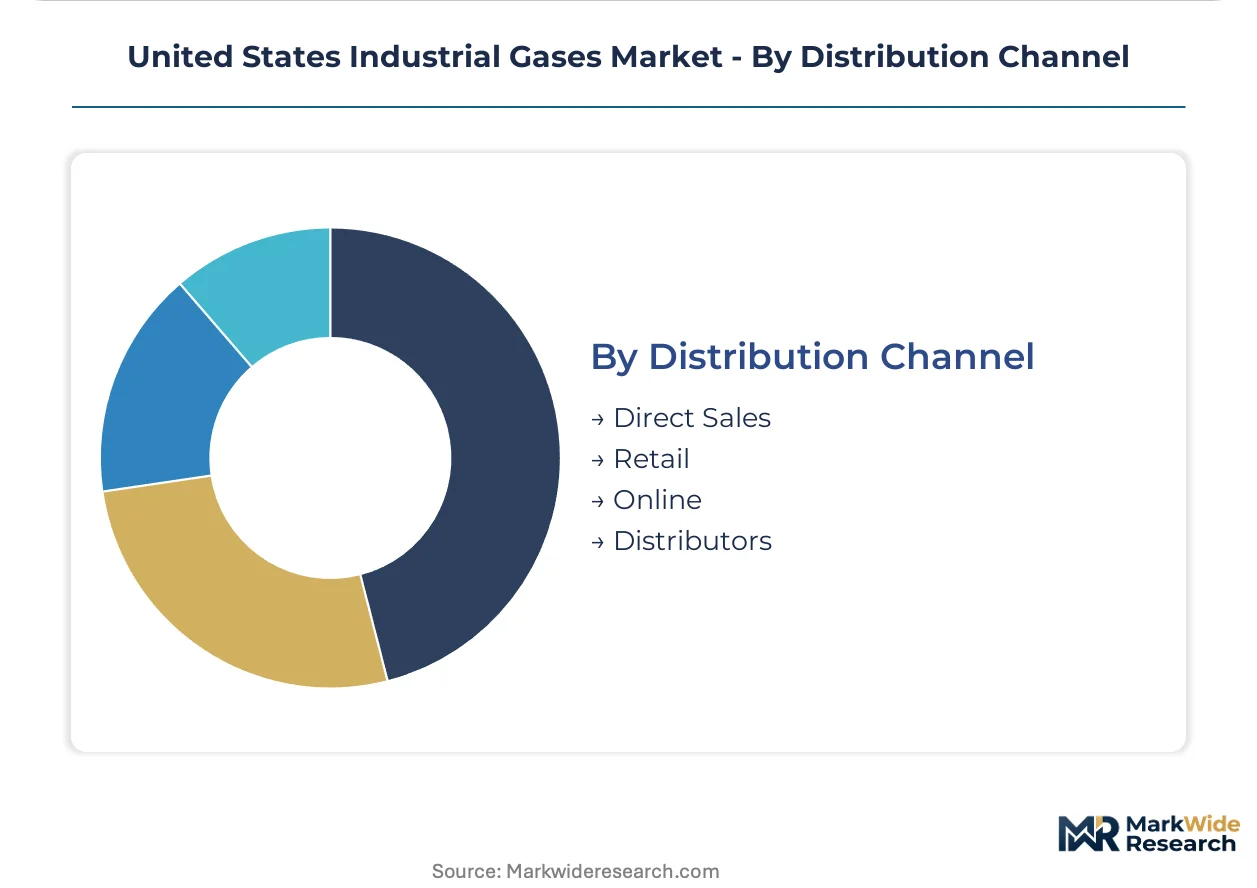
Distribution Channel:
Supply concentration in pipeline corridors versus dispersed cylinder delivery creates divergent margin structures and capital intensity requirements.
- Direct Sales:On-site air separation units and dedicated pipeline supply for large-volume chemical and steel customers eliminate distribution markup but require 15-20 year contract tenures to recover capital.
- Retail:Welding supply stores and gas cylinder exchange networks serve fragmented metal fabrication and construction demand, with logistics density determining competitive position.
- Online:E-procurement platforms for standard cylinder specifications are gaining traction among mid-size manufacturers seeking price transparency, though cryogenic liquids resist digital commoditization.
- Distributors:Regional bulk gas distributors aggregate demand from food processors, hospitals, and smaller manufacturers, competing on delivery reliability rather than production scale.
Capital lock-in favors direct sales; service flexibility favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast consumes hydrogen at intensities unmatched elsewhere, while the Midwest and Southwest diverge toward oxygen-heavy steel and nitrogen-heavy semiconductor applications respectively.
Gulf Coast
Texas and Louisiana refineries drive hydrogen demand through hydrotreating and sulfur reduction compliance. EPA emissions rules under the Clean Air Act compress procurement timelines toward captive on-site generation. The Houston Ship Channel and Port Arthur industrial corridor concentrates long-term supply contracts with dedicated air separation units.
Midwest
Indiana and Ohio steel mills anchor oxygen consumption for basic oxygen furnaces and electric arc operations. OSHA workplace exposure limits govern cylinder handling automation investments across metal fabrication clusters. The Gary-Chicago industrial arc represents the densest pipeline-connected bulk gas infrastructure outside the Gulf.
Southwest
Arizona and New Mexico fabs pull electronics-grade nitrogen and argon for semiconductor lithography under CHIPS Act reshoring incentives. FDA Current Good Manufacturing Practice requirements enforce purity certifications that constrain supplier qualification. The Phoenix-Tucson corridor hosts the fastest-expanding ultra-high-purity gas demand in domestic manufacturing.
Appalachia
Pennsylvania and Ohio shale gas proximity enables stranded gas monetization through small-scale hydrogen and syngas production. IRA hydrogen production tax credits restructure economics for regional steel and chemical offtake. The Ohio River Valley chemical corridor is emerging as a testbed for distributed generation models.
West Coast
California's LCFS mandates lifecycle emissions accounting for transportation fuels, reshaping hydrogen procurement specifications toward certified low-carbon supply. Food-grade CO2 demand from Central Valley agriculture and Permian Basin enhanced oil recovery offtake create dual market pull. The Los Angeles-Long Beach port complex drives specialized helium and nitrogen requirements for aerospace ground support.
United States Industrial Gases Market Key Industry Players
Capability concentration sits with integrated producers commanding cryogenic infrastructure; scale advantage sits with global operators leveraging multi-train air separation networks. The vendor base organizes around three archetypes: pipeline-anchored on-site specialists, electronics-grade purity leaders, and regional bulk distributors competing on logistics density. Dominant competitive moves include backward integration into electrolyzer manufacturing and 15-20 year take-or-pay contract structures that transfer price risk to buyers.
Among the integrated tier, Linde plc and Air Products and Chemicals, Inc. exemplify divergent strategic positioning—Linde through extensive Gulf Coast plant networks, Air Products through captive electrolyzer supply chains for low-carbon hydrogen projects. Messer North America, Inc. occupies a position within the regional distribution archetype, competing on delivery reliability rather than global production scale. These three represent the structural fault lines between scale-driven and service-flexible competitive models.
| Leading Market Players |
|---|
| Linde plc |
| Air Products and Chemicals, Inc. |
| Air Liquide |
| Messer North America, Inc. |
| Matheson Tri-Gas, Inc. |
| BASF SE |
| Universal Industrial Gases, Inc. |
| Iwatani Corporation |
| AIR WATER INC. |
| Others |
Cost & Logistics Intelligence
Houston Ship Channel freight corridors anchor cost dynamics across the United States industrial gases landscape, compressing delivered pricing for Gulf Coast refiners while inflating inland premiums. Pipeline-connected on-site supply concentrates buyer power among Texas and Louisiana hydrotreating operations, forcing merchant suppliers to absorb logistics markup or surrender volume to captive generation.
Pricing Analysis
Long-term take-or-pay contracts dominate hydrogen procurement from Gulf Coast refiners, displacing spot merchant purchases as EPA sulfur reduction deadlines tighten. Price differentiation stems from carbon intensity certification tiers under IRA production tax credits and volume scale commitments above 50,000 Nm3/hr. Pricing pressure intensifies in standard-grade oxygen as steel mill demand softens, while electronics-grade nitrogen commands premium resilience. Merchant buyers in inland manufacturing clusters exhibit highest price sensitivity; integrated chemical producers with on-site ASUs demonstrate lowest.
Supply Chain Analysis
Natural gas feedstock from Texas, Louisiana, and Pennsylvania shale formations anchors hydrogen and syngas production economics across domestic supply networks. Cryogenic air separation units depend on specialized aluminum heat exchangers, molecular sieve adsorbents, and grid-scale electricity contracts. Single-source vulnerability concentrates in Gulf Coast pipeline corridors where hurricane disruption risk elevates supply continuity premiums. Distribution runs through dedicated on-site plants for large-volume chemical and steel customers, with regional bulk distributors aggregating fragmented food processing and healthcare demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue from predictive maintenance contracts and remote monitoring subscriptions is expanding faster than hardware sales across cryogenic infrastructure, reframing competitive advantage around uptime guarantees rather than unit throughput.
For Market Incumbents:Pre-empt electrolyzer manufacturing capacity constraints by securing exclusive supply agreements with PEM stack producers before IRA hydrogen tax credits accelerate project queues. Consolidate position in Arizona and Ohio semiconductor corridors through dedicated ultra-high-purity nitrogen plants with CHIPS Act-aligned commissioning timelines.
For New Entrants and Emerging Players:Establish a beachhead in Appalachian small-scale hydrogen production by monetizing stranded shale gas for regional steel and chemical offtake. Target medical gas home delivery networks in post-acute respiratory therapy, where FDA certification barriers deter commodity competitors and last-mile logistics density determines winner-take-all dynamics.
For Investors and Strategic Acquirers:Regional bulk distributors with dense cylinder exchange networks and established hospital GPO relationships offer the most defensible acquisition profile in a consolidating vendor landscape. Monitor electrolyzer project commissioning timelines as the inflection signal for green hydrogen supply cost parity against steam methane reforming.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks in 15-20 year hydrogen offtake from Texas refineries facing EPA sulfur mandates. |
| Backward Integration | Captures electrolyzer manufacturing margin for IRA-subsidized low-carbon hydrogen projects. |
| Capacity Expansion | Adds electronics-grade nitrogen supply to Arizona fabs under CHIPS Act reshoring incentives. |
| Joint Venture | Combines stranded gas access with hydrogen offtake certainty in Appalachian shale corridors. |
| Green Manufacturing Transition | Documents carbon intensity scores for California LCFS-compliant transportation fuel supply. |
Research Approach
A spread of perspectives from refinery procurement directors, cryogenic plant operators, medical gas distribution managers, and FDA regulatory consultants converged on the working assumptions shaping demand forecasts. Primary fieldwork combined structured interviews with secondary validation against EIA energy consumption data, SEC 10-K filings from integrated gas producers, ACC industry statistics, and customs records for cryogenic equipment imports. Bottom-up capacity installation tracking triangulated against top-down end-use consumption estimates across the analysis window.
Demand-supply-balance framing structured the analytical approach, modeling volume trajectories across product type, application intensity, end-user contract structure, and distribution channel configuration. Segmentation dimensions included purity grade tier, regional production hub proximity, and on-site versus merchant delivery mode. CAGRs derived from installed capacity expansion schedules, regulatory compliance deadline clustering, and technology substitution curves for electrolysis versus steam methane reforming. Forecast inputs incorporated Henry Hub natural gas futures, IRA hydrogen tax credit tiering, and CHIPS Act fab construction timelines.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity rates, steel production utilization, or semiconductor capital expenditure cycles would shift the trajectory from modeled outputs. Forecasts reflect documented assumptions about regulatory enforcement timing and technology cost decline curves. Cross-checking against EIA Short-Term Energy Outlook and ACC Chemical Activity Barometer is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Welding Gas Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Argon Gas Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Industrial Gas Regulator Market