
 Oxygen Market | 2026-2036
Oxygen Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Market Intelligence
The transition from captive on-site generation to outsourced bulk supply models is rebalancing competitive dynamics. Linde PLC dominates the market for large-scale air separation units supplied to industrial complexes. In contrast, Air Liquide specializes in high-purity grades for electronics and healthcare applications. Air Products and Chemicals, Inc. leverages its extensive pipeline network to serve industrial clusters in the United States and China.
Oxygen is a chemical element essential for respiration and combustion, most commonly found as a diatomic gas (O2). Industrial production primarily relies on cryogenic air separation, which liquefies air and separates its components. Industrial oxygen for steel manufacturing and chemical synthesis constitutes the largest volume segment. Medical oxygen, driven by demand from hospitals and pharmaceutical manufacturers, is a higher-margin category with stringent purity requirements.
Regulatory oversight is critical, with the FDA in the United States and the EMA in Europe defining standards for medical-grade oxygen. Global frameworks like ISO 13485 also govern the design and manufacturing of related medical equipment. These rules mandate specific purity levels, cylinder handling protocols, and traceability. End users must now evaluate the trade-offs between capital-intensive on-site production and the supply security of long-term gas contracts.
Market Dynamics
The central dynamic in the oxygen market is the tension between large-scale, centralized cryogenic production and the rising adoption of decentralized, on-site generation. This structural shift is driven by end-user demand for greater supply autonomy and cost control.
Growth Catalysts
- Steel Sector Expansion:Renewed investment in steel manufacturing, particularly in India and Southeast Asia, directly increases consumption of industrial-grade oxygen for blast furnace and basic oxygen steelmaking processes.
- Healthcare Infrastructure Mandates:Stricter guidelines from the WHO on medical gas availability are compelling governments in developing nations to expand hospital capacity and invest in reliable oxygen supply systems.
- High-Purity Applications:The electronics industry's demand for ultra-high-purity oxygen as an oxidizing and cleaning agent in semiconductor fabrication creates a high-margin growth vector.
Market Restraints
- Energy Price Volatility:Cryogenic air separation is an energy-intensive process, making oxygen production costs highly sensitive to fluctuations in electricity prices, which can compress supplier margins.
- Distribution Logistics:The capital-intensive nature of transporting liquid oxygen via specialized cryogenic tankers and maintaining extensive pipeline networks creates significant logistical hurdles and geographic limitations.
- Regulatory Compliance Costs:Adhering to stringent purity and handling standards for medical-grade oxygen, as defined by regulators like the FDA and EMA, imposes substantial compliance costs.
Strategic Opportunities
- Decentralized Medical Supply:Developing smaller, modular on-site generation systems (PSA/VPSA) for clinics and hospitals in remote or underserved regions of Africa and Latin America presents a significant growth opportunity.
- Aquaculture and Water Treatment:The use of oxygen to improve water quality and stock density in aquaculture and for ozone-based water purification represents a nascent but expanding application segment.
- Green Hydrogen Production:Oxygen is a co-product of water electrolysis for green hydrogen production; integrating oxygen capture and sales can improve the economic viability of new hydrogen projects.
Industry Challenges
- Capital Expenditure Cycles:The construction of new large-scale air separation units (ASUs) requires massive upfront capital investment and long planning cycles, creating a barrier to rapid capacity expansion.
- Traceability and Quality Assurance:Implementing and maintaining robust traceability systems from production to point-of-use to comply with medical device regulations like ISO 13485 is a complex operational challenge.
- Supply Chain Resilience:Ensuring an uninterrupted supply of medical oxygen during public health emergencies or geopolitical disruptions requires redundant systems and resilient distribution networks, straining existing logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Market |
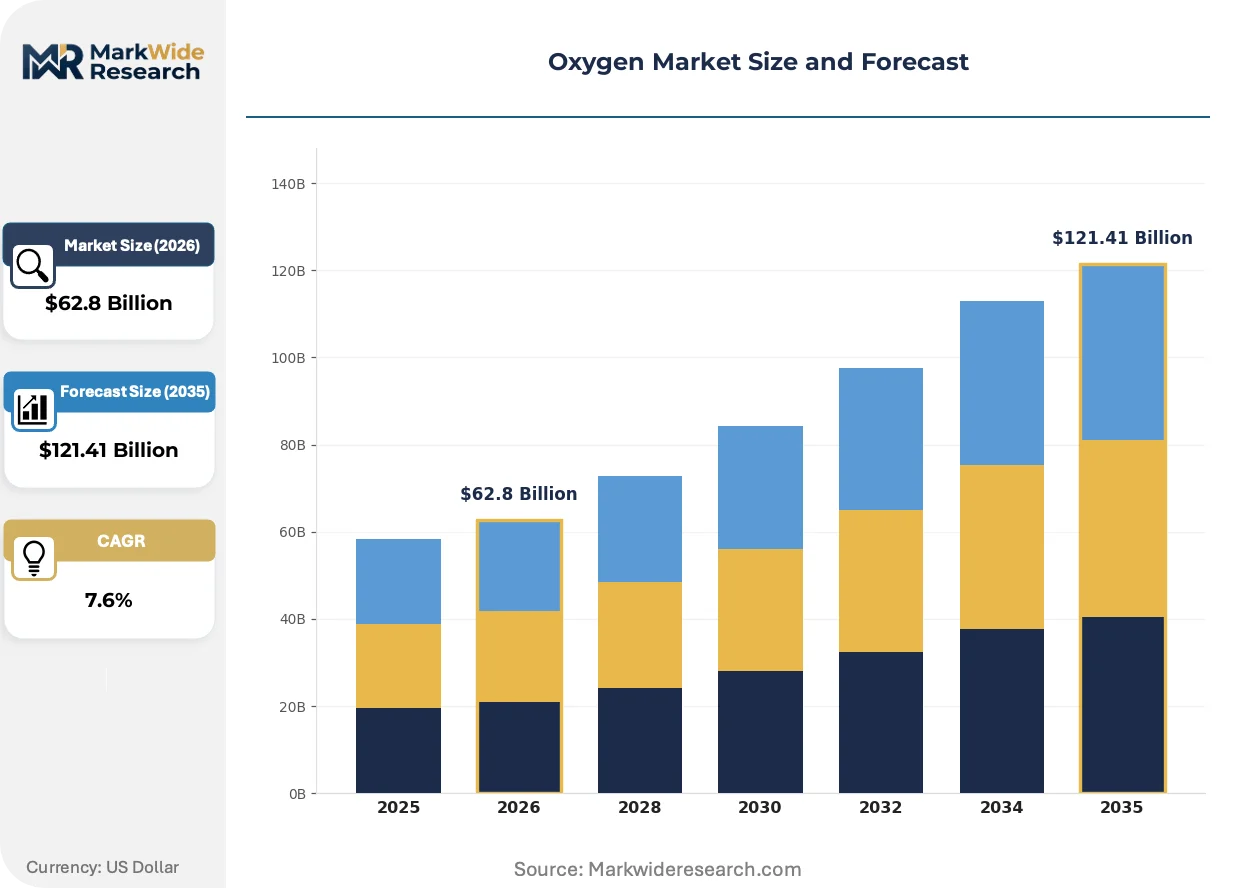
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $121.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Oxygen, Medical Oxygen, High-Purity Oxygen, Liquid Oxygen, Gaseous Oxygen Application: Steel Manufacturing, Water Treatment, Chemical Synthesis, Aerospace Propulsion, Welding End User: Hospitals, Pharmaceutical Manufacturers, Metal Fabricators, Aerospace Companies, Laboratories Distribution Channel: Direct Sales, Distributors, Online Platforms, Gas Suppliers, Equipment Manufacturers |
| Companies Covered | Nippon Sanso Holdings Corporation, Atlas Copco Group, Linde PLC, INOX Air Products Inc., Iwatani Corporation, Air Liquide, Messer SE & Co. KGaA, Keen Compressed Gas Co., Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Market Strategic Shifts & Innovations
Digitalization and modular production technologies are reshaping the oxygen supply chain. Remote monitoring of tank levels, purity, and consumption rates allows for more efficient logistics and predictive maintenance, while smaller-scale generation units offer new flexibility for end-users.
Advanced Pressure Swing Adsorption (PSA) technology, utilizing improved molecular sieves, provides an efficient method for on-site oxygen generation. Hospitals, aquaculture farms, and mid-sized industrial facilities are adopting these systems to reduce reliance on bulk liquid deliveries. This modular technology is expanding into markets previously dominated by centralized cryogenic production, offering users greater supply autonomy.
Stricter WHO recommendations for medical oxygen supply security are becoming national policy in many countries. This regulatory pressure is forcing healthcare providers in nations like Brazil and Indonesia to upgrade their infrastructure. The medical oxygen segment is most affected, leading to dual investments in both on-site PSA generators for primary supply and bulk liquid tanks for backup.
A transition from simple volume-based purchasing to service-oriented supply agreements is altering procurement patterns. This model disrupts traditional bulk delivery contracts by bundling gas supply with remote monitoring, inventory management, and compliance reporting services. This shift is most prominent in the healthcare sectors of North America and Europe, where hospitals seek to optimize operational efficiency and ensure regulatory adherence.
Oxygen Market Segmentation
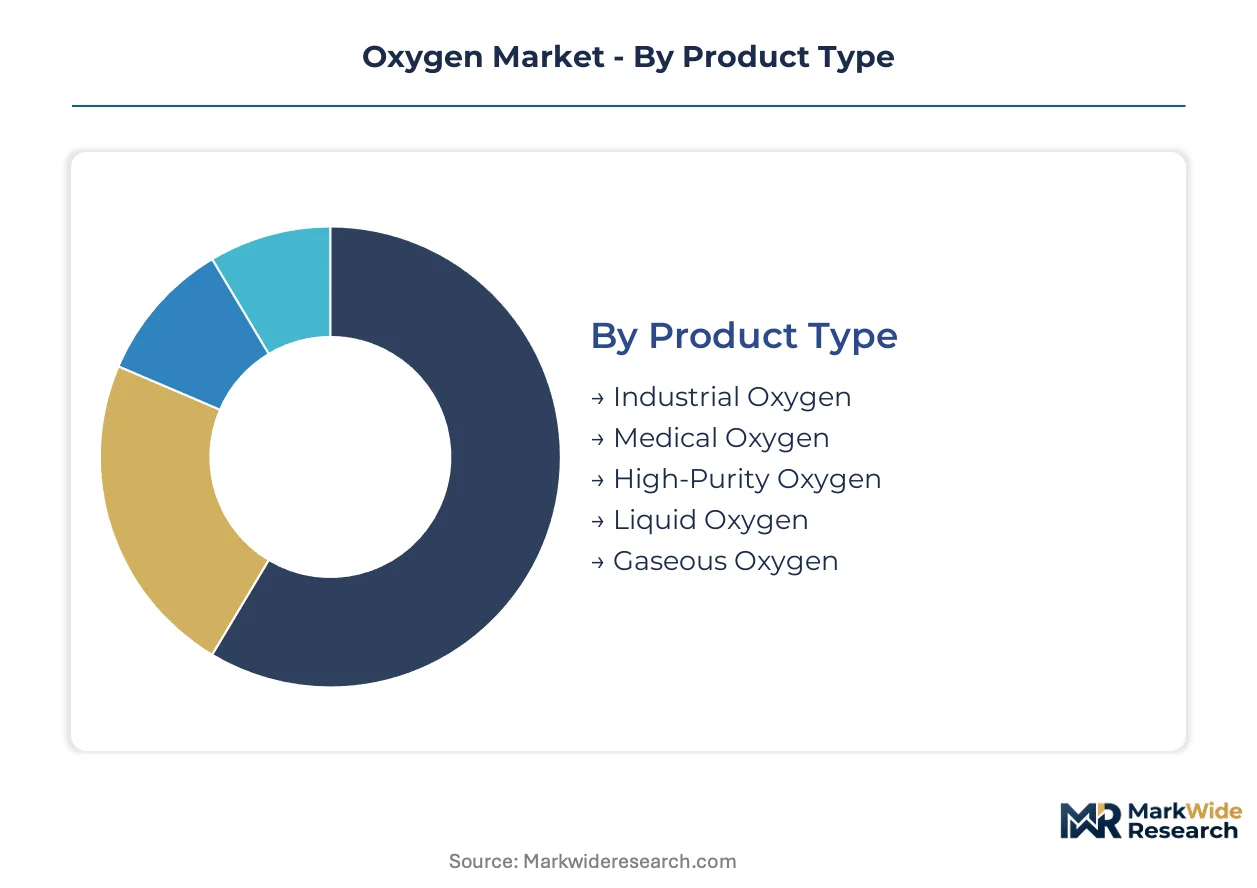
The oxygen market's segmentation highlights the diverse requirements of industrial, medical, and specialized applications. Understanding these distinct segments is crucial for suppliers to tailor product specifications, distribution strategies, and regulatory compliance efforts effectively. This granular view informs strategic investments in production capacity and logistical infrastructure.
Product Type:
The oxygen market segments by product type reflect a spectrum from highly standardized industrial gases to precisely customized high-purity medical and electronics grades.
- Industrial Oxygen:This product type is typically 99.5% pure, produced in large volumes for heavy industry. Demand concentrates in steel manufacturing facilities across India and China, where it is critical for optimizing blast furnace efficiency.
- Medical Oxygen:Meeting stringent purity standards (typically 99.0% or higher), medical oxygen is classified as a drug and requires regulatory approval. Hospitals and healthcare providers in Europe and North America drive demand, ensuring patient respiration and anesthesia support.
- High-Purity Oxygen:This grade achieves purity levels exceeding 99.999% and is essential for sensitive manufacturing processes. Semiconductor fabrication in Taiwan and South Korea utilizes this oxygen as an oxidizing agent and for chemical vapor deposition.
- Liquid Oxygen:Stored at cryogenic temperatures, liquid oxygen offers a compact and efficient method for bulk transport and storage. It serves large industrial users and medical facilities requiring significant, continuous supply.
- Gaseous Oxygen:Compressed into cylinders, gaseous oxygen is suitable for smaller-scale applications and portable medical devices. This form is common in welding, small clinics, and home medical oxygen therapy.
Most installed capacity flows through Industrial Oxygen. Expansion is steepest in High-Purity Oxygen.
Application:
Application-based segmentation highlights varying volume contributions and operational criticality across diverse industrial and healthcare processes.
- Steel Manufacturing:Oxygen enhances combustion in blast furnaces and converts iron to steel in basic oxygen furnaces. This application represents the largest volume consumption of industrial oxygen, particularly in the steel-producing regions of Asia.
- Chemical Synthesis:Oxygen acts as a crucial reactant in producing various chemicals, including ethylene oxide, vinyl acetate monomer, and titanium dioxide. Chemical plants in Germany and the United States rely on oxygen for oxidation processes to create these foundational compounds.
- Water Treatment:Oxygen is used in aeration processes to improve water quality and support biological treatment of wastewater. Aquaculture farms in Norway and Chile also employ oxygen to increase dissolved oxygen levels for fish health.
- Aerospace Propulsion:Liquid oxygen serves as an oxidizer in rocket engines, enabling the combustion of fuel for spacecraft and launch vehicles. Space agencies in the United States and Europe are major consumers for their launch programs.
- Welding:Oxygen supports high-temperature combustion in oxy-fuel welding and cutting processes, providing the necessary heat for metal fabrication. Small workshops and large industrial facilities utilize oxygen for precise metalworking tasks.
Demand for Steel Manufacturing drives the largest volumes, while Aerospace Propulsion exhibits strong growth potential.
End User:
End-user segmentation reveals distinct procurement patterns and regulatory compliance needs among different customer types.
- Hospitals:These institutions require medical-grade oxygen for patient respiration, anesthesia, and life support systems. Hospitals in developed nations like the United States and Japan face stringent FDA or PMDA regulations for oxygen supply and purity.
- Metal Fabricators:This segment comprises companies involved in welding, cutting, and shaping metals for various industries. Metal fabricators in Brazil and Mexico consume industrial oxygen for their manufacturing processes.
- Pharmaceutical Manufacturers:Oxygen is used in fermentation processes, sterile environments, and packaging of certain drugs. Companies in Ireland and Switzerland adhere to strict EMA guidelines for oxygen quality in drug production.
- Aerospace Companies:These firms utilize oxygen for rocket propulsion, specialized welding, and environmental control systems within aircraft. Major aerospace contractors in France and the United Kingdom are key consumers.
- Laboratories:Research and development facilities use oxygen for various analytical instruments, cell culture, and experimental setups. University research labs and private testing facilities globally rely on high-purity oxygen.
Hospitals represent a high-margin segment, whereas Metal Fabricators consume significant industrial volumes.
Distribution Channel:
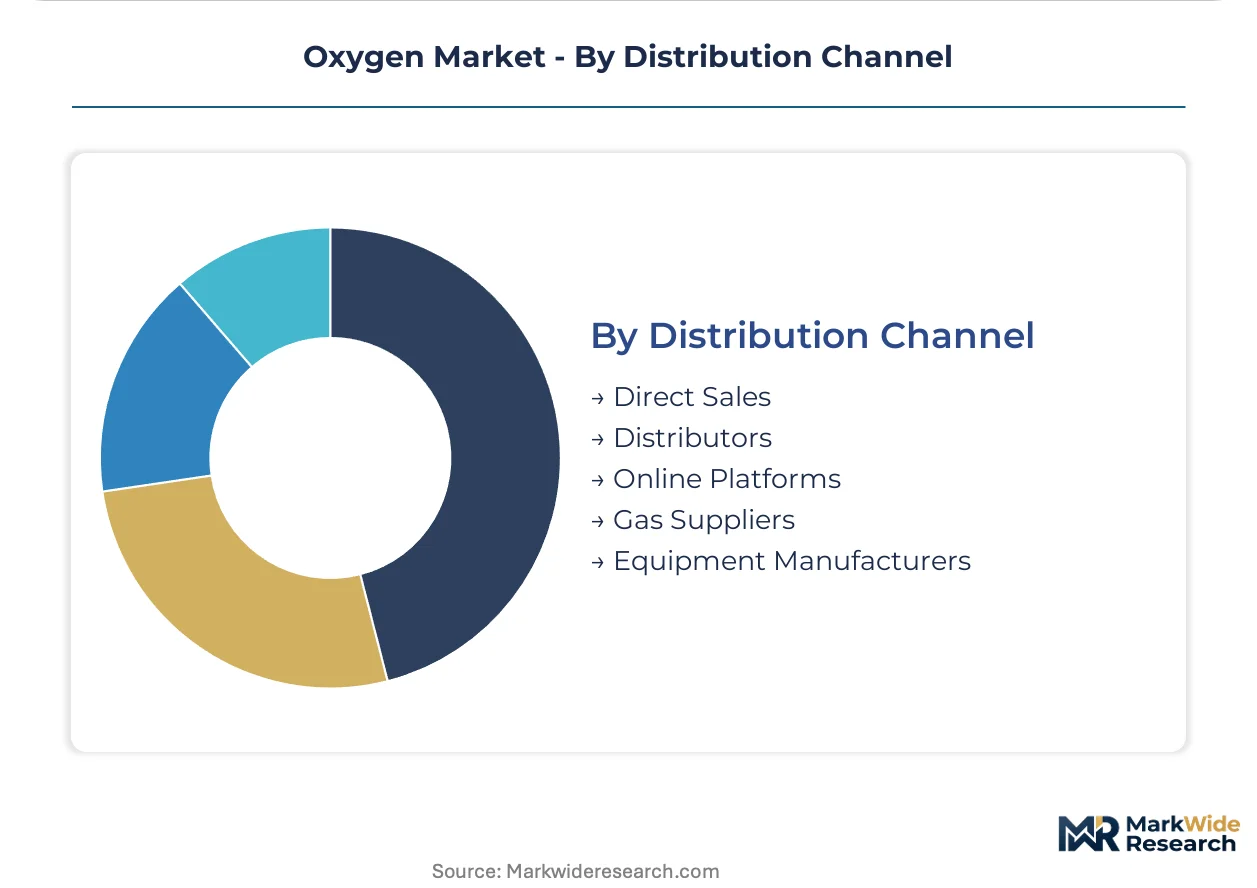
Distribution channel analysis underscores the logistical complexities and supply chain models employed to deliver oxygen to diverse end-users.
- Direct Sales:Large industrial consumers and major hospitals often procure oxygen directly from producers through long-term contracts. This channel is prevalent for bulk liquid oxygen deliveries to steel mills in Germany and chemical plants in China.
- Gas Suppliers:Companies specializing in industrial gases manage the entire supply chain, from production to delivery and equipment maintenance. Air Liquide and Linde PLC operate extensive networks serving diverse clients globally.
- Distributors:These intermediaries purchase oxygen in bulk and redistribute it to smaller end-users, often in cylinders or smaller tanks. Local distributors provide essential supply to small businesses and regional healthcare facilities.
- Equipment Manufacturers:Some manufacturers integrate oxygen generation systems (like PSA units) into their offerings, especially for on-site production. This channel supports hospitals and industrial sites seeking greater supply autonomy.
- Online Platforms:A nascent but growing channel for smaller, standardized oxygen products, particularly for home medical use or niche industrial applications. E-commerce sites in North America facilitate direct-to-consumer sales of portable oxygen concentrators.
The majority of bulk oxygen is supplied through Direct Sales, with Distributors serving a wide array of smaller clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance costs and varying environmental standards influence oxygen production and distribution, creating a dynamic where production migrates to optimize cost-of-compliance gaps. This structural shift impacts global supply chain configurations, especially for industrial-grade oxygen. Demand for medical oxygen remains largely localized due to stringent purity and distribution requirements.
India
India's steel sector expansion drives significant demand for industrial oxygen, particularly for blast furnace operations. The country's PLI scheme for medical devices encourages domestic manufacturing and reliable oxygen supply systems for hospitals. Major industrial clusters in Maharashtra and Gujarat are seeing increased investment in large-scale air separation units.
United States
The United States experiences strong demand for high-purity oxygen from its advanced electronics manufacturing sector. FDA regulations mandate strict purity and handling standards for medical oxygen, affecting hospital supply chains. Silicon Valley and other tech hubs in California continue to require ultra-high-purity gases for semiconductor fabrication.
Germany
Germany's chemical synthesis industry relies heavily on industrial oxygen as a crucial reactant for various chemical processes. EMA guidelines for pharmaceutical-grade oxygen ensure high quality for drug production across Europe. Chemical parks in North Rhine-Westphalia and Bavaria are primary consumers of bulk oxygen supplies.
China
China's robust steel manufacturing industry consumes the largest volumes of industrial oxygen, vital for its extensive blast furnace and basic oxygen steelmaking processes. The country's dual carbon goals promote efficiency improvements in energy-intensive industries, including oxygen production. Industrial zones in Hebei and Jiangsu provinces anchor significant oxygen consumption.
Brazil
Brazil's metal fabrication sector utilizes industrial oxygen for welding and cutting applications across various industries. ANVISA, the national health surveillance agency, defines standards for medical oxygen, driving infrastructure upgrades in healthcare. Manufacturing hubs in São Paulo and Minas Gerais require consistent oxygen supplies for their operations.
Oxygen Market Key Industry Players
Established producers occupy the standard tier, leveraging extensive infrastructure and long-term contracts; emerging entrants pursue decentralized generation and specialized niche applications. The market structure exhibits consolidation among major industrial gas suppliers with global reach. Companies primarily compete through strategic partnerships and capacity expansion to secure market share.
Global industrial gas giants like Linde PLC and Air Liquide exemplify this scale-driven approach, utilizing vast production capabilities and pipeline networks to serve large industrial complexes and healthcare systems worldwide. Air Products and Chemicals, Inc. occupies a position among these leading players, known for its extensive infrastructure, particularly in the United States and China. These firms anchor the market by providing comprehensive gas supply and related services.
| Leading Market Players |
|---|
| Nippon Sanso Holdings Corporation |
| Atlas Copco Group |
| Linde PLC |
| INOX Air Products Inc. |
| Iwatani Corporation |
| Air Liquide |
| Messer SE & Co. KGaA |
| Keen Compressed Gas Co. |
| Air Products and Chemicals, Inc. |
| Others |
Cost & Logistics Intelligence
Specialized cryogenic engineering expertise in developed regions like the United States influences labor-cost differentials, which in turn impact pricing-tier spreads for high-purity and medical oxygen. This skilled workforce is critical for maintaining complex production and distribution infrastructure.
Pricing Analysis
Distributor margins for oxygen products vary significantly based on volume and purity requirements. Long-term contract-based offtake agreements dominate bulk industrial and medical oxygen pricing, while smaller volumes often follow per-unit transactional models. Price differentiation stems from specific quality grades and volume scale; regulatory compliance burdens also influence costs. Pricing softness reflects energy price volatility and the rising adoption of on-site generation, making metal fabricators highly price-sensitive, while hospitals prioritize supply security.
Supply Chain Analysis
Domestic manufacturing incentives, such as India's PLI scheme for medical devices, are reshaping sourcing strategies for oxygen generation equipment. The supply of bulk industrial oxygen concentrates in manufacturing hubs like China, the United States, and Germany. Production relies on consistent electricity supply for cryogenic separation and specialized molecular sieves for PSA units. Logistics chokepoints, particularly the limited availability of cryogenic tankers, pose a significant supply chain risk, while distribution runs through direct sales and extensive gas supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxygen market functions as a stable compounder, driven by the indispensable nature of oxygen across industrial output and public health imperatives. Continuous demand from steel manufacturing and healthcare infrastructure expansion ensures sustained growth.
For Market Incumbents: Lock in long-term contracts with major industrial users and healthcare systems to secure demand against decentralized on-site generation. Expand pipeline networks into emerging industrial clusters in India and Southeast Asia to reinforce distribution control. Invest in advanced cryogenic separation technologies to improve energy efficiency and mitigate energy price volatility. Strengthen compliance protocols for medical-grade oxygen to maintain competitive advantage against smaller players.
For New Entrants and Emerging Players: Capture white space in decentralized medical oxygen supply for remote clinics and hospitals in Africa and Latin America. Target aquaculture farms and water treatment facilities with modular PSA/VPSA systems, offering greater supply autonomy. Penetrate underserved regions by providing oxygen generation as a service, bundling equipment, maintenance, and remote monitoring. Focus on cost-effective, energy-efficient solutions to challenge established bulk delivery models.
For Investors and Strategic Acquirers: Industrial gas giants are the most active acquirers in this space, seeking to consolidate market share and technology. The market offers long-term viability over the next 5-10 years, underpinned by essential industrial processes and critical healthcare needs. Target specialized on-site generation technology providers and regional distributors with robust local networks. Increased M&A activity in modular PSA/VPSA technology firms will signal market inflection towards decentralized solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses rising industrial oxygen demand from steel sectors in India and China. |
| Long-term Supply Agreement | Secures revenue streams with major chemical synthesis plants in Germany and the US. |
| Green Manufacturing Transition | Improves energy efficiency of cryogenic air separation, reducing operational costs. |
| Joint Venture | Facilitates market entry and localized distribution in emerging healthcare markets like Brazil. |
| Backward Integration | Ensures consistent supply of specialized molecular sieves for PSA unit production. |
Research Approach
Bottom-up end-use modeling for steel manufacturing and healthcare, reconciled against top-down industrial gas supplier tracking, forms the analytical core of this study. Primary interviews with plant managers, hospital procurement officers, R&D directors, and logistics managers provided qualitative insights. Secondary validation utilized industrial gas association reports, FDA/EMA guidelines, company financial filings, and trade statistics. This approach ensured comprehensive data triangulation.
Historical trendline analysis, coupled with macroeconomic indicators, informed foundational market projections across the analysis window. Segmentation dimensions modeled included product type, application, end-user, distribution channel, and regional economic growth. Compound annual growth rates derived from regression analysis and expert consensus. Steel production forecasts and healthcare infrastructure investment plans served as critical industry inputs.
Energy price shocks, geopolitical disruptions, and new regulatory mandates are the dominant revision risks for market forecasts. These projections reflect assumptions regarding industrial output stability and healthcare spending trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Dielectric Gases Market
Industrial Gases
Gas Processing Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
High Purity Gas Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Argon Gas Market
Industrial Gases
Helium Market