
 Food-Grade Gases Market | 2026-2036
Food-Grade Gases Market Size, Share, and Industry Trends Forecast 2026-2036
Food-Grade Gases Market Intelligence
Cryogenic technician shortages across North America and Western Europe are redrawing competitive boundaries for on-site gas production and distribution networks. Linde plc leverages its dense regional fill-plant network to sustain same-day delivery commitments for carbonation-grade carbon dioxide. Air Liquide anchors its position through long-term take-or-pay contracts with multinational beverage producers. Messer SE & Co. KGaA differentiates via specialized nitrogen generators designed for small-to-mid-size meat processing facilities.
Food-grade gases comprise purified atmospheric and process-derived gases meeting compositional thresholds for direct or indirect food contact, typically specified at 99.9% minimum purity with controlled moisture, hydrocarbon, and particulate limits, and serve primarily to displace oxygen, maintain pressure, or control temperature throughout food handling and storage. Carbon dioxide dominates value contribution in the beverage carbonation application where high-pressure liquid delivery systems generate recurring revenue streams. Nitrogen leads growth velocity within the packaging application as modified-atmosphere formats displace vacuum-sealed alternatives in premium meat and cheese segments.
The FDA enforces Current Good Manufacturing Practice regulations for food-contact substances that constrain residual impurity levels in supply cylinders, while the EPA's Clean Air Act amendments phase down certain fluorinated refrigerants and indirectly elevate demand for cryogenic nitrogen freezing systems. The European Food Safety Authority maintains additive-specific purity schedules under Regulation 231/2012 that govern carbon dioxide and nitrogen food additive classifications. Stakeholders must monitor evolving national implementations of the EU F-Gas Regulation and assess whether cryogenic freezing investments accelerate relative to mechanical refrigeration retrofits.
Market Dynamics
Modified-atmosphere packaging adoption across European meat and cheese processing is compressing delivery windows and forcing gas suppliers to co-locate production assets near customer clusters.
Growth Catalysts
- FSMA cold-chain mandates:The FDA's updated Food Safety Modernization Act rules tighten traceability requirements for temperature-sensitive gas deliveries, expanding contracted service relationships between dairies and specialty gas distributors.
- Nitrogen freezing conversion:Mechanical refrigeration retrofits face accelerating phase-down pressures under EPA Clean Air Act amendments, redirecting capital toward cryogenic nitrogen tunnel freezers in poultry processing plants.
- Industrial bakery consolidation:German meat processors and baked goods manufacturers are merging procurement functions, creating volume pools that justify dedicated on-site nitrogen generation investments.
Market Restraints
- Carbon dioxide feedstock volatility:Ammonia plant curtailments and ethanol production swings constrain beverage-grade carbon dioxide availability, exposing carbonation-dependent bottlers to spot-market price spikes.
- Cryogenic technician scarcity:North American and Western European labor markets lack certified technicians for bulk cryogenic system maintenance, extending equipment commissioning timelines and inflating service premiums.
- EFSA additive reclassification risk:European Food Safety Authority reviews of carbon dioxide and nitrogen food additive status under Regulation 231/2012 create compliance uncertainty for cross-border suppliers.
Strategic Opportunities
- Small-scale nitrogen generation:Containerized pressure-swing adsorption units enable mid-size meat processors to bypass bulk liquid delivery infrastructure, capturing margin previously lost to distributor markups.
- EU F-Gas Regulation acceleration:National implementation timelines for fluorinated refrigerant phase-downs are compressing payback periods for cryogenic freezing investments in Spain and Italy.
- Ready-meal packaging integration:Gas suppliers partnering with tray-sealing equipment manufacturers can embed nitrogen flushing systems into turnkey packaging lines, locking in long-term gas offtake contracts.
Industry Challenges
- Cylinder fleet certification lag:FDA Current Good Manufacturing Practice updates require enhanced residual impurity testing protocols, forcing distributors to idle cylinders during recertification and compressing available fleet capacity.
- Legacy mechanical refrigeration lock-in:Existing capital depreciation schedules and maintenance contracts slow cryogenic freezing adoption despite superior temperature control performance, particularly in family-owned processing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food-Grade Gases Market |
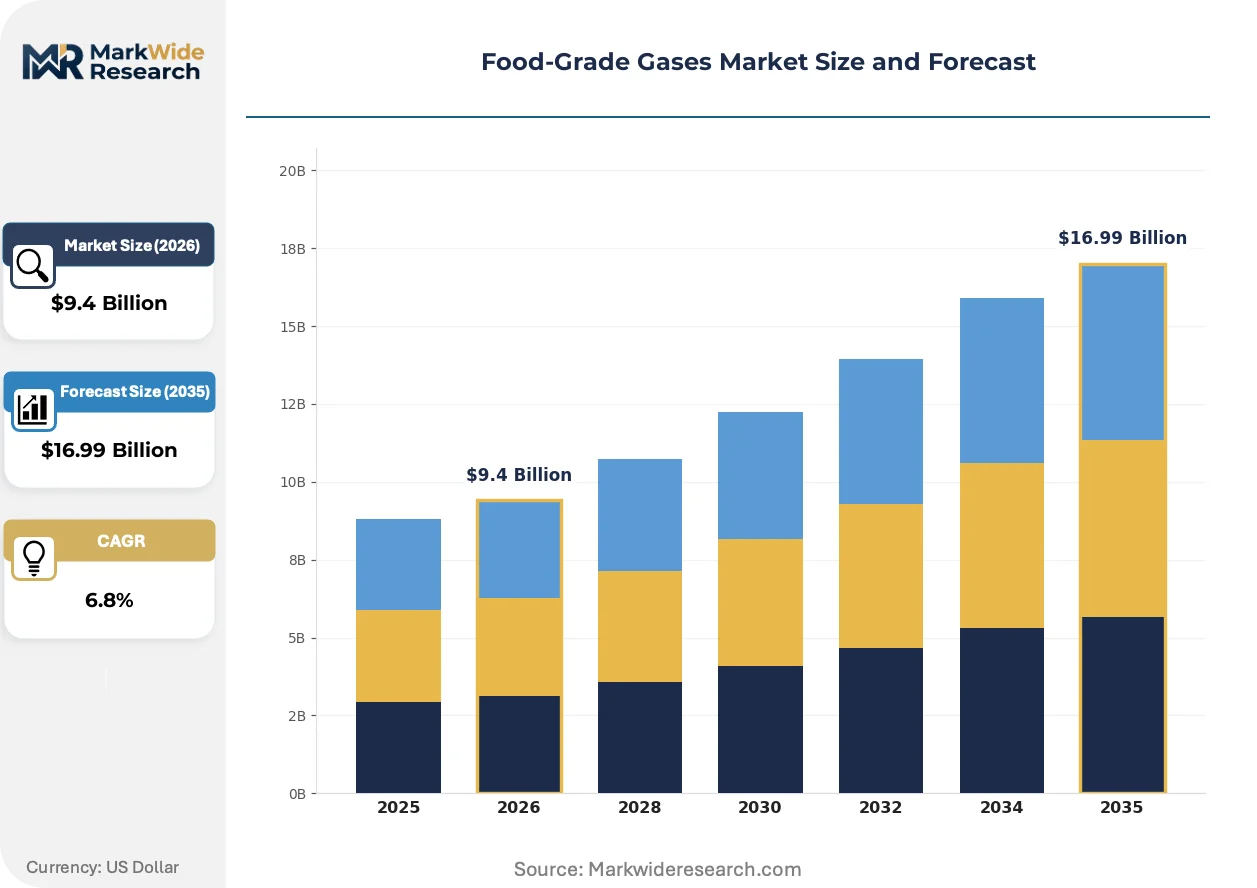
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
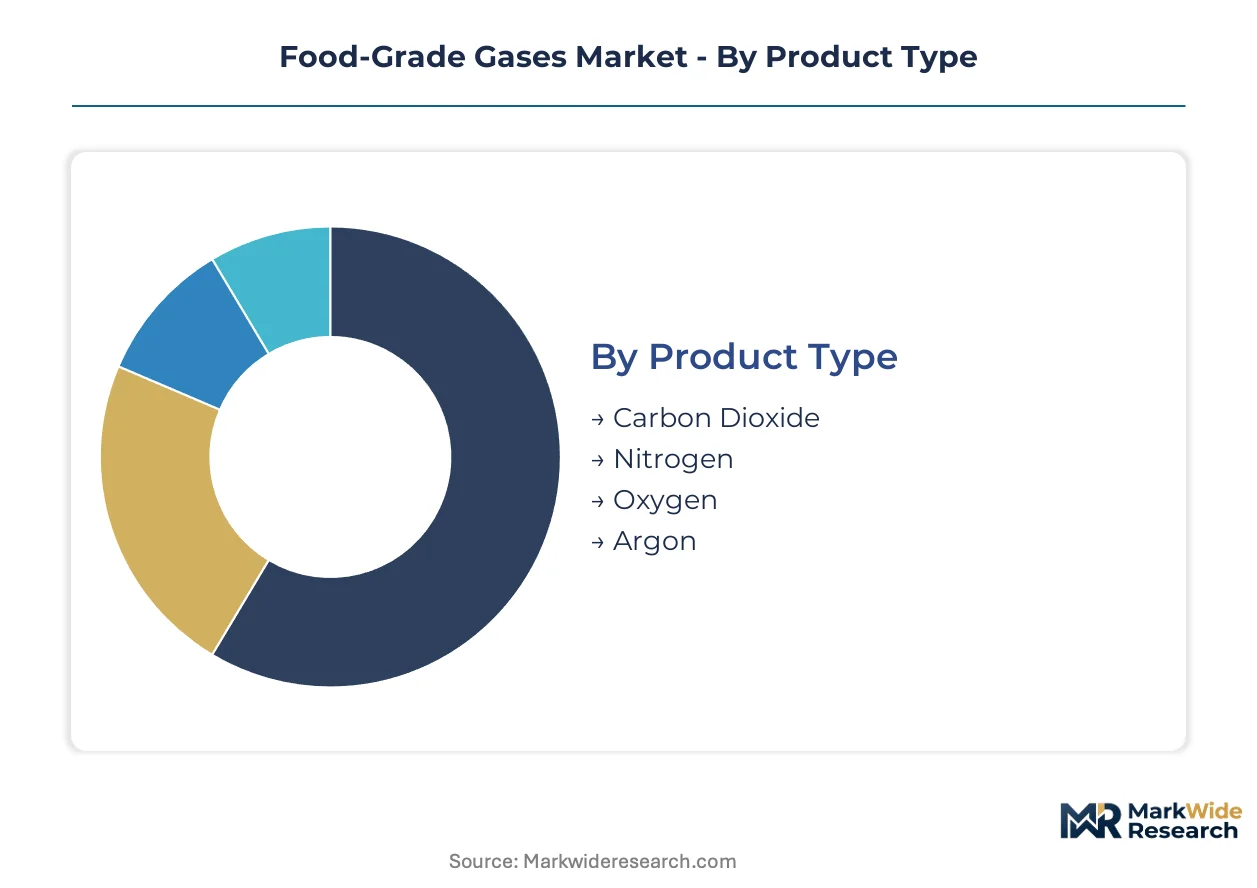
| Segmentation | Product Type: Carbon Dioxide, Nitrogen, Oxygen, Argon Application: Packaging, Preserving, Carbonation, Transportation End User: Food Manufacturers, Beverage Producers, Grocery Stores, Restaurants Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Messer SE & Co. KGaA, Taiyo Nippon Sanso Corporation, SOL Group, Gulf Cryo, Matheson Tri-Gas, Inc., Gruppo SIAD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food-Grade Gases Market Strategic Shifts & Innovations
Packaging format evolution and regulatory refrigerant phase-downs are reconfiguring equipment procurement priorities across protein processing and beverage manufacturing segments.
Membrane nitrogen generation technology is miniaturizing. Containerized pressure-swing adsorption systems now deliver food-grade nitrogen purity at outputs previously requiring bulk liquid infrastructure. Mid-size meat processors in the Netherlands and Belgium are adopting these units to eliminate distributor dependency. The technology is miniaturizing capital barriers, enabling captive gas production at processing volumes below ten thousand tons annually.
The EPA's Clean Air Act amendments targeting hydrofluorocarbon refrigerants are accelerating mechanical-to-cryogenic freezing conversions. Poultry and seafood processors face compressed retrofit timelines as state-level enforcement tightens. California and Washington facilities are prioritizing nitrogen tunnel freezers over hybrid systems to preempt compliance exposure.
Consolidated procurement functions at multinational dairy and ready-meal producers are unbundling gas supply from equipment service contracts. Category managers now negotiate nitrogen and carbon dioxide volumes separately from freezer or carbonator maintenance agreements. This bifurcation is most advanced in Germany, where industrial bakery mergers have created centralized purchasing desks with direct supplier negotiation authority.
Food-Grade Gases Market Segmentation
Segmentation in food-grade gases determines procurement economics and regulatory exposure. Gas purity specifications, delivery infrastructure requirements, and end-use certification standards create distinct commercial boundaries between segments.
Product Type:
Channel-mix patterns diverge sharply: carbon dioxide flows predominantly through direct sales with high-pressure liquid delivery systems, while nitrogen penetrates via distributors for smaller packaging users and on-site generation for large processors.
- Carbon Dioxide:Purified to 99.9% minimum purity with controlled moisture and hydrocarbon limits, this gas serves beverage carbonation through high-pressure liquid delivery systems. Demand concentrates in Germany's consolidated dairy and ready-meal segments where carbonation-grade specifications command premium pricing.
- Nitrogen:Delivered as cryogenic liquid or generated on-site via pressure-swing adsorption, nitrogen displaces oxygen in modified-atmosphere packaging. German meat processors and industrial bakeries are consolidating procurement contracts around this segment, driving same-day delivery commitments from regional fill-plant networks.
- Oxygen:Limited food-grade applications include controlled-atmosphere storage for fresh produce; distribution runs through specialty gas distributors with FDA Current Good Manufacturing Practice certification.
- Argon:Niche applications in wine preservation and premium packaging; procurement typically bundled with nitrogen contracts through industrial gas distributors.
By volume, carbon dioxide leads. By growth pace, nitrogen is expanding most quickly.
Application:
Cost tier differentiation separates capital-intensive freezing installations from consumable gas supply contracts.
- Packaging:Modified-atmosphere formats displace vacuum-sealed alternatives in premium meat and cheese segments, requiring nitrogen or carbon dioxide-nitrogen mixtures. EFSA Regulation 231/2012 additive classifications govern cross-border supply compliance.
- Preserving:Cryogenic freezing systems convert mechanical refrigeration users facing EPA Clean Air Act refrigerant phase-downs; California and Washington poultry processors prioritize nitrogen tunnel freezers.
- Carbonation:Beverage producers anchor long-term take-or-pay contracts; ammonia plant curtailments and ethanol production swings constrain feedstock availability.
- Transportation:Cold-chain integrity mandates under FDA Food Safety Modernization Act rules tighten traceability requirements for temperature-sensitive gas deliveries.
Preserving commands the highest equipment attach rates. Packaging shows the steepest expansion trajectory.
End User:
Customer type determines contract structure: multinational beverage producers negotiate centralized procurement, while family-owned processors remain locked in legacy mechanical refrigeration maintenance contracts.
- Food Manufacturers:Dairy and ready-meal producers unbundle gas supply from equipment service contracts; German industrial bakery mergers have created centralized purchasing desks with direct supplier negotiation authority.
- Beverage Producers:Carbonation-dependent bottlers face spot-market price spikes when ammonia plant curtailments constrain beverage-grade carbon dioxide availability.
- Grocery Stores:In-store bakery and deli operations source through wholesale distributors with cylinder fleet certification.
- Restaurants:Draft beverage systems and sous-vide applications drive small-volume carbon dioxide and nitrogen demand through local gas distributors.
Food manufacturers generate the largest contract volumes. Beverage producers maintain the longest contract durations.
Distribution Channel:
Supply concentration varies: direct sales attach to on-site generation investments, while distributor networks carry cylinder fleet recertification burdens under updated FDA protocols.
- Direct Sales:Long-term take-or-pay contracts with multinational producers; Linde plc leverages dense regional fill-plant networks for same-day carbonation-grade carbon dioxide delivery.
- Distributors:Mid-size meat processors in the Netherlands and Belgium bypass bulk liquid infrastructure through containerized pressure-swing adsorption units.
- Online Retail:Limited to small-cylinder replacement markets for restaurants and grocery delis; regulatory compliance documentation constraints restrict growth.
- Wholesalers:Aggregate demand from fragmented restaurant and small retail segments; face compressed margins from cylinder idle time during FDA-mandated recertification.
Direct sales capture the premium tier. Distributors are gaining share fastest in mid-market nitrogen generation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. Germany concentrates nitrogen demand within consolidated meat processing procurement pools, while the United States fragments across beverage carbonation and cryogenic freezing applications. China exhibits fastest adoption velocity in on-site generation systems for mid-scale food manufacturing.
United States
Poultry processors in California and Washington convert mechanical refrigeration to nitrogen tunnel freezers under EPA Clean Air Act refrigerant phase-down pressures. FDA Food Safety Modernization Act cold-chain mandates tighten traceability for temperature-sensitive gas deliveries. The Pacific Northwest corridor anchors cryogenic freezing conversion demand.
Germany
Industrial bakery mergers and meat processor consolidation create centralized procurement desks with direct supplier negotiation authority. EFSA Regulation 231/2012 governs carbon dioxide and nitrogen food additive classifications for cross-border supply. The North Rhine-Westphalia cluster drives same-day delivery commitments from regional fill-plant networks.
China
Mid-scale food manufacturers adopt containerized pressure-swing adsorption units to bypass bulk liquid infrastructure. National standards under SAMR constrain residual impurity levels in supply cylinders. The Yangtze River Delta concentration accelerates captive nitrogen generation investments.
Netherlands
Meat processors deploy miniaturized membrane nitrogen generation at volumes below ten thousand tons annually. EU F-Gas Regulation implementation compresses payback periods for cryogenic freezing retrofits. The Rotterdam-Antwerp corridor concentrates modified-atmosphere packaging demand.
India
Dairy cooperatives expand carbonation-grade carbon dioxide procurement for value-added beverage lines. FSSAI standards govern food-contact gas purity specifications. The Maharashtra-Gujarat industrial belt concentrates cold-chain infrastructure investment.
Food-Grade Gases Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in food-grade gases. The upper tier commands dense regional fill-plant networks and long-term take-or-pay contracts with multinational beverage producers. The specialist tier differentiates through containerized on-site generation systems and same-day delivery commitments. Consolidation pressures favor backward integration into feedstock sources and captive nitrogen generation technology.
Within the integrated tier, Linde plc and Air Liquide exemplify scale-driven positioning through regional infrastructure density and beverage contract anchoring. Messer SE & Co. KGaA occupies a specialist position focused on nitrogen generation systems for mid-scale meat processing facilities. These three entities represent the dominant competitive archetypes: network-anchored incumbents, contract-locked multinationals, and equipment-integrated specialists.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Messer SE & Co. KGaA |
| Taiyo Nippon Sanso Corporation |
| SOL Group |
| Gulf Cryo |
| Matheson Tri-Gas, Inc. |
| Gruppo SIAD |
| Others |
Cost & Logistics Intelligence
Same-day delivery commitments for carbonation-grade carbon dioxide compress to four-hour windows in Germany's North Rhine-Westphalia cluster, concentrating pricing power with regional fill-plant operators and forcing distributors to absorb fleet idle costs during FDA-mandated cylinder recertification.
Pricing Analysis
Long-term take-or-pay contracts anchor beverage carbonation pricing, while spot-market exposure punishes carbonation-dependent bottlers when ammonia plant curtailments constrain feedstock. Three-tier pricing structure across beverage-grade, packaging-grade, and industrial-grade purity levels separates multinational producers from mid-size meat processors and small grocery delis. Cost compression in cylinder fleet operations is intensifying because recertification protocols under FDA Current Good Manufacturing Practice updates idle assets for extended testing cycles. Family-owned processing operations show highest price sensitivity due to legacy mechanical refrigeration lock-in, while consolidated dairy procurement desks leverage volume pools for standard-tier nitrogen pricing.
Supply Chain Analysis
Germany and the United States anchor food-grade gas production through dense regional fill-plant networks and cryogenic liquid infrastructure. Feedstock draws from ammonia plants, ethanol production facilities, and air separation units for nitrogen generation. Single-source vulnerability concentrates in beverage-grade carbon dioxide where ammonia plant curtailments ripple through carbonation supply. Distribution runs through direct sales for multinational producers and specialty gas distributors for mid-size processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA cylinder certification and EFSA additive classification creates sticky supplier relationships that resist disintermediation.
For Market Incumbents: Compound network density advantages by embedding containerized nitrogen generation systems at German meat processor clusters, locking in equipment-service bundled contracts before Messer SE expands its specialized generator footprint. Prioritize backward integration into air separation feedstock sources to buffer ammonia plant volatility threatening carbon dioxide margins. For New Entrants and Emerging Players: Same-day delivery gaps in secondary US markets present white-space openings where Linde's fill-plant network thins beyond Pacific Northwest corridors. Target mid-scale poultry processors in California and Washington facing compressed EPA refrigerant phase-down timelines with nitrogen tunnel freezer lease-to-own structures. Lead with cryogenic technician training partnerships to neutralize labor scarcity premiums. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial gas parents where food-grade specialization remains under-resourced relative to healthcare or electronics segments. Five-to-ten year viability hinges on captive nitrogen generation technology ownership and regional fill-plant network density. Monitor EPA state-level enforcement acceleration as inflection signal for cryogenic freezing conversion capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Air Separation Feedstock | Captive nitrogen supply buffers ammonia plant volatility affecting carbon dioxide availability. |
| Containerized Nitrogen Generation Deployment | Pressure-swing adsorption units capture margin from distributor-dependent mid-size meat processors. |
| Cryogenic Technician Training Partnerships | Certified labor pipelines neutralize North American and Western European maintenance scarcity premiums. |
| Long-term Take-or-Pay Contract Extension | Beverage producer anchoring secures recurring revenue against spot-market carbon dioxide price spikes. |
| EU F-Gas Regulation Compliance Positioning | Preemptive nitrogen tunnel freezer installations capture poultry processor retrofit demand in Spain and Italy. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with cryogenic system maintenance directors, industrial gas procurement managers at dairy and ready-meal producers, FDA regulatory compliance officers, and EFSA additive classification specialists. Secondary validation drew from FDA Current Good Manufacturing Practice filings, EPA Clean Air Act amendment dockets, EFSA Regulation 231/2012 purity schedules, and customs data on cryogenic equipment imports. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down production capacity assessments from air separation and ammonia plant operators.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning gas purity grade, delivery infrastructure type, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion pipelines. Industry-specific inputs included EPA refrigerant phase-down enforcement timelines and EFSA additive reclassification review cycles.
Underlying assumptions cover stable FDA certification protocol timelines and EFSA additive status continuity, with deviation risk concentrated in ammonia plant curtailment frequency and cryogenic technician certification pipeline throughput. Forecasts reflect these baseline conditions with sensitivity bands around feedstock volatility and labor supply constraints. Recalibration cycles align with material shifts in EPA state-level enforcement patterns and EU F-Gas Regulation national implementation accelerations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Krypton-85 Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Global Argon Market
Industrial Gases
Noble Gas Market
Industrial Gases
Krypton Gas Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
Helium Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Welding Gas Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
GCC Industrial Gases Market