
 Ammonia Market | 2026-2036
Ammonia Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonia Market Analysis
Buyer concentration among agricultural cooperatives and nitrogen traders is rebalancing as distributed biofuel and marine fuel off-takers fragment procurement patterns. CF Industries Holdings leverages its North American gas cost position to sustain export competitiveness against Middle Eastern producers. Yara International anchors its European footprint through carbon capture integration at Norwegian facilities. Nutrien competes by controlling inland distribution infrastructure across the North American Corn Belt.
Ammonia is a colorless alkaline gas with the chemical formula NH3, produced primarily through the Haber-Bosch process using nitrogen and hydrogen feedstocks at pressures of 150-250 bar and temperatures of 400-500°C; its dominant commercial purpose is as a nitrogen carrier for agricultural fertilizers and as a feedstock for industrial chemicals including nitric acid and urea. Anhydrous ammonia dominates bulk fertilizer applications where high nitrogen concentration minimizes transport cost per nutrient unit, while aqueous ammonia serves industrial cleaning and water treatment segments with lower vapor pressure handling requirements. The refrigerants application retains structural importance in cold chain logistics despite environmental pressure, though industrial chemicals represents the fastest-growing margin pool as ammonia gains traction in hydrogen carrier and marine fuel trials.
The EPA regulates ammonia emissions under the Clean Air Act, while OSHA enforces permissible exposure limits in workplace environments; in Europe, REACH and the EU Green Deal's carbon border adjustment mechanism are reshaping import competitiveness and production technology choices. India's Fertilizer Ministry operates under nutrient-based subsidy frameworks administered by the Department of Fertilizers, directly conditioning farmer-facing prices and domestic plant economics. Stakeholders must monitor which regulatory jurisdictions first certify ammonia as an approved hydrogen carrier fuel, as this determination will redirect infrastructure investment and offtake contracting structures.
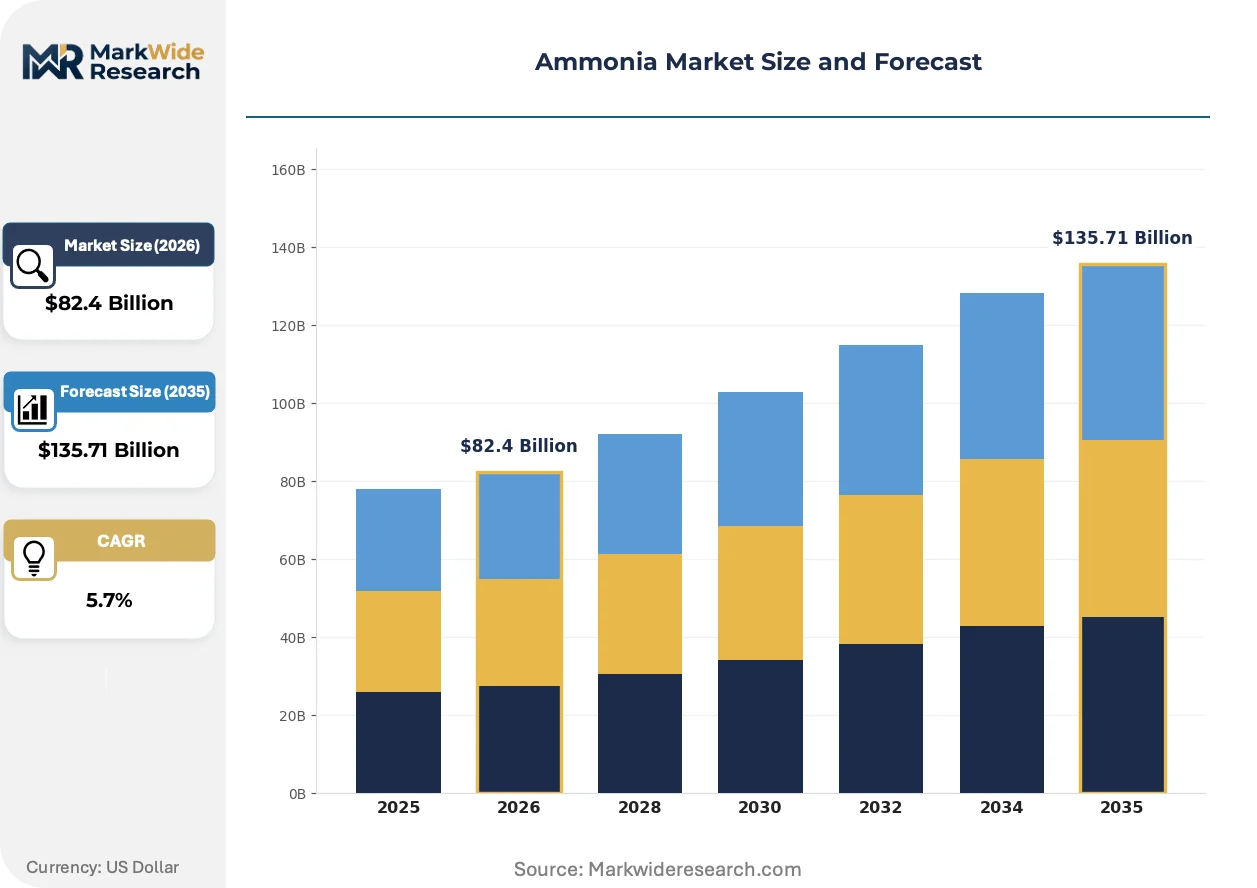
Market Dynamics
Capital rotation toward low-carbon ammonia pathways is restructuring production economics, as carbon border mechanisms and hydrogen carrier certification protocols force asset owners to choose between retrofitting existing Haber-Bosch capacity or constructing greenfield electrolytic facilities.
Growth Catalysts
- Nutrient-Based Subsidy Regimes:India's Department of Fertilizers administers price controls that stabilize domestic plant offtake, insulating local manufacturers from international price volatility while expanding procurement volumes.
- Marine Fuel Certification:The International Maritime Organization's draft guidelines for ammonia bunkering are creating contractual certainty for port infrastructure investments in Rotterdam and Singapore.
- Carbon Capture Retrofits:Post-combustion capture integration at existing steam methane reforming facilities is extending asset life while qualifying output for EU Green Deal-compliant supply chains.
Market Restraints
- Natural Gas Feedstock Volatility:European ammonia producers face margin compression when TTF benchmark prices spike, forcing curtailments at high-cost facilities in Germany and Poland.
- Electrolyzer Capital Intensity:Green ammonia production requires renewable hydrogen at scale, where electrolyzer stack costs and renewable power purchase agreements dominate unit economics.
- Storage and Handling Infrastructure:Anhydrous ammonia's toxic properties necessitate specialized pressurized vessels and refrigeration systems that limit distribution radius from production sites.
Strategic Opportunities
- US Gulf Coast Export Hubs:Low Henry Hub gas prices and existing pipeline networks position Texas and Louisiana facilities to serve Latin American and Asian agricultural markets.
- Hydrogen Carrier Arbitrage:Ammonia's higher volumetric energy density versus liquid hydrogen is attracting power-to-X developers seeking to bridge renewable generation gaps in Japan and South Korea.
- Digital Yield Optimization:Precision agriculture platforms that tie nitrogen application rates to real-time soil sensors are creating premium pricing tiers for certified low-carbon ammonia.
Industry Challenges
- Process Safety Expertise Scarcity:The specialized knowledge required for high-pressure synthesis loop operation and cryogenic handling is concentrating among aging workforces at legacy production sites.
- Cross-Border Certification Fragmentation:Divergent national standards for ammonia-as-fuel safety protocols are forcing project developers to pursue multiple parallel approval tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonia Market |
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $135.71 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Ammonia, Anhydrous Ammonia, Liquid Ammonia, Ammonium Nitrate Application: Fertilizers, Refrigerants, Industrial Chemicals, Cleaning Agents End User: Agriculture, Chemicals, Food & Beverage, Pharmaceuticals Delivery Mode: Bulk, Cylinders, Containers, Packaged Solutions |
| Companies Covered | CF Industries Holdings, Yara International, Nutrien, Koch Fertilizer, OCI Global, SABIC, BASF, Acron, Qatar Fertiliser Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonia Market Emerging Trajectories
Electrification of ammonia synthesis and carbon accounting transparency are converging to separate commodity nitrogen carriers into distinct carbon-intensity grades, with procurement contracts now specifying production pathway verification.
Solid oxide electrolyzer technology paired with Haber-Bosch retrofits is consolidating the green ammonia technology stack, reducing equipment count and thermal losses versus alkaline electrolyzer routes. Fertilizer traders in Brazil and agricultural cooperatives in the US Midwest are piloting offtake agreements tied to certified renewable hydrogen origin. This convergence is compressing the cost gap between gray and blue ammonia production while establishing electrolytic capacity as the marginal supply setter for premium segments.
REACH registration requirements and the EU Green Deal's carbon border adjustment mechanism are tightening import specifications for ammonia-derived fertilizers entering European customs territory. The regulation forces third-country exporters to document production emissions or face tariff penalties, redirecting trade flows toward certified low-carbon suppliers. Nitrogen traders with European blending operations are restructuring supply chains to source from Norwegian and Middle Eastern facilities with verified carbon capture.
Long-term offtake contracting is displacing spot market purchasing among nitrogen traders serving agricultural cooperatives, as price volatility and carbon certification requirements favor bilateral agreements with defined production pathways. Marine fuel distributors and power-to-X developers are negotiating 10-15 year purchase commitments with electrolytic ammonia projects, locking in volume before construction financing closes. This pattern is most visible in Northwest Europe and East Asia, where hydrogen import strategies depend on ammonia cracking infrastructure deployment.
Ammonia Market Segmentation
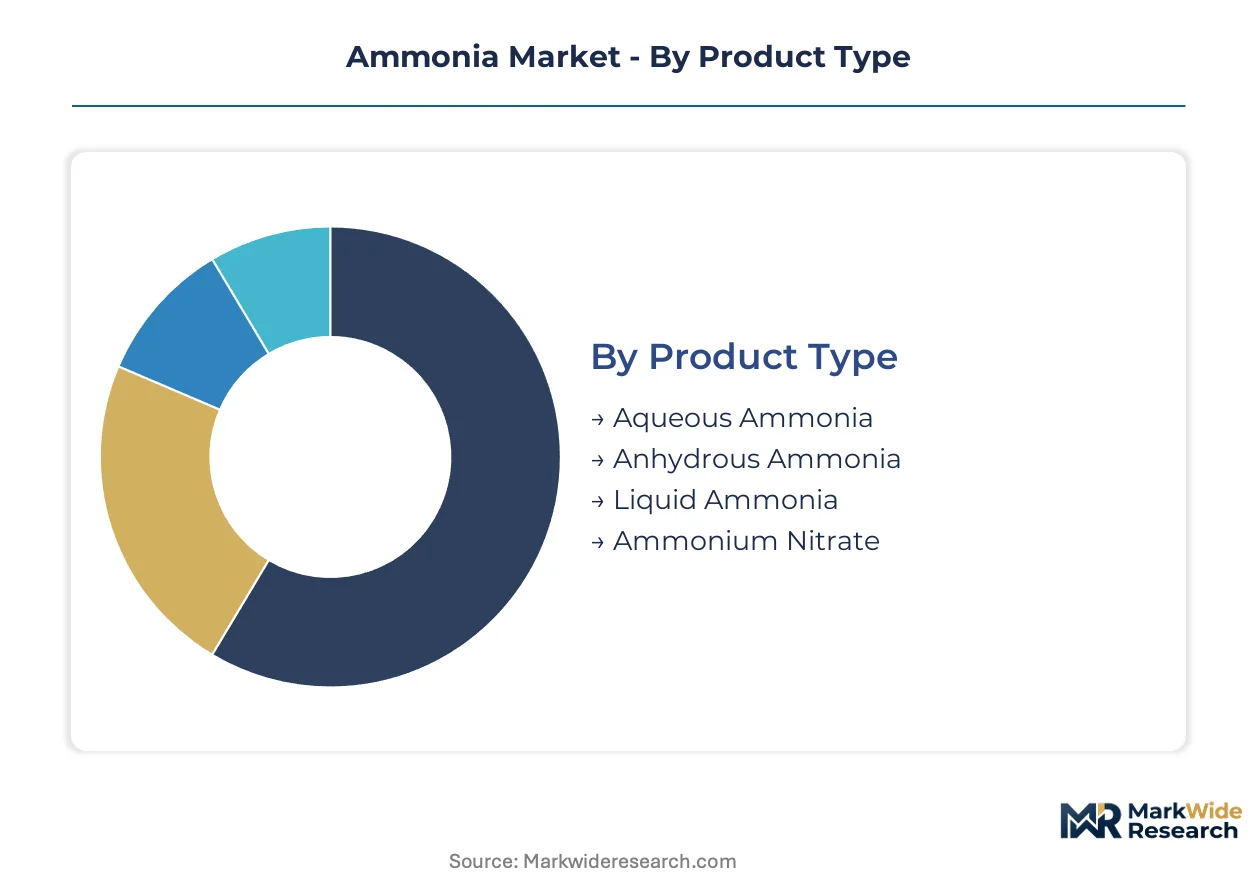
Ammonia's physical state and purity specifications dictate handling infrastructure, transport economics, and end-use compatibility. Segment boundaries are hardening as carbon certification requirements split commodity grades from premium low-carbon supply tiers.
Product Type:
Upgrade cycles in fertilizer application equipment and marine fuel handling systems are reshaping procurement specifications across product grades.
- Anhydrous Ammonia:Contains 82% nitrogen by weight with vapor pressure of 8.5 bar at 20°C, requiring pressurized storage and specialized handling protocols. Demand concentrates in the US Corn Belt and Black Sea grain belts where high-nutrient density minimizes per-ton freight costs for bulk fertilizer distributors.
- Aqueous Ammonia:20-30% NH3 solution in water with negligible vapor pressure at ambient temperature, enabling safer handling in confined industrial spaces. Water treatment facilities in Japan and semiconductor fabs in South Korea are expanding offtake for pH control and precision cleaning applications.
- Liquid Ammonia:Cryogenic liquid form at -33°C, stored in insulated vessels for large-volume industrial supply. Petrochemical complexes in Rotterdam and Singapore use this grade for continuous feedstock delivery.
- Ammonium Nitrate:Solid derivative produced through neutralization with nitric acid, regulated as explosive precursor in most jurisdictions. Mining explosives manufacturers in Australia and quarry operators in Brazil represent core demand clusters.
Anhydrous ammonia sits at the top of the volume ranking, with aqueous ammonia climbing the fastest as industrial safety regulations tighten.
Application:
Cost tier divergence is pronounced between commodity nitrogen carriers and emerging premium segments tied to carbon intensity certification.
- Fertilizers:Direct soil injection or granular compound production consumes the majority of global ammonia flow. Indian cooperative procurement under nutrient-based subsidy regimes and Brazilian soybean planting cycles drive seasonal demand spikes.
- Industrial Chemicals:Feedstock for nitric acid, caprolactam, and acrylonitrile synthesis with stringent purity specifications. German automotive suppliers and Chinese nylon producers are negotiating long-term offtake tied to verified low-carbon production pathways.
- Refrigerants:Thermodynamic properties enable efficient heat absorption in cold chain logistics despite environmental pressure from leakage regulations. Food processing clusters in Denmark and pharmaceutical distribution hubs in Switzerland retain structural demand.
- Cleaning Agents:Alkaline dissolution properties suit industrial degreasing and emissions control in power generation. US ethanol plants and Middle East desalination facilities represent concentrated procurement pockets.
Fertilizers dominate absolute volume, while industrial chemicals is gaining share fastest as hydrogen carrier trials convert speculative demand into contracted offtake.
End User:
Customer type fragmentation is accelerating as marine fuel off-takers and power-to-X developers join traditional agricultural procurement pools.
- Agriculture:Row crop producers, specialty vegetable growers, and plantation operators across temperate and tropical zones. Argentine wheat farmers and Vietnamese rice cooperatives are locking in forward purchases to hedge price volatility.
- Chemicals:Integrated petrochemical producers and specialty chemical formulators requiring consistent feedstock quality. BASF's Ludwigshafen complex and SABIC's Jubail facilities anchor regional demand concentration.
- Food & Beverage:Refrigeration system operators and food freezing processors with zero-tolerance for contamination risk. New Zealand dairy cooperatives and Norwegian aquaculture cold chains specify food-grade certification.
- Pharmaceuticals:Active ingredient synthesis and excipient production with pharmacopeia compliance requirements. Swiss contract manufacturers and Indian API exporters drive specification intensity.
Agriculture sits at the top of the volume ranking, with chemicals climbing the fastest as ammonia-to-hydrogen cracking projects advance.
Delivery Mode:
Supply concentration in pipeline corridors and port terminals dictates distribution economics for each delivery format.
- Bulk:Rail tank cars, river barges, and ocean vessels for volumes exceeding 1,000 tonnes. US Gulf Coast export terminals and Yuzhny port in Ukraine (when operational) handle the largest single lifts.
- Cylinders:Pressurized steel containers for industrial maintenance and small-scale agricultural application. Independent distributors across the Australian outback and Canadian prairie provinces maintain cylinder exchange networks.
- Containers:ISO tank units enabling multimodal transfer without transloading. Singapore bunkering hubs and Rotterdam ammonia cracking pilot projects are standardizing container specifications.
- Packaged Solutions:Pre-diluted or buffered formulations for laboratory and specialty agricultural use. Precision viticulture operations in France and controlled-environment agriculture in the Netherlands specify packaged grades.
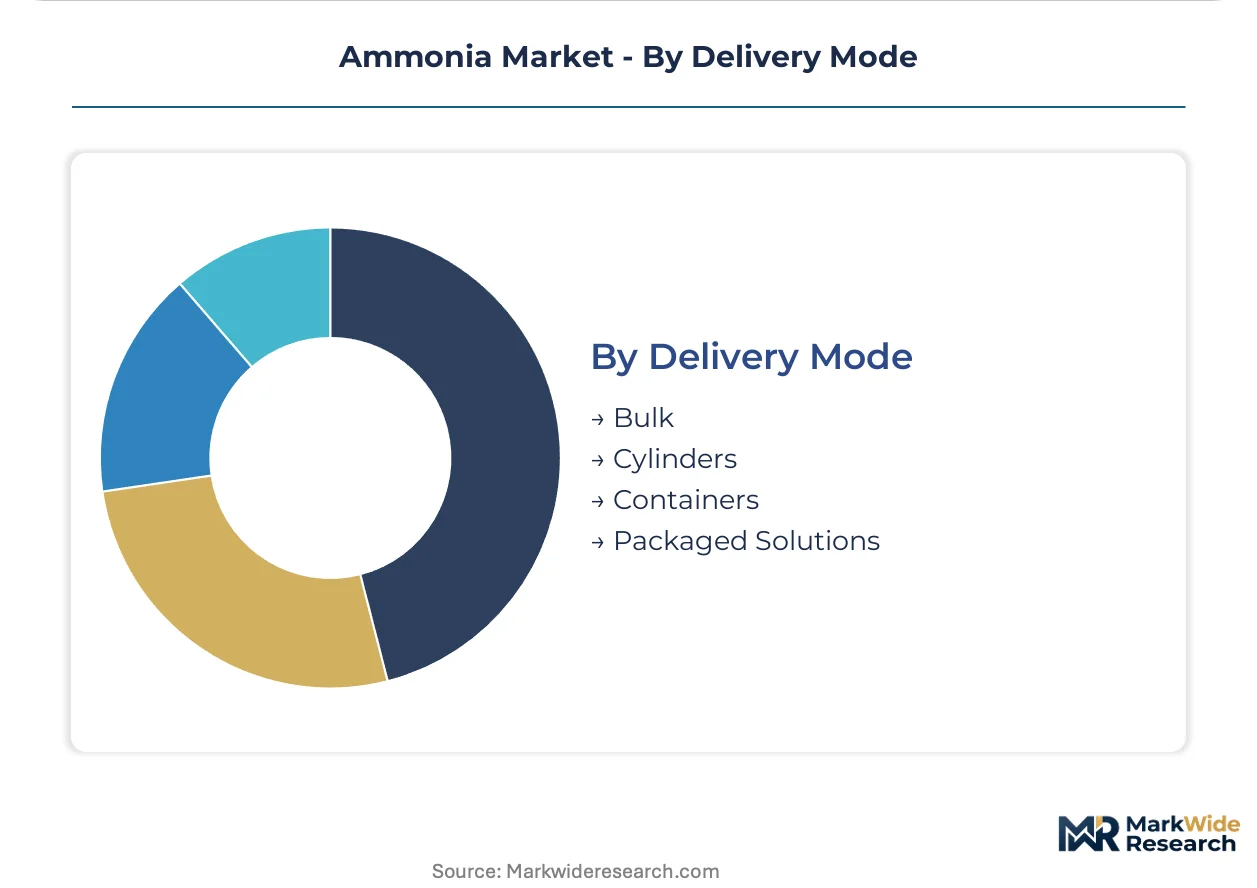
Bulk sits at the top of the volume ranking, with containers climbing the fastest as marine fuel logistics standardizes around ISO tank frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's nutrient-based subsidy regime stabilizes domestic offtake volumes, while Qatar leverages gas feedstock economics to anchor export-oriented ammonia complexes serving Asian and European agricultural markets.
United States
Henry Hub gas prices sustain export competitiveness for Gulf Coast producers serving Latin American fertilizer distributors. EPA regulations under the Clean Air Act condition emissions compliance for steam methane reforming facilities. The Texas-Louisiana corridor concentrates pipeline and terminal infrastructure for bulk export to Brazil and Mexico.
India
Fertilizer cooperatives expand procurement under the Department of Fertilizers' nutrient-based subsidy framework, insulating domestic plants from international price volatility. The Fertilizer Ministry's price control mechanisms directly condition farmer-facing economics. Gujarat and Maharashtra host the largest integrated ammonia-urea complexes serving the Indo-Gangetic grain belt.
Qatar
North Field gas reserves enable ultra-low production costs for export-oriented ammonia complexes targeting Asian nitrogen traders. The country's national hydrocarbon regulator oversees feedstock allocation for petrochemical expansion. Ras Laffan Industrial City concentrates world-scale ammonia export terminals with dedicated loading infrastructure.
Germany
TTF benchmark volatility forces production curtailments at high-cost steam methane reforming facilities during price spikes. The EU Green Deal's carbon border adjustment mechanism reshapes import competitiveness for nitrogen derivatives. Ludwigshafen and the Rhine corridor host integrated chemical complexes negotiating long-term offtake tied to verified low-carbon pathways.
Saudi Arabia
SABIC's Jubail facilities anchor regional demand concentration for industrial chemical feedstock applications. The national industrial development program conditions capital allocation for blue ammonia demonstration projects. The Eastern Province concentrates gas-based ammonia production integrated with petrochemical and fertilizer export infrastructure.
Ammonia Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct carbon-intensity tiers. The structure consolidates around integrated gas-to-fertilizer operators, nitrogen traders with distribution infrastructure, and emerging electrolytic developers. Three archetypes dominate: legacy Haber-Bosch operators retrofitting carbon capture, Gulf-based gas advantaged exporters, and power-to-X developers targeting hydrogen carrier certification. Competitive moves center on long-term offtake contracting for certified low-carbon supply and strategic partnerships for ammonia cracking infrastructure deployment.
Among North American gas-advantaged producers, CF Industries Holdings exemplifies the retrofitting archetype with carbon capture integration, while Nutrien occupies a position combining upstream mining with inland distribution control. Yara International represents the European incumbent navigating carbon border pressures through Norwegian facilities. These three anchors illustrate divergent strategic responses to the same regulatory pressure: certification-driven procurement fragmentation.
| Leading Market Players |
|---|
| CF Industries Holdings |
| Yara International |
| Nutrien |
| Koch Fertilizer |
| OCI Global |
| SABIC |
| BASF |
| Acron |
| Qatar Fertiliser Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon border adjustment mechanisms are forcing nitrogen traders to document production emissions or face tariff penalties, compelling supply chain restructuring toward verified low-carbon sources and compressing margins for uncertified gray ammonia.
Pricing Analysis
Capacity additions in Qatar and Saudi Arabia are reshaping price floors for seaborne ammonia trade. Contract-based long-term offtake dominates procurement, with price differentiation driven by carbon certification grade and volume scale. Cost compression in gray ammonia is intensifying because Middle Eastern gas-advantaged producers expand export volumes. Agricultural cooperatives in India and Brazil show highest price sensitivity, while marine fuel distributors in Rotterdam and Singapore accept premium pricing for certified low-carbon supply tiers.
Supply Chain Analysis
Process safety expertise scarcity in Germany and Poland constrains operational readiness at legacy Haber-Bosch facilities. Manufacturing concentrates in Qatar, Saudi Arabia, and the United States Gulf Coast. Feedstock supply draws from North Field gas reserves, Henry Hub-priced domestic supply, and TTF-indexed European molecules. Single-source vulnerability runs through Strait of Hormuz transit corridors. Distribution runs through dedicated ammonia export terminals at Ras Laffan, integrated pipeline networks in Texas and Louisiana, and ISO tank container frameworks for marine bunkering trials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ammonia procurement is shifting toward certified low-carbon grades as hydrogen carrier certification protocols mature, elevating quality specifications above commodity nitrogen carrier baselines.
For Market Incumbents: Acquire carbon capture retrofit assets at existing steam methane reforming facilities to extend asset life and qualify output for EU Green Deal-compliant supply chains. Secure long-term renewable power purchase agreements for electrolytic capacity expansions to defend position against emerging Gulf-based gas-advantaged exporters.
For New Entrants and Emerging Players: Launch via ISO tank container distribution models targeting marine fuel bunkering hubs in Singapore and Rotterdam. White-space opportunity concentrates in electrolytic ammonia for hydrogen carrier applications in Japan and South Korea, where power-to-X developers seek volumetric energy density advantages over liquid hydrogen.
For Investors and Strategic Acquirers: Asymmetric upside sits with electrolytic developers holding approved hydrogen carrier certification and secured offtake from marine fuel distributors. Five-to-ten year viability hinges on ammonia cracking infrastructure deployment pace. Watch IMO ammonia bunkering guideline finalization as inflection indicator for contractual certainty and port infrastructure investment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | Extends Haber-Bosch asset life while qualifying output for EU carbon border compliance. |
| Electrolytic Capacity Buildout | Positions developers as marginal supply setters for premium low-carbon ammonia tiers. |
| Long-term Offtake Contracting | Locks in volume commitments from marine fuel distributors before construction financing closes. |
| Ammonia Cracking Infrastructure | Enables hydrogen carrier arbitrage for Japanese and Korean power-to-X import strategies. |
| Green Certification Program | Documents renewable hydrogen origin for procurement contracts specifying production pathway verification. |
Methodological Framework
Multiple input streams — executive interviews with ammonia plant managers and nitrogen trader procurement leads, customs and trade flow databases, and SEC 10-K filings from listed fertilizer producers — were reconciled against production capacity databases and carbon intensity disclosure reports. Bottom-up triangulation across facility-level operating rates and top-down validation through regional consumption models anchored volume estimates. Primary fieldwork captured operating cost structures at steam methane reforming and electrolytic facilities across the analysis window.
Segmentation dimensions modeled include product grade tier, end-use application, carbon intensity certification status, and regional production hub configuration. CAGRs were derived through slope analysis of annual capacity additions against demand absorption rates. Forecast inputs incorporated Henry Hub and TTF gas price scenario bands, electrolyzer capital cost learning curves, and IMO regulatory timeline assumptions for marine fuel certification.
Several conditions sit outside the modeled scope, including unannounced policy shifts in Indian nutrient-based subsidy regimes and accelerated IMO decarbonization mandates beyond current draft guidelines. Forecasts reflect documented assumptions regarding carbon border mechanism enforcement timelines and hydrogen carrier cracking technology commercialization pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Muriatic Acid Market
Chemicals
Global Organobromine Market
Chemicals
Calcium Borate Market
Chemicals
Diethyl Sulfate Market
Chemicals
Fluorochemicals Market
Chemicals
Potassium Iodide Market
Chemicals
RDX and HMX Market
Chemicals
Acid Anhydrides Market
Chemicals
Global Bleaching Agents Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Europe Biguanide Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Vinyl Acetate Market
Chemicals
SLS and LABSA Market
Chemicals
Methanol to Gasoline Market