
 Welding Gas Market | 2026-2036
Welding Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Gas Market Analysis
Specialty gas distribution networks is reshaping how welding gases reach fragmented end users across industrial zones. Linde leverages its on-site production model to anchor supply relationships with large-scale automotive manufacturers in Germany and the United States. Air Liquide competes through localized micro-bulk delivery systems that reduce cylinder handling costs for mid-sized metal fabricators. Messer Group specializes in customized argon-CO2 blends for high-alloy steel applications, differentiating its portfolio from commodity oxygen suppliers.
Welding gas denotes industrial gases—primarily argon, carbon dioxide, oxygen, and acetylene—blended or applied singularly to shield molten weld pools from atmospheric contamination, with purity grades typically exceeding 99.5% for critical applications. These gases prevent oxidation and porosity in arc welding processes across carbon steel, stainless steel, and aluminum substrates. Argon-based shielding mixtures dominate margin pools in aerospace and precision fabrication, where defect tolerance approaches zero. CO2 segments sustain volume leadership in construction and heavy equipment welding, where cost sensitivity outweighs premium gas requirements. Metal fabrication applications represent the fastest-growing demand cluster, driven by infrastructure renewal programs and modular construction adoption.
The U.S. OSHA mandates exposure limits for welding fumes and ozone, compelling gas suppliers to certify shielding mixtures for reduced fume generation in confined-space operations. The EU REACH framework and F-Gas Regulation restrict certain fluorinated additives, redirecting R&D toward inert gas recycling and closed-loop delivery architectures. China's GB standards and MEE emissions protocols enforce cylinder traceability and leak-rate thresholds for industrial gas logistics. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance costs for multi-national gas portfolios will determine competitive viability in cross-border contract bidding.
Market Dynamics
Automated welding adoption in East Asian shipyards is compressing demand cycles for high-purity shielding gases while forcing suppliers to reconfigure delivery architectures around just-in-time production schedules.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP fluorinated gases redirects R&D investment toward inert gas recovery systems and closed-loop welding processes.
- Modular construction:Prefabricated building components require precision TIG welding with argon-helium blends, expanding specialty gas consumption in factory-controlled environments.
- Shanghai-Busan industrial corridor:Concentrated shipbuilding and automotive manufacturing clusters generate sustained bulk demand for customized shielding mixtures.
Market Restraints
- Helium supply concentration:Qatar and the United States control over 75% of global helium extraction, exposing argon-helium blend pricing to geopolitical disruption.
- Acetylene feedstock volatility:Calcium carbide production depends on Chinese metallurgical coke availability, creating input cost instability for oxy-acetylene welding segments.
- Cylinder asset intensity:Gas distributors must maintain depreciating cylinder fleets across fragmented customer bases, compressing working capital efficiency.
Strategic Opportunities
- India metal fabrication:The country's PLI scheme for capital goods and infrastructure build-out creates underpenetrated demand for packaged shielding gases outside traditional industrial clusters.
- Micro-bulk delivery systems:Cryogenic liquid tank installations at mid-sized fabricators eliminate cylinder handling labor and reduce gas losses from decanting.
- ISO 14175 standard harmonization:Unified global classification of shielding gas mixtures simplifies cross-border specification and reduces regional formulation complexity.
Industry Challenges
- Welding procedure qualification:ASME Section IX and ISO 15614 certification timelines for new gas mixtures delay commercial deployment by 12-18 months.
- Cryogenic logistics integration:Matching liquid argon delivery schedules with variable fabrication shop consumption requires predictive demand modeling capabilities most distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Gas Market |
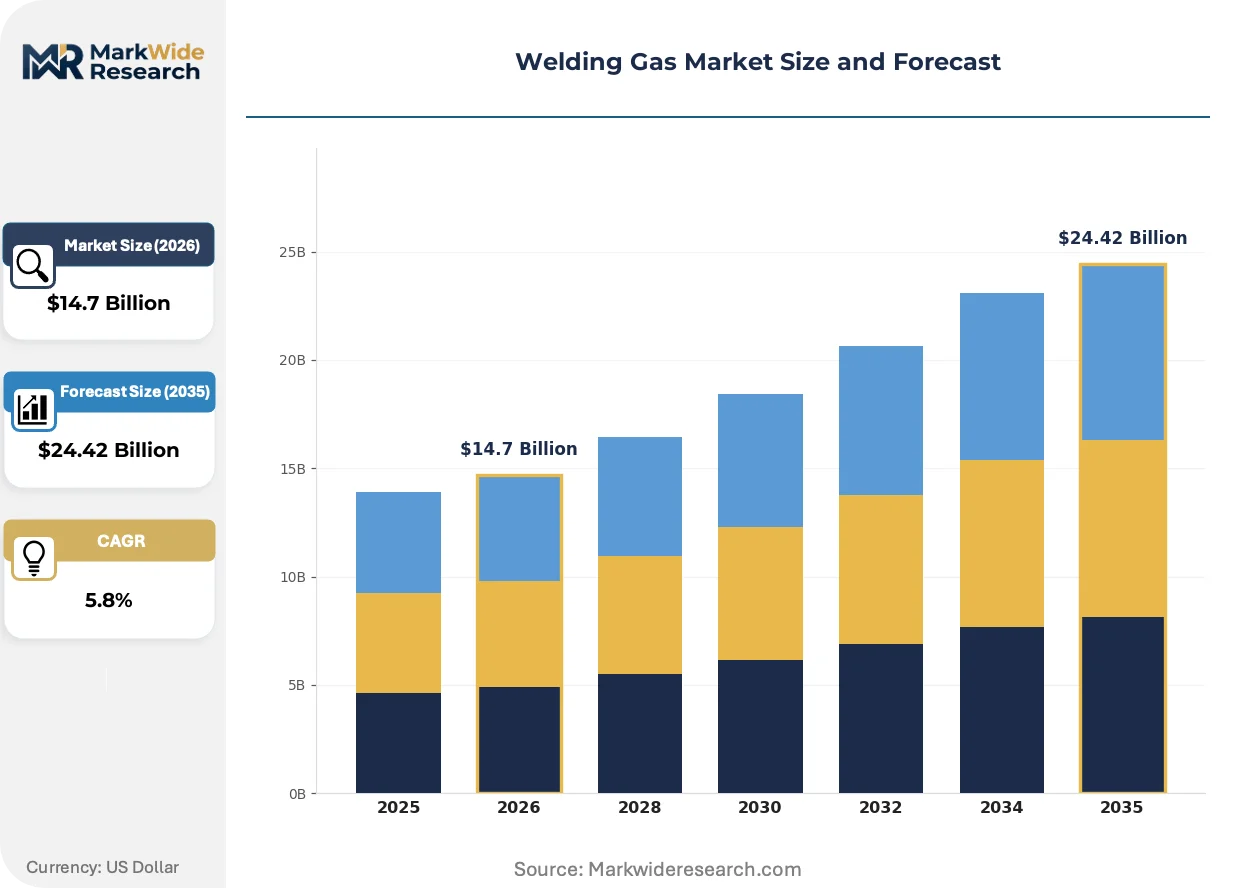
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Gas Type: Argon, Acetylene, Oxygen, CO2 Application: Metal Fabrication, Automotive, Construction, Aerospace End User: Manufacturers, Contractors, Repair Shops, Educational Institutions Distribution Channel: Direct Sales, Retail, Online Sales, Distributors |
| Companies Covered | Air Liquide, Linde, Air Products and Chemicals, Messer Group, Praxair, Iwatani Corporation, Taiyo Nippon Sanso Corporation, Iceblick, Gulf Cryo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Gas Market Emerging Trajectories
Real-time weld pool monitoring and predictive gas consumption analytics are compressing traditional supply relationships while enabling outcome-based service models.
Sensor-integrated shielding gas delivery systems is digitizing weld quality assurance. Automotive manufacturers in Germany and Japan deploy mass flow controllers with IoT connectivity to log gas consumption per weld seam. This capability is digitizing quality traceability requirements and forcing distributors to integrate data layers into cylinder management platforms.
REACH authorization requirements for chromium-containing welding consumables are accelerating substitution toward inert gas processes. The restriction affects stainless steel fabrication workflows across EU member states. Metal fabricators in Northern Italy and the Czech Republic respond by qualifying argon-nitrogen blends for thin-gauge applications previously dependent on flux-cored wire.
Consolidated procurement through industrial gas management contracts is displacing spot cylinder purchases. Large metal fabricators in the United States negotiate enterprise agreements bundling gas supply, equipment maintenance, and safety training. This shift concentrates buying power with national distributors and marginalizes independent welding supply retailers in the Midwest manufacturing belt.
Welding Gas Market Segmentation
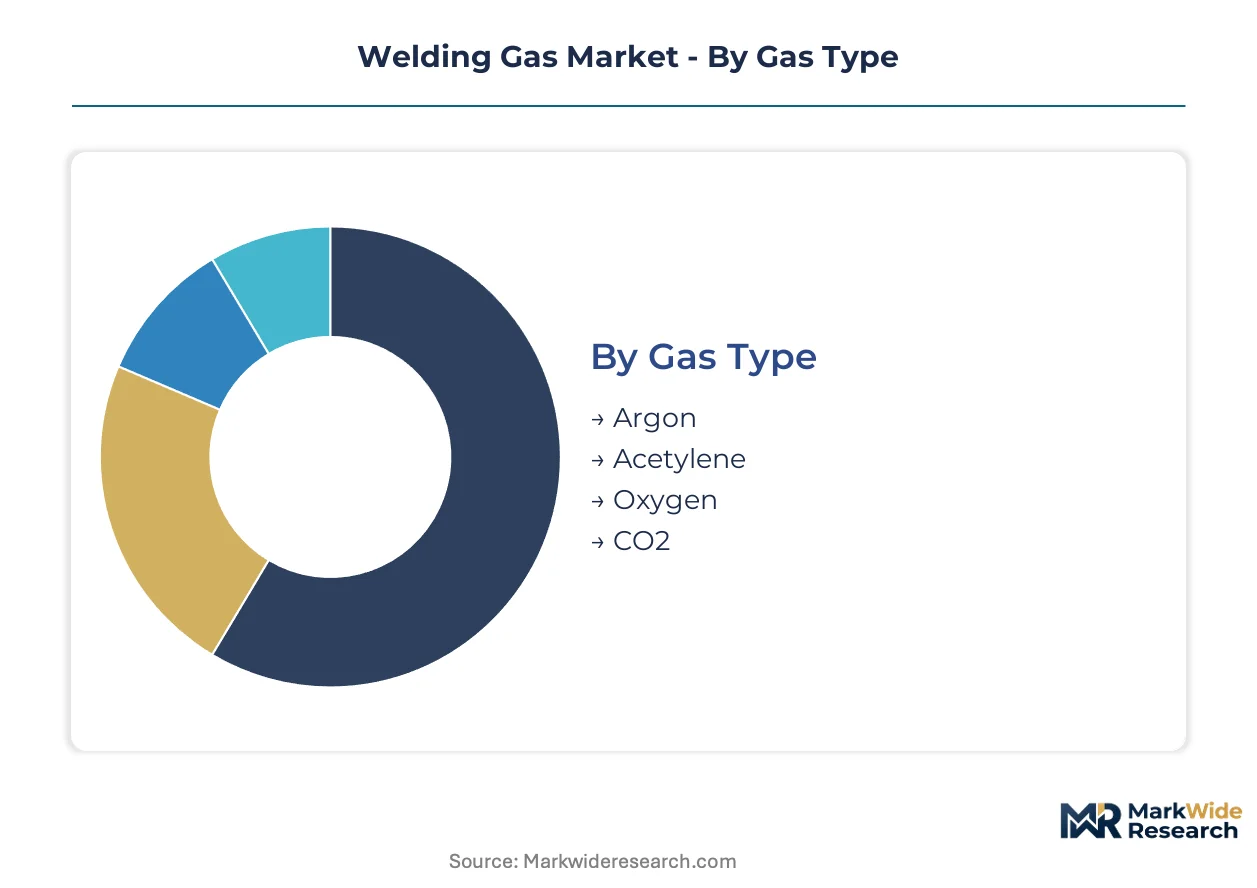
Welding gas segmentation reveals how purity grades, delivery modes, and end-use requirements fragment procurement patterns. Suppliers configure product portfolios and logistics networks around these divides to capture margin pools that commodity oxygen cannot access.
Gas Type:
Cost tier determines margin structure across inert, reactive, and fuel gas categories.
- Argon:High-purity inert shielding gas, typically 99.995% grade for TIG and MIG welding processes. Demand concentrates in aerospace component manufacturing around Hamburg and Toulouse, where defect tolerance requirements and ASME certification standards lock in premium pricing.
- Acetylene:Fuel gas produced from calcium carbide reaction, delivering the hottest flame temperature among common welding gases. Oxy-acetylene cutting dominates shipbreaking yards in Alang, India and demolition contractors across the US Gulf Coast, though feedstock volatility from Chinese coke markets compresses margin stability.
- Oxygen:Oxidizing support gas for oxy-fuel cutting and plasma arc processes, with industrial grades at 99.5% purity. Steel service centers in the Ruhr region and Osaka Bay clusters sustain bulk consumption through pipeline delivery.
- CO2:Active shielding gas for MAG welding of carbon steels, offering cost efficiency over argon blends. Construction equipment manufacturers in Caterpillar's Decatur, Illinois operations and Hyundai's Ulsan complex drive volume procurement through long-term supply agreements.
Argon commands the established base. The steepest expansion runs through CO2 as infrastructure welding intensifies across South Asian industrial corridors.
Application:
End-use maturity separates specification-driven segments from price-sensitive volume markets.
- Metal Fabrication:Precision cutting and joining of structural steel components, pressure vessels, and process equipment. German Mittelstand fabricators in Baden-Württemberg and emerging metalworking clusters in Vietnam's Bac Ninh province drive demand for customized argon-CO2 blends with certified weld procedures.
- Automotive:Robotic MIG welding of body-in-white assemblies and exhaust systems requiring consistent shielding gas flow rates. Toyota's Georgetown, Kentucky plant and BMW's Spartanburg facility anchor just-in-time bulk delivery contracts with penalty clauses for supply interruption.
- Construction:Field welding of structural steel frames, rebar, and infrastructure components exposed to atmospheric conditions. High-rise projects in Dubai's Business Bay and Mumbai's BKC district sustain cylinder-based acetylene and oxygen procurement through distributor networks.
- Aerospace:Critical fusion welding of titanium alloys and nickel-based superalloys demanding 99.999% purity argon with moisture specifications below 3 ppm. Airbus's Toulouse final assembly and SpaceX's Hawthorne operations qualify single-source gas suppliers through 18-month certification cycles.
Construction commands the established base. Aerospace gains share fastest through defense procurement expansion and commercial aviation backlog recovery.
End User:
Customer scale dictates delivery architecture from bulk cryogenic tanks to individual cylinder exchanges.
- Manufacturers:Integrated production facilities with dedicated gas storage and vaporization systems. Caterpillar's East Peoria foundry and Samsung Heavy Industries' Geoje shipyard operate on-site argon production or pipeline connections to minimize logistics cost per cubic meter.
- Contractors:Mobile welding operations serving construction, maintenance, and turnaround projects. Pipeline construction crews in Alberta's oil sands and offshore platform fabricators in Singapore's Jurong shipyard rely on manifolded cylinder packs and bulk liquid trailers.
- Repair Shops:Small-scale maintenance welding with intermittent consumption patterns. Independent automotive repair garages in Mexico City's Iztapalapa district and agricultural equipment service centers in Australia's Riverina region purchase through retail welding supply stores.
- Educational Institutions:Vocational training programs teaching SMAW, GMAW, and GTAW certification curricula. Community colleges in Texas's Permian Basin and technical institutes in Poland's Silesian region consume packaged gases through government procurement frameworks.
Manufacturers command the established base. Contractors expand most quickly as modular construction and infrastructure maintenance outsourcing accelerate.
Distribution Channel:
Supply concentration shapes how gas molecules reach fragmented consumption points.
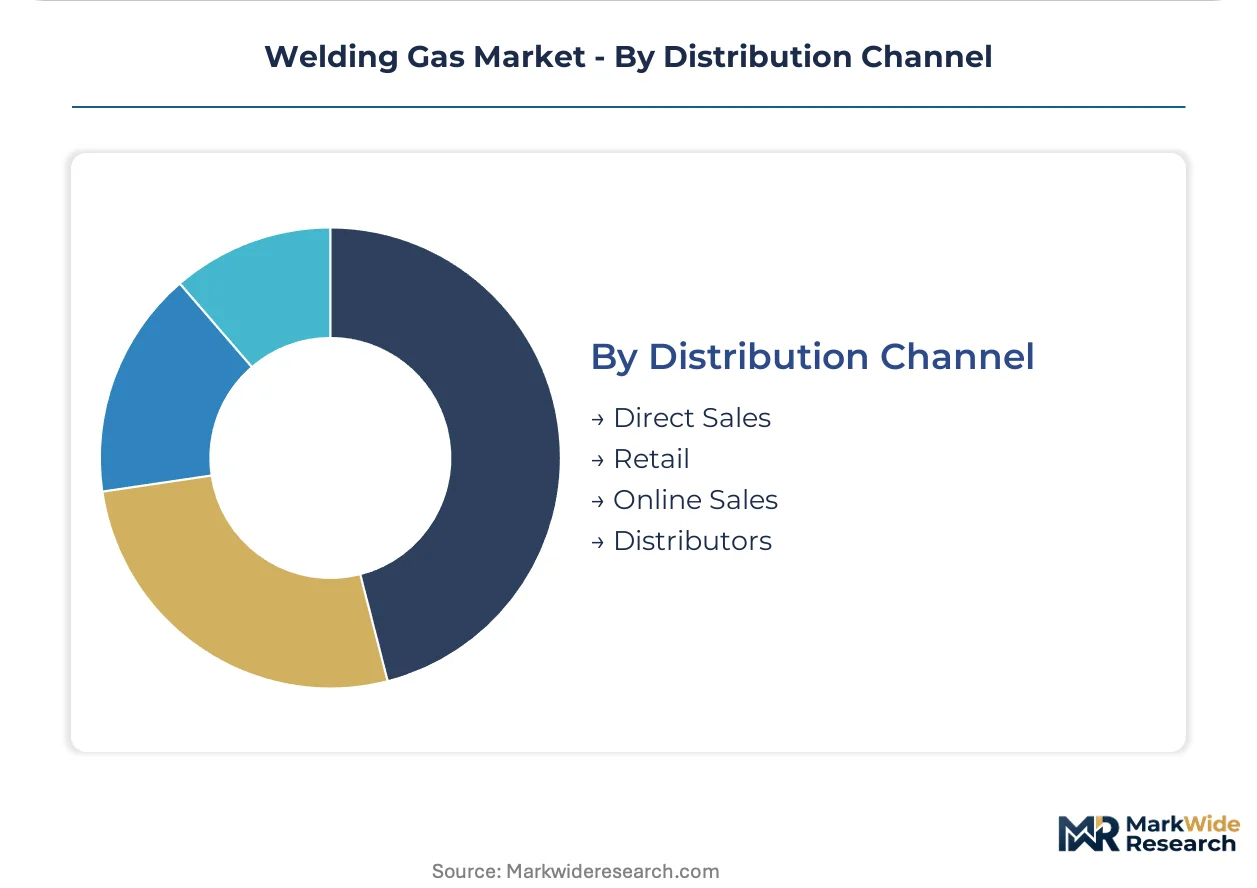
- Direct Sales:Long-term contracts between producers and large-volume consumers with dedicated account management. Linde's hydrogen pipeline networks in the US Gulf Coast and Air Liquide's on-site air separation units at ThyssenKrupp steelworks exemplify captive supply relationships.
- Retail:Physical storefronts serving walk-in customers with immediate cylinder exchange needs. Independent welding supply stores in Ohio's Mahoning Valley and franchise operations in France's Rhône-Alpes region maintain local cylinder fleets and consumables inventory.
- Online Sales:E-commerce platforms for equipment, accessories, and scheduled gas deliveries. Amazon Business and specialized industrial marketplaces capture small-fabricator procurement in South Korea's Gyeonggi-do manufacturing belt.
- Distributors:Independent intermediaries consolidating multi-brand gas and equipment portfolios. Regional distributors in Italy's Veneto region and Brazil's São Paulo state aggregate demand from mid-sized metal fabricators to negotiate volume discounts with national producers.
Direct sales command the established base. Micro-bulk delivery through distributor networks climbs the fastest as mid-cap fabricators upgrade from cylinder handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA mandates exposure limits for welding fumes across the United States, compelling gas suppliers to certify shielding mixtures for reduced fume generation. This regulatory anchor shapes how industrial gas markets develop across major manufacturing economies.
United States
Automotive manufacturers in Michigan and Kentucky drive bulk demand for argon-based shielding gases through robotic welding lines. OSHA enforcement of confined-space exposure limits accelerates adoption of certified low-fume mixtures. The Gulf Coast petrochemical corridor sustains pipeline-delivered oxygen consumption for maintenance welding.
Germany
Mittelstand metal fabricators in Baden-Württemberg require customized argon-CO2 blends with certified weld procedures for precision components. The EU F-Gas Regulation redirects investment toward gas recovery systems and closed-loop delivery architectures. Automotive plants in Bavaria anchor just-in-time bulk supply contracts with penalty clauses for interruption.
China
Shipbuilding clusters around Shanghai and Busan generate sustained demand for high-purity shielding mixtures in automated welding. GB standards and MEE emissions protocols enforce cylinder traceability and leak-rate thresholds for industrial gas logistics. Infrastructure renewal programs across the Yangtze River Delta expand CO2 consumption for construction equipment welding.
Japan
Precision fabrication around Nagoya and Osaka demands 99.999% purity argon with moisture specifications below 3 ppm for aerospace component welding. METI industrial policy supports gas recycling technology development. Shipbuilders in Kure and Yokohama adopt advanced shielding gas blends for automated hull assembly.
India
The PLI scheme for capital goods creates underpenetrated demand for packaged shielding gases outside traditional industrial clusters. BIS certification requirements for cylinder safety standards shape distributor investment priorities. Metal fabrication growth in Gujarat and Maharashtra drives cylinder-based procurement through regional distributor networks.
Welding Gas Market Vendor Landscape
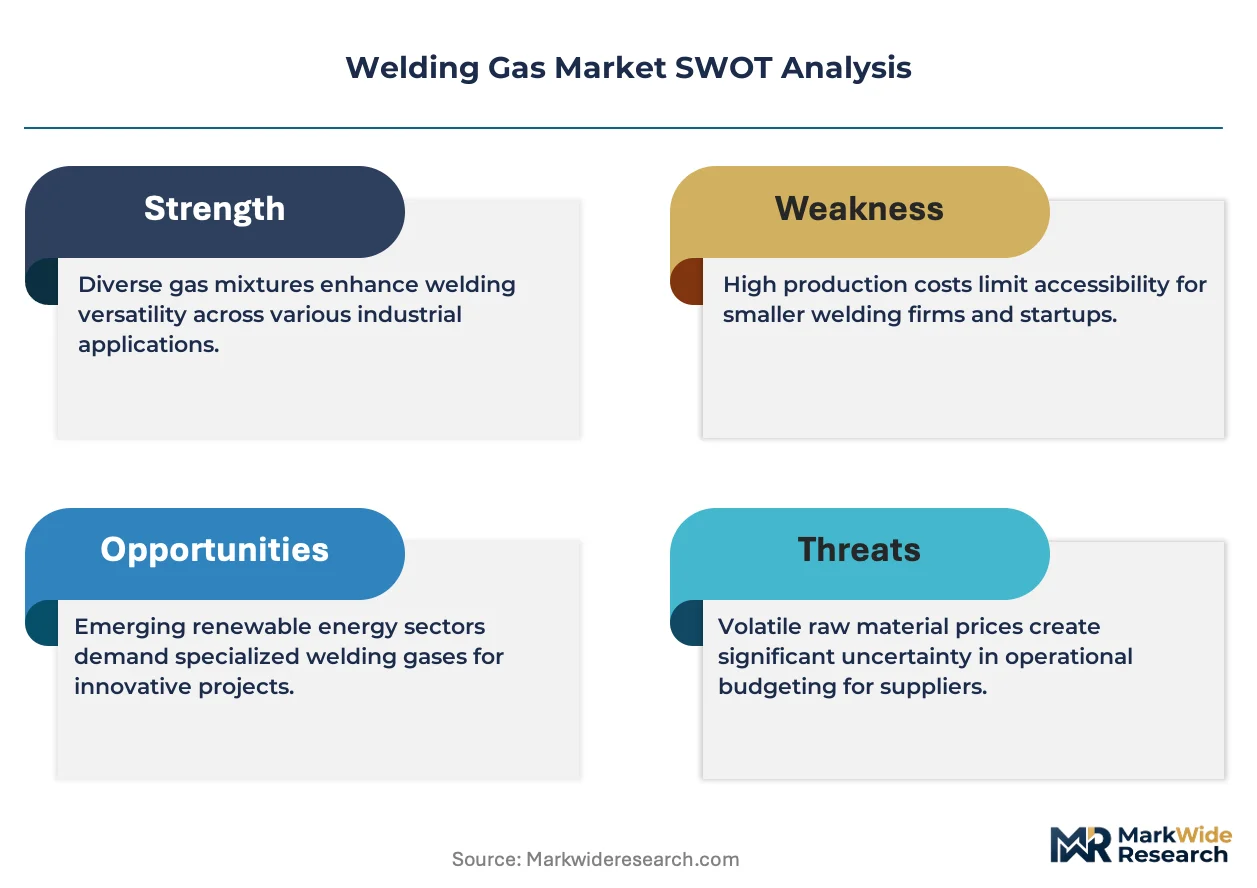
Vertically integrated gas majors and regional specialists split the market through divergent delivery architectures. The vendor base concentrates around three strategic archetypes: on-site production operators with pipeline networks, micro-bulk delivery specialists with cryogenic tank fleets, and packaged gas distributors with cylinder exchange infrastructure. Competitive moves center on backward integration into air separation capacity and forward integration into welding equipment service contracts.
Within the multinational tier, Air Liquide and Linde occupy positions as integrated gas suppliers with captive production infrastructure across multiple continents. Messer Group exemplifies the regional specialist archetype, concentrating customized blend formulations for high-alloy steel applications. These three anchors demonstrate how scale and specialization create defensible positions against commodity oxygen competition.
| Leading Market Players |
|---|
| Air Liquide |
| Linde |
| Air Products and Chemicals |
| Messer Group |
| Praxair |
| Iwatani Corporation |
| Taiyo Nippon Sanso Corporation |
| Iceblick |
| Gulf Cryo |
| Others |
Supply Flow & Price Mechanics
Qatar's Ras Laffan helium extraction complex anchors global supply for argon-helium blends, translating upstream concentration into pricing power for aerospace-grade shielding gases. This geographic chokepoint forces Japanese and German fabricators to absorb volatility through long-term offtake contracts or switch to nitrogen-substituted formulations.
Pricing Analysis
Regional price spreads between Gulf Coast pipeline oxygen and packaged cylinder deliveries in India's secondary cities exceed threefold. Three-tier pricing structure across aerospace-certified, industrial-grade, and construction-economy levels separates ASME-certified argon from commodity CO2. Pricing pressure stems from Chinese calcium carbide feedstock instability for acetylene production. Construction contractors exhibit highest price sensitivity, while aerospace manufacturers accept premium tiers for defect-free certification.
Supply Chain Analysis
Contract manufacturing concentration rests with Linde's on-site air separation units and Air Liquide's micro-bulk cryogenic tank networks. Supply concentrates in the United States, Qatar, and China for helium and rare gas extraction. Raw material dependencies include metallurgical coke for calcium carbide, natural gas feedstock for hydrogen production, and cryogenic equipment for liquefaction. Single-source vulnerability runs through Qatar's helium dominance. Distribution runs through direct pipeline connections for bulk consumers and distributor cylinder exchanges for fragmented fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEMs and shipbuilders negotiating enterprise gas management contracts, marginalizing independent welding supply retailers across the US Midwest and Germany's Ruhr region.
For Market Incumbents: Entrench position through backward integration into captive air separation capacity at automotive anchor plants in Kentucky and Bavaria. Deepen certification investment for ISO 14175 harmonization to lock out regional blend competitors. Counter the threat of IoT-enabled gas monitoring startups by embedding sensor layers into existing cylinder management platforms. For New Entrants and Emerging Players: India's Gujarat and Maharashtra metal fabrication clusters offer geographic underpenetration for packaged shielding gas distribution outside traditional industrial corridors. Target mid-sized Vietnamese fabricators in Bac Ninh province with micro-bulk tank installations eliminating cylinder handling labor. Pursue government procurement frameworks for technical institute gas supply as a low-competition entry channel. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with customized blend capabilities over commodity oxygen producers. Long-term viability hinges on gas recycling technology and closed-loop delivery architectures. Target acquisition archetypes include cryogenic logistics operators with predictive demand modeling software. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for inert gas recovery system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Air Separation | Captive argon production at Toyota's Georgetown plant eliminates third-party margin extraction. |
| Micro-Bulk Delivery System Deployment | Cryogenic tank installations at mid-sized fabricators reduce cylinder handling costs and gas losses. |
| ISO 14175 Standard Harmonization | Unified gas mixture classification simplifies cross-border specification for multinational contracts. |
| Gas Recovery Technology Investment | Closed-loop welding processes align with EU F-Gas Regulation phasedown requirements. |
| IoT-Enabled Consumption Monitoring | Sensor-integrated mass flow controllers at BMW Spartanburg digitize quality traceability per weld seam. |
Methodological Framework
Initial hypotheses were tested against primary input from welding gas procurement managers, automotive Tier 1 supplier engineers, shipyard fabrication directors, and industrial gas distribution executives, then refined through secondary validation. Sources included customs trade data for argon and helium flows, SEC filings from listed gas majors, EU ECHA REACH authorization databases, and national cylinder safety standards. Bottom-up demand modeling from end-use consumption points and top-down supply capacity assessments were triangulated for convergence.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by gas purity grade, delivery mode, end-use application, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical consumption patterns and projected infrastructure spending trajectories. Forecast inputs incorporated shipbuilding order backlogs at South Korean yards, automotive production schedules for electric vehicle platforms, and modular construction adoption rates in North American and European markets.
Practitioners should monitor helium supply disruption indicators, EU F-Gas Regulation amendment timelines, and Chinese calcium carbide export quota announcements for early signals of forecast revision. Assumptions reflect current regulatory frameworks and production capacity configurations. Quarterly review of shipbuilding contract awards, automotive OEM gas management RFPs, and infrastructure stimulus disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Syngas Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
Helium Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Oxygen Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Noble Gas Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market