
 Industrial Hydrogen Market | 2026-2036
Industrial Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hydrogen Market Insights
Green hydrogen certification standards are reorganizing procurement priorities across energy-intensive sectors. Linde plc leverages its pipeline network density to sustain delivery reliability for Gulf Coast refiners. Air Liquide anchors European production scale through electrolyzer partnerships in the Netherlands and France. Siemens Energy AG differentiates via proton exchange membrane technology leadership for modular electrolyzer systems.
Industrial hydrogen is a diatomic gas produced through steam methane reforming, electrolysis, or gasification, typically supplied at purities ranging from 99.9% to 99.999% depending on application requirements, serving primarily as a feedstock for ammonia synthesis, petroleum hydrotreating, and direct reduction iron processes. Steam methane reforming occupies the dominant share of current output volume due to established infrastructure and cost structure, though electrolysis represents the fastest-expanding production method as renewable electricity costs decline and offtake contracts attach green premiums. Ammonia production commands the largest application segment by volume, while fuel cells attract disproportionate capital allocation from transportation end users seeking zero-emission powertrains.
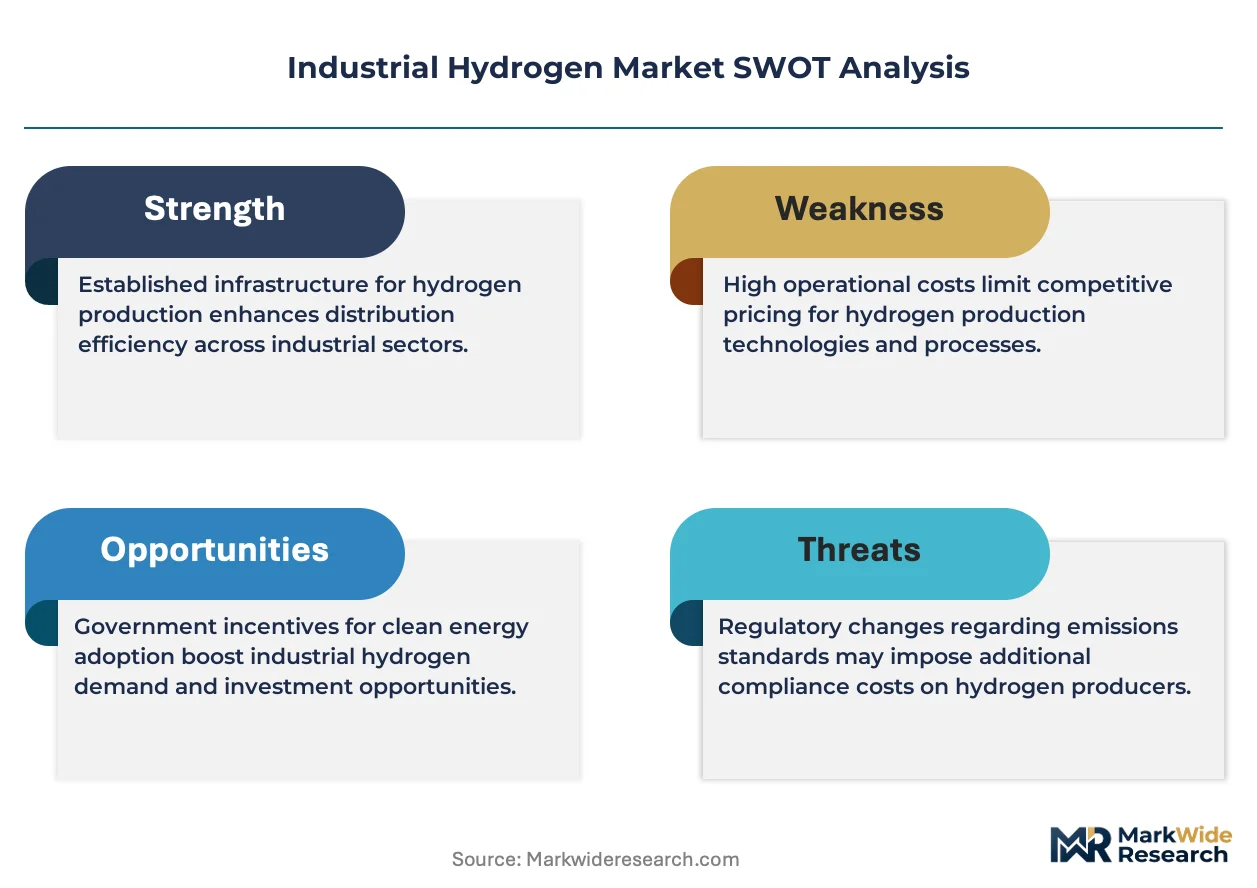
The EPA enforces emissions thresholds that tighten compliance margins for steam methane reforming facilities, while the IRA production tax credits reshape project economics for electrolytic hydrogen in the United States. OSHA process safety management standards govern bulk storage and handling protocols, influencing site selection and engineering design for new production assets. Stakeholders must weigh feedstock cost trajectories against policy durability when committing capital to multi-decade production infrastructure.
Market Dynamics
Electrolyzer cost curves and renewable electricity tariffs are compressing green hydrogen production premiums against gray hydrogen baselines faster than anticipated infrastructure buildouts can absorb.
Growth Catalysts
- IRA Production Tax Credits:The Inflation Reduction Act's tiered credit structure for clean hydrogen production reshapes project finance assumptions for electrolyzer deployments along the US Gulf Coast.
- Steel sector decarbonization mandates:Direct reduction iron producers in Germany's industrial corridor anchor long-term offtake agreements, creating demand visibility for electrolyzer manufacturers.
- Carbon Border Adjustment Mechanism:The EU's CBAM phases in embodied carbon tariffs on imported steel and chemicals, redirecting capital toward electrolytic hydrogen to preserve export competitiveness.
Market Restraints
- Renewable electricity cost volatility:Intermittency-driven price spikes in European power markets erode electrolyzer economics during peak demand periods.
- Pipeline infrastructure concentration:Gulf Coast hydrogen transmission networks remain controlled by incumbent industrial gas suppliers, limiting new entrant market access.
- Electrolyzer stack durability gaps:Proton exchange membrane degradation rates under high-frequency cycling constrain operational flexibility for grid-balancing applications.
Strategic Opportunities
- US Midwest ammonia corridor:Corn belt fertilizer producers seek to displace imported gray hydrogen with regionally produced electrolytic supply.
- Maritime fuel cell propulsion:Port authorities in Rotterdam and Singapore pilot bunkering infrastructure for hydrogen-derived ammonia as shipping fuel.
- Power-to-X regulatory sandboxes:Denmark and the Netherlands exempt pilot electrolyzer projects from full grid tariff obligations, accelerating learning-curve capture.
Industry Challenges
- Electrolyzer engineering talent scarcity:Specialized membrane fabrication and stack assembly skills concentrate in Germany and Japan, constraining workforce scaling.
- Green certification verification timelines:Guarantees of origin schemes lack harmonized auditing protocols, delaying premium pricing realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hydrogen Market |
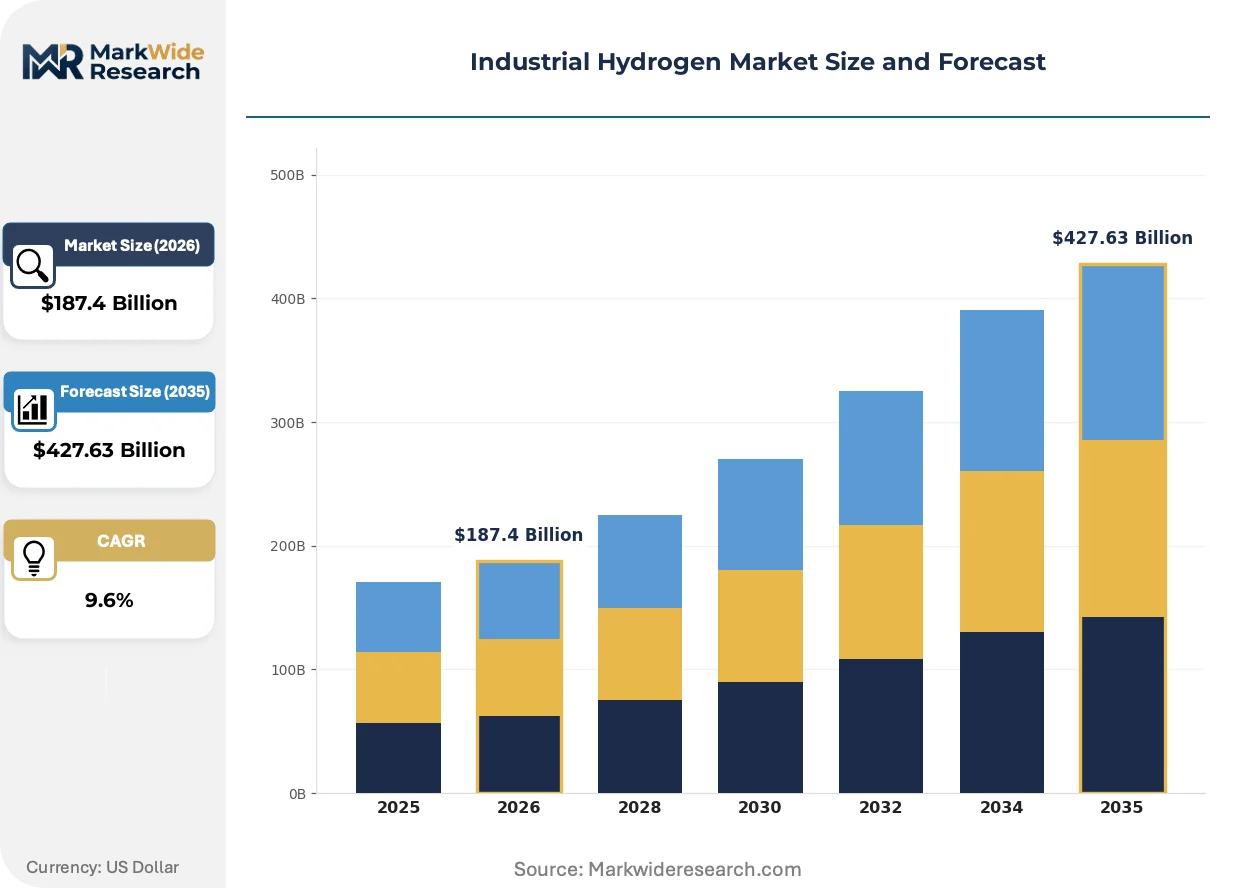
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $427.63 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Steam Methane Reforming, Electrolysis, Gasification, Water Gas Shift Application: Ammonia Production, Oil Refining, Fuel Cells, Metallurgy End User: Chemicals, Energy, Manufacturing, Transportation Distribution Channel: Pipelines, Tankers, On-site Production, Gas Cylinders |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Chart Industries, Shell plc, Siemens Energy AG, Cummins Inc., ENGIE SA, Plug Power Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hydrogen Market Trends and Innovations
Modular electrolyzer architectures and digital twin integration are compressing project development cycles while enabling distributed production models that bypass centralized infrastructure constraints.
Containerized alkaline electrolyzer systems are miniaturizing. Steel mini-mills and chemical clusters adopt skid-mounted 5-10 MW units for captive hydrogen production. This topology eliminates pipeline dependence and compresses commissioning timelines from years to months.
The EU's F-Gas Regulation tightens fluorinated gas phase-down schedules for cooling systems in electrolyzer balance-of-plant equipment. Industrial gas suppliers redesign thermal management architectures. German and French electrolyzer OEMs accelerate hydrocarbon refrigerant adoption to maintain CE marking compliance.
Long-term offtake contracting is displacing spot procurement in ammonia and refining applications. Project developers demand 10-15 year purchase agreements to secure construction financing. This pattern concentrates buyer power among integrated chemical producers with balance sheet capacity, squeezing merchant hydrogen traders from the value chain.
Industrial Hydrogen Market Segmentation
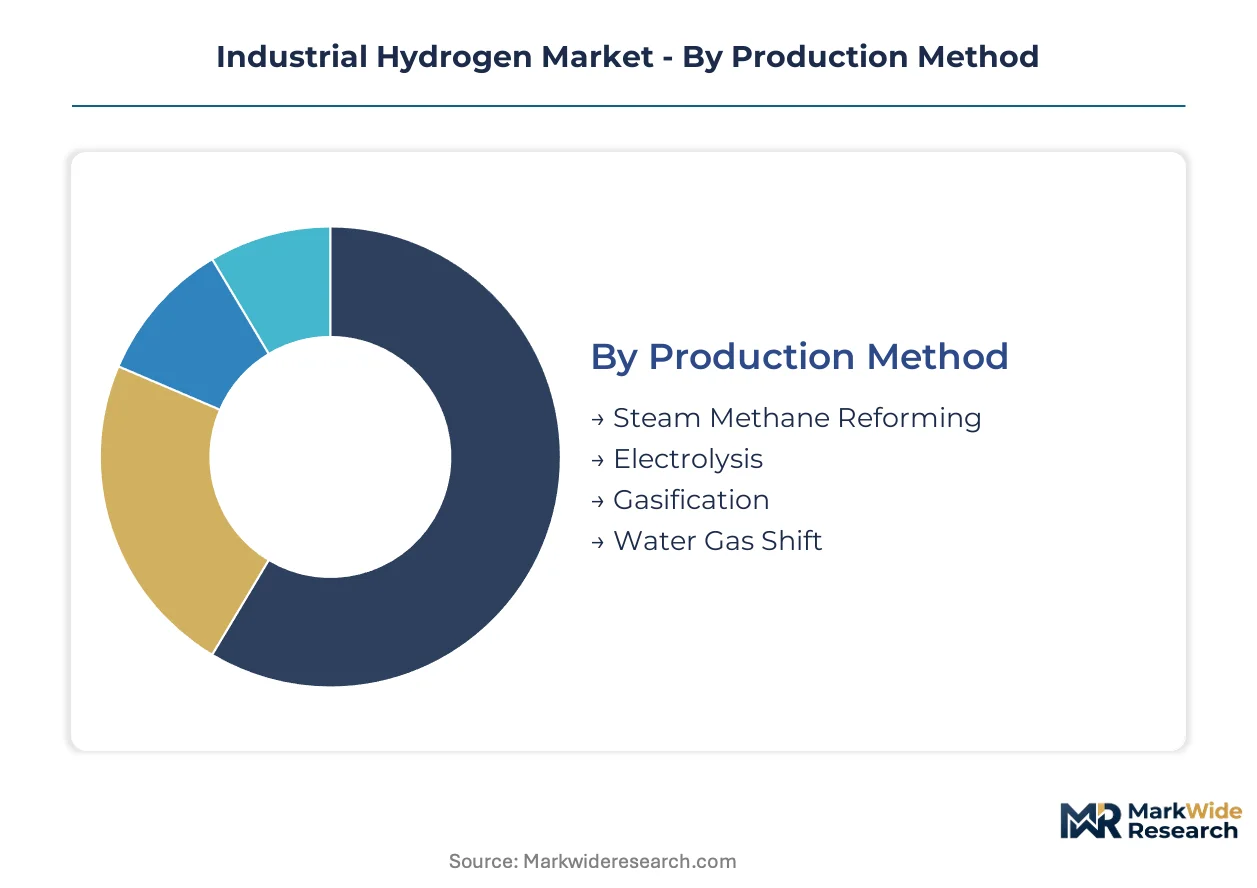
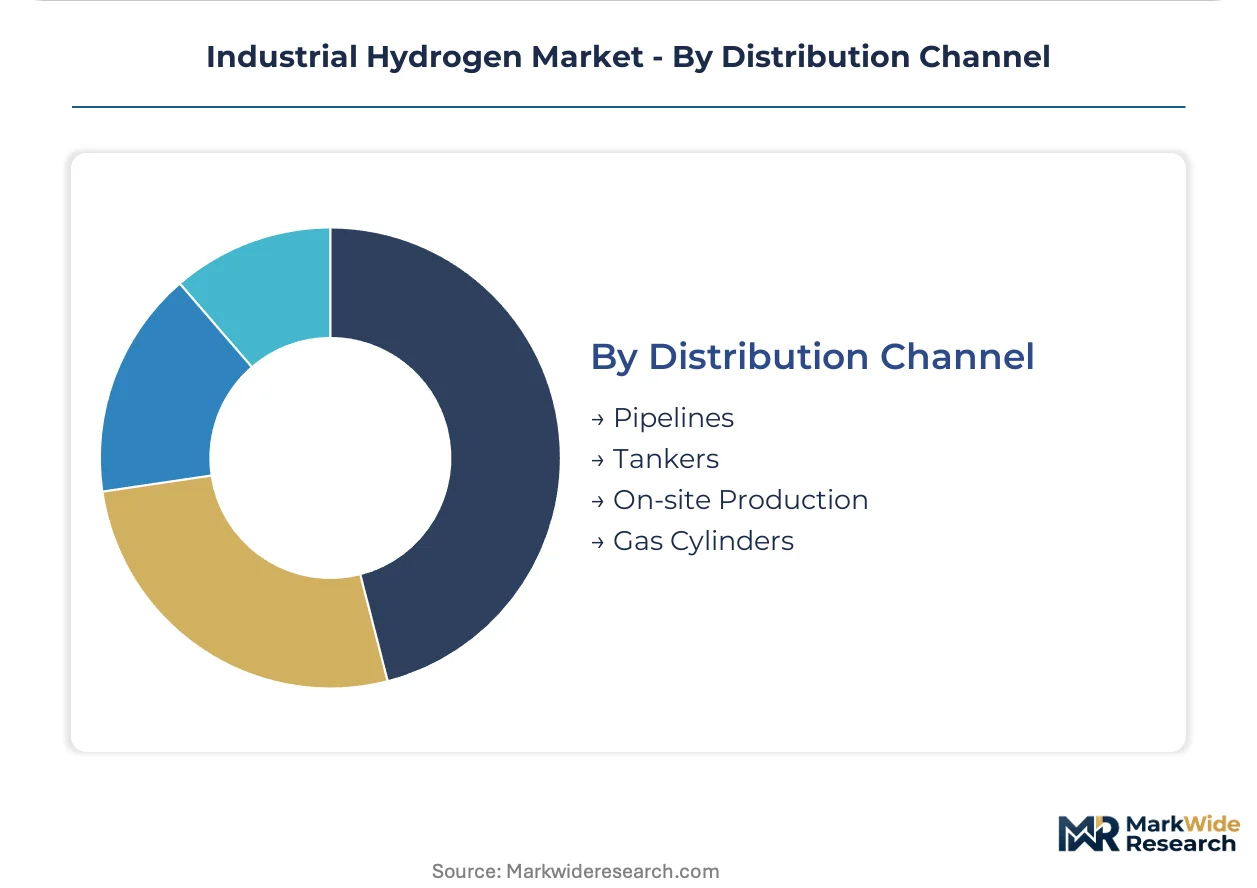
Industrial hydrogen flows through distinct production and delivery pathways that shape procurement economics. Channel configuration varies sharply by purity requirements, volume scale, and proximity to consumption clusters.
Production Method:
Steam methane reforming dominates pipeline deliveries to Gulf Coast refiners, while electrolysis concentrates in renewable-rich zones seeking green certification premiums.
- Steam Methane Reforming:Natural gas feedstock conversion yields 99.9% purity hydrogen through catalytic reaction with steam. US refinery operators along the Texas-Louisiana corridor anchor demand, constrained by tightening EPA emissions thresholds for CO2 venting.
- Electrolysis:Electric current splits water into hydrogen and oxygen, achieving 99.999% purity for semiconductor and fuel cell applications. Germany's industrial corridor concentrates PEM electrolyzer deployments, driven by Carbon Border Adjustment Mechanism compliance deadlines for steel exports.
- Gasification:Coal or biomass partial oxidation produces syngas for ammonia synthesis. China deploys integrated gasification combined cycle plants for coal-to-chemicals complexes.
- Water Gas Shift:Catalytic CO conversion adjusts hydrogen-to-carbon ratios in syngas streams. Refinery hydrogen recovery units employ this step for purge gas upgrading.
By volume, steam methane reforming leads. By growth pace, electrolysis is expanding most quickly.
Application:
Cost tier stratification separates commodity ammonia feedstock from premium fuel cell grades commanding certification markups.
- Ammonia Production:Haber-Bosch synthesis consumes hydrogen at 150-250 bar pressure with iron-based catalysts. Corn belt fertilizer producers in Iowa and Illinois seek electrolytic supply to displace imported gray hydrogen.
- Oil Refining:Hydrocracking and hydrotreating desulfurize transport fuels. US Gulf Coast refiners scale hydrogen intake to process heavier crude slates.
- Fuel Cells:Proton exchange membrane stacks demand 99.97% minimum purity with CO contamination below 0.2 ppm. South Korean automotive OEMs anchor polymer electrolyte membrane procurement.
- Metallurgy:Direct reduction iron furnaces replace coke with hydrogen reductant. Swedish steelmakers pilot HYBRIT technology for fossil-free sponge iron.
Ammonia production commands the largest volume share. Fuel cells show the steepest expansion trajectory.
End User:
Customer type determines contract structure, with integrated chemical producers locking 10-15 year offtake agreements while merchant traders face margin compression.
- Chemicals:Methanol synthesis and hydrogenation reactions anchor captive production at petrochemical complexes. BASF's Ludwigshafen site operates Europe's largest steam methane reforming capacity.
- Energy:Power-to-gas storage and synthetic fuel production absorb intermittent renewable generation. Danish regulatory sandboxes exempt pilot electrolyzers from full grid tariffs.
- Manufacturing:Glass float lines and semiconductor fabs require ultra-high purity for float glass and silicon wafer processing. Japanese electronics clusters specify 99.9999% purity for epitaxial deposition.
- Transportation:Heavy-duty fuel cell trucks and maritime ammonia bunkering pilot zero-emission logistics. Rotterdam port authority develops hydrogen-derived ammonia loading infrastructure.
Chemicals end users lead by contracted volume. Transportation is gaining share fastest on maritime decarbonization mandates.
Distribution Channel:
Supply concentration dictates access economics, with incumbent pipeline operators controlling Gulf Coast corridors while modular units bypass infrastructure bottlenecks.
- Pipelines:Dedicated hydrogen transmission systems operate at 10-70 bar pressure across 1,600 km of US Gulf Coast network. Linde plc's pipeline density sustains delivery reliability for Texas refiners.
- Tankers:Liquid hydrogen carriers at -253°C transport intercontinental volumes. Kawasaki Heavy Industries develops 160,000 m3 LH2 vessels for Australian-Japanese supply chains.
- On-site Production:Captive steam methane reforming or electrolysis eliminates transport costs. Steel mini-mills adopt 5-10 MW skid-mounted alkaline units for direct reduction iron feedstock.
- Gas Cylinders:Tube trailers and bundled cylinders serve laboratories and small-scale industrial users. Regional gas distributors manage cylinder exchange logistics for metal fabrication shops.
Pipelines carry the highest volume throughput. On-site production shows the fastest capacity addition rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian producers are positioning liquefied hydrogen exports toward Japanese and South Korean buyers, with Kawasaki Heavy Industries developing specialized carriers for the trade corridor. This intercontinental flow is reshaping investment patterns across Pacific Rim production zones.
United States
Gulf Coast refiners in Texas and Louisiana scale hydrogen intake for hydrocracking heavier crude slates. The EPA enforces tightening emissions thresholds for steam methane reforming facilities, while IRA production tax credits reshape electrolyzer project economics. Houston anchors pipeline network density, with Linde plc sustaining delivery reliability across 1,600 kilometers of dedicated transmission infrastructure.
Germany
Steelmakers and chemical producers in the industrial corridor anchor long-term offtake agreements for electrolytic supply. The EU Carbon Border Adjustment Mechanism phases in embodied carbon tariffs on imported steel, redirecting capital toward electrolyzer installations. The Ruhr region concentrates direct reduction iron pilot projects, with ThyssenKrupp and Salzgitter trialing fossil-free sponge iron production.
Netherlands
Rotterdam port authority pilots hydrogen-derived ammonia bunkering infrastructure for maritime decarbonization. Power-to-X regulatory sandboxes exempt pilot electrolyzer projects from full grid tariff obligations, accelerating learning-curve capture. The Eemshaven industrial cluster attracts electrolyzer partnerships seeking North Sea offshore wind integration.
China
Coal-to-chemicals complexes deploy integrated gasification combined cycle plants for ammonia synthesis feedstock. MEE enforces dual carbon goals that tighten compliance margins for carbon-intensive production methods. The Ningxia and Inner Mongolia coal belts concentrate gasification capacity, though coastal provinces trial electrolyzer deployments for renewable-rich manufacturing zones.
Japan
South Korean automotive OEMs anchor polymer electrolyte membrane procurement for fuel cell powertrains. METI coordinates hydrogen supply chain development through the Green Growth Strategy. The Kawasaki and Yokohama industrial zones concentrate fuel cell stack assembly, with Kobe developing liquefied hydrogen import terminal capacity for Australian supply.
Industrial Hydrogen Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base stratifies between integrated industrial gas conglomerates with pipeline network control and modular electrolyzer specialists pursuing distributed production models. Three archetypes dominate: incumbent pipeline operators leveraging infrastructure moats, electrolyzer OEMs racing down cost curves, and project developers aggregating offtake contracts for construction financing. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing renewable electricity supply agreements and long-term purchase commitments.
Within the integrated industrial gas tier, Linde plc and Air Liquide exemplify pipeline network density strategies. Siemens Energy AG occupies a position representing proton exchange membrane technology specialization for modular systems. These three anchors illustrate divergent pathways: infrastructure control versus equipment supply versus project development aggregation.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Chart Industries |
| Shell plc |
| Siemens Energy AG |
| Cummins Inc. |
| ENGIE SA |
| Plug Power Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Gulf Coast steam methane reforming facilities anchors price floors for gray hydrogen deliveries, with scale concentration among incumbent pipeline operators compressing margins for merchant suppliers while electrolyzer OEMs struggle to close cost gaps against established production economics.
Pricing Analysis
Gray-to-green hydrogen pricing gaps separate incumbent steam methane reforming from emerging electrolytic supply, with IRA production tax credits narrowing but not eliminating premiums for certified renewable-derived molecules. Price differentiation rests on carbon intensity certification and volume commitment scale, with spot procurement facing mounting pressure from long-term offtake contracting that locks in buyer power among integrated chemical producers. Pricing pressure intensifies in merchant hydrogen trading as pipeline network control concentrates bargaining leverage with Linde plc and Air Liquide. Refinery operators show lowest price sensitivity due to hydrocracking process criticality, while fertilizer producers exhibit highest elasticity as ammonia margins tighten.
Supply Chain Analysis
Strait of Hormuz transit exposure for natural gas feedstock deliveries underwrites supply security planning for steam methane reforming operators, though domestic shale sourcing has reduced dependency. Supply concentration centers on the United States, China, and Germany for production capacity, with Australia and Saudi Arabia emerging as liquefied hydrogen export nodes. Raw material dependencies span natural gas molecules, iridium and platinum catalyst metals, and fluoropolymer membrane substrates. Single-source vulnerability concentrates in proton exchange membrane stack assembly, where German and Japanese engineering talent pools constrain workforce scaling. Distribution runs through dedicated pipeline networks on the US Gulf Coast, with tanker-based liquid hydrogen emerging for intercontinental trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial hydrogen constitutes a defensive-moat market where pipeline network density creates regulatory-entrenched switching costs that protect incumbent cash flows while complicating new entrant access.
For Market Incumbents: Shield pipeline corridor control through strategic compression capacity additions along the Texas-Louisiana hydrogen spine, while accelerating electrolyzer partnerships to neutralize green certification threats from modular competitors. Capacity expansion in Rotterdam and Eemshaven secures European Carbon Border Adjustment Mechanism positioning before 2026 compliance deadlines. Certification investment in guarantees of origin schemes preserves premium capture against merchant traders. For New Entrants and Emerging Players: Merchant hydrogen supply gaps in the US Midwest ammonia corridor offer white-space penetration where corn belt fertilizer producers seek electrolytic alternatives to imported gray molecules. Skid-mounted 5-10 MW alkaline units for steel mini-mill captive production represent the most penetrable application, bypassing pipeline infrastructure bottlenecks entirely. Direct reduction iron feedstock contracting provides the strongest go-to-market angle, with 10-15 year offtake structures mirroring incumbent financing requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrolyzer OEMs with proton exchange membrane cost curves and stack durability improvements still ahead, while integrated gas majors face stranded asset risk from emissions compliance tightening. Long-term viability across the 5-10 year window hinges on green hydrogen certification standardization and renewable electricity tariff stability. Acquisition targets with electrolyzer manufacturing scale and North Sea offshore wind offtake agreements warrant priority attention. IRA credit durability and EU CBAM phase-in velocity constitute the critical inflection signals to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Capacity Buildout | North Sea offshore wind integration anchors green hydrogen cost competitiveness for EU steel exports. |
| Backward Integration into Catalyst Supply | Iridium and platinum sourcing control secures PEM stack production against metal price volatility. |
| Long-term Offtake Agreement | 10-15 year purchase commitments unlock project finance for Gulf Coast electrolyzer deployments. |
| Pipeline Network Expansion | Texas-Louisiana corridor density sustains delivery reliability for hydrocracking demand concentration. |
| Green Certification Program | Guarantees of origin harmonization enables premium pricing realization across ammonia and refining applications. |
Research Methodology
Operator-level perspectives from refinery hydrogen procurement managers, electrolyzer OEM technical directors, steelmaker direct reduction iron project leads, and industrial gas distribution channel heads anchored the qualitative base. Primary interview findings combined with secondary validation from EIA energy statistics, IEA hydrogen technology reports, SEC 10-K filings from listed industrial gas majors, and EU ETS carbon price databases. Bottom-up electrolyzer deployment tracking and top-down refinery hydrogen demand modeling enabled triangulation across production method, application, and regional regulatory cluster dimensions.
Sensitivity analysis around renewable electricity tariff trajectories and IRA credit durability assumptions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass production method, application grade tier, end-use industry, distribution channel format, and regional regulatory framework. CAGRs derived from electrolyzer cost curve slopes and offtake contract velocity indicators, with industry-specific inputs including EPA emissions threshold compliance timelines and EU CBAM phase-in schedules.
Forecasts assume regulatory continuity in US IRA credit structures and EU F-Gas Regulation enforcement; material policy shifts would require re-modeling of electrolyzer project economics and green hydrogen premium sustainability. Practitioners should keep alternative scenarios live as CBAM tariff phase-ins and renewable electricity interconnection permitting velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Gas Processing Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Krypton-85 Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Neon Gas Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Asia-Pacific Syngas Market