
 Asia-Pacific Industrial Gases Market | 2026-2036
Asia-Pacific Industrial Gases Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Gases Market Insights
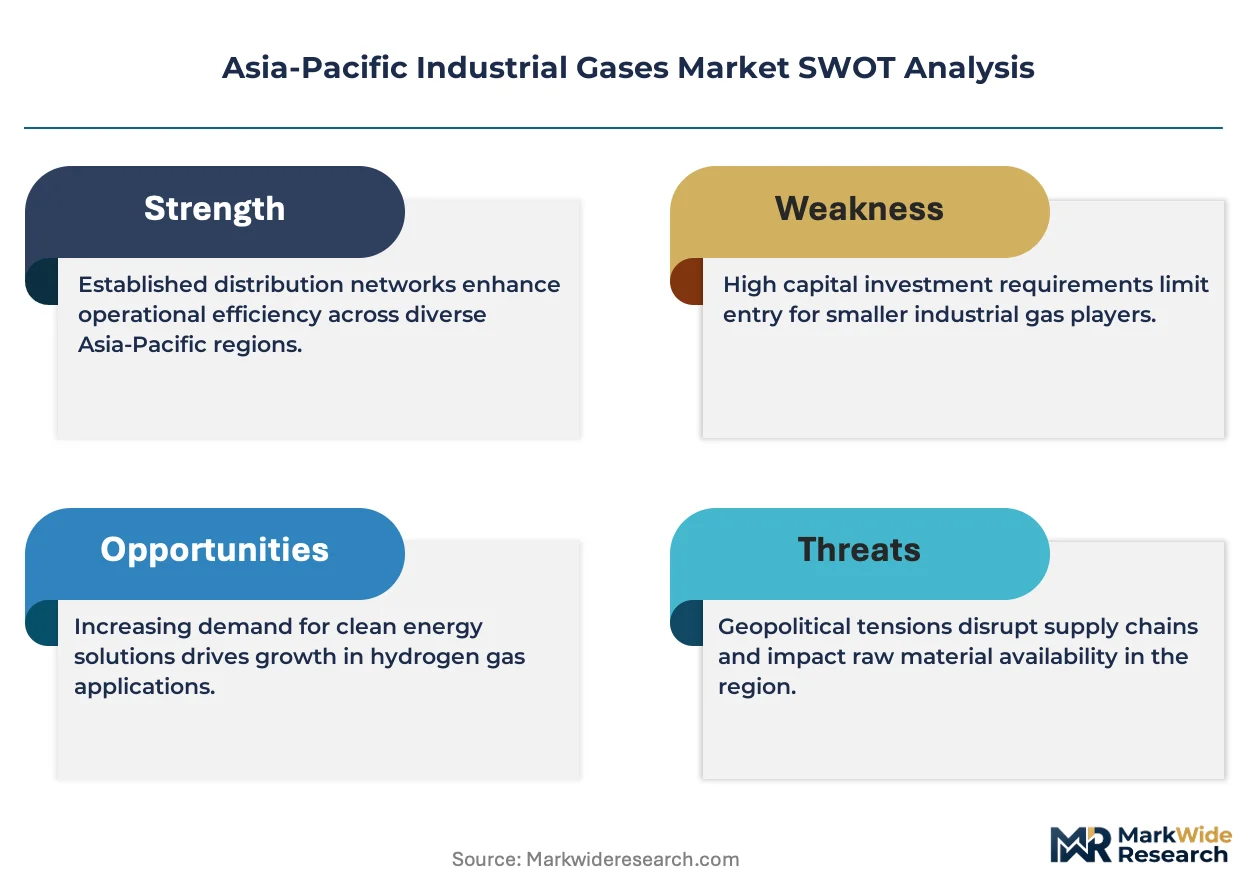
The price-performance gap between premium and commodity tiers is hardening across the Asia-Pacific industrial gases landscape. On-site generation contracts with integrated steel and chemical complexes now command 40-60% longer tenures and stricter purity specifications than standard cylinder supply. Air Liquide anchors this premium segment through captive pipeline networks around major petrochemical hubs. Hangzhou Oxygen Plant Group Co Ltd competes aggressively on cryogenic equipment scale, while Yingde Gases Shanghai dominates merchant liquid bulk distribution across China's interior provinces.
Asia-Pacific industrial gases encompass atmospheric and process gases produced through cryogenic air separation, pressure swing adsorption, or steam methane reforming, typically delivered at purities ranging from industrial-grade (99.5%) to ultra-high-purity (99.999%) depending on application. These gases serve essential functions in oxidation, inerting, hydrogenation, and thermal processing across heavy industry and precision manufacturing. Oxygen leads by volume, with pipeline delivery to integrated steel mills representing the largest single value pool, while hydrogen grows fastest as refiners and ammonia producers in South Korea and Japan decarbonize feedstock. On-site generation captures disproportionate margin relative to cylinder supply due to 15-20 year take-or-pay contracts and embedded equipment financing.
China's MIIT enforces GB standards on industrial gas purity and cylinder safety, while India's CEA mandates energy audits that favor efficient on-site air separation units over energy-intensive liquid distribution. Japan's METI hydrogen roadmap and South Korea's hydrogen economy framework reshape demand composition, redirecting investment toward electrolysis and carbon capture integration. Stakeholders must weigh stranded asset risk in legacy liquid bulk infrastructure against the capital intensity of building pipeline-connected generation at new industrial zones.
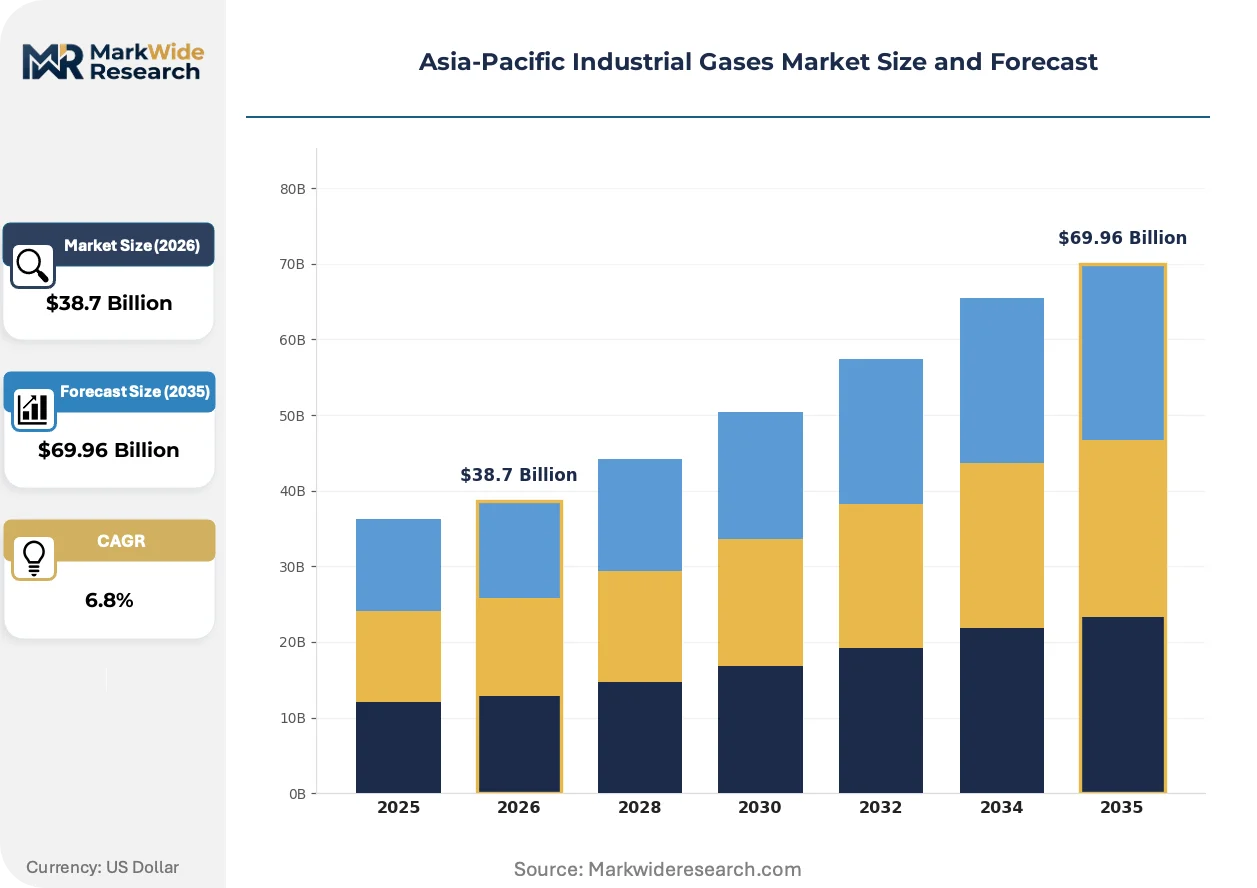
Market Dynamics
China's dual carbon goals and India's PLI scheme for manufacturing are compressing the merchant liquid bulk model while accelerating on-site generation contracts with 15-20 year tenures. Steelmakers and chemical complexes now demand integrated pipeline networks that embed equipment financing and purity guarantees directly into supply agreements.
Growth Catalysts
- On-site generation systems:China's MIIT enforces GB standards that favor energy-efficient air separation units over liquid distribution for integrated steel and petrochemical complexes.
- Hydrogen economy frameworks:South Korea's hydrogen roadmap and Japan's METI hydrogen strategy redirect refiner and ammonia producer investment toward electrolysis and carbon capture integration.
- Industrial corridor concentration:Eastern China's manufacturing belt stretching from Shanghai through Jiangsu to Shandong province anchors pipeline-connected captive supply networks.
Market Restraints
- Electricity cost volatility:Cryogenic air separation and steam methane reforming face margin compression from grid price fluctuations across India's CEA-mandated energy audit jurisdictions.
- Cryogenic equipment scale barriers:Domestic fabrication capacity for large-scale cold boxes concentrates among a limited supplier base in China's eastern provinces.
- Merchant liquid bulk substitution:Cylinder and microbulk delivery faces displacement from pipeline networks in high-volume oxidation and inerting applications.
Strategic Opportunities
- Carbon capture integration:Japan's METI hydrogen roadmap creates white space for electrolysis-coupled industrial gas production at coastal refinery clusters.
- Interior province penetration:China's western industrial zones in Sichuan and Shaanxi remain underpenetrated by pipeline networks relative to coastal density.
- Electrolysis-ASU convergence:Hybrid production systems combining cryogenic separation with green hydrogen generation attract capital from ammonia producers seeking feedstock decarbonization.
Industry Challenges
- Cryogenic welding and commissioning expertise:Pipeline network expansion outpaces qualified technician availability for cold box installation and startup.
- Legacy liquid bulk asset stranding:Tanker fleets and regional fill plants face utilization pressure as take-or-pay contracts shift volume to on-site generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Gases Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen, Nitrogen, Argon, Hydrogen Delivery Mode: Cylinder, Liquid Bulk, Pipeline, On-Site Generation End User: Manufacturing, Healthcare, Food Processing, Chemical Application: Welding, Metal Fabrication, Water Treatment, Laboratory |
| Companies Covered | Taiyo Nippon Sanso Corporation, Hangzhou Oxygen Plant Group Co Ltd, Linde plc, BASF, Iwatani Corporation, Air Liquide, Yingde Gases Shanghai, Goyal MG Gases Pvt Ltd, Air Products and Chemicals Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Gases Market Trends and Innovations
Electrolysis-coupled production architectures and modular pressure swing adsorption units are fragmenting the traditional cryogenic separation monopoly. Buyers now specify purity tiers and carbon intensity metrics alongside volume commitments.
Modular pressure swing adsorption systems are overtaking small-scale cryogenic units for nitrogen and oxygen supply to remote mining and food processing sites. Australian and Indonesian mining operators now specify containerized PSA skids with 95-99.5% purity ranges rather than liquid bulk delivery over poor road infrastructure. This technology is overtaking the merchant model in geographies where tanker transit costs exceed on-site generation capital recovery periods.
India's CEA mandates energy audits for designated consumers that favor efficient on-site air separation units over energy-intensive liquid distribution models. Steel plants above specified consumption thresholds must document specific energy consumption metrics that pipeline-connected generation satisfies more readily than merchant supply. Integrated steel complexes in Odisha and Jharkhand are responding by contracting captive ASU construction with embedded power purchase agreements.
Buyer consolidation among integrated steel and chemical complexes has compressed switching cycles from annual tendering to multi-decade partnership negotiations. Procurement teams now bundle purity certification, equipment financing, and carbon accounting into single-source agreements rather than splitting merchant liquid, cylinder, and on-site decisions. This pattern concentrates contract value in eastern China's industrial corridor where pipeline density enables competitive benchmarking against liquid bulk alternatives.
Asia-Pacific Industrial Gases Market Segmentation
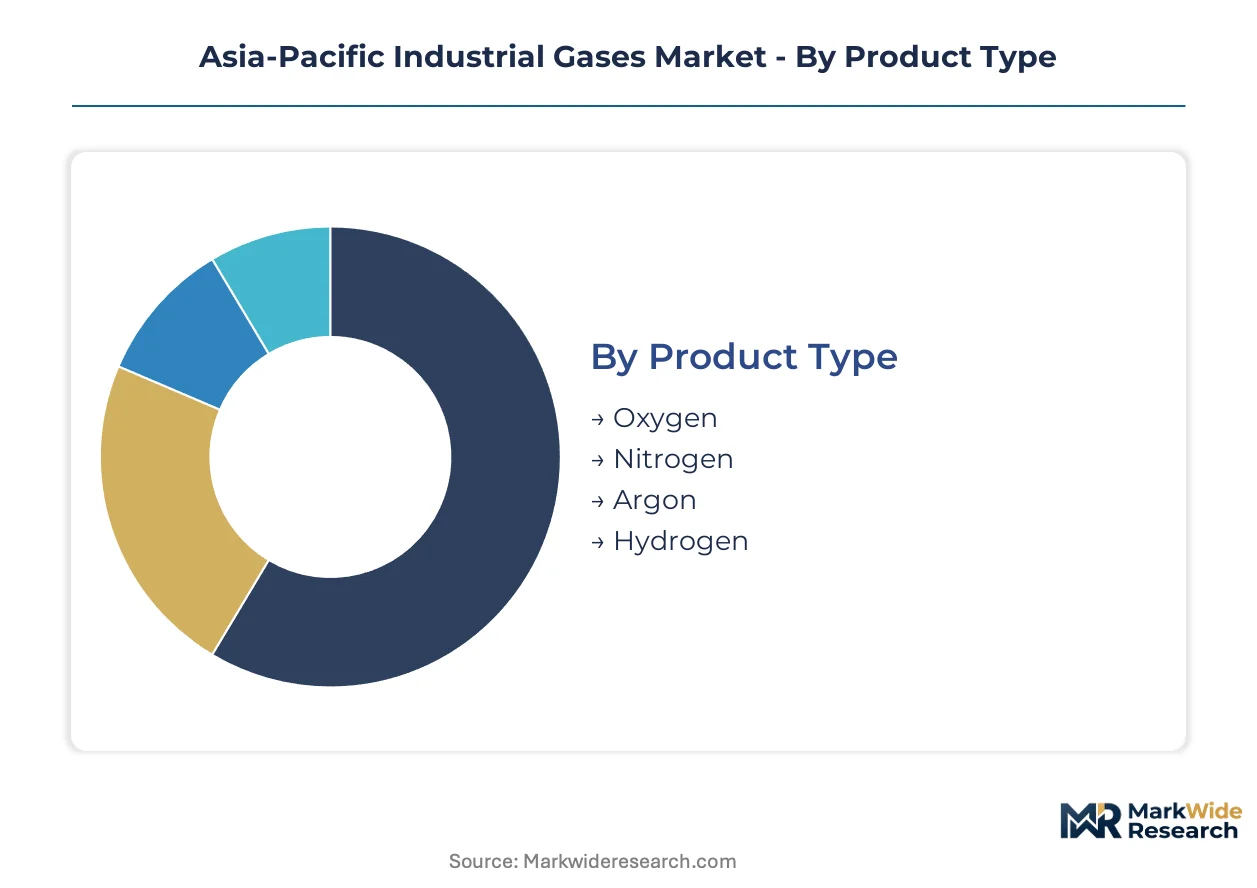
Industrial gas procurement decisions in Asia-Pacific hinge on purity specifications, volume thresholds, and carbon intensity requirements that vary sharply across steelmaking, electronics, and healthcare end-uses. Segmentation reveals how supply mode economics and application-critical specifications reshape contract structures and margin pools.
Product Type:
Purity tiers and oxidation chemistry drive buyer selection between atmospheric and process gases.
- Oxygen:Cryogenic separation yields 99.5% to 99.95% purity grades for basic oxygen furnace steelmaking across eastern China's industrial corridor. Integrated mills in Jiangsu and Shandong provinces anchor pipeline-connected captive supply with 15-20 year take-or-pay structures that embed equipment financing.
- Hydrogen:Steam methane reforming and emerging electrolysis routes supply 99.999% purity for ammonia feedstock and refinery desulfurization. South Korea's hydrogen economy framework and Japan's METI roadmap redirect investment toward electrolysis-coupled production at coastal industrial clusters.
- Nitrogen:Inerting and blanketing applications in electronics and chemical processing favor pressure swing adsorption for volumes below pipeline thresholds.
- Argon:Tungsten inert gas welding and semiconductor crystal growth require 99.999% purity with ultra-low moisture content.
Volume sits with oxygen; growth tilts toward hydrogen.
Delivery Mode:
Capital recovery periods and logistics infrastructure determine the break-even threshold between merchant and captive supply.
- On-Site Generation:Cryogenic air separation units and steam methane reformers installed at steel and petrochemical complexes eliminate liquid distribution costs. China's MIIT energy efficiency standards and India's CEA-mandated energy audits favor these systems for designated consumers above specified consumption thresholds.
- Pipeline:Dense networks around Shanghai, Jiangsu, and Shandong enable multi-customer connectivity with purity guarantees and integrated carbon accounting.
- Liquid Bulk:Tanker delivery serves mid-volume customers in regions where pipeline density remains insufficient for economic connection.
- Cylinder:Packaged gas supply retains relevance for remote mining sites and specialty welding applications across Indonesia and Australia's interior.
Contract value concentrates in on-site generation; merchant liquid bulk faces utilization pressure from pipeline expansion.
End User:
Process intensity and regulatory exposure segment buyers by contract tenure and specification stringency.
- Manufacturing:Steel, automotive, and electronics production consume atmospheric gases for oxidation, inerting, and thermal processing at scales that justify captive generation.
- Chemical:Ammonia, methanol, and petrochemical synthesis require hydrogen and syngas with carbon intensity certification under emerging feedstock decarbonization mandates.
- Healthcare:Medical oxygen and nitrous oxide demand pharmaceutical-grade purity with batch traceability under national pharmaceutical regulator requirements.
- Food Processing:Modified atmosphere packaging and freezing applications use nitrogen and carbon dioxide with food safety certification.
Steel and chemical sectors dominate contract value; healthcare commands premium pricing for certification compliance.
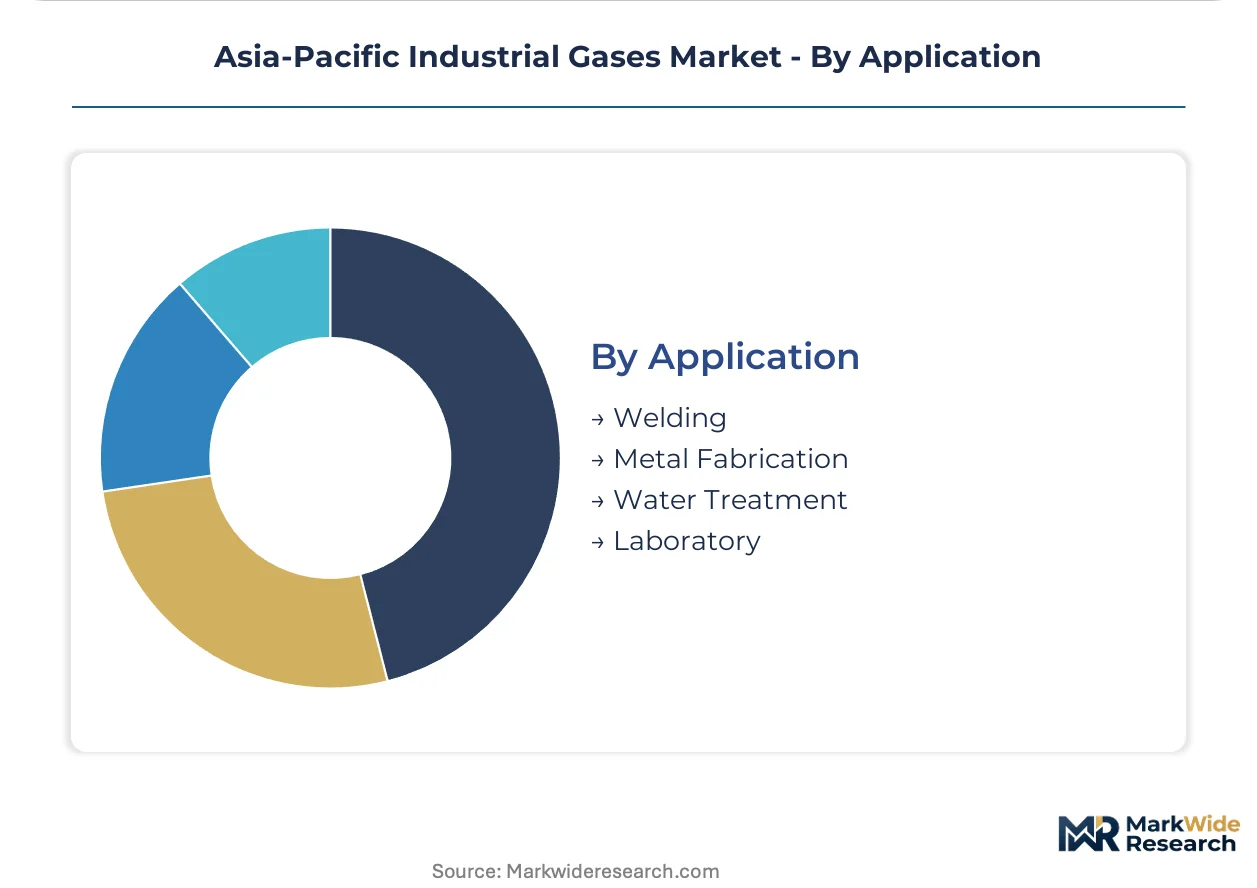
Application:
Precision requirements and safety criticality determine specification tiers and supplier qualification barriers.
- Metal Fabrication:Oxy-fuel cutting and TIG welding drive oxygen and argon consumption across shipbuilding and construction sectors in South Korea and Japan.
- Welding:Shielding gas mixtures for MIG and flux-cored processes specify dew point and particulate limits that cylinder supply satisfies more readily than bulk.
- Water Treatment:Ozone generation and pH control use oxygen in municipal and industrial wastewater facilities.
- Laboratory:Analytical instruments and research applications require ultra-high-purity grades with documented impurity profiles.
Metal fabrication anchors volume; laboratory applications sustain the steepest purity premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Jiangsu-Shandong industrial corridor anchors pipeline-connected industrial gas infrastructure across eastern China, while India's Odisha-Jharkhand steel belt and South Korea's Ulsan petrochemical cluster drive divergent contract structures.
China
Integrated steel mills in Jiangsu and Shandong provinces consume bulk oxygen through 15-20 year take-or-pay contracts that embed equipment financing. MIIT enforces GB standards on energy efficiency that favor on-site air separation units over liquid distribution for designated consumers above specified thresholds. The Yangtze River Delta manufacturing belt concentrates pipeline density, with captive generation displacing merchant supply at new petrochemical complexes.
India
Steel plants in Odisha and Jharkhand above specified consumption thresholds drive captive ASU construction with embedded power purchase agreements. CEA-mandated energy audits for designated consumers document specific energy consumption metrics that pipeline-connected generation satisfies more readily than merchant liquid bulk. The Delhi-Mumbai Industrial Corridor anchors new industrial zones where on-site generation contracts are displacing cylinder and microbulk delivery.
Japan
Coastal refinery clusters in Chiba and Yokkaichi redirect investment toward electrolysis-coupled hydrogen production under METI's hydrogen roadmap. Ammonia producers and refiners specify carbon intensity certification for feedstock hydrogen, reshaping procurement toward electrolysis and carbon capture integration. The Kanto industrial zone concentrates demand for ultra-high-purity gases in semiconductor and electronics manufacturing.
South Korea
Ulsan petrochemical complexes and steelworks drive hydrogen demand for refinery desulfurization and ammonia feedstock under the national hydrogen economy framework. The government's hydrogen roadmap redirects capital toward electrolysis-coupled production at coastal industrial clusters. Busan-Ulsan manufacturing belt anchors pipeline-connected supply networks with integrated carbon accounting requirements.
Australia
Remote mining operations in Western Australia and Queensland specify containerized PSA skids with 95-99.5% purity ranges rather than liquid bulk delivery over poor road infrastructure. Mining operators in the Pilbara and Bowen Basin favor on-site generation where tanker transit costs exceed capital recovery periods. The country's interior geographies sustain cylinder supply for specialty welding applications where pipeline density remains insufficient.
Asia-Pacific Industrial Gases Market Competitive Landscape
Premium-margin players sit above commodity-margin players across contract tenure and purity specification dimensions, with on-site generation specialists commanding 40-60% longer tenures than standard cylinder suppliers. The market structures around three archetypes: international majors with captive pipeline networks, regional cryogenic equipment fabricators, and domestic liquid bulk distributors. Consolidation pressure runs through M&A activity targeting stranded liquid bulk assets and strategic partnerships for electrolysis-coupled production.
Within the international major tier, Air Liquide and Linde plc exemplify pipeline-connected captive supply archetypes with integrated equipment financing structures. Hangzhou Oxygen Plant Group Co Ltd represents the regional equipment fabricator position, competing on cryogenic scale for domestic project execution. Yingde Gases Shanghai occupies the merchant liquid bulk distribution vector across China's interior provinces where pipeline density remains insufficient for economic connection.
| Leading Market Players |
|---|
| Taiyo Nippon Sanso Corporation |
| Hangzhou Oxygen Plant Group Co Ltd |
| Linde plc |
| BASF |
| Iwatani Corporation |
| Air Liquide |
| Yingde Gases Shanghai |
| Goyal MG Gases Pvt Ltd |
| Air Products and Chemicals Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive pipeline networks around eastern China's industrial corridor anchor both supply position and pricing power for integrated industrial gas producers. These 15-20 year take-or-pay contracts embed equipment financing and purity guarantees that commodity liquid bulk distributors cannot match, compressing margin pools in standard cylinder supply while concentrating value in on-site generation partnerships.
Pricing Analysis
Throughput-linked pricing models dominate long-term supply agreements with integrated steel and petrochemical complexes, where buyers pay for guaranteed uptime rather than volume alone. Price differentiation rests on purity certification tiers and carbon intensity metrics demanded under Japan's METI hydrogen roadmap and South Korea's hydrogen economy framework. Cost compression in merchant liquid bulk is intensifying because pipeline networks displace tanker delivery in high-volume oxidation applications. Steelmakers in Jiangsu and Shandong provinces show lowest price sensitivity due to process-critical purity requirements, while remote mining operators in Australia's interior exhibit highest sensitivity to logistics-inflated cylinder costs.
Supply Chain Analysis
Direct-to-mill pipeline channels handle integrated steel complex demand across China's Yangtze River Delta, while merchant liquid bulk serves mid-volume chemical processors in regions where pipeline density remains insufficient. Supply concentration centers on China, South Korea, and Japan for cryogenic air separation equipment and hydrogen production infrastructure. Raw material dependencies include specialized aluminum alloys for cold box fabrication, rare earth catalysts for hydrogen purification, and high-grade stainless steel for pipeline construction. Single-source vulnerability concentrates in large-scale cryogenic welding and commissioning expertise, where qualified technician availability lags network expansion. Distribution runs through three-tier structures: captive pipelines for designated consumers, regional liquid bulk terminals for mid-scale buyers, and cylinder depots for remote specialty applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's MIIT energy efficiency standards and India's CEA-mandated energy audits erect barrier-to-entry moats for players with certified on-site generation capabilities.
For Market Incumbents: Lock in multi-decade pipeline contracts with integrated steel and ammonia complexes before electrolysis-coupled production reshapes hydrogen procurement. Prioritize carbon capture integration at coastal refinery clusters to preempt feedstock decarbonization mandates from Japan's METI and South Korea's hydrogen framework. Defend against modular PSA substitution in remote mining by embedding power purchase agreements that match containerized unit economics. For New Entrants and Emerging Players: Remote mining operators in Western Australia and Queensland's Bowen Basin represent the most penetrable buyer archetype, where poor road infrastructure and tanker transit costs exceed on-site generation capital recovery periods. Target containerized PSA skids with 95-99.5% purity specifications for nitrogen and oxygen supply to Indonesian nickel processing sites. Enter through equipment financing partnerships that mimic incumbent take-or-pay structures without requiring captive pipeline investment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by international majors seeking stranded liquid bulk asset repositioning. Long-term viability favors electrolysis-coupled production specialists with coastal industrial cluster access and carbon accounting integration. Watch for CEA audit threshold expansions in India and MIIT efficiency standard tightening in China as inflection indicators for accelerated on-site generation adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolysis-Coupled Production Buildout | Japan's METI hydrogen roadmap redirects refiner investment toward coastal electrolysis clusters with carbon capture. |
| Backward Integration into Cryogenic Equipment | Hangzhou Oxygen Plant Group's domestic cold box fabrication reduces import dependency for Chinese project execution. |
| Long-Term Pipeline Supply Agreement | Air Liquide's 15-20 year take-or-pay contracts with Jiangsu steel mills embed financing and purity guarantees. |
| Modular PSA Geographic Expansion | Australian mining operators specify containerized nitrogen skids for Pilbara sites where tanker costs dominate. |
| Green Hydrogen Certification Program | South Korea's hydrogen economy framework mandates carbon intensity accounting for ammonia feedstock procurement. |
Research Methodology
Trade flow databases, national energy regulator filings, and industrial gas association statistics formed the secondary backbone for demand quantification. Primary interviews with cryogenic equipment procurement managers at integrated steel complexes, pipeline network operations directors, and CEA-designated consumer energy auditors combined with customs data on air separation unit imports and MIIT efficiency compliance disclosures. Bottom-up project pipeline tracking and top-down sectoral consumption estimates were triangulated against disclosed contract tenures and capacity announcements.
Historical trendline analysis of on-site generation adoption rates, pipeline network expansion patterns, and merchant liquid bulk displacement informed the projection framework. Segmentation dimensions modeled include product purity tier, delivery mode economics, end-use process intensity, and regional regulatory cluster. CAGRs were derived from installed capacity buildout schedules, consumption threshold expansions under CEA and MIIT jurisdictions, and hydrogen economy framework investment commitments. Industry-specific inputs incorporated electrolysis cost curves and carbon capture integration timelines at coastal refinery clusters.
Revisions become necessary when electricity grid price volatility exceeds historical bands or when cryogenic equipment fabrication capacity constraints delay project commissioning. Practitioners should monitor CEA audit threshold announcements, MIIT efficiency standard updates, and hydrogen economy framework subsidy modifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Argon Gas Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Neon Gas Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
Europe Syngas Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Krypton-85 Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
South-East Asia (SEA) Syngas Market