
 Gas and Liquid Argon Market | 2026-2036
Gas and Liquid Argon Market Size, Share, and Industry Trends Forecast 2026-2036
Gas and Liquid Argon Market Analysis
Aftermarket service revenue for cryogenic storage and distribution systems is rewriting margin economics across the industrial gas value chain. Linde plc leverages its global maintenance network to sustain recurring income from long-term argon supply contracts. Air Liquide anchors its position through backward integration into air separation unit technology, while Messer SE & Co. KGaA competes on regional density in European manufacturing corridors.
Gas and liquid argon constitute inert atmospheric gases produced via fractional distillation of liquid air, yielding purity grades from standard industrial to ultra-high purity for semiconductor applications where oxygen content must remain below one part per billion. The product serves primarily as a shielding medium in welding and as a process gas in silicon crystal growth and plasma etching. Liquid argon commands premium positioning due to cryogenic handling requirements and density advantages in bulk transport, whereas argon mixtures dominate welding applications where cost-performance balance determines specification. Electronics manufacturing represents the fastest-expanding application segment as foundry capacity additions in East Asia absorb contracted volumes years ahead of delivery.
ISO 20486 governs leak detection standards for cryogenic argon systems, while OSHA regulates workplace exposure limits for inert gas asphyxiation hazards in confined industrial environments. EPA emissions frameworks for air separation facilities increasingly shape capital allocation toward energy-efficient liquefaction trains. Stakeholders must monitor how semiconductor fabrication subsidies in multiple jurisdictions redirect argon offtake commitments and strain existing supply agreements.
Market Dynamics
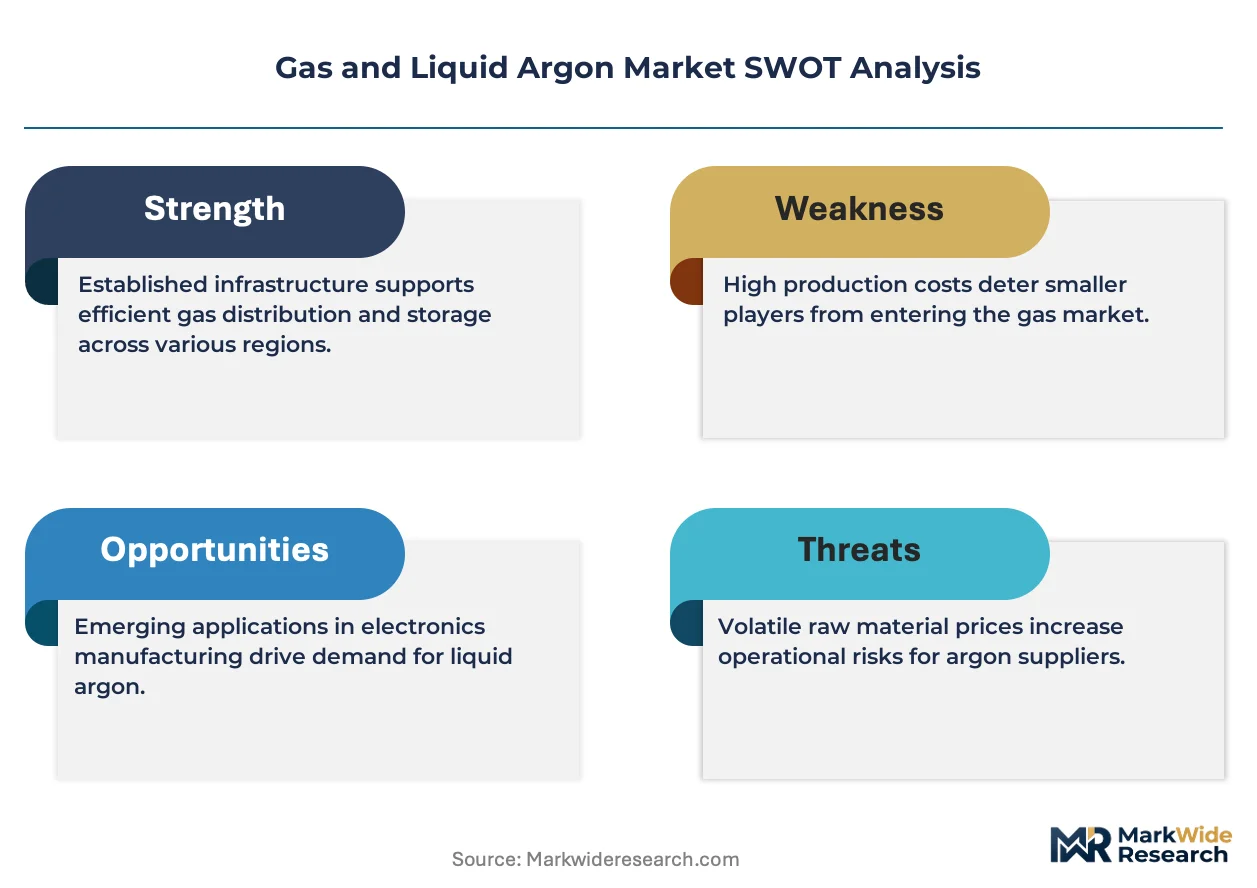
Semiconductor foundry expansion in East Asia is compressing argon supply timelines and forcing air separation operators to front-load capacity investments ahead of contracted delivery windows.
Growth Catalysts
- MEE emissions enforcement:China's Ministry of Ecology and Environment is tightening industrial gas facility standards, redirecting capital toward cryogenic recovery systems that improve argon yield rates from air separation units.
- Plasma etching intensity:Advanced node semiconductor fabrication below 7nm requires higher argon volumes per wafer pass, pulling incremental supply into electronics manufacturing corridors.
- ISO 20486 leak detection mandates:Cryogenic system certification requirements are standardizing maintenance protocols and extending equipment replacement cycles across bulk argon distribution networks.
Market Restraints
- Electricity cost volatility:Air separation unit economics depend on grid power pricing, with liquefaction trains consuming 0.8-1.2 kWh per cubic meter of argon produced.
- Supply concentration in East Asia:Over 60% of ultra-high purity argon capacity sits within 500 kilometers of Taipei, Kaohsiung, and Seoul, creating geographic vulnerability to regional disruptions.
- Helium substitution in select welding:Argon-helium mixtures face cost-driven displacement in automated welding applications where heat transfer efficiency outweighs inert gas purity requirements.
Strategic Opportunities
- Indian semiconductor subsidies:The country's PLI scheme for electronics manufacturing is attracting foundry investments that will require captive argon supply agreements by 2028.
- Carbon capture convergence:Cryogenic argon handling expertise is transferring to CO2 liquefaction infrastructure, opening shared equipment platforms across industrial gas operators.
- On-site generation contracts:Large-volume consumers in steel and solar manufacturing are adopting membrane and pressure swing adsorption systems to reduce liquid argon delivery dependence.
Industry Challenges
- Cryogenic technician scarcity:Specialized certification for liquid argon handling and storage system maintenance is constraining maintenance network expansion.
- Ultra-high purity validation timelines:Semiconductor-grade argon qualification requires 12-18 months of continuous sampling before foundry acceptance, locking working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas and Liquid Argon Market |
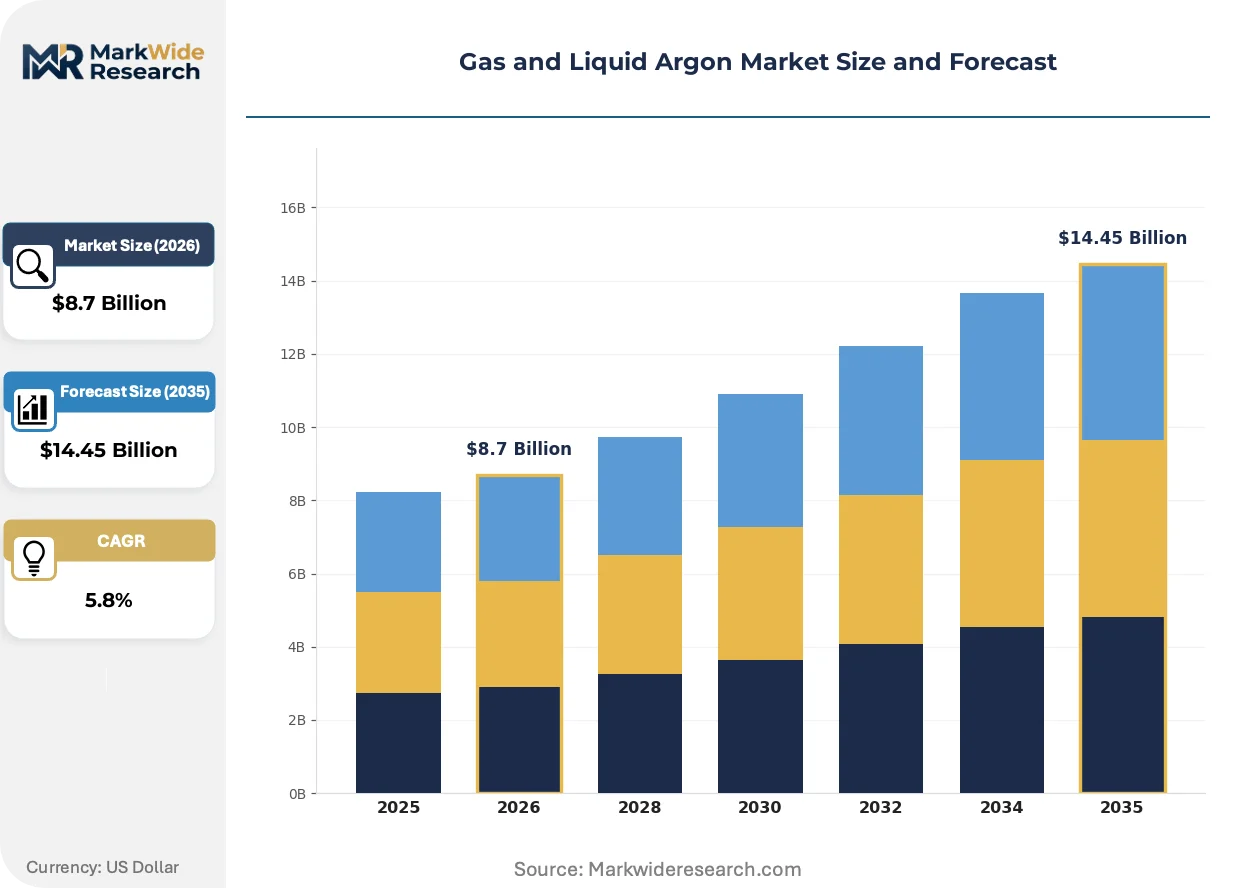
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Argon, Liquid Argon, Argon Mixtures, Cryogenic Argon Application: Welding, Metal Fabrication, Electronics Manufacturing, Healthcare End User: Manufacturing, Medical Facilities, Research Laboratories, Aerospace Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Supply |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Messer SE & Co. KGaA, Praxair Inc., Nippon Sanso Holdings Corporation, Iwatani Corporation, BASF SE, Air Water Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas and Liquid Argon Market Emerging Trajectories
Digital twin technology is penetrating cryogenic asset management, compressing maintenance response times and enabling predictive intervention before purity degradation impacts semiconductor yield.
Membrane separation technology is virtualizing portions of the traditional cryogenic distillation value chain. Modular nitrogen-argon separation units are scaling to 500 ton-per-day outputs, allowing mid-volume electronics manufacturers to site-produce standard purity grades. This distributed architecture is compressing the addressable market for liquid argon trucking in industrial corridors.
EPA emissions frameworks for air separation facilities are tightening monitoring requirements for fluorinated greenhouse gases used in refrigeration loops. Facility operators must retrofit leak detection infrastructure or face permit restrictions. The semiconductor manufacturing segment is responding by specifying low-global-warming-potential refrigerants in new cryogenic equipment procurement.
Long-term take-or-pay contracts are fragmenting into shorter-duration agreements with embedded volume flexibility clauses. Electronics foundries are unbundling base-load argon commitments from spot-market top-up volumes, transferring price volatility risk to air separation operators. This pattern is most visible in Taiwanese and South Korean semiconductor clusters where multi-year supply agreements once dominated procurement.
Gas and Liquid Argon Market Segmentation
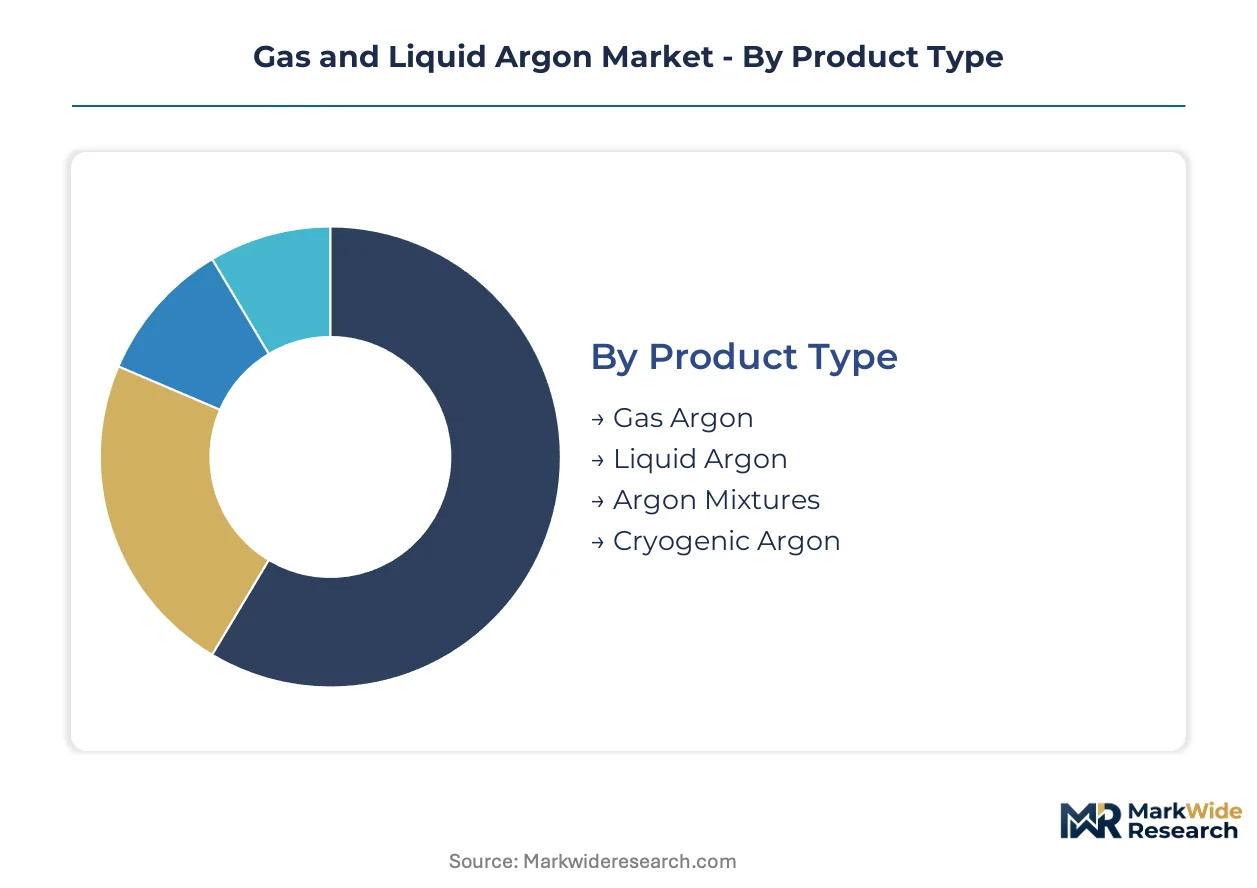
Argon segmentation reveals divergent margin profiles across physical states and purity grades. Cryogenic handling requirements create aftermarket revenue streams that vary dramatically by product category, while semiconductor-grade specifications command qualification timelines that reshape working capital deployment.
Product Type:
Aftermarket service intensity peaks with cryogenic formats where maintenance contracts extend across decades of asset life. Gas and liquid variants generate divergent recurring revenue profiles based on storage infrastructure requirements.
- Liquid Argon:Cryogenic liquid at -186°C enables dense bulk transport and long-duration storage in vacuum-insulated vessels. Semiconductor foundries in Taiwan and South Korea specify liquid delivery for plasma etching operations where purity thresholds demand sub-ppb oxygen content.
- Gas Argon:Compressed gas in high-pressure cylinders serves distributed welding operations and laboratory applications. Manufacturing corridors across Germany and the US Midwest absorb cylinder gas volumes where pipeline infrastructure remains uneconomical.
- Argon Mixtures:Blends with helium or carbon dioxide optimize arc stability and heat transfer in automated welding. Cost-driven displacement pressures emerge where helium substitution improves deposition rates in thick-section joining.
- Cryogenic Argon:Ultra-high purity grades require specialized liquefaction trains and dedicated distribution assets. EPA emissions frameworks for air separation facilities increasingly shape capital allocation toward energy-efficient production.
Liquid argon holds the largest share; momentum sits with cryogenic argon as semiconductor node advancement intensifies purity requirements.
Application:
Cost tier differentiation separates commodity welding consumption from premium electronics-grade volumes. Plasma process intensity creates divergent pricing power across application segments.
- Electronics Manufacturing:Silicon crystal growth and plasma etching consume ultra-high purity argon where oxygen contamination destroys wafer yield. Advanced node fabrication below 7nm requires higher argon volumes per wafer pass.
- Welding:Shielding gas applications in arc welding represent volume-dominant consumption with price-sensitive procurement. Automated welding systems in automotive manufacturing specify argon-helium mixtures for heat transfer optimization.
- Metal Fabrication:Structural steel and shipbuilding operations deploy argon for TIG and MIG welding of alloy components. ISO 20486 leak detection mandates standardize maintenance protocols across bulk distribution networks.
- Healthcare:Cryopreservation and medical gas applications require pharmaceutical-grade handling with FDA or EMA compliance documentation. Tissue storage and cryosurgery procedures specify liquid argon for controlled thermal destruction.
Welding holds the largest share; electronics manufacturing is climbing the fastest as foundry capacity expansion accelerates.
End User:
Customer type determines contract structure, with captive on-site generation displacing merchant supply in volume-intensive segments. Procurement patterns diverge between spot-market flexibility and long-term take-or-pay commitments.
- Manufacturing:Steel production, automotive assembly, and solar panel fabrication absorb merchant liquid argon through bulk delivery contracts. Large-volume consumers are adopting membrane and pressure swing adsorption systems to reduce delivery dependence.
- Medical Facilities:Hospitals and cryobiology centers require continuous supply assurance with backup redundancy for patient-critical applications. Regulatory compliance with national pharmaceutical regulators governs storage and handling protocols.
- Research Laboratories:Academic and government research facilities consume high-purity grades for spectroscopy and particle detection. India's semiconductor subsidies are attracting foundry investments that will require captive supply agreements.
- Aerospace:Propulsion testing and satellite thermal management specify cryogenic argon for inert purge and cooling applications. Launch facility operations in Florida and French Guiana coordinate supply logistics around mission windows.
Manufacturing holds the largest share; research laboratories are gaining share fastest as public R&D funding expands.
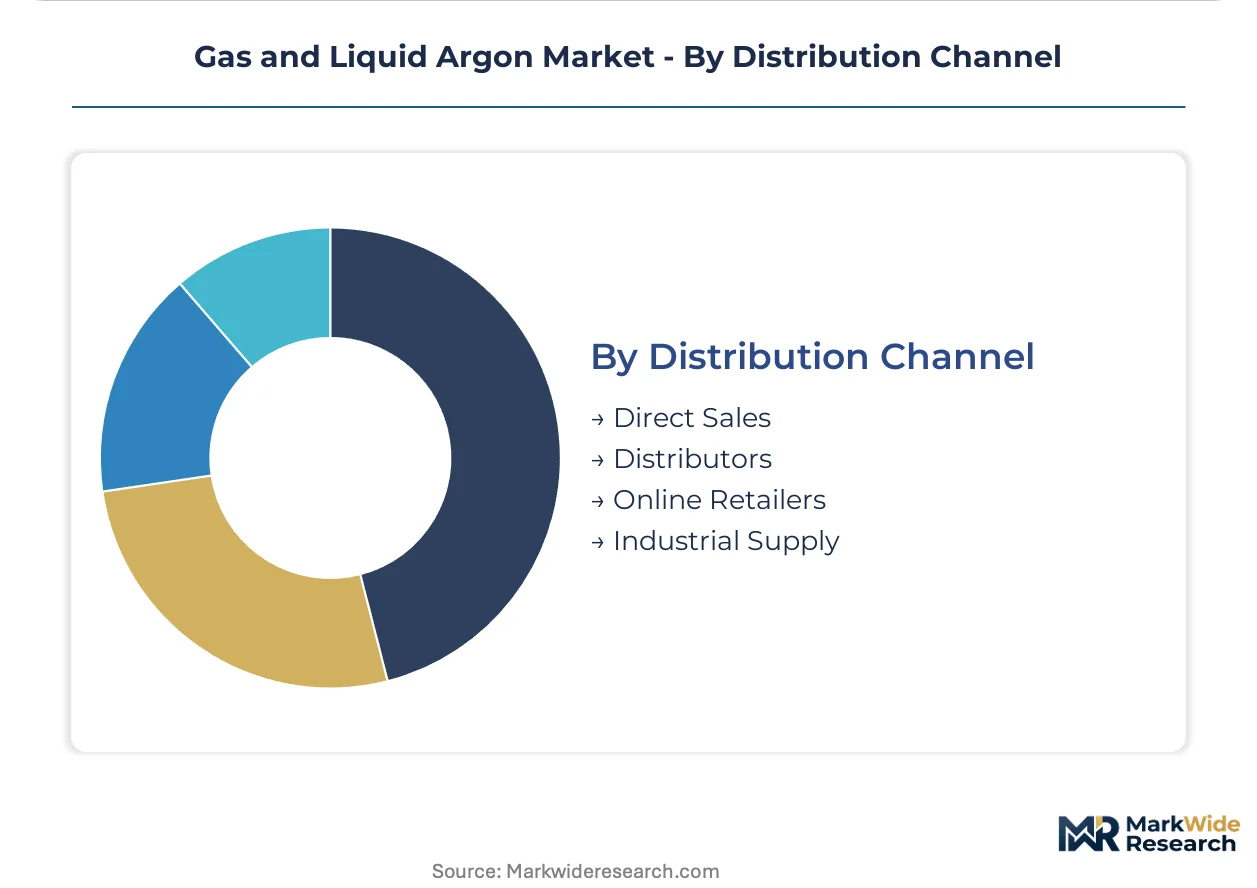
Distribution Channel:
Supply concentration dictates channel economics, with direct sales dominating high-volume corridors and distributors serving fragmented demand. Geographic density determines whether bulk delivery or packaged gas prevails.
- Direct Sales:Long-term contracts with on-site storage and pipeline delivery serve semiconductor foundries and steel mills. Linde plc leverages its global maintenance network to sustain recurring income from these arrangements.
- Distributors:Regional gas distributors aggregate demand from small and mid-volume consumers across industrial clusters. Messer SE & Co. KGaA competes on regional density in European manufacturing corridors.
- Industrial Supply:Integrated industrial gas merchants bundle argon with oxygen, nitrogen, and acetylene for fabrication customers. Air Liquide anchors its position through backward integration into air separation unit technology.
- Online Retailers:E-commerce platforms serve hobbyist welders and small repair shops with cylinder exchange and disposable container formats. Digital procurement is compressing order-to-delivery timelines for standard purity grades.
Direct sales holds the largest share; industrial supply is expanding most quickly as bundled gas procurement consolidates vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argon buyers in welding and metal fabrication remain acutely price-sensitive, while semiconductor foundries absorb substantial premiums for ultra-high purity grades. This elasticity divergence is reshaping regional investment patterns. Supply security concerns now override cost optimization in electronics manufacturing corridors.
China
Steel production and solar panel manufacturing absorb bulk liquid argon volumes through merchant delivery contracts. MEE emissions enforcement is redirecting capital toward cryogenic recovery systems that improve yield rates from air separation units. Yangtze River Delta industrial clusters around Shanghai and Suzhou concentrate foundry demand for plasma etching gases.
United States
Automotive welding operations and aerospace propulsion testing sustain cylinder gas and cryogenic consumption. EPA emissions frameworks for air separation facilities shape capital allocation toward energy-efficient liquefaction trains. Gulf Coast petrochemical corridors and Florida launch facilities coordinate supply logistics around mission-critical delivery windows.
South Korea
Memory and logic chip fabrication drives ultra-high purity argon absorption at advanced nodes below 7nm. MFDS pharmaceutical-grade handling standards govern medical gas applications in Seoul hospital networks. Pyeongtaek and Hwaseong semiconductor clusters strain existing supply agreements with multi-year contracted volumes.
Germany
Automated welding systems in automotive assembly and precision engineering deploy argon-helium mixtures for heat transfer optimization. REACH compliance and EU F-Gas Regulation mandate low-global-warming-potential refrigerants in new cryogenic equipment procurement. Bavarian and Baden-Württemberg manufacturing corridors anchor Messer SE & Co. KGaA regional density strategies.
India
Steel mills and emerging electronics manufacturing absorb merchant supply while PLI scheme subsidies attract foundry investments requiring captive agreements by 2028. BIS standards govern industrial gas purity specifications across Maharashtra and Gujarat industrial zones. Karnataka and Tamil Nadu semiconductor clusters are negotiating long-term take-or-pay contracts ahead of fab construction completion.
Gas and Liquid Argon Market Vendor Landscape
Capability concentration sits with cryogenic technology specialists; scale advantage sits with diversified industrial gas conglomerates. The market structure exhibits tiered consolidation where global operators control air separation infrastructure while regional distributors serve fragmented welding demand. Three archetypes dominate: integrated gas majors with backward integration into liquefaction technology, regional density specialists with maintenance network advantages, and captive on-site generation providers for steel and solar manufacturers. Competitive moves center on long-term contract restructuring with volume flexibility clauses and geographic expansion through distributor acquisitions.
Within the integrated gas major tier, Linde plc and Air Liquide exemplify divergent strategic positioning. Linde plc leverages global maintenance networks to sustain recurring aftermarket revenue from cryogenic storage systems. Air Liquide anchors market presence through in-house air separation unit technology and bundled gas procurement relationships. Messer SE & Co. KGaA occupies a position among regional density specialists, competing through concentrated service presence in European manufacturing corridors rather than global scale.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Messer SE & Co. KGaA |
| Praxair Inc. |
| Nippon Sanso Holdings Corporation |
| Iwatani Corporation |
| BASF SE |
| Air Water Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese industrial gas corridors is compressing spot-market argon premiums and forcing air separation operators toward long-term service contracts that lock in aftermarket revenue streams. Utilization rates below 75% in Yangtze River Delta production hubs are eroding merchant liquid pricing power while simultaneously accelerating bundled maintenance offerings that protect margins through cryogenic storage system lifecycles.
Pricing Analysis
Aftermarket service contracts spanning cryogenic storage infrastructure now generate lifetime value multiples exceeding initial equipment sales. Three-tier pricing structure across ultra-high purity semiconductor grades, standard industrial liquid, and packaged cylinder gas separates foundry procurement from welding shop spot purchases. Cost compression in merchant liquid tiers is intensifying because membrane separation technology enables on-site generation for mid-volume steel and solar manufacturers. Electronics foundries exhibit minimal price sensitivity due to wafer yield destruction from oxygen contamination, while automotive welding operations negotiate aggressively on argon-helium mixture volumes.
Supply Chain Analysis
Extended payment terms from semiconductor foundries are straining working capital for regional distributors serving fragmented welding demand. Production gravity centers on China, South Korea, and Taiwan, with over 60% of ultra-high purity capacity concentrated within 500 kilometers of Taipei and Seoul. Feedstock for air separation units draws from grid electricity, atmospheric air intake, and specialized refrigeration loops using fluorinated gases. Single-source vulnerability from geographic concentration in East Asian semiconductor clusters exposes supply chains to regional disruption risks. Distribution runs through direct pipeline and bulk liquid delivery for high-volume foundries, with cylinder gas networks serving dispersed fabrication shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic maintenance service contracts are expanding faster than air separation unit hardware sales, transforming capital equipment vendors into recurring revenue platforms. This service-attach opportunity favors operators with dense technician networks and long-duration customer relationships.
For Market Incumbents: Build technician certification moats through proprietary training programs for ISO 20486 leak detection compliance. Anchor position through backward integration into membrane separation technology that displaces merchant liquid demand. Defend against on-site generation entrants by embedding predictive maintenance digital twins into long-term supply agreements. Prioritize capacity addition in Indian semiconductor corridors ahead of PLI scheme foundry commissioning. For New Entrants and Emerging Players: Mid-volume solar panel and specialty steel manufacturers in Southeast Asia represent the most penetrable entry point for modular pressure swing adsorption systems. Distributed electronics manufacturing in Vietnam and Malaysia offers white-space for standard purity argon production bypassing cryogenic infrastructure. Pursue joint venture structures with industrial park developers to secure captive offtake before facility construction. For Investors and Strategic Acquirers: Capital is best deployed toward regional density specialists with concentrated maintenance networks in European manufacturing corridors. Long-term viability hinges on contract structures that embed volume flexibility clauses transferring price risk to operators. Target acquisition archetype: cryogenic service providers with semiconductor-grade qualification capabilities. Watch for inflection when foundry capacity utilization crosses thresholds that trigger spot-market premium volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Recovery System Deployment | MEE emissions enforcement in China redirects capital toward yield-improving air separation retrofits. |
| Long-term Supply Agreement Restructuring | Electronics foundries unbundle base-load commitments from spot top-up volumes in Taiwanese clusters. |
| Membrane Separation Technology Integration | Modular nitrogen-argon units compress addressable market for liquid argon trucking corridors. |
| Digital Twin Asset Management | Predictive intervention capabilities compress maintenance response times for semiconductor yield protection. |
| Regional Density Expansion | Maintenance network concentration in Bavarian manufacturing corridors anchors Messer SE positioning. |
Methodological Framework
The analysis maps cryogenic liquid, compressed gas, argon mixtures, and ultra-high purity grades, each validated through air separation unit operators, semiconductor foundry procurement directors, welding equipment distributors, and cryogenic storage maintenance technicians. Primary interviews with plant managers at steel mills and solar panel manufacturers combined with secondary validation from SEC filings of listed industrial gas majors, EPA emissions framework documentation, and ISO 20486 certification records. Bottom-up capacity installation tracking and top-down end-use consumption estimates were triangulated against customs trade data for cryogenic equipment imports.
Assumptions held fixed include regulatory enforcement timelines for MEE emissions standards and continuation of semiconductor fabrication subsidies across analyzed jurisdictions. Segmentation dimensions modeled encompass physical state, purity grade, application intensity, and regional production hub clustering. CAGRs were derived through regression analysis of historical capacity additions against foundry construction pipelines. Forecast inputs incorporated electricity pricing volatility scenarios and membrane separation technology diffusion curves.
Macroeconomic conditions sit as an overlay; deviation in grid power pricing, semiconductor capital expenditure cycles, or trade policy restricting cryogenic equipment would shift the trajectory. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Syngas Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Argon Gas Market