
 Industrial Gas Phase Filtration System Market | 2026-2036
Industrial Gas Phase Filtration System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gas Phase Filtration System Market Foresight
Remote monitoring and predictive maintenance subscriptions is broadening the commercial scope of gas phase filtration contracts beyond hardware-only sales. Freudenberg leverages its materials science heritage to sustain captive supply of proprietary activated carbon media. Camfil AB anchors Nordic aftermarket service density through long-term filter replacement agreements with pulp and paper mills. Donaldson Company competes on manufacturing scale across North American power generation installations.
An industrial gas phase filtration system removes molecular contaminants from process and ventilation air streams using adsorptive media, catalytic substrates, or electrostatic mechanisms, typically achieving removal efficiencies from 95% to 99.97% depending on pore structure and dwell time. These systems protect sensitive manufacturing environments, extend catalyst life in petrochemical operations, and ensure worker safety in facilities handling corrosive or toxic gases. Activated carbon filters occupy the largest installed base due to decades of proven performance in solvent recovery and odor control applications, though membrane separation is gaining share in pharmaceutical applications where zero-contamination assurance commands premium pricing. HEPA filters retain dominant positioning in cleanroom and nuclear ventilation architectures where particulate and gas phase threats coexist. Chemical filters concentrate margin pools in semiconductor fabrication, where ppb-level contaminant removal justifies specialized media formulations and short replacement cycles.
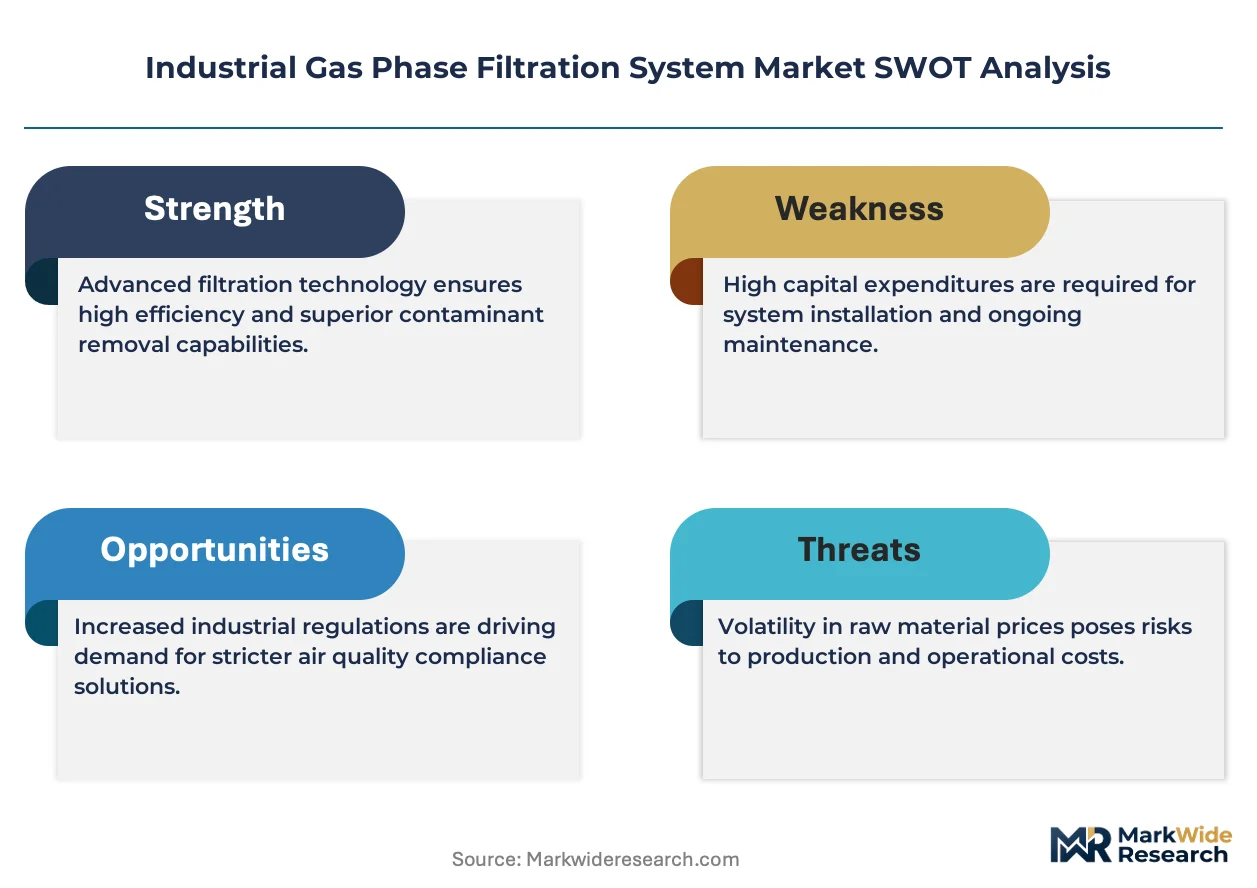
EPA National Emission Standards for Hazardous Air Pollutants and OSHA Permissible Exposure Limits shape product specifications and replacement frequency across United States industrial facilities, while REACH registration requirements in Europe constrain media chemistry options for suppliers serving EU manufacturing sites. ISO 16890 test standards for filter classification are displacing older EN 779 protocols, forcing recalibration of performance claims across supplier portfolios. Stakeholders must weigh capital intensity against total lifecycle service revenue when structuring contract terms for multi-site industrial accounts.
Market Dynamics
Remote monitoring subscriptions are restructuring contract economics from hardware-centric sales toward recurring service revenue, compressing upfront capital requirements while extending customer lifetime value through predictive maintenance platforms.
Growth Catalysts
- EPA NESHAP mandates:Tightening hazardous air pollutant limits force petrochemical facilities in Texas and Louisiana to accelerate filter replacement cycles and upgrade to higher-efficiency media arrays.
- Semiconductor fabrication:Taiwan and South Korea fabs are deploying specialized chemical filters for ppb-level contaminant removal as process nodes shrink below 3nm, creating premium demand for proprietary media formulations.
- Activated carbon regeneration:Solvent recovery applications in German chemical clusters are driving circular economy adoption, where spent carbon reactivation reduces raw material costs and waste disposal liabilities.
Market Restraints
- Raw material concentration:Coconut shell activated carbon supply concentrates in Southeast Asian processing facilities, exposing buyers to weather-related harvest volatility and shipping cost spikes.
- REACH registration barriers:European chemical filter manufacturers face extended compliance timelines and testing costs for novel media chemistries, slowing product iteration versus Asian competitors.
- Membrane substitution threat:Polymeric separation technologies are capturing share in pharmaceutical sterile processing where zero-contamination assurance justifies capital-intensive infrastructure.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO cleanroom certification requirements are expanding as contract development and manufacturing organizations build capacity for export markets, creating filter system demand in Hyderabad and Ahmedabad clusters.
- Carbon capture integration:Amine-based post-combustion capture systems at US power plants require specialized gas phase filtration for amine degradation products, opening adjacent application space.
- Digital service platforms:IoT-enabled pressure differential monitoring and automated reorder systems are unbundling traditional distributor relationships, allowing manufacturers to capture aftermarket revenue directly.
Industry Challenges
- Cross-functional expertise scarcity:Filter system design now requires simultaneous competence in materials science, airflow modeling, and regulatory interpretation, tightening talent pipelines for field application engineers.
- ISO 16890 transition friction:Laboratories and certification bodies face backlogs in retesting legacy product portfolios against updated filter classification standards, delaying new product launches.
- Legacy control system integration:Brownfield industrial facilities in the US Midwest and German Ruhr region require costly retrofit engineering to connect modern filtration monitoring to decades-old SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gas Phase Filtration System Market |
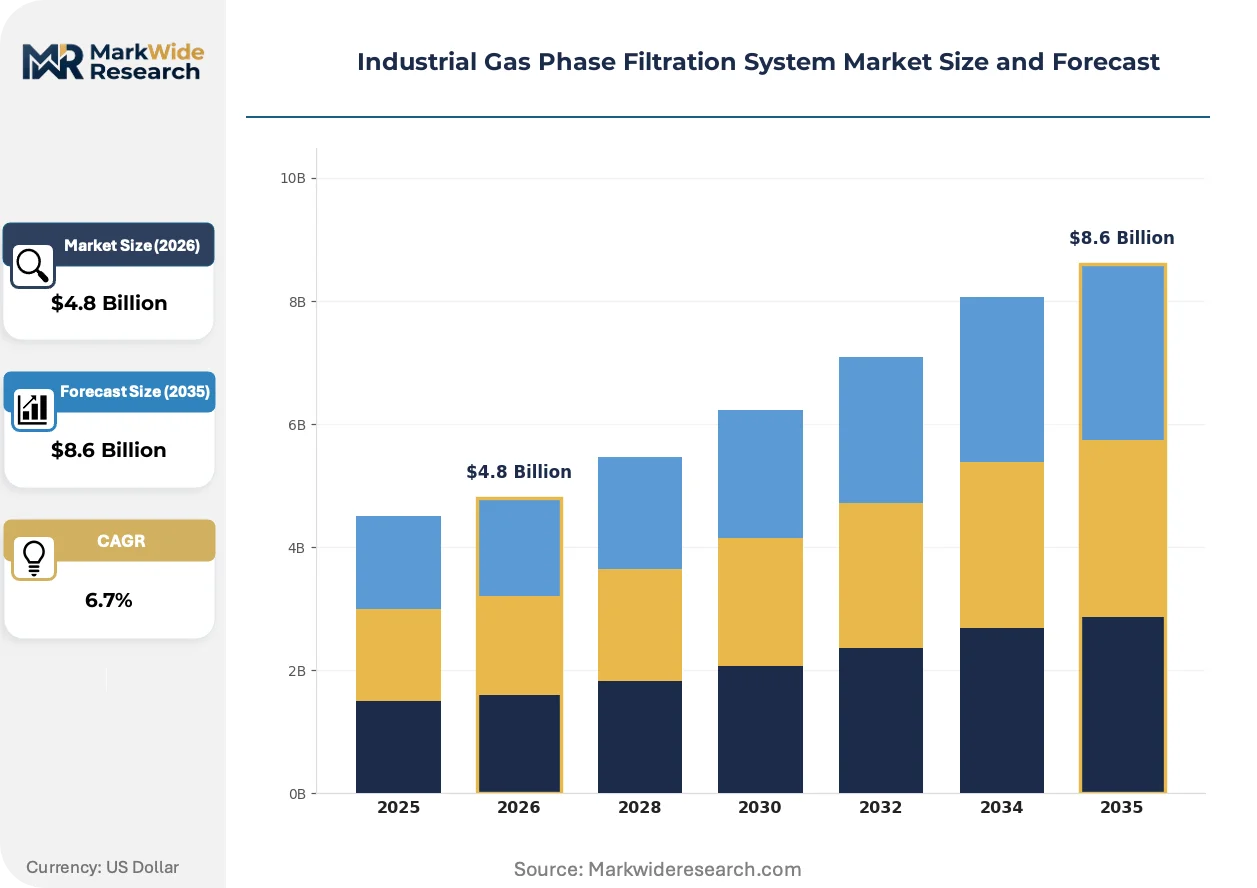
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon Filters, HEPA Filters, Electrostatic Precipitators, Chemical Filters Application: Air Purification, Odor Control, Industrial Ventilation, Gas Treatment End User: Oil & Gas, Pharmaceuticals, Food & Beverage, Power Generation Technology: Absorption, Adsorption, Catalytic Oxidation, Membrane Separation |
| Companies Covered | Freudenberg, Circul-Aire Inc., AAF International, Filtration Group Corporation, Koch Filter, Camfil AB, Bry-Air (Asia) Pvt. Ltd., Purafil, Donaldson Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gas Phase Filtration System Market Shifts & Advancements
Electrochemical sensing and machine learning algorithms are converging to enable real-time contaminant detection, shifting maintenance from scheduled replacement to condition-based intervention and compressing total cost of ownership calculations.
Metal-organic framework materials are absorbing polar volatile organic compounds at higher selectivity than conventional activated carbon, enabling smaller footprint systems. Pharmaceutical sterile processing facilities in Switzerland and Massachusetts are piloting MOF-based arrays for solvent vapor recovery. The technology is absorbing margin from traditional carbon suppliers by commanding 40-60% price premiums for equivalent removal capacity.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of impregnated carbon chemistries used in mercury and hydrogen sulfide removal. German chemical manufacturers are accelerating qualification of alternative metal oxide substrates ahead of 2026 sunset dates. Semiconductor fabs in Dresden and Leuven are pre-qualifying replacement media to avoid supply interruption during transition windows.
Multi-site industrial accounts are consolidating filter procurement through corporate sustainability offices rather than decentralized plant engineering, centralizing supplier selection criteria around lifecycle carbon footprint and circularity metrics. Food and beverage multinationals with operations across Denmark, Netherlands, and Belgium are deploying standardized filter specifications to simplify compliance auditing. This concentration is compressing supplier margins while rewarding vertically integrated manufacturers with regeneration service capabilities.
Industrial Gas Phase Filtration System Market Segmentation
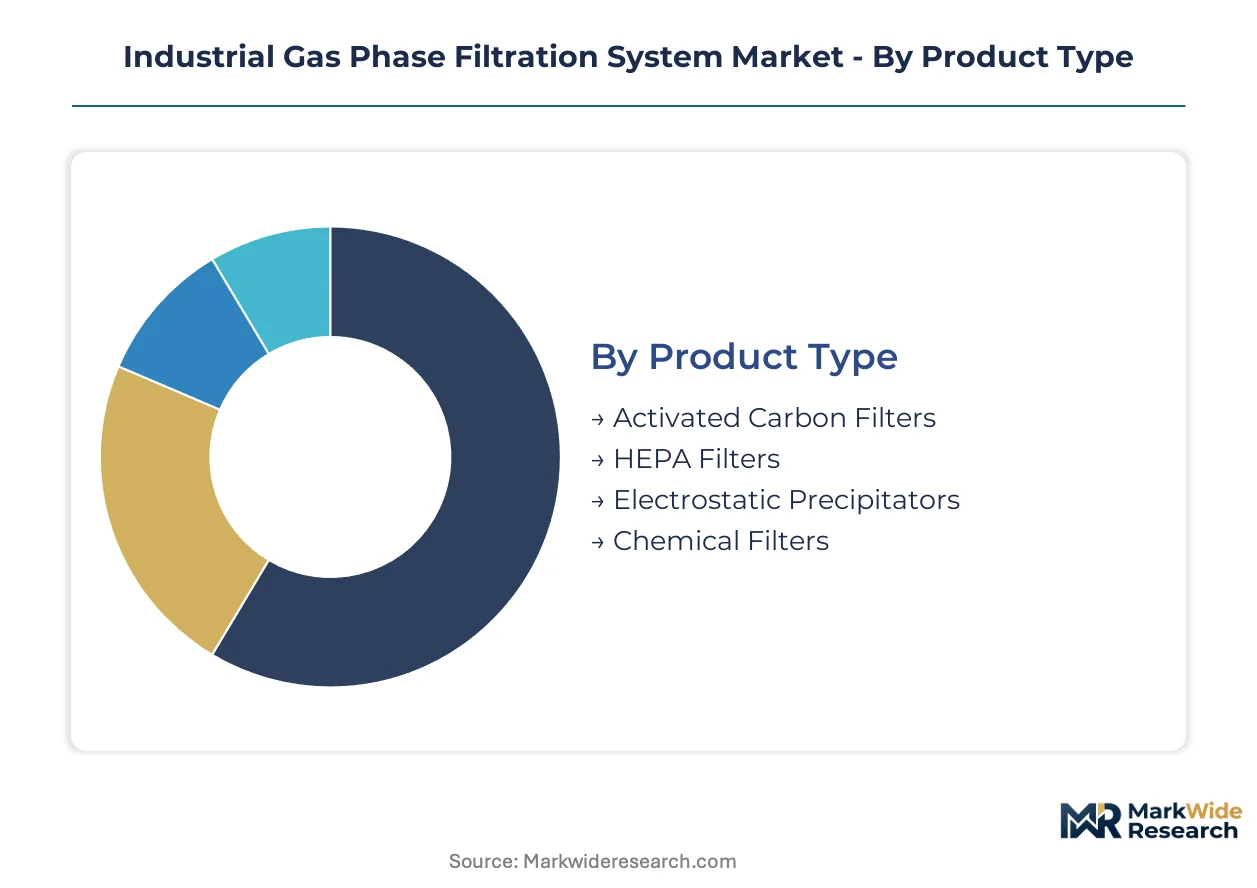
Gas phase filtration architectures diverge sharply by contaminant class, airflow volume, and regulatory exposure. Segment selection determines media replacement economics, capital intensity, and service contract structures across industrial verticals.
Product Type:
Media composition dictates removal efficiency, pressure drop characteristics, and regeneration potential across installation bases.
- Activated Carbon Filters:Porous carbonaceous media with surface areas exceeding 1,000 m²/g trap organic vapors through physical adsorption. German chemical manufacturing clusters in Ludwigshafen and Leverkusen drive replacement cycles for solvent recovery arrays, with REACH authorization timelines forcing reformulation of impregnated variants for mercury removal.
- Chemical Filters:Impregnated substrates with proprietary chemistries target specific molecular contaminants at parts-per-billion thresholds. Semiconductor fabrication facilities in Taiwan and South Korea deploy these for ammonia and acid gas control at sub-3nm process nodes, justifying 40-60% price premiums over conventional carbon.
- HEPA Filters:Glass fiber pleated media rated H13-H14 capture particulates coexisting with gas phase threats in nuclear ventilation and pharmaceutical cleanrooms.
- Electrostatic Precipitators:Ionization-based systems remove charged particulates and aerosols from high-temperature process streams in power generation flue gas treatment.
Mature deployment sits with Activated Carbon Filters. Newer deployment is concentrated in Chemical Filters.
Application:
Functional use case determines airflow architecture, monitoring requirements, and compliance documentation burdens.
- Air Purification:Controlled environment systems achieving ISO 14644-1 Class 5-8 cleanliness for pharmaceutical sterile processing and microelectronics assembly. Massachusetts and Switzerland facilities pilot metal-organic framework arrays for solvent vapor recovery, commanding premium pricing for zero-contamination assurance.
- Industrial Ventilation:Process exhaust handling corrosive or toxic atmospheres in petrochemical and metal finishing operations. Texas and Louisiana refineries face EPA NESHAP mandates tightening hazardous air pollutant limits, accelerating filter replacement cycles.
- Odor Control:Activated carbon systems addressing nuisance emissions from wastewater treatment and food processing facilities.
- Gas Treatment:Amine degradation product filtration at carbon capture installations in US power plants, opening adjacent application space for specialized media.
Volume concentration rests with Industrial Ventilation. Margin expansion is climbing fastest in Air Purification.
End User:
Industry verticals impose distinct contamination sensitivity thresholds, batch versus continuous operation patterns, and procurement centralization trends.
- Pharmaceuticals:Sterile manufacturing environments with FDA and EMA validation requirements for filter integrity testing. CDSCO cleanroom certification expansion in Hyderabad and Ahmedabad clusters is creating system demand as Indian contract development organizations build export capacity.
- Oil & Gas:Refinery and petrochemical operations with high-volume solvent recovery and sulfur compound removal needs. German chemical clusters are accelerating circular economy adoption through spent carbon reactivation services.
- Power Generation:Flue gas treatment and turbine inlet air filtration for combined-cycle plants across North American installations.
- Food & Beverage:Odor control and process air quality for fermentation and packaging operations, with multinationals in Denmark, Netherlands, and Belgium centralizing procurement through corporate sustainability offices.
Procurement consolidation is most advanced in Food & Beverage. Technical complexity is deepest in Pharmaceuticals.
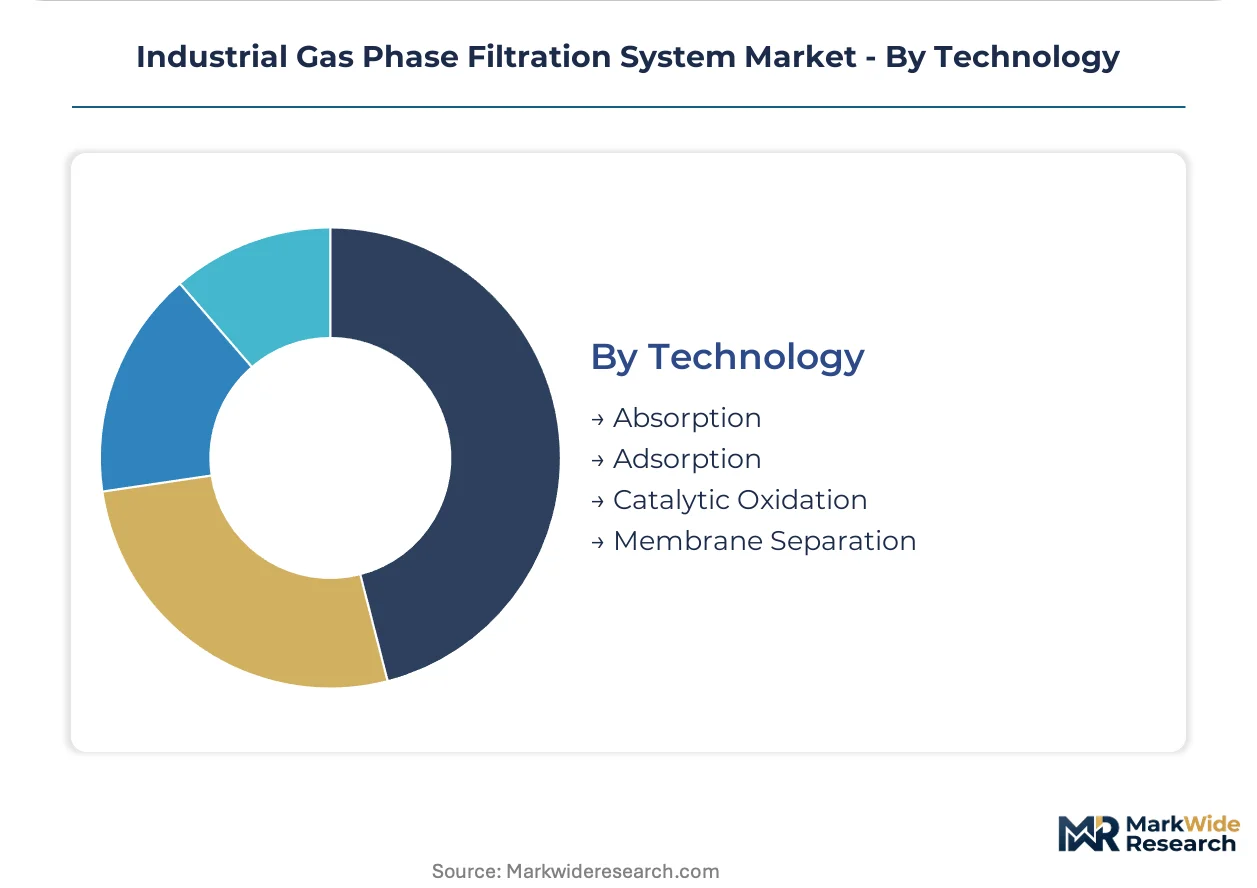
Technology:
Mechanism of contaminant removal determines selectivity, energy consumption, and compatibility with process conditions.
- Adsorption:Surface-based capture on porous media, dominated by activated carbon but increasingly incorporating metal-organic frameworks with higher polar VOC selectivity. The technology is absorbing margin from traditional carbon suppliers through footprint reduction and regeneration economics.
- Membrane Separation:Polymeric barriers achieving molecular-level separation without phase change. Pharmaceutical sterile processing facilities are capturing share from adsorption where zero-contamination assurance justifies capital-intensive infrastructure.
- Absorption:Liquid-phase scrubbing for high-concentration acid gas and ammonia streams in chemical process industries.
- Catalytic Oxidation:Thermal destruction of VOCs through precious metal catalysts, applied where recovery value is insufficient to justify adsorption.
Installed base dominance belongs to Adsorption. Steepest expansion trajectory is observed in Membrane Separation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of activated carbon media concentrates in Southeast Asian processing facilities, while consumption clusters in German chemical manufacturing, US petrochemical corridors, and East Asian semiconductor fabrication. This geographic split creates supply chain exposure to shipping cost volatility and harvest seasonality.
United States
Petrochemical refineries in Texas and Louisiana face accelerating filter replacement cycles under EPA NESHAP mandates tightening hazardous air pollutant limits. OSHA Permissible Exposure Limits for volatile organic compounds are compressing upgrade timelines for industrial ventilation systems. Carbon capture installations at power plants in the Midwest are creating adjacent demand for amine degradation product filtration.
Germany
Chemical manufacturing clusters in Ludwigshafen and Leverkusen drive replacement cycles for solvent recovery arrays using activated carbon and chemical filter systems. REACH authorization requirements for persistent organic pollutants are forcing reformulation of impregnated carbon chemistries ahead of 2026 sunset dates. Spent carbon reactivation services are accelerating circular economy adoption across the Ruhr industrial region.
China
Semiconductor fabrication investments are expanding cleanroom gas phase filtration deployments as domestic chip manufacturing scales. GB standards for industrial air quality are tightening enforcement in coastal manufacturing zones. Yangtze River Delta chemical parks are piloting metal-organic framework arrays for polar volatile organic compound removal.
South Korea
Memory and logic fabs are deploying specialized chemical filters for ppb-level contaminant removal as process nodes shrink below 3nm. MFDS pharmaceutical cleanroom certification requirements are expanding filter system demand in biologics manufacturing. Seoul Capital Area industrial complexes are consolidating procurement through corporate sustainability offices.
India
CDSCO cleanroom certification expansion is driving filter system demand as contract development organizations build export capacity in Hyderabad and Ahmedabad clusters. BIS standards for industrial air quality are tightening in pharmaceutical manufacturing zones. Western India chemical corridors are adopting activated carbon regeneration services to reduce raw material costs.
Industrial Gas Phase Filtration System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the filtration value chain, creating a tiered structure where integrated media manufacturers capture margin upstream while system integrators compete on project delivery speed. The vendor base spans multinational conglomerates with captive carbon production, regional specialists in aftermarket service density, and emerging technology developers commercializing metal-organic frameworks. Two strategic archetypes dominate: vertically integrated manufacturers controlling proprietary media formulations, and service-intensive operators anchoring replacement revenue through long-term agreements. Competitive moves concentrate on geographic expansion into pharmaceutical manufacturing clusters and technology licensing for carbon capture adjacencies.
Among European-based integrated manufacturers, Freudenberg and Camfil AB exemplify contrasting approaches to value capture. Freudenberg leverages materials science heritage to sustain captive supply of activated carbon media, while Camfil AB anchors Nordic aftermarket service density through long-term filter replacement agreements. Donaldson Company occupies a position among North American scale-driven competitors focused on power generation installations. These three represent the dominant competitive archetypes: upstream-integrated media control, service-anchored lifecycle revenue, and manufacturing scale across standardized applications.
| Leading Market Players |
|---|
| Freudenberg |
| Circul-Aire Inc. |
| AAF International |
| Filtration Group Corporation |
| Koch Filter |
| Camfil AB |
| Bry-Air (Asia) Pvt. Ltd. |
| Purafil |
| Donaldson Company |
| Others |
Supply & Pricing Matrix
Captive production of activated carbon media anchors both supply security and pricing power for integrated manufacturers serving semiconductor and pharmaceutical cleanroom operators. This upstream control insulates Freudenberg and similar vertically positioned suppliers from raw material volatility while enabling premium capture on proprietary chemical filter formulations.
Pricing Analysis
Margin tightening in standard activated carbon tiers reflects coconut shell supply volatility and Southeast Asian processing concentration. Three-tier pricing structure across premium, standard, and economy levels separates HEPA-integrated gas phase systems from standalone carbon arrays and commodity odor control units. Semiconductor fabs in Taiwan and South Korea absorb premium pricing for ppb-rated chemical filters, while municipal wastewater operators in Texas and Louisiana exhibit acute price sensitivity on replacement cycles.
Supply Chain Analysis
Coconut shell activated carbon feedstock draws from Indonesian and Philippine processing facilities, with Sri Lankan suppliers capturing specialty grades for mercury removal applications. Chemical filter substrates rely on German and Japanese specialty chemical manufacturers for impregnated media formulations. Single-source vulnerability concentrates in Southeast Asian carbon activation capacity, where monsoon harvest patterns disrupt supply continuity. Distribution runs through authorized service networks and direct OEM channels to multi-site industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal-organic framework materials are displacing conventional activated carbon in pharmaceutical solvent recovery, compressing margins for legacy suppliers while opening premium positioning for materials science innovators.
For Market Incumbents: Hedge against membrane substitution in sterile processing by accelerating MOF pilot qualifications with Swiss and Massachusetts pharmaceutical operators. Deepen captive carbon regeneration capabilities in the German Ruhr region to defend service revenue against circular economy entrants. Prioritize ISO 16890 certification completion to avoid product launch delays during laboratory backlog periods. For New Entrants and Emerging Players: Begin with carbon capture adjacencies at US Midwest power plants, where amine degradation filtration lacks established supplier relationships. Target Indian pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad, where CDSCO certification expansion outpaces local technical service density. Pursue technology licensing arrangements with semiconductor equipment OEMs rather than direct fab sales cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by industrial conglomerates seeking filtration technology platforms. Five-to-ten-year viability favors vertically integrated manufacturers with regeneration service networks over pure-play hardware suppliers. Watch for REACH authorization deadline acceleration as inflection indicator for media chemistry reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Activated Carbon Production | Captive supply secures margin pools against Southeast Asian harvest volatility. |
| Regeneration Service Network Expansion | Circular economy positioning captures replacement revenue from German chemical clusters. |
| Metal-Organic Framework Commercialization | Polar VOC selectivity commands 40-60% premiums over conventional carbon in Swiss pharmaceutical facilities. |
| Digital Service Platform Development | IoT-enabled monitoring unbundles distributor relationships for direct aftermarket capture. |
| Carbon Capture Adjacency Entry | Amine degradation filtration opens adjacent application space at US power generation installations. |
Research Methodology
Multi-period observation of filter replacement cycle frequencies, regulatory compliance expenditure patterns, and media technology adoption rates anchored the trend analysis, supplemented by interviews with plant engineering directors at petrochemical facilities, procurement leads at semiconductor fabs, aftermarket service managers at filtration OEMs, and regulatory affairs specialists at pharmaceutical manufacturers. Secondary validation drew from EPA NESHAP enforcement data, REACH authorization timelines published by ECHA, customs records of activated carbon trade flows, and SEC filings of publicly traded filtration equipment suppliers. Bottom-up unit economics triangulated against top-down market sizing across product type, application, and end-use verticals.
Segment-weighting approaches distributed value and volume estimates across media composition tiers, functional use cases from air purification to odor control, and industry verticals from pharmaceuticals to power generation. CAGRs were derived from regression analysis of historical installation data and forward projection of regulatory mandate compliance timelines. Forecast inputs incorporated semiconductor node shrinkage trajectories, pharmaceutical cleanroom certification expansion rates, and carbon capture deployment pipelines at US power plants.
Underlying measurement precision varies by segment; semiconductor and pharmaceutical applications carry tighter precision than general industrial ventilation due to documented procurement transparency. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, technology substitution rates, and raw material supply continuity. Supply disruption from Southeast Asian weather patterns, REACH authorization timeline acceleration, and membrane technology cost curves warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Krypton Gas Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Syngas Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Argon Gas Market