
 Nitrogen Generator Market | 2026-2036
Nitrogen Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrogen Generator Market Analysis
China is reshaping competitive dynamics through aggressive capacity expansion in industrial gas equipment manufacturing. Parker Hannifin Corporation leverages its filtration and motion control portfolio to anchor premium positioning in membrane and PSA systems. Air Products and Chemicals, Inc. sustains technology leadership through deep R&D investment in adsorption materials and process intensification. Linde plc dominates cryogenic and large-scale onsite generation through its integrated engineering and gas supply heritage.
A nitrogen generator produces high-purity nitrogen gas from compressed air through pressure swing adsorption, membrane separation, or cryogenic distillation, typically delivering 95% to 99.999% purity depending on application requirements. The equipment eliminates reliance on delivered bulk liquid or cylinder gas, reducing logistics costs and supply interruption risks for continuous industrial operations. PSA nitrogen generators command the largest installed base due to proven reliability across food packaging and electronics inerting applications, while membrane systems gain share in mobile and offshore oil & gas deployments where compact footprint and rapid start-up matter most. Cryogenic generators retain margin concentration at the highest purity tiers serving pharmaceutical aseptic processing and semiconductor fabrication.
FDA food safety regulations and pharmaceutical GMP standards enforced by the EPA and OSHA shape equipment specification, material certification, and validation documentation requirements across domestic installations. The EU F-Gas Regulation and REACH compliance frameworks in Europe impose additional refrigerant and material disclosure obligations on cryogenic system exporters. Stakeholders must monitor evolving purity standards in semiconductor and cell therapy manufacturing, as these specifications determine technology selection and capital allocation priorities.
Market Dynamics
On-site nitrogen generation is displacing bulk liquid delivery models as industrial operators prioritize supply chain autonomy and FDA food safety compliance accelerates capital redeployment toward self-contained systems.
Growth Catalysts
- FDA Food Safety Modernization Act enforcement:Food packaging facilities face mandatory preventive controls that favor continuous on-site nitrogen supply over interruptible bulk deliveries, driving PSA system installations.
- Semiconductor fabrication purity escalation:Advanced node manufacturing requires 99.9999% nitrogen purity that cryogenic generators reliably deliver, pulling capital into ultra-high-purity equipment segments.
- Pharmaceutical GMP mandates:Aseptic processing regulations from the EPA and OSHA compel validated nitrogen systems with full documentation trails, favoring integrated generator packages over commodity gas supply.
Market Restraints
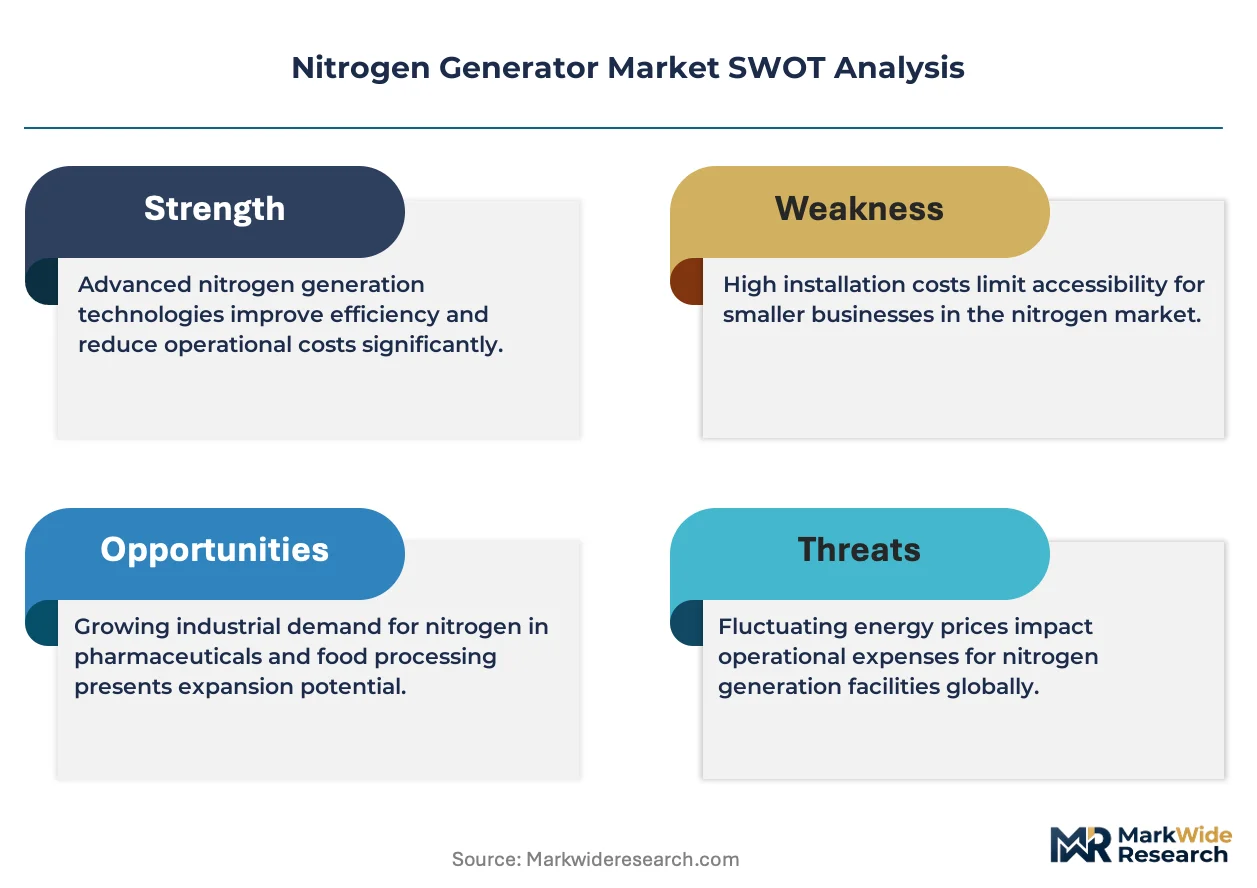
- Specialized adsorbent material concentration:Zeolite and carbon molecular sieve supply chains concentrate among limited specialty chemical producers, creating input cost volatility and lead time risk for PSA system manufacturers.
- Cryogenic equipment technical floor:Sub-ambient distillation requires stainless steel fabrication and vacuum insulation expertise that few engineering firms possess, constraining capacity expansion at the premium purity tier.
- EU F-Gas Regulation compliance friction:Cryogenic system exporters face refrigerant disclosure obligations and material certification requirements that extend validation timelines and raise documentation costs for European deployments.
Strategic Opportunities
- Offshore oil and gas platform electrification:Membrane nitrogen systems with compact footprints and rapid start-up capabilities capture replacement demand as floating production facilities abandon nitrogen cylinder logistics.
- Cell therapy manufacturing emergence:Cryogenic nitrogen purity specifications for cryopreservation and aseptic filling create a new equipment category between pharmaceutical and semiconductor grade requirements.
- India PLI scheme for specialty chemicals:Domestic pharmaceutical manufacturing incentives attract nitrogen generator deployments as multinational API producers localize production under production-linked incentive frameworks.
Industry Challenges
- Adsorption process engineering talent scarcity:PSA system optimization requires rare expertise in mass transfer modeling and valve sequencing that outpaces vocational training program output.
- Multi-standard certification complexity:Equipment must simultaneously satisfy FDA validation protocols, EPA emissions requirements, and OSHA pressure vessel codes, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogen Generator Market |
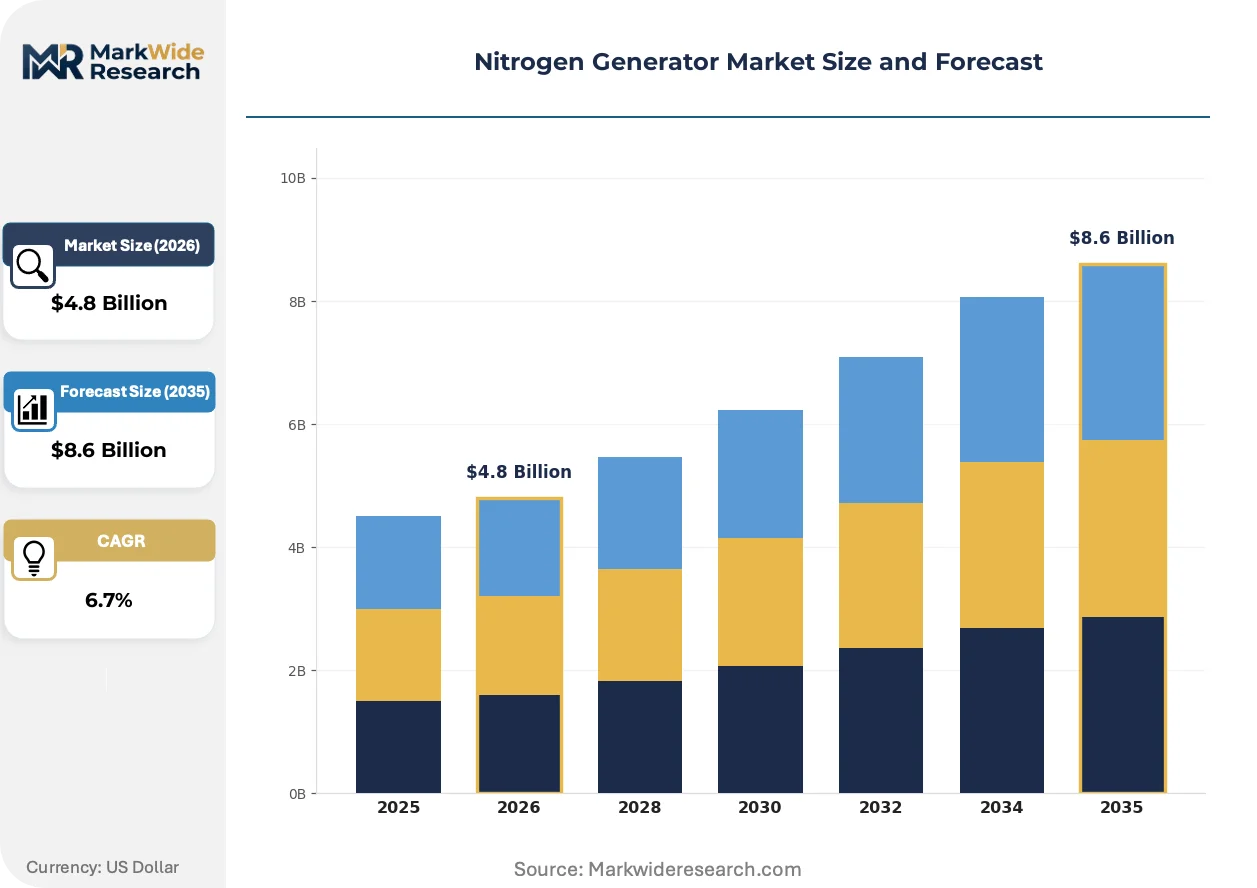
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
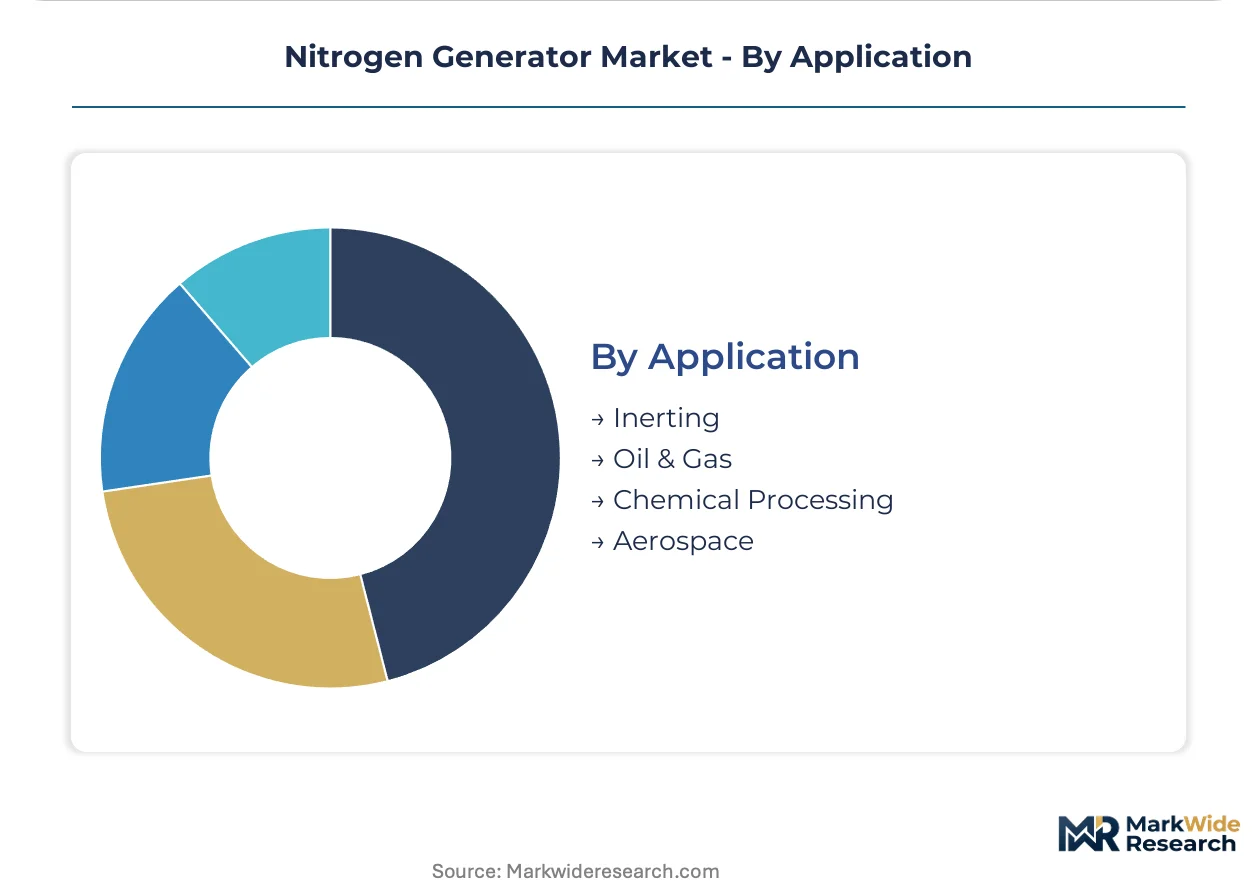
| Segmentation | Product Type: Membrane Nitrogen Generators, PSA Nitrogen Generators, Cryogenic Nitrogen Generators, Turboexpanders End User: Food Packaging, Pharmaceuticals, Electronics, Metal Manufacturing Technology: Filtration, Absorption, Distillation, Adsorption Application: Inerting, Oil & Gas, Chemical Processing, Aerospace |
| Companies Covered | Parker Hannifin Corporation, Air Products and Chemicals, Inc., Air Liquide, Linde plc, Atlas Copco AB, Ingersoll Rand, NOVAIR SAS, On Site Gas Systems, Inc., Hitachi Industrial Equipment Systems Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogen Generator Market Emerging Trajectories
Digital monitoring architectures and modular system designs are compressing commissioning cycles and enabling predictive maintenance models that reshape equipment lifecycle economics.
AI-driven predictive maintenance software is virtualizing traditional service contracts by embedding real-time performance analytics directly into PSA and membrane control systems. Food packaging operators now demand remote purity monitoring and automated regeneration scheduling as standard features. Equipment vendors respond by shifting revenue toward subscription-based analytics platforms rather than discrete hardware sales.
REACH substance restrictions and EU F-Gas Regulation amendments are forcing refrigerant substitutions in cryogenic generator designs. Manufacturers face reformulation of heat exchange fluids and insulation materials to maintain thermal efficiency under tightened chemical disclosure rules. European pharmaceutical and semiconductor installations drive this compliance urgency as they cannot accept equipment with non-conforming material certifications.
Buyers increasingly unbundle equipment procurement from long-term service agreements, compressing vendor lock-in periods and intensifying aftermarket competition. Industrial gas specialists and independent service firms now compete directly with original manufacturers for maintenance contracts. This pattern concentrates in United States manufacturing corridors where facilities operate large installed bases and possess in-house compressed air expertise.
Nitrogen Generator Market Segmentation
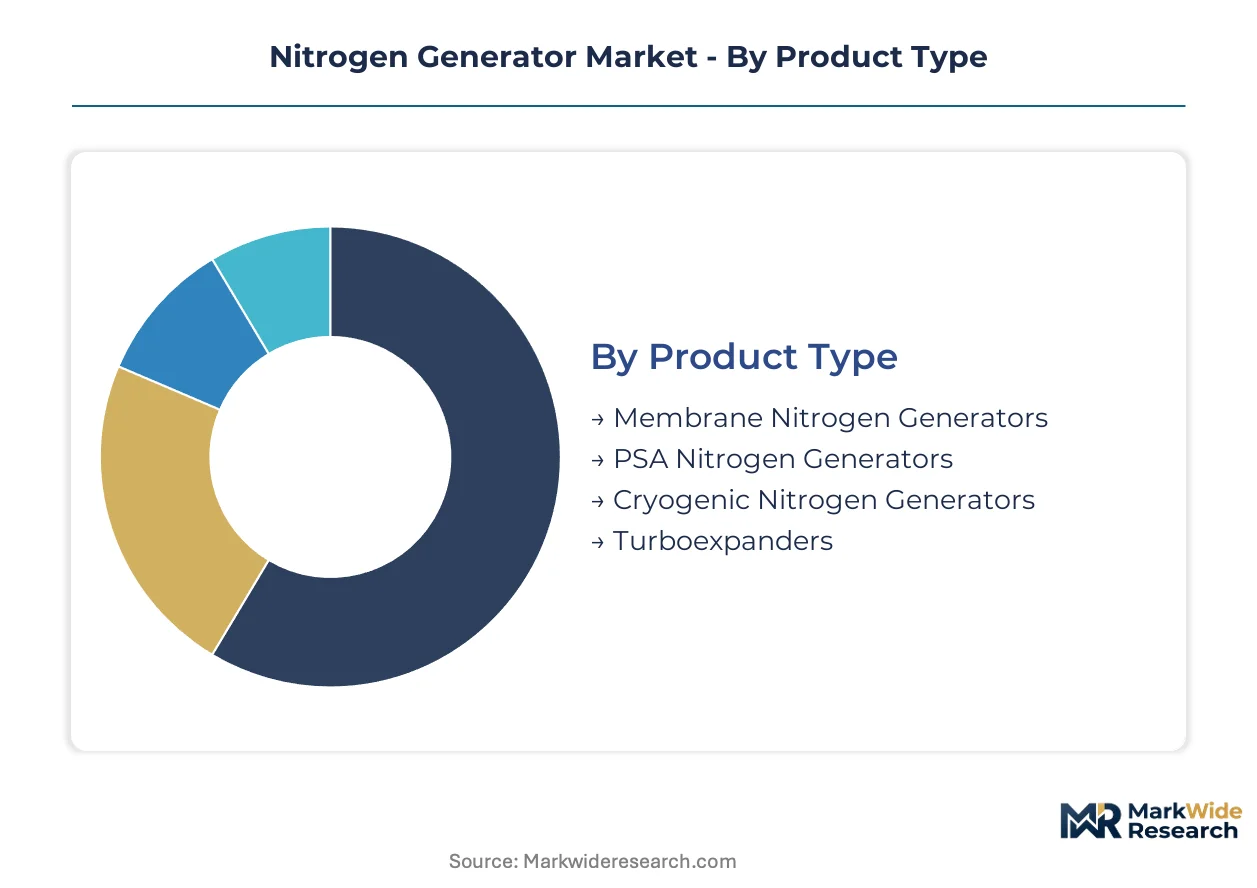
Nitrogen generator segmentation reveals distinct capital cycle patterns across product architectures, with membrane and PSA systems turning over faster than cryogenic installations. End-use concentration in food packaging and pharmaceuticals creates divergent specification requirements that reshape vendor portfolio priorities.
Product Type:
Replacement cycles stretch from 7 years for membrane units to 15+ years for cryogenic trains, compressing revenue recognition windows for faster-turnover segments.
- Membrane Nitrogen Generators:Hollow-fiber polymer membranes separate nitrogen from compressed air through selective permeability, delivering 95-99.5% purity without moving parts. Offshore oil and gas platforms in the Gulf of Mexico and North Sea favor these systems for their 30-second start-up and minimal maintenance footprint, though permeate losses limit efficiency at higher purities.
- PSA Nitrogen Generators:Pressure swing adsorption cycles compressed air through carbon molecular sieve beds, achieving 95-99.999% purity through alternating pressurization and venting sequences. Food packaging facilities across the United States deploy PSA systems most heavily, as FDA preventive control regulations mandate uninterrupted nitrogen supply that bulk liquid deliveries cannot guarantee.
- Cryogenic Nitrogen Generators:Sub-ambient distillation of liquefied air yields 99.9999%+ purity for semiconductor and pharmaceutical applications requiring elimination of trace oxygen and moisture.
- Turboexpanders:Expansion turbines recover refrigeration work in large-scale cryogenic trains, improving thermal efficiency for high-volume industrial gas production.
PSA systems dominate installed base. Membrane generators are where expansion concentrates.
End User:
Customer concentration patterns split between high-volume commodity buyers and specification-intensive premium purchasers.
- Food Packaging:Modified atmosphere packaging for meat, snack foods, and ready-to-eat meals consumes nitrogen for oxygen displacement and shelf-life extension. United States meat processing corridors in the Midwest and Southeast drive replacement demand as aging bulk liquid contracts expire.
- Pharmaceuticals:Aseptic filling lines and API manufacturing require validated nitrogen systems with full FDA 21 CFR Part 11 documentation trails. EPA and OSHA GMP enforcement compels integrated generator packages over commodity gas supply, concentrating capital deployment at multi-product facilities in New Jersey and Massachusetts.
- Electronics:Semiconductor fabrication and SMT assembly use nitrogen for inerting, reflow soldering, and wafer handling.
- Metal Manufacturing:Laser cutting and heat treatment operations employ nitrogen as assist gas and protective atmosphere.
Food packaging anchors volume demand. Pharmaceuticals command the steepest expansion trajectory.
Technology:
Process selection determines both capital intensity and operating cost structure across installation scales.
- Filtration:Coalescing and particulate filters protect downstream separation media from compressor oil and atmospheric contaminants, extending adsorbent life in PSA systems.
- Absorption:Chemical scrubbing removes carbon dioxide and moisture from feed air prior to cryogenic distillation, preventing ice formation in cold boxes.
- Distillation:Cryogenic fractionation separates air components through boiling point differences at temperatures below -180°C, delivering ultra-high-purity nitrogen for semiconductor nodes.
- Adsorption:Surface-mediated separation using zeolites or carbon molecular sieves enables pressure-driven nitrogen production without refrigeration equipment.
Adsorption commands the largest equipment footprint. Distillation captures the premium purity tier.
Application:
Use-case requirements span from intermittent portable supply to continuous high-availability industrial service.
- Inerting:Oxygen exclusion for chemical storage, pharmaceutical processing, and electronics manufacturing demands reliable nitrogen blanket maintenance with minimal deviation.
- Oil & Gas:Enhanced oil recovery, pipeline purging, and offshore platform inerting favor membrane systems for mobility and rapid deployment in the Permian Basin and Bakken formation.
- Chemical Processing:Reactor blanketing and catalyst regeneration require consistent nitrogen quality to prevent runaway reactions or contamination.
- Aerospace:Aircraft fuel tank inerting and ground support equipment use nitrogen for fire suppression and system testing.
Inerting spans the broadest end-use base. Oil and gas applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor and its pipeline networks anchor United States nitrogen generator demand, while Rotterdam's industrial gas hub and Rhine barge terminals sustain European distribution. Asian manufacturing belts rely on Shanghai's Yangshan port and Singapore's Jurong Island storage for feedstock security.
United States
Midwest meat processing clusters and Southeast pharmaceutical corridors drive PSA system deployments for FDA-compliant food packaging and aseptic manufacturing. OSHA pressure vessel codes and EPA emissions requirements shape equipment specifications across New Jersey and Massachusetts multi-product facilities. Houston's petrochemical complex sustains cryogenic demand for refinery inerting and catalyst regeneration operations.
Germany
Baden-Württemberg's automotive stamping plants and Bavarian semiconductor fabs require ultra-high-purity nitrogen for laser cutting and wafer handling processes. REACH substance restrictions and EU F-Gas Regulation amendments force refrigerant substitutions in cryogenic system designs. The Ruhr industrial belt maintains membrane generator installations for chemical storage blanketing and pipeline maintenance.
China
Yangtze River Delta electronics manufacturers and Pearl River Delta battery cell plants consume nitrogen for lithium-ion electrode production and SMT assembly inerting. MIIT industrial upgrading guidelines and dual carbon goals accelerate domestic PSA equipment substitution for imported bulk liquid supply. Shandong's chemical parks deploy large-scale cryogenic trains for ammonia synthesis and fertilizer production.
India
Maharashtra's API manufacturing hubs and Gujarat's specialty chemical zones attract nitrogen generator investments under the PLI scheme's production-linked incentives. CDSCO pharmaceutical validation requirements and BIS equipment standards compel documented purity systems over commodity gas contracts. Karnataka's biotech corridor emerges as a cell therapy manufacturing cluster with cryogenic-grade nitrogen specifications.
Japan
Kyushu's semiconductor foundries and Nagoya's automotive component suppliers demand 99.9999% purity for advanced node fabrication and precision welding. METI energy efficiency mandates and JIS certification protocols favor integrated generator packages with remote monitoring capabilities. Osaka's pharmaceutical district sustains validated nitrogen systems for aseptic filling and API synthesis operations.
Nitrogen Generator Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in filtration, valve, and adsorbent supply. The market structures around three tiers: diversified industrial gas conglomerates with cryogenic heritage, compressed air equipment manufacturers extending into gas generation, and pure-play nitrogen system specialists. Strategic moves concentrate on backward integration into adsorbent production and geographic expansion through local assembly partnerships in India and Southeast Asia.
Among diversified industrial gas conglomerates, Linde plc and Air Products and Chemicals, Inc. anchor the premium cryogenic segment through integrated engineering capabilities. Parker Hannifin Corporation occupies a position within the component-to-system migration tier, leveraging filtration and motion control portfolios. These three exemplify distinct competitive archetypes: gas supply heritage, equipment manufacturing scale, and precision component integration.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Air Products and Chemicals, Inc. |
| Air Liquide |
| Linde plc |
| Atlas Copco AB |
| Ingersoll Rand |
| NOVAIR SAS |
| On Site Gas Systems, Inc. |
| Hitachi Industrial Equipment Systems Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese membrane manufacturing is compressing mid-tier equipment margins while concentrating pricing power among cryogenic specialists with vacuum insulation expertise. This utilization asymmetry forces PSA system vendors toward subscription-based service models to defend returns against commoditized hardware sales.
Pricing Analysis
FDA 21 CFR Part 11 validation requirements dictate the pricing tier structure across pharmaceutical-grade nitrogen generators, separating documented systems from commodity equipment. Three-tier pricing structure across premium cryogenic, standard PSA, and economy membrane levels reflects certification burden and purity specification rather than manufacturing cost alone. Cost compression in membrane systems is intensifying because hollow-fiber polymer capacity expansion in Asia outpaces demand growth. Food packaging operators show highest price sensitivity due to thin operating margins, while semiconductor fabs accept premium positioning for 99.9999% purity guarantees.
Supply Chain Analysis
Contract manufacturing for carbon molecular sieve beds concentrates among German and Japanese specialty chemical producers with proprietary zeolite formulations. Zeolite and hollow-fiber membrane feedstocks draw from limited specialty chemical suppliers, creating input concentration risk for PSA and membrane system builders. Single-source vulnerability in adsorbent supply chains exposes manufacturers to lead time volatility when pharmaceutical demand spikes. Distribution runs through compressed air equipment OEMs and independent industrial gas specialists competing for aftermarket service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nitrogen generator market is entering a cyclical upswing as FDA enforcement of preventive controls in food packaging forces replacement of bulk liquid contracts with captive generation systems.
For Market Incumbents: Harden defensive positions through backward integration into carbon molecular sieve production and captive membrane fiber extrusion capabilities. Lock in multi-year service contracts with pharmaceutical facilities before independent service firms capture FDA validation documentation expertise. Priority levers include regional assembly partnerships in India under PLI scheme incentives and embedded AI monitoring platforms that virtualize traditional maintenance revenue.
For New Entrants and Emerging Players: Southeast Asian electronics manufacturing corridors offer the most penetrable white space for membrane system deployment, particularly Vietnam and Indonesia where SMT assembly capacity is expanding faster than bulk liquid infrastructure. Target offshore oil and gas platform electrification projects with compact nitrogen packages that displace cylinder logistics. Go-to-market angle should emphasize rapid commissioning and minimal footprint against incumbent cryogenic alternatives.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-anchored infrastructure play because FDA, EPA, and OSHA mandates create durable replacement demand with limited technology substitution risk. Acquisition target archetype: pure-play nitrogen system specialists with validated pharmaceutical installations and remote monitoring software stacks. Signal to watch is CDSCO and BIS enforcement tightening in India that would accelerate domestic equipment substitution for imported bulk supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adsorbent Production | Captive carbon molecular sieve supply secures margin control against specialty chemical oligopoly pricing. |
| AI-Driven Predictive Maintenance Platform Launch | Embedded analytics virtualize service contracts and create recurring revenue streams beyond hardware sales. |
| Regional Assembly Partnership in India | PLI scheme incentives and CDSCO validation requirements attract multinational API producers to localize supply. |
| Refrigerant Substitution for EU F-Gas Compliance | Reformulated heat exchange fluids maintain cryogenic efficiency under REACH substance disclosure obligations. |
| Long-Term Service Agreement Unbundling | Independent aftermarket competition intensifies as buyers separate equipment procurement from maintenance contracts. |
Methodological Framework
A standing panel of plant engineers, maintenance directors at food packaging facilities, pharmaceutical GMP compliance officers, and compressed air equipment procurement managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EPA emissions compliance databases, SEC 10-K equipment disclosures, and industrial gas trade association technical bulletins. Bottom-up installation counts triangulated against top-down industrial gas market sizing from customs and trade flow data.
Scenario bracketing anchored the analytical framework with high-low purity demand cases across the projection horizon. Segmentation dimensions modeled include product architecture, end-use industry concentration, application requirement, and regional regulatory cluster intensity. CAGRs derived from equipment replacement cycle analysis and capital expenditure pipeline tracking across pharmaceutical and semiconductor fabrication buildouts. Forecast inputs incorporated MIIT industrial upgrading guidelines and dual carbon policy implementation timelines in China.
Practitioners should monitor FDA enforcement intensity, REACH amendment schedules, and semiconductor node transition announcements for early signals of forecast revision risk. Quarterly review of carbon molecular sieve spot pricing, cryogenic equipment order backlogs, and pharmaceutical facility commissioning timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Carbon Monoxide Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
3D Printing Gases Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Gas Processing Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
North America Industrial Gases Market