
 Electrical Insulation Coatings Market | 2026-2036
Electrical Insulation Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Insulation Coatings Market Intelligence
New production capacity for high-performance epoxies in China and Germany is rebalancing the supply chain for specialty coatings. BASF SE leverages its broad chemical engineering expertise to serve diverse end-user requirements. ELANTAS PDG Inc. specializes in advanced insulation systems for demanding applications in motors and generators. PPG Industries Inc. competes on the strength of its global distribution network and product availability.
Electrical insulation coatings are polymer-based materials applied to conductive substrates to prevent current leakage. These materials are engineered for high dielectric strength and thermal stability, ensuring operational safety and component longevity. Epoxy-based coatings dominate the market due to their mechanical robustness and cost-effectiveness in industrial machinery. Silicone formulations represent the fastest-growing product type, driven by their superior performance in high-temperature electronics and automotive components.
Regulatory frameworks such as the EU's REACH and RoHS directives directly influence material composition. In the United States, EPA standards on volatile organic compounds (VOCs) push manufacturers toward water-based or high-solids formulations. Material selection now requires a careful balance between achieving specific dielectric properties and adhering to increasingly stringent global environmental health and safety standards.
Market Dynamics
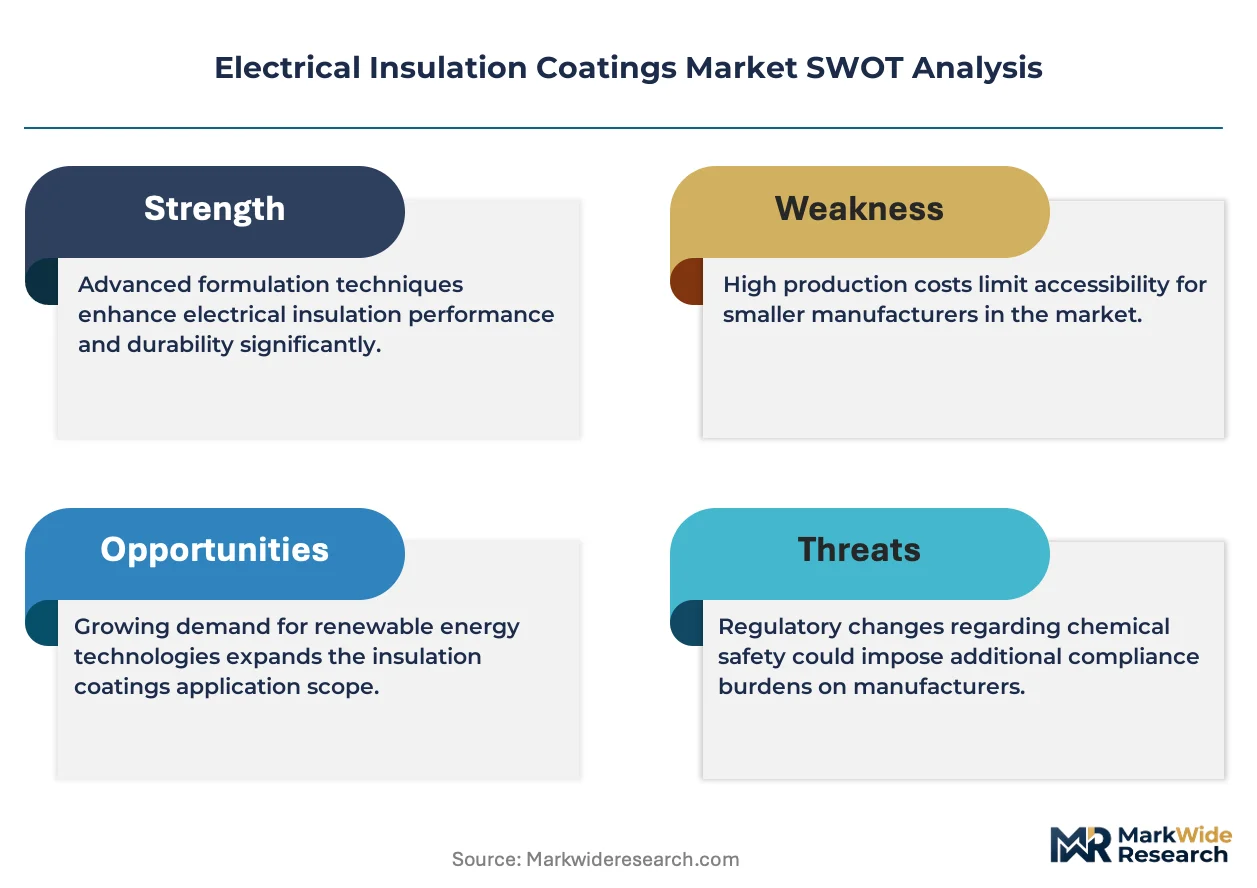
The electrical insulation coatings market is defined by the need to balance escalating performance requirements from electrification with tightening global chemical regulations. This tension between achieving higher dielectric strength and thermal endurance for applications like EV motors and adhering to substance restrictions under frameworks like the EU's RoHS directive is the central structural force shaping material innovation and product development.
Growth Catalysts
- Electric Vehicle Production:The global expansion of electric vehicle manufacturing, particularly in China and Germany, creates substantial demand for coatings for battery packs, motors, and power electronics to ensure safety and thermal management.
- Power Grid Modernization:Upgrades to aging power generation and transmission infrastructure in North America and Europe necessitate high-performance insulation for transformers, switchgear, and generators to improve efficiency and reliability.
- Miniaturization of Electronics:The trend toward smaller, more powerful consumer and industrial electronics requires advanced, thin-film insulation coatings that offer high dielectric strength in confined spaces, preventing electrical shorts and heat buildup.
Market Restraints
- Raw Material Price Volatility:Fluctuation in the cost of key precursors, such as epoxy resins, silicone polymers, and specialty solvents, creates pricing instability and margin pressure for coating manufacturers.
- Stringent Regulatory Hurdles:Divergent and evolving environmental regulations, including the EU's REACH and the US EPA's VOC standards, increase compliance costs and lengthen product development timelines for new formulations.
- Technical Adhesion Challenges:Achieving durable adhesion on new and varied substrates, such as advanced composites and novel metal alloys used in aerospace and automotive components, presents a significant technical barrier for coating performance.
Strategic Opportunities
- Bio-Based Formulations:Developing insulation coatings from renewable or bio-based feedstocks presents an opportunity to meet growing demand from OEMs for sustainable materials and to comply with corporate environmental, social, and governance goals.
- Coatings for Energy Storage:The rapid growth of battery energy storage systems (BESS) creates a new application frontier for specialized coatings that provide dielectric insulation, thermal management, and fire retardancy for battery modules.
- Expansion in Southeast Asia:Growing industrialization and electronics manufacturing in countries like Vietnam and Malaysia offer an underpenetrated market for insulation coatings beyond the established hub in China.
Industry Challenges
- Complex Certification Processes:Navigating the lengthy and expensive qualification and certification processes required by bodies like Underwriters Laboratories (UL) and the IEC for new materials slows market entry for innovative products.
- Application Expertise Scarcity:A shortage of technicians skilled in the precise application and quality control of high-performance coatings, especially with automated systems, can lead to performance inconsistencies and field failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Insulation Coatings Market |
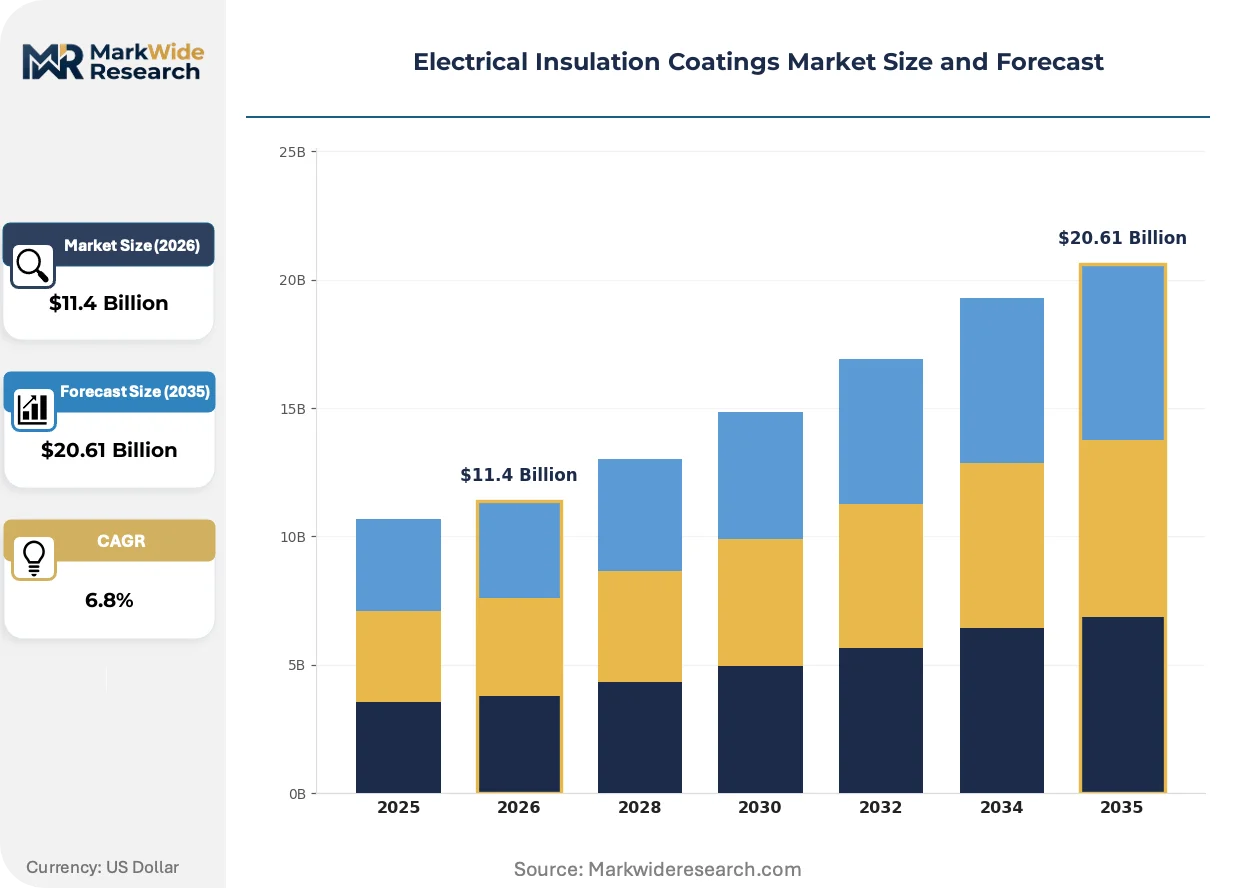
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silicone, Acrylic Application: Automotive Components, Power Generation Equipment, Electronics, Industrial Machinery End User: Manufacturing, Aerospace, Energy, Telecommunications Technology: High Voltage Insulation, Low Voltage Insulation, Thermal Insulation, Corrosion Resistance |
| Companies Covered | 3M, Evonik Industries AG, Akzo Nobel N.V., BASF SE, The Sherwin-Williams Company, PPG Industries Inc., ELANTAS PDG Inc., Jotun A/S, Axalta Coating Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Insulation Coatings Market Strategic Shifts & Innovations
Material science innovation is focused on developing multifunctional coatings that address simultaneous electrical, thermal, and mechanical stresses. This evolution is a direct response to the increasing power density of modern electronics and electrical equipment, which pushes traditional single-function insulators to their operational limits.
Multi-functional coatings that combine high dielectric strength with enhanced thermal conductivity are a primary product evolution. The aerospace and data center sectors are early adopters, using these materials to manage heat dissipation in increasingly compact and powerful systems. This integrated capability is absorbing the role of separate thermal interface materials and insulation films, simplifying device assembly and reducing component count.
The EU's RoHS directive, which restricts hazardous substances in electrical equipment, is forcing a fundamental reformulation of many legacy coating systems. This has a direct industrial consequence on supply chains, compelling a move away from certain lead-based stabilizers or brominated flame retardants. The consumer electronics and automotive electronics segments are most affected, accelerating the transition to compliant halogen-free epoxies and water-based polyurethane dispersions.
A notable shift in purchasing behavior involves end-users specifying coatings based on total system lifecycle analysis rather than on initial material cost alone. This change disrupts the traditional component-level procurement model, creating an advantage for suppliers who can provide validated data on how their coatings improve the energy efficiency or extend the service life of a finished product. This trend is most visible within the industrial motor and transformer manufacturing sectors in Germany and Japan.
Electrical Insulation Coatings Market Segmentation
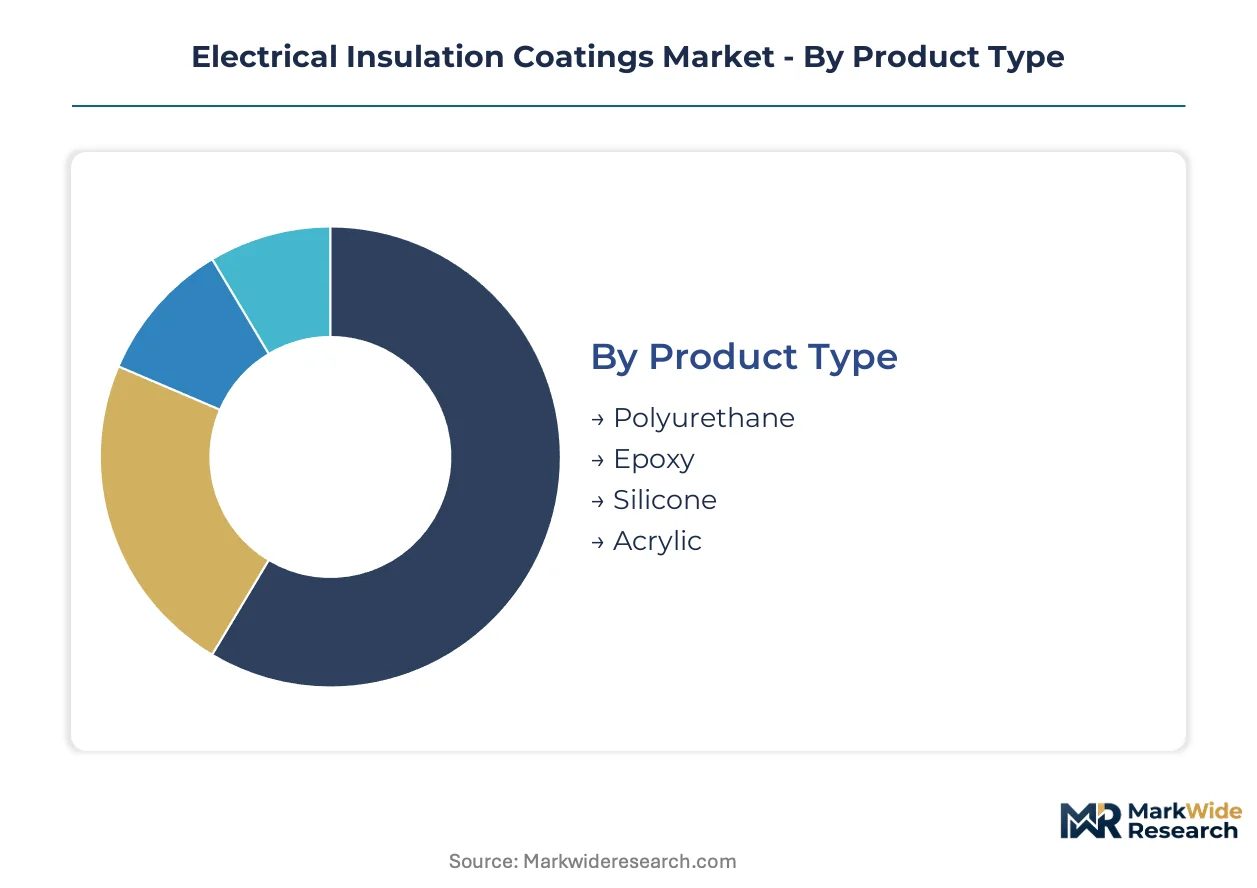
The electrical insulation coatings market segmentation highlights the diverse technical requirements and regulatory pressures influencing product development. Understanding these distinct segments allows manufacturers to tailor formulations for specific performance criteria and compliance standards. This granular analysis reveals opportunities for specialized material innovation across various end-use sectors.
Product Type:
The composition of electrical insulation coatings often dictates the certification pathways required for various applications.
- Epoxy:Epoxy-based coatings dominate the market due to their mechanical robustness and cost-effectiveness in industrial machinery. These materials frequently require adherence to specific industrial standards for durability.
- Silicone:Silicone formulations represent the fastest-growing product type, driven by their superior performance in high-temperature electronics and automotive components. These often necessitate UL recognition for high-thermal applications.
- Polyurethane:Polyurethane coatings provide excellent abrasion resistance and flexibility, finding use in applications requiring durable, protective layers.
- Acrylic:Acrylic coatings offer good weatherability and UV resistance, suitable for outdoor electrical components and general protective insulation.
Epoxy sits at the top of the volume ranking, with Silicone climbing the fastest.
Application:
Performance requirements vary significantly across different application sectors, influencing material selection for electrical insulation coatings.
- Automotive Components:Coatings for battery packs, motors, and power electronics in electric vehicles require high dielectric strength and thermal management, often needing specialized UL certifications for safety.
- Power Generation Equipment:Insulation for transformers, switchgear, and generators in power grids demands exceptional thermal stability and long-term dielectric performance, often under IEC standards.
- Electronics:Miniaturized electronics require thin-film insulation coatings that prevent electrical shorts and manage heat buildup in confined spaces.
- Industrial Machinery:Coatings for industrial machinery prioritize mechanical robustness and chemical resistance to ensure long operational lifecycles.
Market expansion is primarily driven by increasing electrification in automotive components, while power generation equipment continues to demand high-reliability solutions.
End User:
End-user industries exhibit distinct procurement patterns and regulatory landscapes for electrical insulation coatings.
- Energy:The energy sector, encompassing power generation and battery storage systems, requires coatings with robust dielectric properties and fire retardancy for safety and operational efficiency.
- Aerospace:Aerospace applications demand lightweight, high-performance insulation coatings capable of withstanding extreme temperatures and vibrations in compact electronic systems.
- Manufacturing:General manufacturing operations utilize insulation coatings for various machinery and equipment, prioritizing cost-effectiveness and broad applicability.
- Telecommunications:Telecommunications infrastructure relies on insulation coatings for protection against environmental factors and consistent signal integrity.
Demand for advanced materials is most acute in the energy and aerospace sectors, pushing innovation in coating performance.
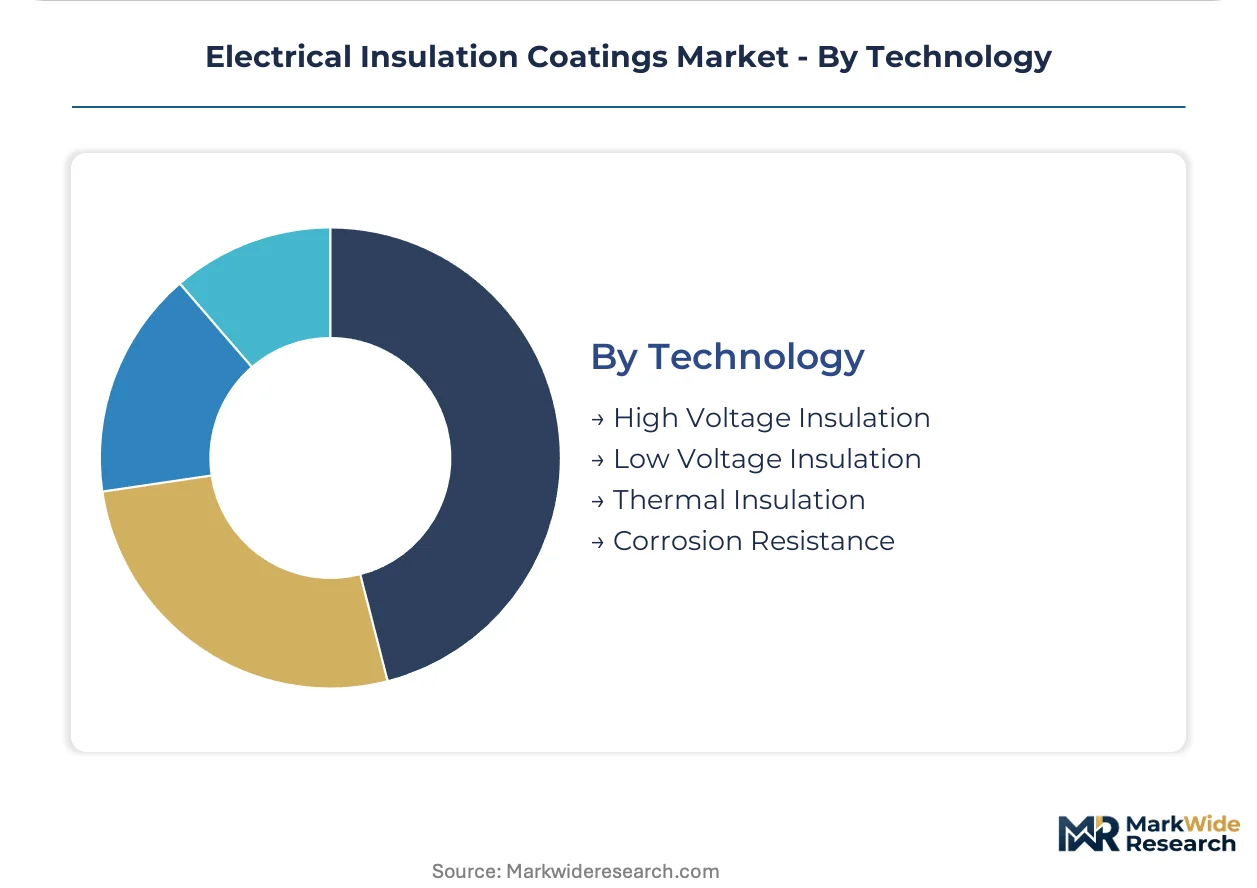
Technology:
The primary technical function of the coating dictates specific material engineering and design priorities.
- High Voltage Insulation:Coatings designed for high voltage applications require exceptional dielectric strength and partial discharge resistance to prevent breakdown in critical power electronics and grid infrastructure.
- Thermal Insulation:Thermal insulation coatings are engineered to manage heat dissipation in compact electronic devices and EV components, preventing overheating and extending component lifespan.
- Low Voltage Insulation:These coatings provide basic electrical isolation for everyday electronics and wiring, focusing on cost-efficiency and ease of application.
- Corrosion Resistance:Coatings offering corrosion resistance protect conductive substrates from environmental degradation, extending the lifespan of electrical components.
High voltage and thermal insulation technologies are critical for overall system reliability and safety in modern electrical systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global electrical insulation coatings market experiences a dynamic rebalancing of production and demand, driven partly by regulatory arbitrage where manufacturers seek optimal operating environments. Varying environmental and safety standards across jurisdictions influence investment in new capacity and material formulation strategies. This shift impacts the cost structure and supply chain resilience for high-performance coatings.
China
Electric vehicle manufacturing and advanced electronics production drive demand for insulation coatings in China. The country's dual carbon goals and GB standards push for more sustainable and high-performance material solutions. Industrial clusters in the Yangtze River Delta and Pearl River Delta are expanding capacity for specialized epoxy and silicone formulations.
Germany
Germany's robust automotive sector, particularly in electric vehicle components, and its advanced industrial machinery manufacturing require sophisticated insulation coatings. European regulations like REACH and RoHS mandate the development of halogen-free and low-VOC formulations. Production hubs in Bavaria and Baden-Württemberg are leading innovation in high-temperature silicone and epoxy systems.
United States
Modernization of the power grid infrastructure and miniaturization of electronics create significant demand for advanced electrical insulation coatings in the United States. EPA standards on volatile organic compounds influence a shift towards water-based and high-solids coating technologies. Technology clusters in Silicon Valley and manufacturing centers in Texas are adopting thin-film and multifunctional coatings for power electronics.
Japan
Japan's high-precision electronics industry and demand for reliable industrial machinery necessitate high-performance electrical insulation coatings. Strict JIS standards and corporate environmental goals promote the adoption of thermally stable and eco-friendly materials. Manufacturing zones in the Kanto and Chubu regions are specializing in advanced silicone and polyurethane coatings for demanding applications.
India
Growing industrialization and the expansion of electronics manufacturing in India are increasing the need for diverse electrical insulation coatings. India's BIS standards focus on product quality and safety, encouraging the use of certified insulation materials. Production facilities in Maharashtra and Karnataka are scaling up to meet the rising demand from automotive and power sector applications.
Electrical Insulation Coatings Market Key Industry Players
Asian producers anchor one tier of the electrical insulation coatings market, focusing on scale and cost-effectiveness, while European and North American specialists hold positions in high-performance and regulated segments. The market structure features a mix of large chemical conglomerates and specialized niche players. Strategic archetypes include diversified chemical giants, focused insulation system providers, and regional coating specialists. Dominant competitive moves involve capacity expansion for new material types and portfolio diversification to address emerging application areas like energy storage.
Global chemical engineering firms like BASF SE represent the diversified chemical giant archetype, leveraging broad expertise to serve multiple end-user requirements across various coating types. ELANTAS PDG Inc. exemplifies a specialized innovator, focusing on advanced insulation systems for demanding applications in motors and generators. PPG Industries Inc. occupies a position as a global coatings provider, competing on the strength of its extensive distribution network and product availability across diverse industries.
| Leading Market Players |
|---|
| 3M |
| Evonik Industries AG |
| Akzo Nobel N.V. |
| BASF SE |
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| ELANTAS PDG Inc. |
| Jotun A/S |
| Axalta Coating Systems LLC |
| Others |
Cost & Logistics Intelligence
Epoxy resin futures volatility directly influences electrical insulation coating costs, cascading through the manufacturing process to impact final product pricing tiers. This instability creates margin pressure for producers and affects procurement strategies for end-users.
Pricing Analysis
Distributor margins represent a significant component of the final cost for standard electrical insulation coatings. The market largely operates on a per-unit transactional model for commodity products, transitioning to contract-based long-term offtake for specialized high-performance formulations. Price differentiation stems from quality grade, specific certification levels like UL or IEC, and order volume scale. Pricing softness reflects intense competition and raw material price volatility, with industrial machinery end-users exhibiting higher price sensitivity than aerospace and energy sectors.
Supply Chain Analysis
Direct-to-OEM channels handle large-volume procurement for major automotive and electronics manufacturers, while regional distributors serve smaller industrial clients. Global production of electrical insulation coatings concentrates heavily in China and Germany, reflecting advanced manufacturing capabilities. The supply chain draws from critical raw materials such as epoxy resins and silicone polymers. A primary structural risk remains the volatility in raw material prices, creating instability for manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical insulation coatings market is evolving into a late-cycle quality story, driven by the demand-shift toward premium specifications in electrification for automotive components. This necessitates materials with superior dielectric strength and thermal stability.
For Market Incumbents: Lock in long-term supply agreements for critical raw materials like specialty silicone polymers to mitigate price volatility. Invest in capacity expansion for halogen-free epoxy and water-based polyurethane formulations, addressing evolving RoHS and EPA regulations. Deepen R&D into multifunctional coatings that combine dielectric strength with thermal conductivity. Pursue advanced UL and IEC certifications to reinforce market leadership against emerging niche players.
For New Entrants and Emerging Players: Bio-based formulations represent a technology-first wedge for market entry, addressing sustainability demands from OEMs. Target the rapidly expanding energy storage systems (BESS) segment, focusing on specialized coatings for thermal management and fire retardancy. Penetrate the Southeast Asian market by offering compliant halogen-free materials for electronics manufacturing. Differentiate through agile product development and strong regional technical support.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized innovators possessing proprietary technology in high-performance electrical insulation. The market demonstrates long-term viability, driven by sustained electrification trends and tightening global environmental regulations. Target acquisitions of companies with strong R&D capabilities in advanced silicone or multifunctional epoxy systems. Watch for increased M&A activity among diversified chemical giants seeking to expand their high-performance coatings portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Advanced Materials | Increases supply of high-performance silicone and halogen-free epoxy coatings for critical applications. |
| R&D in Multifunctional Coatings | Develops materials combining dielectric strength with thermal conductivity, simplifying device assembly. |
| Certification Standard Attainment (UL/IEC) | Ensures product safety and regulatory compliance, enabling market access for specialized applications. |
| Bio-Based Formulation Development | Addresses OEM demand for sustainable materials and aligns with corporate ESG objectives. |
| Strategic Partnerships with EV OEMs | Secures long-term contracts and integrates coating solutions into next-generation electric vehicle designs. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a robust market analysis. Primary data involved discussions with R&D directors at coating manufacturers, procurement leads at automotive OEMs, and regulatory affairs specialists. Secondary validation drew from industry association reports, government environmental agency publications, and company financial filings. This approach ensured comprehensive bottom-up and top-down triangulation of market data.
The quantitative model reconciled diverse data streams to project market dynamics across the analysis window. Segmentation dimensions modeled included product type, application, end user, technology, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends, projected growth drivers like EV production forecasts, and anticipated power grid modernization budgets. This framework provided granular insights into future market expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and raw material price volatility. The analysis reflects assumptions regarding electrification trends and environmental compliance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Polyaspartic Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Fillers and Coating Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Zero Friction Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Packaging Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
Acrylic Coating Market
Coatings
Shipping Container Coatings Market