
 High Purity Base Metals Market | 2026-2036
High Purity Base Metals Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Base Metals Market Intelligence
Semiconductor foundry procurement is pivoting toward long-term offtake contracts with certified smelters, concentrating buyer power among a dozen advanced-chip manufacturers. Codelco leverages its Chuquicamata refining complex to sustain cathode purity above 99.99% for sputtering target applications. KGHM Polska Miedź S.A. anchors European supply through its Głogów smelter, while Aluminum Corporation of China Limited dominates ingot output for substrate manufacturing.
High purity base metals are refined to impurity levels below ten parts per million, typically via electrolytic refining, zone melting, or chemical vapor transport, serving applications where trace contaminants degrade electrical conductivity, corrosion resistance, or thin-film uniformity. Electronic-grade copper leads product-type revenue due to interconnect demand in logic and memory chips, while solar-grade nickel experiences the fastest trajectory as heterojunction cell architectures replace passivated emitter designs. Aerospace-grade titanium concentrates margin pools in vacuum-arc-remelted ingots certified to single-melt specifications.
The EPA enforces emission caps on secondary smelters that elevate capital costs for domestic refiners, while REACH restricts hexavalent chromium in surface treatments and the EU AI Act imposes supply-chain traceability on metals used in high-performance computing hardware. China's SAMR enforces GB standards for rare-earth-doped alloys that compete with pure metal solutions in magnetic applications. Stakeholders must monitor purity-grade certification timelines against tightening fab qualification windows.
Market Dynamics
Semiconductor node migration below three nanometers is compressing fab qualification windows for cathode suppliers, forcing simultaneous upgrades to electrolytic refining infrastructure and traceability systems.
Growth Catalysts
- Sub-3nm node proliferation:Logic chip foundries in South Korea's Pyeongtaek corridor now mandate 99.999% copper purity for interconnect layers, pulling volume from certified Chilean and Polish smelters.
- EU AI Act traceability mandates:Supply-chain documentation requirements for high-performance computing metals are accelerating investment in blockchain-verified provenance systems across European substrate manufacturers.
- Heterojunction solar cell architectures:Nickel-based transparent conductive oxide layers are displacing silver busbars in photovoltaic manufacturing, creating parallel demand streams from solar-grade refiners.
Market Restraints
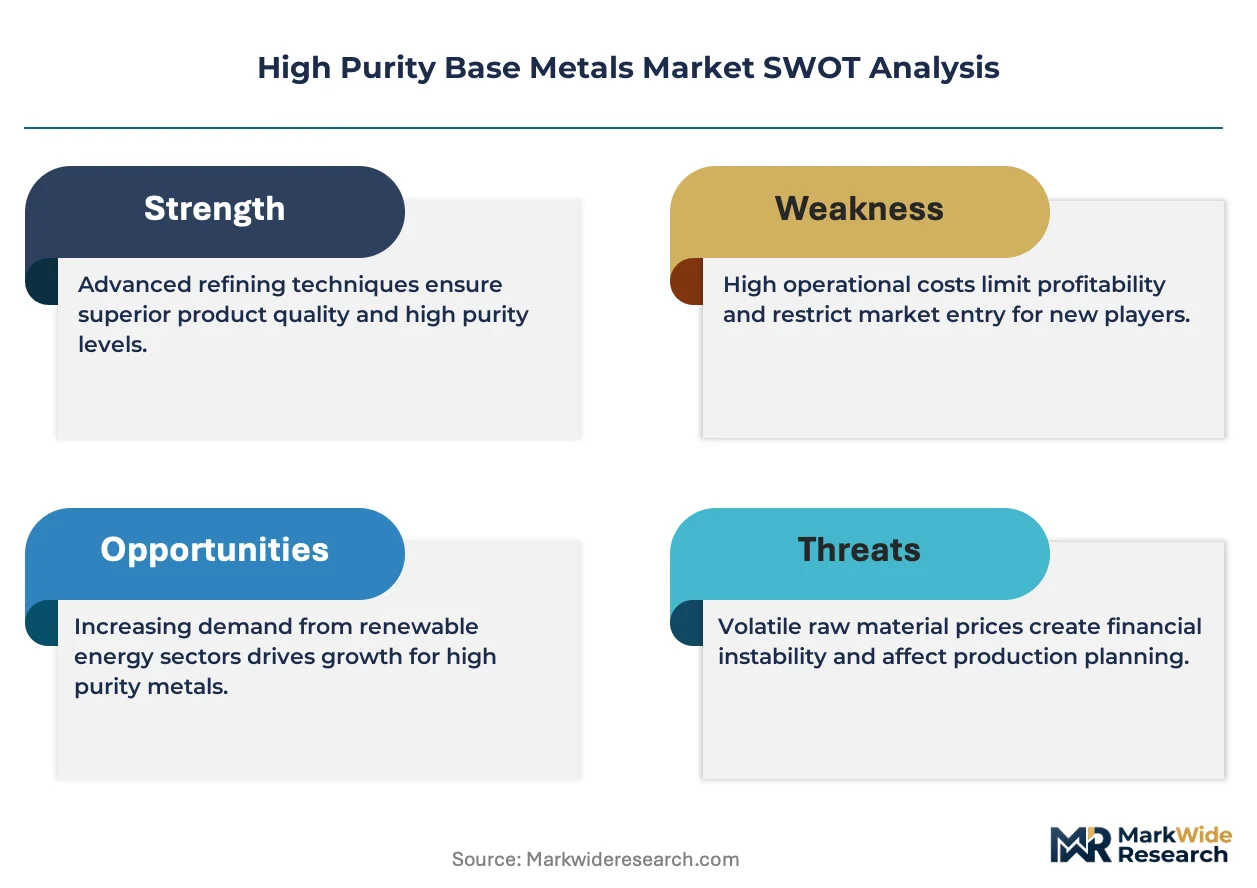
- Energy cost volatility:Electrolytic refining consumes 2,500-3,000 kWh per ton of cathode copper; European smelters face input cost spikes tied to natural gas price fluctuations.
- Smelter concentration risk:Five integrated miners control 70% of electronic-grade copper refining capacity, creating single-source vulnerability for specialty semiconductor chemical suppliers.
- Substitution by rare-earth alloys:China's GB-standardized neodymium-doped alternatives compete in magnetic applications previously served by pure nickel and cobalt.
Strategic Opportunities
- Underpenetrated Indian fabrication:India's PLI scheme for semiconductor manufacturing is attracting sputtering target producers seeking localized high-purity metal supply.
- Dual-use aerospace certification:Vacuum-arc-remelted titanium ingots meeting single-melt specifications command margin premiums from defense contractors and commercial satellite builders.
- Closed-loop urban mining:Japanese METI-endorsed recycling protocols for end-of-life electronics are enabling secondary refined metal streams with purity grades approaching primary production.
Industry Challenges
- Electrochemical engineer scarcity:Zone melting and chemical vapor transport operations require specialized technicians; training pipelines lag facility expansion timelines in Taiwan and Arizona.
- Fab qualification compression:Smelters must complete 18-month purity certification cycles while semiconductor manufacturers accelerate node roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Base Metals Market |
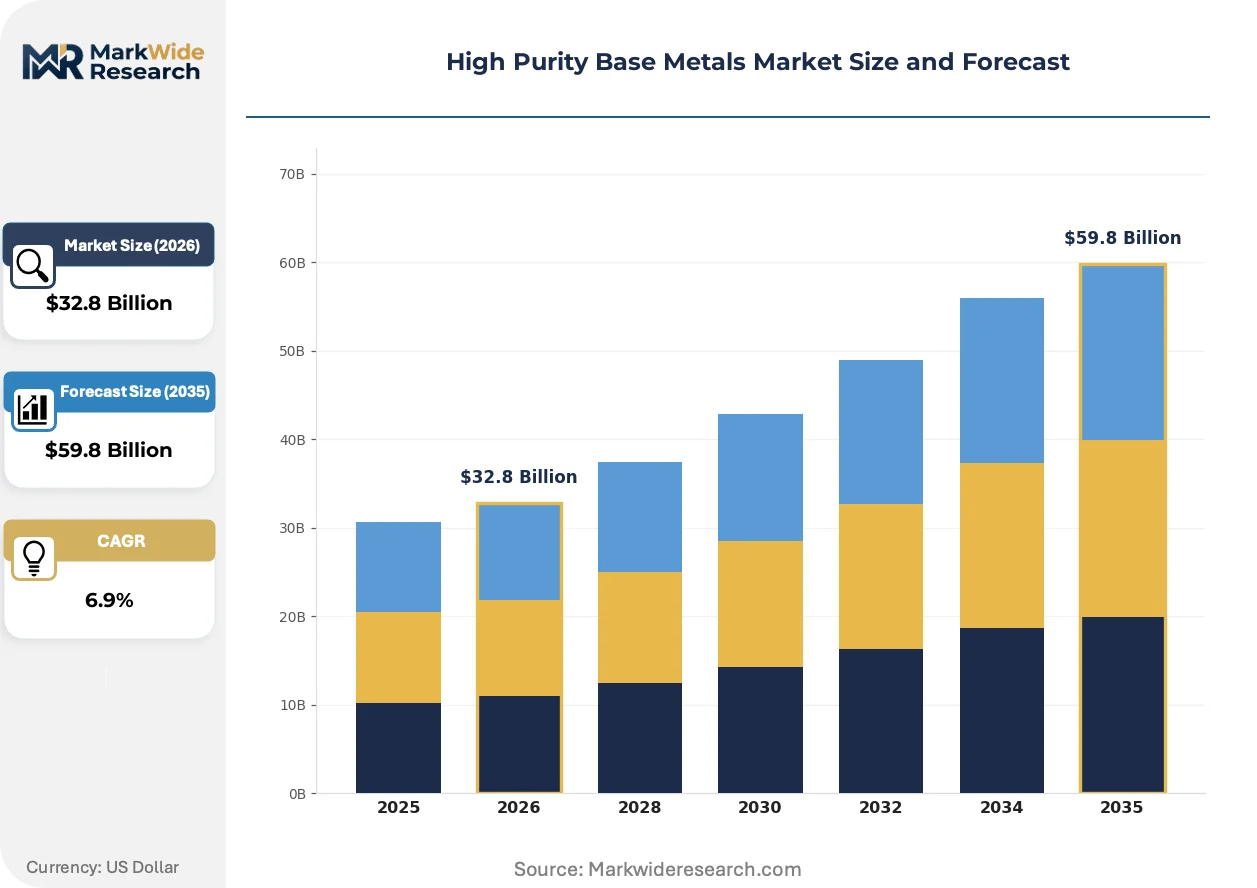
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $59.8 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper, Aluminum, Nickel, Zinc, Titanium, Chromium Purity Grade: 99.9%, 99.99%, 99.999%, Electronic Grade, Solar Grade, Aerospace Grade End Use Industry: Electronics, Aerospace & Defense, Renewable Energy, Chemical Manufacturing, Semiconductor Fabrication, Precision Engineering Form: Ingots, Foils, Powders, Rods, Sheets, Plates |
| Companies Covered | Codelco, KGHM Polska Miedź S.A., Aluminum Corporation of China Limited, Nyrstar, Norsk Hydro ASA, BHP, Hindalco Industries, Rio Tinto, Boliden Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Base Metals Market Strategic Shifts & Innovations
Zone refining automation and AI-driven impurity detection are compressing the gap between laboratory-grade and production-scale metal purification, enabling real-time process control previously confined to research facilities.
Zone melting technology for ultra-high-purity aluminum is converging with atomic layer deposition requirements in gate-all-around transistor manufacturing. Samsung Foundry and TSMC have both qualified 6N-grade aluminum suppliers for their 2025-2026 process nodes. This convergence is eliminating the historical separation between sputtering target producers and semiconductor chemical suppliers.
REACH restrictions on hexavalent chromium surface treatments are forcing nickel and copper processors to adopt trivalent passivation chemistries. The industrial consequence is a 12-18 month reformulation cycle for plating baths used in leadframe manufacturing. German automotive electronics suppliers and Dutch semiconductor equipment builders are most affected, with some relocating surface treatment steps to non-EU jurisdictions.
Long-term offtake contracting is displacing spot market purchasing among advanced-chip manufacturers. Foundries now secure 5-7 year supply agreements directly with certified smelters, bypassing traditional metal traders and merchant banks. This pattern is most visible in Taiwan's Hsinchu Science Park, where MediaTek and GlobalFoundries have both executed direct cathode supply contracts with South American refiners.
High Purity Base Metals Market Segmentation
Purity thresholds and form factor specifications dictate supplier qualification timelines across semiconductor, aerospace, and renewable energy value chains. Buyers segment procurement portfolios by certification grade rather than commodity pricing, creating parallel supply channels for electronic-grade versus industrial-grade material streams.
Product Type:
Application-specific conductivity and corrosion requirements drive metal selection in advanced manufacturing workflows.
- Copper:Refined to 99.999% purity via electrolytic processing for interconnect layers in sub-3nm logic chips. Samsung Foundry and TSMC procurement in South Korea's Pyeongtaek corridor and Taiwan's Hsinchu Science Park now mandate cathode certification above 5N grade.
- Nickel:Solar-grade refinement for heterojunction photovoltaic cells displaces silver busbars in transparent conductive oxide layers. Demand concentrates in Chinese solar cell manufacturing clusters where SAMR-enforced GB standards compete with pure metal solutions.
- Aluminum:Zone-melted 6N-grade supply for gate-all-around transistor gate stacks.
- Zinc:High-purity anodes for corrosion protection in offshore wind turbine foundations.
- Titanium:Vacuum-arc-remelted ingots certified to single-melt aerospace specifications.
- Chromium:REACH-restricted hexavalent alternatives forcing trivalent passivation chemistry adoption in European leadframe manufacturing.
Volume sits with copper cathode procurement; growth tilts toward nickel for photovoltaic architectures.
Purity Grade:
Certification tiers separate commodity metal traders from qualified semiconductor chemical suppliers.
- 99.999% (5N):Baseline threshold for sputtering target production in advanced logic foundries. Codelco's Chuquicamata complex and KGHM's Głogów smelter anchor certified output for this tier.
- Electronic Grade:Traceability documentation mandated by EU AI Act for high-performance computing hardware supply chains. Blockchain-verified provenance systems now accompany 5-7 year offtake contracts between Taiwanese foundries and South American refiners.
- 99.9%:Standard industrial purity for general electrical applications.
- 99.99%:Intermediate tier for automotive electronics and industrial sensors.
- Solar Grade:Nickel-specific certification for heterojunction cell manufacturing.
- Aerospace Grade:Vacuum-arc-remelted titanium meeting single-melt defense contractor specifications.
Procurement volume clusters at 5N purity; qualification pipelines are expanding fastest for electronic-grade certification.
End Use Industry:
Fab qualification windows and defense procurement cycles create divergent buyer timelines.
- Semiconductor Fabrication:Node migration below three nanometers compresses smelter certification cycles to 18 months while accelerating interconnect layer material requirements. Direct cathode contracts now bypass traditional metal traders in Taiwan's Hsinchu Science Park.
- Renewable Energy:Heterojunction solar architectures pull nickel-based transparent conductive oxides into volume manufacturing. Chinese solar cell producers drive specification development as passivated emitter designs phase out.
- Electronics:Leadframe and substrate manufacturing with REACH-compliant surface treatments.
- Aerospace & Defense:Dual-use titanium ingot certification for commercial satellite and defense contractor supply.
- Chemical Manufacturing:Catalyst-grade metal requirements for specialty chemical production.
- Precision Engineering:Ultra-high-purity aluminum for atomic layer deposition equipment components.
Revenue concentration favors semiconductor fabrication; steepest expansion trajectory belongs to renewable energy applications.
Form:
Downstream processing economics favor specific geometries for thin-film deposition versus bulk structural applications.
- Ingots:Primary feedstock for vacuum-arc remelting and zone refining operations. Aerospace-grade titanium and electronic-grade aluminum both originate from certified ingot casting before secondary purification.
- Foils:Sputtering target substrates and flexible electronics substrates. Samsung Foundry and TSMC qualification of 6N aluminum foil suppliers eliminated historical separation between target producers and chemical suppliers.
- Powders:Additive manufacturing feedstock and powder metallurgy applications.
- Rods:Electrical discharge machining electrodes and welding filler materials.
- Sheets:Shielding and heat spreader applications in computing hardware.
- Plates:Structural components in chemical processing equipment.
Ingots dominate primary refining output; foil specifications are gaining share fastest in semiconductor target manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for high purity base metals concentrates in East Asian electronics manufacturing clusters, where semiconductor fabrication and solar cell production drive procurement volumes. South Korea's Pyeongtaek corridor and Taiwan's Hsinchu Science Park anchor cathode consumption for sub-3nm logic chips. Chinese solar manufacturers and Indian emerging fabs are reshaping regional supply dynamics.
China
Domestic solar cell producers drive nickel demand for heterojunction transparent conductive oxide layers. SAMR enforces GB standards for rare-earth-doped alloys that compete with pure metal magnetic applications. The Yangtze River Delta hosts aluminum zone-refining operations serving gate-all-around transistor gate stack requirements.
South Korea
Samsung Foundry and SK Hynix mandate 5N-grade copper cathodes for interconnect layers at nodes below three nanometers. The Pyeongtaek semiconductor corridor concentrates sputtering target consumption and direct smelter offtake contracting. Local procurement bypasses traditional metal traders through 5-7 year supply agreements.
Taiwan
TSMC and MediaTek execute direct cathode contracts with South American refiners, eliminating merchant bank intermediaries. The Hsinchu Science Park anchors 6N aluminum foil qualification for atomic layer deposition equipment. EPA-equivalent emissions oversight shapes secondary smelter investment decisions.
United States
Arizona and Texas fab construction compresses electrochemical engineer training pipelines against facility expansion timelines. EPA emission caps on secondary smelters elevate capital costs for domestic electronic-grade copper refining. The Southwest concentrates emerging substrate manufacturing with blockchain-verified provenance requirements.
Poland
KGHM's Głogów smelter anchors European electronic-grade copper supply for REACH-compliant semiconductor chemical suppliers. The EU AI Act traceability mandates accelerate investment in provenance systems across Polish-German supply corridors. Lower Silesia hosts vacuum-arc remelting capacity for aerospace-grade titanium certification.
High Purity Base Metals Market Key Industry Players
Chilean and Polish producers anchor one tier; Chinese state-owned enterprises and Australian diversified miners hold scale positions in adjacent metal streams. Five integrated miners control roughly seventy percent of electronic-grade copper refining capacity, creating tiered supply access based on certification status. Strategic archetypes include integrated mining-smelting conglomerates, national champions with captive refining infrastructure, and diversified base metals traders with purification partnerships. Capacity expansion and long-term offtake contracting dominate competitive moves as fabs accelerate direct supplier relationships.
Among Chilean state-owned producers, Codelco exemplifies the integrated mining-smelter archetype through its Chuquicamata refining complex. KGHM Polska Miedź S.A. occupies a parallel position in European supply architecture. Aluminum Corporation of China Limited represents the state-backed scale tier with ingot output dominance for substrate manufacturing clusters.
| Leading Market Players |
|---|
| Codelco |
| KGHM Polska Miedź S.A. |
| Aluminum Corporation of China Limited |
| Nyrstar |
| Norsk Hydro ASA |
| BHP |
| Hindalco Industries |
| Rio Tinto |
| Boliden Group |
| Others |
Cost & Logistics Intelligence
Advanced-chip manufacturers concentrate procurement power through 5-7 year direct cathode contracts, locking in long-term offtake pricing that displaces spot market volatility. This buyer concentration forces certified smelters to absorb electrolytic refining energy costs while competing on purity certification timelines.
Pricing Analysis
Volume procurement of 5N-grade copper cathodes commands thin margins, while aerospace-grade titanium and 6N aluminum foils capture premium spreads. Price differentiation rests on certification grade and fab qualification status, with electronic-grade premiums widening as node migration accelerates. Cost compression in standard-grade industrial metal is intensifying because European smelters face natural gas input spikes. Solar-grade nickel buyers exhibit highest price sensitivity; semiconductor foundries show least sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Dual-sourcing mandates from Samsung Foundry and TSMC require qualified suppliers in both Chile and Poland to mitigate single-source vulnerability. Raw material flows draw from Chuquicamata mining complexes, Głogów concentrate streams, and Yangtze River Delta zone-refining operations. Supply chain risk centers on electrochemical engineer scarcity compressing facility expansion timelines in Taiwan and Arizona. Distribution runs through direct smelter-foundry contracts that bypass traditional metal traders and merchant banking intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over electrolytic refining infrastructure and downstream fab qualification relationships determine competitive position. Players are pursuing captive smelter capacity to secure purity certification pipelines.
For Market Incumbents: Acquire zone-refining and vacuum-arc remelting assets to defend against rare-earth alloy substitution in magnetic applications. Expand electrolytic refining capacity in Poland and Chile to capture Indian PLI scheme demand before qualification windows close. Certification investment in 6N aluminum production represents the critical defensive lever against Chinese state-backed competitors. For New Entrants and Emerging Players: Indian semiconductor fabrication clusters present the most penetrable white-space target, with sputtering target producers seeking localized high-purity metal supply. Solar-grade nickel for heterojunction architectures offers parallel entry path with shorter qualification cycles than semiconductor grades. Go-to-market execution should emphasize blockchain-verified provenance systems to satisfy EU AI Act traceability mandates. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with existing aerospace certification infrastructure that can extend into semiconductor-grade production. Long-term viability hinges on 5-10 year fab offtake contract visibility rather than spot market exposure. Watch for EPA emission cap enforcement on US secondary smelters as inflection signal for domestic supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Codelco's Chuquicamata complex secures cathode purity above 5N grade for sputtering targets. |
| Long-term Supply Agreement Execution | Direct 5-7 year cathode contracts in Taiwan's Hsinchu Science Park eliminate merchant bank intermediaries. |
| Certification Investment in 6N Aluminum | Samsung Foundry and TSMC qualification converges target producers with semiconductor chemical suppliers. |
| Geographic Expansion to India | PLI scheme for semiconductor manufacturing attracts localized high-purity metal supply investment. |
| Closed-loop Urban Mining Protocol | Japanese METI-endorsed recycling enables secondary refined metal streams approaching primary production purity. |
Research Approach
Multi-period observation of fab qualification timelines, smelter certification cycles, and offtake contract structures anchored the trend analysis, supplemented by interviews with electrolytic refining plant managers, semiconductor foundry procurement leads, sputtering target producers, and aerospace-grade titanium certification specialists. Secondary validation drew from SEC filings of integrated mining-smelting conglomerates, EPA emission enforcement records, EU AI Act traceability documentation requirements, and SAMR GB standards publications. Bottom-up volume modeling across purity grades and end-use segments triangulated against top-down smelter capacity assessments.
Segment-weighting applied differential growth assumptions across electronic-grade, solar-grade, and aerospace-grade certification tiers, with purity thresholds and form factor specifications driving allocation coefficients. The analytical framework modeled end-use industry demand, regional production hub concentration, and form factor evolution across the projection horizon. CAGRs derived from electrolytic refining capacity expansion schedules, node migration roadmaps from South Korea's Pyeongtaek corridor, and heterojunction solar cell architecture penetration curves.
Revisions become necessary when semiconductor node roadmaps accelerate beyond 18-month smelter qualification windows, or when EPA emission caps tighten secondary smelter economics materially. Deviation in rare-earth alloy substitution rates for magnetic applications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
US Ferrochrome Market
Metals
Vietnam Aluminum Market
Metals
Global Precious Metal Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Lithium Tungstate Market
Metals
North America Electrical Steel Market
Metals
Bearing Steel Market
Metals
Hafnium Foil Market
Metals
Amorphous Metal Cores Market
Metals
Aluminum Wire Market
Metals
GCC Metal Forging Market
Metals
Europe Aluminium Wire Rod Market
Metals
Grain Oriented Electrical Steel Market
Metals
Barium Market
Metals
Aluminum Sheet Market
Metals
China Neodymium Iron Boron Magnet Market