
 Aluminum Sheet Market | 2026-2036
Aluminum Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Sheet Market Analytics
AS9100 certification for aerospace-grade aluminum sheet is reorganizing supplier tiers across the value chain, forcing secondary rollers to upgrade metallurgical controls or exit premium segments. Novelis Inc. leverages its closed-loop recycling network to secure primary aluminum supply for automotive body sheet programs. Hindalco Industries Limited anchors South Asian demand through integrated smelter-rolling complexes serving construction and packaging customers. Alcoa Corporation competes on bauxite-to-sheet traceability, sustaining margins in regulated European and North American markets.
Aluminum sheet denotes flat-rolled aluminum alloy products manufactured through hot or cold rolling, typically ranging from 0.2 mm to 6.35 mm in thickness, with specific tempers achieved through controlled thermal processing to meet strength, formability, and corrosion resistance requirements. These sheets serve as critical inputs for lightweight structural panels, thermal management systems, and barrier packaging where the metal's high strength-to-weight ratio and infinite recyclability deliver functional advantage. Cold rolled sheet commands premium positioning in aerospace and precision automotive applications where tight dimensional tolerances and superior surface finish justify higher conversion margins. Hot rolled sheet dominates construction and industrial fabrication volumes, benefiting from lower unit economics and broader gauge availability. Grade 6061 aluminum sheet is gaining share in structural applications requiring weldability and moderate strength, displacing some legacy steel designs in mass transit infrastructure.
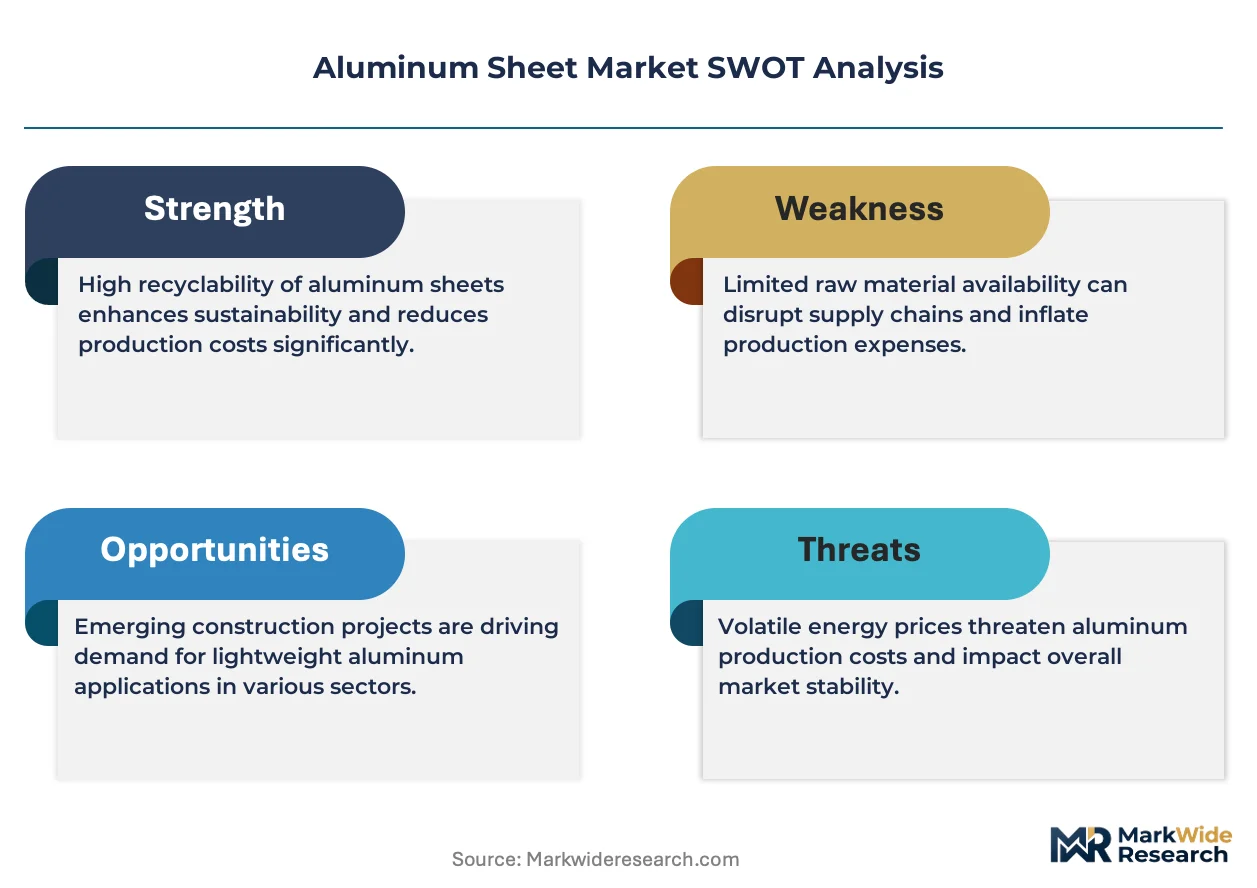
The EPA enforces emissions benchmarks that incentivize automotive lightweighting, directly expanding qualified aluminum sheet demand for body panels and chassis components. The EU Green Deal and associated CBAM framework impose carbon intensity disclosures on imported aluminum products, reshaping sourcing strategies for European fabricators and their international suppliers. China's MEE enforces dual carbon goals that constrain primary smelting capacity, pushing domestic rollers toward scrap-based production models for sheet grades. Stakeholders must monitor evolving alloy qualification protocols and carbon border adjustments to preserve market access and margin structures across regional supply chains.
Market Dynamics
Automotive OEMs are mandating aluminum sheet content in electric vehicle platforms to achieve weight reduction targets, forcing supply chain reconfiguration toward AS9100-certified mills and closed-loop recycling networks.
Growth Catalysts
- EPA Emissions Benchmarks:US automotive lightweighting mandates expand qualified aluminum sheet demand for body panels and chassis components.
- China's Smelter-Roller Integration:Domestic capacity additions for transportation-grade sheet accelerate supply availability for EV manufacturers.
- EU F-Gas Regulation:Material traceability requirements for rolled aluminum products tighten, favoring certified suppliers with integrated bauxite-to-sheet documentation.
Market Restraints
- Primary Aluminum Input Volatility:LME-linked ingot costs create margin compression for non-integrated rollers lacking captive smelter supply.
- China Supply Concentration:Dual carbon goals enforced by MEE constrain primary smelting capacity, limiting export availability of high-purity sheet grades.
- Steel Substitution Threat:Advanced high-strength steel formulations compete in cost-sensitive construction and industrial fabrication segments.
Strategic Opportunities
- India Construction Uptake:Integrated smelter-rolling complexes serving infrastructure projects offer penetration potential for Grade 6061 structural sheet.
- EU CBAM Carbon Border Adjustment:Carbon intensity disclosure requirements create first-mover advantage for scrap-based production models with verified low-carbon credentials.
- Aerospace Thermal Management Convergence:Battery pack cooling plates and avionics heat sinks merge specification requirements, enabling cross-segment alloy qualification.
Industry Challenges
- AS9100 Certification Timeline:Aerospace-grade metallurgical control upgrades demand 18-24 month qualification periods, excluding secondary rollers from premium contract bidding.
- Scrap Sorting Technology Gap:Alloy-specific separation capabilities lag behind closed-loop recycling ambitions, contaminating high-grade sheet feedstock streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Sheet Market |
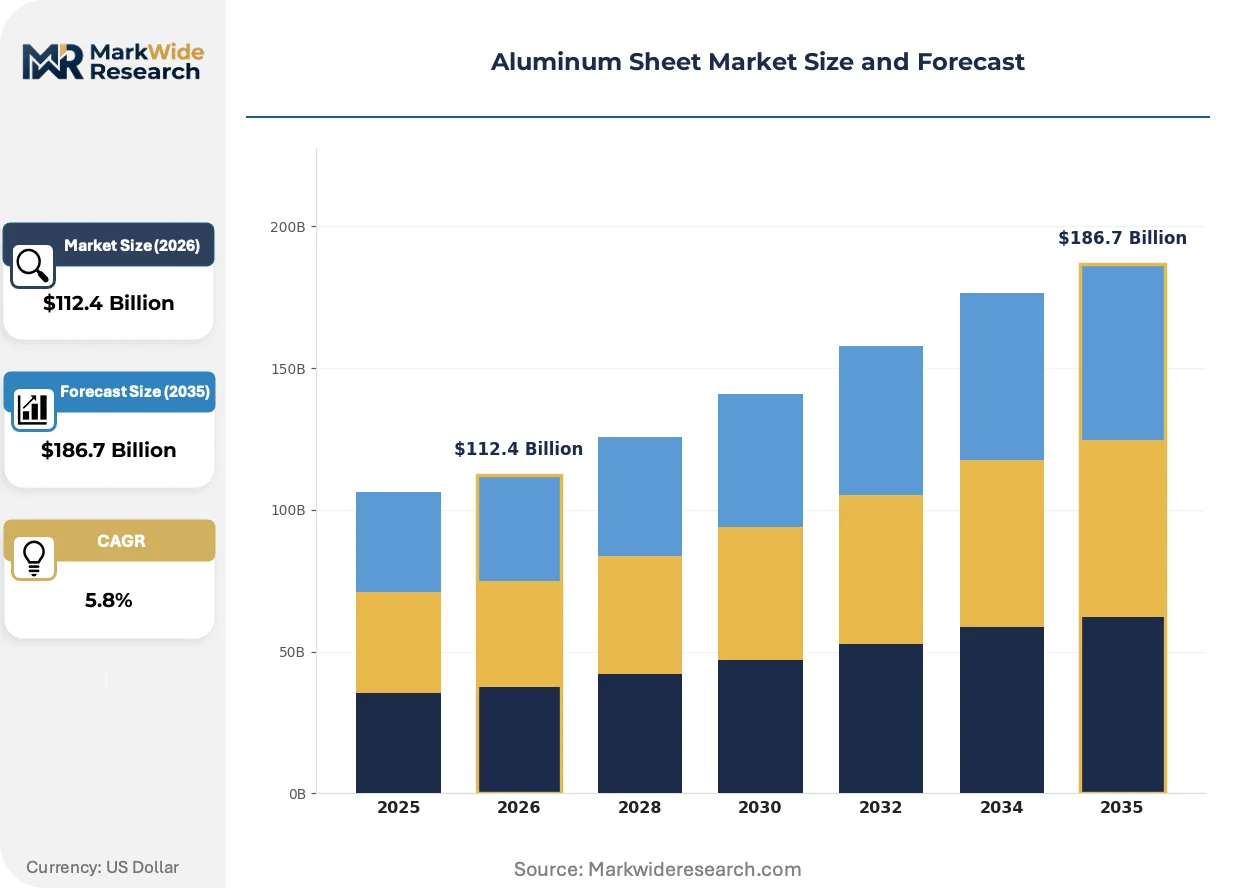
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled, Cold Rolled, Anodized, Painted Application: Aerospace, Automotive Components, Packaging, Construction End User: Manufacturers, Contractors, Retailers, Distributors Grade: 3003, 5052, 6061, 7075 |
| Companies Covered | Novelis Inc., Hindalco Industries Limited, Alcoa Corporation, Arconic Corporation, Kaiser Aluminum Corporation, Constellium SE, UACJ Corporation, Norsk Hydro ASA, JW Aluminum Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Sheet Market Evolving Landscape
Specification convergence across automotive and aerospace segments is compressing alloy development cycles while digitizing supply chain traceability. Three developments warrant monitoring.
Continuous casting technology for thin-gauge aluminum sheet is miniaturizing the minimum viable production scale for automotive body sheet programs. Tier-2 fabricators in Germany and Michigan are piloting these systems to bypass traditional hot mill investments. The technology is miniaturizing capital barriers that previously locked premium sheet supply to billion-dollar integrated complexes.
REACH compliance frameworks are extending substance restriction lists to rolled aluminum surface treatments and lubricant residues. European fabricators now face reformulation mandates for rolling oils and passivation chemistries. Cold rolled sheet destined for food packaging and medical barrier applications bears the highest compliance burden, with German and French regulators conducting expanded facility audits.
Buyers are consolidating qualified supplier lists around carbon disclosure capabilities, replacing spot-market purchasing with multi-year offtake agreements tied to verified emissions data. Tier-1 automotive stamping operations in Stuttgart, Detroit, and Shanghai now require quarterly carbon intensity reports from aluminum sheet vendors. This behavioral shift favors integrated producers with bauxite mine-to-mill traceability over merchant rollers lacking upstream asset control.
Aluminum Sheet Market Segmentation
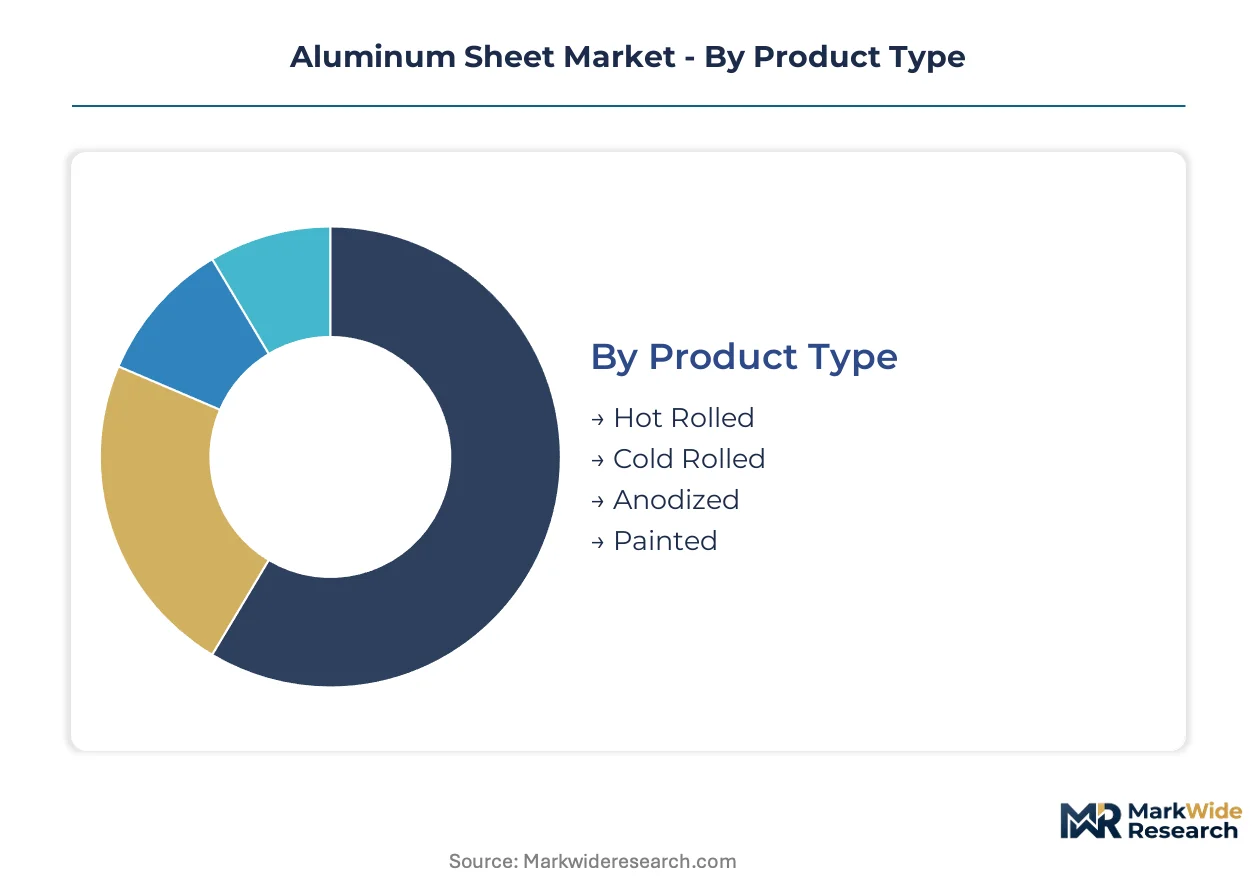
Aluminum sheet segmentation reveals divergent margin structures across processing methods and end-use specifications. Understanding these divides helps suppliers align metallurgical capabilities with buyer qualification requirements and regional regulatory pressures.
Product Type:
Domestic consumption concentrates in hot rolled and cold rolled grades serving construction and automotive stamping operations across Germany, China, and the United States. Export flows favor higher-value cold rolled and surface-treated products bound for aerospace fabricators in France and precision automotive plants in Japan.
- Hot Rolled:Produced through elevated-temperature rolling above recrystallization thresholds, yielding broader gauge tolerance and lower unit economics. Demand clusters in Chinese infrastructure projects and US commercial construction where cost sensitivity overrides surface finish requirements.
- Cold Rolled:Manufactured below recrystallization temperatures to achieve tight dimensional control and superior surface quality. German and Japanese automotive OEMs specify these grades for exposed body panels requiring Class A surface finish and precise formability.
- Anodized:Electrochemically enhanced oxide layers provide corrosion resistance and decorative finishes for architectural applications.
- Painted:Pre-coated sheets eliminate downstream finishing steps for appliance housings and building cladding systems.
Hot rolled commands the established base. The steepest expansion runs through cold rolled grades qualifying for electric vehicle body-in-white programs.
Application:
Margin tiers separate aerospace and automotive specifications demanding AS9100 certification from construction volumes competing on delivered cost per ton.
- Aerospace:Stringent fatigue resistance and damage tolerance specifications govern alloy selection and heat treatment protocols. French and US airframe manufacturers source exclusively from mills with Nadcap-accredited thermal processing capabilities.
- Automotive Components:Stamping-grade sheets require controlled earing behavior and consistent mechanical properties across coil lengths. Detroit and Stuttgart stamping operations now mandate quarterly carbon intensity disclosures from aluminum vendors.
- Packaging:Thin-gauge products for food and beverage containers prioritize surface cleanliness and lacquer adhesion properties.
- Construction:Structural and architectural applications emphasize weldability and atmospheric corrosion resistance over precision tolerances.
Aerospace retains premium positioning. Automotive components are gaining share fastest as EV platforms displace steel body structures.
End User:
Direct procurement patterns split between integrated manufacturers with metallurgical expertise and intermediaries serving fragmented fabrication bases.
- Manufacturers:Tier-1 automotive and aerospace OEMs negotiate multi-year offtake agreements tied to verified emissions data and alloy qualification protocols.
- Contractors:Construction sector buyers purchase through distributor networks with limited specification leverage.
- Retailers:Small-volume service centers stock standard gauges for maintenance and repair applications.
- Distributors:Merchant intermediaries consolidate fragmented demand from job shops and secondary fabricators.
Manufacturers anchor volume commitments. Distributors are expanding most quickly in emerging markets lacking integrated mill presence.
Grade:
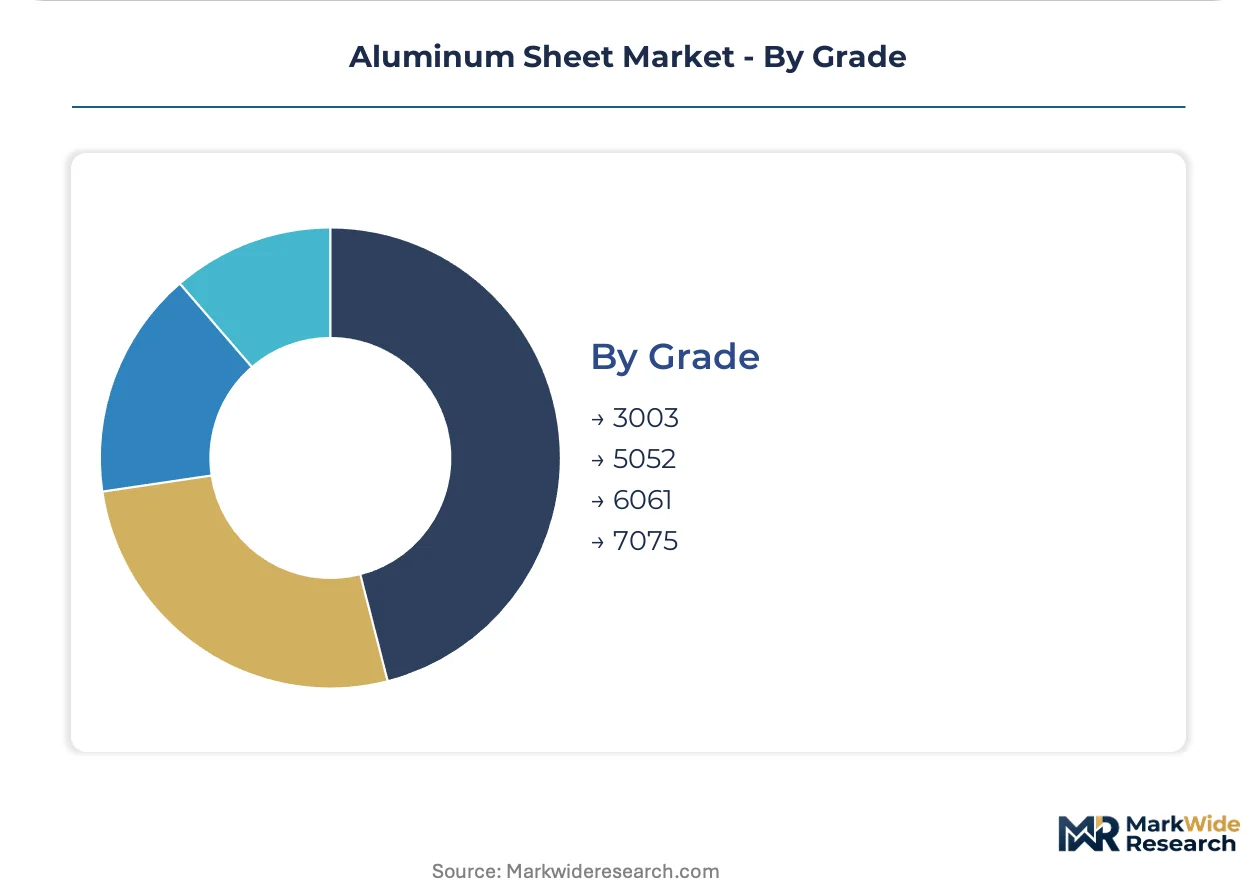
Alloy selection traces directly to strength-to-weight requirements and corrosion exposure conditions across target applications.
- 3003:Manganese-alloyed non-heat-treatable grade offering excellent formability and moderate strength. Food packaging and heat exchanger manufacturers in Japan and South Korea specify this grade for deep-drawn components.
- 5052:Magnesium-bearing alloy delivering superior marine corrosion resistance and weldability. Norwegian and Greek shipbuilders source these sheets for hull structures and deck applications.
- 6061:Heat-treatable magnesium-silicide system balancing strength, machinability, and corrosion resistance. Indian infrastructure projects specify this grade for mass transit structural extrusions and bridge components.
- 7075:Zinc-magnesium-copper alloy achieving the highest strength levels in wrought aluminum systems. US and Israeli defense contractors specify these sheets for airframe structures and armor applications.
3003 holds the volume base. The steepest climb tracks 6061 as structural engineers substitute aluminum for steel in transportation infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive stamping operations in Stuttgart, Detroit, and Shanghai anchor procurement concentration for transportation-grade aluminum sheet, with EV body-in-white programs driving qualified supplier consolidation around certified mills with carbon disclosure capabilities.
United States
EPA emissions benchmarks compel Detroit automakers to expand aluminum sheet content in electric truck and SUV platforms. The Inflation Reduction Act domestic content provisions incentivize sourcing from mills with verified low-carbon production models. Stamping clusters in Michigan and Ohio are reconfiguring supply chains around closed-loop recycling networks with quarterly emissions reporting.
Germany
EU F-Gas Regulation and REACH compliance frameworks enforce material traceability for rolled aluminum products bound for automotive and aerospace fabricators. The CBAM carbon border adjustment mechanism pressures Stuttgart-based OEMs to document bauxite-to-sheet emissions intensity. Bavarian rolling mills are upgrading metallurgical controls to preserve premium contract access.
China
Domestic smelter-to-roller integration accelerates capacity additions for transportation-grade sheet serving BYD and Tesla Shanghai operations. MEE dual carbon goals constrain primary smelting capacity, pushing rollers toward scrap-based production models. Yangtze River Delta clusters concentrate high-purity sheet output for battery pack cooling plates and EV structural components.
India
Integrated smelter-rolling complexes in Odisha and Gujarat serve infrastructure projects specifying Grade 6061 structural sheet for mass transit and bridge applications. BIS certification requirements tighten alloy qualification protocols for construction-grade products. Mumbai-Pune industrial corridors attract downstream fabrication investments linked to domestic sheet supply.
Japan
Precision automotive plants in Nagoya and Toyota City specify cold rolled grades with Class A surface finish requirements for exposed body panels. METI carbon neutrality roadmaps pressure mills to disclose Scope 3 emissions across coil supply chains. Kansai-region fabricators consolidate qualified supplier lists around vendors with verified low-carbon credentials.
Aluminum Sheet Market Competitive Landscape
Player mix skews toward integrated aluminum conglomerates with captive smelter supply and closed-loop recycling infrastructure. Secondary merchant rollers face margin compression from LME-linked ingot volatility and AS9100 certification barriers. Three archetypes dominate: bauxite-to-sheet integrated majors, scrap-based recycling specialists, and regional construction-grade suppliers. Competitive moves concentrate on backward integration into primary aluminum supply and multi-year offtake agreements tied to carbon intensity disclosures.
Among North American integrated producers, Alcoa Corporation and Kaiser Aluminum Corporation exemplify the bauxite-to-sheet traceability archetype, securing positioning in regulated markets requiring mine-to-mill documentation. Novelis Inc. occupies a distinctive position as a recycling-centric operator leveraging closed-loop networks to serve automotive body sheet programs. Constellium SE and UACJ Corporation represent the aerospace-automotive cross-segment qualification strategy, spanning Nadcap-accredited thermal processing and EV platform alloy development. Norsk Hydro ASA anchors European low-carbon positioning with verified emissions data aligned to CBAM requirements.
| Leading Market Players |
|---|
| Novelis Inc. |
| Hindalco Industries Limited |
| Alcoa Corporation |
| Arconic Corporation |
| Kaiser Aluminum Corporation |
| Constellium SE |
| UACJ Corporation |
| Norsk Hydro ASA |
| JW Aluminum Company |
| Others |
Value Network & Pricing Analysis
Ninety-day coil inventory cycles at Yangtze River Delta rolling mills concentrate pricing power among integrated producers with captive smelter supply, while LME-linked ingot volatility squeezes merchant rollers lacking upstream bauxite control. This lead-time compression favors AS9100-certified mills commanding premium contract terms from Stuttgart and Detroit stamping operations.
Pricing Analysis
Cost-plus contracts indexed to LME primary aluminum ingot benchmarks dominate transaction structures, with quarterly price adjustments tethering conversion margins to volatile raw material swings. Price differentiation separates AS9100-certified aerospace grades from construction-grade hot rolled sheet, with carbon disclosure capabilities emerging as a tiering mechanism in automotive procurement. Pricing pressure stems from China's MEE dual carbon goals constraining high-purity primary smelting capacity. Construction contractors exhibit highest price sensitivity, while aerospace OEMs prioritize qualification security over unit cost.
Supply Chain Analysis
Inventory compression to sixty-day cycles at German automotive stamping plants reflects just-in-time coordination with Bavarian rolling mills serving Stuttgart OEMs. Supply concentrates in China, Germany, and the United States, with bauxite-to-sheet integration anchoring cost structures. Raw material dependencies center on alumina refining capacity, primary smelter output, and alloy-specific scrap streams. Tariff exposure on Chinese semi-finished products creates structural risk for European fabricators. Distribution runs through mill-direct contracts for Tier-1 automotive and aerospace OEMs, with merchant distributors serving fragmented construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum sheet demand sits in early-cycle expansion as EV body-in-white programs displace steel platforms, with automotive OEM lightweighting mandates accelerating qualified supplier consolidation around certified mills.
For Market Incumbents: Fortify backward integration into primary aluminum supply or captive scrap sorting infrastructure to defend margins against LME volatility and AS9100 certification barriers. Lock multi-year offtake agreements with quarterly carbon intensity disclosures to secure positioning against EU CBAM compliance requirements. Prioritize metallurgical control upgrades for aerospace-grade qualification timelines. For New Entrants and Emerging Players: Differentiate on scrap-based production models with verified low-carbon credentials to exploit EU carbon border adjustment first-mover advantages. Target India's Grade 6061 structural sheet segment for mass transit infrastructure, where BIS certification requirements remain less stringent than aerospace tiers. Pursue continuous casting technology pilots to bypass billion-dollar hot mill capital barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with underperforming rolled products divisions lacking EV platform qualification. Long-term viability hinges on bauxite-to-sheet traceability and closed-loop recycling network density. Watch for AS9100 certification backlog clearance as inflection signal for premium segment access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Smelting | Captive alumina supply insulates margins from LME volatility for German and Chinese integrated producers. |
| AS9100 Certification Investment | Nadcap-accredited thermal processing unlocks aerospace contract bidding against Arconic and Constellium positions. |
| Closed-Loop Recycling Network Expansion | Scrap-based production models align with EU CBAM carbon intensity disclosure requirements for Stuttgart OEMs. |
| Continuous Casting Technology Deployment | Miniaturized production scales enable Tier-2 fabricator entry into automotive body sheet programs. |
| Multi-Year Carbon-Linked Offtake Agreements | Quarterly emissions reporting secures Tier-1 automotive procurement from Detroit and Shanghai stamping clusters. |
Research Methodology
Cross-validation between primary interviews with rolling mill operations managers, automotive Tier-1 procurement directors, and aerospace quality assurance leads anchors the qualitative findings against secondary validation from customs trade data, SEC 10-K filings, and ECHA REACH substance restriction updates. Bottom-up coil shipment analysis triangulates with top-down smelter capacity assessments across the modeling period.
Sensitivity analysis around LME price bands and carbon border adjustment implementation timelines shapes the analytical framework. Segmentation dimensions include processing method, alloy grade, end-use application, and regional production hub. CAGRs derive from installed capacity expansion schedules and EV platform aluminum content trajectories, with scrap availability curves and dual carbon policy enforcement serving as industry-specific forecast inputs.
Material uncertainties — primary smelter curtailment orders, alloy-specific scrap contamination rates, and AS9100 certification timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions around regulatory enforcement intensity and automotive lightweighting penetration curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Industrial Metal Strips Market
Metals
Steel Casting Market
Metals
Silico Manganese Market
Metals
Metallurgical Silicon Market
Metals
Steel Drums and Ibcs Market
Metals
Ferrosilicon Magnesium Market
Metals
Global Bronze Market
Metals
Europe Metal Service Centers Market
Metals
Copper Smelting Market
Metals
Metal Powder Market
Metals
Europe Metal Casting Market
Metals
Europe Aluminium Cans Market
Metals
Stainless Steel 400 Series Market
Metals
Qatar Metalworking Market
Metals
Steel Ingots Market
Metals
Europe Aluminium Wire Rod Market