
 US Ferrochrome Market | 2026-2036
US Ferrochrome Market Size, Share, and Industry Trends Forecast 2026-2036
US Ferrochrome Market Insights
A shift from single-source South African supply toward multi-source procurement is rebalancing how US stainless mills secure ferrochrome. Glencore International AG anchors long-haul seaborne deliveries through its integrated chrome mining network. Tata Steel Limited leverages transatlantic logistics expertise to sustain consistent alloy-grade shipments into East Coast ports. Samancor Chrome Limited competes on volume scale, while Atlantic Equipment Engineers differentiates through specialized packaging and just-in-time distribution to mid-sized foundries.
Ferrochrome is an iron-chromium alloy typically containing 50-70% chromium by weight, produced through carbothermic reduction of chromite ore in submerged arc furnaces and essential for imparting corrosion resistance to stainless steel. High carbon ferrochrome dominates volume flows into bulk stainless steel production, while low carbon ferrochrome commands premium pricing from aerospace and nuclear-grade alloy mills seeking minimal residual carbon content. Charge chrome remains the workhorse grade for standard 300-series stainless output, though medium carbon variants are gaining traction among tool steel manufacturers balancing cost with performance specifications.
EPA enforcement under the Clean Air Act shapes smelter emissions standards, while OSHA mandates govern furnace operator exposure limits in domestic ferrochrome handling facilities. The Department of Commerce maintains tariff schedules on imported chromium materials that directly influence landed cost structures for US buyers. Stakeholders must monitor how NHTSA vehicle lightweighting standards and FAA corrosion-resistance requirements for airframe alloys redirect specification demand toward higher-purity ferrochrome grades.
Market Dynamics
EPA emissions enforcement under the Clean Air Act is forcing stainless steel mills across Ohio and Pennsylvania to accelerate low-carbon ferrochrome adoption while reconfiguring supplier relationships away from single-source dependence.
Growth Catalysts
- Clean Air Act enforcement:EPA tightening of smelter emissions standards drives electric arc furnace operators toward low-carbon ferrochrome grades for compliance.
- Aerospace alloy specifications:FAA corrosion-resistance mandates for airframe components redirect demand toward higher-purity ferrochrome with minimal residual carbon.
- Great Lakes industrial corridor expansion:Stainless steel capacity additions in Ohio and Pennsylvania concentrate procurement volume in a logistics-advantaged region.
Market Restraints
- Chromite ore cost volatility:South African supply concentration exposes US buyers to rand-dollar exchange swings and bulk shipping rate spikes.
- Submerged arc furnace energy intensity:Domestic smelting faces structural disadvantage against imported ferrochrome produced on lower-cost thermal power.
- Tariff schedule rigidity:Department of Commerce duty structures on chromium materials limit procurement flexibility during supply disruptions.
Strategic Opportunities
- NHTSA vehicle lightweighting standards:Automotive corrosion-resistance specifications create specification pull for specialty ferrochrome grades in exhaust and structural components.
- Multi-source procurement models:Mills diversifying beyond South African supply chains can integrate transatlantic and alternative seaborne routes.
- Nuclear-grade alloy certification:Emerging reactor construction programs specify ultra-low carbon ferrochrome for radiation-resistant stainless steels.
Industry Challenges
- Furnace operator exposure compliance:OSHA mandates on hexavalent chromium handling require capital-intensive ventilation and monitoring retrofits at domestic facilities.
- Smelter emissions abatement capex:Baghouse and scrubber installations for Clean Air Act compliance strain balance sheets of mid-sized alloy producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ferrochrome Market |
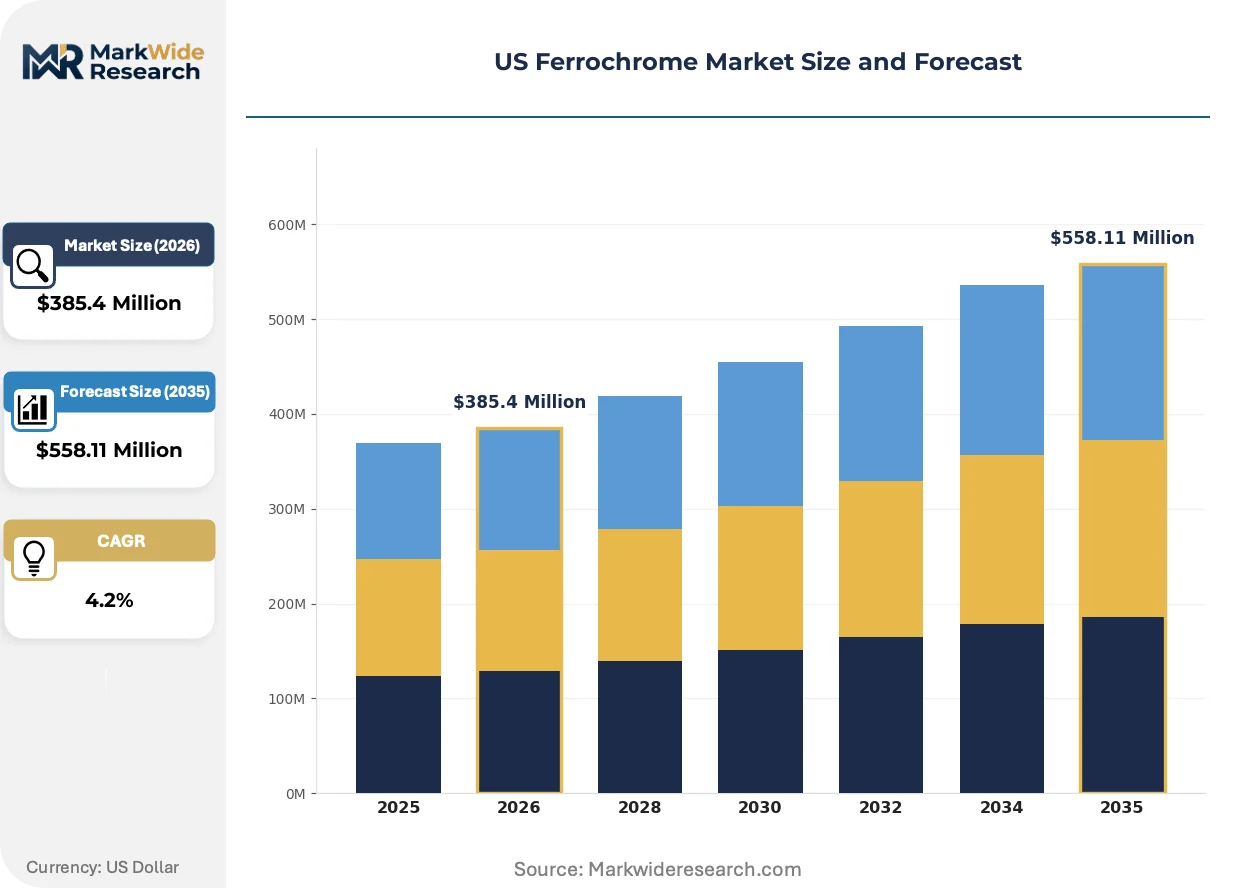
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Ferrochrome, Charge Chrome, High Carbon Ferrochrome, Medium Carbon Ferrochrome, Low Carbon Ferrochrome Application: Stainless Steel Production, Alloy Steel Manufacturing, Foundry Castings, Welding Electrodes, Industrial Catalysts End User: Steelmakers, Foundry Operators, Welding Companies, Chemical Producers, Metal Fabricators Distribution Channel: Direct Sales, Distributors, Online Platforms, Exporters |
| Companies Covered | MM Metals USA LLC, Atlantic Equipment Engineers, Tata Steel Mining Limited, MBR METALS OÜ, Glencore International AG, Tata Steel Limited, Samancor Chrome Limited, Eurasian Resources Group Sarl, South32 Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ferrochrome Market Trends and Innovations
Carbon reduction imperatives are compressing specification windows across the US ferrochrome value chain. Technology, regulation, and procurement logic are converging to reward purity-optimized production methods.
Plasma-based ferrochrome refining is unifying carbon control with energy efficiency in next-generation smelting configurations. Aerospace and nuclear-grade alloy mills in Pennsylvania and Ohio are piloting these systems to meet sub-0.05% carbon thresholds. This unifying capability collapses the traditional trade-off between volume scale and purity grade that has structured the market for decades.
EPA enforcement protocols under the Clean Air Act are mandating continuous emissions monitoring at submerged arc furnace operations. Stainless steel mills face stepped compliance timelines with penalties for exceedance events. Great Lakes corridor facilities are responding with predictive maintenance systems tied to baghouse differential pressure sensors.
Specification-driven procurement is consolidating buyer power among tier-one stainless producers capable of certifying alloy chemistry at receipt. Mid-sized foundries lacking in-house metallurgical laboratories are losing access to premium-grade supply allocations. This pattern concentrates most acutely in specialty tool steel and aerospace subcontracting channels serving Pennsylvania and Ohio manufacturing clusters.
US Ferrochrome Market Segmentation
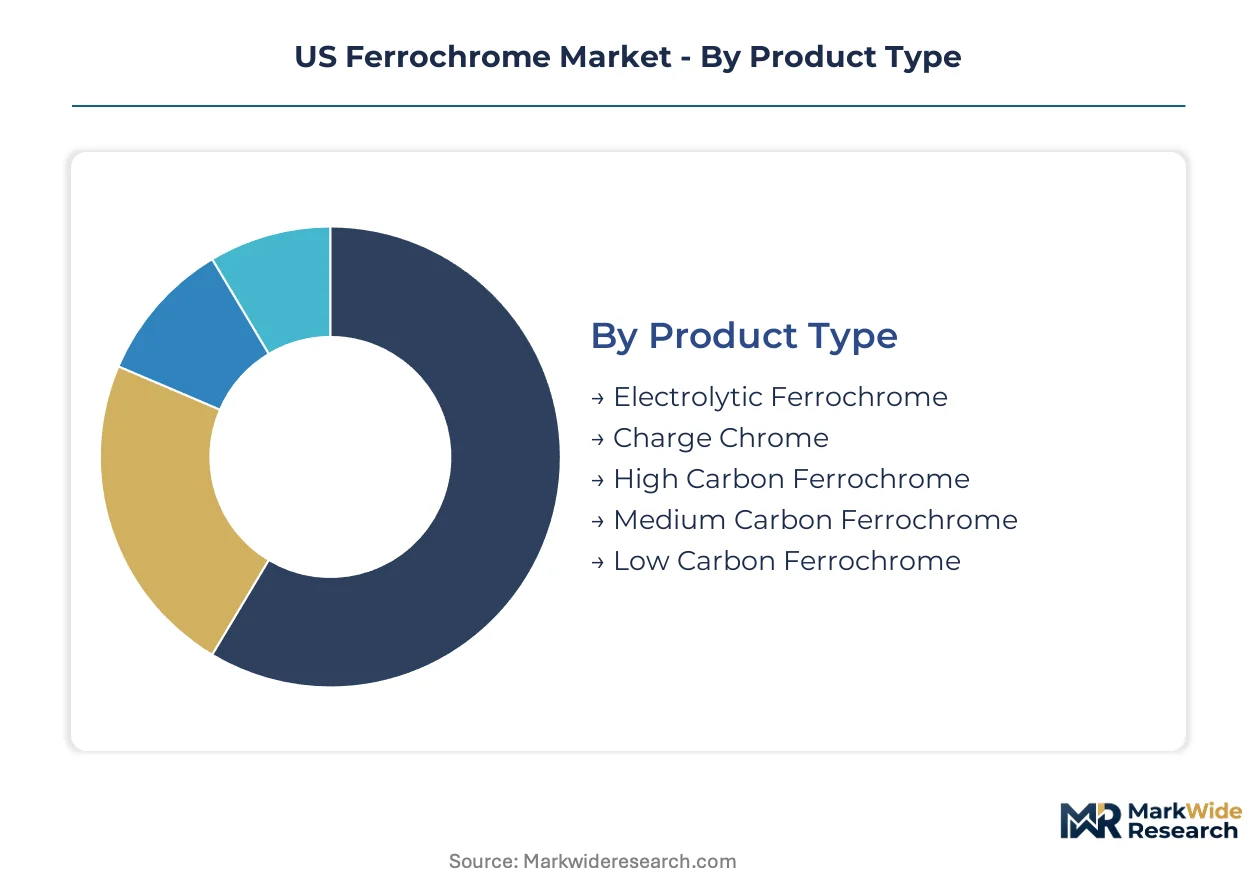
Ferrochrome specification tiers determine carbon thresholds, energy intensity, and end-use eligibility across the US stainless steel value chain. Product-grade selection directly shapes EPA compliance pathways and procurement cost structures for Great Lakes corridor mills.
Product Type:
Carbon content thresholds define the technical hierarchy, with smelting method and energy input determining grade classification.
- High Carbon Ferrochrome:Contains 4-8% carbon by weight, produced through conventional submerged arc furnace carbothermic reduction. Ohio and Pennsylvania bulk stainless mills consume this grade for standard 300-series output where residual carbon tolerance remains above 0.08%.
- Low Carbon Ferrochrome:Achieves sub-0.05% carbon through silicon-based reduction or argon-oxygen decarburization. Aerospace alloy producers in Pennsylvania specify this grade for FAA-compliant airframe components requiring minimal intergranular corrosion risk.
- Charge Chrome:High-carbon variant with 52-54% chromium content, serving as the workhorse feedstock for commodity stainless production.
- Medium Carbon Ferrochrome:Bridges carbon ranges at 0.5-4%, gaining traction among tool steel manufacturers balancing cost with performance specifications.
- Electrolytic Ferrochrome:Ultra-high purity grade produced through electrochemical refining, reserved for nuclear-grade alloy certification and specialty superalloy applications.
High carbon ferrochrome leads on scale; low carbon ferrochrome leads on momentum as EPA enforcement tightens emission thresholds.
Application:
End-use specifications cascade from corrosion-resistance requirements through metallurgical performance thresholds.
- Stainless Steel Production:Absorbs approximately two-thirds of US ferrochrome volume, with 304 and 316 grade mills in the Great Lakes corridor driving procurement concentration. EPA Clean Air Act compliance timelines are accelerating specification shifts toward lower-carbon feedstocks.
- Alloy Steel Manufacturing:Tool steel and high-strength low-alloy producers in Pennsylvania require precise chromium distribution for hardness and wear resistance. NHTSA vehicle lightweighting standards are redirecting specification demand toward higher-purity grades in automotive structural components.
- Foundry Castings:Mid-sized operations in Ohio consume charge chrome for abrasion-resistant castings and pump components.
- Welding Electrodes:Stainless steel coating applications demand consistent chromium recovery rates.
- Industrial Catalysts:Chemical producers utilize ferrochrome in oxidation process applications.
Stainless steel production dominates volume absorption; alloy steel manufacturing is climbing the fastest on specification upgrading.
End User:
Procurement scale and metallurgical capability determine buyer power across the value chain.
- Steelmakers:Integrated mills and electric arc furnace operators in Ohio and Pennsylvania command tier-one supplier relationships and volume pricing leverage. These buyers are consolidating procurement through multi-source models to reduce South African supply concentration risk.
- Foundry Operators:Mid-sized facilities lack in-house laboratories, losing access to premium-grade allocations as specification-driven procurement tightens.
- Welding Companies:Electrode manufacturers source standard grades through distributor networks.
- Chemical Producers:Catalyst applications require certified purity documentation.
- Metal Fabricators:Job shops purchase small lots through regional distributors.
Steelmakers lead on procurement scale; foundry operators face the steepest access constraints on premium grades.
Distribution Channel:
Logistics configuration and buyer scale determine channel selection across the procurement spectrum.
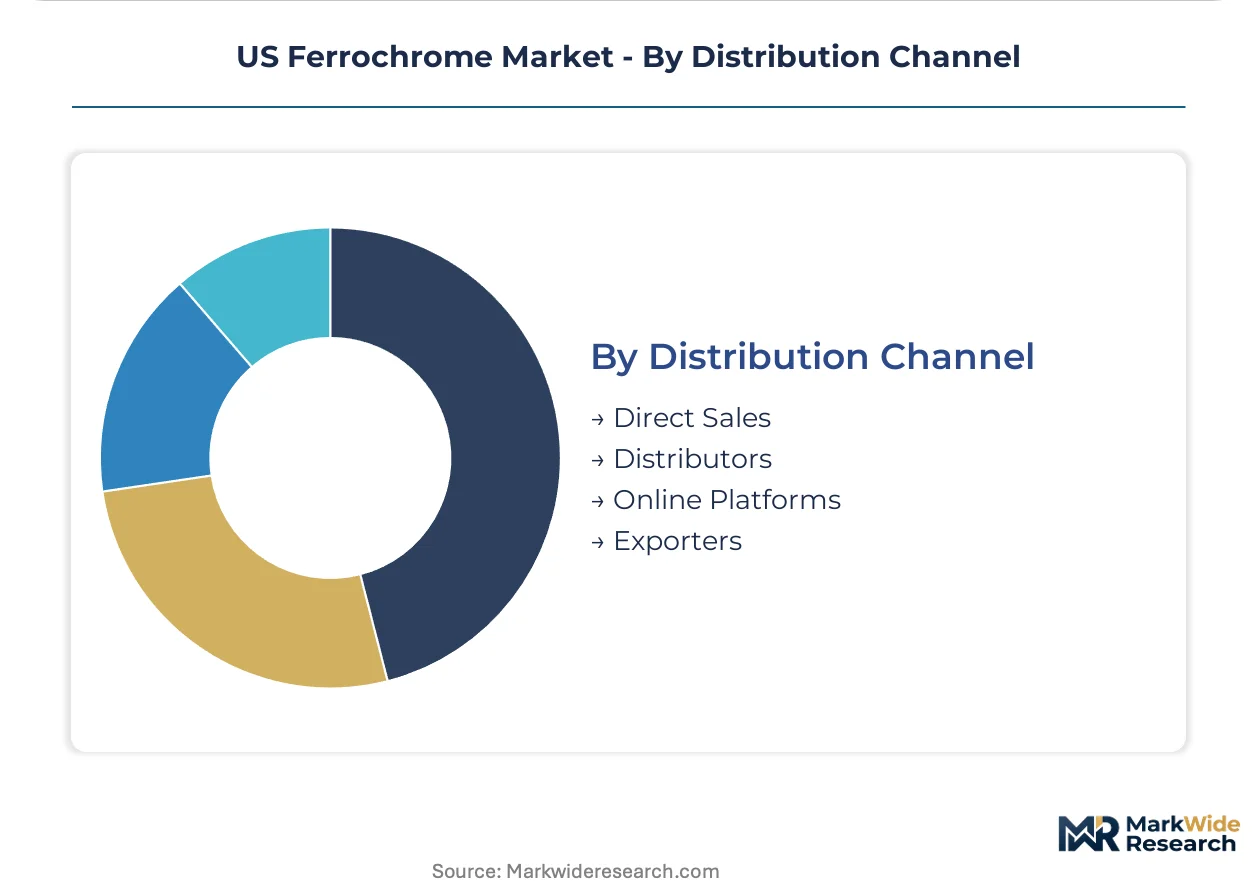
- Direct Sales:Major steelmakers contract directly with Glencore, Tata Steel, and Samancor for seaborne deliveries into East Coast and Great Lakes ports. These arrangements secure volume commitments and specification certification at receipt.
- Distributors:Atlantic Equipment Engineers and regional alloy suppliers serve mid-sized foundries with specialized packaging and just-in-time delivery.
- Online Platforms:Emerging digital procurement channels facilitate spot market transactions for smaller fabricators.
- Exporters:Limited outbound flow given domestic demand absorption and tariff structures.
Direct sales leads on volume concentration; distributors retain critical positioning for fragmented demand segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes industrial corridor concentrates US ferrochrome demand through Ohio and Pennsylvania stainless steel clusters. EPA emissions enforcement under the Clean Air Act is accelerating specification shifts toward low-carbon grades across this geography.
Ohio
Cleveland-Toledo arc furnace operators consume bulk high-carbon ferrochrome for commodity 300-series stainless output. OSHA hexavalent chromium exposure mandates require ventilation retrofits at Canton and Youngstown handling facilities. The Mahoning Valley steel cluster is consolidating procurement through multi-source models to reduce South African supply dependence.
Pennsylvania
Pittsburgh-area specialty alloy mills specify low-carbon ferrochrome for aerospace and nuclear-grade certifications. FAA corrosion-resistance requirements for airframe components redirect procurement toward sub-0.05% carbon thresholds. The Monongahela Valley manufacturing corridor is piloting plasma-based refining systems to meet purity specifications.
Indiana
Gary-Hammond stainless producers face stepped EPA compliance timelines for submerged arc furnace emissions. The Department of Commerce tariff schedules on imported chromium materials influence landed cost structures for Lake Michigan port deliveries. Northwest Indiana steel capacity is integrating predictive maintenance systems tied to baghouse differential pressure sensors.
Michigan
Detroit-area automotive suppliers source medium-carbon ferrochrome for NHTSA-driven lightweighting specifications in exhaust and structural components. The state's foundry casting sector consumes charge chrome for abrasion-resistant pump components serving Great Lakes industrial infrastructure. Saginaw-Bay City metal fabricators purchase through regional distributors lacking direct mill relationships.
Illinois
Chicago-Gary logistics hubs consolidate ferrochrome transhipment from East Coast seaborne arrivals. FERC-regulated grid pricing shapes electric arc furnace operating economics for Rockford-area tool steel manufacturers. The Calumet Region industrial cluster is losing mid-sized foundry access to premium-grade allocations as specification-driven procurement tightens.
US Ferrochrome Market Competitive Landscape
Global majors compete with regional champions across procurement scale and specification certification. Integrated mining-smelting conglomerates anchor seaborne supply through long-haul contracts into East Coast and Great Lakes ports. Domestic distributors and specialized alloy engineers occupy fragmented mid-market tiers serving foundries without direct mill relationships. Competitive moves center on multi-source procurement partnerships and emissions-compliant refining technology licensing.
Within the integrated mining-smelting tier, Glencore International AG and Samancor Chrome Limited represent archetypal global suppliers with captive chromite ore networks and submerged arc furnace scale. Atlantic Equipment Engineers occupies a specialized position among domestic distributors, exemplifying just-in-time logistics and customized packaging for mid-sized foundry customers lacking metallurgical laboratory capabilities. Tata Steel Limited anchors transatlantic supply relationships through consolidated shipping arrangements into Pennsylvania and Ohio port facilities.
| Leading Market Players |
|---|
| MM Metals USA LLC |
| Atlantic Equipment Engineers |
| Tata Steel Mining Limited |
| MBR METALS OÜ |
| Glencore International AG |
| Tata Steel Limited |
| Samancor Chrome Limited |
| Eurasian Resources Group Sarl |
| South32 Limited |
| Others |
Pricing and Supply Chain Analysis
EPA Clean Air Act enforcement is redirecting Great Lakes stainless mills toward low-carbon ferrochrome grades, forcing suppliers to reconfigure smelting methods and compressing margins on high-carbon variants that once dominated procurement volumes.
Pricing Analysis
Chromite ore cost pass-through from South African mining operations anchors contract pricing for seaborne deliveries into East Coast and Great Lakes ports. Three-tier pricing structure across premium low-carbon, standard medium-carbon, and economy high-carbon levels reflects carbon content thresholds and certification documentation. Pricing pressure stems from rand-dollar exchange volatility and bulk shipping rate spikes that compress margins for US distributors. Mid-sized foundries without direct mill relationships exhibit highest price sensitivity, while integrated steelmakers with volume commitments secure most favorable terms.
Supply Chain Analysis
Department of Commerce tariff schedules on imported chromium materials reshape sourcing decisions for domestic buyers seeking procurement flexibility during disruptions. Supply concentrates in South Africa, Kazakhstan, and India for chromite ore extraction and initial smelting, with Finland and Turkey emerging as alternative refining hubs. Raw material dependencies center on lumpy chromite ore, metallurgical coke reductant, and electrical power for submerged arc furnace operations. Single-source vulnerability from South African supply concentration exposes buyers to geopolitical and logistics disruptions. Distribution runs through direct long-term offtake contracts for major steelmakers and specialized distributor networks for fragmented foundry demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US ferrochrome market functions as a regulatory compounder where EPA emissions milestones under the Clean Air Act continuously reset specification thresholds and procurement priorities across the Great Lakes industrial corridor.
For Market Incumbents: Extend backward integration into captive chromite sourcing or alternative seaborne routes to reduce South African supply concentration risk. Secure plasma-based refining technology licenses to defend position against emerging low-carbon specialists capable of sub-0.05% carbon production. Reinforce direct mill relationships through multi-year offtake commitments that lock in premium-grade allocations before specification-driven procurement tightens further.
For New Entrants and Emerging Players: Regional distributors serving mid-sized foundries represent the most accessible channel for market entry without competing directly against Glencore or Samancor volume contracts. Target specialty tool steel manufacturers in Pennsylvania and Ohio seeking medium-carbon grades with just-in-time delivery requirements. Pursue certification partnerships with Atlantic Equipment Engineers to leverage established packaging and logistics infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic distributors possessing metallurgical laboratory capabilities and EPA-compliant handling infrastructure. Long-term viability favors acquisition targets with multi-source procurement relationships and nuclear-grade alloy certification pathways. Watch NHTSA vehicle lightweighting standard revisions as the inflection signal for specialty grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Procurement Partnership | Diversifies supply beyond South African concentration to reduce rand-dollar and shipping exposure. |
| Plasma-Based Refining Technology License | Enables sub-0.05% carbon production for EPA-compliant and aerospace-grade specifications. |
| Predictive Maintenance System Deployment | Links baghouse sensors to compliance timelines for Clean Air Act emissions monitoring. |
| Nuclear-Grade Alloy Certification Investment | Captures emerging reactor construction demand for ultra-low carbon radiation-resistant steels. |
| Just-in-Time Distribution Network Expansion | Serves mid-sized foundries losing direct mill access under specification-driven procurement consolidation. |
Research Methodology
Bottom-up stainless steel production modeling reconciled against top-down ferrochrome supply tracking forms the analytical core of this study. Primary interviews with electric arc furnace operators, specialty alloy procurement managers, foundry technical directors, and distributor logistics coordinators were combined with secondary validation from EPA enforcement databases, Department of Commerce tariff schedules, and SEC filings of integrated mining-smelting conglomerates. Trade flow analysis of chromite ore and ferrochrome shipments through East Coast and Great Lakes ports provided supply-side triangulation against demand estimates from Ohio and Pennsylvania steel cluster capacity.
Input-output matrices linking chromite ore extraction through submerged arc furnace smelting to stainless steel mill consumption drove volume projections across the analysis window. Segmentation dimensions modeled include carbon content tier, end-use application, buyer scale archetype, and regional production cluster within the Great Lakes corridor. CAGRs were derived from trend extrapolation of EPA compliance timeline impacts and specification shift velocities observed in aerospace and nuclear-grade alloy procurement. Forecast inputs incorporated NHTSA vehicle lightweighting standard evolution and FERC-regulated grid pricing for electric arc furnace operating economics.
Revisions become necessary when EPA emissions enforcement timelines accelerate, South African supply disruptions materialize, or plasma-based refining technology achieves commercial scale faster than baseline assumptions. Forecasts reflect documented assumptions about regulatory compliance costs and specification adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Scandium Market
Metals
Platinum Market
Metals
Titanium Powder Market
Metals
Aluminum Casting Market
Metals
Aluminum Scrap Recycling Market
Metals
Global Brass Rods Market
Metals
Global High Purity Titanium Powder Market
Metals
Global Wire Rods Market
Metals
High Purity Tungsten Market
Metals
Platinum Group Metals Market
Metals
Neodymium Market
Metals
High Purity Aluminium Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Aluminium Powder Market
Metals
Zirconium Market
Metals
Tungsten Metal Powder Market