
 Barium Market | 2026-2036
Barium Market Size, Share, and Industry Trends Forecast 2026-2036
Barium Market Analysis
REACH registration requirements for barium compounds is expanding compliance burdens for European importers. Solvay S.A. leverages its integrated chlor-alkali platform to control raw material flows across multiple barium derivative lines. Sakai Chemical Industry Co., Ltd. anchors its position through decades of specialization in ultrafine barium sulfate for electronics-grade applications. Chemical Products Corporation competes on geographic proximity to domestic oilfield service customers in North America.
Barium is a soft alkaline earth metal (atomic number 56) that occurs chiefly as barite ore (BaSO₄) and witherite (BaCO₃), with commercial grades requiring 98% minimum purity after acid reduction or thermal decomposition processing. Its primary industrial purpose centers on imparting density, opacity, and chemical stability across drilling fluids, specialty glass, ceramic glazes, and contrast media formulations. Barium sulfate dominates product type revenue streams due to irreplaceable density specifications in deepwater drilling formulations, while medical grade variants command premium positioning through FDA and EMA purity certifications. Oil drilling application volumes lead absolute consumption, though pharmaceutical and healthcare end use industries exhibit faster structural growth tied to aging demographics and diagnostic imaging expansion.
FDA oversight of barium sulfate suspensions for radiographic contrast, coupled with EMA's MDR requirements for medical-grade suppliers, creates dual-jurisdiction compliance complexity for multinational producers. China's SAMR enforces GB standards on barium carbonate and chloride exports, directly shaping which purification technologies justify capital investment. Stakeholders must monitor how REACH authorization timelines and evolving EPA mining waste rules alter feedstock economics for Western producers.
Market Dynamics
Deepwater drilling specifications are tightening density requirements for barium sulfate weighting agents, forcing purification technology upgrades across the supplier base while China's GB standards compress import tolerance windows for foreign producers.
Growth Catalysts
- REACH registration expansion:ECHA's evolving authorization timelines for barium compounds are filtering out marginal European suppliers and consolidating volume among compliant producers.
- Diagnostic imaging expansion:Aging demographics in Japan and Germany are accelerating hospital procurement of barium sulfate suspensions for gastrointestinal radiography.
- Shaanxi-Hubei manufacturing clusters:East Asian production concentration is driving logistics efficiencies and just-in-time feedstock delivery to specialty glass and ceramics facilities.
Market Restraints
- Barite ore supply concentration:Chinese state-owned mining enterprises control roughly two-thirds of global barite extraction, exposing downstream processors to export quota volatility.
- Strontium carbonate substitution:Ceramic glaze manufacturers in Italy and Spain are partially substituting barium carbonate with strontium-based alternatives to bypass REACH compliance costs.
- Acid reduction processing limitations:Thermal decomposition methods for witherite ore cannot achieve the 99.5% purity thresholds required for medical-grade barium sulfate without prohibitively expensive secondary refining.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic barium derivative production incentives are attracting joint venture proposals from European chlor-alkali producers seeking tariff-advantaged supply positions.
- Electronics-grade ultrafine sulfate:Semiconductor packaging and printed circuit board laminates are absorbing sub-micron barium sulfate for dielectric constant control at loadings below 5% by weight.
- Dual carbon goals compliance:China's MEE carbon intensity benchmarks for chemical processing are rewarding producers with integrated acid recovery systems and captive energy generation.
Industry Challenges
- FDA-EMA dual jurisdiction complexity:Medical-grade barium sulfate producers must maintain parallel quality management systems and separate batch documentation for US and European regulatory submissions.
- Deepwater drilling certification timelines:API specification testing for high-pressure high-temperature drilling fluids requires 18-24 month qualification periods that lock out new barium sulfate entrants from active rig procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Market |
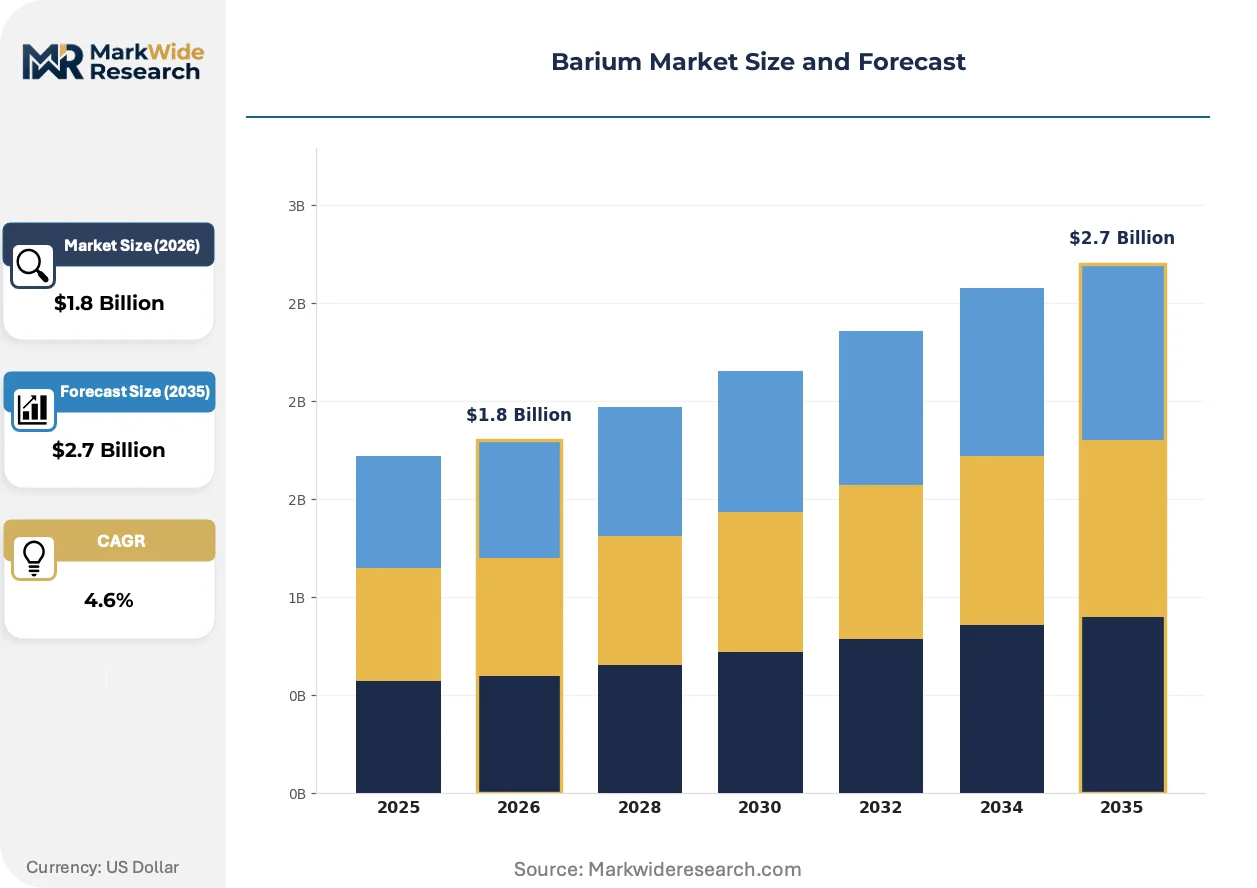
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barium Carbonate, Barium Sulfate, Barium Hydroxide, Barium Chloride Application: Paints, Glass Manufacturing, Oil Drilling, Pharmaceuticals End Use Industry: Chemicals, Construction, Automotive, Healthcare Grade: Industrial Grade, Reagent Grade, Medical Grade, Food Grade |
| Companies Covered | Solvay S.A., Chemical Products Corporation, Sakai Chemical Industry Co., Ltd., Shaanxi Ankang Jianghua Group Co., Ltd., Hubei Jingshan Chutian Barium Salt Corp., Nippon Chemical Industrial Co., Ltd., American Elements, Vishnu Chemicals Ltd., Hebei Xinji Chemical Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Market Emerging Trajectories
Processing technology is bifurcating between commodity-scale acid reduction for drilling grades and precision-controlled precipitation methods for electronics and pharmaceutical applications, with capital allocation increasingly favoring the latter.
Ultrafine barium sulfate produced through controlled precipitation is absorbing volume from conventional milled barite in electronics-grade applications. Semiconductor substrate manufacturers in South Korea and Taiwan are qualifying sub-500 nanometer particle distributions for high-frequency laminate dielectrics. This specification compression is absorbing margin from commodity producers while rewarding integrated chemical processors with in-house precipitation expertise.
China's SAMR enforcement of revised GB standards for barium carbonate and chloride exports is tightening heavy metal impurity thresholds to 10 parts per million for lead and arsenic. European importers are redirecting procurement toward domestic thermal decomposition facilities to avoid border rejection risk. Medical-grade suppliers with existing FDA master files are accelerating EMA MDR technical documentation updates to capture displaced import volume.
Long-term contracting for barite ore is displacing spot market purchasing among North American oilfield service companies. Halliburton and Schlumberger procurement teams are negotiating 36-48 month offtake agreements directly with Chinese mining consortiums to secure density specification consistency. This preference shift is most visible in Permian Basin drilling operations where barite quality variability has caused downhole weighting agent segregation failures.
Barium Market Segmentation
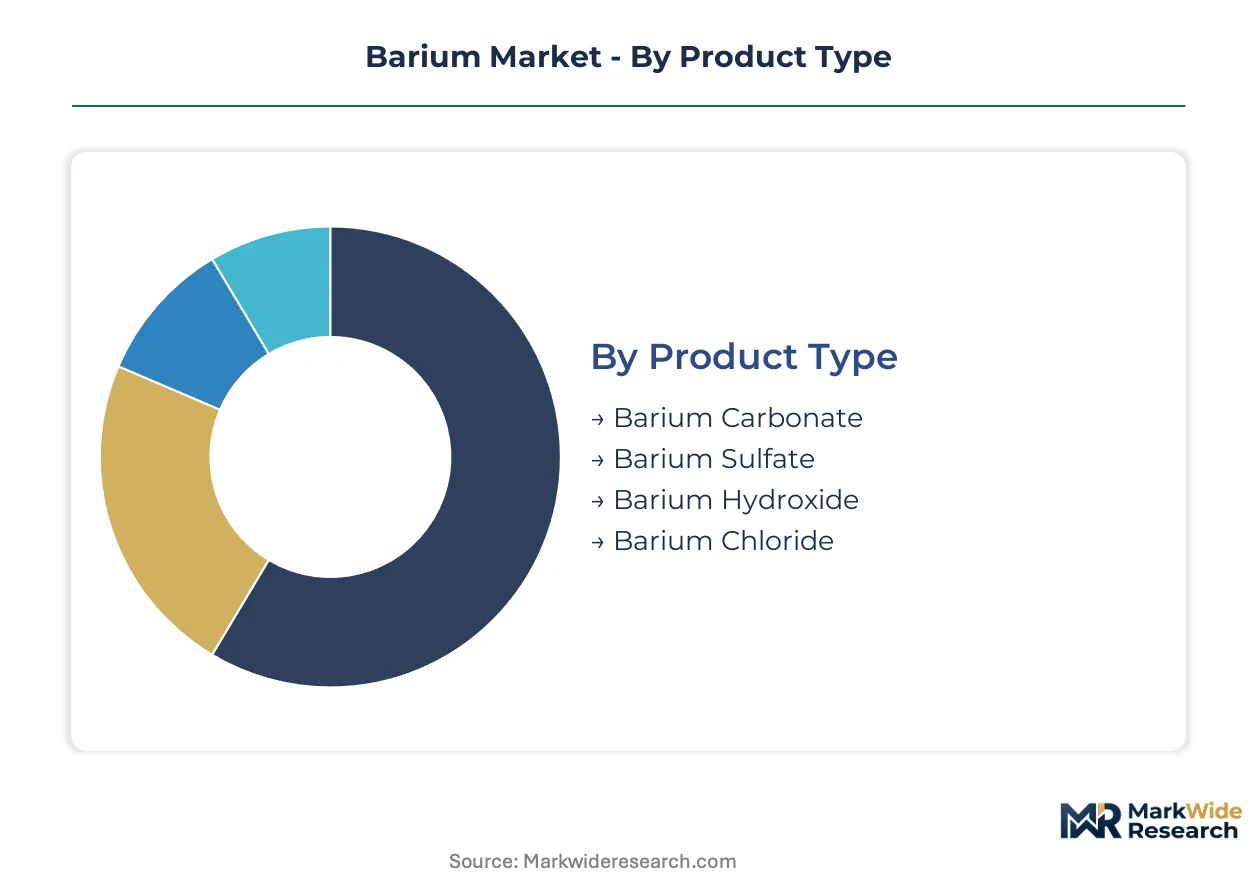
Barium derivatives exhibit stark specification divergence across end uses, with drilling fluid weighting agents tolerating 95% purity while medical contrast media demands 99.5% thresholds. Segmentation logic tracks this purity-to-volume tradeoff, where commodity grades absorb ore tonnage and specialty grades capture margin.
Product Type:
Customization intensity varies sharply across this category, from standardized milled barite for drilling to precipitation-engineered ultrafine sulfates for electronics.
- Barium Sulfate:Dominates as the density-imparting weighting agent in deepwater drilling fluids, with API specification 13A governing particle size distribution and specific gravity minimums of 4.2. Demand concentrates in Gulf of Mexico and West African offshore operations where 15,000+ psi well pressures require consistent density performance. Halliburton and Schlumberger procurement teams negotiate long-term offtake agreements directly with Chinese mining consortiums to secure specification consistency.
- Barium Carbonate:Functions as the primary fluxing agent in specialty glass and ceramic glaze formulations, with fluxing action dependent on controlled decomposition temperatures between 811°C and 1450°C. Italian and Spanish ceramic manufacturers are partially substituting with strontium carbonate to bypass REACH compliance costs, compressing volume in European markets while Asian construction growth sustains demand.
- Barium Hydroxide:Serves niche applications in sugar refining and synthetic rubber vulcanization, with octahydrate and monohydrate crystalline forms determining handling characteristics for specific process chemistries.
- Barium Chloride:Deploys primarily in heat treatment salts for steel hardening and as a laboratory reagent, with hygroscopic properties limiting storage duration and geographic distribution economics.
Leading the category by volume: Barium Sulfate. Growing fastest: Barium Sulfate in electronics-grade precipitation variants.
Application:
Cost tier stratification separates commodity volume applications from premium-margin specialty uses, with drilling fluids at the base and pharmaceuticals at the apex.
- Oil Drilling:Absorbs the majority of global barite ore extraction as weighting agents for drilling mud density control, with deepwater specifications tightening to 4.2 specific gravity minimums and sub-74 micron particle distributions. Permian Basin operators have experienced downhole segregation failures from quality variability, driving 36-48 month contracting preferences over spot purchasing.
- Pharmaceuticals:Commands premium positioning through FDA and EMA dual-jurisdiction compliance for barium sulfate suspensions used in gastrointestinal radiography, with aging demographics in Japan and Germany accelerating hospital procurement. Batch documentation must satisfy parallel quality management systems for US and European regulatory submissions.
- Glass Manufacturing:Utilizes barium carbonate as a flux and barium sulfate for decolorizing, with specialty optical glass for camera lenses requiring ultralow iron content below 50 ppm.
- Paints:Employs barium sulfate as a filler and extender pigment, with precipitated variants offering controlled particle size for gloss retention in automotive coatings.
Drilling applications lead absolute consumption. Pharmaceutical and healthcare end uses are climbing the fastest, tied to diagnostic imaging expansion.
End Use Industry:
Customer type diversity spans state-owned mining enterprises, multinational oilfield service companies, and hospital procurement networks, each with distinct specification protocols and contracting horizons.
- Chemicals:Encompasses chlor-alkali integrated producers like Solvay S.A. controlling raw material flows across multiple barium derivative lines, with captive hydrochloric acid supply determining cost competitiveness in carbonate and chloride production.
- Healthcare:Demands medical-grade barium sulfate with FDA master files and EMA MDR technical documentation, with diagnostic imaging volume expanding most quickly in aging populations.
- Construction:Absorbs barium carbonate for ceramic tile glazes and barium hydroxide for concrete additives, with Chinese infrastructure investment sustaining regional demand concentration.
- Automotive:Qualifies sub-500 nanometer barium sulfate for high-frequency laminate dielectrics in electric vehicle power electronics, with South Korean and Taiwanese substrate manufacturers driving specification compression.
Chemicals sector dominates procurement tonnage. Healthcare exhibits the steepest expansion trajectory on demographic and diagnostic imaging drivers.
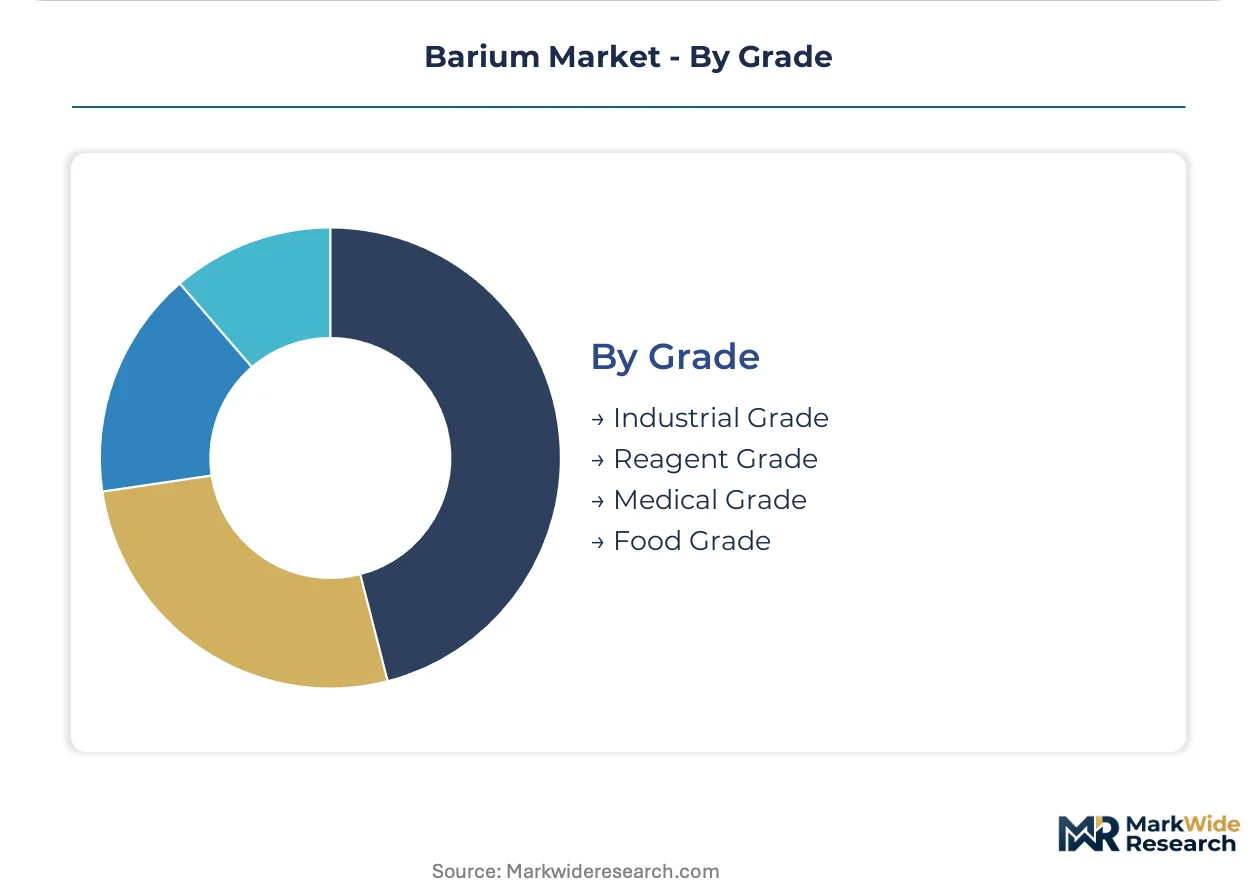
Grade:
Margin structure inverts with purity, where industrial grade commands single-digit percentage margins and medical grade sustains multiples through certification barriers.
- Industrial Grade:Tolerates 95-98% purity with controlled impurities for drilling fluids, construction chemicals, and bulk glass manufacturing, with acid reduction processing from barite ore achieving specification at commodity scale.
- Medical Grade:Requires 99.5% minimum purity with heavy metal impurities below 10 ppm for lead and arsenic, with thermal decomposition of witherite ore demanding prohibitively expensive secondary refining to achieve threshold. China's SAMR enforcement of revised GB standards is tightening export tolerance windows.
- Reagent Grade:Serves laboratory and analytical chemistry applications with ACS or ISO specification compliance, with batch certification and traceability documentation adding cost premiums over industrial equivalents.
- Food Grade:Applies limited regulatory acceptance for barium sulfate as a color additive in certain jurisdictions, with EFSA and FDA maintaining restrictive permitted use catalogs due to toxicity concerns.
Industrial Grade leads by volume across all product types. Medical Grade is gaining share fastest on diagnostic imaging expansion and regulatory displacement of non-compliant imports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates roughly two-thirds of global barite ore extraction, with downstream processing clustering around specific industrial corridors. Demand-side weight concentrates in East Asian manufacturing hubs, North American oilfield services, and European specialty chemical applications.
China
Shaanxi and Hubei provinces anchor domestic barium salt production, with Jianghua Group and Chutian Barium Salt operating integrated mining-to-derivative facilities. SAMR enforces tightening GB standards on heavy metal impurities for exported barium carbonate and chloride. The Yangtze River Delta absorbs volume for electronics-grade ultrafine sulfate qualification by South Korean substrate manufacturers.
United States
Permian Basin drilling operations drive procurement of API 13A-certified barium sulfate weighting agents, with Halliburton and Schlumberger negotiating 36-48 month offtake agreements. EPA mining waste rules alter feedstock economics for domestic processors. Gulf Coast chemical corridors host thermal decomposition facilities serving medical-grade specifications.
Germany
Aging demographics accelerate hospital procurement of barium sulfate suspensions for gastrointestinal radiography across Bavaria and North Rhine-Westphalia. ECHA's REACH authorization timelines filter marginal suppliers from the European market. Specialty glass manufacturers in the country's industrial south qualify ultralow-iron barium carbonate for optical lens applications.
Japan
Diagnostic imaging expansion in Tokyo and Osaka metropolitan areas sustains premium demand for medical-grade barium sulfate. METI oversees chemical purity standards alignment with EMA MDR requirements. Sakai Chemical Industry anchors decades of specialization in ultrafine barium sulfate for electronics-grade dielectric applications.
India
PLI scheme incentives for specialty chemicals attract joint venture proposals from European chlor-alkali producers seeking tariff-advantaged supply positions. BIS standards govern import quality thresholds for barium derivatives used in construction ceramics. Gujarat and Maharashtra industrial corridors concentrate domestic processing capacity for oilfield chemical re-exports.
Barium Market Vendor Landscape
Chinese state-owned mining enterprises and integrated chemical processors anchor one tier; European and Japanese specialty manufacturers hold certification-dependent premium positions. The supplier base stratifies between ore-controlled volume players and precipitation-technology specialists. Three archetypes dominate: integrated mining-to-derivative operators, chlor-alkali platform diversifiers, and ultrafine precipitation specialists. Competitive moves center on long-term ore offtake contracting and dual-jurisdiction regulatory compliance investments.
Within the integrated mining-to-derivative tier, Shaanxi Ankang Jianghua Group Co., Ltd. and Hubei Jingshan Chutian Barium Salt Corp. exemplify Chinese state-affiliated concentration. Solvay S.A. occupies a position among European chlor-alkali platform diversifiers leveraging captive acid supply. Sakai Chemical Industry Co., Ltd. represents the ultrafine precipitation specialist archetype with decades of electronics-grade focus.
| Leading Market Players |
|---|
| Solvay S.A. |
| Chemical Products Corporation |
| Sakai Chemical Industry Co., Ltd. |
| Shaanxi Ankang Jianghua Group Co., Ltd. |
| Hubei Jingshan Chutian Barium Salt Corp. |
| Nippon Chemical Industrial Co., Ltd. |
| American Elements |
| Vishnu Chemicals Ltd. |
| Hebei Xinji Chemical Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive mining-to-derivative integration among Chinese state-owned enterprises anchors both supply security and pricing power across the barium value chain, with Jianghua Group and Chutian Barium Salt controlling ore extraction through finished salt production to capture margin compression from tightening GB standards.
Pricing Analysis
Volume-massive drilling-grade barium sulfate trades at commodity margins while medical-grade variants command substantial premiums through FDA and EMA certification barriers. Three-tier pricing structure across medical, industrial, and reagent grades reflects purity thresholds and compliance documentation burdens. Cost compression in drilling-grade milled barite intensifies as Permian Basin operators consolidate procurement through 36-48 month offtake agreements. Oilfield service companies exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize specification consistency over unit cost.
Supply Chain Analysis
Reverse-logistics flows for barium sulfate are negligible given single-use consumption patterns in drilling and diagnostic applications, though spent drilling mud reclamation programs are emerging in Gulf of Mexico regulatory compliance frameworks. Raw material supply concentrates in China, India, and Morocco, with Chinese state-owned mining enterprises controlling roughly two-thirds of global barite extraction. Downstream processing draws from acid reduction and thermal decomposition technologies with captive hydrochloric acid supply determining cost competitiveness. Single-source vulnerability from Chinese export quota volatility represents the dominant structural risk. Distribution runs through direct long-term contracting between mining consortiums and oilfield service majors, supplemented by specialty chemical distributors for pharmaceutical and electronics-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization expansion and China's tightening GB standards are forcing consolidation among marginal European and import-dependent suppliers, rewarding integrated producers with captive ore supply and dual-jurisdiction certification capabilities.
For Market Incumbents: Anchor market position through backward integration into barite ore offtake agreements with Chinese mining consortiums, securing 36-48 month supply continuity against export quota volatility. Accelerate EMA MDR technical documentation updates to capture volume displaced by SAMR enforcement of revised heavy metal thresholds. Solvay S.A.'s chlor-alkali platform model demonstrates how captive acid supply defends margin position against commodity-grade competitors. For New Entrants and Emerging Players: Launch via specialty electronics-grade precipitation technology targeting South Korean and Taiwanese semiconductor substrate manufacturers qualifying sub-500 nanometer particle distributions. India's PLI scheme for specialty chemicals offers tariff-advantaged supply positioning through joint venture structures with European chlor-alkali producers. Focus initial capacity on ultrafine sulfate for high-frequency laminate dielectrics rather than competing in commoditized drilling-grade barite. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of precipitation-technology specialists with existing FDA master files and EMA MDR technical documentation, as regulatory compliance investments create irreplicable certification moats. Long-term viability favors integrated mining-to-derivative operators with captive energy generation meeting China's MEE carbon intensity benchmarks. Monitor SAMR enforcement actions on heavy metal impurity thresholds as inflection indicator for import displacement volume capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Ore Supply | Secures feedstock continuity against Chinese export quota volatility for drilling-grade producers. |
| Dual-Jurisdiction Certification Investment | FDA and EMA parallel quality systems capture pharmaceutical volume from displaced non-compliant imports. |
| Ultrafine Precipitation Capacity Expansion | Sub-500 nanometer particle qualification meets South Korean semiconductor substrate specifications. |
| Joint Venture under India's PLI Scheme | Tariff-advantaged supply positioning attracts European chlor-alkali platform diversification. |
| Integrated Acid Recovery Systems | MEE carbon intensity benchmark compliance rewards producers with captive energy generation. |
Methodological Framework
Document review covered SEC 10-K filings, customs and trade databases, and ACC industry reports, complemented by interviews with plant managers at integrated barium salt facilities, procurement leads at oilfield service companies, technical R&D directors at specialty chemical firms, and distribution channel partners. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis and capacity utilization assessments across Shaanxi and Hubei production clusters.
Cross-referencing historical pricing trajectories against expert panel input on REACH authorization timelines and SAMR enforcement intensity shaped the projection framework. Segmentation dimensions modeled include product type purity tier, end-use industry application, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions across oil drilling, pharmaceutical, and electronics-grade demand trajectories throughout the forecast period, with specific inputs from API specification testing timelines and diagnostic imaging expansion rates in aging demographics.
Export quota volatility, REACH authorization timeline acceleration, and semiconductor substrate qualification delays are the dominant revision risks to modeled outcomes. Practitioners should monitor SAMR enforcement actions, ECHA substance evaluation updates, and South Korean substrate manufacturer qualification windows for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Galvanized Steel Wire Market
Metals
Cerium Market
Metals
Silver Sulphate Market
Metals
Zinc Dust Market
Metals
Seamless Stainless Steel Products Market
Metals
Global Superconducting Wire Market
Metals
Europe Aluminium Wire Rod Market
Metals
Steel Drums Market
Metals
Industrial Metal Strips Market
Metals
Palladium Market
Metals
Copper and Copper Alloy Powder Market
Metals
Ferro Aluminum Market
Metals
Global Precious Metal Market
Metals
Europe Welding Consumables Market
Metals
Global Bronze Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market