
 Europe Metal Service Centers Market | 2026-2036
Europe Metal Service Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Service Centers Market Foresight
EU Carbon Border Adjustment Mechanism is restructuring the landed cost equation for non-EU steel and aluminum, forcing service centers to rebalance import portfolios toward domestic and near-shore mill relationships. Kloeckner Metals leverages its integrated digital platform to match mill production with fragmented customer specifications across twelve European countries. Voestalpine Steel & Service Center anchors its position through captive supply from Austrian integrated mills, while thyssenkrupp Materials differentiates via specialized high-strength steel distribution for automotive tier-one suppliers.
Europe metal service centers function as intermediaries that procure semi-finished metal products—typically coils, sheets, bars, and plates in gauges ranging from 0.4 mm to 25 mm—then apply value-added processing before delivering to industrial end users. Carbon steel distribution commands the largest volume footprint due to construction and general manufacturing offtake, while aluminum processing represents the fastest-expanding margin pool as aerospace and electric vehicle lightweighting requirements intensify. Laser cutting technology leads capital deployment among processing capabilities, though CNC machining claims premium pricing for tight-tolerance components serving medical and precision engineering segments.
REACH compliance administered by ECHA governs chemical composition disclosures and restricted substance thresholds for coated and surface-treated metals circulating within the single market, while CE marking under the EU Construction Products Regulation mandates performance declarations for structural steel entering building applications. The EU Green Deal's embedded carbon benchmarks are filtering procurement specifications toward mills with verified emissions credentials. Stakeholders must monitor how upcoming revisions to the EU Emissions Trading System cap trajectory reshape the cost structure of primary metal production and, by extension, the inventory valuation models that service centers employ.
Market Dynamics
EU Carbon Border Adjustment Mechanism is restructuring landed cost economics for imported steel and aluminum, forcing European service centers to rebalance procurement portfolios toward domestic mill relationships and near-shore supply corridors.
Growth Catalysts
- Automotive Lightweighting Mandates:Electric vehicle manufacturers across Germany and Poland are expanding just-in-time aluminum sourcing from regional centers to meet EU fleet emission targets.
- REACH Compliance Framework:ECHA-administered chemical disclosure requirements are elevating demand for certified coated metals with verified substance thresholds.
- Laser Cutting Capital Deployment:Service centers in the Ruhr-to-Bavaria industrial corridor are installing fiber laser systems to capture high-margin precision processing contracts.
Market Restraints
- Scrap Price Volatility:Ferrous scrap input costs fluctuate with Turkish export demand and energy-intensive electric arc furnace operating rates.
- Mill Concentration Risk:Flat-rolled coil supply concentrates among integrated producers in Austria and Germany, limiting negotiating leverage for independent distributors.
- Technical Limitation in Gauge Range:Service center slitting and leveling equipment typically handles 0.4 mm to 25 mm, excluding ultra-thin automotive skin panels and heavy plate for offshore wind.
Strategic Opportunities
- Polish Industrial Expansion:Manufacturing investment in Lower Silesia and Greater Poland regions is outpacing local metal processing capacity.
- EU Green Deal Embedded Carbon Benchmarks:Procurement specifications are filtering toward mills with verified emissions credentials, creating premium positioning for low-carbon distributors.
- Digital Platform Convergence:Inventory management systems are converging with mill production scheduling to match fragmented customer specifications against available coil dimensions.
Industry Challenges
- CNC Programming Talent Scarcity:Precision machining cells require operators capable of translating CAD files into multi-axis toolpaths for medical and aerospace components.
- CE Marking Certification Timelines:EU Construction Products Regulation performance declarations for structural steel create documentation bottlenecks before building project delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Service Centers Market |
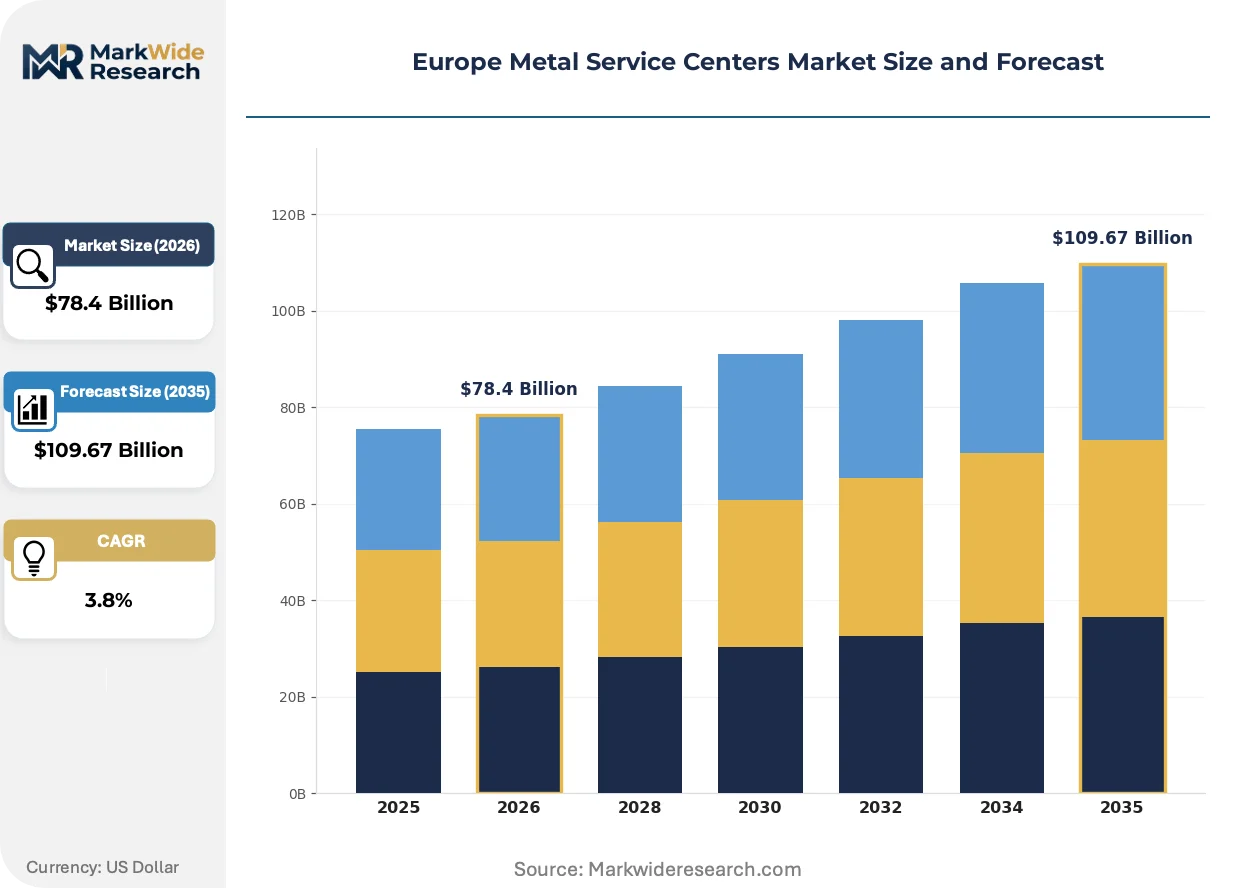
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $109.67 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Carbon Steel, Aluminum, Copper End User: Aerospace, Construction, Automotive, Energy Service Type: Processing, Distribution, Inventory Management, Supply Chain Solutions Technology: Laser Cutting, Plasma Cutting, CNC Machining, Welding |
| Companies Covered | SSAB, Ryerson Holding Corporation, Kloeckner Metals, Russel Metals, Samuel, Son & Co., thyssenkrupp Materials, Reliance Steel & Aluminum Co., VDM Metals, Voestalpine Steel & Service Center, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Service Centers Market Shifts & Advancements
Digital inventory matching platforms are compressing the traditional quote-to-delivery cycle, while processing automation and regulatory carbon tracking reshape how European service centers compete for industrial contracts.
Fiber laser cutting systems with automated material handling are converging with cloud-based nesting software to optimize yield from master coils. Automotive tier-one suppliers in Stuttgart and Wolfsburg are adopting these integrated cells for prototype-to-production workflows. The technology is converging with predictive maintenance algorithms to minimize unplanned downtime during high-volume contract runs.
EU Emissions Trading System cap trajectory revisions are elevating carbon cost pass-through mechanisms in mill pricing. Service centers must now inventory primary metal with embedded emissions liabilities that fluctuate with allowance auction prices. German distributors serving construction and mechanical engineering are restructuring supplier agreements to share carbon price risk.
Consolidated buyer procurement portals are displacing traditional phone-and-fax ordering for standard carbon steel grades. Large manufacturing groups in the Netherlands and Belgium are mandating electronic data interchange for invoice matching and delivery confirmation. This channel shift concentrates volume with service centers offering real-time inventory visibility and API-connected enterprise resource planning integration.
Europe Metal Service Centers Market Segmentation
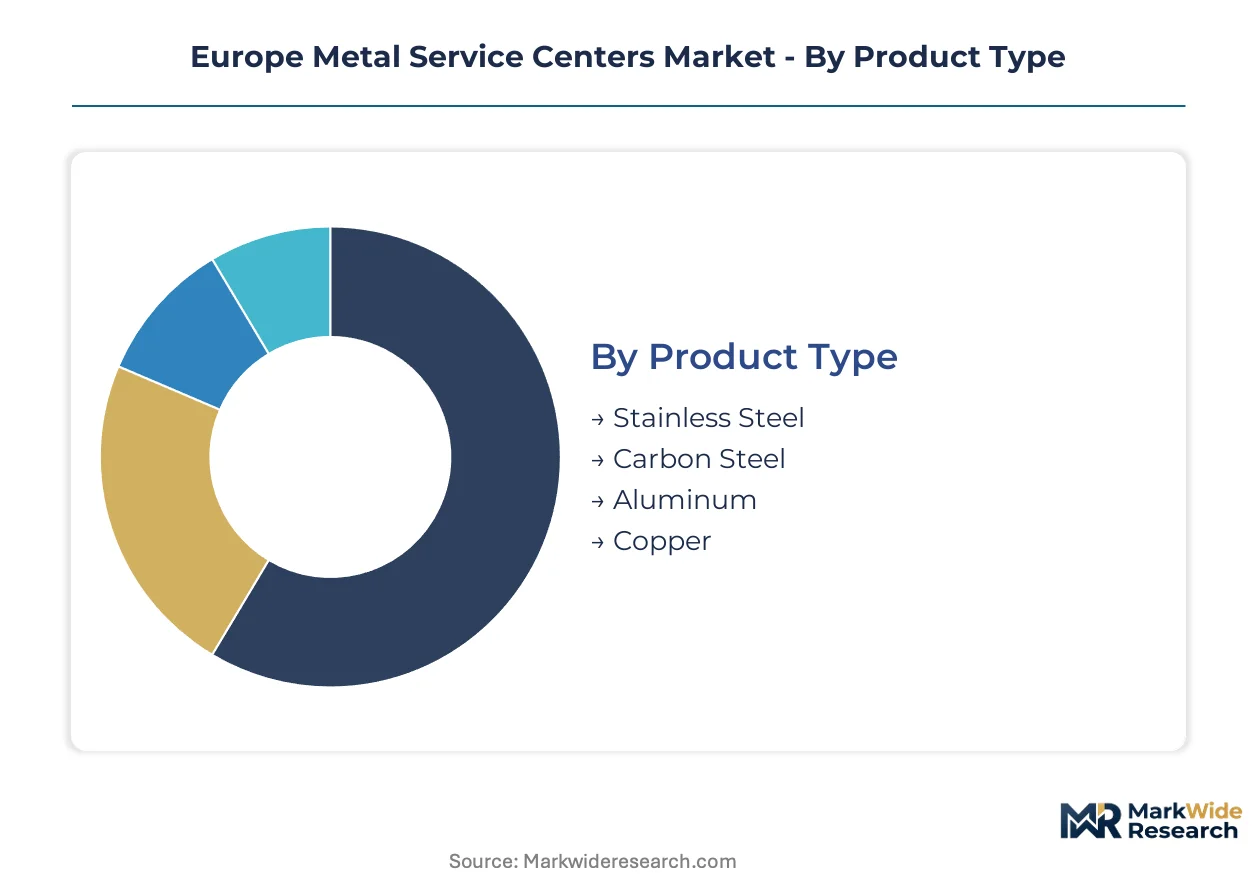
Service centers across Europe configure operations around metal grades, end-use specifications, and processing capabilities. Segmentation reveals where capital deployment concentrates and which customer relationships command premium positioning.
Product Type:
Customization intensity varies sharply across this category, from specification-tolerant carbon grades to alloy-critical aerospace materials.
- Stainless Steel:Austenitic and ferritic grades dominate European inventory, with duplex variants gaining share in chemical processing and marine applications. German pharmaceutical equipment manufacturers and Dutch food processing OEMs anchor demand for surface-finished coils with verified REACH compliance documentation.
- Carbon Steel:Hot-rolled and cold-rolled flat products constitute the volume foundation of European service center operations. Construction activity across Poland and the Czech Republic drives offtake of structural sections and reinforcing bar, though margin compression intensifies amid mill-direct competition on standard grades.
- Aluminum:5xxx and 6xxx series sheets serve automotive lightweighting and building facade applications. Coil anodizing capabilities differentiate regional processors serving Scandinavian architectural markets.
- Copper:Electrolytic tough pitch and phosphorus-deoxidized grades concentrate in electrical and heat exchanger applications. Inventory cycles track closely with German power transmission investment and HVAC manufacturing schedules.
Most installed capacity flows through Carbon Steel. Expansion is steepest in Aluminum.
End User:
Application-driven requirements reshape service center capabilities from commodity distribution to engineered solutions.
- Aerospace:AS9100-certified processing cells handle aluminum-lithium and titanium alloys for wing and fuselage structures. Toulouse and Hamburg manufacturing clusters source precision-machined components with full material traceability and NADCAP surface treatment credentials.
- Automotive:Just-in-time delivery contracts with OEMs and tier-one suppliers mandate sequenced coil supply and blanking operations. High-strength steel processing for electric vehicle battery enclosures commands capital investment in hard-tooling press lines.
- Construction:Structural steel distribution follows project-based procurement with CE marking under EU Construction Products Regulation. Spanish and Italian service centers maintain extensive rebar and merchant bar inventories for infrastructure contractors.
- Energy:Offshore wind tower fabrication demands heavy plate processing beyond typical service center gauge ranges. Nuclear qualification requirements limit viable suppliers for pressure vessel applications.
Automotive relationships generate the highest revenue per ton. Energy applications are climbing the fastest.
Service Type:
Revenue composition shifts from transactional metal sales toward integrated service contracts.
- Processing:Slitting, cut-to-length, and blanking operations transform master coils into customer-specific dimensions. Polish and Romanian centers are adding temper rolling and tension leveling to capture higher-margin automotive specifications.
- Distribution:Stock-and-release programs with consignment inventory reduce working capital burdens for midsize mechanical engineering customers. German distributors leverage Ruhr-based warehouse networks for next-day flat-rolled delivery.
- Inventory Management:Vendor-managed inventory systems integrate with customer ERP platforms for automatic replenishment triggers. Real-time coil location tracking via RFID reduces search time in high-SKU operations.
- Supply Chain Solutions:Milk-run logistics and cross-docking consolidate multi-mill sourcing into single-point delivery. Integrated offerings are displacing pure distribution on contracts above five thousand tons annually.
Distribution still handles the greatest tonnage. Supply Chain Solutions are gaining share fastest.
Technology:
Capital allocation across processing technologies reflects the tradeoff between throughput and geometric complexity.
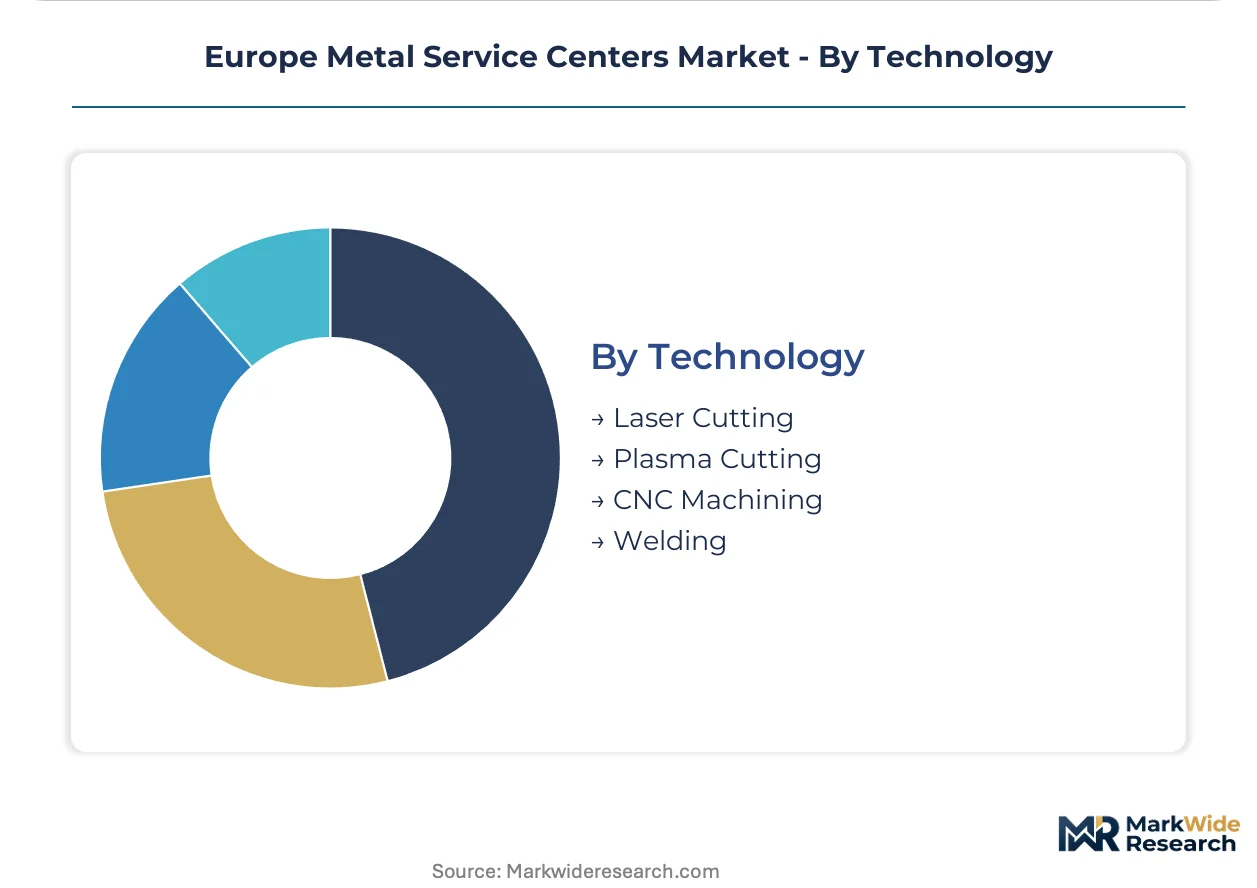
- Laser Cutting:Fiber laser systems with automated material handling dominate new equipment investment. Stuttgart-area automotive prototype shops specify these cells for rapid nesting optimization and minimal heat-affected zones on advanced high-strength steels.
- CNC Machining:Multi-axis milling and turning centers serve medical device and precision engineering customers with tight tolerance requirements. Programming talent scarcity constrains capacity expansion across the German industrial corridor.
- Plasma Cutting:High-definition plasma remains cost-competitive for thick plate and structural sections where edge quality requirements permit. Shipyards in Gdansk and Split source bevel-cut plate through regional processors.
- Welding:Robotic MIG and TIG cells add fabricated assemblies to component supply portfolios. CE marking compliance for welded structures requires certified welding procedure specifications and operator qualifications.
Laser Cutting commands the largest share of recent capital expenditure. CNC Machining delivers the highest margin per processing hour.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled CNC programming talent concentrates in the German industrial corridor, anchoring precision processing capabilities that radiate across Central European supply chains.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive just-in-time aluminum and high-strength steel sourcing. REACH compliance administered by ECHA governs chemical composition disclosures for coated metals entering the single market. The Ruhr-to-Bavaria industrial belt hosts the densest concentration of fiber laser cutting and CNC machining capacity.
Poland
Manufacturing investment in Lower Silesia and Greater Poland outpaces local metal processing infrastructure. The EU Carbon Border Adjustment Mechanism recalibrates procurement economics toward domestic and near-shore mill relationships. Automotive suppliers in Wrocław and Poznań are expanding contract volumes with regional service centers for sequenced coil delivery.
France
Aerospace manufacturers in Toulouse source AS9100-certified aluminum-lithium and titanium alloy processing. CE marking under the EU Construction Products Regulation mandates performance declarations for structural steel entering building applications. Lyon and Grenoble precision engineering clusters demand tight-tolerance CNC machining for medical device components.
Italy
Infrastructure contractors drive offtake of structural sections and reinforcing bar for construction projects. The EU Green Deal's embedded carbon benchmarks filter procurement specifications toward mills with verified emissions credentials. Milan and Turin service centers maintain extensive stainless steel inventories for pharmaceutical equipment and food processing OEMs.
Netherlands
Large manufacturing groups mandate electronic data interchange for invoice matching and delivery confirmation. ECHA-administered RoHS restrictions govern substance thresholds in electrical and heat exchanger applications. Rotterdam and Eindhoven distributors leverage real-time inventory visibility and API-connected ERP integration to capture consolidated buyer procurement portal volumes.
Europe Metal Service Centers Market Competitive Landscape
The competitive structure tilts toward integrated mill-captive distributors and independent multi-site processors. Independent service centers compete on processing specialization and geographic density, while mill-affiliated operations leverage captive supply security. Three archetypes dominate: integrated steel mill service divisions, independent multi-metal distributors with digital platforms, and regional specialists in aerospace or automotive certification tiers. Consolidation through bolt-on acquisitions and capacity expansion in Polish and Southeast European markets represent the dominant competitive moves.
Among integrated mill-affiliated operators, Voestalpine Steel & Service Center and thyssenkrupp Materials exemplify the captive supply archetype, anchoring positions through upstream mill relationships. Kloeckner Metals occupies a position within the independent distributor tier, representing digital platform convergence across fragmented European specifications.
| Leading Market Players |
|---|
| SSAB |
| Ryerson Holding Corporation |
| Kloeckner Metals |
| Russel Metals |
| Samuel, Son & Co. |
| thyssenkrupp Materials |
| Reliance Steel & Aluminum Co. |
| VDM Metals |
| Voestalpine Steel & Service Center |
| Others |
Supply & Pricing Matrix
Hot-rolled coil index settlements in Northwest Europe cascade through three distinct pricing tiers as service centers bundle processing, logistics, and inventory management into consolidated contracts. Mill concentration in Austria and Germany compresses negotiating leverage for independent distributors while amplifying carbon cost pass-through from EU ETS allowance auctions.
Pricing Analysis
Bundled service contracts versus unbundled metal-only transactions define the dominant pricing split across European service centers. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace processing from commodity carbon steel distribution and spot-market salvage. Price differentiation hinges on REACH documentation depth and CE marking certification status. Cost compression in standard-grade flat-rolled products is intensifying because mill-direct competition on construction specifications erodes distributor margins. Automotive OEMs demonstrate lowest price sensitivity due to just-in-time delivery penalties, while general mechanical engineering buyers prioritize landed cost above certification tier.
Supply Chain Analysis
Single-source vulnerability sits with Austrian integrated mills supplying captive service center networks across Central Europe. Geographic supply concentration centers on Germany, Austria, and Poland for flat-rolled coil, with Italian and Spanish mills serving southern demand corridors. Raw material flows draw from Turkish scrap export markets, Ukrainian semi-finished slab, and domestic electric arc furnace output. Tariff exposure through the EU Carbon Border Adjustment Mechanism threatens cost competitiveness of non-EU sourced aluminum and steel. Distribution runs through hub-and-spoke warehouse networks anchored in the Ruhr industrial belt, with regional satellites in Poznań and Wrocław serving Polish manufacturing expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
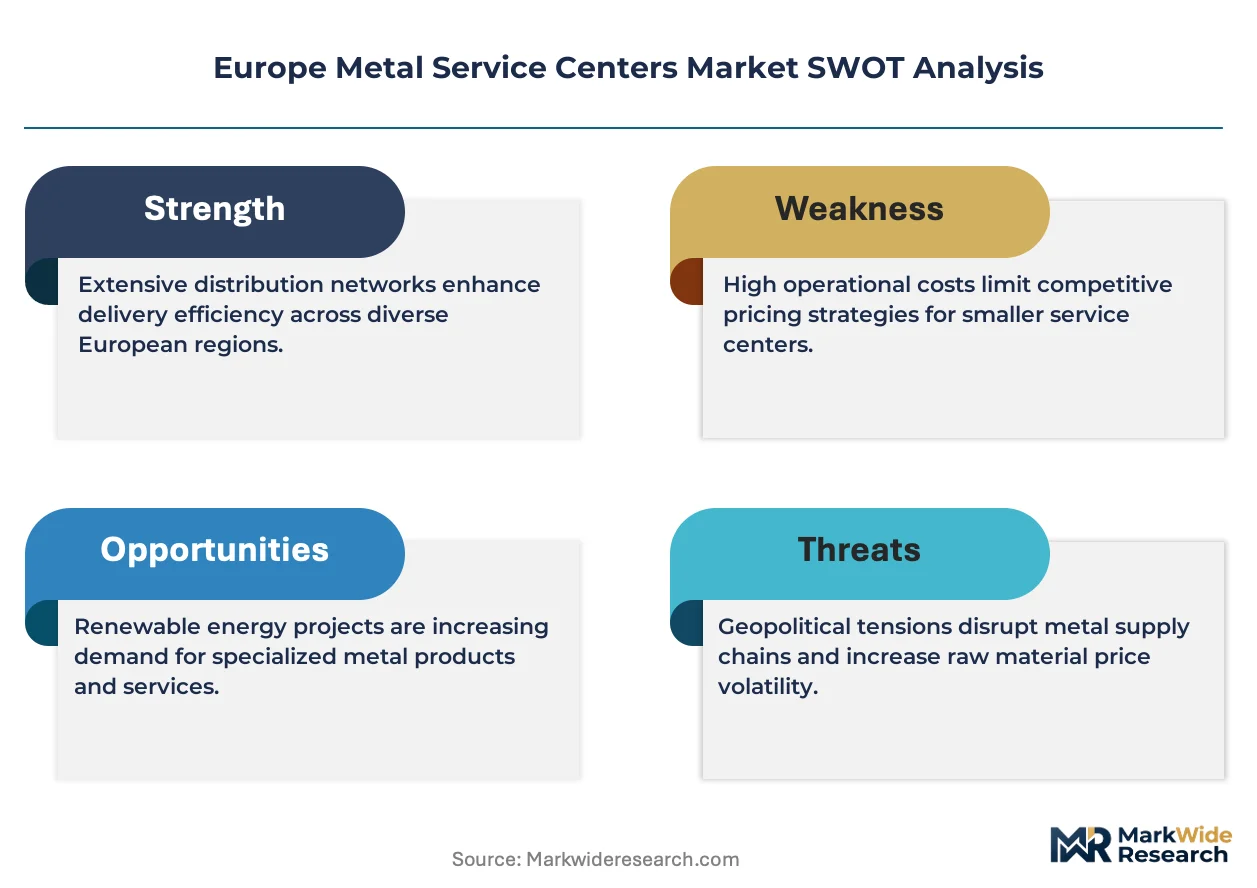
This market functions as a geographic-arbitrage play between Polish manufacturing cost advantages and German regulatory compliance premiums, with the EU Carbon Border Adjustment Mechanism widening the effective cost differential between near-shore and distant supply origins.
For Market Incumbents: Acquire Polish processing capacity to capture automotive supplier migration into Lower Silesia and Greater Poland. Consolidate regional service center networks to defend against mill-direct competition on standard carbon grades. Invest in fiber laser cutting cells with automated material handling to maintain differentiation against price-focused distributors. CE marking certification capabilities represent a critical defensive lever as EU Construction Products Regulation enforcement tightens.
For New Entrants and Emerging Players: API-connected inventory visibility platforms offer the lowest-friction entry path for midsize mechanical engineering accounts displaced by consolidated procurement portals. Target aerospace-tier processing in Toulouse and Hamburg clusters where AS9100 and NADCAP credentials create artificial supply scarcity. Establish vendor-managed inventory systems with automatic replenishment triggers as the primary go-to-market wedge against legacy phone-and-fax distributors.
For Investors and Strategic Acquirers: Asymmetric upside sits with independent multi-metal distributors possessing digital platform infrastructure and cross-border specification-matching capabilities. The five-to-ten year viability window favors operators with demonstrated carbon accounting systems as EU Green Deal embedded carbon benchmarks harden into procurement requirements. Acquisition targets should display integrated processing capabilities rather than pure distribution footprints. The signal to watch is EU ETS cap trajectory announcements, which reshape inventory valuation models and carbon liability allocation between mills and service centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Processing | Captive slitting and leveling capacity insulates margin from mill-direct competition on standard grades. |
| Digital Platform Convergence | Real-time inventory matching compresses quote-to-delivery cycles for fragmented automotive specifications. |
| Green Certification Program | Verified low-carbon metal sourcing commands premium positioning under EU Green Deal procurement filters. |
| Geographic Expansion into Poland | Lower Silesia and Greater Poland manufacturing investment outpaces local metal processing infrastructure. |
| Long-term Supply Agreement | Carbon price risk-sharing contracts with Austrian and German mills stabilize input cost volatility. |
Research Methodology
Coverage spans Germany, Poland, France, Italy, and the Netherlands, with primary inputs from each market informing cross-border pattern identification. The analysis combines structured interviews with service center operations directors, automotive tier-one procurement managers, and ECHA regulatory compliance officers with secondary validation from EU trade statistics, mill production disclosures, and national construction activity indices. Bottom-up capacity utilization surveys triangulate against top-down metal consumption forecasts across end-use segments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including metal grade tier, end-use industry vertical, processing technology intensity, and regional regulatory cluster. CAGRs derive from installed capacity expansion schedules, automotive production platform mix shifts, and EU ETS carbon price scenario bands. Industry-specific forecast inputs incorporate REACH compliance timeline acceleration and fiber laser equipment deployment rates in the Ruhr-to-Bavaria corridor.
The model assumes a particular technology adoption path for automated nesting software and predictive maintenance algorithms; alternative pathways for cloud-based inventory matching would alter the outlook for independent distributor competitive positioning. Forecasts reflect assumptions regarding EU Carbon Border Adjustment Mechanism implementation scope and electric vehicle production mix trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Zinc Dust Market
Metals
Molybdenum Market
Metals
Europe Aluminium Cans Market
Metals
Silver Cyanide Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
High Purity Base Metals Market
Metals
Copper Powder Market
Metals
Cold Drawn Wire Market
Metals
High Purity Boron Market
Metals
US Metal Fabrication Market
Metals
Amorphous Metal Cores Market
Metals
Ferrite Market
Metals
Aluminum Slugs Market
Metals
Aluminum Casting Market
Metals
Palladium Market
Metals
Global Duplex Stainless Steel Market