
 Bearing Steel Market | 2026-2036
Bearing Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Bearing Steel Market Insights
Advanced vacuum degassing and ladle metallurgy is reconfiguring cleanliness benchmarks for bearing steels used in critical rotating machinery. SKF Group leverages in-house steel qualification protocols to secure supply chain reliability for its bearing operations across European manufacturing hubs. Nippon Steel Corporation anchors premium-grade output through integrated blast furnace-to-bar production at its Japanese coastal facilities. Tata Steel competes on cost-optimized carbon and manganese grades serving heavy machinery builders in South Asia.
Bearing steel is an ultra-clean alloy steel, typically containing chromium in the range of 1.0-1.5 percent with controlled oxygen levels below 10 ppm, engineered to withstand cyclic contact stresses exceeding 2,000 MPa in rolling-element bearings. Chrome steel remains the dominant product type due to its established fatigue life performance in automotive and industrial bearings, while stainless steel grades gain traction in food processing and medical equipment where corrosion resistance overrides cost considerations. Aerospace assemblies represent a concentrated margin pool within the application landscape, as AS9100-certified material commands substantial premiums over standard bearing grades for commercial aircraft producers.
Japan's METI enforces JIS standards that mandate inclusion ratings and microstructural uniformity for bearing steels supplied to domestic precision engineering firms. China's SAMR administers GB standards that increasingly align with ISO 683-17 specifications, raising barriers for uncertified imports into the country's vehicle assembler supply chains. India's BIS certification requirements for alloy steels used in railway and wind energy applications are expanding testing obligations for domestic mills. Stakeholders must monitor how carbon border adjustment mechanisms and evolving alloy scrap availability reshape raw material sourcing economics for bearing steel production.
Market Dynamics
Advanced vacuum degassing and ladle metallurgy is reconfiguring cleanliness benchmarks for bearing steels used in critical rotating machinery. SKF Group leverages in-house steel qualification protocols to secure supply chain reliability for its bearing operations across European manufacturing hubs. Nippon Steel Corporation anchors premium-grade output through integrated blast furnace-to-bar production at its Japanese coastal facilities. Tata Steel competes on cost-optimized carbon and manganese grades serving heavy machinery builders in South Asia.
Growth Catalysts
- Wind turbine OEM procurement:Manufacturers of multi-megawatt turbines are expanding orders for large-diameter bearing rings requiring ultra-clean steel grades. This demand concentrates in Germany's industrial corridor around Schweinfurt.
- EU F-Gas Regulation:Tightened cleanliness requirements for steel used in precision rotating equipment are accelerating qualification protocols across European supply chains. The regulation mandates specific inclusion ratings for compressor bearings.
- China's GB standards alignment:SAMR-administered specifications increasingly mirror ISO 683-17, raising entry barriers for uncertified imports into vehicle assembler supply chains.
Market Restraints
- Alloy scrap availability constraints:Volatile chromium and molybdenum scrap flows from stainless steel recycling disrupt raw material sourcing economics for electric arc furnace producers.
- Supply concentration risk:Premium bearing steel production clusters among integrated blast furnace operators in Japan and Germany, limiting buyer leverage during capacity tightness.
- Ceramic bearing substitution:Silicon nitride rolling elements displace steel in high-speed spindle applications above 30,000 RPM, compressing addressable volume in precision machining.
Strategic Opportunities
- India's wind energy certification expansion:BIS testing obligations for alloy steels used in renewable energy applications create captive demand for domestic mills with metallurgical laboratory investments.
- Carbon border adjustment mechanisms:The EU's CBAM creates preferential positioning for low-carbon-intensity steel producers with hydrogen-reduction pilot operations.
- Medical equipment corrosion resistance:Stainless steel grades gain traction in surgical robotics and imaging equipment where 440C and nitrogen-alloyed martensitic grades command performance premiums.
Industry Challenges
- AS9100 certification timelines:Aerospace material qualification requires 18-24 month validation cycles for bearing steels, locking out non-integrated suppliers from commercial aircraft programs.
- Vacuum arc remelt capacity scarcity:Triple-melt capability for the cleanest bearing grades remains concentrated among specialty steel forgers with limited expansion announcements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bearing Steel Market |
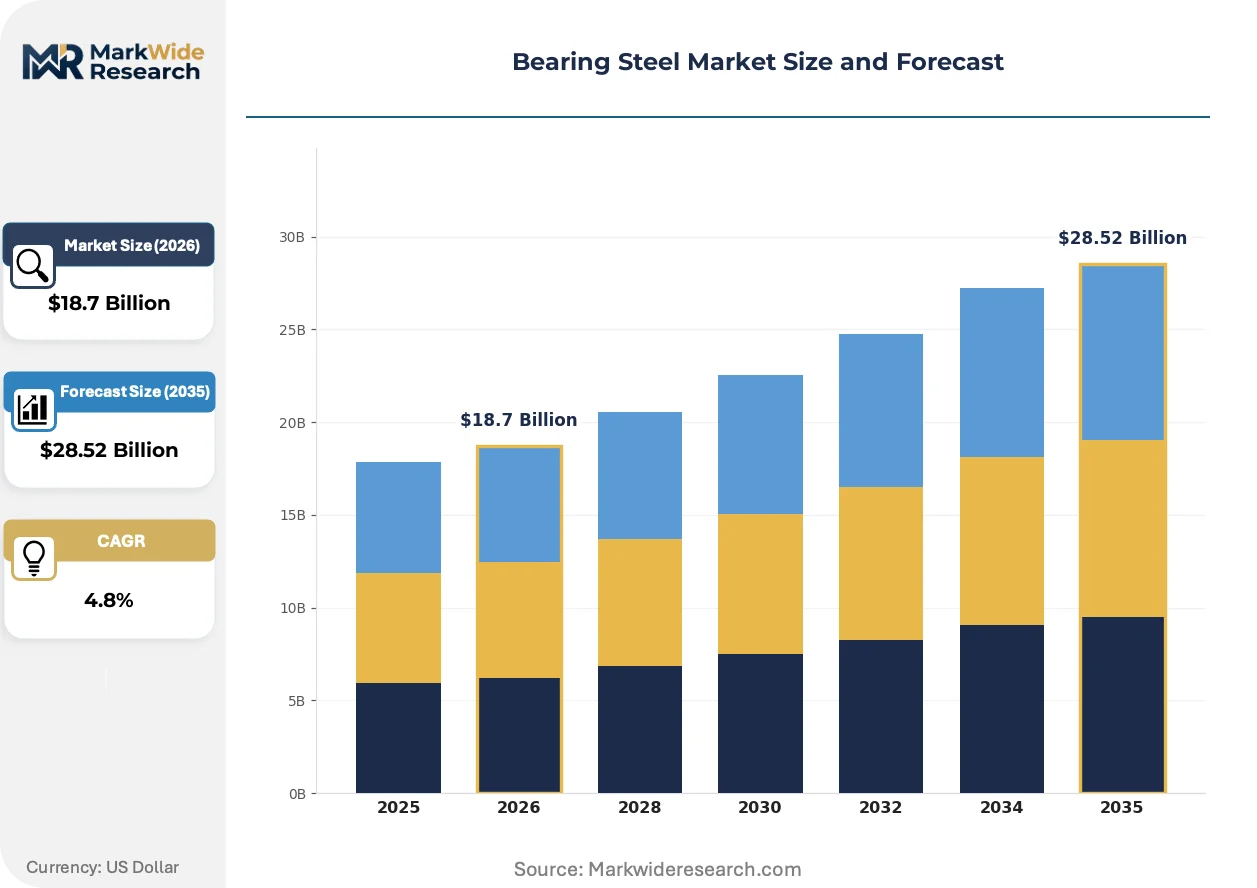
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chrome Steel, Stainless Steel, Carbon Steel, Manganese Steel, High-Speed Steel Application: Power Transmission, Machinery Components, Bearings, Automotive Components, Aerospace Assemblies End User Industry: Heavy Machinery Manufacturers, Vehicle Assemblers, Aircraft Producers, Electrical Equipment Makers, Precision Engineering Firms Form: Bars, Sheets, Rings, Wire, Forged Components |
| Companies Covered | SKF Group, The Timken Company, JTEKT Corporation, Nippon Steel Corporation, Schaeffler Group, Ovako Group, Tata Steel, Baosteel, NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bearing Steel Market Trends and Innovations
Vacuum degassing protocols and predictive metallurgy software are compressing development cycles for next-generation bearing alloys. These advances enable tighter oxygen control and inclusion management than conventional ladle refining permits.
Electroslag remelting is hybridizing with conventional vacuum arc remelting in premium bearing steel production. Japanese precision engineering firms are adopting this dual-melt approach for main shaft bearings in large-scale industrial gearboxes. The technology is compressing lead times for certified material while maintaining fatigue life performance above 2,000 MPa contact stress thresholds.
China's GB standards administered by SAMR are tightening inclusion rating requirements for bearing steels supplied to domestic electric vehicle powertrain manufacturers. The regulation mandates automated ultrasonic testing protocols that exceed prior sampling inspection norms. European bearing OEMs with established Chinese joint ventures are accelerating local laboratory certification to maintain supply chain access.
Consolidated procurement by wind turbine OEMs is compressing supplier qualification cycles from 24 months to 12 months for bearing steel mills. Tier-1 turbine manufacturers in Denmark and Germany now mandate direct mill relationships rather than distributor intermediation for critical ring forgings. This behavioral shift concentrates volume among integrated producers with in-house forging capability.
Bearing Steel Market Segmentation
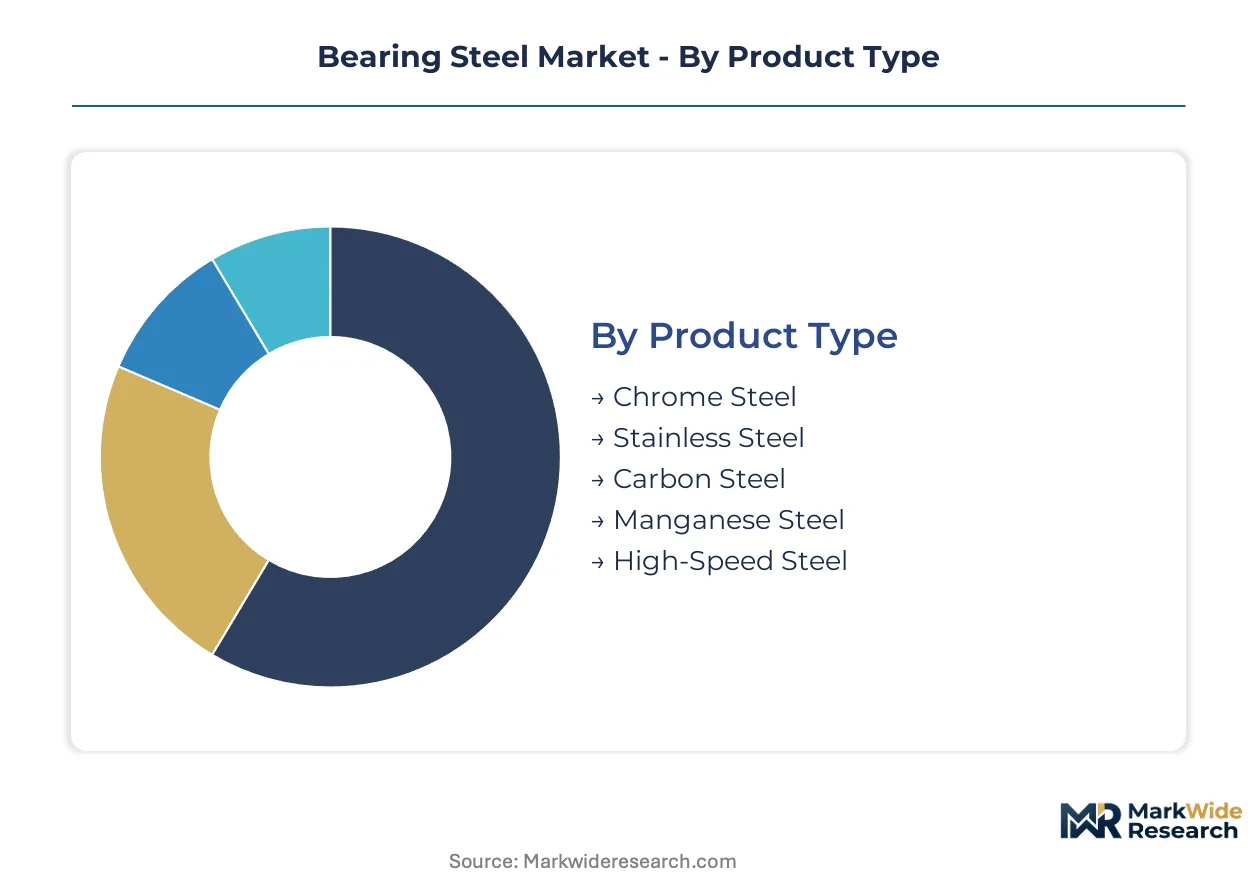
Bearing steel segmentation reveals how metallurgical specifications align with stress thresholds and regulatory environments across rotating machinery applications. Product chemistry, component geometry, and end-use certification requirements create distinct commercial corridors with divergent margin structures.
Product Type:
Cost tier differentiation separates commodity carbon grades from vacuum-remelted specialty alloys with inclusion-controlled microstructures.
- Chrome Steel:Chromium content of 1.0-1.5 percent delivers fatigue life performance above 2,000 MPa contact stress in rolling-element bearings. Demand concentrates in Germany's Schweinfurt industrial corridor where SKF and Schaeffler operations source ultra-clean grades for automotive and industrial bearing production.
- Stainless Steel:Martensitic 440C and nitrogen-alloyed grades provide corrosion resistance for food processing and surgical robotics applications. Japan's METI-administered JIS standards mandate inclusion ratings that favor domestic mill supply to precision engineering firms in Osaka and Nagoya manufacturing zones.
- Carbon Steel:Cost-optimized grades serve heavy machinery builders in South Asia with less stringent cleanliness requirements than rotating equipment applications.
- Manganese Steel:Work-hardening characteristics suit impact-loaded components in mining and construction equipment where fatigue life specifications are relaxed.
- High-Speed Steel:Tungsten and molybdenum additions enable cutting tool applications with secondary bearing component use in machine tool spindles.
Chrome steel holds installed capacity. Stainless steel is rotating up the share rankings.
Application:
Application segmentation tracks how contact stress magnitude and duty cycle intensity dictate alloy selection and certification depth.
- Power Transmission:Gearbox main shaft bearings require vacuum-degassed grades with oxygen levels below 10 ppm to withstand cyclic loading in wind turbine drivetrains. Procurement from Danish and German turbine OEMs now mandates direct mill relationships rather than distributor channels.
- Aerospace Assemblies:AS9100-certified material commands substantial premiums over standard bearing grades for commercial aircraft producers. Qualification cycles of 18-24 months lock out non-integrated suppliers from Boeing and Airbus supply chains.
- Machinery Components:General industrial bearings operate at moderate stress levels where conventional ladle-refined grades satisfy performance thresholds.
- Bearings:Standard rolling-element applications span automotive wheel hubs to electric motor shafts with tiered cleanliness specifications.
- Automotive Components:Vehicle assembler supply chains in China require GB standard alignment with ISO 683-17 specifications administered by SAMR.
Power transmission commands volume concentration. Aerospace assemblies capture margin expansion.
End User Industry:
Customer type segmentation reflects how certification burden and volume scale create divergent procurement leverage.
- Heavy Machinery Manufacturers:Cost-optimized carbon and manganese grades from Tata Steel serve construction and mining equipment builders with less stringent inclusion rating requirements than precision applications.
- Aircraft Producers:Boeing and Airbus tier-1 suppliers require triple-melt capability concentrated among Japanese and German specialty steel forgers with limited expansion announcements.
- Vehicle Assemblers:Electric vehicle powertrain manufacturers in China face tightening GB standards with automated ultrasonic testing protocols exceeding prior sampling inspection norms.
- Electrical Equipment Makers:Motor and generator bearings operate at moderate speeds where conventional cleanliness grades suffice.
- Precision Engineering Firms:Japanese manufacturers in Osaka and Nagoya zones source JIS-certified material with mandated microstructural uniformity.
Heavy machinery manufacturers anchor volume demand. Aircraft producers enforce the steepest certification barriers.
Form:
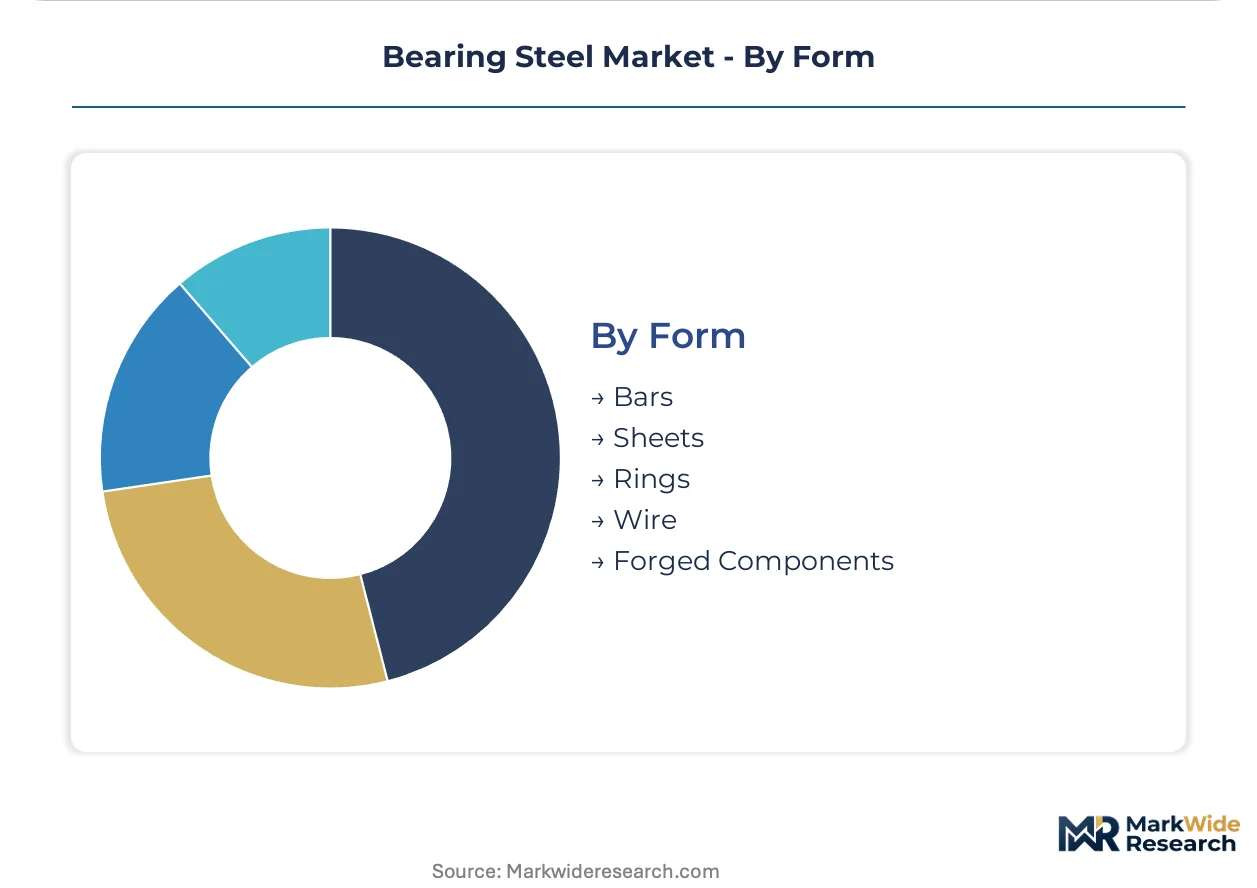
Geometry segmentation determines how downstream processing requirements influence mill product mix and forging investments.
- Rings:Large-diameter bearing rings for multi-megawatt wind turbines require integrated forging capability at mills supplying Germany's Schweinfurt cluster. Consolidated OEM procurement has compressed supplier qualification cycles from 24 months to 12 months.
- Forged Components:Direct mill relationships with turbine OEMs in Denmark and Germany bypass distributor intermediation for critical ring forgings.
- Bars:Long products feed machining centers producing bearing races and rolling elements with standardized dimensional tolerances.
- Sheets:Flat products serve limited bearing applications including thrust washer manufacture.
- Wire:Rod and wire forms supply ball and roller production with specialized spheroidizing heat treatment requirements.
Rings concentrate forging capacity investment. Forged components are climbing the fastest in procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wind turbine OEMs and precision engineering firms concentrate procurement leverage in specific industrial corridors. Bearing steel demand clusters where rotating equipment manufacturers maintain captive forging relationships with specialty mills.
Germany
Schaeffler and SKF operations in the Schweinfurt industrial corridor source ultra-clean chrome steel grades for automotive and industrial bearing production. The EU's F-Gas Regulation mandates specific inclusion ratings for compressor bearings used in precision rotating equipment. Vacuum arc remelt capacity for aerospace-grade material concentrates among specialty steel forgers in Baden-Württemberg and North Rhine-Westphalia.
China
Electric vehicle powertrain manufacturers are expanding orders for GB-certified bearing steels as domestic vehicle assembler supply chains scale production. SAMR-administered GB standards increasingly align with ISO 683-17 specifications, raising barriers for uncertified imports. Automated ultrasonic testing protocols now exceed prior sampling inspection norms for mills supplying the Yangtze River Delta manufacturing zones.
Japan
Precision engineering firms in Osaka and Nagoya manufacturing zones source JIS-certified material with mandated microstructural uniformity for main shaft bearings. METI-enforced JIS standards control inclusion ratings and cleanliness benchmarks for domestic bearing steel supply. Nippon Steel Corporation anchors premium-grade output through integrated blast furnace-to-bar production at coastal facilities serving Kanto and Kansai industrial corridors.
India
Wind energy OEMs are driving BIS certification requirements for alloy steels used in multi-megawatt turbine drivetrains. The central government's renewable energy targets are expanding testing obligations for domestic mills with metallurgical laboratory investments. Tata Steel competes on cost-optimized carbon and manganese grades serving heavy machinery builders in Maharashtra and Gujarat industrial zones.
United States
Aerospace tier-1 suppliers require AS9100-certified bearing steels for commercial aircraft programs with 18-24 month qualification cycles. The Timken Company leverages in-house steel qualification protocols to secure supply chain reliability for bearing operations across Midwest manufacturing hubs. FAA oversight of commercial aircraft material traceability reinforces concentration among integrated producers with triple-melt capability.
Bearing Steel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification requirements. The market structure separates integrated blast furnace operators with captive forging capability from electric arc furnace producers dependent on alloy scrap flows. Three archetypes dominate: premium-grade specialists with vacuum remelt capacity, cost-optimized carbon steel producers serving heavy machinery, and bearing OEMs with backward integration into steel qualification. Competitive moves center on direct mill relationships with wind turbine OEMs and accelerated laboratory certification for Chinese joint ventures.
Among European integrated producers, Ovako Group and Schaeffler Group exemplify the premium-grade specialist archetype with concentration in Germany's industrial corridor. SKF Group occupies a position as a bearing OEM with in-house steel qualification protocols securing supply chain reliability. These three entities represent distinct strategic postures: mill-based forging integration, component manufacturing scale, and channel-controlled procurement leverage.
| Leading Market Players |
|---|
| SKF Group |
| The Timken Company |
| JTEKT Corporation |
| Nippon Steel Corporation |
| Schaeffler Group |
| Ovako Group |
| Tata Steel |
| Baosteel |
| NSK Ltd. |
| Others |
Pricing and Supply Chain Analysis
Integrated blast furnace operators in Japan and Germany anchor premium-grade bearing steel supply, capturing margin pools in aerospace AS9100-certified material and wind turbine ring forgings where triple-melt capacity scarcity limits buyer leverage. Cost-optimized electric arc furnace producers in South Asia compete on carbon and manganese grades for heavy machinery, feeding a bifurcated pricing landscape shaped by metallurgical cleanliness tiers.
Pricing Analysis
Long-term offtake contracts with London Metal Exchange-linked indexation for chromium and molybdenum feedstocks dominate procurement between wind turbine OEMs and integrated mills. Three-tier pricing structure across vacuum-remelted aerospace grades, ladle-refined industrial bearings, and carbon steel heavy machinery segments reflects oxygen-level thresholds and certification depth. Cost compression in standard industrial grades is intensifying because consolidated procurement by Danish and German turbine manufacturers compresses supplier margins. Heavy machinery builders in South Asia exhibit highest price sensitivity, while aircraft producers accept substantial premiums for AS9100-qualified material with 18-24 month validation cycles.
Supply Chain Analysis
Specialty steel forgers in Germany, Japan, and Sweden hold concentrated vacuum arc remelt and electroslag remelting capacity for ultra-clean bearing grades. Raw material sourcing draws from volatile chromium and molybdenum scrap flows from stainless steel recycling, plus virgin alloy additions from South African and Kazakh mining operations. Single-source vulnerability concentrates in triple-melt capability for aerospace bearings, where limited expansion announcements lock out new entrants. Distribution runs through direct mill relationships mandated by Tier-1 wind turbine OEMs, bypassing traditional distributor channels for critical ring forgings.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metallurgical testing and certification services represent a service-attach opportunity expanding faster than commodity steel volume, as BIS, SAMR, and METI mandates multiply laboratory validation requirements across wind energy and electric vehicle supply chains.
For Market Incumbents: Pre-empt ceramic bearing substitution in high-speed spindle applications above 30,000 RPM by accelerating nitrogen-alloyed martensitic grade development for surgical robotics and imaging equipment. Capture hydrogen-reduction pilot positioning ahead of EU CBAM implementation to secure preferential carbon-intensity ratings. Defensive consolidation around vacuum arc remelt capacity in Baden-Württemberg and North Rhine-Westphalia reinforces scarcity value against emerging Asian competitors. For New Entrants and Emerging Players: Build out BIS-certified metallurgical laboratory infrastructure in Maharashtra and Gujarat industrial zones to serve India's expanding wind energy certification requirements. Target captive demand from domestic mills lacking in-house testing capability for alloy steels in multi-megawatt turbine drivetrains. Partner with European bearing OEMs' Chinese joint ventures to accelerate local GB standard qualification and bypass 24-month import validation timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum remelt capacity expansions as electroslag hybridization and predictive metallurgy software compress development cycles. Long-term viability favors integrated producers with captive forging capability and direct OEM relationships over electric arc furnace operators exposed to alloy scrap volatility. Monitor qualification cycle compression from 24 months to 12 months for wind turbine ring forgings as the signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Qualification | SKF and Timken in-house protocols secure supply chain reliability against mill concentration risk. |
| Vacuum Arc Remelt Capacity Expansion | Japanese coastal facilities anchor premium-grade output for METI-mandated JIS certification compliance. |
| Electroslag Hybridization Investment | Dual-melt approach compresses lead times for Osaka and Nagoya precision engineering firms. |
| Direct Mill Relationship Mandates | Danish and German turbine OEMs bypass distributors to concentrate volume among integrated forgers. |
| Localized Laboratory Certification | European bearing OEMs accelerate Chinese joint venture testing to maintain SAMR-administered GB standard access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed steel producers, JIS and GB standard documentation, and wind turbine OEM procurement disclosures. Primary interviews engaged metallurgical laboratory directors, bearing OEM procurement leads, specialty steel forge operators, and wind energy project developers across Germany, Japan, China, and India. Bottom-up volume modeling triangulates against top-down alloy consumption estimates from national steel association reports.
Forecast inputs span product chemistry tiers, component geometry specifications, end-use certification requirements, and regional regulatory cluster alignment with ISO 683-17. Segmentation dimensions include chrome versus stainless versus carbon steel grades, ring versus bar versus wire forms, and aerospace versus power transmission versus automotive applications. CAGRs derive from elasticity-adjusted demand projections for wind turbine installations and electric vehicle powertrain scaling across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese integrated mills or accelerated ceramic bearing substitution would shift outcomes. Quarterly review of vacuum arc remelt utilization rates, alloy scrap price volatility indices, and OEM qualification cycle durations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High Purity Base Metals Market
Metals
Colloidal Metal Particles Market
Metals
Amorphous Metal Cores Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Stainless Steel Sheet Market
Metals
Steel Casting Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Powder Metallurgy Market
Metals
Galvanizing Market
Metals
Silver Nitrate Market
Metals
Magnesium Metal Market
Metals
Rubidium Market
Metals
GCC Aluminium Powder Market
Metals
Metallic Rope Cords Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market