
 GCC Metal Forging Market | 2026-2036
GCC Metal Forging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Metal Forging Market Intelligence
Market Context
The GCC metal forging sector is pivoting on a widening gap between aerospace-grade precision output and commodity construction forgings. Precision Metal Industries FZC leverages its Jebel Ali base to dominate closed-die work for oilfield equipment. Doosan Corporation anchors regional energy demand through heavy forging capacity tied to power plant and desalination projects. AL NASR FORGING differentiates via long-standing relationships with Saudi Aramco and petrochemical contractors.
Technical Definition and Segment Structure
Metal forging in the GCC context involves shaping metal through localized compressive forces, typically at temperatures between 950°C and 1250°C for carbon steels, to achieve grain flow alignment and fatigue resistance superior to cast or machined equivalents. Closed die forging commands the deepest margin pools due to tooling complexity and aerospace qualification barriers, while open die forging sustains volume leadership through energy and construction offtake. Steel retains material dominance across the GCC, though titanium competes aggressively in Saudi defense and UAE aerospace channels. Energy end users occupy the largest demand block, but automotive applications are gaining structural weight as electric vehicle supply chains seek localized axle and gear production.
Regulatory Environment
Saudi Standards, Metrology and Quality Organization (SASO) and Emirates Authority for Standardization and Metrology (ESMA) enforce material traceability and mechanical testing protocols that filter out uncertified suppliers. The Gulf Standardization Organization (GSO) harmonizes technical regulations across member states, reducing cross-border compliance friction but raising baseline quality thresholds. Stakeholders must monitor how Saudi Arabia's local content mandates and the UAE's in-country value programs redirect procurement toward domestic forging capacity rather than established Asian supply lines.
Market Dynamics
Aerospace procurement from Gulf carriers is compressing supplier qualification timelines while SABIC certification requirements force Saudi-based forgers to absorb tooling costs faster than regional peers can replicate.
Growth Catalysts
- Defense localization mandates:Saudi Arabia's Vision 2030 military industrial targets redirect titanium and superalloy forging contracts toward domestic closed-die specialists, bypassing traditional European supply channels.
- ESMA traceability protocols:Emirates Authority for Standardization and Metrology enforcement of material origin documentation filters out uncertified Asian competitors, consolidating UAE-based forging capacity.
- Jebel Ali corridor clustering:Concentration of oilfield equipment procurement offices within Dubai's industrial zone creates captive demand pools for precision-forged wellhead components.
Market Restraints
- Scrap steel price volatility:GCC forgers remain exposed to Turkish and Indian scrap export fluctuations, compressing margin buffers on commodity-grade construction forgings.
- Asian supply concentration:Chinese and South Korean closed-die specialists retain cost advantages on sub-50kg precision components, limiting GCC penetration in automotive tier-two supply chains.
- Titanium billet import dependency:Regional aerospace forgers lack domestic sponge or ingot capacity, forcing reliance on US and Russian feedstock subject to export licensing friction.
Strategic Opportunities
- Qatar North Field expansion:Unprecedented offshore platform construction creates demand for large-diameter forged flanges and subsea connectors beyond current regional heavy-forging capacity.
- Electric vehicle axle localization:Saudi and UAE automotive assembly investments require localized gear blank and driveshaft forging to satisfy in-country value thresholds.
- Closed-die robotics integration:Convergence of automated die handling with predictive thermal monitoring enables GCC forgers to compress aerospace qualification cycles.
Industry Challenges
- NADCAP heat treatment certification:Aerospace forgers face 18-24 month accreditation timelines for specialized furnace controls, delaying contract awards.
- Die steel inventory carrying costs:Tooling-grade H13 and premium-grade materials require substantial working capital commitments before first article approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Metal Forging Market |
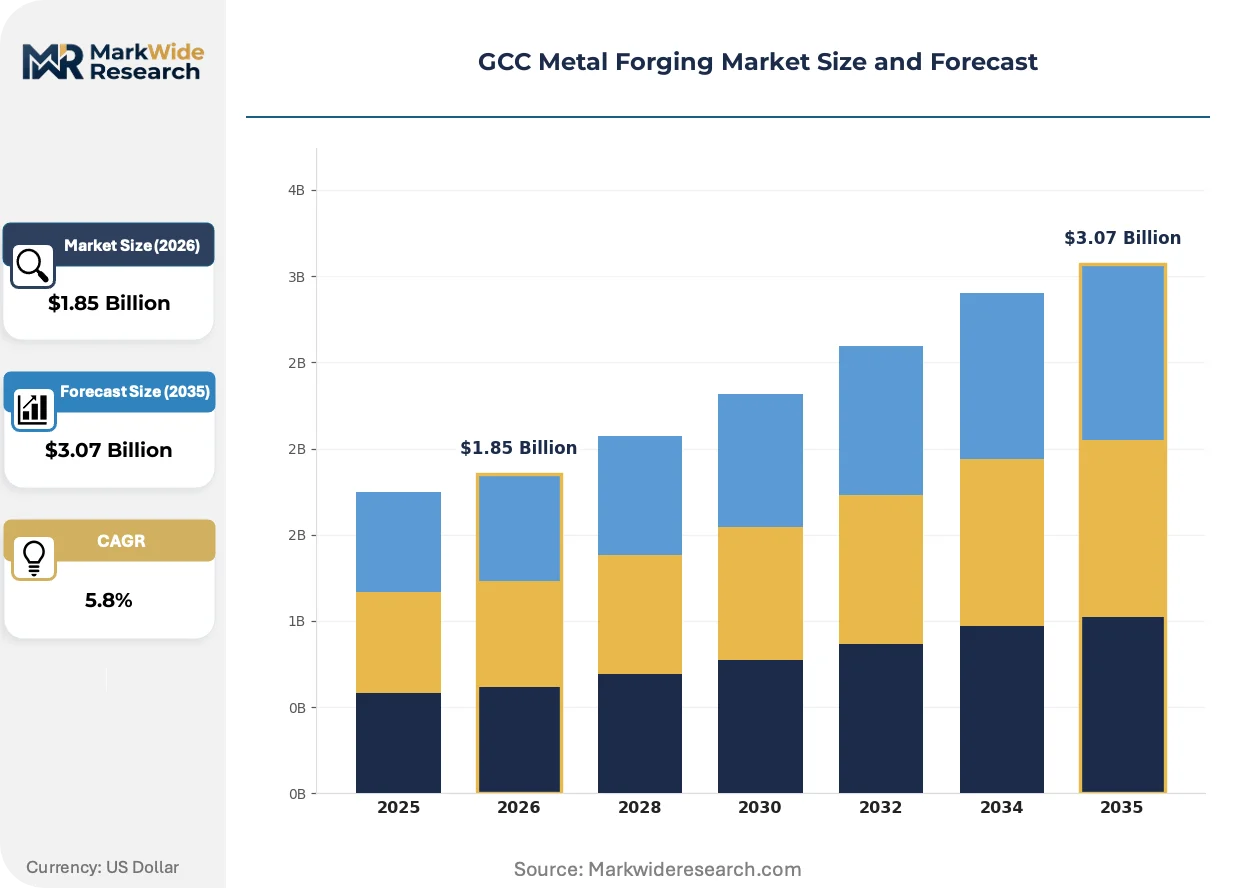
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Die Forging, Closed Die Forging, Rolled Forging, Automated Forging Material: Aluminum, Steel, Titanium, Copper End User: Aerospace, Automotive, Construction, Energy Application: Structural Components, Fasteners, Gears, Axles |
| Companies Covered | Precision Metal Industries FZC, Doosan Corporation, AL NASR FORGING, Galperti Group, FUCHS Group, FTV Proclad LLC, Steel Forgings Gulf, ALKAFAA, Precision Forgings Factory, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Metal Forging Market Strategic Shifts & Innovations
Digital thread implementation across forging workflows is compressing design-to-qualification cycles while regulatory pressure on material traceability forces investment in blockchain-based certification systems.
Isothermal forging of nickel-based superalloys is converging with real-time thermal imaging to enable net-shape turbine disk production for regional MRO facilities. Saudi Aramco and Emirates airline engineering divisions are piloting these systems to reduce machining waste on high-value aerospace components. The technology is converging with predictive maintenance platforms, allowing forgers to offer throughput guarantees rather than unit pricing.
SASO's updated technical regulations for pressure equipment mandate third-party witnessed mechanical testing for all forgings deployed in Saudi petrochemical facilities. This regulatory tightening eliminates self-certification pathways that previously accelerated procurement cycles. Mid-cap UAE forgers are responding by establishing satellite testing laboratories in Dammam to retain Saudi market access.
Long-term service agreements are displacing spot purchasing for critical oilfield forgings, with operators bundling inspection, replacement, and inventory management into decade-long contracts. This procurement evolution concentrates volume with forgers capable of maintaining consignment stock within Jebel Ali free zone warehouses. The shift is most visible among ADNOC and Saudi Aramco drilling divisions, which now specify vendor-managed inventory clauses in master service agreements.
GCC Metal Forging Market Segmentation
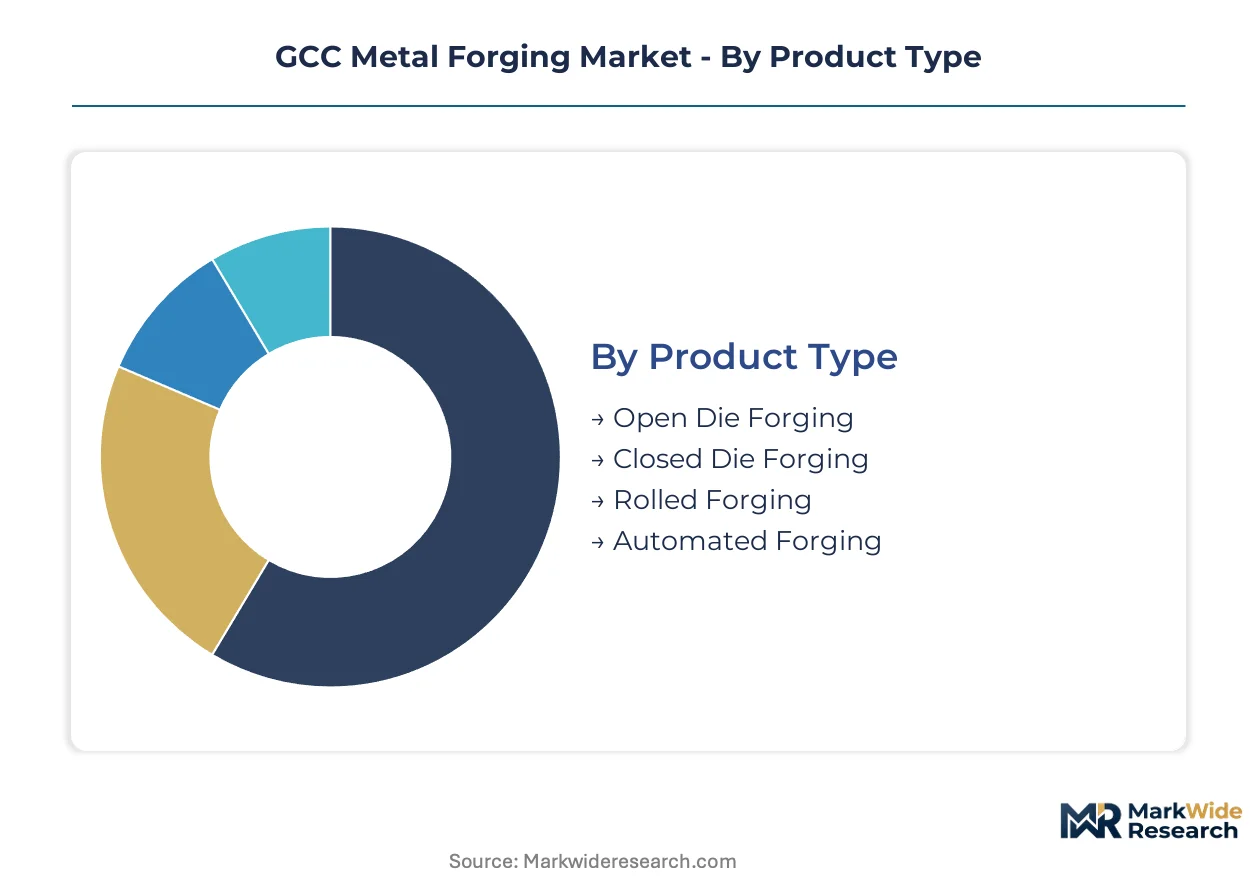
Segmentation in GCC metal forging reveals how process complexity, material certification barriers, and end-use qualification requirements stratify supplier capabilities and margin structures across the Gulf industrial corridor.
Product Type:
Process precision and tooling investment separate commodity volume plays from aerospace-grade qualification pathways.
- Closed Die Forging:Precision shaping within hardened dies produces net-shape components with aligned grain flow for fatigue-critical applications. Saudi Aramco and Emirates airline engineering divisions concentrate procurement here for wellhead equipment and turbine disks, though NADCAP heat treatment certification compresses supplier pools.
- Open Die Forging:Hammer or press forming between flat dies allows large-diameter workpieces for pressure vessels and offshore platforms. Qatar North Field expansion is driving demand for flanges beyond current regional heavy-forging capacity, forcing capacity investments in Dammam and Jebel Ali.
- Rolled Forging:Rotary reduction between cylindrical dies yields elongated shafts and rings for power transmission equipment.
- Automated Forging:Robotic die handling converges with predictive thermal monitoring to compress aerospace qualification cycles.
Mature deployment sits with Open Die Forging. Newer deployment is concentrated in Automated Forging.
Material:
Feedstock availability and import dependency shape competitive positioning across the Gulf.
- Steel:Carbon and alloy grades dominate construction and energy applications, though scrap price volatility from Turkish and Indian export markets compresses margin buffers on commodity forgings.
- Titanium:Sponge and ingot reliance on US and Russian sources subjects Saudi defense and UAE aerospace forgers to export licensing friction. Vision 2030 localization mandates are redirecting contracts toward domestic closed-die specialists capable of billet conversion.
- Aluminum:Lightweight structural forgings serve aerospace and automotive weight-reduction targets.
- Copper:Electrical conductivity applications concentrate in power generation and desalination infrastructure.
Steel retains volume leadership. Titanium is climbing the fastest on defense localization.
End User:
Customer qualification intensity and contract duration differentiate revenue stability across segments.
- Energy:Oilfield equipment and power generation absorb the largest forging tonnage, with ADNOC and Saudi Aramco drilling divisions now specifying vendor-managed inventory clauses in decade-long master service agreements.
- Aerospace:Gulf carrier procurement and regional MRO facilities demand isothermal superalloy forging with real-time thermal imaging, though ESMA traceability protocols filter out uncertified Asian competitors.
- Automotive:Electric vehicle axle localization in Saudi and UAE assembly plants requires gear blank and driveshaft forging to satisfy in-country value thresholds.
- Construction:Structural steel forgings face Asian supply concentration on sub-50kg precision components.
Energy commands contract duration. Aerospace is gaining share fastest on qualification barriers.
Application:
Functional performance requirements determine material specification and testing protocol intensity.
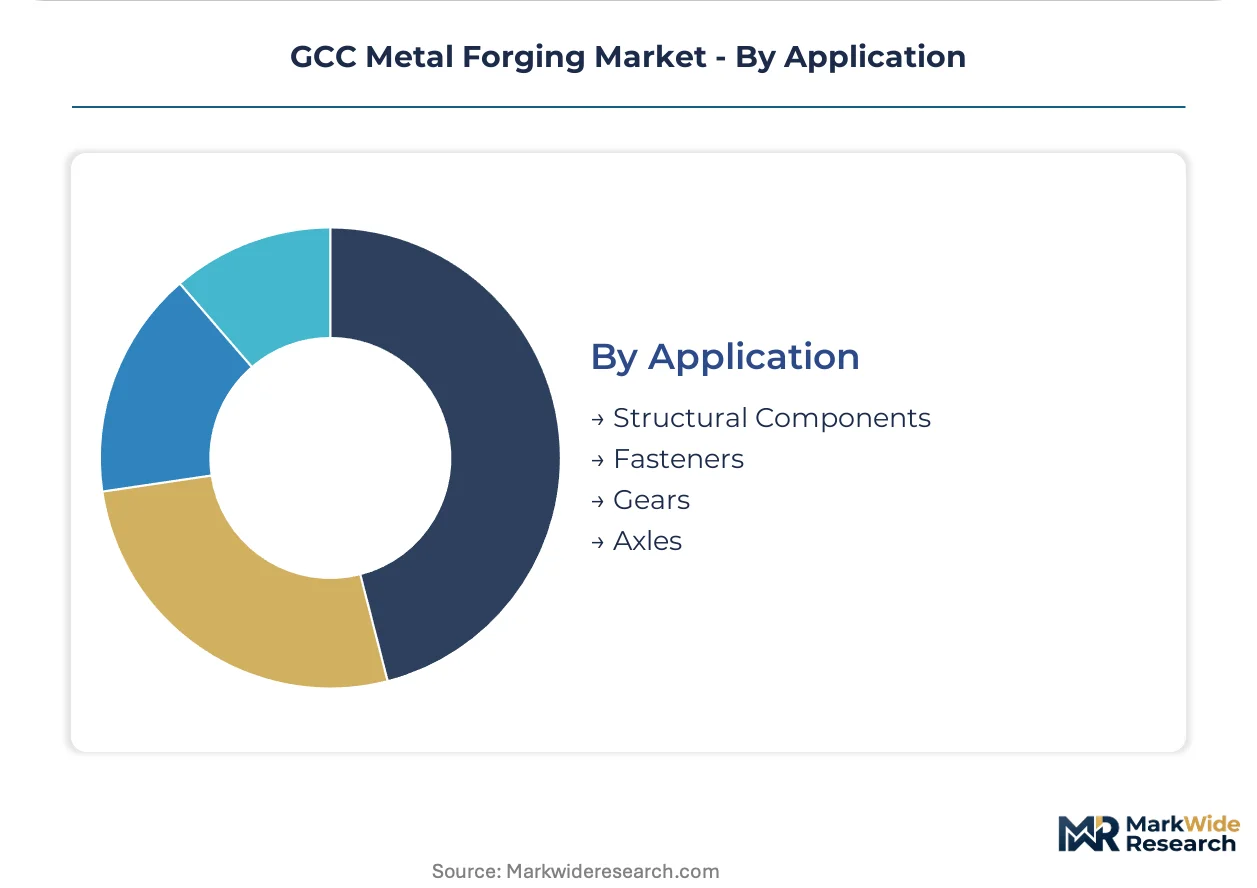
- Structural Components:Load-bearing forgings for pressure equipment face SASO-mandated third-party witnessed mechanical testing that eliminates self-certification pathways.
- Gears:Transmission components for automotive and industrial drives require precision tooth forming and case hardening.
- Fasteners:High-strength bolting for offshore platforms concentrates demand in Jebel Ali corridor clustering.
- Axles:Driveline forgings for electric vehicle platforms are pulling capacity toward Saudi automotive supplier parks.
Structural Components anchor petrochemical procurement. Axles are expanding most quickly on EV localization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali anchors GCC forging capacity through its free zone clustering of oilfield procurement offices and heavy industrial infrastructure. The corridor concentrates precision-forged wellhead component demand from ADNOC and Saudi Aramco drilling divisions. This spatial concentration compresses supplier qualification timelines while raising barriers for uncertified competitors.
Saudi Arabia
SABIC certification requirements compress supplier timelines for closed-die specialists serving petrochemical and defense contracts. SASO mandates third-party witnessed mechanical testing for pressure equipment forgings, eliminating self-certification pathways that previously accelerated procurement. Dammam's industrial corridor hosts capacity investments targeting Qatar North Field flange demand beyond current regional heavy-forging limits.
United Arab Emirates
ESMA traceability protocols filter out uncertified Asian competitors, consolidating UAE-based forging capacity around documented material origin requirements. Dubai's Jebel Ali industrial zone captures captive demand pools from concentrated oilfield equipment procurement offices. The emirate's in-country value programs redirect aerospace and energy contracts toward domestic closed-die specialists.
Qatar
North Field expansion drives demand for large-diameter forged flanges and subsea connectors exceeding current regional heavy-forging capacity. Qatar Petroleum's offshore platform construction schedules force procurement timelines that favor GCC-based suppliers over Asian alternatives. Ras Laffan Industrial City concentrates project management offices for forging specification and vendor qualification.
Kuwait
Kuwait Oil Company drilling divisions specify vendor-managed inventory clauses in master service agreements for critical wellhead forgings. The country's national oil company procurement frameworks emphasize long-term service agreements over spot purchasing for fatigue-critical components. Shuaiba Industrial Area hosts maintenance and replacement forging demand from downstream petrochemical complexes.
Bahrain
Alba's aluminum smelting operations generate localized demand for copper electrical conductivity forgings in power generation infrastructure. The country's central bank regulatory framework supports trade finance for raw material imports subject to scrap steel price volatility from Turkish and Indian export markets. Askar Industrial Area concentrates light forging capacity serving regional desalination and power plant maintenance.
GCC Metal Forging Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a market structure that stratifies around tooling investment depth and certification timeline compression. The supplier base organizes into three tiers: NADCAP-certified aerospace specialists, Aramco-approved energy forgers, and commodity construction players exposed to Asian import pressure. Strategic moves concentrate on die steel inventory pre-positioning before first article approval and satellite laboratory establishment to retain Saudi market access under SASO-mandated testing protocols.
Among UAE-based fabricators, Precision Metal Industries FZC exemplifies the Jebel Ali corridor clustering strategy, while AL NASR FORGING occupies a position within the Saudi Aramco relationship tier. Doosan Corporation represents the scale-driven multinational archetype with regional heavy forging capacity. These three anchors illustrate how geographic positioning and customer qualification intensity stratify competitive access across the GCC industrial corridor.
| Leading Market Players |
|---|
| Precision Metal Industries FZC |
| Doosan Corporation |
| AL NASR FORGING |
| Galperti Group |
| FUCHS Group |
| FTV Proclad LLC |
| Steel Forgings Gulf |
| ALKAFAA |
| Precision Forgings Factory |
| Others |
Cost & Logistics Intelligence
SASO-mandated third-party witnessed mechanical testing gates both qualified supply and premium-tier pricing access, compressing supplier pools while elevating certification-grade output above commodity spot markets. Buyers without documented material origin face exclusion from Saudi Aramco and ADNOC drilling divisions, forcing price stratification around compliance capability rather than tonnage alone.
Pricing Analysis
Throughput-based contracting anchors value-based pricing for critical oilfield forgings, with ADNOC and Saudi Aramco drilling divisions now specifying vendor-managed inventory clauses in decade-long master service agreements. Price differentiation separates NADCAP-certified aerospace specialists from commodity construction players, with certification level and die steel inventory carrying costs as primary tiering mechanisms. Cost compression in commodity-grade construction forgings is intensifying because Turkish and Indian scrap export fluctuations erode margin buffers. State-linked energy procurement offices exhibit lowest price sensitivity, while construction contractors exposed to Asian import pressure face acute margin constraints.
Supply Chain Analysis
Skilled die maintenance technicians and NADCAP-qualified heat treatment engineers concentrate in Dammam and Jebel Ali manufacturing corridors, constraining capacity expansion timelines for new entrants. Raw material sourcing draws from US and Russian titanium sponge, Turkish and Indian scrap steel, and premium-grade H13 die steel from European specialty mills. Single-source vulnerability in titanium billet import dependency exposes regional aerospace forgers to export licensing friction. Distribution runs through Jebel Ali free zone warehousing and Dammam industrial corridor consignment stock arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where SASO-mandated testing protocols and NADCAP certification timelines force capital-constrained mid-cap forgers toward exit or acquisition.
For Market Incumbents: Lock in long-term service agreement renewals with ADNOC and Saudi Aramco drilling divisions before satellite laboratory investments by UAE competitors mature. Prioritize backward integration into die steel inventory pre-positioning to compress first-article approval cycles, defending against emerging automated forging specialists with robotics integration capabilities.
For New Entrants and Emerging Players: Capture Qatar North Field expansion demand for large-diameter forged flanges exceeding current regional heavy-forging capacity, where procurement timelines favor GCC-based suppliers. Target electric vehicle axle localization in Saudi automotive supplier parks as the most penetrable segment, leveraging in-country value thresholds that exclude established Asian competitors.
For Investors and Strategic Acquirers: NADCAP heat treatment accreditation queue lengthening is the leading indicator that certified aerospace forging capacity will command scarcity premiums. Position for five-to-ten year holding periods around closed-die specialists with existing Saudi Aramco relationships and satellite laboratory infrastructure, watching titanium billet import license friction as the signal for regional feedstock investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Die Steel Inventory | H13 and premium-grade material pre-positioning compresses first-article approval timelines for aerospace contracts. |
| Satellite Testing Laboratory Establishment | Dammam-based facilities retain Saudi market access under SASO-mandated third-party witnessed mechanical testing protocols. |
| Automated Forging Robotics Integration | Robotic die handling with predictive thermal monitoring accelerates NADCAP qualification cycles for regional MRO facilities. |
| Long-term Service Agreement Expansion | Vendor-managed inventory clauses in ADNOC and Saudi Aramco master service agreements lock in decade-long revenue visibility. |
| Titanium Billet Conversion Capability | Domestic sponge-to-ingot capacity reduces exposure to US and Russian export licensing friction for defense contracts. |
Research Approach
Independent corroboration across forging plant managers, procurement leads at Saudi Aramco and ADNOC, distribution channel partners, and technical R&D directors at precision forgers underwrites the qualitative findings. Secondary validation draws from customs and trade data, SASO and ESMA regulatory filings, SEC 10-K disclosures by listed industrial conglomerates, and project development databases for Qatar North Field expansion. Bottom-up capacity assessments and top-down demand modeling triangulate across primary interviews and secondary sources.
Comparable-period anchoring to historical certification timeline data and scrap steel price volatility patterns frames the projection horizon across process type, material grade, end-use industry, and regional production hub dimensions. CAGRs derive from segmented demand elasticity modeling and capacity utilization trajectories, incorporating isothermal forging technology adoption curves and electric vehicle localization policy intensity as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium billet export licensing friction, NADCAP accreditation queue dynamics, and Saudi Vision 2030 defense localization mandate acceleration. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Brass Rods Market
Metals
Galvanized Steel Market
Metals
Amorphous Metal Cores Market
Metals
Aluminum Welding Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Europe Metal Casting Market
Metals
Base Metals Market
Metals
Global Welding Powder Market
Metals
Electrolytic Iron Market
Metals
Aluminum Smelting Market
Metals
Metallurgical Coal Market
Metals
Lithium Foil Market
Metals
Ferrite Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Platinum Compounds Market
Metals
Global Steel Market