
 Metal Polish Products Market | 2026-2036
Metal Polish Products Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Polish Products Market Foresight
Modular kit packaging is pivoting how industrial buyers procure metal polish systems, replacing single-unit purchases with bundled cleaner-polish-sealer combinations that reduce procurement touchpoints. 3M Company leverages its adhesive and abrasives ecosystem to anchor bundled offerings across aerospace maintenance channels. Turtle Wax Inc. competes through automotive retail dominance, while Henkel AG & Co. KGaA specializes in industrial-grade formulations for automated polishing lines.
Metal polish products are abrasive or chemical formulations containing alumina, silica, or proprietary solvent blends designed to remove oxidation, scratches, and tarnish from metallic surfaces while restoring luster and protective properties. Liquid polish dominates volume sales through ease of application in high-throughput automotive detailing operations, whereas paste polish commands premium positioning among restoration specialists serving brass and copper antique markets. Spray polish formats are gaining fastest in marine applications where corrosion resistance demands frequent, rapid treatment of large surface areas.
EPA volatile organic compound regulations and REACH substance restrictions in Europe are forcing reformulation away from petroleum-distillate carriers toward water-based and bio-derived solvent systems. OSHA workplace exposure limits further shape industrial application methods, driving investment in automated dispensing and enclosed polishing equipment. Stakeholders must monitor evolving chemical compliance thresholds to determine whether regional formulation specialization or unified global product platforms offer superior returns.
Market Dynamics
REACH substance restrictions and EPA volatile organic compound rules are forcing simultaneous reformulation across petroleum-distillate carriers, water-based alternatives, and bio-derived solvent systems while automotive OEMs and aerospace maintenance channels accelerate specification updates.
Growth Catalysts
- Automotive refinishing expansion:OEM assembly lines in Germany's precision manufacturing belt are specifying metal polish systems for automated polishing lines, creating pull-through demand for bundled cleaner-polish-sealer combinations.
- Marine corrosion protocols:Spray polish formats are gaining traction in coastal maintenance operations where corrosion resistance demands frequent, rapid treatment of large surface areas on vessels and offshore equipment.
- REACH compliance specialization:European chemical manufacturers are capturing premium positioning by developing proprietary solvent blends that satisfy ECHA substance restrictions while maintaining performance parity with legacy formulations.
Market Restraints
- Petroleum-distillate input volatility:Crude oil price fluctuations directly compress margins on traditional solvent-based formulations still dominant in industrial-grade product lines.
- Alumina supply concentration:Abrasive raw material sourcing clusters in China's Yangtze River Delta industrial corridor, creating geographic concentration risk for Western formulators.
- Water-based performance gaps:Aqueous carrier systems exhibit slower evaporation rates and reduced cutting efficiency on heavily oxidized brass and copper antique restoration projects.
Strategic Opportunities
- India precision manufacturing:BIS certification requirements for industrial metal finishing are creating entry barriers that favor established formulators with compliance infrastructure already deployed.
- Automated dispensing convergence:Integration of enclosed polishing equipment with IoT-enabled consumption monitoring is enabling predictive replenishment contracts in high-volume automotive detailing operations.
- Bio-derived solvent mandates:EU Green Deal procurement guidelines are tilting public-sector maintenance contracts toward bio-based formulations, rewarding early movers in enzymatic polishing catalyst development.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in balancing abrasive particle size distribution with volatile organic compound compliance is concentrated among aging technical workforces in Germany and the United States.
- Multi-jurisdiction certification timelines:Simultaneous EPA registration, REACH dossier preparation, and BIS conformity assessment for unified product platforms extends time-to-revenue by 18-24 months.
- Legacy equipment incompatibility:Water-based and bio-derived formulations require retrofitting of existing automated polishing lines originally engineered for petroleum-distillate chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Polish Products Market |
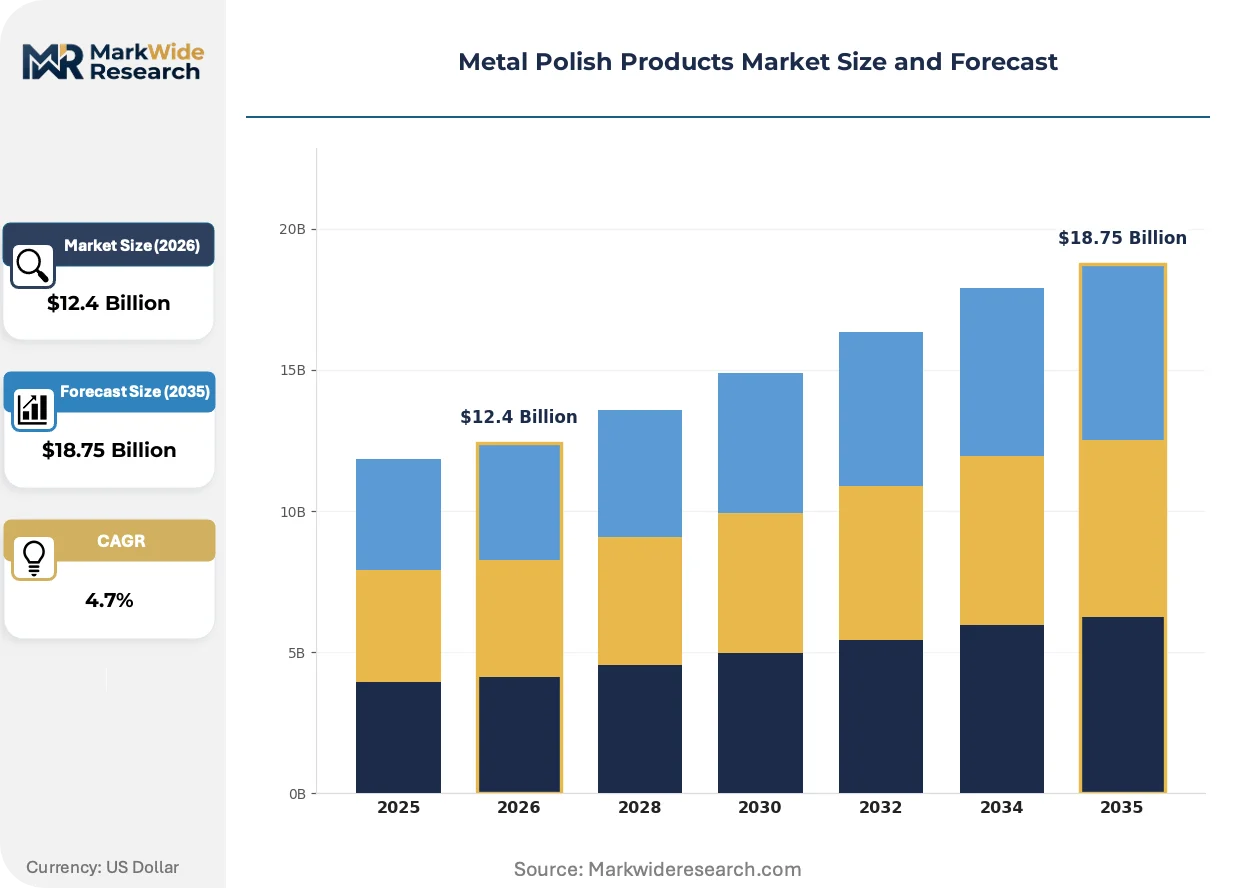
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Polish, Cream Polish, Spray Polish, Paste Polish Application: Automotive, Aerospace, Marine, Industrial Equipment Material: Aluminum, Stainless Steel, Copper, Brass Packaging Type: Bottle, Can, Tube, Jar |
| Companies Covered | S. C. Johnson & Son Inc., Turtle Wax Inc., Reckitt Benckiser Group PLC, Weiman Products LLC., 3M Company, Henkel AG & Co. KGaA, Meguiar's, Halfords Limited, Tri-Peek International Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Polish Products Market Shifts & Advancements
Formulation chemistry and application hardware are converging to redefine performance benchmarks and procurement economics across industrial maintenance, automotive refinishing, and heritage restoration segments.
Nano-engineered alumina suspensions with controlled particle morphology are decentralizing the performance advantage previously held by paste polish specialists serving brass and copper antique markets. Automotive detailing operations in Germany and China's Yangtze River Delta industrial corridor are adopting these liquid-format equivalents at accelerating rates. The technology is decentralizing premium margin capture from restoration craftsmen toward high-throughput industrial channels capable of spec-driven volume procurement.
EPA volatile organic compound regulations are tightening permissible limits on petroleum-distillate carriers in industrial metal polish formulations. Manufacturers serving United States automotive refinishing shops are accelerating water-based and bio-derived solvent development programs. Liquid polish segments face the steepest compliance costs, whereas paste formats with lower solvent content maintain temporary regulatory shelter in heritage restoration applications.
Modular kit packaging is replacing single-unit metal polish purchases with bundled cleaner-polish-sealer combinations that reduce procurement touchpoints for industrial buyers. Aerospace maintenance channels are specifying these integrated systems to streamline inventory management and application training. China's Yangtze River Delta industrial corridor exhibits the fastest adoption of kit-based procurement, driven by state-owned enterprise central purchasing reforms.
Metal Polish Products Market Segmentation
Metal polish procurement patterns diverge sharply across application environments, with aerospace maintenance teams prioritizing specification compliance while automotive detailers optimize for throughput speed. Understanding these segment boundaries clarifies where formulation investments yield differential returns.
Product Type:
Particle suspension chemistry and carrier viscosity define performance ceilings across application methods.
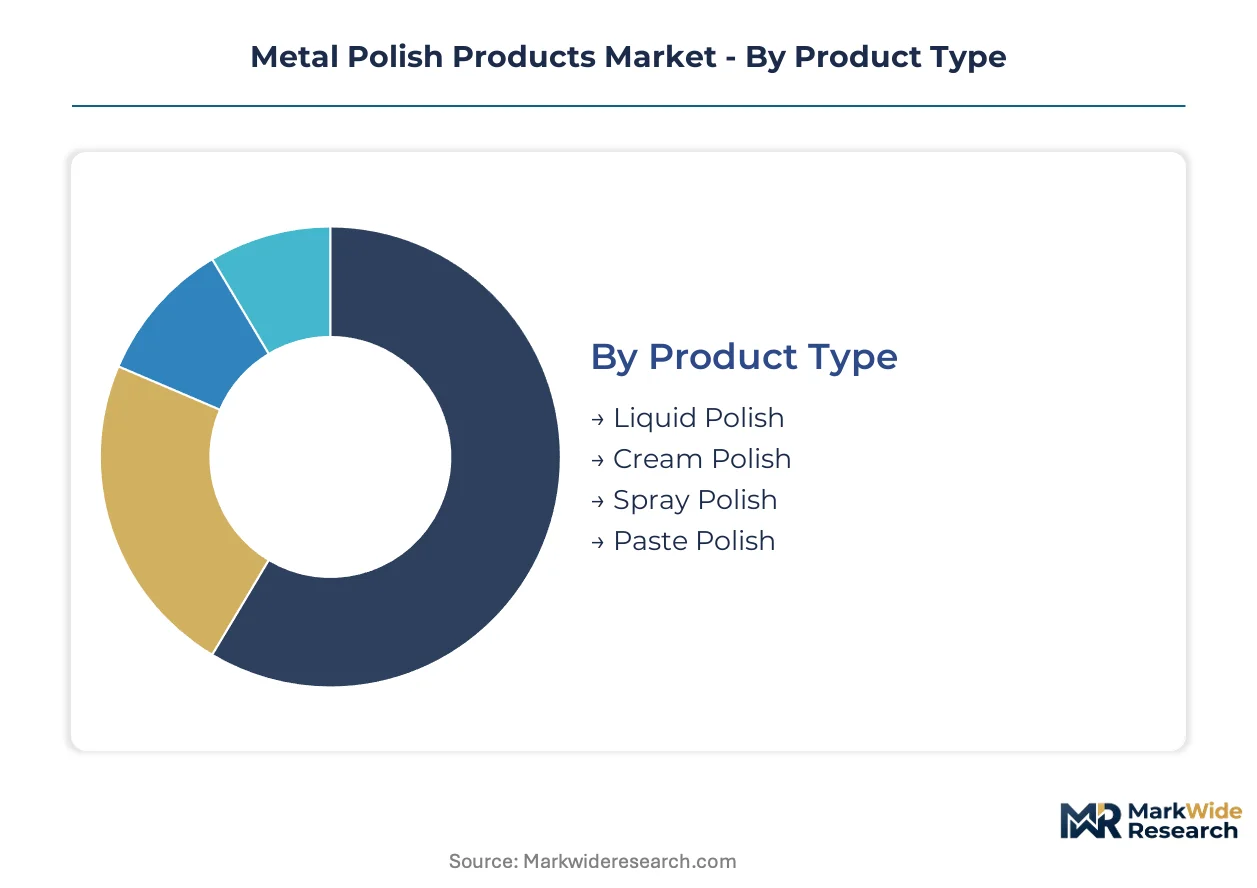
- Liquid Polish:Low-viscosity suspensions of alumina or silica in petroleum-distillate or water-based carriers enable rapid coverage of large surface areas. High-throughput automotive detailing operations in Germany's precision manufacturing belt specify liquid formats for automated dispensing systems.
- Spray Polish:Aerosolized or pump-dispersed formulations deliver thin, uniform films ideal for corrosion-prone marine environments. Coastal maintenance operations on vessels and offshore equipment favor spray formats for frequent, rapid treatment protocols where application speed outweighs cutting depth.
- Cream Polish:Mid-viscosity emulsions balance working time with ease of removal for hand-finishing operations.
- Paste Polish:High-abrasive-load formulations with extended working times serve restoration specialists addressing heavily oxidized heritage metals.
Mature deployment sits with liquid polish in industrial channels. Newer deployment is concentrated in spray formats for marine corrosion management.
Application:
End-use specifications determine permissible chemistry sets and performance validation requirements.
- Automotive:OEM assembly lines and refinishing shops drive volume demand through specification-driven procurement of bundled cleaner-polish-sealer systems. EPA volatile organic compound regulations constrain carrier chemistry selections for United States-based operations.
- Industrial Equipment:Automated polishing lines in China's Yangtze River Delta industrial corridor require formulations compatible with enclosed dispensing equipment and IoT-enabled consumption monitoring.
- Aerospace:Maintenance repair organizations enforce stringent material compatibility testing for airframe and engine component finishing.
- Marine:Salt-spray corrosion resistance requirements prioritize frequent reapplication cycles over single-treatment durability.
Volume concentration favors automotive. Margin expansion is climbing the fastest in aerospace specification compliance.
Material:
Substrate reactivity dictates abrasive selection and protective additive requirements.
- Aluminum:Soft, oxidation-prone surfaces demand fine-particle alumina suspensions with pH-neutral chemistry to prevent etching. Aerospace manufacturers specify aluminum-compatible formulations for airframe maintenance.
- Stainless Steel:Passivation-layer preservation requires controlled oxidation removal without surface roughening, driving demand for precision-graded abrasive systems in food-processing and medical equipment applications.
- Copper:Rapid tarnish formation in atmospheric exposure creates recurring maintenance demand among heritage restoration specialists.
- Brass:Zinc content sensitivity limits permissible pH ranges and solvent selections for decorative and functional finishing.
Specification density is highest for stainless steel. Volume expansion is gaining share fastest in aluminum for lightweighting trends.
Packaging Type:
Container format shapes dispensing method, shelf stability, and procurement economics.
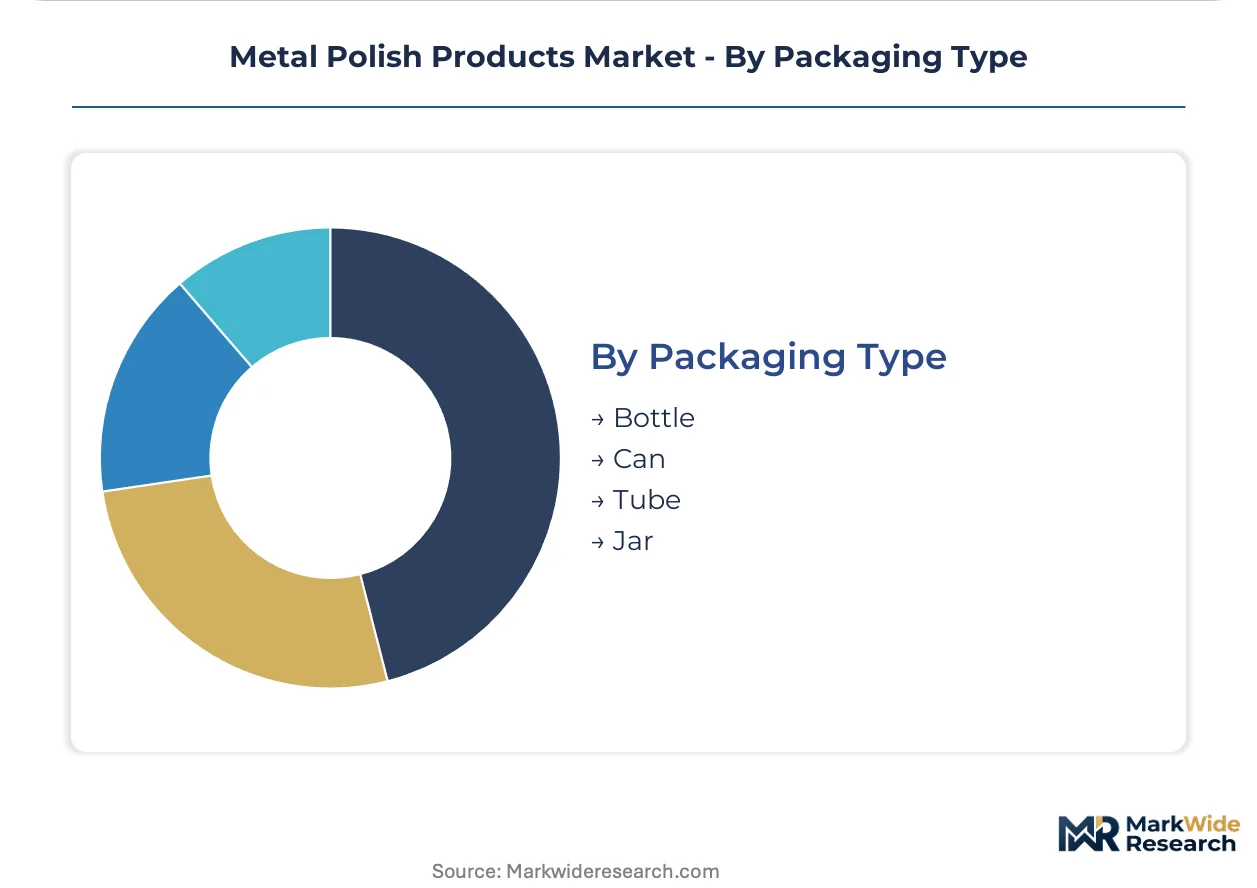
- Bottle:Screw-cap polyethylene containers dominate liquid polish distribution through automotive retail and industrial supply channels. Germany's precision manufacturing belt exhibits high adoption of bottle formats for automated dispensing line integration.
- Can:Aerosol or pressurized tinplate containers enable spray polish delivery for marine and field maintenance applications.
- Tube:Collapsible aluminum or laminate tubes suit cream polish formats for controlled dispensing in restoration workshops.
- Jar:Wide-mouth glass or polyethylene containers accommodate paste polish viscosity and brush application methods.
Procurement standardization favors bottles. Format innovation is expanding most quickly in cans for spray delivery systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's Yangtze River Delta industrial corridor while consumption gravitates toward Germany's precision manufacturing belt and United States automotive refinishing hubs. This geographic split shapes regional formulation specialization and regulatory compliance investments.
United States
Automotive refinishing shops and OEM assembly lines in Michigan and Ohio drive specification-grade metal polish procurement. EPA volatile organic compound rules constrain petroleum-distillate carrier formulations, pushing formulators toward water-based alternatives. Dallas-Fort Worth aerospace maintenance clusters are adopting bundled cleaner-polish-sealer systems to streamline MRO inventory.
Germany
Precision manufacturing across Baden-Württemberg and Bavaria anchors European industrial-grade demand for automated polishing line formulations. REACH substance restrictions enforced by ECHA mandate proprietary solvent blend development. Stuttgart's automotive engineering corridor specifies nano-engineered alumina suspensions for high-throughput metal finishing operations.
China
Yangtze River Delta industrial corridor dominates both alumina abrasive supply and automated polishing equipment manufacturing. MIIT dual carbon goals are accelerating bio-derived solvent pilot programs among state-owned enterprise formulators. Shanghai's central purchasing reforms favor modular kit packaging for bundled procurement efficiency.
India
Maharashtra and Gujarat precision manufacturing hubs are expanding metal finishing capacity for automotive component exports. BIS certification requirements for industrial metal polish create compliance barriers favoring established multinationals. Pune's automotive supplier parks are specifying enclosed polishing equipment with IoT-enabled consumption monitoring.
Japan
Kanto region aerospace manufacturers and Chubu automotive suppliers enforce stringent material compatibility testing for metal polish formulations. METI industrial standards guide solvent selection for automated application systems. Nagoya's Toyota supplier ecosystem demands predictive replenishment contracts tied to enclosed dispensing equipment.
Metal Polish Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and application hardware domains. Market structure tilts toward consolidated tier-one suppliers with cross-border compliance infrastructure, while mid-tier regional formulators capture niche heritage restoration segments. Strategic archetypes include adhesive-and-abrasives ecosystem players, automotive retail channel dominators, and industrial-grade automated line specialists. Dominant competitive moves encompass backward integration into captive alumina supply and strategic partnerships with enclosed equipment manufacturers.
Within the diversified conglomerate tier, 3M Company and Henkel AG & Co. KGaA exemplify multinational formulators with adhesive and abrasives ecosystems spanning aerospace and automotive channels. Turtle Wax Inc. occupies a position as an automotive retail-focused specialist with consumer-facing brand equity. S. C. Johnson & Son Inc. represents the household products conglomerate archetype with distribution scale across maintenance chemical categories. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| S. C. Johnson & Son Inc. |
| Turtle Wax Inc. |
| Reckitt Benckiser Group PLC |
| Weiman Products LLC. |
| 3M Company |
| Henkel AG & Co. KGaA |
| Meguiar's |
| Halfords Limited |
| Tri-Peek International Limited |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap formulators in Germany's precision manufacturing belt exercise outsized pricing discipline through multi-decade customer relationships and captive technical service capabilities that commodity traders cannot replicate. Their ownership structure insulates pricing decisions from quarterly earnings pressure, allowing sustained investment in REACH-compliant solvent development that petroleum-distillate competitors deferred.
Pricing Analysis
Price erosion across liquid polish tiers traces to water-based formulation scale economies eroding the premium historically commanded by solvent-based alternatives. Three-tier pricing structure across premium, standard, and economy levels separates aerospace specification-grade from automotive OEM-approved and generic maintenance categories. Certification tier—specifically ECHA REACH dossier completeness—drives price differentiation more than abrasive load or brand equity. Cost-down pressure on economy-tier products accelerates because Chinese state-owned enterprises leverage alumina supply control to undercut Western formulators on spot procurement. Automotive refinishing shops exhibit highest price sensitivity, while aerospace maintenance repair organizations prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's BIS certification regime are reshaping sourcing patterns, forcing multinational formulators to establish local blending operations rather than rely on imported finished goods. Alumina abrasive supply concentrates in China's Yangtze River Delta, Germany's Ruhr industrial region, and Australia's bauxite processing corridor. Formulation chemistry rests on petroleum-distillate carriers, water-based solvent systems, and bio-derived enzymatic catalysts as the three input pillars. Single-source vulnerability sits with alumina particle processing clusters exposed to export licensing volatility. Distribution runs through industrial chemical distributors serving automotive refinishing channels, with direct procurement gaining share among aerospace maintenance organizations specifying bundled cleaner-polish-sealer systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA volatile organic compound rules and REACH substance restrictions erect barrier-to-entry moats favoring incumbents with deployed regulatory infrastructure over opportunistic traders.
For Market Incumbents: Acquire distressed regional formulators in India's Maharashtra and Gujarat corridors to preempt BIS certification bottlenecks before domestic competitors consolidate. Backward integration into captive alumina supply insulates margin compression from Yangtze River Delta export volatility. Defensive positioning requires accelerated bio-derived solvent scale-up ahead of EU Green Deal procurement guideline enforcement.
For New Entrants and Emerging Players: Aerospace maintenance channel partners represent the most penetrable entry vector, as specification-grade formulator scarcity in Dallas-Fort Worth and Nagoya clusters creates procurement gaps. Marine spray polish applications in coastal maintenance operations offer white-space expansion with lower certification barriers than automotive OEM channels. Go-to-market execution should emphasize IoT-enabled consumption monitoring bundled with predictive replenishment contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with deployed REACH dossiers and established aerospace maintenance relationships in Germany and Japan. Long-term viability centers on formulation chemistry capabilities that survive petroleum-distillate phase-out. The inflection signal to monitor is BIS certification timeline acceleration in India, which would compress valuation windows for unprepared targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | Captive abrasive sourcing insulates margin compression from Yangtze River Delta export volatility. |
| Bio-Derived Solvent Scale-Up | EU Green Deal procurement guidelines tilt public-sector contracts toward enzymatic catalyst formulations. |
| Modular Kit Packaging Expansion | Bundled cleaner-polish-sealer combinations reduce procurement touchpoints in China's state-owned enterprise reforms. |
| Automated Dispensing Equipment Partnership | Integration with IoT-enabled consumption monitoring enables predictive replenishment in German automotive detailing. |
| BIS Certification Infrastructure Deployment | India's compliance barriers favor early movers with established conformity assessment capabilities in Maharashtra. |
Research Methodology
Independent corroboration across primary interviews with formulation chemists, automotive refinishing shop procurement managers, aerospace maintenance repair organization specification engineers, and industrial chemical distributors underwrites the qualitative findings. Secondary validation drew from EPA enforcement actions, ECHA substance restriction dossiers, BIS certification registries, and customs trade data for alumina abrasive flows. Bottom-up demand modeling across automotive, aerospace, marine, and industrial equipment channels triangulated against top-down chemical industry production estimates.
Rate-of-change decomposition across the projection horizon separates volume expansion from price-mix effects and regulatory-driven formulation substitution. Segmentation dimensions modeled include product type, application environment, substrate material, and packaging format, with regional regulatory cluster as the cross-cutting overlay. CAGRs derived from historical trajectory analysis adjusted for EPA volatile organic compound rule implementation timing and REACH substance restriction phase-in schedules. Industry-specific forecast inputs incorporated automotive production forecasts and aerospace maintenance cycle projections.
Caveats apply where alumina supply disruptions, accelerated bio-derived solvent performance breakthroughs, or unilateral regulatory timeline shifts could materially shift the outlook. Forecasts reflect documented assumptions about compliance cost pass-through elasticity and substitution rates between solvent systems. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market