
 Vietnam Aluminum Market | 2026-2036
Vietnam Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Aluminum Market Analytics
Multi-source procurement from domestic extruders is shifting how Vietnamese construction firms secure aluminum profiles. Sapa Ben Thanh Aluminium Profiles leverages its European technical lineage to sustain premium positioning in architectural systems. Dong Duong Aluminum specializes in customized industrial profiles that anchor its presence in northern manufacturing zones. Global Vietnam Aluminum Co., Ltd competes on scale, operating one of the largest billet casting facilities serving downstream fabricators nationwide.
Vietnam aluminum encompasses primary and secondary metal processed into semi-finished forms with alloy grades typically ranging from 1000-series pure aluminum to 6000-series magnesium-silicon alloys for structural applications. Manufacturers deploy direct chill casting followed by extrusion or rolling to produce shapes meeting tensile strength requirements between 150 and 350 MPa for construction and transportation end-uses. Extruded products dominate volume flows as Vietnamese infrastructure build-out absorbs profile and bar forms for curtain walls, window systems, and industrial framing. Rolled sheet commands tighter margins in packaging and electrical applications where surface finish and gauge precision determine supplier selection. Cast aluminum occupies a narrower niche serving automotive and machinery producers seeking complex near-net shapes.
Vietnam's national standards body issues aluminum product certifications aligned with TCVN specifications, while the Ministry of Natural Resources and Environment enforces emissions controls on smelting operations that constrain brownfield expansion. The country's central bank monitors foreign currency exposure for import-dependent processors, creating working capital pressures when the Vietnamese dong weakens against US dollar-denominated alumina contracts. Stakeholders must track bauxite mining license allocations in Lam Dong and Dak Nong provinces, as upstream feedstock access will determine which midstream processors can sustain cost-competitive operations without reliance on imported primary metal.
Market Dynamics
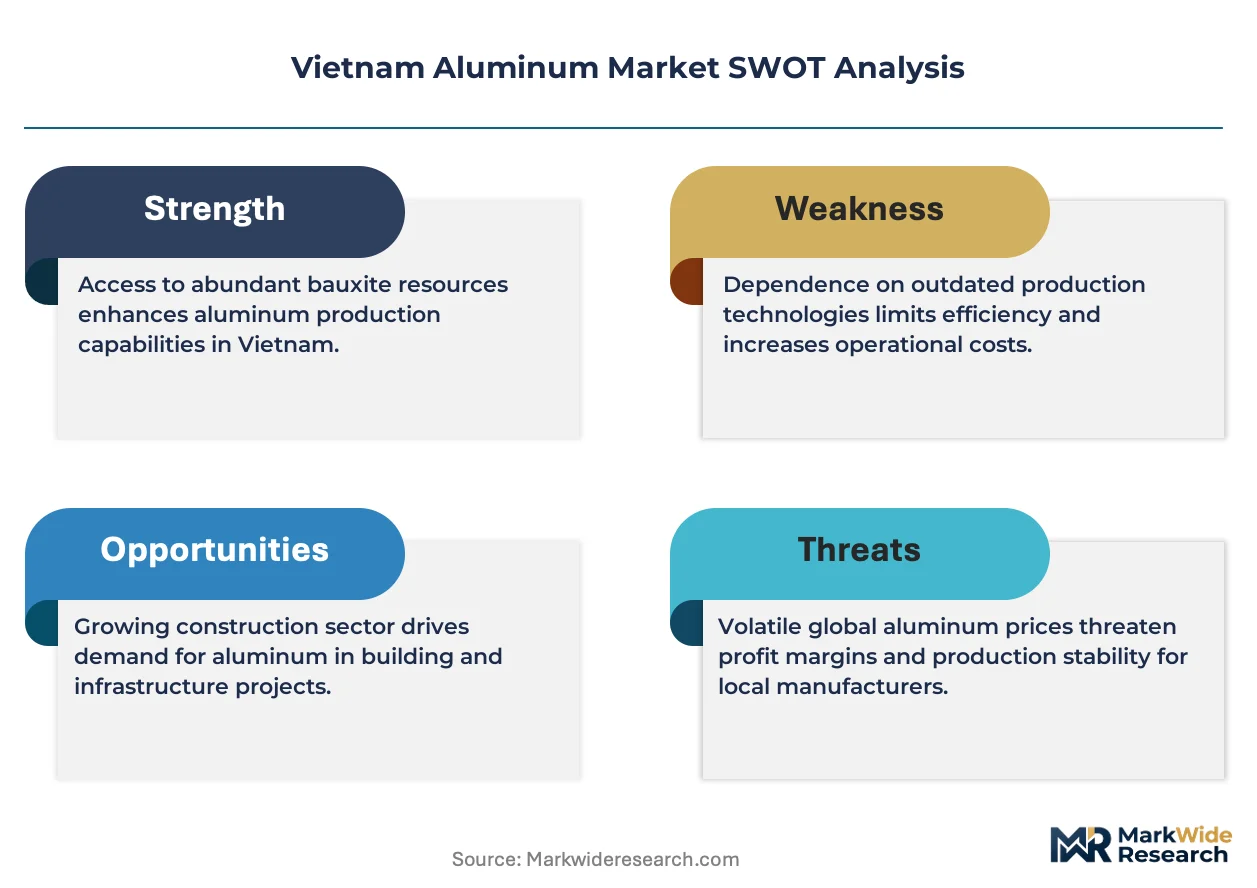
Domestic smelting capacity expansion in Vietnam's northern bauxite belt is compressing supply chains and redirecting investment flows away from import-dependent processors in the Red River Delta corridor.
Growth Catalysts
- High-rise construction procurement:Vietnamese developers are sourcing extruded profiles locally for residential towers and commercial complexes, pulling volume through domestic extruders rather than import channels.
- TCVN certification alignment:The national standards body's specifications for structural aluminum products are creating procurement preference for certified domestic output in public infrastructure tenders.
- Alumina refining technology:Bayer process refineries in Lam Dong province are scaling output, reducing feedstock dependence on Australian and Indonesian alumina shipments.
Market Restraints
- Alumina import exposure:Vietnamese dong depreciation against US dollar-denominated alumina contracts squeezes working capital for processors without captive bauxite supply.
- Smelting emissions controls:The Ministry of Natural Resources and Environment's constraints on brownfield expansion limit capacity growth at existing facilities in industrial zones.
- Scrap aluminum competition:Secondary aluminum from Chinese scrap imports competes on price for non-structural applications, compressing margins for primary metal processors.
Strategic Opportunities
- Electric vehicle battery enclosures:Vietnamese automotive assemblers are qualifying 6000-series extrusions for battery tray applications, opening a new demand vertical beyond traditional construction.
- Renewable energy mounting systems:Solar farm developers in central provinces are specifying aluminum structural profiles for tracker systems, creating geographic demand rotation toward the Central Highlands.
- Industrial zone clustering:The Ministry of Industry and Trade's incentives for smelter-proximate fabrication parks in Dak Nong province are attracting downstream extruders to co-locate with upstream supply.
Industry Challenges
- Alloy formulation expertise:Vietnamese technical institutes produce insufficient metallurgists capable of optimizing 6000-series heat treatment protocols for automotive-grade tensile specifications.
- Direct chill casting equipment:Domestic billet producers face 18-24 month lead times for German and Chinese casting line imports, delaying capacity ramp schedules.
- Surface finish certification:Architectural anodizing facilities struggle to achieve Qualicoat and Qualanod international certifications required for export-grade curtain wall contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Aluminum Market |
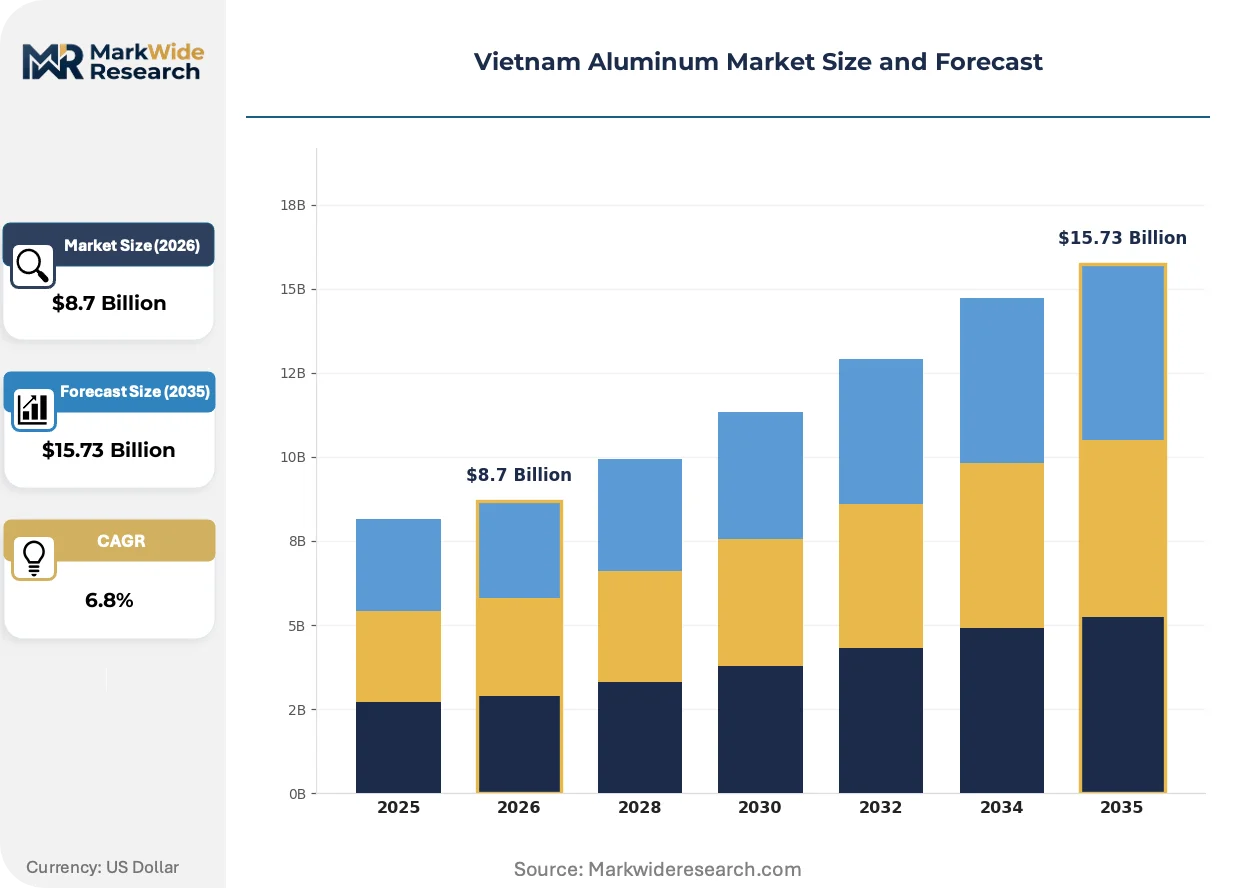
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded, Rolled, Forged, Cast Application: Construction, Transportation, Packaging, Electrical End User: Manufacturing, Aerospace, Automotive, Consumer Goods Form: Sheet, Plate, Bar, Profile |
| Companies Covered | Sapa Ben Thanh Aluminium Profiles Co., Ltd, East Asia Aluminum Co., Ltd, Dong Duong Aluminum Company Limited, Grando Aluminum (Do Thanh Aluminum Joint Stock Company), Daiki Aluminium Industry Co. Ltd, Aicomex Company Limited, Ngoc Diep Aluminum Joint Stock Company, Kama Vina Joint Stock Company, Global Vietnam Aluminum Co., Ltd (GVA), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Aluminum Market Evolving Landscape
Aluminum processing in Vietnam is converging around energy efficiency mandates and digital quality control, compressing the gap between primary production and precision fabrication.
Continuous homogenization technology is unifying billet thermal treatment with inline extrusion, eliminating reheating stages. Northern Vietnamese extruders serving construction markets are retrofitting gas-fired homogenizing furnaces with induction systems to reduce energy costs per metric ton. This unifying architecture is collapsing the traditional separation between casting and extrusion operations, enabling single-heat processing from liquid metal to finished profile.
The Ministry of Industry and Trade's circular economy roadmap is mandating scrap content thresholds in government-procured aluminum products. Industrial zones around Hanoi are installing electromagnetic sorting lines to separate 5000-series from 6000-series scrap streams. Construction contractors bidding on public housing projects now face documentation requirements proving recycled content compliance, shifting supplier qualification criteria.
Buyer concentration among Vietnamese real estate developers is compressing supplier negotiation cycles and unbundling technical specification from logistics contracting. Large residential developers in Ho Chi Minh City are issuing master service agreements covering five-year aluminum supply with embedded price adjustment clauses tied to London Metal Exchange benchmarks. This contractual evolution is most visible in the southern corridor, where integrated developers self-perform facade installation rather than delegating to general contractors.
Vietnam Aluminum Market Segmentation
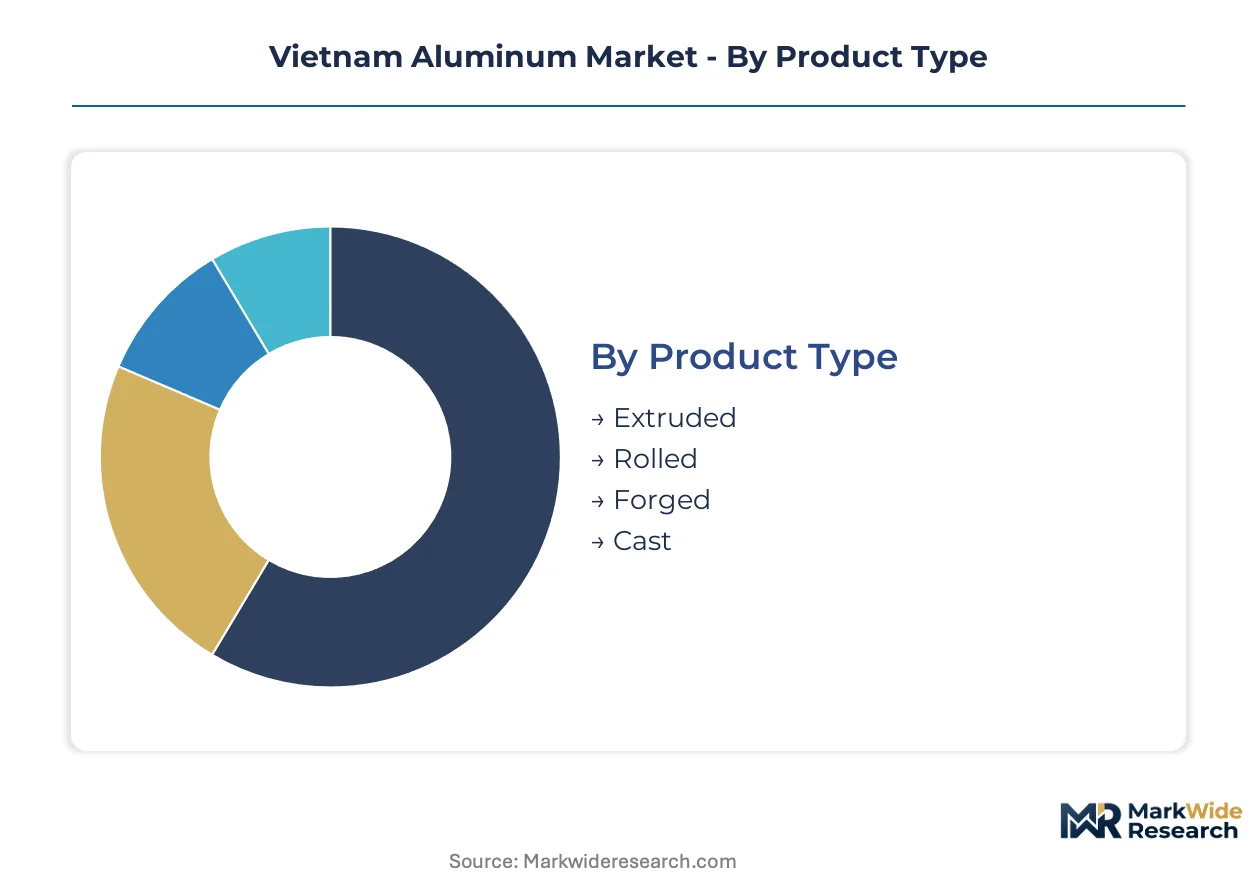
Segmentation in Vietnam's aluminum market reveals how alloy specifications and processing methods align with distinct procurement channels. Vietnamese buyers source through separate qualification pathways for construction tenders versus automotive supply chains.
Product Type:
Processing technology determines the mechanical properties achievable and the capital intensity required for market entry.
- Extruded:Direct chill casting feeds hydraulic presses shaping 6000-series alloys into profiles with 150-350 MPa tensile strength. Red River Delta fabricators consume the majority for Hanoi high-rise curtain walls and Hai Phong industrial framing.
- Rolled:Continuous casting lines produce sheet and coil with tight gauge tolerance for packaging and electrical applications. Surface finish precision commands supplier selection in food-grade foil and transformer winding segments.
- Forged:High-pressure forming of 7000-series alloys yields aerospace-grade components with superior fatigue resistance. Limited domestic capability pushes Vietnamese buyers toward imported billet for aircraft structural parts.
- Cast:Gravity and pressure die casting generates near-net shapes for automotive engine blocks and machinery housings. Secondary aluminum feeds this segment competitively against primary metal.
Extruded products lead on scale; rolled products lead on momentum as packaging demand accelerates.
Application:
End-use specifications diverge sharply between structural load-bearing requirements and surface-critical electrical applications.
- Construction:TCVN-certified extruded profiles dominate residential tower facades and commercial complex framing. Vietnamese developers increasingly self-perform procurement through master service agreements with five-year duration.
- Transportation:Automotive assemblers qualify 6000-series extrusions for electric vehicle battery tray enclosures. Rail and marine applications absorb plate and bar forms for hull and chassis structures.
- Packaging:Rolled sheet commands tight margins where surface finish and gauge precision determine supplier selection. Food-grade foil and beverage can stock require continuous casting investment.
- Electrical:High-conductivity 1000-series and 6000-series alloys serve transformer windings and busbar applications. Power grid expansion in northern provinces pulls volume through specialized conductors.
Construction leads on scale; transportation leads on momentum as automotive electrification drives alloy qualification.
End User:
Customer technical capabilities determine whether procurement flows through spot markets or long-term contractual arrangements.
- Manufacturing:Industrial machinery producers source cast and forged components for equipment frames and precision parts. Factory automation build-out across Bac Ninh and Hai Duong provinces sustains demand.
- Aerospace:Vietnamese maintenance repair operations import forged 7000-series alloys for airframe component replacement. Domestic metallurgical capacity gaps constrain local supply development.
- Automotive:Assemblers in Vinh Phuc and Quang Nam provinces specify extruded battery enclosures and cast powertrain housings. Foreign-invested plants drive technical specification alignment with global parent company standards.
- Consumer Goods:Appliance and electronics manufacturers absorb rolled sheet for heat sinks and decorative trim. Price sensitivity in this segment exposes processors to Chinese scrap aluminum competition.
Manufacturing leads on scale; automotive leads on momentum as electrification reshapes material specifications.
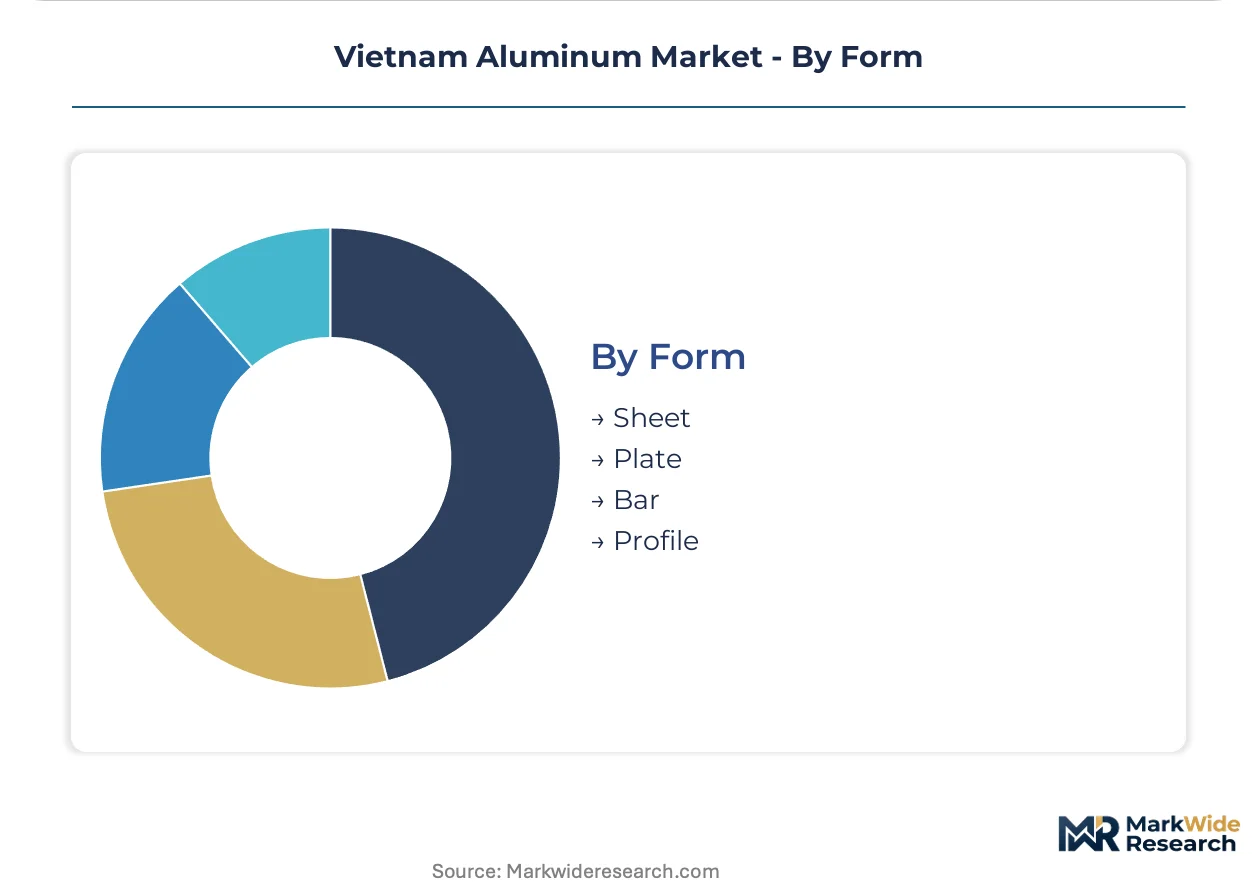
Form:
Dimensional output determines downstream processing requirements and logistics economics for Vietnamese distributors.
- Sheet:Continuously rolled thin-gauge product serves packaging laminates and electrical conductor applications. Coil weight and width specifications align with Vietnamese converter equipment constraints.
- Plate:Thick-rolled sections absorb mechanical stress in marine hulls, heavy machinery bases, and mold tooling. Plate mills require heavier capital investment than sheet lines.
- Bar:Long products in round, square, and hexagonal sections feed machining centers for precision component fabrication. Mechanical engineering clusters around Hanoi consume the majority of domestic bar output.
- Profile:Custom extruded cross-sections match architectural system specifications for curtain walls and window frames. Profile libraries differentiate Vietnamese extruders competing for developer master agreements.
Profile leads on scale; sheet leads on momentum as packaging and electrical applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward Vietnamese provinces where environmental compliance costs trail northern industrial zones, creating a regulatory-arbitrage corridor that redirects smelting investment into bauxite-rich territories.
Red River Delta
High-rise residential towers and commercial complexes in Hanoi and Hai Phong absorb extruded profiles for curtain wall systems. The Ministry of Industry and Trade's industrial zone incentives concentrate downstream fabricators around Bac Ninh and Hai Duong provinces. Extrusion presses in this corridor process billet from both domestic smelters and imported primary metal.
Northern Highlands
Bauxite mining concessions in Lam Dong and Dak Nong provinces feed Bayer-process refineries scaling alumina output. The Ministry of Natural Resources and Environment's emissions controls constrain brownfield expansion in older industrial zones, pushing new smelting capacity toward these upstream locations. Northern provinces now host captive supply chains linking bauxite extraction to billet casting.
Central Coast
Solar farm developers in Binh Dinh and Quang Nam provinces specify aluminum structural profiles for photovoltaic tracker systems. Provincial industrial promotion boards offer land concessions for fabrication parks serving renewable energy infrastructure. Central Vietnam's port access reduces logistics costs for imported alloy additives.
Southern Economic Zone
Ho Chi Minh City real estate developers self-perform aluminum procurement through master service agreements with five-year duration. The State Bank of Vietnam's foreign exchange monitoring creates working capital pressures for import-dependent processors when the dong weakens. Southern fabricators face price competition from Chinese scrap aluminum flows through border provinces.
Southeast Industrial Belt
Foreign-invested automotive assemblers in Dong Nai and Binh Duong provinces qualify 6000-series extrusions for electric vehicle battery enclosures. Provincial authorities fast-track environmental permits for facilities meeting technical workforce training quotas. Southeast Vietnam's supplier parks co-locate aluminum processors with electronics and appliance manufacturers.
Vietnam Aluminum Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized alloy formulations for automotive and renewable energy applications. The market structures around three archetypes: European-heritage technical specialists, scale-driven billet casters, and regional extrusion houses serving construction procurement. Capacity expansion and certification alignment represent the dominant competitive vectors as players position for public infrastructure tenders and export-grade contracts.
Among Vietnamese fabricators, Sapa Ben Thanh Aluminium Profiles Co., Ltd represents the European technical lineage archetype, while Global Vietnam Aluminum Co., Ltd anchors the scale-driven casting segment. Dong Duong Aluminum Company Limited occupies a position within the customized industrial profile specialization tier. These three exemplify how geographic clustering and technical positioning stratify competitive identity without requiring identical strategic moves.
| Leading Market Players |
|---|
| Sapa Ben Thanh Aluminium Profiles Co., Ltd |
| East Asia Aluminum Co., Ltd |
| Dong Duong Aluminum Company Limited |
| Grando Aluminum (Do Thanh Aluminum Joint Stock Company) |
| Daiki Aluminium Industry Co. Ltd |
| Aicomex Company Limited |
| Ngoc Diep Aluminum Joint Stock Company |
| Kama Vina Joint Stock Company |
| Global Vietnam Aluminum Co., Ltd (GVA) |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between TCVN-compliant domestic output and import-dependent commodity metal creates parallel pricing tracks that reshape procurement behavior across Vietnamese construction and automotive supply chains. Premium architectural extruders command sustained margin positions through Qualicoat-aligned surface finish capabilities, while standard-grade processors absorb cost compression from Chinese scrap aluminum competition at the border.
Pricing Analysis
Distributor margins in the Red River Delta corridor compress as large developers shift toward direct-to-extruder master service agreements with embedded London Metal Exchange price adjustment clauses. Pricing stratifies across premium, standard, and economy tiers based on certification level and surface finish capability, with TCVN structural certification and Qualanod anodizing approval commanding measurable premiums. Cost compression in standard-grade construction profiles intensifies due to secondary aluminum inflows from Chinese scrap channels. Manufacturing end-users in Bac Ninh and Hai Duong provinces exhibit highest price sensitivity, while automotive assemblers in Vinh Phuc prioritize tensile specification compliance over unit cost.
Supply Chain Analysis
Workforce availability constraints in northern industrial zones around Hanoi and Hai Phong push billet casting investment toward Lam Dong and Dak Nong provinces where mining concessions anchor captive supply chains. Vietnam's aluminum sector draws from Australian and Indonesian alumina shipments, domestic bauxite extraction in the Central Highlands, and Chinese scrap metal flows through border provinces. Single-source vulnerability concentrates in German and Chinese direct chill casting equipment, where 18-24 month import lead times constrain capacity expansion timelines. Distribution runs through industrial zone clusters co-locating extruders with downstream fabricators, reducing logistics costs for curtain wall and battery enclosure applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's aluminum market functions as a regulatory compounder where Ministry of Industry and Trade circular economy mandates on scrap content thresholds are restructuring supplier qualification criteria and procurement preferences across public infrastructure tenders.
For Market Incumbents: Hedge against Chinese scrap aluminum price competition by securing captive bauxite supply through northern mining concession partnerships in Lam Dong province. Deepen backward integration into Bayer-process alumina refining to reduce working capital exposure to Vietnamese dong depreciation against US dollar-denominated import contracts. Prioritize Qualicoat and Qualanod certification investment to defend premium positioning in architectural extrusion segments where international project specifications determine supplier selection. For New Entrants and Emerging Players: TCVN certification alignment in Vietnam opens a window for specialized 6000-series automotive-grade extrusion targeting electric vehicle battery tray applications in Vinh Phuc and Quang Nam assembly plants. Target solar farm mounting system specifications in Binh Dinh and Quang Nam provinces where renewable energy infrastructure deployment outpaces domestic fabrication capacity. Pursue co-location incentives in Dak Nong province fabrication parks to secure smelter-proximate feedstock access and streamlined environmental permitting tied to technical workforce training quotas. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale extruders lack captive bauxite supply and face margin compression from both primary metal import costs and Chinese scrap competition. Long-term viability centers on backward-integrated assets linking mining concessions through billet casting, with premium positioning sustained by international surface finish certifications. Monitor Ministry of Natural Resources and Environment emissions control enforcement intensity as the inflection indicator for brownfield expansion viability versus greenfield relocation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Captive feedstock access in Lam Dong province eliminates alumina import currency exposure for processors. |
| Qualicoat Certification Investment | International surface finish approval unlocks export-grade curtain wall contracts from Vietnamese developers. |
| Industrial Zone Co-location | Dak Nong fabrication park incentives reduce logistics costs through smelter-proximate extrusion operations. |
| Automotive Alloy Qualification | 6000-series heat treatment protocol optimization targets electric vehicle battery enclosure specifications. |
| Scrap Sorting Infrastructure | Electromagnetic separation lines in Hanoi industrial zones enable circular economy compliance for public tenders. |
Research Methodology
Coverage spans Vietnam's Red River Delta, Northern Highlands, Central Coast, and Southern Economic Zone, with primary inputs from each region combined with secondary validation. Primary interviews engaged extrusion plant managers, procurement leads at real estate developers, Ministry of Industry and Trade officials, and technical directors at automotive assembly plants. Secondary sources included customs and trade data on alumina and scrap aluminum flows, TCVN certification registries, industrial zone investment promotion board filings, and State Bank of Vietnam foreign exchange monitoring reports. Bottom-up facility capacity assessments triangulated against top-down consumption estimates from construction and automotive end-use sectors.
Granularity-level modeling addressed product type, application, end user, and form dimensions across the projection horizon, with alloy specification and processing technology as additional industry-specific variables. CAGRs were derived through trend extrapolation of historical consumption patterns adjusted for capacity expansion timelines and regulatory milestone impacts. Forecast inputs incorporated smelter commissioning schedules, bauxite mining license allocations, and electric vehicle platform localization announcements from foreign-invested assemblers.
Revisions become necessary when Ministry of Natural Resources and Environment emissions enforcement intensifies, State Bank of Vietnam foreign exchange policy shifts, or Chinese scrap aluminum border flows face tariff disruption. Forecasts reflect assumptions on industrial zone incentive continuity and TCVN certification requirement expansion in public procurement. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper and Brass Flat Products Market
Metals
Carbon Steel Market
Metals
Aluminum Wire Market
Metals
Global Tool Steel Market
Metals
Copper and Copper Alloy Powder Market
Metals
Cold Drawn Wire Market
Metals
Global Flat Carbon Steel Market
Metals
Iron Casting Market
Metals
Armour Steel Plate Market
Metals
Ferrochrome Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Lithium Foil Market
Metals
Electrolytic Iron Market
Metals
Metallurgical Silicon Market
Metals
Liquid Metal Thermal Pad Market
Metals
Titanium Sponge Market