
 Nickel Powder Plating Market | 2026-2036
Nickel Powder Plating Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Powder Plating Market Analytics
The gap between premium electroless nickel formulations and commodity-grade nickel cyanide baths is shifting procurement criteria across the supply chain. MMC Norilsk Nickel leverages captive mining assets to anchor raw material security for high-purity powder output. Vale differentiates through integrated refining complexes in Canada and Brazil that sustain consistent sulfate feedstock quality.
Nickel powder plating deposits a controlled-thickness metallic nickel layer onto substrates through electrochemical or autocatalytic reduction, typically achieving 5-50 micrometer coatings with hardness values of 500-700 HV after heat treatment. Electroless nickel dominates functional applications requiring uniform thickness on complex geometries, while high-phosphorus variants command premium positioning in electronics and medical devices due to superior corrosion resistance and solderability. Thermal spray technology leads heavy-duty aerospace and automotive repair segments where coating adhesion under mechanical stress determines component lifecycle.
EPA effluent limitations and REACH nickel compound restrictions shape permissible chemistries and waste handling protocols across manufacturing facilities. ISO 4527 and ASTM B733 define coating porosity and adhesion benchmarks that OEMs enforce through supplier qualification programs. Stakeholders must track evolving PFAS restrictions and nickel salt classification revisions, as these regulatory shifts will determine process substitution timelines and capital allocation for compliant plating infrastructure.
Market Dynamics
Electroless nickel plating is displacing conventional electrolytic methods in precision manufacturing, driven by aerospace and medical device OEMs demanding uniform coating thickness on complex geometries without electrical contact requirements.
Growth Catalysts
- Aerospace Component Mandates:Turbine blade manufacturers specify electroless nickel for corrosion protection under FAA airworthiness directives, accelerating qualification programs across US and European MRO facilities.
- REACH Nickel Compound Restrictions:ECHA classification revisions for nickel salts are elevating process standards, forcing facilities toward closed-loop chemistries that reduce effluent discharge and extend bath life.
- Automotive Electronics Miniaturization:High-phosphorus deposits achieve sub-5 micrometer uniformity on connector housings, matching the tolerances required for electric vehicle battery management systems.
Market Restraints
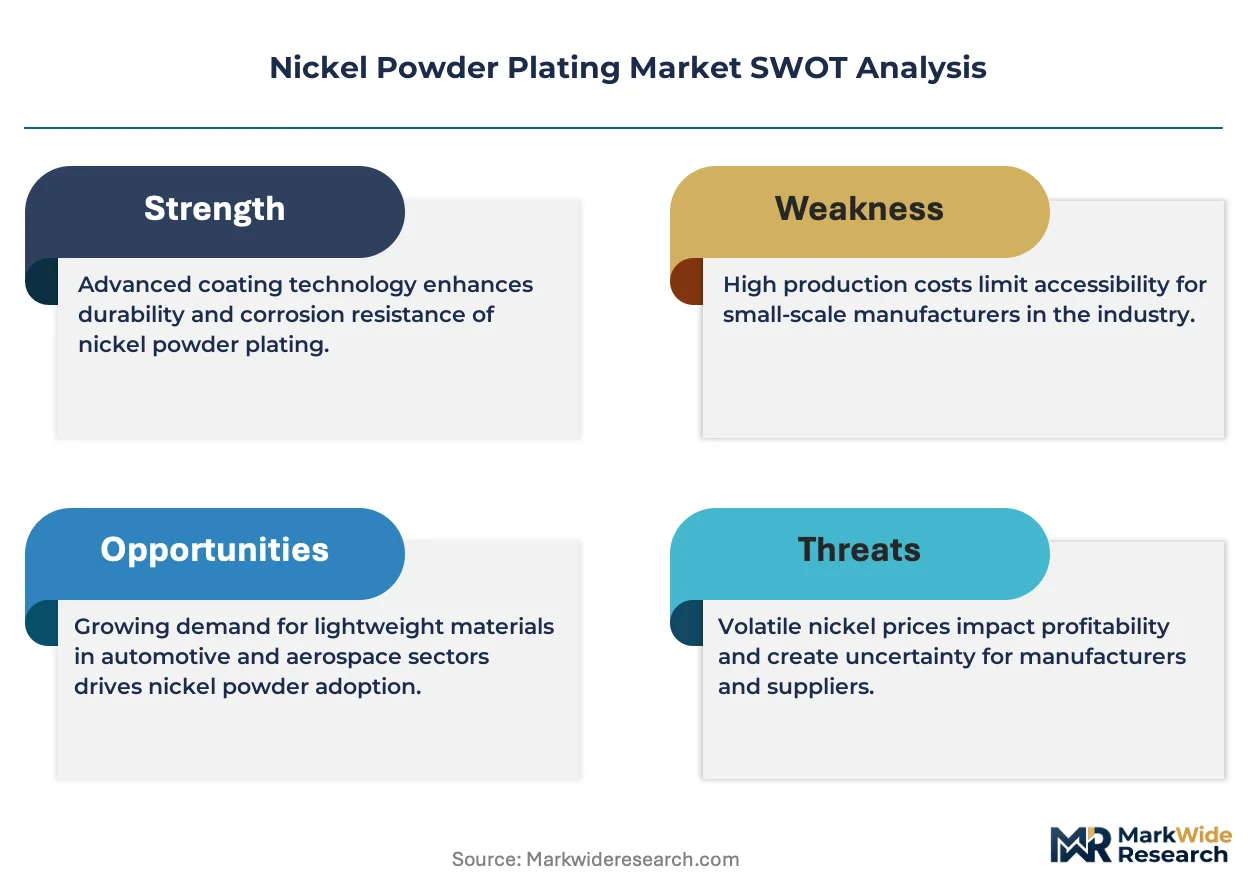
- Sulfate Feedstock Volatility:Nickel sulfate prices fluctuate with London Metal Exchange spot movements, compressing margins for independent plating job shops without long-term offtake agreements.
- Concentrated Mining Geography:Russian and Indonesian ore dominance creates supply security exposure for European and North American processors dependent on seaborne concentrate.
- Cyanide Bath Substitution Limits:Decorative bright nickel applications retain electrolytic cyanide chemistries where mirror-finish aesthetics outweigh functional performance requirements.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and mobile phone assembly are creating captive plating demand in Gujarat and Tamil Nadu clusters.
- Hydrogen Infrastructure Coatings:Electroless nickel-phosphorus deposits provide alkaline resistance for electrolyzer bipolar plates, opening process licensing opportunities with electrolyzer OEMs.
- Closed-Loop Chemistry Systems:Regenerative bath technologies reduce nickel drag-out losses below 2%, aligning with EPA effluent guidelines while lowering raw material consumption.
Industry Challenges
- Specialized Operator Training:Electroless bath chemistry management requires metallurgical expertise distinct from conventional plating, creating workforce bottlenecks in regions with limited technical education infrastructure.
- ISO 4527 Certification Timelines:OEM qualification programs demand 12-18 month validation cycles for new plating suppliers, delaying market entry for emerging process technologies.
- Legacy Equipment Retrofit Costs:Converting electrolytic lines to electroless operation requires tank heating systems, filtration upgrades, and automated replenishment controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Powder Plating Market |
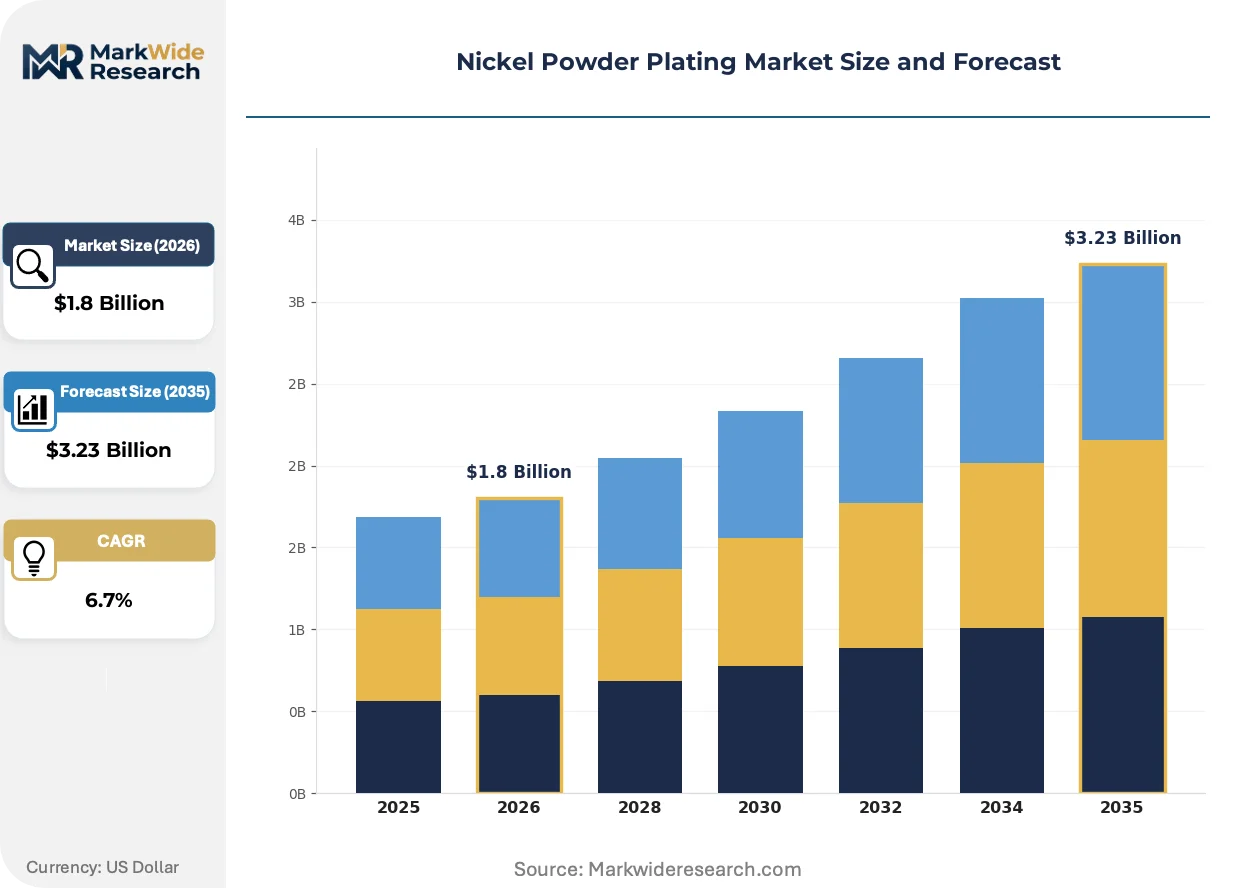
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroless Nickel, Nickel Sulfamate, Nickel Cyanide, High-Phosphorus Nickel Application: Aerospace, Automotive, Electronics, Medical Devices End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Maintenance Services Technology: Electroplating, Thermal Spray, Metallizing, Composite Plating |
| Companies Covered | MMC Norilsk Nickel, Jinchuan Group, Vale, BHP Billiton, Anglo American, Sumitomo Metal Mining, Sherritt, Xstrata, Nizi International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Powder Plating Market Evolving Landscape
Process automation and real-time bath monitoring are compressing quality variability in high-volume plating operations, while regulatory chemistry restrictions accelerate formulation innovation.
Composite electroless nickel incorporating silicon carbide or PTFE particles is integrating wear-resistant and low-friction properties into single-deposit systems. Automotive transmission component suppliers adopt these variants for synchronizer hubs and valve bodies. The technology is integrating previously separate coating and surface finishing steps, reducing line footprint and work-in-process inventory.
EPA effluent limitation guidelines under the Clean Water Act are tightening allowable nickel discharge concentrations for metal finishing facilities. Plating operations in Ohio, Michigan, and California industrial corridors face capital decisions on end-of-pipe treatment versus chemistry substitution. High-phosphorus electroless formulations with extended bath life are gaining preference in affected jurisdictions.
Automotive Tier-1 suppliers now specify plating process certification as a condition of supplier qualification, not merely finished-part testing. This shifts commercial risk onto plating subcontractors who must maintain continuous compliance documentation. German and Japanese automotive electronics manufacturers enforce this most stringently, rejecting suppliers without IATF 16949-aligned process controls.
Nickel Powder Plating Market Segmentation
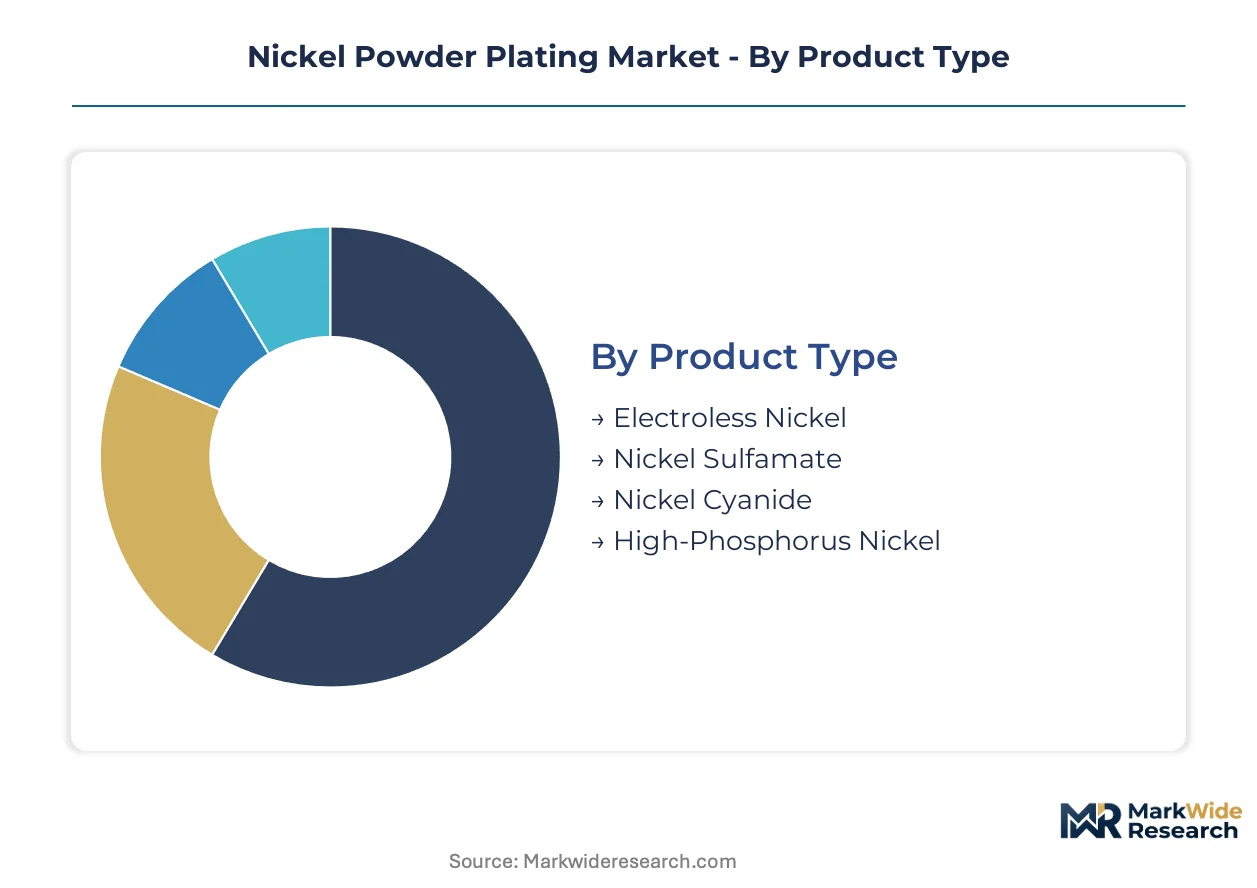
Segmentation in nickel powder plating reveals how process chemistry and deposition technology align with end-use performance requirements. Each category captures distinct procurement patterns shaped by regulatory compliance, substrate complexity, and coating functional specifications.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity baths to highly formulated proprietary chemistries requiring precise bath management protocols.
- Electroless Nickel:Autocatalytic reduction deposits uniform nickel-phosphorus or nickel-boron layers without external current, achieving exceptional thickness consistency on internal diameters and complex geometries. Aerospace turbine blade manufacturers in the United States and Germany specify this chemistry under FAA and EASA airworthiness directives for corrosion protection in hot-section components.
- High-Phosphorus Nickel:Amorphous deposits containing 10-14% phosphorus deliver superior corrosion resistance and solderability for electronics interconnects. Medical device OEMs in Switzerland and Japan select this variant for surgical instrument coatings requiring biocompatibility certification under MDR and PMDA frameworks.
- Nickel Sulfamate:Low-stress deposits favored for thick-build applications where ductility and minimal hydrogen embrittlement matter.
- Nickel Cyanide:Bright decorative finishes retained in consumer goods where mirror aesthetics override functional performance metrics.
Leading the category by volume: Electroless Nickel. Growing fastest: High-Phosphorus Nickel.
Application:
End-use differentiation tracks directly with component lifecycle value and failure-mode consequences, from catastrophic turbine failure to cosmetic electronics finishing.
- Aerospace:FAA-mandated corrosion protection for turbine blades, landing gear, and fuel system components drives specification of high-phosphorus electroless nickel with 25-75 micrometer deposits. MRO facilities in Ohio, Arizona, and Hamburg cluster around major airline maintenance bases.
- Electronics:Miniaturized connector housings and battery management system components require sub-5 micrometer uniformity achievable only through precision electroless processes. Semiconductor packaging growth in Gujarat and Tamil Nadu clusters under India's PLI scheme is expanding captive plating capacity.
- Automotive:Transmission synchronizers and fuel injection components balance wear resistance with cost constraints.
- Medical Devices:Surgical instruments and implantable component coatings demand biocompatibility documentation and lot traceability.
Highest specification requirements: Aerospace. Expanding most quickly: Electronics.
End User:
Procurement authority and technical capability determine whether plating occurs in-house or through qualified subcontractor networks.
- OEMs:Aerospace primes and automotive manufacturers maintain captive plating lines for critical components, investing in ISO 4527-certified processes with continuous bath monitoring and automated replenishment. Boeing, Airbus, and Siemens Energy enforce supplier qualification programs requiring 12-18 month validation cycles.
- Tier-1 Suppliers:Continental, Bosch, and Denso operate regional plating facilities proximate to assembly plants, balancing just-in-time delivery with process standardization across manufacturing sites.
- Aftermarket Providers:Independent job shops serve repair and refurbishment demand without OEM captive capacity.
- Maintenance Services:MRO operators perform field-restoration plating for aging infrastructure and legacy equipment.
Dominant procurement volume: OEMs. Fastest qualification expansion: Tier-1 Suppliers.
Technology:
Capital intensity and substrate compatibility separate established electrolytic methods from emerging deposition approaches.
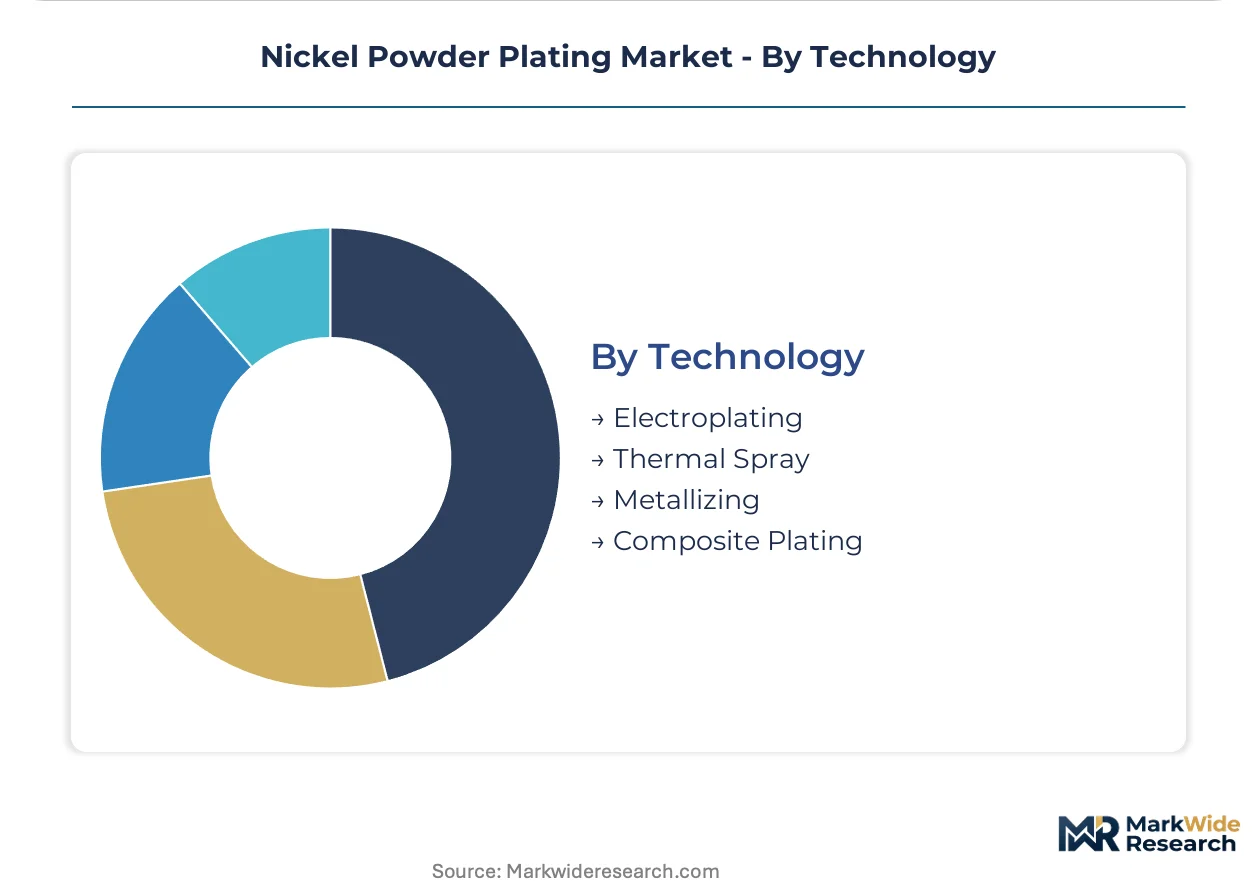
- Electroplating:Conventional electrolytic processes dominate high-volume decorative and functional applications where electrical contact geometry permits uniform current distribution. Automotive bright trim and consumer electronics housings rely on commodity sulfate and sulfamate chemistries with established waste treatment infrastructure.
- Thermal Spray:High-velocity oxygen fuel and plasma spray systems deposit thick nickel coatings for aerospace component repair and heavy machinery restoration. GE Aviation and Rolls-Royce authorize these processes for turbine blade dimensional restoration in certified repair stations.
- Metallizing:Vacuum deposition and chemical vapor techniques serve specialized electronics and optical applications.
- Composite Plating:Electroless matrices incorporating silicon carbide or PTFE particles integrate wear and friction properties in single-deposit systems.
Widest installed base: Electroplating. Steepest capability investment: Thermal Spray.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive plating corridor anchors North American electroless nickel demand for transmission and fuel system components. European aerospace clusters in Hamburg and Toulouse drive high-specification coating volumes under EASA mandates. Asian electronics manufacturing zones in Gujarat and Shenzhen concentrate precision plating capacity for semiconductor packaging.
United States
Aerospace MRO facilities in Ohio and Arizona specify electroless nickel for turbine blade restoration under FAA airworthiness directives. EPA effluent limitation guidelines under the Clean Water Act tighten allowable nickel discharge concentrations for metal finishing operations in Michigan and California industrial corridors. Boeing and GE Aviation enforce supplier qualification programs requiring ISO 4527-certified processes with continuous bath monitoring.
Germany
Automotive Tier-1 suppliers in Baden-Württemberg operate captive plating lines for transmission synchronizers and fuel injection components. ECHA REACH classification revisions for nickel salts elevate process standards, forcing facilities toward closed-loop chemistries that reduce effluent discharge. Siemens Energy and Continental enforce IATF 16949-aligned process controls across regional supplier networks.
China
Electronics manufacturing clusters in Shenzhen and Dongguan expand captive plating capacity for connector housings and battery management systems under MIIT industrial upgrading programs. NMPA and GB standards govern medical device coating biocompatibility for surgical instrument exports. Yangtze River Delta automotive plants balance wear-resistant coating costs with electric vehicle production scale targets.
India
PLI scheme incentives for semiconductor packaging and mobile phone assembly create captive plating demand in Gujarat and Tamil Nadu clusters. BIS certification requirements align with ISO 4527 coating porosity benchmarks for automotive electronics suppliers. Tata Electronics and Foxconn India establish regional plating facilities proximate to assembly plants.
Japan
Medical device OEMs in Osaka and Tokyo select high-phosphorus nickel variants for surgical instrument coatings requiring PMDA biocompatibility certification. METI industrial technology roadmaps prioritize process automation and real-time bath monitoring for high-volume operations. Denso and Bosch Japan enforce 12-18 month supplier validation cycles for new plating subcontractors.
Nickel Powder Plating Market Competitive Landscape
Premium-margin players sit above commodity-margin players across raw material security and captive refining integration. MMC Norilsk Nickel leverages mining assets to anchor feedstock supply for high-purity powder output, while Vale sustains consistent sulfate quality through integrated refining complexes. Three archetypes dominate: vertically integrated miners with captive plating chemical production, independent refiners dependent on spot concentrate markets, and regional distributors aggregating commodity-grade formulations. Competitive moves concentrate on long-term offtake agreements with aerospace primes and regenerative bath technology licensing to Tier-1 automotive suppliers.
Within the integrated mining tier, MMC Norilsk Nickel and Vale exemplify upstream-controlled supply security. Jinchuan Group represents Chinese state-backed consolidation of nickel sulfate refining capacity. Sumitomo Metal Mining occupies a position bridging Pacific Rim concentrate supply with Japanese electronics industry plating demand.
| Leading Market Players |
|---|
| MMC Norilsk Nickel |
| Jinchuan Group |
| Vale |
| BHP Billiton |
| Anglo American |
| Sumitomo Metal Mining |
| Sherritt |
| Xstrata |
| Nizi International |
| Others |
Value Network & Pricing Analysis
Nickel sulfate feedstock costs cascade through three distinct pricing tiers, with London Metal Exchange spot volatility compressing margins at independent plating job shops while integrated miners with captive refining anchor premium-grade electroless nickel formulations at aerospace primes.
Pricing Analysis
Yield-guaranteed throughput pricing anchors premium electroless nickel contracts, where aerospace OEMs pay for certified coating performance rather than bath chemistry alone. Price differentiation separates ISO 4527-certified high-phosphorus formulations from commodity cyanide decorative baths, with certification tier and volume scale as primary drivers. Pricing pressure stems from sulfate feedstock spot volatility, eroding margins at non-integrated job shops. Tier-1 automotive suppliers exhibit highest price sensitivity due to just-in-time inventory constraints, while medical device OEMs prioritize biocompatibility documentation over unit cost.
Supply Chain Analysis
Skilled metallurgical technician shortages in Michigan and Ohio industrial corridors constrain electroless bath management capacity at independent plating facilities. Raw material supply draws from Russian and Indonesian mining concentration for nickel ore, Canadian and Brazilian refining complexes for sulfate feedstock, and German and Japanese chemical specialists for proprietary bath formulations. Single-source vulnerability runs through seaborne concentrate dependence for European and North American processors. Distribution runs through qualified subcontractor networks vetted via 12-18 month OEM validation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance capabilities, with EPA effluent guidelines and REACH nickel compound restrictions forcing smaller independent job shops toward acquisition or exit.
For Market Incumbents: To counter margin compression from sulfate spot volatility, secure long-term offtake agreements with aerospace primes and license regenerative closed-loop bath technology to Tier-1 automotive suppliers. Backward integration into captive sulfate refining or strategic partnerships with Canadian and Brazilian integrated miners stabilizes feedstock cost exposure. For New Entrants and Emerging Players: Digital-channel process automation platforms offer the most penetrable entry vector, targeting mid-size plating job shops in India's Gujarat and Tamil Nadu electronics clusters lacking ISO 4527 certification infrastructure. White-space opportunity sits in hydrogen electrolyzer bipolar plate coating licensing, where alkaline-resistant electroless nickel-phosphorus deposits face limited qualified competition. For Investors and Strategic Acquirers: Tier-1 automotive supplier qualification program announcements are the leading indicator that captive plating capacity expansion is accelerating, signaling acquisition timing for regional electroless nickel specialists with existing IATF 16949 alignment. Target archetypes include mid-cap plating subcontractors in Germany's Baden-Württemberg automotive corridor with certified high-phosphorus capabilities and documented process automation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Chemistry Licensing | Regenerative bath technology reduces nickel drag-out below 2%, aligning with EPA effluent guidelines. |
| Long-Term Offtake Agreements | Contracted sulfate supply insulates independent job shops from London Metal Exchange spot volatility. |
| ISO 4527 Certification Investment | Coating porosity and adhesion benchmarks unlock 12-18 month OEM supplier qualification pipelines. |
| Hydrogen Infrastructure Partnership | Electrolyzer bipolar plate coating demand opens process licensing with alkaline-resistant formulations. |
| Indian Electronics Cluster Expansion | PLI scheme incentives in Gujarat and Tamil Nadu concentrate captive plating capacity near assembly plants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plating plant managers, aerospace procurement leads at Boeing and Airbus, Tier-1 automotive supplier quality directors, and electroless nickel chemical formulators. Secondary sources included EPA effluent limitation databases, ECHA REACH substance registrations, SEC 10-K filings from integrated miners, and national trade statistics from USITC and Eurostat. Bottom-up plating capacity estimates triangulated against top-down end-use demand modeling.
Segment-level granularity modeled chemistry type, application sector, end-user procurement authority, and deposition technology across the projection horizon. Aerospace turbine blade specifications, automotive electronics miniaturization tolerances, and medical device biocompatibility requirements informed demand elasticity assumptions. CAGRs derived from volume-weighted segment growth rates applied against base-year market sizing, with cross-validation against electrolytic versus electroless process substitution trends.
The model holds under stable regulatory enforcement of EPA and REACH nickel compound restrictions; deviation in PFAS classification revisions or nickel salt hazard reclassifications would shift process substitution timelines. Forecasts reflect assumptions regarding continued aerospace MRO demand and electric vehicle electronics content expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Saudi Arabia Aluminum Market
Metals
Copper and Copper Alloy Powder Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Electrolytic Iron Market
Metals
Weathering Steel Market
Metals
Ferro Aluminum Market
Metals
Global Electrolytic Copper Foil Market
Metals
North America Metal Casting Market
Metals
Global Hot Rolled Coil Steel Market
Metals
HSLA Steel Plate Market
Metals
US Metal Fabrication Market
Metals
TMCP Steel Market
Metals
Ferrochrome Market
Metals
Aluminum Fluoride Market
Metals
Palladium Market
Metals
Aluminum Welding Wires Market