
 China Neodymium Iron Boron Magnet Market | 2026-2036
China Neodymium Iron Boron Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
China Neodymium Iron Boron Magnet Market Intelligence
Automotive traction motor demand is realigning procurement priorities across China's magnet value chain. Ningbo Tongchuang Magnetic Materials leverages vertical integration from rare-earth separation to finished magnet fabrication. JL Mag Rare-Earth Co., Ltd. anchors high-coercivity product lines for elevated-temperature EV applications. SDM Magnetics Co., Ltd. differentiates through grain-boundary diffusion technology for heavy-rare-earth reduction.
Neodymium iron boron magnets consist of an Nd₂Fe₁₄B tetragonal crystalline structure produced via powder metallurgy sintering or polymer-bonded compression molding, delivering maximum energy products exceeding 400 kJ/m³ for electromechanical torque conversion. Sintered magnets dominate volume owing to superior magnetic remanence and coercivity, while bonded variants capture cost-sensitive electronics applications with complex geometries. Renewable energy generators represent the fastest-expanding application pool as offshore wind installations multiply along China's eastern seaboard.
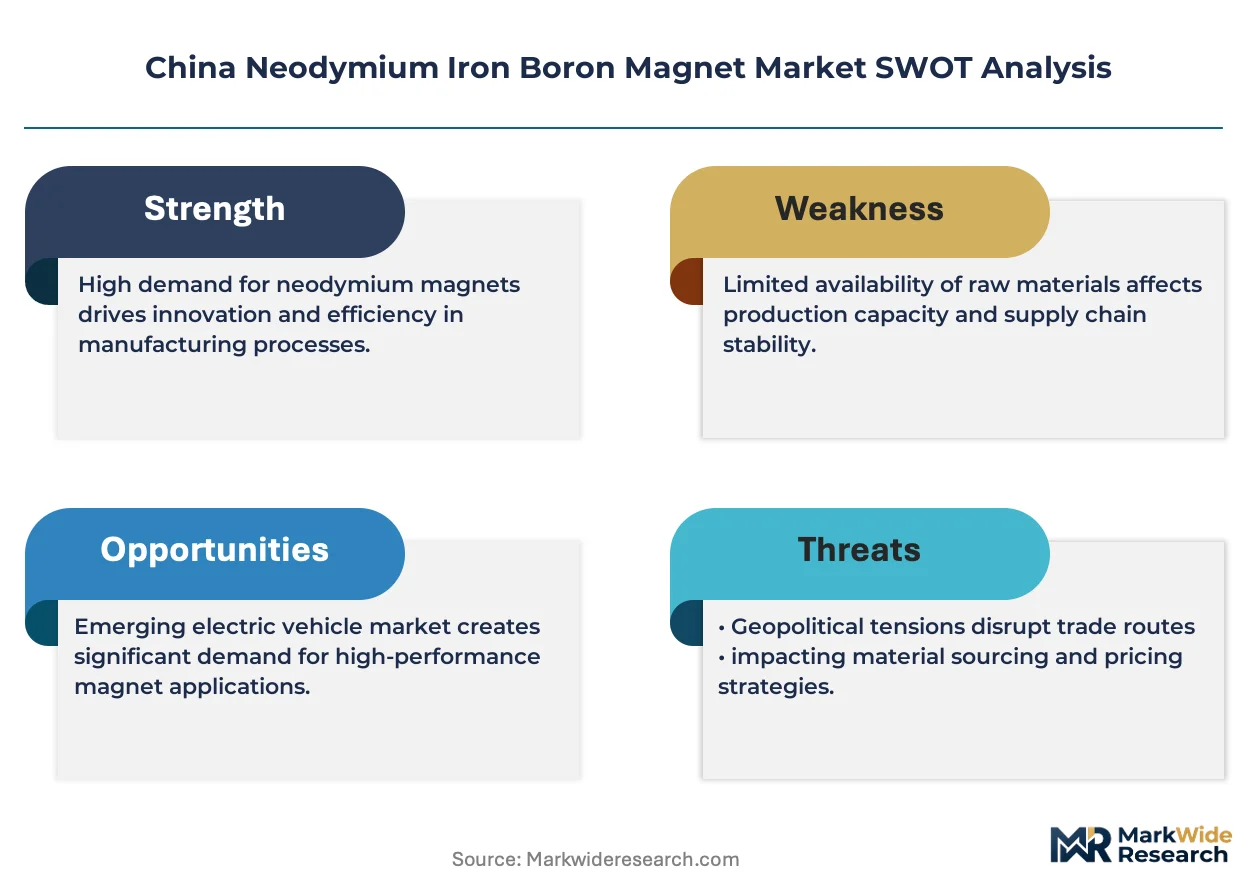
MIIT production quota regulations constrain rare-earth oxide supply, while SAMR enforces GB/T 13560-2017 magnetic performance standards that filter subscale producers from grid-tender eligibility. The country's dual carbon goals mandate magnet recyclability disclosures under MEE circular economy directives. Stakeholders must monitor quota allocation shifts and GB standard revision timelines to secure feedstock access and maintain certification currency.
Market Dynamics
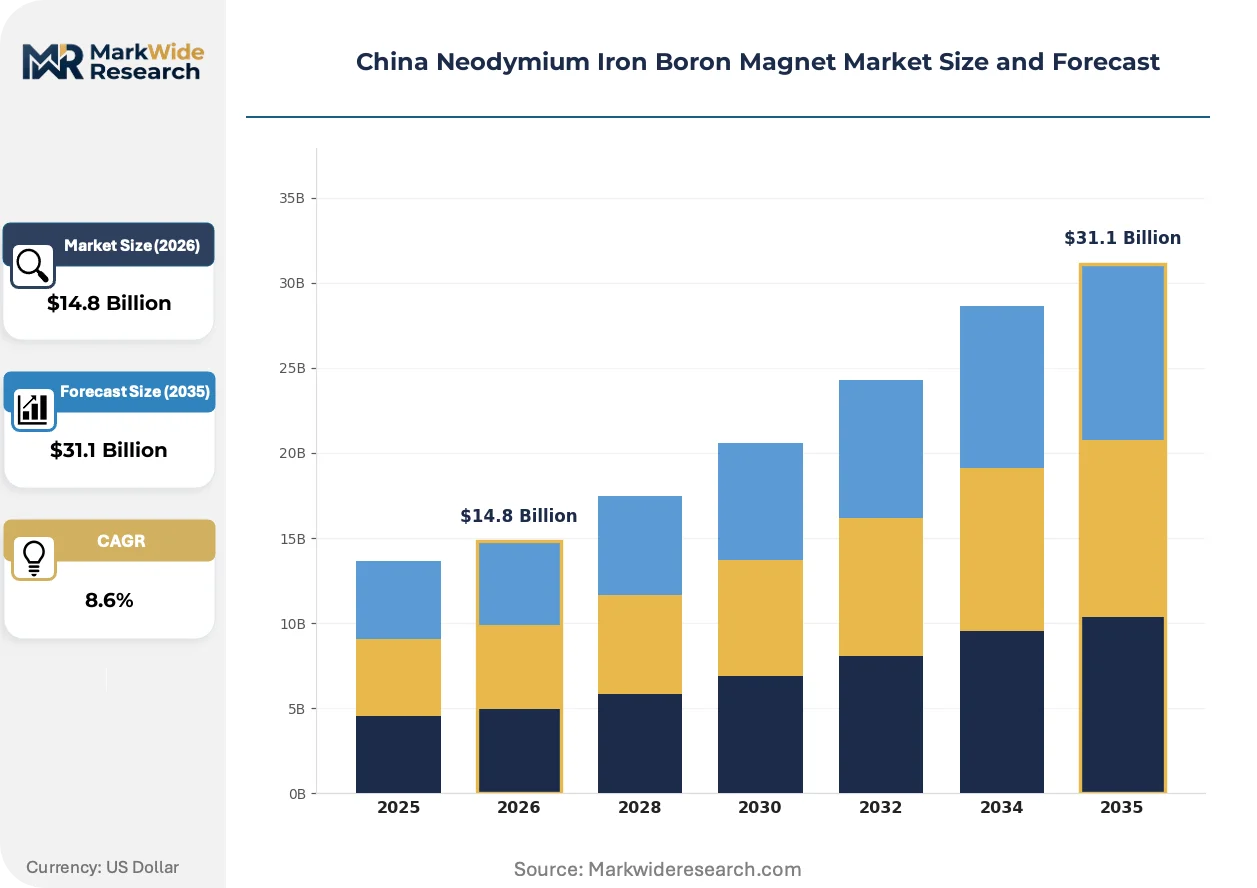
MIIT rare-earth processing quotas and GB/T magnetic performance standards are compressing supply elasticity while EV motor procurement concentrates demand around Ningbo's fabrication cluster. This regulatory-demand squeeze is forcing magnet producers to secure feedstock access through captive separation assets or risk quota exclusion.
Growth Catalysts
- Automotive electrification mandates:China's new energy vehicle subsidy extensions and dual carbon goals are pulling sintered NdFeB volumes into traction motor supply chains. Ningbo and Jiangsu corridors are expanding sintering capacity to match procurement schedules.
- Offshore wind generator procurement:Coastal provinces are tendering multi-gigawatt offshore wind arrays requiring direct-drive permanent magnet generators. These installations specify high-coercivity magnet grades that command premium pricing tiers.
- GB/T 13560-2017 certification expansion:SAMR enforcement of magnetic performance standards is filtering subscale producers from grid-tender eligibility. Certified producers are capturing volume that uncertified competitors cannot access.
Market Restraints
- Dysprosium-terbium price volatility:Heavy rare-earth prices swing with Myanmar import disruptions and ionic clay mining quotas. Magnet fabricators face margin compression when hedging fails to cover spot spikes.
- Upstream supply concentration:Six state-owned rare-earth groups control oxide separation under MIIT quota allocation. Private magnet producers remain price-takers on feedstock without backward integration into separation.
- Samarium-cobalt substitution in aerospace:Defense and satellite applications are specifying SmCo for temperature stability above 180°C. NdFeB cannot penetrate these segments without uneconomic heavy-rare-earth loading.
Strategic Opportunities
- Western China processing expansion:Sichuan and Gansu rare-earth deposits remain underdeveloped relative to Inner Mongolia and Jiangxi. Quota allocation shifts toward these provinces could unlock captive oxide supply for integrated producers.
- Magnet recyclability certification:MEE circular economy directives are mandating recyclability disclosures for industrial equipment procurement. First movers in hydrometallurgical magnet recovery are positioning for preferential tender scoring.
- Grain-boundary diffusion process scaling:Heavy-rare-earth reduction through grain-boundary diffusion is cutting Dy/Tb content by 30-50% while maintaining coercivity. Process licensors are capturing technology transfer fees from second-tier sintering houses.
Industry Challenges
- Magnet alloy formulation expertise scarcity:Master alloy design for elevated-temperature EV applications requires rare-earth metallurgy PhDs. Ningbo and Zhejiang employers are poaching talent from state research institutes at premium compensation multiples.
- Sintering furnace capex intensity:Continuous hydrogen decrepitation and jet milling lines require 200M+ RMB per greenfield line. Mid-scale producers face financing constraints against state-backed competitors.
- GB standard revision timeline uncertainty:Draft GB/T revisions for higher temperature-grade classification remain in committee. Producers cannot commit R&D budgets without clarity on test protocols and certification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Neodymium Iron Boron Magnet Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sintered, Bonded, Disc, Block Application: Electronics, Automotive, Renewable Energy, Healthcare End User: OEMs, Tier-1 Suppliers, Research Institutions, Aftermarket Providers Distribution Channel: Direct Sales, Online Sales, Distributors, Resellers |
| Companies Covered | Ningbo Tongchuang Magnetic Materials Co., Ltd., Zhejiang Sheensen Magnetics Technology Co., Ltd., SDM Magnetics Co., Ltd., Zhaobao Magnet Co., Ltd., Ningbo Ketian Magnet Co., Ltd., JL Mag Rare-Earth Co., Ltd., Baotou Tianhe Magnetics Technology Co., Ltd., MainRich Magnets, HGT Advanced Magnets, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Neodymium Iron Boron Magnet Market Strategic Shifts & Innovations
Magnet fabrication technology is pivoting toward heavy-rare-earth efficiency as procurement specifications tighten. Three converging developments are compressing legacy process economics and rewiring competitive positioning across the value chain.
Grain-boundary diffusion technology is absorbing the technical risk of Dy/Tb reduction in high-temperature motor applications. JL Mag and SDM Magnetics are scaling diffusion-processed magnet output for 150°C continuous-operation EV inverters. The technology is absorbing market share from conventional sintering routes that require full-alloy heavy-rare-earth loading.
MIIT quota allocation mechanisms are tightening supply discipline through quarterly rare-earth oxide release schedules. State-owned processors must demonstrate downstream magnet fabrication offtake agreements to secure full quota rights. Grid-tendering provinces are responding by requiring magnet traceability documentation from generator suppliers.
Magnet procurement is consolidating around vertically integrated suppliers with captive separation assets. Wind turbine OEMs are bypassing trading houses to contract directly with Ningbo-based fabricators holding Jiangxi or Sichuan oxide offtake. This disintermediation is most visible in Jiangsu procurement corridors where tender documentation now specifies smelter-origin certificates.
China Neodymium Iron Boron Magnet Market Segmentation
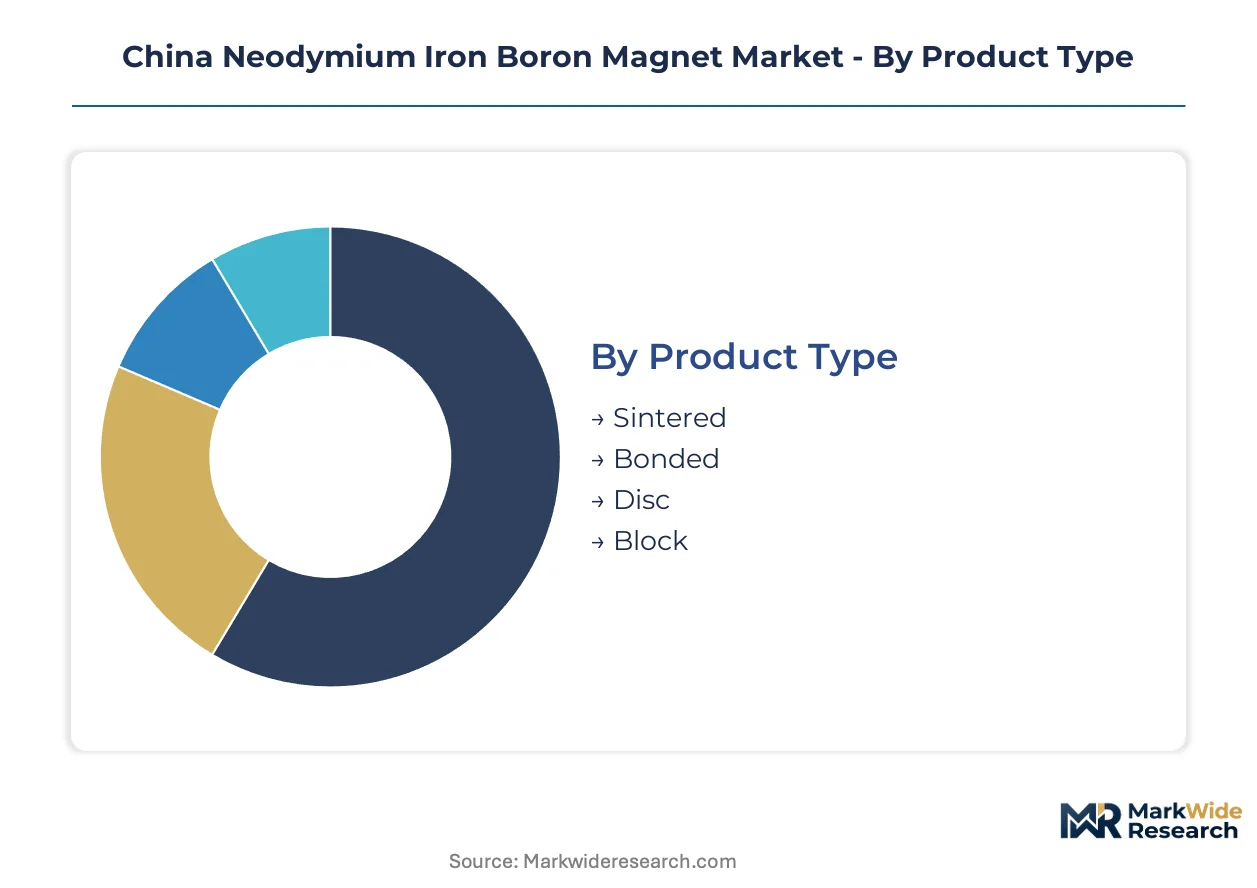
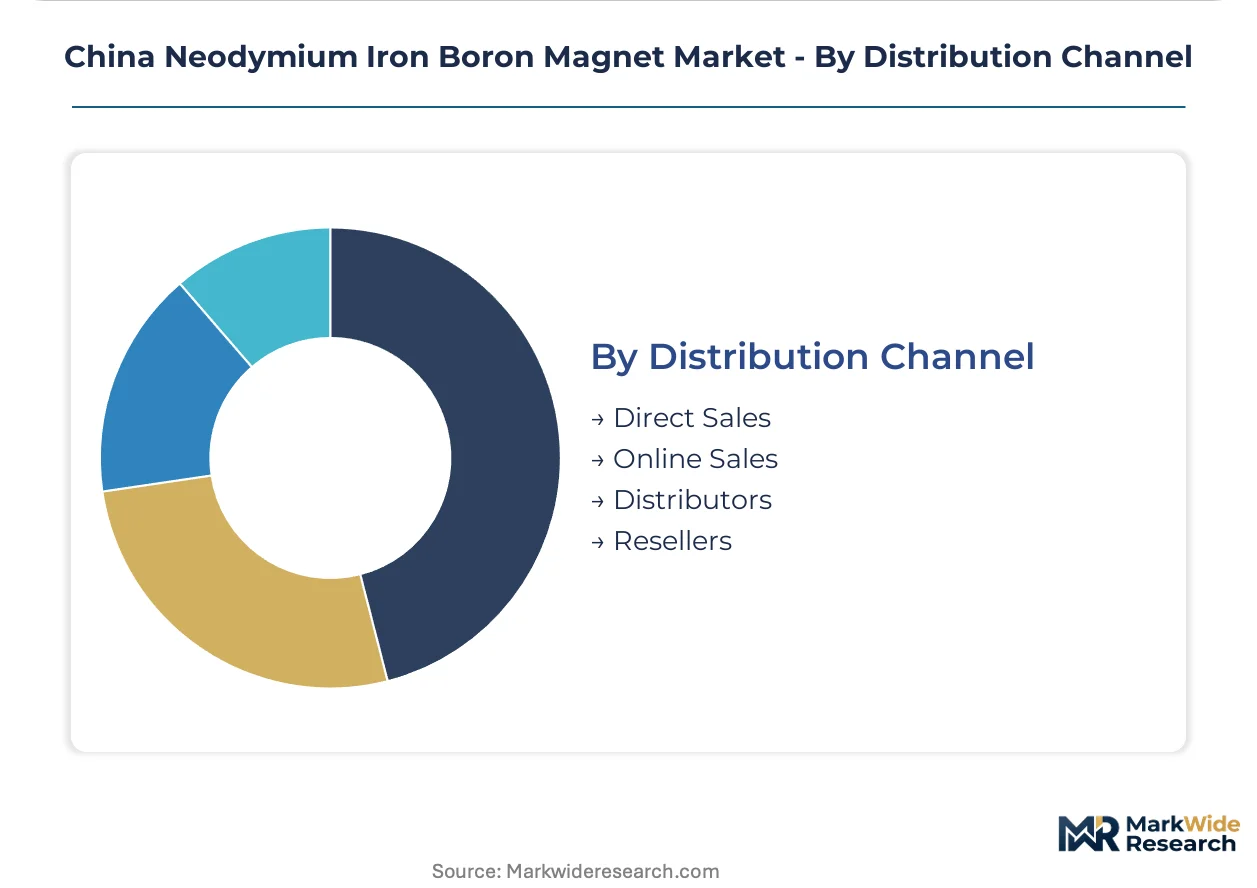
China's NdFeB magnet market fragments across product architecture, application torque requirements, and procurement channel structures. Each segmentation axis reveals distinct margin profiles and certification barriers that determine supplier access.
Product Type:
Buyers in this category differentiate by magnetic energy density requirements and geometric complexity tolerances.
- Sintered:Powder metallurgy sintering achieves maximum energy products exceeding 400 kJ/m³ through aligned Nd₂Fe₁₄B crystal structures. EV traction motor procurement in Ningbo and Jiangsu corridors absorbs the highest-grade sintered volumes under GB/T 13560-2017 certification requirements.
- Bonded:Polymer-bonded compression molding enables complex geometries with isotropic magnetic properties for cost-sensitive electronics. Consumer electronics OEMs in Guangdong specify bonded magnets where dimensional precision outweighs remanence demands.
- Disc:Axially magnetized cylindrical forms serve rotational motor assemblies requiring uniform field distribution. Appliance motor manufacturers in Zhejiang source disc configurations for compressor and pump applications.
- Block:Rectangular prism geometries accommodate linear actuator and sensor housing designs. Industrial automation suppliers in Jiangsu procure block magnets for conveyor and positioning systems.
Volume sits with sintered grades; growth tilts toward bonded variants expanding in wearable electronics.
Application:
End-use specifications in this category range from ambient-temperature consumer devices to 150°C continuous-operation EV inverters.
- Automotive:Traction motor and inverter applications demand high-coercivity grades with heavy-rare-earth stabilization. Ningbo fabricators with grain-boundary diffusion capability are capturing procurement from domestic EV OEMs accelerating platform launches.
- Renewable Energy:Direct-drive permanent magnet generators for offshore wind arrays specify temperature-stable grades. Jiangsu and Fujian coastal provinces are tendering multi-gigawatt installations requiring magnet traceability documentation.
- Electronics:Miniaturized speakers, hard disk drives, and vibration motors consume bonded and low-grade sintered volumes. Shenzhen electronics clusters prioritize unit cost over magnetic performance metrics.
- Healthcare:MRI gradient coils and surgical navigation systems require homogeneous magnetic fields with tight tolerance bands. Medical device OEMs specify certified suppliers with ISO 13485 quality management systems.
Procurement volume clusters in automotive; steepest expansion trajectory belongs to renewable energy generator specifications.
End User:
Customer scale in this category determines quota access negotiation leverage and contract tenure structures.
- OEMs:Original equipment manufacturers with multi-year production programs contract directly for sintered magnet supply. BYD and NIO anchor procurement volumes with backward-integrated magnet specifications.
- Tier-1 Suppliers:Motor and generator subsystem integrators aggregate demand across OEM platforms. Valeo Siemens and Bosch China filter specifications through their supplier qualification systems.
- Research Institutions:National laboratories and university engineering centers procure small-batch specialty grades for prototype development. Chinese Academy of Sciences facilities drive specifications for next-generation high-temperature formulations.
- Aftermarket Providers:Replacement motor and sensor suppliers source through trading houses without captive oxide access. Price sensitivity dominates procurement criteria in this channel.
Contract value concentrates with OEMs; procurement flexibility expands fastest among Tier-1 suppliers diversifying magnet sources.
Distribution Channel:
Channel selection in this category reflects order scale, technical specification complexity, and certification documentation requirements.
- Direct Sales:Magnet fabricators with captive separation assets contract bilaterally with wind turbine OEMs and automotive platforms. MIIT quota allocation incentives favor direct channel volume with demonstrated downstream offtake.
- Distributors:Regional trading houses aggregate small-to-mid scale demand from industrial automation and appliance manufacturers. Inventory risk concentrates with distributors holding spot oxide exposure.
- Online Sales:E-commerce platforms serve prototype and maintenance-repair-operations demand with standard-grade catalog offerings. Alibaba and JD Industrial channels capture price-transparent spot purchasing.
- Resellers:Secondary market intermediaries source excess inventory and off-specification lots for cost-sensitive applications. Quality consistency varies without manufacturer warranty coverage.
Revenue gravity centers on direct sales; channel expansion is accelerating through distributor networks penetrating western China manufacturing bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo Economic and Technological Development Zone magnet fabrication incentives are concentrating sintered NdFeB capacity along Zhejiang's coastal corridor. Provincial governments in Jiangsu and Fujian are matching these policies with dedicated rare-earth processing parks.
Yangtze River Delta
Automotive traction motor procurement from BYD and NIO is pulling high-coercivity magnet volumes into Jiangsu manufacturing corridors. SAMR enforces GB/T 13560-2017 certification for grid-tender eligibility across the region. Suzhou and Changzhou industrial clusters are expanding hydrogen decrepitation capacity to meet EV platform launch schedules.
Pearl River Delta
Consumer electronics OEMs in Shenzhen specify bonded magnets for miniaturized speakers and vibration motors where dimensional precision outweighs remanence demands. Guangdong provincial standards align with MIIT rare-earth processing quota compliance documentation. Dongguan magnet trading houses aggregate spot demand from appliance manufacturers without captive oxide access.
Beijing-Tianjin-Hebei
Wind turbine OEM procurement of direct-drive permanent magnet generators is specifying temperature-stable grades for offshore arrays along the Bohai Rim. MEE circular economy directives mandate recyclability disclosures for industrial equipment tendering in the capital region. Tianjin port logistics clusters are consolidating import channels for Myanmar heavy rare-earth feedstock.
Sichuan-Chongqing
Western China rare-earth deposits in Mianning and Dechang remain underdeveloped relative to Inner Mongolia and Jiangxi baselines. MIIT quota allocation shifts toward these provinces could unlock captive oxide supply for integrated producers. Chengdu magnet research institutes are driving specifications for next-generation high-temperature formulations.
Shandong Peninsula
Industrial automation suppliers in Qingdao procure block magnets for conveyor and positioning systems with moderate coercivity requirements. Provincial environmental bureaus enforce MEE magnet waste recovery standards for manufacturing facility licensing. Yantai port infrastructure is developing dedicated rare-earth concentrate handling terminals.
China Neodymium Iron Boron Magnet Market Key Industry Players
Top-tier vendors anchor premium-grade sintered magnet supply, while mid-scale fabricators compete on bonded variant cost structures. The vendor base stratifies across three tiers: state-backed groups with captive separation assets, Ningbo-Zhejiang integrated specialists, and trading-dependent regional processors. Two dominant competitive moves are capacity expansion in Jiangsu sintering corridors and strategic partnerships securing MIIT quota allocation rights.
Among Ningbo-based integrated fabricators, Ningbo Tongchuang Magnetic Materials Co., Ltd., SDM Magnetics Co., Ltd., and JL Mag Rare-Earth Co., Ltd. exemplify the vertical specialist archetype with backward integration into rare-earth separation. Zhejiang Sheensen Magnetics Technology Co., Ltd. and Ningbo Ketian Magnet Co., Ltd. occupy positions within the regional trading house network. Baotou Tianhe Magnetics Technology Co., Ltd. represents the northern China processing cluster with proximity to Inner Mongolia oxide supply. These named entities serve as anchors for understanding competitive positioning without attributing specific strategic actions or market shares.
| Leading Market Players |
|---|
| Ningbo Tongchuang Magnetic Materials Co., Ltd. |
| Zhejiang Sheensen Magnetics Technology Co., Ltd. |
| SDM Magnetics Co., Ltd. |
| Zhaobao Magnet Co., Ltd. |
| Ningbo Ketian Magnet Co., Ltd. |
| JL Mag Rare-Earth Co., Ltd. |
| Baotou Tianhe Magnetics Technology Co., Ltd. |
| MainRich Magnets |
| HGT Advanced Magnets |
| Others |
Cost & Logistics Intelligence
State-backed rare-earth groups with captive separation assets anchor feedstock pricing power, compressing margin flexibility for private magnet fabricators without backward integration into oxide supply. MIIT quota allocation mechanisms tighten supply discipline quarterly, forcing non-integrated producers to absorb spot price volatility or exit grid-tender eligibility.
Pricing Analysis
Short lead-time premiums for certified high-coercivity grades separate emergency procurement from scheduled offtake contracts in Ningbo and Jiangsu corridors. Contract-based long-term offtake dominates automotive traction motor supply, with price differentiation driven by GB/T 13560-2017 certification tier and demonstrated heavy-rare-earth reduction through grain-boundary diffusion. Cost compression in standard-grade sintered magnets intensifies as second-tier producers compete for appliance motor volumes. Aftermarket providers through trading houses exhibit highest price sensitivity; wind turbine OEMs with direct fabricator contracts show least.
Supply Chain Analysis
Magnet waste recovery flows through hydrometallurgical refineries are emerging as secondary feedstock channels under MEE circular economy directives. Primary supply concentrates in China, with Myanmar and Australia as critical heavy rare-earth sources. The chain draws from dysprosium-terbium oxide, neodymium-praseodymium alloy, and polymer binder inputs. Single-source vulnerability in Myanmar ionic clay imports poses structural risk. Distribution runs through direct bilateral contracts between integrated fabricators and OEM platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT rare-earth processing quotas function as the binding capacity constraint, sustaining pricing premiums for quota-holding integrated producers while excluding trading-dependent competitors from automotive and wind tender eligibility.
For Market Incumbents: To counter SmCo substitution in aerospace and defense temperature applications, anchor R&D investment in heavy-rare-earth reduction through grain-boundary diffusion scaling. Secure captive separation assets in Sichuan or Gansu through quota allocation partnerships to defend feedstock access. Certification maintenance under draft GB/T revisions represents the critical defensive lever. For New Entrants and Emerging Players: MEE circular economy directives in China open a window for hydrometallurgical magnet recovery specialists to capture preferential tender scoring. Target western China processing expansion in Sichuan-Chongqing corridors where rare-earth deposits remain underdeveloped relative to Jiangxi baselines. Position through recyclability certification as the go-to-market angle for industrial equipment procurement. For Investors and Strategic Acquirers: Draft GB/T standard revisions entering committee review is the leading indicator that certification currency will concentrate market share among prepared producers. Five-to-ten-year viability favors integrated fabricators with captive oxide supply and grain-boundary diffusion licensure. Monitor MIIT quota allocation shifts toward western provinces as the inflection signal for feedstock cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Separation | Captive oxide supply secures MIIT quota allocation rights and insulates margin from spot volatility. |
| Grain-Boundary Diffusion Process Licensing | Technology transfer fees capture value from second-tier sintering houses seeking Dy/Tb reduction compliance. |
| GB/T 13560-2017 Certification Expansion | SAMR enforcement filters uncertified competitors from grid-tender eligibility in Jiangsu wind corridors. |
| Hydrometallurgical Magnet Recovery Scale-Up | MEE circular economy directives mandate recyclability disclosures for preferential industrial equipment scoring. |
| Direct Sales Channel Deepening with Wind OEMs | Bypassing trading houses captures margin through bilaterally contracted smelter-origin certificate provision. |
Research Approach
Independent corroboration across MIIT quota allocation records, SAMR certification registries, and provincial tender documentation underwrites the qualitative findings. Primary interviews with rare-earth separation plant managers, magnet fabrication procurement leads, wind turbine OEM platform engineers, and automotive motor subsystem integrators combined with secondary validation from customs trade data, SEC filings of listed magnet producers, and GB standards committee drafts. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition across product architecture, application torque requirements, and procurement channel structures drives the analytical framework over the projection horizon. Segmentation dimensions modeled include sintered versus bonded product types, automotive versus renewable energy versus electronics applications, and OEM versus Tier-1 versus aftermarket end-user tiers. CAGRs derive from installed base growth in EV traction motors and offshore wind generator procurement schedules, with heavy-rare-earth price volatility and GB standard revision timing as sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for grain-boundary diffusion versus conventional heavy-rare-earth loading would alter the outlook. Forecasts reflect assumptions regarding MIIT quota enforcement consistency and Myanmar import stability. Practitioners should monitor draft GB/T revision committee progress and western China quota allocation shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Platinum Group Metals Market
Metals
Europe Aluminium Powder Market
Metals
Global Brass Rods Market
Metals
Precious Metals Wire Market
Metals
US Metal Fabrication Market
Metals
Galvanizing Market
Metals
Global Chromium Market
Metals
Beryllium Copper Billet Market
Metals
Global Electrolytic Copper Foil Market
Metals
High Carbon Bearing Steel Market
Metals
Neodymium Market
Metals
Industrial Metal Strips Market
Metals
Osmium Market
Metals
Global Brazing Consumable Market
Metals
Cobalt Market
Metals
Prebaked Anodes for Aluminum Market