
 Grain Oriented Electrical Steel Market | 2026-2036
Grain Oriented Electrical Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Oriented Electrical Steel Market Analysis
Modular core assembly is pivoting buyer preference away from monolithic transformer designs toward segmented, repairable configurations. Nippon Steel Corporation leverages proprietary domain-refinement technology to dominate premium high-permeability segments. Baowu Group anchors supply security through captive silicon sourcing and integrated hot-band capacity. Tata Steel Limited competes on specialized coating chemistries that reduce transformer noise and core loss.
Grain oriented electrical steel is a ferrosilicon alloy with oriented crystal structure engineered for minimal hysteresis loss, produced through precise hot rolling, cold reduction, and high-temperature annealing to achieve Goss texture. Its primary purpose is fabrication of laminated transformer cores and rotating machine components where magnetic flux directionality governs efficiency. Silicon steel grades still occupy the largest volume pool across utility procurement, though high permeability steel captures expanding share in ultra-high-voltage transformers where core loss penalties compound at scale. Motors and generators represent mature, price-sensitive application segments with thinner margin profiles than grid-scale transformer deployments.
China's MIIT enforces progressively stricter GB standards on core loss density, compelling domestic mills to upgrade annealing lines or cede share to import-qualified suppliers. India's BIS certification requirements for electrical steel used in government-procured transformers create non-tariff barriers that filter supplier eligibility. The EU F-Gas Regulation indirectly amplifies GOES demand by accelerating transformer replacement cycles to reduce cooling-system greenhouse gas leakage. Stakeholders must monitor how divergent national efficiency benchmarks fragment grade specifications and complicate inventory positioning across multi-jurisdiction supply chains.
Market Dynamics
Transformer core assembly is modularizing as utilities prioritize repairable, field-serviceable designs over monolithic welded constructions, compressing procurement cycles and reshaping grade specifications across utility procurement offices.
Growth Catalysts
- China's GB Standard Upgrades:MIIT-mandated core loss density reductions force domestic mill upgrades and expand import-qualified supplier opportunities for high-permeability grades serving ultra-high-voltage transformer fleets.
- India Grid Modernization:State transmission utilities are procuring high-permeability GOES for new transformer installations as BIS certification requirements filter supplier eligibility toward qualified domestic and import sources.
- EU F-Gas Regulation:Accelerated transformer replacement cycles to reduce cooling-system greenhouse gas leakage indirectly amplify GOES demand across European utility procurement schedules.
Market Restraints
- Silicon Metal Price Volatility:Ferrosilicon alloy input costs fluctuate with energy-intensive smelting operations, compressing mill margins and complicating long-term utility contract pricing.
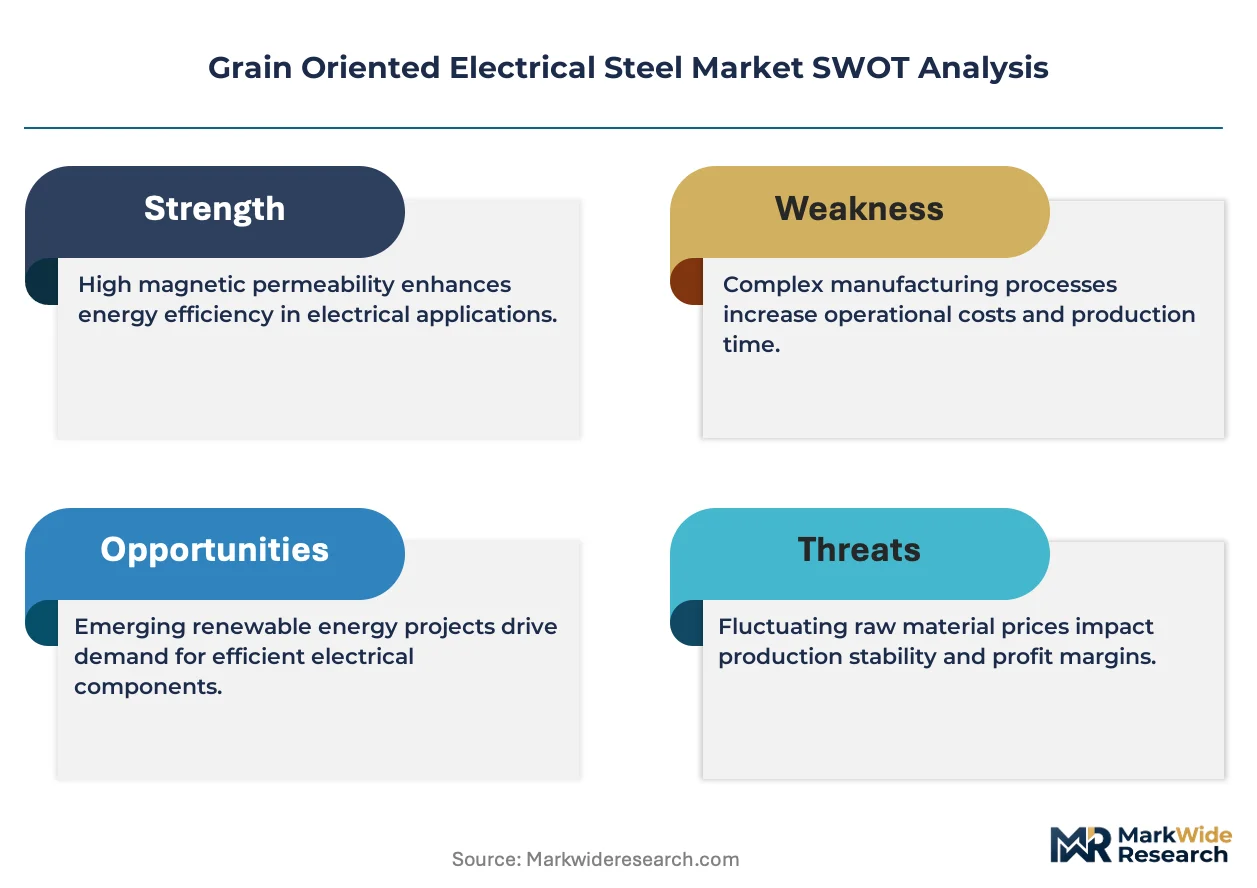
- Annealing Line Bottlenecks:High-temperature annealing capacity concentrates among integrated producers with captive hot-band supply, limiting new entrant participation in premium grade segments.
- Amorphous Metal Substitution:Distribution transformer applications face competitive pressure from amorphous alloy cores offering lower core loss in lower-flux-density operating regimes.
Strategic Opportunities
- Southeast Asia Renewable Interconnection:Vietnam, Thailand, and Indonesia are expanding transmission infrastructure with limited domestic GOES supply, creating import-dependent demand pools for qualified exporters.
- Domain-Refinement Technology Convergence:Laser scribing and plasma irradiation techniques combined with conventional processing enable next-generation high-permeability grades with sub-1.0 W/kg core loss performance.
- Digital Procurement Platforms:Utility-owned e-procurement portals with embedded BIS certification verification are streamlining supplier qualification and compressing tender-to-delivery timelines.
Industry Challenges
- Goss Texture Control Expertise Gap:Precise hot rolling and cold reduction process engineering requires specialized metallurgical talent scarce outside established Japanese and Chinese mill technical centers.
- Multi-Jurisdiction Certification Complexity:Divergent national efficiency benchmarks across China's GB standards, India's BIS requirements, and EU technical specifications fragment inventory positioning and complicate supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Oriented Electrical Steel Market |
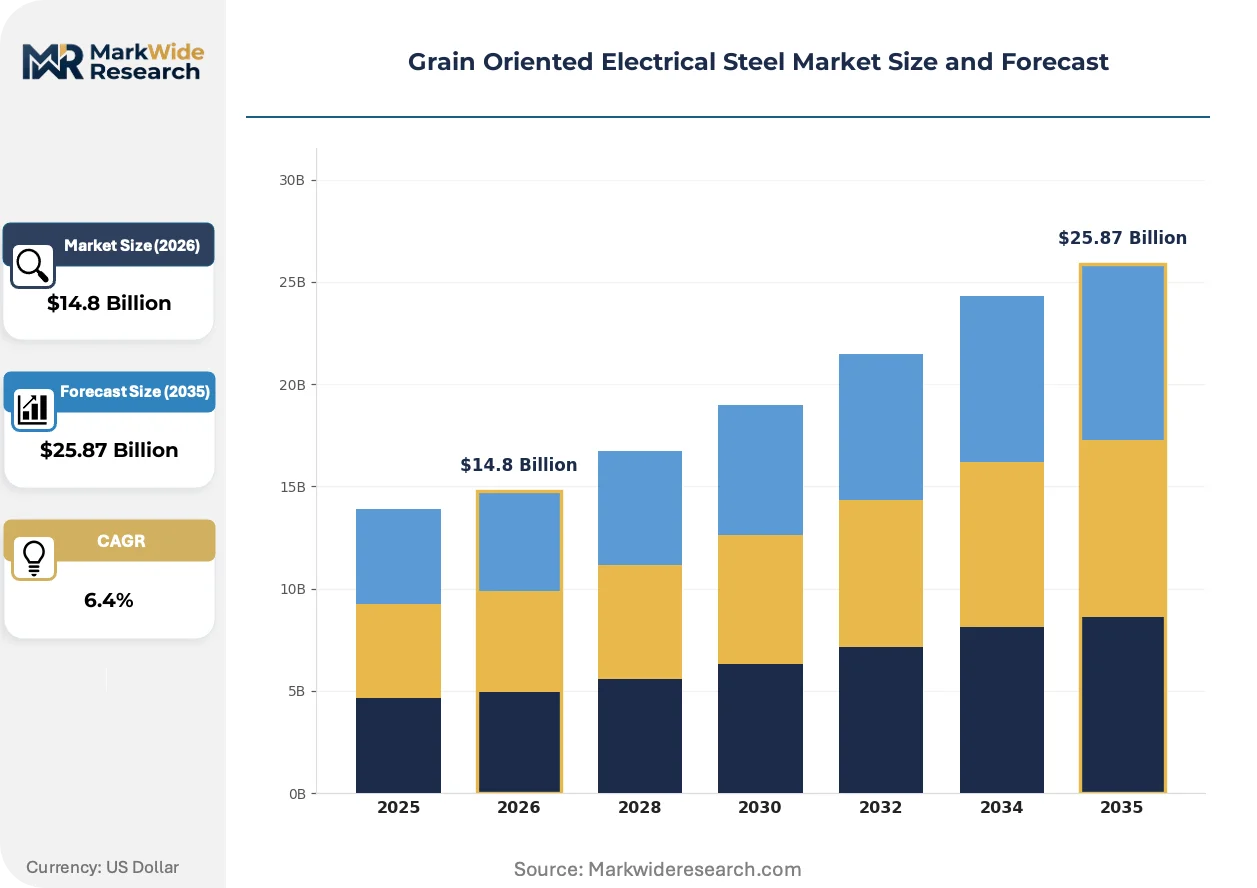
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Steel, Non-Silicon Steel, High Permeability Steel, Others Application: Transformers, Motors, Generators, Inductors End User: Power Utilities, Industrial Equipment, Automotive, Consumer Electronics Grade: Non-Graded, Electric Grade, Special Grade, High Grade |
| Companies Covered | Thyssenkrupp AG, Baowu Group, Nippon Steel Corporation, Tata Steel Limited, United States Steel Corporation, ArcelorMittal, JFE Steel Corporation, NLMK Group, POSCO International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Oriented Electrical Steel Market Emerging Trajectories
Domain-refinement processing and modular core architectures are compressing performance thresholds while regulatory efficiency mandates accelerate grade turnover across transformer procurement specifications.
Thin-gauge high-permeability steel with laser-scribed domain refinement is modularizing transformer core design, enabling segmented assembly that utilities now specify for repairability. State grid operators in India and China are adopting these grades for new ultra-high-voltage installations. The technology is modularizing procurement specifications away from thickness-based grades toward performance-tiered loss categories.
China's MIIT enforcement of progressively stricter GB standards on core loss density is compelling domestic mills to upgrade annealing lines or cede share to import-qualified suppliers. Industrial consequence includes accelerated capital deployment toward high-temperature processing equipment. High-permeability grade production is most affected, with domestic producers responding through joint ventures with Japanese technical licensors.
Utility procurement offices are consolidating supplier panels around certified mills with demonstrated coating chemistry consistency for noise reduction. Direct mill relationships are displacing distributor-mediated sourcing for large transformer OEMs. This concentration is most visible in India's state transmission utility tenders, where BIS-certified domestic supply is preferred despite import price competitiveness.
Grain Oriented Electrical Steel Market Segmentation
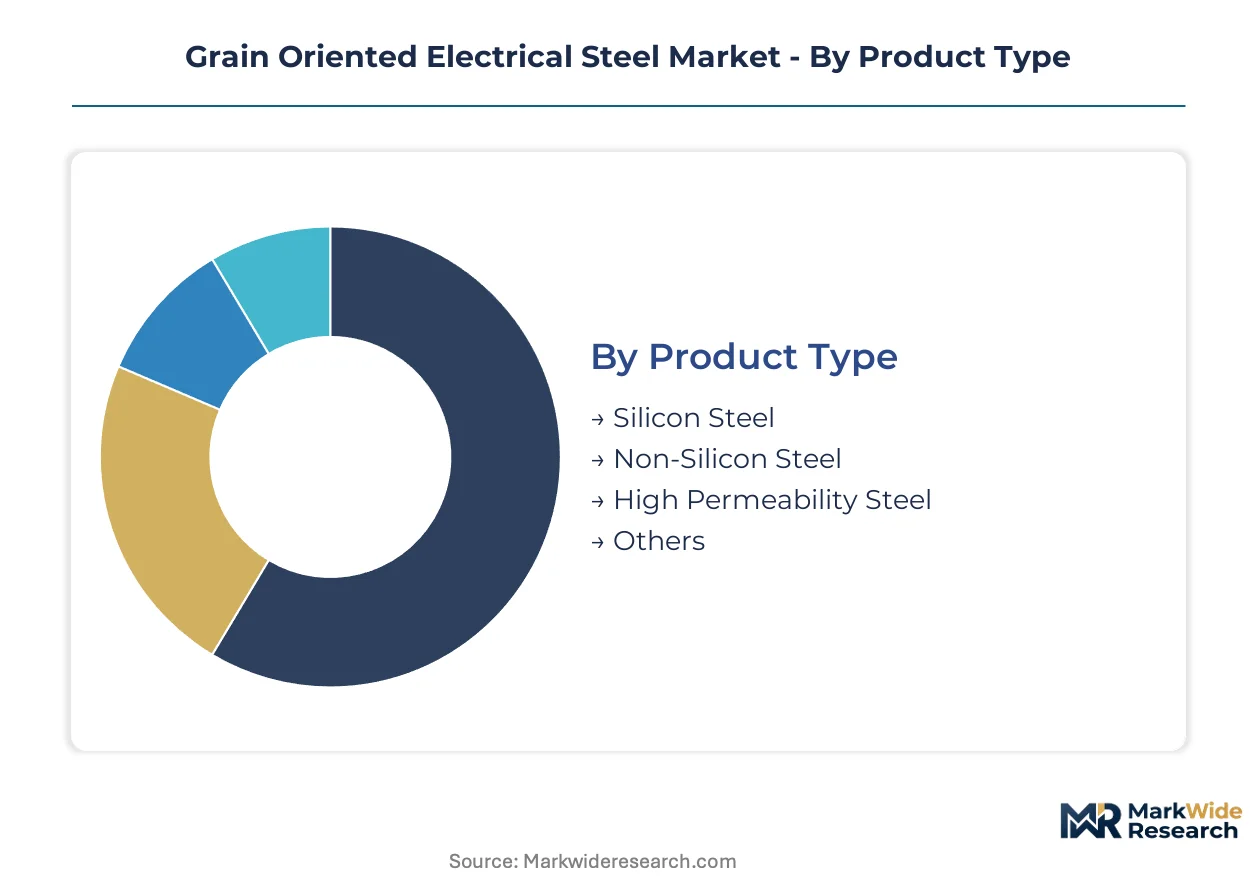
Grain oriented electrical steel procurement splits across technical performance tiers, equipment categories, and customer sophistication levels. Each segmentation axis reveals distinct margin structures, certification requirements, and supply chain access patterns that shape supplier strategy.
Product Type:
Buyers differentiate by core loss tolerance, permeability requirements, and annealing sophistication rather than commodity pricing alone.
- Silicon Steel:Ferrosilicon alloy with oriented Goss texture engineered through precise hot rolling and high-temperature annealing. Volume concentrates in China's state grid transformer procurement where GB standard compliance filters supplier pools toward integrated mills with captive hot-band capacity.
- High Permeability Steel:Domain-refined grades with laser scribing or plasma irradiation achieving sub-1.0 W/kg core loss performance. India's state transmission utilities specify these for ultra-high-voltage installations as BIS certification requirements tighten efficiency benchmarks.
- Non-Silicon Steel:Lower-silicon alternatives for cost-sensitive rotating machine applications.
- Others:Emerging alloy formulations and experimental coating chemistries for specialized magnetic applications.
Volume sits with Silicon Steel; growth tilts toward High Permeability Steel.
Application:
Equipment type dictates thickness specifications, core assembly geometry, and repairability requirements in utility procurement.
- Transformers:Laminated core assemblies for grid-scale power conversion and distribution. India's grid modernization programs and China's ultra-high-voltage expansion anchor demand for modular, field-serviceable core designs specified by state operators.
- Motors:Rotating machinery components where magnetic flux directionality governs efficiency. Industrial equipment OEMs in Southeast Asia procure standardized grades for manufacturing and process automation systems.
- Generators:Mature, price-sensitive segment with thinner margins than transformer deployments.
- Inductors:Specialized wound components for power electronics and filtering applications.
Procurement scale favors Transformers; margin expansion concentrates in Motors for premium efficiency tiers.
End User:
Customer sophistication determines certification complexity, contract duration, and technical service expectations.
- Power Utilities:State transmission operators with multi-year procurement cycles and embedded BIS or GB certification verification. India's CEA-mandated efficiency upgrades and China's MIIT enforcement of core loss density standards reshape tender specifications toward high-permeability grades.
- Industrial Equipment:Manufacturing and process automation OEMs with standardized grade requirements and distributor-mediated sourcing patterns.
- Automotive:Electric traction motor applications with emerging thin-gauge specifications for power density.
- Consumer Electronics:Small-core inductor and transformer applications with price-sensitive, high-volume procurement.
Contract stability clusters with Power Utilities; volume velocity concentrates in Industrial Equipment.
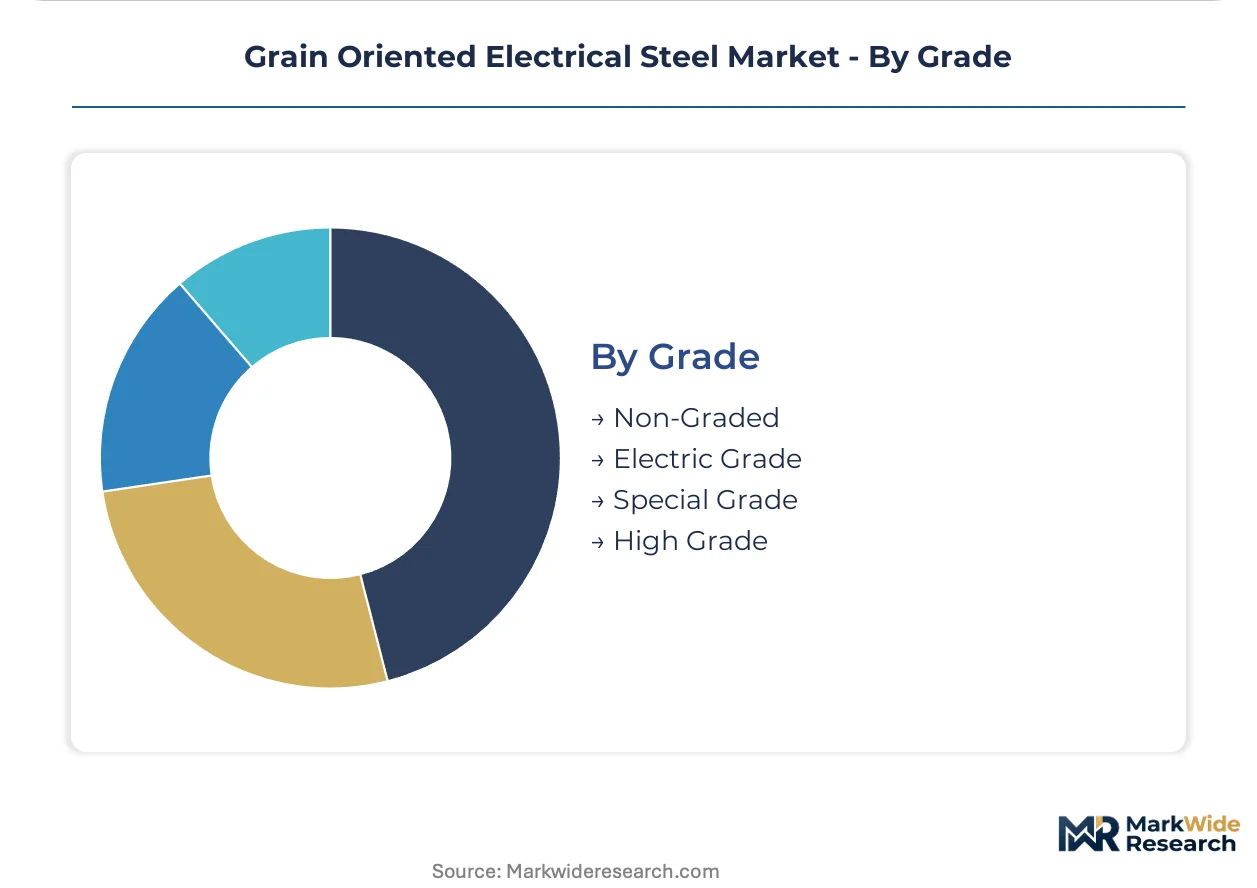
Grade:
Performance tiering separates commodity procurement from premium segments requiring metallurgical process control expertise.
- High Grade:Thinnest gauges with tightest Goss texture control for ultra-low core loss in ultra-high-voltage transformers. China's domestic mills upgrade annealing lines or partner with Japanese technical licensors to meet MIIT-mandated GB standard upgrades.
- Special Grade:Domain-refined variants with noise-reduction coating chemistries specified by European utilities under EU F-Gas Regulation accelerated replacement cycles.
- Electric Grade:Mid-tier specifications for standard distribution transformers and industrial motors.
- Non-Graded:Unclassified material for non-critical applications with minimal magnetic performance requirements.
Technical capability concentrates in High Grade; price competition dominates Non-Graded.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asian integrated mills while consumption surges across South Asian and Southeast Asian transmission buildouts. This geographic mismatch creates trade flow dependencies and certification complexity for exporters.
China
MIIT enforcement of progressively stricter GB standards on core loss density compels domestic mills to upgrade annealing lines or cede share to import-qualified suppliers. Baowu Group anchors supply security through captive silicon sourcing and integrated hot-band capacity in Shanghai and Wuhan. Yangtze River Delta transformer OEMs source preferentially from domestic mills meeting updated efficiency benchmarks.
India
State transmission utilities are procuring high-permeability GOES for new transformer installations as BIS certification requirements filter supplier eligibility. CEA-mandated efficiency upgrades reshape tender specifications toward domain-refined grades. Maharashtra and Gujarat host the densest clusters of transformer fabrication facilities serving Power Grid Corporation of India procurement cycles.
Japan
Nippon Steel Corporation leverages proprietary domain-refinement technology to dominate premium high-permeability segments serving ultra-high-voltage transformer fleets. METI-aligned technical standards influence regional procurement specifications across Northeast Asia. Chubu and Kansai industrial corridors concentrate specialized coating chemistry expertise for noise-reduction applications.
South Korea
POSCO International Corporation occupies a position within the integrated producer tier, drawing on captive raw material access and continuous annealing line investments. Domestic transformer OEMs supply Southeast Asian renewable interconnection projects. Busan-Ulsan industrial complex hosts downstream lamination and core assembly operations for regional export.
Germany
EU F-Gas Regulation accelerates transformer replacement cycles to reduce cooling-system greenhouse gas leakage, indirectly amplifying GOES demand across European utility procurement schedules. Thyssenkrupp AG and ArcelorMittal serve continental distribution transformer and industrial motor segments. Ruhr industrial basin maintains legacy rolling capacity though premium grades increasingly source from East Asian technical licensors.
Grain Oriented Electrical Steel Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered performance segments. Integrated producers with captive hot-band supply control premium high-permeability grade output while merchant processors serve standardized distribution transformer demand. Three archetypes dominate: Japanese technical licensors with domain-refinement IP, Chinese state-linked mills with backward-integrated silicon supply, and European legacy producers with coating chemistry specialization. Competitive moves concentrate on annealing line upgrades and BIS/GB certification qualification rather than greenfield capacity.
Within the integrated producer tier, Baowu Group and Nippon Steel Corporation exemplify divergent strategic positions. Baowu anchors supply security through captive silicon sourcing and domestic GB standard compliance. Nippon Steel occupies the premium-tier vector through proprietary laser-scribing and plasma irradiation techniques. Tata Steel Limited represents the specialized coating chemistry archetype, competing on noise-reduction formulations for utility-specified transformer cores.
| Leading Market Players |
|---|
| Thyssenkrupp AG |
| Baowu Group |
| Nippon Steel Corporation |
| Tata Steel Limited |
| United States Steel Corporation |
| ArcelorMittal |
| JFE Steel Corporation |
| NLMK Group |
| POSCO International Corporation |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between domain-refined high-permeability steel and commodity silicon steel manifests in contract pricing tied to GB standard tiers and annealing line access. Procurement officers at China's state grid utilities pay premiums for MIIT-certified low-loss grades while Indian BIS compliance filters supplier pools toward certified domestic mills.
Pricing Analysis
Margin tightening in high-permeability grades reflects ferrosilicon alloy input volatility and energy-intensive annealing costs. Contract-based long-term offtake dominates utility procurement, with price differentiation driven by certification level (BIS/GB tier) and volume scale. Cost compression runs through standard silicon steel as merchant processors compete on spot pricing. Industrial equipment OEMs exhibit highest price sensitivity; ultra-high-voltage transformer operators show lowest.
Supply Chain Analysis
Specialized metallurgical talent scarcity in Japan's Chubu corridor and China's Yangtze River Delta constrains Goss texture process engineering capacity. Supply concentrates in China, Japan, and South Korea, drawing from captive silicon metal, hot-band substrate, and coating chemistry inputs. Single-source vulnerability concentrates in high-temperature annealing equipment. Distribution runs through direct mill relationships displacing distributor channels for large transformer OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where India's BIS certification requirements and China's MIIT-mandated GB standard upgrades erect barrier-to-entry moats favoring certified integrated producers.
For Market Incumbents: Deploy annealing line upgrades as the primary defensive lever against Japanese technical licensors encroaching on premium segments. Consolidate coating chemistry expertise for noise-reduction specifications specified under EU F-Gas Regulation replacement cycles. Capture backward integration into captive silicon sourcing to buffer ferrosilicon price volatility. For New Entrants and Emerging Players: The mid-tier price-point gap between Nippon Steel's premium domain-refined grades and commodity silicon steel offers white-space entry. Southeast Asia's renewable interconnection buildout in Vietnam and Indonesia presents the most penetrable geography. Pursue joint venture structures with established technical licensors to bypass Goss texture control expertise gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of BIS-certified domestic mills serving India's CEA-mandated grid modernization. Long-term viability favors integrated producers with captive hot-band capacity across the next decade. Monitor amorphous metal substitution rates in distribution transformer applications as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Annealing Line Upgrade | MIIT-mandated GB standard compliance forces capital deployment toward high-temperature processing equipment. |
| Joint Venture with Technical Licensor | Chinese domestic mills partner with Japanese domain-refinement IP holders to access premium grade production. |
| BIS Certification Investment | India's state transmission utilities filter supplier eligibility toward certified domestic and import sources. |
| Backward Integration into Silicon Sourcing | Baowu Group anchors supply security through captive ferrosilicon alloy input control. |
| Specialized Coating Chemistry Development | Tata Steel competes on noise-reduction formulations for utility-specified transformer core procurement. |
Methodological Framework
Document review covered customs trade data, MIIT regulatory filings, and BIS certification registers, complemented by interviews with transformer OEM procurement directors, state utility planning officers, steel mill technical directors, and coating chemistry R&D leads. Secondary validation drew from SEC 10-K filings, industry association capacity reports, and transformer installation databases. Bottom-up grade-volume estimates triangulated against top-down regional demand aggregation.
Historical capacity utilization patterns cross-referenced against panel input from annealing line operators and silicon metal suppliers informed the analytical framework. Segmentation dimensions modeled include product type (silicon steel, high-permeability steel), application (transformers, motors, generators), and end user (power utilities, industrial equipment). CAGRs derived from regression analysis against installed transformer base expansion and efficiency upgrade cycles. Forecast inputs incorporated renewable interconnection project pipelines and F-Gas Regulation replacement schedules.
Inputs from BIS certification databases and GB standard enforcement records were available through the study window; gaps in real-time annealing line capacity utilization introduce uncertainty bands around high-permeability grade supply projections. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and silicon metal price trajectories. Material deviation in amorphous metal substitution rates or MIIT standard acceleration timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Scandium Market
Metals
Global Copper Cathode Market
Metals
Electrolytic Iron Market
Metals
Platinum Group Metals Market
Metals
Aluminum Scrap Recycling Market
Metals
Palladium Market
Metals
Base Metals Market
Metals
Aluminum Extrusion Market
Metals
Industrial Metal Strips Market
Metals
Heat-Treated Steel Plates Market
Metals
India Steel Market
Metals
Tinplate Market
Metals
Chrome Metal Powder Market
Metals
Stainless Steel Sheet Market
Metals
Rhodium Market
Metals
North America Aluminum Market