
 Prebaked Anodes for Aluminum Market | 2026-2036
Prebaked Anodes for Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
Prebaked Anodes for Aluminum Market Insights
Petroleum coke calciner expertise is unwinding across the prebaked anode supply base as experienced kiln operators retire faster than apprenticeship pipelines refill. Chalco leverages captive green coke supplies and in-house calcination to insulate margin structures from feedstock volatility. Rio Tinto anchors its Atlantic smelting network with long-term anode offtake tied to low-carbon aluminum certification schemes. RUSAL competes through Siberian hydro-powered smelters that demand high-performance anodes engineered for extreme cold-climate electrolysis stability.
Prebaked anodes are carbonaceous consumable electrodes manufactured from calcined petroleum coke, coal tar pitch binder, and recycled butts, then baked to 1,100–1,200°C to achieve electrical resistivity below 55 μΩ·m and compressive strength exceeding 35 MPa for Hall-Héroult cell insertion. Their primary purpose is to conduct direct current into molten cryolite-alumina baths while sacrificially oxidizing to maintain cell chemistry equilibrium. Carbon Blocks dominate product-type value pools due to standardized dimensional compatibility with existing potline infrastructure, though Composite Anodes are capturing R&D investment as smelters pursue extended cell life and reduced net carbon consumption. Shaft Type technology leads installation volumes in greenfield Middle Eastern smelters, while High-Density formulations command premium positioning in European installations governed by tight particulate emission thresholds.
China's MEE enforces GB standards on industrial carbon emissions that disqualify conventional anode formulations from new smelter licensing, while the EU Green Deal's carbon border adjustments redirect trade flows toward verified low-carbon anode suppliers. REACH and RoHS frameworks in Europe constrain coal tar pitch additive chemistries, compelling reformulation investments across export-oriented manufacturers. Stakeholders must monitor divergence between China's dual carbon enforcement timelines and European CBAM phase-in schedules, as misalignment risks strand conventional capacity or prematurely obsolete compliant assets.
Market Dynamics
China's dual carbon goals and GB standards on industrial emissions are compressing legacy anode capacity while redirecting procurement toward higher-density formulations that satisfy tightening environmental licensing thresholds.
Growth Catalysts
- MEE emission enforcement:China's Ministry of Ecology and Environment disqualifies conventional anode formulations from new smelter licensing, forcing retrofits and premium product substitution across Shandong and Henan corridors.
- Hall-Héroult cell expansion:Greenfield Middle Eastern smelters deploying Shaft Type anode technology generate incremental demand for standardized carbon block configurations compatible with automated potline insertion systems.
- Coal tar pitch chemistry advancement:Reformulated binder systems achieving lower softening points and improved coking values enable denser anode structures that reduce net carbon consumption per tonne of aluminum output.
Market Restraints
- Petroleum coke supply concentration:High-sulfur green coke availability concentrates in specific refinery configurations, leaving calciners exposed to fuel-grade coke price arbitrage and marine freight volatility.
- REACH additive constraints:ECHA restrictions on polycyclic aromatic hydrocarbon content in coal tar pitch imports compel European smelters to source reformulated binders at structural cost premiums.
- Kiln operator attrition:Experienced calciner technicians retire faster than apprenticeship pipelines refill, constraining capacity utilization rates and quality consistency across independent supply bases.
Strategic Opportunities
- Odisha smelter cluster expansion:India's National Aluminium Company and Vedanta Limited capacity additions create captive anode demand exceeding domestic supply, opening import substitution windows for compliant exporters.
- EU Green Deal CBAM alignment:Carbon border adjustment mechanisms reward verified low-carbon anode suppliers with preferential market access, incentivizing hydro-powered smelter integration in Norway and Iceland.
- Composite anode R&D convergence:Silicon carbide and titanium diboride additive research programs target extended cell life and reduced anode change frequency, promising lifecycle cost advantages for high-amperage potlines.
Industry Challenges
- Calcination energy intensity:Rotary kiln and shaft calciner operations require sustained natural gas or petroleum coke fuel inputs, exposing margin structures to commodity price spikes and carbon pricing mechanisms.
- Butt recycling contamination control:Recycled anode residue processing demands precise metal and sulfur separation to prevent bath chemistry disruption, complicating closed-loop material flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prebaked Anodes for Aluminum Market |
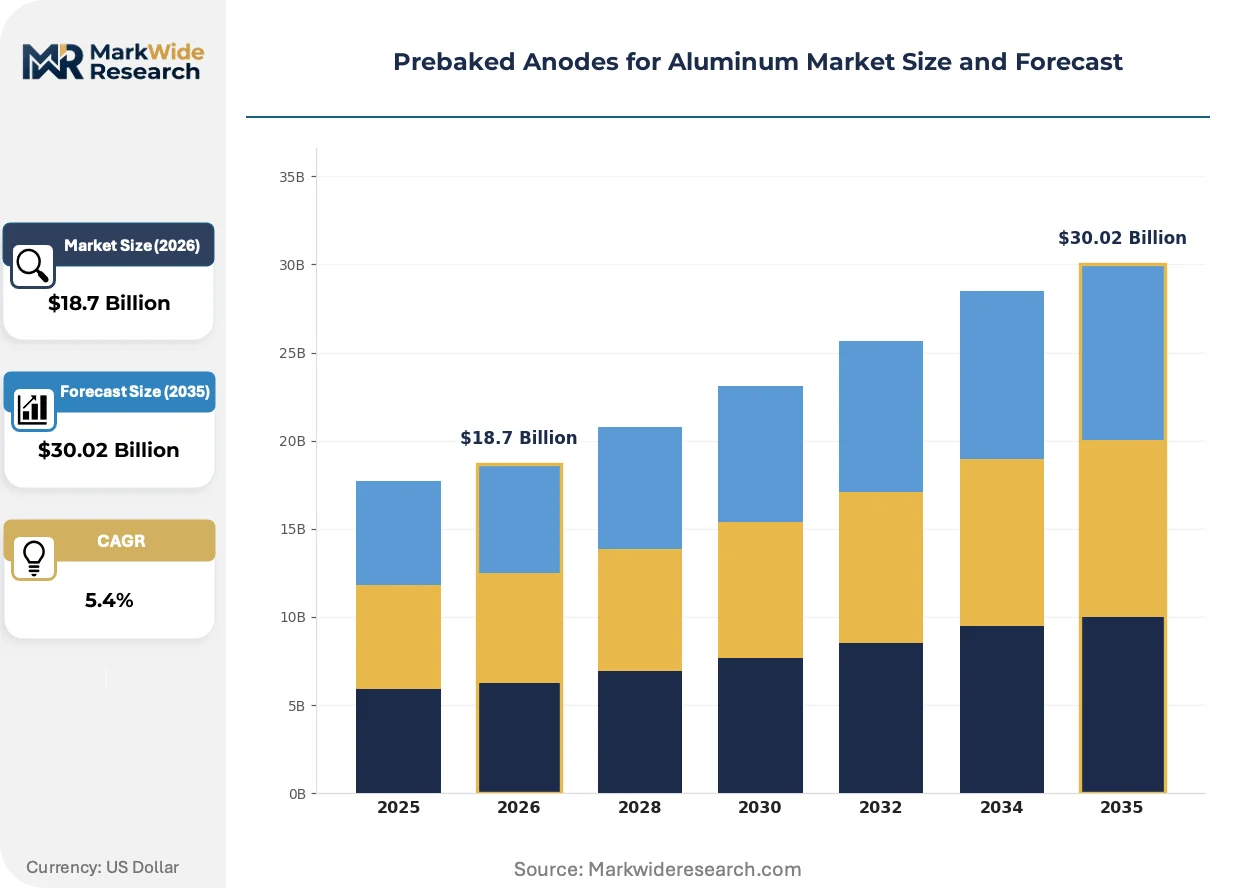
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Blocks, Graphitized Rods, Composite Anodes, Paste Anodes, Carbon Plates Technology: Shaft Type, Block Type, Carbon Paste, Preformed, High-Density Application: Primary Smelting, Secondary Refining, Electrolysis Process, Metal Recovery, Alloy Production End User: Mineral Processing Plants, Metal Fabricators, Electroplating Units, Smelting Facilities |
| Companies Covered | Chalco, Rio Tinto, RUSAL, Alcoa Corporation, Rain CII Carbon, Aluchemie, Emirates Global Aluminium, Norsk Hydro, Carbonorca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prebaked Anodes for Aluminum Market Trends and Innovations
Electrolysis efficiency targets and emission compliance thresholds are fragmenting established anode specifications, creating parallel demand tracks for conventional carbon blocks and next-generation composite formulations.
High-density anode technology is fragmenting procurement patterns across European smelters governed by tight particulate emission thresholds. German and Norwegian operators now specify compressive strength exceeding 40 MPa and electrical resistivity below 50 μΩ·m as baseline requirements. This performance tier commands manufacturing complexity premiums that compress margins for calciners lacking in-house green coke supplies.
EU Green Deal carbon border adjustments are redirecting trade flows toward verified low-carbon anode suppliers. REACH and RoHS frameworks constrain coal tar pitch additive chemistries, compelling reformulation investments across export-oriented manufacturers. Smelters in Iceland and Norway leverage hydro-powered certification schemes to secure premium positioning in continental procurement tenders.
Buyer concentration among integrated aluminum majors is compressing spot market liquidity and elongating contract durations. Chalco and Rio Tinto anchor procurement through multi-year offtake agreements tied to low-carbon aluminum certification schemes. This contractual shift is most visible in Atlantic basin trade corridors where smelters prioritize supply security over price discovery.
Prebaked Anodes for Aluminum Market Segmentation
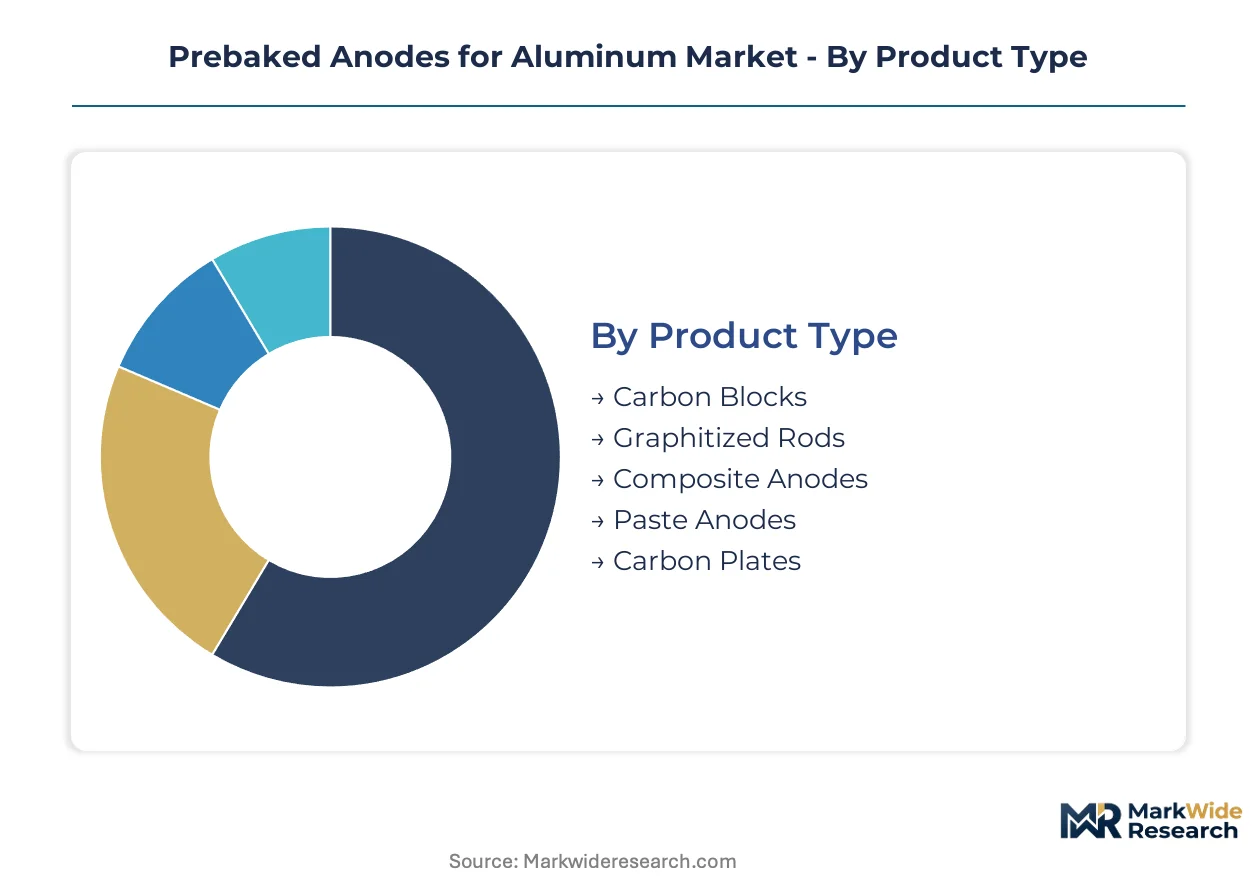
Prebaked anode procurement patterns diverge sharply across product formulations and installation technologies. Smelter operators select specifications based on amperage load, emission compliance thresholds, and potline automation levels rather than commodity pricing alone.
Product Type:
Carbon Blocks anchor domestic procurement across Chinese and Indian smelter corridors, while Graphitized Rods and Composite Anodes concentrate in export-driven supply to European and Middle Eastern buyers.
- Carbon Blocks:Manufactured from calcined petroleum coke and coal tar pitch binder, these standardized rectangular electrodes achieve electrical resistivity below 55 μΩ·m. Demand concentrates in Shandong and Henan province smelters where GB standards on industrial emissions disqualify lower-density alternatives. Chalco and Rio Tinto specify these for automated potline insertion systems.
- Composite Anodes:Silicon carbide and titanium diboride additives extend cell life and reduce net carbon consumption per tonne of aluminum output. Norwegian and Icelandic smelters leveraging hydro-powered certification schemes drive premium procurement for high-amperage operations governed by EU Green Deal thresholds.
- Graphitized Rods:High-purity formulations for specialty electrolysis applications requiring enhanced thermal conductivity.
- Paste Anodes:Soderberg-derived formulations retained in legacy Russian and Eastern European installations.
- Carbon Plates:Dimensional variants for non-standard cell geometries in boutique alloy production.
Carbon Blocks command the established base. The steepest expansion runs through Composite Anodes.
Technology:
Shaft Type and High-Density formulations concentrate margin premiums in export markets, while Block Type and Carbon Paste technologies dominate cost-sensitive domestic procurement.
- Shaft Type:Vertical anode configurations designed for greenfield Middle Eastern smelters with automated rodding and stubbing systems. Emirates Global Aluminium and Ma'aden specify these for new 500+ kA potlines where reduced labor exposure and faster anode change cycles offset capital intensity.
- High-Density:Compressive strength exceeding 40 MPa and electrical resistivity below 50 μΩ·m satisfy German and Norwegian emission thresholds. REACH constraints on coal tar pitch additives compel reformulated binder systems that raise manufacturing complexity premiums.
- Block Type:Conventional horizontal configurations for legacy potline retrofits.
- Carbon Paste:Continuous electrode replacement systems in Russian Siberian smelters.
- Preformed:Precision-machined stubs for rapid installation in high-amperage cells.
Block Type retains volume leadership. High-Density climbs the fastest on emission compliance premiums.
Application:
Primary Smelting and Electrolysis Process applications concentrate in integrated aluminum majors, while Secondary Refining and Metal Recovery fragment across independent processors.
- Primary Smelting:Hall-Héroult cell operations consuming 400-500 kg of anode per tonne of aluminum produced. Odisha cluster expansions by National Aluminium Company and Vedanta Limited create captive demand exceeding domestic Indian supply, opening import substitution windows for compliant exporters.
- Electrolysis Process:Direct current conduction into molten cryolite-alumina baths at 950-980°C. MEE enforcement of GB standards across new Chinese smelter licensing compresses legacy formulation demand toward higher-density substitutes.
- Secondary Refining:Remelt and alloying operations with lower purity tolerance.
- Metal Recovery:Slag reprocessing and dross treatment applications.
- Alloy Production:Silicon and magnesium alloying cells requiring modified thermal profiles.
Primary Smelting anchors procurement volumes. Electrolysis Process specifications gain share fastest on efficiency targets.
End User:
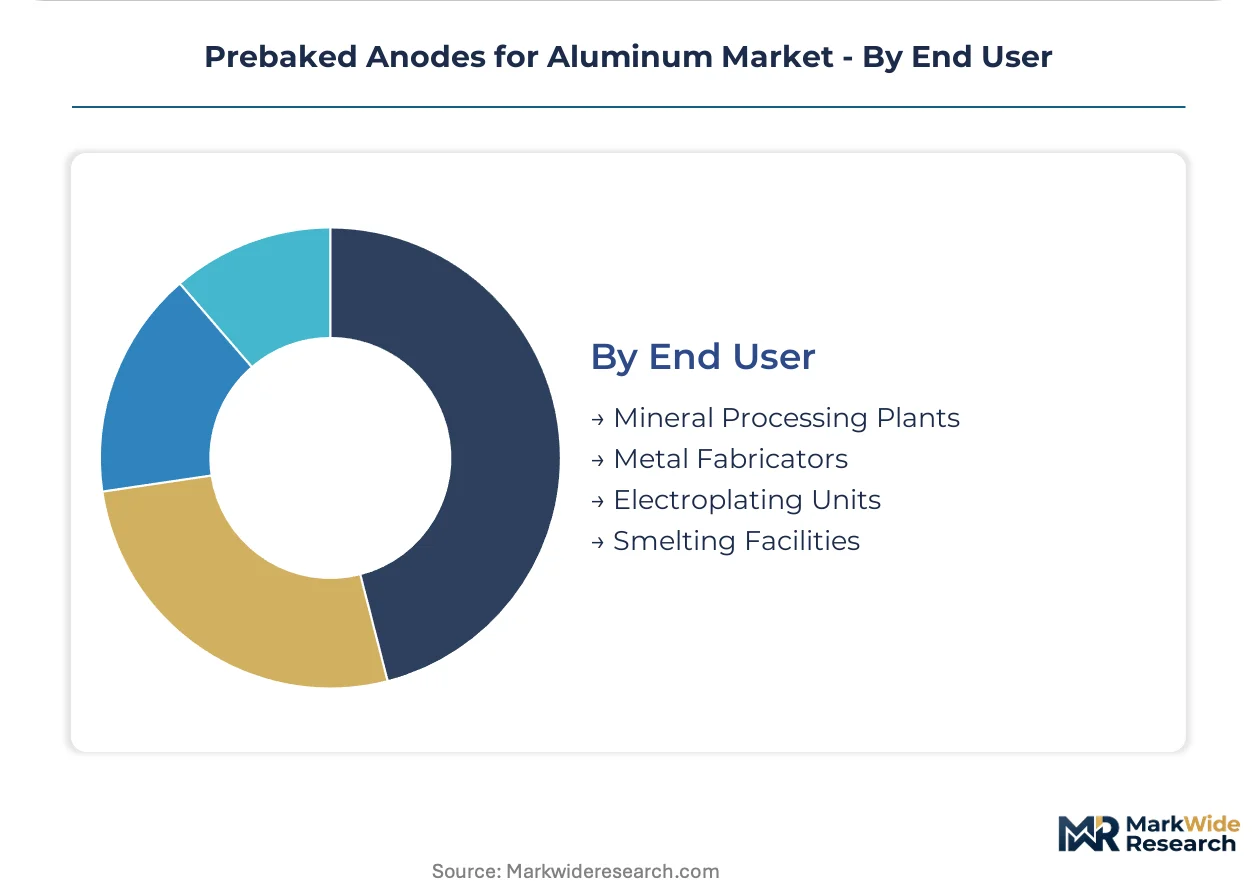
Smelting Facilities and Mineral Processing Plants drive volume concentration, while Metal Fabricators and Electroplating Units fragment across specialty grade requirements.
- Smelting Facilities:Integrated aluminum producers operating 200+ cell potlines with annual capacity exceeding 200,000 tonnes. Rio Tinto's Atlantic network and Chalco's captive supply chains anchor multi-year offtake agreements tied to low-carbon certification schemes.
- Mineral Processing Plants:Alumina-to-aluminum conversion sites with integrated carbon plants. RUSAL's Siberian hydro-powered operations demand high-performance anodes engineered for extreme cold-climate electrolysis stability.
- Metal Fabricators:Secondary remelt and casting operations with spot market purchasing.
- Electroplating Units:Specialty anode requirements for surface treatment applications.
Smelting Facilities command the established base. The steepest expansion runs through Mineral Processing Plants on captive integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement of GB standards on industrial carbon emissions is compressing legacy anode capacity across China's Shandong and Henan corridors while redirecting procurement toward higher-density formulations. This regulatory pressure cascades through supply chains in India, the Middle East, and Europe as smelters recalibrate procurement specifications.
China
Shandong and Henan province smelters consume the majority of domestic carbon block output as MEE licensing rules disqualify conventional formulations from new potline approvals. The Ministry of Ecology and Environment compresses legacy capacity through emission intensity thresholds that favor captive calcination and in-house green coke supplies. Zhengzhou and Jinan industrial clusters anchor reformulation investment toward compressive strength exceeding 40 MPa specifications.
India
National Aluminium Company and Vedanta Limited expansions in Odisha generate captive anode demand exceeding domestic supply, opening import substitution windows for compliant exporters. Central Electricity Authority grid reliability programs support smelter corridor electrification that stabilizes Hall-Héroult cell amperage loads. The Angul-Jharsuguda belt concentrates greenfield capacity where procurement specifications increasingly mirror Chinese MEE-aligned density thresholds.
United Arab Emirates
Emirates Global Aluminium and Ma'aden greenfield smelters deploy Shaft Type anode technology in 500+ kA potlines where automated rodding systems reduce labor exposure. The country's national industrial regulator enforces emission benchmarks that align with EU Green Deal anticipation, favoring suppliers with verified low-carbon certification. Jebel Ali and Khalifa Industrial Zones concentrate carbon plant investment tied to long-term aluminum offtake agreements.
Norway
Norsk Hydro anchors Atlantic basin procurement through hydro-powered smelter certification schemes that reward verified low-carbon anode suppliers with preferential tender positioning. REACH constraints on coalyclic aromatic hydrocarbon content in coal tar pitch imports compel reformulated binder sourcing at structural cost premiums. The Sunndal and Årdal industrial corridors specify electrical resistivity below 50 μΩ·m as baseline requirements for high-amperage operations.
Germany
German smelters governed by tight particulate emission thresholds now specify compressive strength exceeding 40 MPa and electrical resistivity below 50 μΩ·m as non-negotiable procurement criteria. ECHA restrictions on coal tar pitch additive chemistries force reformulation investments across export-oriented manufacturers supplying the Rhine-Ruhr aluminum corridor. The Voerde and Essen industrial clusters compress spot market liquidity through multi-year offtake agreements tied to low-carbon aluminum certification schemes.
Prebaked Anodes for Aluminum Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across calcination expertise and geographic proximity to smelter demand. The upper tier consolidates around captive petroleum coke supplies and in-house carbon plant operations that insulate margin structures from feedstock volatility. Three archetypes dominate: integrated aluminum majors with backward control over anode production, independent carbon specialists with kiln operator expertise, and state-affiliated entities leveraging domestic coke reserves. Competitive moves concentrate on long-term offtake anchoring and emission-compliant capacity expansion.
Among integrated aluminum majors, Chalco exemplifies the captive supply archetype through green coke access and in-house calcination that shields operations from marine freight volatility. Rio Tinto occupies a position within the Atlantic certification tier where hydro-powered smelter integration secures preferential procurement positioning under EU Green Deal frameworks. RUSAL represents the cold-climate specialization vector with Siberian operations engineered for extreme electrolysis stability. These three entities anchor the competitive structure through multi-year contractual anchoring that compresses spot market liquidity across their respective supply corridors.
| Leading Market Players |
|---|
| Chalco |
| Rio Tinto |
| RUSAL |
| Alcoa Corporation |
| Rain CII Carbon |
| Aluchemie |
| Emirates Global Aluminium |
| Norsk Hydro |
| Carbonorca |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements spanning five-to-ten year horizons lock in supply access for integrated aluminum majors while stripping price discovery from spot markets across Shandong and Henan corridors. These contractual structures tether anode procurement to low-carbon certification premiums and GB standard compliance thresholds, compressing margin visibility for independent calciners lacking captive green coke supplies.
Pricing Analysis
Price spreads between European high-density formulations and Chinese carbon blocks reflect REACH additive reformulation costs and hydro-powered certification premiums. Three-tier pricing structure across premium composite anodes, standard high-density blocks, and economy carbon paste configurations stratifies procurement tiers. Pricing pressure stems from petroleum coke calciner margin compression as experienced kiln operators retire faster than apprenticeship pipelines refill. Smelting facilities with integrated carbon plants exhibit lowest price sensitivity; independent spot-market buyers face greatest exposure to fuel-grade coke arbitrage volatility.
Supply Chain Analysis
China and the United States anchor green petroleum coke production, with Indian calciners drawing from Middle Eastern refinery outputs to serve Odisha smelter expansion. Calcined petroleum coke, coal tar pitch binder, and recycled butts constitute the three critical input streams. Single-source vulnerability concentrates in high-sulfur green coke availability from specific refinery configurations. Distribution runs through captive carbon plants at integrated aluminum majors, with residual spot market liquidity fragmenting across independent specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery anchored to Hall-Héroult cell expansion across Middle Eastern greenfield smelters, where automated potline investment is restarting demand visibility after emission-driven compression in Chinese corridors.
For Market Incumbents: Compound defensive positioning through backward integration into captive green coke supplies and in-house calcination capacity that insulates margin structures from petroleum coke price arbitrage. Prioritize MEE-aligned reformulation investment toward compressive strength exceeding 40 MPa specifications to defend licensing eligibility as GB standards tighten. Channel control through multi-year offtake anchoring with Rio Tinto and Chalco procurement networks compresses spot market liquidity for emerging competitors. For New Entrants and Emerging Players: Anchor in Odisha smelter cluster expansion where National Aluminium Company and Vedanta Limited capacity additions exceed domestic Indian anode supply, creating import substitution windows for compliant exporters. Target white-space in composite anode R&D convergence where silicon carbide additive programs promise lifecycle cost advantages for high-amperage potlines. Go-to-market angle: hydro-powered certification alignment with EU Green Deal CBAM anticipation to secure preferential tender positioning in Atlantic basin procurement. For Investors and Strategic Acquirers: Independent carbon specialists with kiln operator expertise and geographic proximity to Middle Eastern greenfield demand represent the most defensible acquisition archetype for five-to-ten year holding periods. Long-term viability hinges on calcination energy intensity management as natural gas price volatility and carbon pricing mechanisms reshape margin structures. Signal to watch: divergence between China's dual carbon enforcement timelines and European CBAM phase-in schedules as inflection indicator for stranded conventional capacity risk.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Green Coke Integration | Chalco's in-house calcination shields margins from marine freight volatility across Pacific corridors. |
| High-Density Formulation Certification | REACH-compliant binder systems unlock German and Norwegian smelter procurement at structural premiums. |
| Odisha Supply Base Establishment | Vedanta Limited expansion creates captive demand exceeding domestic Indian anode production capacity. |
| Composite Anode R&D Partnership | Silicon carbide additive programs target extended cell life for Emirates Global Aluminium 500+ kA potlines. |
| Hydro-Powered Certification Alignment | Norsk Hydro's Atlantic procurement tenders reward verified low-carbon anode suppliers with preferential access. |
Research Methodology
The analysis maps carbon block, composite anode, and graphitized rod sub-sectors, each validated through primary interviews with carbon plant managers, smelter procurement leads, petroleum coke supply specialists, and kiln operations technicians. Secondary validation draws from customs trade data, SEC filings by integrated aluminum majors, Chinese MEE emission enforcement records, and EU ETS carbon price benchmarks. Bottom-up capacity modeling triangulates against top-down aluminum production forecasts across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs through cross-referencing with Hall-Héroult cell expansion databases and anode consumption coefficients per tonne of aluminum output. The analytical framework models product type, technology tier, application intensity, and end-user integration level across the projection horizon. CAGRs derive from regression analysis of historical capacity utilization against amperage load trends and emission compliance investment cycles.
Material uncertainties — petroleum coke price volatility, kiln operator attrition rates, and misalignment between Chinese dual carbon timelines and European CBAM schedules — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and greenfield smelter commissioning cadence. Recalibration cycles align with material shifts in MEE licensing thresholds and EU Green Deal implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Recycling Market
Metals
Aluminum Welding Wires Market
Metals
Lightweight Aluminium Pistons Market
Metals
HSLA Steel Plate Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Clutch Spring Wires Market
Metals
Niobium Market
Metals
Russia Metal Fabrication Market
Metals
Steel Wire Market
Metals
Nickel Foam Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Molybdenum Market
Metals
High Purity Tungsten Market
Metals
Zinc Plating Market
Metals
Global Oxygen-Free Copper Market
Metals
Europe Aluminium Wire Rod Market