
 High Pressure Contrast Media Injectors Market | 2026-2036
High Pressure Contrast Media Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Contrast Media Injectors Market Intelligence
Polymer-based disposable syringe kits are repositioning cost structures away from traditional stainless-steel reusable systems in high-pressure angiography suites. Bayer AG leverages its integrated contrast media and injector portfolio to sustain channel control across European cath labs. Guerbet Group anchors its competitive stance through specialized injector systems optimized for its proprietary contrast formulations. Siemens Healthineers dominates the installed base of MRI-compatible injector platforms through bundled equipment-service contracts with hospital networks.
High pressure contrast media injectors are electromechanical devices engineered to deliver iodinated or gadolinium-based contrast agents at controlled flow rates exceeding 20 mL per second during CT angiography, cardiac catheterization, and MR imaging procedures. These systems incorporate precision piston pumps, pressure-limiting valves, and real-time flow sensors to prevent extravasation while ensuring uniform vascular opacification. Power injectors command the largest revenue share among product types due to their indispensability in emergency coronary interventions requiring sub-second bolus timing. Automated technology is displacing manual injector configurations as interventional radiology departments standardize workflow protocols and reduce operator variability. Cardiovascular imaging remains the dominant application segment, though oncological imaging is gaining traction from rising CT-guided ablation procedures and perfusion studies.
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) impose biocompatibility, electrical safety, and software validation requirements that extend product development timelines and elevate compliance costs for manufacturers. The EPA regulates disposal of iodinated contrast waste streams, influencing hospital procurement preferences toward closed-loop fluid management systems integrated with injector platforms. Stakeholders must monitor evolving cybersecurity standards for networked injector systems as hospital IT infrastructure converges with diagnostic equipment connectivity protocols.
Market Dynamics
Automated injector technology is compressing manual system margins while EU MDR compliance costs are forcing mid-tier manufacturers toward specialized niches or exit.
Growth Catalysts
- Cardiac catheterization lab automation:Emergency coronary intervention protocols now mandate sub-second bolus timing that only power injectors deliver. Cath labs in Germany and Japan are retiring manual syringes at accelerated rates.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for software-upgradable injector platforms reduces time-to-market for iterative improvements. This regulatory clarity encourages R&D investment in flow-sensor precision.
- Closed-loop fluid management integration:EPA disposal regulations for iodinated contrast waste are driving hospital procurement toward injector platforms with integrated waste containment. This bundling raises system switching costs.
Market Restraints
- Premium polymer supply concentration:Medical-grade polycarbonate for disposable syringe kits depends on concentrated petrochemical feedstock suppliers in the US Gulf Coast. Price volatility transmits directly to kit manufacturing costs.
- EU MDR technical documentation burden:Clinical evaluation requirements for Class IIa injectors extend certification timelines by 12-18 months. Small manufacturers lack resources to maintain notified body relationships.
- Reusable stainless-steel depreciation:Hospitals with sunk capital in legacy injector systems face write-off costs when migrating to disposable workflows. This inertia slows automated platform adoption in budget-constrained facilities.
Strategic Opportunities
- Oncological imaging expansion:CT-guided tumor ablation and perfusion studies are creating demand for precision injectors outside cardiovascular suites. Interventional oncology departments represent untapped upgrade cycles.
- Japan MRI-compatible platform gaps:Bundled equipment-service contracts have concentrated the installed base, but independent service organizations can capture aftermarket maintenance revenue from mid-tier hospital networks.
- Cybersecurity standard convergence:IEC 81001-5-1 network security requirements for connected medical devices are creating compliance service opportunities. Injector manufacturers can monetize software validation consulting.
Industry Challenges
- Interventional radiologist training deficits:Automated injector protocols require standardized operator certification that many residency programs have not integrated. Workflow variability persists despite equipment standardization.
- Legacy PACS integration complexity:New injector platforms must interface with decade-old hospital imaging archives. Custom middleware development consumes implementation resources and delays go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Contrast Media Injectors Market |
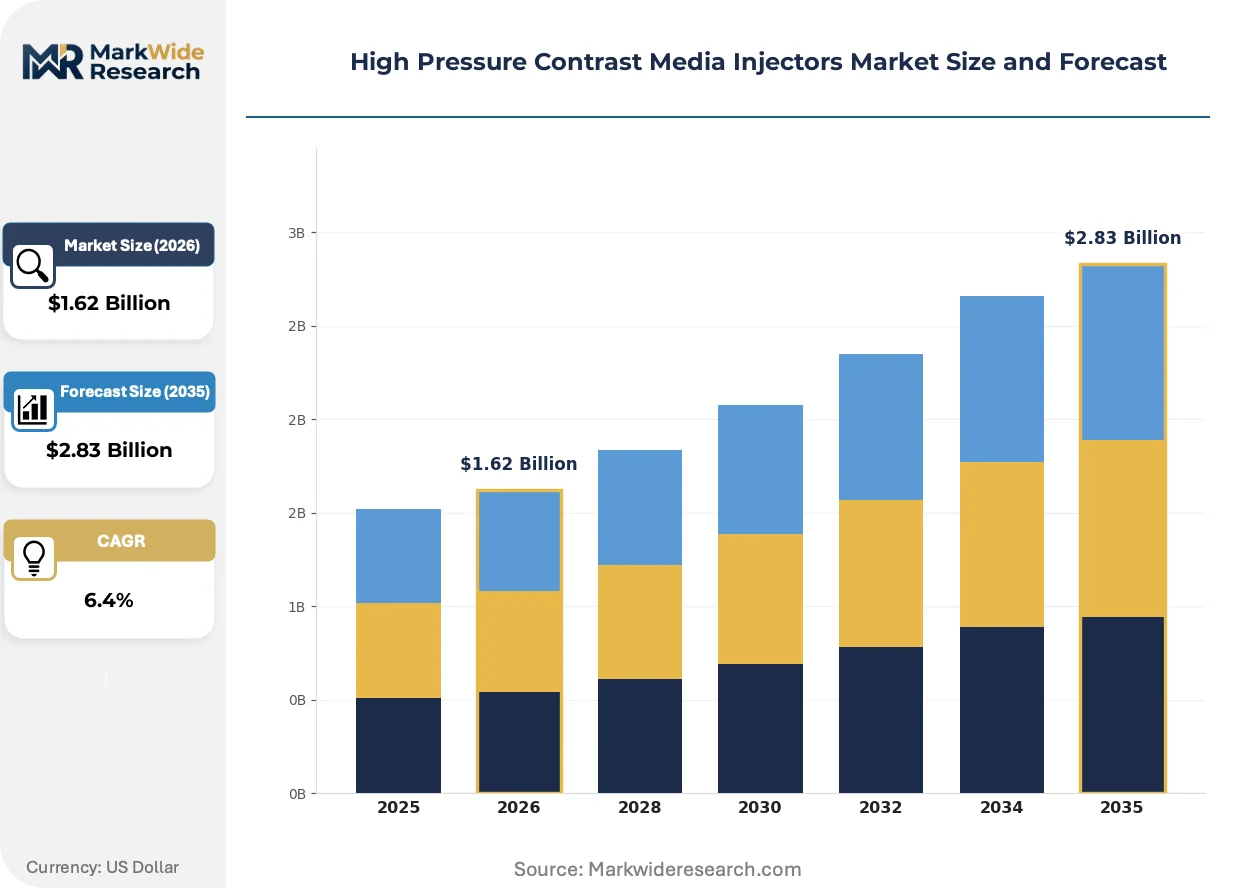
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.83 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Injectors, Syringe Injectors, Manual Injectors, Bulb Injectors Application: Cardiovascular Imaging, Neurological Imaging, Oncological Imaging, Gastrointestinal Imaging End User: Hospitals, Imaging Centers, Diagnostic Labs, Research Institutions Technology: Digital, Automated, Wireless, Contrast-Enhanced |
| Companies Covered | Bayer AG, Bracco Imaging, Guerbet Group, MEDTRON AG, GE Healthcare, Ulrich GmbH & Co. KG, Nemoto Kyorindo, Siemens Healthineers, Sino Medical-Device Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Contrast Media Injectors Market Strategic Shifts & Innovations
Disposable polymer syringe systems are fragmenting the reusable equipment aftermarket while regulatory software requirements are reshaping R&D allocation across product development teams.
Single-use syringe kits with integrated pressure transducers are decentralizing maintenance and calibration workflows away from centralized biomedical engineering departments. Community hospitals and outpatient imaging centers are adopting these platforms to eliminate capital equipment depreciation. The shift is compressing revenue for third-party service contractors who previously captured preventive maintenance contracts.
EU MDR post-market surveillance requirements are mandating systematic collection of real-world performance data for Class IIa injectors. Manufacturers must now fund clinical follow-up studies and incident reporting infrastructure that the Medical Devices Directive did not require. Cardiac catheterization labs in France and Italy are prioritizing suppliers with established European notified body relationships to mitigate supply continuity risk.
Hospital procurement committees are unbundling equipment and consumable purchasing decisions that vendors previously combined into sole-source agreements. Materials management departments now run competitive bids for syringe kits independent of injector platform selection. This behavior is most visible in US health systems with centralized supply chain governance, where GPO contracts no longer guarantee captive consumable revenue.
High Pressure Contrast Media Injectors Market Segmentation
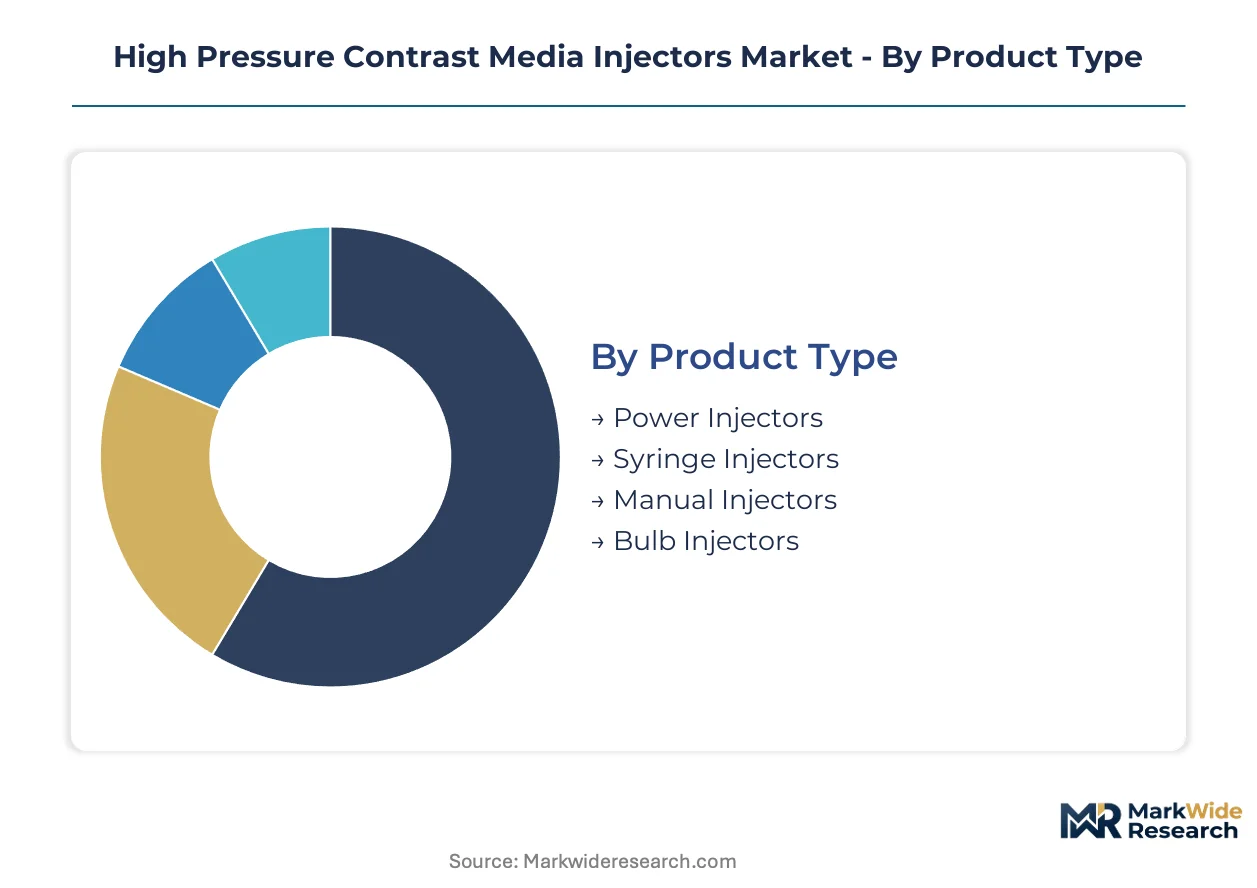
Injector configuration choices directly determine workflow standardization in cath labs and imaging suites. Procurement committees weigh capital depreciation against consumable spend when segmenting vendor selection criteria. Each dimension reveals distinct pressure points between emergency throughput demands and budget cycle constraints.
Product Type:
Standalone injector platforms operate independently from imaging gantries, while embedded systems integrate directly into CT and MRI consoles.
- Power Injectors:Electromechanical piston systems deliver iodinated contrast at flow rates exceeding 20 mL per second with real-time pressure monitoring. Cardiac catheterization labs in Germany and Japan mandate these systems for emergency coronary interventions requiring sub-second bolus timing.
- Syringe Injectors:Precision motor-driven syringe platforms accommodate smaller volume injections for pediatric and peripheral vascular applications. Demand concentrates in outpatient imaging centers where procedure mix spans multiple body regions.
- Manual Injectors:Hand-operated systems retain niche use in low-volume settings and research protocols requiring operator-controlled flow modulation.
- Bulb Injectors:Squeeze-activated disposable devices serve point-of-care ultrasound and bedside imaging where electrical infrastructure is unavailable.
Volume placements concentrate in power injectors; the faster expansion belongs to syringe injectors.
Application:
Procedure reimbursement codes and contrast volume requirements segment injector specification priorities across clinical departments.
- Cardiovascular Imaging:Coronary CT angiography and cardiac catheterization procedures consume the largest installed base of high-pressure systems. Cath lab automation protocols in the United States now require power injector compatibility for accreditation.
- Oncological Imaging:CT-guided tumor ablation and perfusion studies demand precision flow control for therapeutic contrast delivery. Interventional oncology departments in Japan are retrofitting suites with automated platforms.
- Neurological Imaging:Cerebral angiography and stroke protocol CT require rapid bolus timing with extravasation detection algorithms.
- Gastrointestinal Imaging:CT enterography and hepatobiliary studies utilize moderate-pressure injection profiles with extended saline chaser sequences.
Cardiovascular imaging dominates current placements; oncological imaging is climbing the fastest.
End User:
Capital allocation authority and maintenance infrastructure segment procurement behavior across facility types.
- Hospitals:Integrated health systems leverage enterprise purchasing agreements to standardize injector platforms across radiology, cardiology, and emergency departments. Biomedical engineering departments retain in-house preventive maintenance capabilities.
- Imaging Centers:Freestanding facilities prioritize disposable syringe systems to eliminate equipment depreciation and service contract overhead. United States outpatient chains are consolidating vendor relationships under GPO contracts.
- Diagnostic Labs:Hospital-affiliated laboratories process high-throughput screening protocols with dedicated injector lines for contrast-enhanced protocols.
- Research Institutions:Academic medical centers require programmable injectors supporting investigator-initiated protocols with custom flow profiles.
Hospital systems command the largest installed base; imaging centers are gaining share fastest.
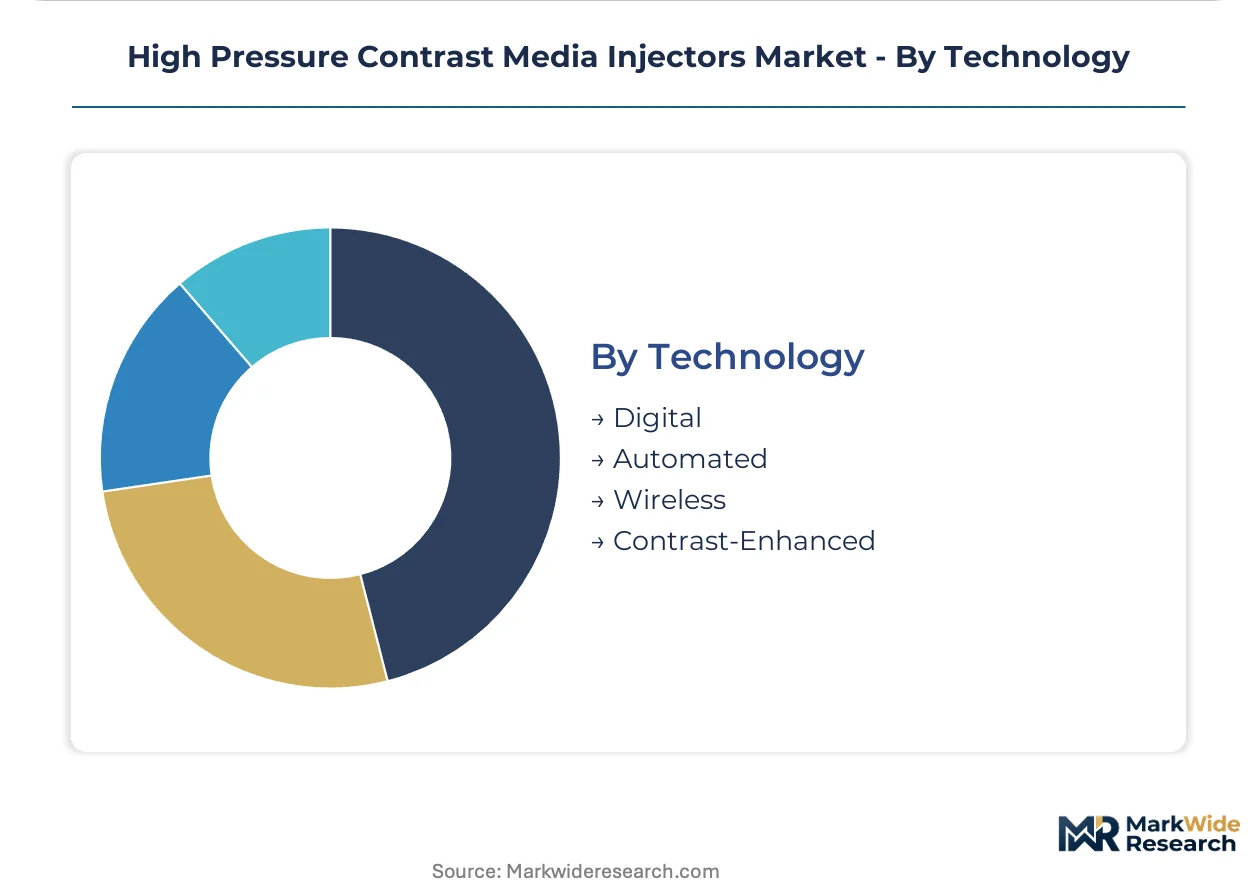
Technology:
Connectivity architecture and operator interface design segment R&D investment and regulatory submission pathways.
- Digital:Microprocessor-controlled flow algorithms with touchscreen programming interfaces enable protocol storage and retrieval. FDA 510(k) submissions for software-upgradable platforms streamline iterative improvements.
- Automated:Closed-loop pressure sensing with automatic flow rate adjustment reduces operator variability and extravasation risk. EU MDR clinical evaluation requirements extend certification timelines for these Class IIa systems.
- Wireless:Bluetooth and Wi-Fi enabled injectors interface with PACS and contrast management information systems.
- Contrast-Enhanced:Integrated saline flush and dual-syringe configurations optimize vascular opacification while minimizing contrast dose.
Digital platforms anchor the installed base; automated technology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital infrastructure modernization programs in the United States, Germany, and Japan concentrate demand for high-pressure contrast media injectors. Cardiac catheterization lab automation and imaging capacity expansion drive procurement cycles in these markets. Regulatory tightening through FDA 510(k) pathways and EU MDR compliance reshapes competitive access across jurisdictions.
United States
Emergency coronary intervention protocols and cath lab accreditation standards mandate power injector compatibility. FDA premarket notification requirements for software-upgradable platforms streamline iterative product improvements. Texas Medical Center in Houston and Cleveland Clinic anchor installed base expansion through enterprise purchasing agreements.
Germany
Cardiac catheterization labs in Bavaria and North Rhine-Westphalia retire manual syringes at accelerated rates. EU Medical Device Regulation clinical evaluation requirements extend certification timelines for Class IIa automated systems. Siemens Healthineers maintains channel leverage through bundled equipment-service contracts with university hospital networks.
Japan
Interventional oncology departments retrofit suites with automated platforms for CT-guided tumor ablation. PMDA pharmaceutical and medical device administration aligns with international harmonization standards for contrast delivery systems. Tokyo and Osaka metropolitan hospital clusters prioritize MRI-compatible injector platforms with integrated saline flush configurations.
United Kingdom
NHS imaging infrastructure programs standardize injector platforms across radiology and cardiology departments. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical documentation requirements. London and Manchester academic medical centers drive demand for programmable injectors supporting investigator-initiated protocols.
China
CT-guided ablation procedure volumes expand in tertiary hospital networks across the Yangtze River Delta. NMPA medical device registration pathways accelerate for domestically manufactured injector platforms. Shanghai and Beijing municipal health commissions prioritize closed-loop fluid management integration in public hospital procurement specifications.
High Pressure Contrast Media Injectors Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated contrast media producers commanding channel control through bundled portfolios. The vendor base concentrates around three strategic archetypes: pharmaceutical-contrast integrated houses, standalone electromechanical specialists, and imaging equipment OEMs with captive injector divisions. Competitive positioning hardens through M&A activity targeting disposable syringe kit manufacturers and strategic partnerships between injector platform developers and PACS integration specialists.
Among European-based integrated houses, Bayer AG and Guerbet Group occupy positions as archetypal contrast-media-coupled competitors, while Siemens Healthineers exemplifies the imaging-OEM-with-captive-division model. These three anchors represent divergent strategic postures: pharmaceutical integration versus equipment bundling versus standalone mechanical specialization.
| Leading Market Players |
|---|
| Bayer AG |
| Bracco Imaging |
| Guerbet Group |
| MEDTRON AG |
| GE Healthcare |
| Ulrich GmbH & Co. KG |
| Nemoto Kyorindo |
| Siemens Healthineers |
| Sino Medical-Device Technology |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees unbundling equipment and consumable purchasing decisions force manufacturers to restructure pricing architectures around standalone syringe kit competitiveness. This shift concentrates negotiating leverage with materials management departments running competitive bids independent of platform selection.
Pricing Analysis
Volume placements anchor revenue in power injector platforms while margins concentrate in disposable polymer syringe kits. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) certification tier and after-sales service bundling. Cost compression in mid-tier automated systems intensifies as EU MDR compliance expenses transmit through notified body certification fees. Imaging centers exhibit highest price sensitivity through GPO-negotiated contracts, whereas integrated health systems prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Freight costs for medical-grade polycarbonate syringe components from US Gulf Coast petrochemical suppliers elevate landed costs for European and Asian kit assemblers. Manufacturing concentration centers on Germany, Japan, and the United States for precision piston pump assemblies. Raw material dependencies include iodinated contrast media formulations, medical-grade polycarbonate resins, and pressure transducer microelectronics. Single-source vulnerability in specialty polymer feedstocks threatens production continuity during petrochemical supply disruptions. Distribution runs through hospital GPO contracts, imaging center purchasing cooperatives, and direct OEM service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over disposable syringe kit manufacturing determines margin capture. Players are pursuing backward integration into medical-grade polymer compounding to secure feedstock cost positions.
For Market Incumbents: Anticipate procurement committee unbundling by establishing standalone syringe kit pricing competitiveness independent of platform bundling. Siemens Healthineers and Bayer AG must deepen captive supply of polymer syringe components to defend against third-party kit manufacturers capturing aftermarket revenue. FDA 510(k) pathway efficiency for software-upgradable platforms remains the priority certification investment. For New Entrants and Emerging Players: Capture interventional oncology retrofit cycles in Japanese mid-tier hospital networks where bundled equipment-service contracts have concentrated incumbent installed bases. Independent service organizations can monetize aftermarket maintenance revenue from MRI-compatible platforms. Target CE marking pathway acceleration through established European notified body relationships to mitigate EU MDR timeline disadvantages. For Investors and Strategic Acquirers: The window for entry favors disposable syringe kit manufacturers with medical-grade polymer sourcing relationships. Long-term viability hinges on vertical integration into contrast media formulation or injector platform engineering. Watch PACS integration complexity resolution as the signal for automated platform adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of medical-grade polycarbonate reduces syringe kit cost volatility from Gulf Coast feedstock suppliers. |
| CE Marking Pathway Acceleration | Established European notified body relationships shorten EU MDR certification timelines for Class IIa automated injectors. |
| Hospital System Partnership | Enterprise purchasing agreements with Texas Medical Center and Cleveland Clinic anchor installed base expansion. |
| Software Companion Development | Closed-loop fluid management integration addresses EPA iodinated contrast waste disposal regulations. |
| Reimbursement Strategy | CT-guided tumor ablation procedure codes drive interventional oncology injector platform procurement. |
Research Approach
Multi-period observation of cath lab automation rates, EU MDR certification timelines, and syringe kit procurement patterns anchored the trend analysis, supplemented by interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA medical device registrations, hospital procurement databases, and CMS Medicare procedure volume data. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates.
Input-output matrix framing connected procedure volume projections across cardiovascular, oncological, and neurological imaging to injector platform and consumable demand. Segmentation dimensions modeled include product type, application, end user, and technology connectivity architecture. CAGRs were derived from regression analysis of historical replacement cycles and projected automation adoption curves. Industry-specific forecast inputs incorporated cath lab accreditation standards and EPA contrast waste disposal compliance costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, cybersecurity standard convergence, and polymer feedstock price volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Global Angiography Catheters Market
Medical Devices
Endoprosthesis Market
Medical Devices
Smart Lenses Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Retinal Implant Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Medical Manifolds Market
Medical Devices
Peripheral Embolization Device Market