
 Japan Cardiovascular Devices Market | 2026-2036
Japan Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Cardiovascular Devices Market Foresight
Domestic stent manufacturing capacity in Osaka and Tokyo is hardening as producers respond to sustained procedural demand. Terumo Corporation anchors catheter and guidewire production through integrated domestic facilities. Boston Scientific Corporation competes in the implantable rhythm management segment with specialized pacemaker distribution networks. Abbott Laboratories differentiates via structural heart portfolios that address Japan's expanding transcatheter valve replacement needs.
Japan cardiovascular devices encompass mechanical and electronic instruments designed to diagnose, monitor, or treat conditions of the heart and vasculature, including drug-eluting stents with cobalt-chromium platforms, bioresorbable scaffolds, and leadless pacemakers operating at 2.5–5.0 volt pulse amplitudes. These devices serve to restore coronary perfusion, correct electrical conduction abnormalities, or replace dysfunctional cardiac valves in clinical settings. Stent platforms generate the largest revenue pool among product types, while pacemaker systems capture premium margins due to battery longevity and miniaturization requirements. Interventional technology leads procedure volume growth as catheter-based alternatives displace open surgical approaches for coronary revascularization.
PMDA enforces Japan-specific quality management system requirements under the Pharmaceutical and Medical Device Act, while METI coordinates industrial policy for domestic medical device manufacturing competitiveness. JIS standards govern material specifications and biocompatibility testing protocols that shape product development timelines. Stakeholders must monitor reimbursement rate revisions by the Central Social Insurance Medical Council and align R&D portfolios with priority disease targets in Japan's national health promotion framework.
Market Dynamics
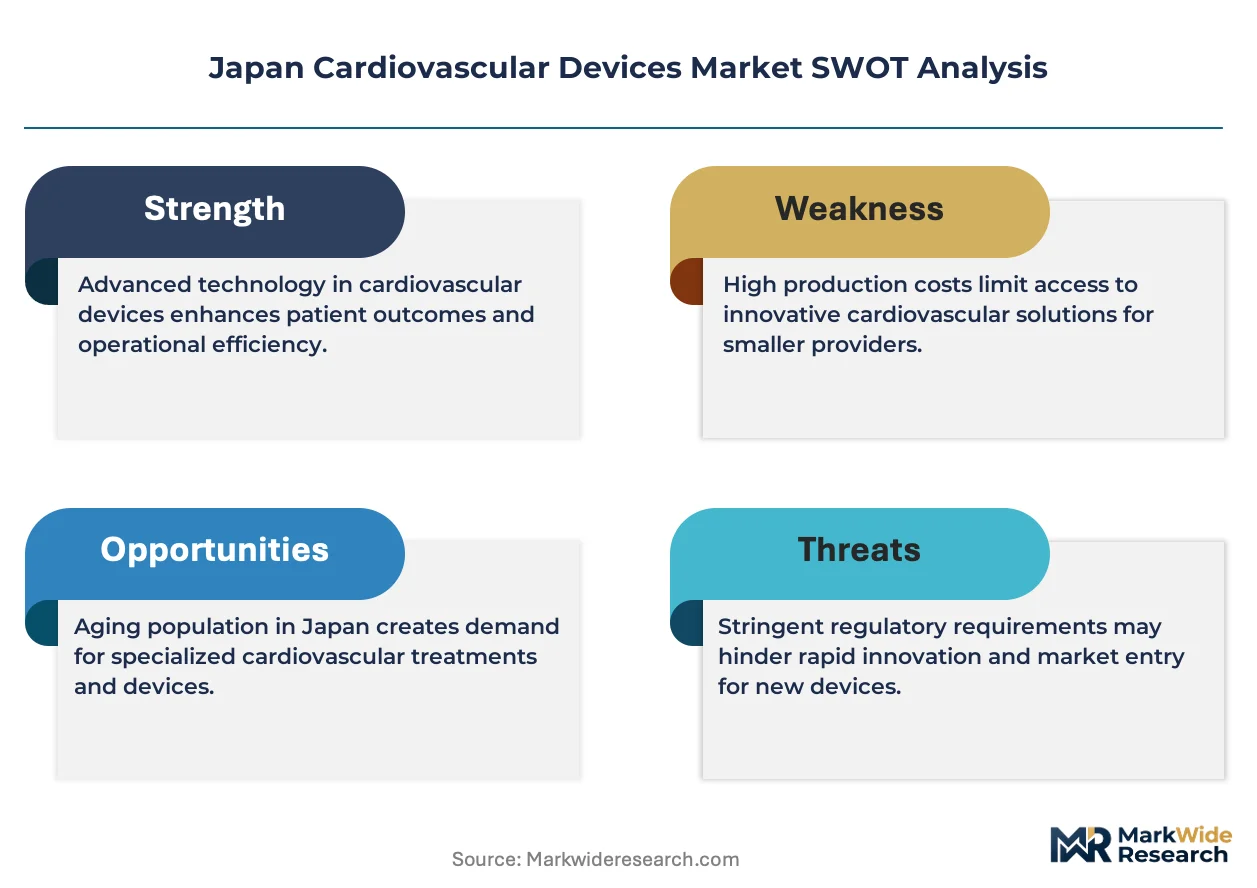
Japan's cardiovascular device sector is absorbing structural pressure from the Central Social Insurance Medical Council's biennial reimbursement rate revisions, which compress margins on mature stent platforms while creating selective incentives for next-generation bioresorbable scaffolds.
Growth Catalysts
- Kanto Region Demographics:Tokyo's tertiary cardiac centers are expanding catheterization laboratory capacity to serve aging populations with complex coronary disease profiles.
- PMDA Breakthrough Pathways:Accelerated regulatory review timelines for novel implantable rhythm management devices are shortening commercialization cycles for domestic and foreign manufacturers.
- Structural Heart Migration:Transcatheter aortic valve replacement procedures are displacing surgical valve replacement in high-risk patient cohorts across Japan's university hospital networks.
Market Restraints
- Cobalt-Chromium Supply Concentration:Japanese stent manufacturers depend on limited qualified suppliers of high-purity cobalt-chromium alloy tubing, creating input cost volatility and qualification bottlenecks.
- Bioresorbable Scaffold Technical Limitations:Scaffold strut thickness and radial strength constraints limit application in calcified lesions, restricting addressable procedure volumes.
- Reimbursement Compression:Central Social Insurance Medical Council rate revisions for drug-eluting stents have reduced procedure economics for hospital operators.
Strategic Opportunities
- Leadless Pacemaker Penetration:Battery-less and miniaturized pacing systems address infection risk and lead management burden in Japan's expanding elderly implant population.
- Osaka-Tokyo Manufacturing Integration:Domestic catheter and guidewire producers are consolidating component supply chains within Japan's industrial heartland to reduce import dependency.
- Remote Monitoring Convergence:Integration of implantable cardiac devices with cloud-based patient management platforms aligns with Japan's national health promotion framework for chronic disease surveillance.
Industry Challenges
- Electrophysiology Talent Scarcity:Complex ablation procedure growth outpaces training pipeline capacity for certified cardiac electrophysiologists in Japanese academic medical centers.
- PMDA Quality Management System Compliance:Pharmaceutical and Medical Device Act documentation requirements extend product registration timelines for foreign manufacturers unfamiliar with Japan-specific clinical data standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Cardiovascular Devices Market |
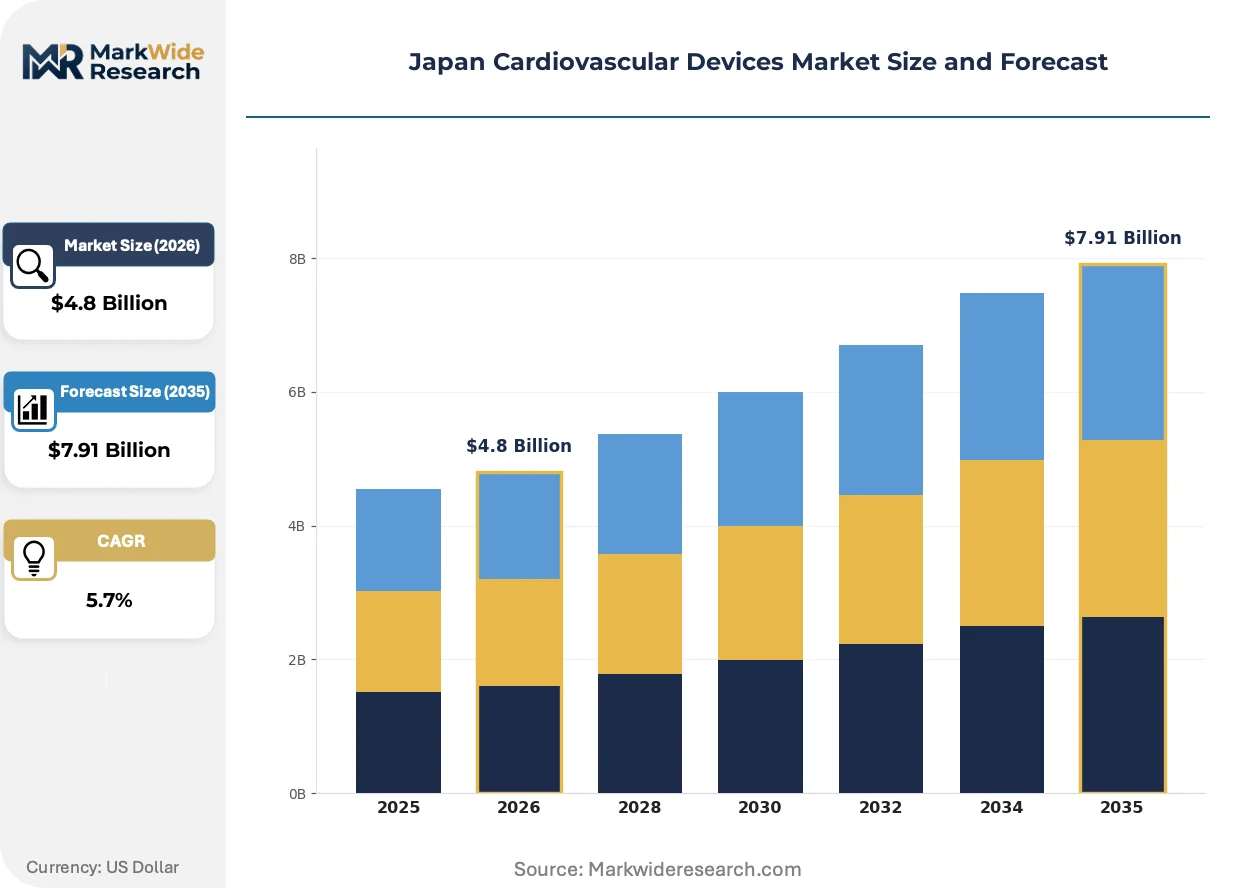
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Balloons End User: Hospitals, Cardiac Centers, Outpatient Clinics, Emergency Services Technology: Interventional, Implantable, Diagnostic, Surgical Application: Coronary Artery Disease, Heart Failure, Arrhythmia, Structural Heart |
| Companies Covered | Boston Scientific Corporation, Japan Lifeline, Terumo Corporation, Fukuda Denshi, Asahi Intecc, Medtronic PLC, Edwards Lifesciences, Canon Medical Systems Corporation, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Cardiovascular Devices Market Shifts & Advancements
Interventional cardiology in Japan is absorbing platform-level innovation across three vectors: material science evolution in implantable scaffolds, regulatory pathway redesign under PMDA modernization, and procurement model transformation among consolidated hospital purchasing groups.
Bioresorbable vascular scaffolds with poly-L-lactic acid cores are absorbing procedural share from permanent metallic stents in select lesion subsets. Japanese interventional cardiologists at university-affiliated centers are adopting these platforms for younger patients with discrete de novo lesions. The technology is absorbing R&D investment from domestic manufacturers seeking differentiation beyond cobalt-chromium commodity platforms.
PMDA's implementation of conditional early approval pathways for breakthrough devices is compressing time-to-market for novel cardiac rhythm management systems. The policy shift rewards manufacturers that generate Japan-specific clinical evidence through prospective registries. Implantable cardioverter-defibrillator segments are responding with accelerated post-market study commitments to secure favorable reimbursement positioning.
Hospital group purchasing organizations in the Kanto and Kansai regions are consolidating procurement authority for cardiovascular consumables. Device vendors face compressed contracting cycles and bundled pricing demands that unbundle traditional device-service support packages. This concentration is most visible among Tokyo's metropolitan hospital networks, where procurement committees now mandate total cost-of-ownership analytics over unit price metrics.
Japan Cardiovascular Devices Market Segmentation
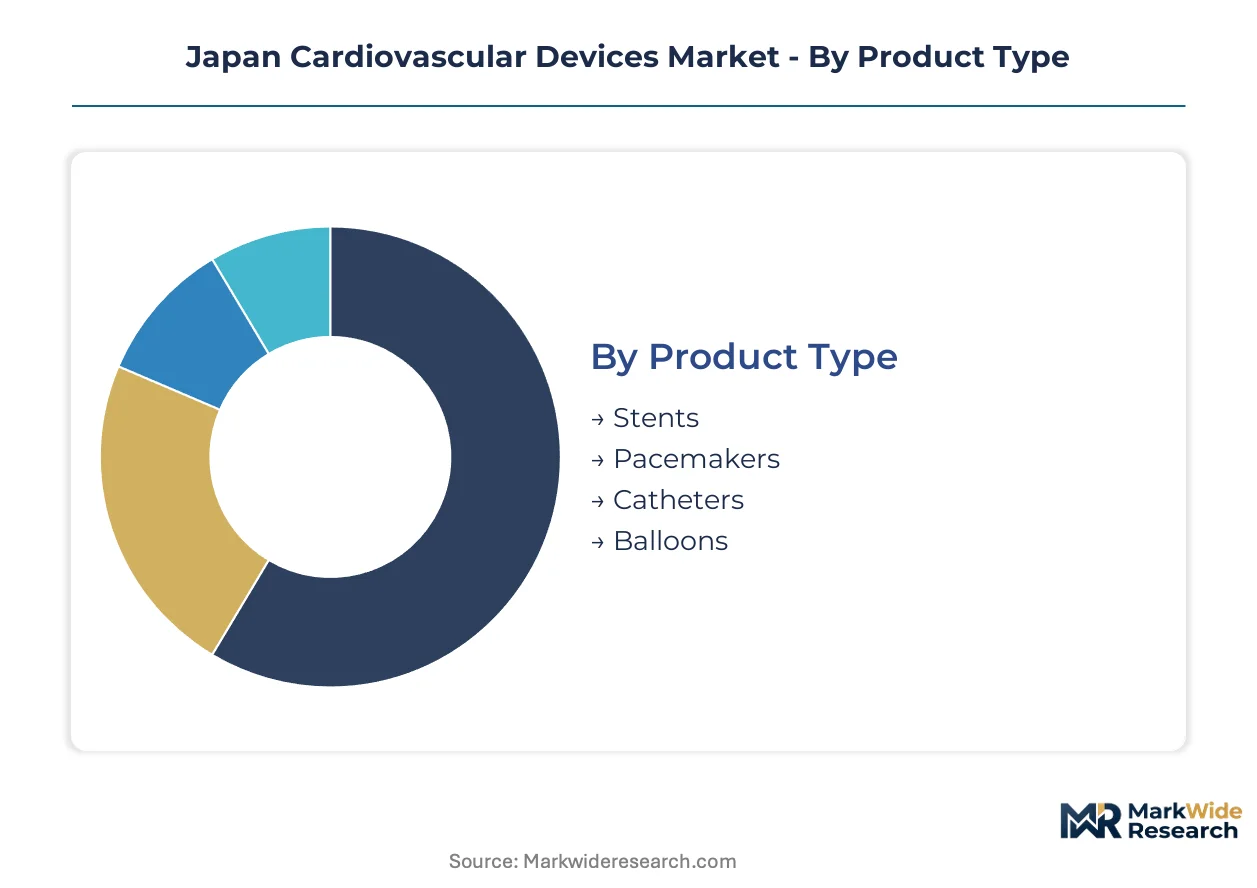
Device segmentation in Japan reflects distinct upgrade cycles across product generations, with metallic stent replacement by bioresorbable platforms and pacemaker migration toward leadless systems driving portfolio reallocation. Hospital procurement committees evaluate segments through total cost-of-ownership lenses that weight device longevity against procedure economics.
Product Type:
Replacement cycles vary sharply across implantable categories, with stent platforms facing accelerated obsolescence from scaffold technology while pacemaker refresh rates extend through battery chemistry improvements.
- Stents:Cobalt-chromium drug-eluting platforms with strut thickness below 80 micrometers dominate coronary revascularization in Tokyo's tertiary centers. Kanto region catheterization laboratories absorb the highest procedural volumes as aging demographics expand addressable patient pools.
- Pacemakers:Miniaturized single-chamber and dual-chamber devices with 8-12 year battery longevity address Japan's expanding elderly implant population. Leadless systems are displacing transvenous designs in infection-risk cohorts across Osaka university hospital networks.
- Catheters:Diagnostic and guiding catheters with hydrophilic coatings enable complex lesion access in bifurcation procedures.
- Balloons:Semi-compliant and non-compliant dilatation platforms prepare calcified lesions for stent deployment.
Stents sit at the top of the volume ranking, with leadless pacemaker configurations climbing the fastest.
End User:
Cost tier stratification separates high-acuity settings with capital-intensive hybrid operating rooms from outpatient facilities constrained by reimbursement ceilings.
- Hospitals:Tertiary medical centers with 24-hour catheterization laboratory staffing perform complex multivessel interventions and structural heart procedures. Tokyo metropolitan hospital networks consolidate procurement authority for cardiovascular consumables through centralized purchasing committees.
- Cardiac Centers:Specialized facilities with dedicated electrophysiology suites and hybrid imaging systems generate premium procedure economics. Kansai region centers are expanding transcatheter aortic valve replacement capacity to capture surgical alternative demand.
- Outpatient Clinics:Diagnostic and follow-up services operate within Central Social Insurance Medical Council reimbursement frameworks.
- Emergency Services:Pre-hospital acute coronary syndrome protocols drive stent deployment in ST-elevation myocardial infarction pathways.
Hospitals command the dominant revenue share, though cardiac centers are expanding capacity most aggressively.
Technology:
Application breadth determines margin structure, with interventional platforms capturing procedure-linked revenue streams against diagnostic equipment constrained by capital budget cycles.
- Interventional:Catheter-based revascularization and structural repair technologies displace open surgical approaches in high-risk patient cohorts. PMDA breakthrough pathways accelerate commercialization timelines for novel delivery systems.
- Implantable:Rhythm management and valve replacement devices with biocompatible coatings address chronic disease surveillance requirements under Japan's national health promotion framework.
- Diagnostic:Intravascular imaging and physiologic assessment tools guide lesion preparation and stent optimization.
- Surgical:Conventional valve replacement and coronary artery bypass grafting platforms retain role in complex redo procedures.
Interventional technology leads procedure volume, with implantable systems delivering the steepest expansion trajectory.
Application:
Maturity gradients separate well-established coronary interventions from emerging structural heart segments where training pipeline limitations constrain growth.
- Coronary Artery Disease:Drug-eluting stent deployment in de novo and restenotic lesions constitutes the procedural backbone of Japanese interventional cardiology. Kanto region demographics sustain demand as diabetes prevalence and aging intersect.
- Structural Heart:Transcatheter aortic valve replacement and mitral repair address surgical ineligibility in Japan's expanding octogenarian population. University hospital networks are absorbing case volume as operator experience accumulates.
- Heart Failure:Cardiac resynchronization therapy and ventricular assist devices manage refractory cases.
- Arrhythmia:Catheter ablation and implantable defibrillator therapy target atrial fibrillation and sudden cardiac death prevention.
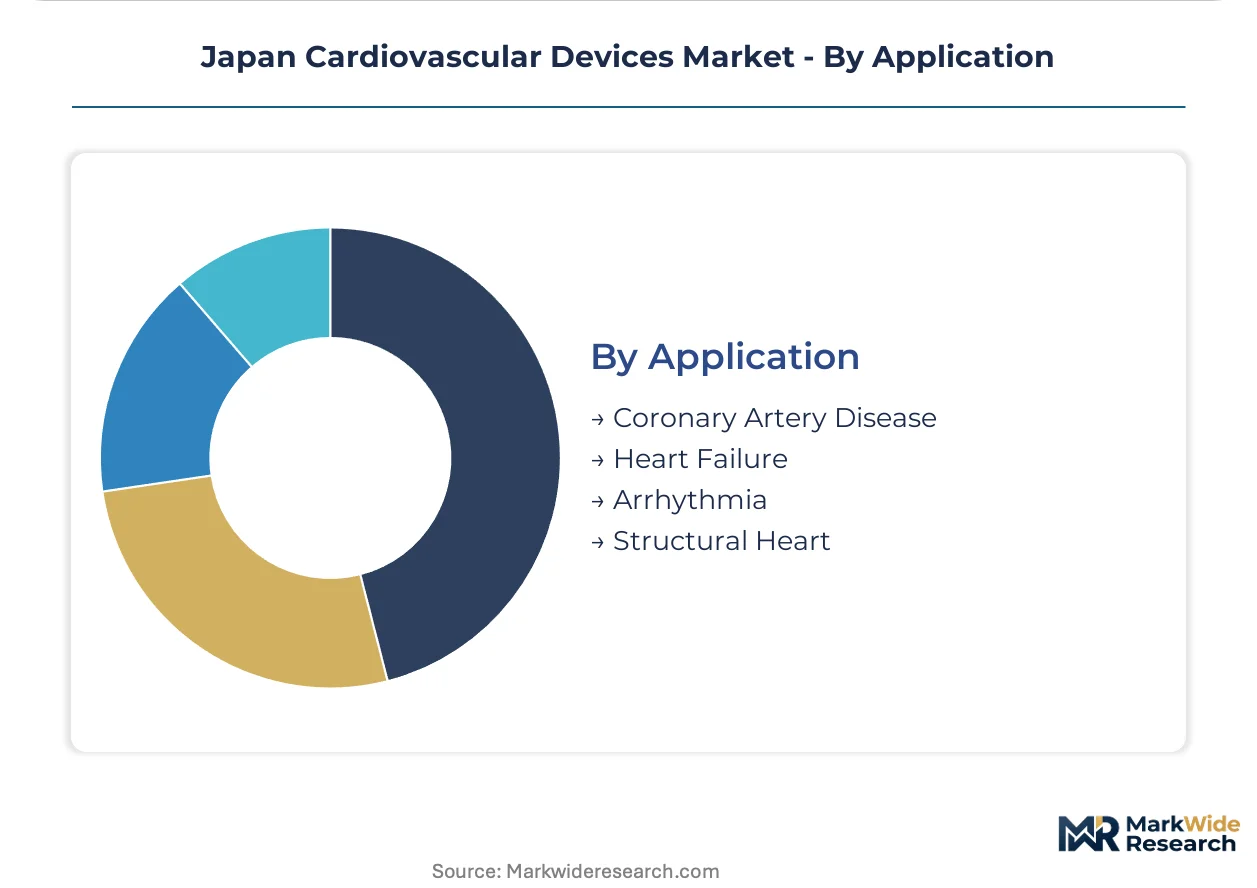
Coronary artery disease procedures retain volume leadership, while structural heart interventions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision stent manufacturing infrastructure contrasts with Japan's catheterization laboratory density, revealing how geography shapes competitive positioning in cardiovascular device markets. National health system architectures and industrial policy choices create divergent entry pathways for implantable rhythm management technologies.
Kanto Region
Tokyo's tertiary cardiac centers absorb the highest procedural volumes as aging demographics expand addressable patient pools for coronary revascularization. PMDA breakthrough pathways accelerate commercialization timelines for novel delivery systems originating from Kanto-based R&D facilities. Metropolitan hospital networks consolidate procurement authority for cardiovascular consumables through centralized purchasing committees.
Kansai Region
Osaka anchors domestic stent manufacturing capacity through integrated catheter and guidewire production facilities. University hospital networks in Kyoto and Osaka are expanding transcatheter aortic valve replacement capacity to capture surgical alternative demand. METI industrial policy coordinates domestic medical device manufacturing competitiveness across the Kansai industrial heartland.
Chubu Region
Nagoya's medical device supply chain supports component qualification for high-purity cobalt-chromium alloy tubing. The Central Social Insurance Medical Council's biennial reimbursement rate revisions compress margins on mature stent platforms throughout Chubu catheterization laboratories. Regional hospital networks align R&D portfolios with priority disease targets in Japan's national health promotion framework.
Kyushu Region
Fukuoka's cardiac centers address infection-risk cohorts through leadless pacemaker deployment in elderly implant populations. PMDA quality management system requirements under the Pharmaceutical and Medical Device Act shape product development timelines for Kyushu-based manufacturers. Regional procurement patterns reflect total cost-of-ownership analytics over unit price metrics.
Hokkaido Region
Sapporo's university hospital networks manage complex redo procedures where conventional valve replacement and coronary artery bypass grafting platforms retain clinical roles. JIS standards govern material specifications and biocompatibility testing protocols that extend product registration timelines for manufacturers serving northern Japan. Remote monitoring convergence aligns implantable cardiac devices with cloud-based patient management platforms.
Japan Cardiovascular Devices Market Competitive Landscape
Japanese producers anchor one tier; US and European specialists hold differentiated positions in implantable rhythm management and structural heart segments. The vendor base stratifies across integrated domestic manufacturers, diversified global health technology conglomerates, and specialized interventional players. Three archetypes dominate: catheter and guidewire generalists, implantable device innovators, and diagnostic imaging platform operators. Competitive moves concentrate on manufacturing consolidation within Japan's industrial heartland and strategic partnerships for Japan-specific clinical evidence generation.
Within the integrated domestic tier, Terumo Corporation and Asahi Intecc exemplify catheter and guidewire production anchored in Osaka and Tokyo manufacturing facilities. Boston Scientific Corporation and Abbott Laboratories occupy positions among diversified global health technology conglomerates competing across implantable rhythm management and structural heart portfolios. Japan Lifeline represents the specialized interventional archetype with domestic distribution networks. These named entities serve as anchors for understanding how geographic origin and company structure shape competitive positioning without ascribing specific strategic actions or market share claims to any individual firm.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Japan Lifeline |
| Terumo Corporation |
| Fukuda Denshi |
| Asahi Intecc |
| Medtronic PLC |
| Edwards Lifesciences |
| Canon Medical Systems Corporation |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Cobalt-chromium alloy spot indices cascade through Japanese stent manufacturing tiers, compressing margins on commodity drug-eluting platforms while amplifying premium capture for bioresorbable scaffolds with qualified domestic supply chains. Central Social Insurance Medical Council reimbursement revisions reinforce this bifurcation, rewarding manufacturers with captive raw-material processing over import-dependent competitors.
Pricing Analysis
Distributor markups on cardiovascular consumables stratify across three tiers: premium bioresorbable scaffolds command certification-linked premiums under PMDA breakthrough pathways, standard cobalt-chromium stents face price erosion from consolidated hospital purchasing committees in Tokyo metropolitan networks, and economy balloon catheters compete on volume scale with minimal service bundling. Price differentiation hinges on JIS standard compliance tier and after-sales clinical support depth. Cost compression runs through standard stent tiers as procurement committees mandate total cost-of-ownership analytics. Academic medical centers exhibit lowest price sensitivity due to research funding offsets, while regional hospitals absorb maximum reimbursement pressure.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss suppliers of high-purity cobalt-chromium alloy tubing, constraining Japanese stent manufacturers to qualified vendor lists with extended qualification timelines. Raw material feeds draw from specialty steel producers in Germany, precision tubing specialists in Switzerland, and secondary processing facilities in Japan's Chubu region. Supply chain risk centers on tariff exposure for EU-origin alloy shipments under evolving trade frameworks. Distribution runs through Terumo's integrated domestic logistics network and specialized medical device distributors serving Kanto and Kansai hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's cardiovascular device sector functions as a geographic-arbitrage play between PMDA's accelerated breakthrough pathways and Europe's lengthier MDR transition timelines, enabling faster commercialization cycles for manufacturers with Japan-specific clinical evidence generation capabilities.
For Market Incumbents: Hedge against bioresorbable scaffold substitution by securing captive cobalt-chromium supply through backward integration into Chubu-region alloy processing. Fortify position against emerging Korean manufacturers by deepening JIS standard compliance investments that foreign entrants cannot replicate without domestic facility presence. Channel control through direct hospital system partnerships in Kanto metropolitan networks remains the critical defensive lever.
For New Entrants and Emerging Players: Begin with leadless pacemaker distribution through Osaka university hospital networks, where infection-risk patient cohorts and electrophysiology talent scarcity create addressable white space. Target Kyushu region cardiac centers for remote monitoring platform deployment, leveraging cloud-based patient management convergence under Japan's national health promotion framework. Partner with domestic GPOs for reimbursement navigation support.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized interventional players possessing Japan-specific regulatory dossiers and established clinician training relationships. Five-to-ten year viability hinges on structural heart migration acceleration and transcatheter valve replacement capacity expansion. Monitor PMDA conditional approval commitments as the signal for portfolio reallocation toward breakthrough-designated device categories.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Breakthrough Pathway Submission | Accelerated review timelines compress commercialization cycles for novel stent platforms. |
| Hospital System Partnership | Tokyo metropolitan networks consolidate procurement authority through centralized purchasing committees. |
| Backward Integration into Alloy Processing | Chubu-region captive supply reduces cobalt-chromium input cost volatility. |
| Software Companion Development | Cloud-based patient management aligns with Japan's chronic disease surveillance framework. |
| Reimbursement Strategy | Central Social Insurance Medical Council alignment secures favorable procedure economics. |
Research Methodology
Direct dialogue with interventional cardiologists, hospital purchasing committee members, biomedical engineers at tertiary cardiac centers, and GPO contracts managers grounded the qualitative foundation. Secondary validation drew from PMDA approval databases, Central Social Insurance Medical Council reimbursement schedules, METI industrial policy white papers, and JIS standard specification documents. Bottom-up procedure volume estimates triangulated against top-down market size benchmarks across the analysis window.
Segment-level outputs reflect modeling across product type, end-user facility tier, interventional versus implantable technology platforms, and coronary versus structural heart applications. CAGRs derived from regression analysis of historical procedure volumes, demographic projections, and reimbursement rate elasticity assumptions. Forecast inputs incorporated PMDA regulatory pathway evolution, bioresorbable scaffold clinical adoption curves, and leadless pacemaker training pipeline capacity constraints.
Several conditions sit outside the modeled scope, including unforeseen PMDA regulatory reversals, cobalt-chromium supply disruptions from geopolitical events, and structural shifts in Japan's national health insurance funding mechanisms. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market