
 Peripheral Embolization Device Market | 2026-2036
Peripheral Embolization Device Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Embolization Device Market Analytics
Hospital procurement channels for embolization devices is narrowing as integrated delivery networks consolidate vendor contracts across multiple sites. Terumo Corporation leverages its interventional systems portfolio to bundle catheter and embolic offerings. Merit Medical Systems anchors its position through direct hospital sales teams covering outpatient and inpatient settings. Cook Medical specializes in custom embolic configurations for complex vascular malformations.
Peripheral embolization devices are implantable or injectable agents delivered via catheter to occlude blood vessels, typically composed of platinum-tungsten alloys, polyvinyl alcohol particles, or N-butyl cyanoacrylate adhesive formulations designed to achieve permanent or temporary vascular occlusion. Coils dominate procedural volume in aneurysm and trauma applications due to established reimbursement and physician training pathways. Liquid embolic agents represent the fastest-expanding product category as catheter technology enables deeper AVM nidus penetration. The application split reveals tumor embolization commands premium pricing while uterine fibroid procedures drive outpatient volume growth.
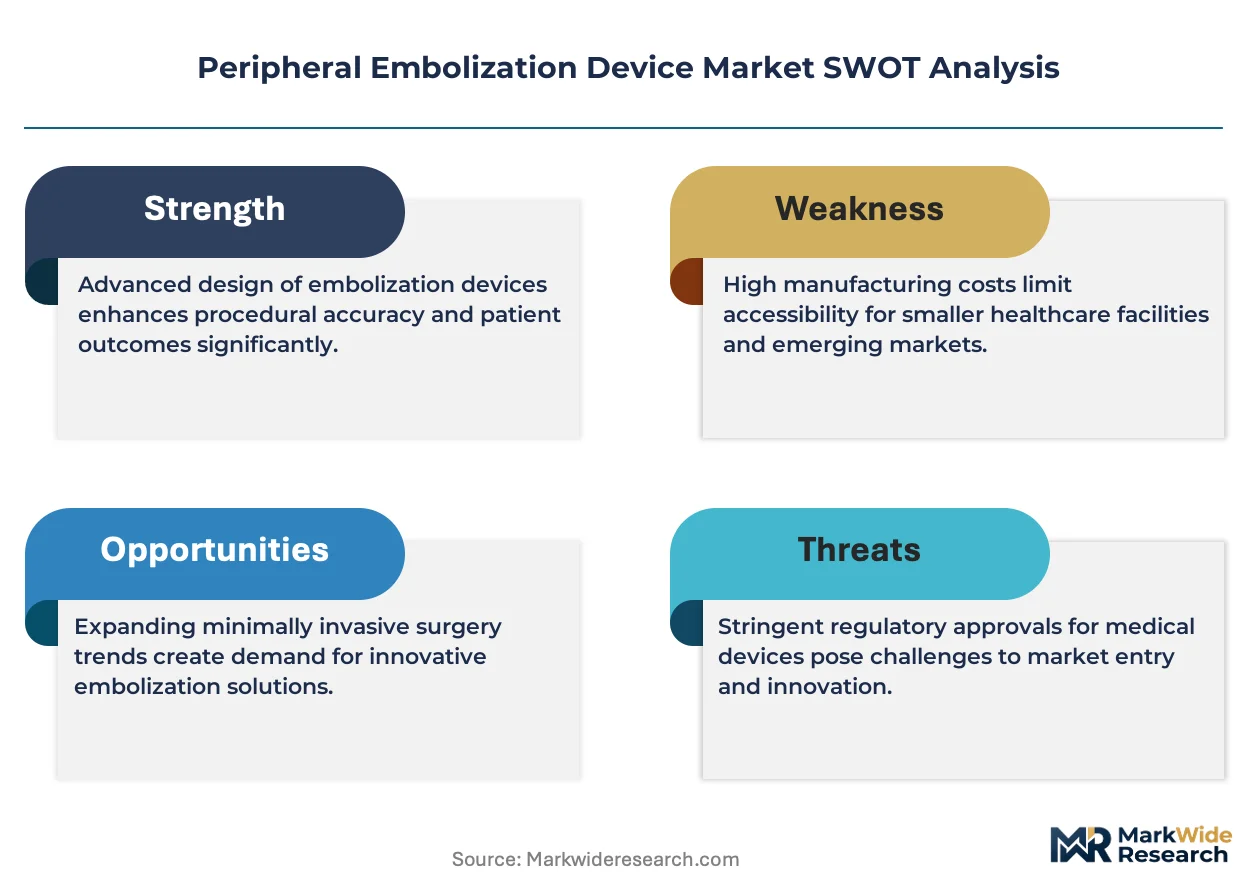
The FDA maintains Class II/III device controls over permanent implants, while the EU MDR imposes strengthened clinical evidence requirements for embolic agents marketed in Europe. Both frameworks elevate barriers for novel materials without predicate device pathways. Stakeholders must monitor evolving CMS outpatient procedure bundling decisions that could reshape site-of-service economics.
Market Dynamics
Integrated delivery networks are consolidating procurement across hospital systems, compressing vendor access points and forcing device manufacturers to restructure their commercial organizations around enterprise-wide contracting rather than site-level sales relationships.
Growth Catalysts
- EU MDR Clinical Evidence Pathways:Strengthened post-market surveillance requirements for permanent implants are accelerating investment in real-world evidence generation, creating competitive moats for established manufacturers with robust clinical datasets.
- Liquid Embolic Agent Technology:Catheter-enabled deeper penetration of arteriovenous malformation nidus is expanding treatable patient populations previously excluded from embolization therapy due to anatomical complexity.
- Academic Medical Center Expansion:Interventional radiology departments at university hospitals are building dedicated embolization service lines, concentrating high-complexity procedural volume and training capacity.
Market Restraints
- Platinum-Tungsten Alloy Supply Concentration:Coil manufacturing depends on specialized metallurgical suppliers concentrated in East Asian refining operations, exposing device makers to input cost volatility and geopolitical supply risk.
- FDA Class II/III Device Controls:Enhanced premarket review pathways for permanent implantable devices are extending development timelines and elevating capital requirements for novel material introductions without predicate pathways.
- Surgical Resection Substitutes:Minimally invasive surgical techniques and radiation therapy advances are competing for tumor and vascular malformation cases, particularly in markets with limited interventional radiology specialist density.
Strategic Opportunities
- Outpatient Procedure Bundling:CMS site-of-service economics are redirecting uterine fibroid and select tumor embolizations to hospital outpatient departments, creating volume concentration opportunities for ambulatory-capable device configurations.
- Bioresorbable Embolic Materials:Convergence of polymer science and controlled-release pharmaceutical formulations is enabling temporary vascular occlusion platforms with programmable resorption timelines for trauma and pediatric applications.
- Direct-to-Hospital Digital Procurement:Integrated delivery networks are piloting vendor-managed inventory platforms with automated consumption tracking, opening channel innovation space beyond traditional distributor relationships.
Industry Challenges
- Interventional Radiology Training Pipeline:Fellowship programs are producing insufficient procedural specialists to match embolization service line expansion, creating workforce bottlenecks at high-volume centers.
- MDR Technical Documentation Burden:European notified body capacity constraints are extending certification timelines for legacy device renewals, forcing resource reallocation from product development to regulatory compliance.
- Catheter-Embolic System Integration:Liquid agent delivery requires precise compatibility between delivery platform and embolic material, complicating supply chain management and clinical training standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Embolization Device Market |
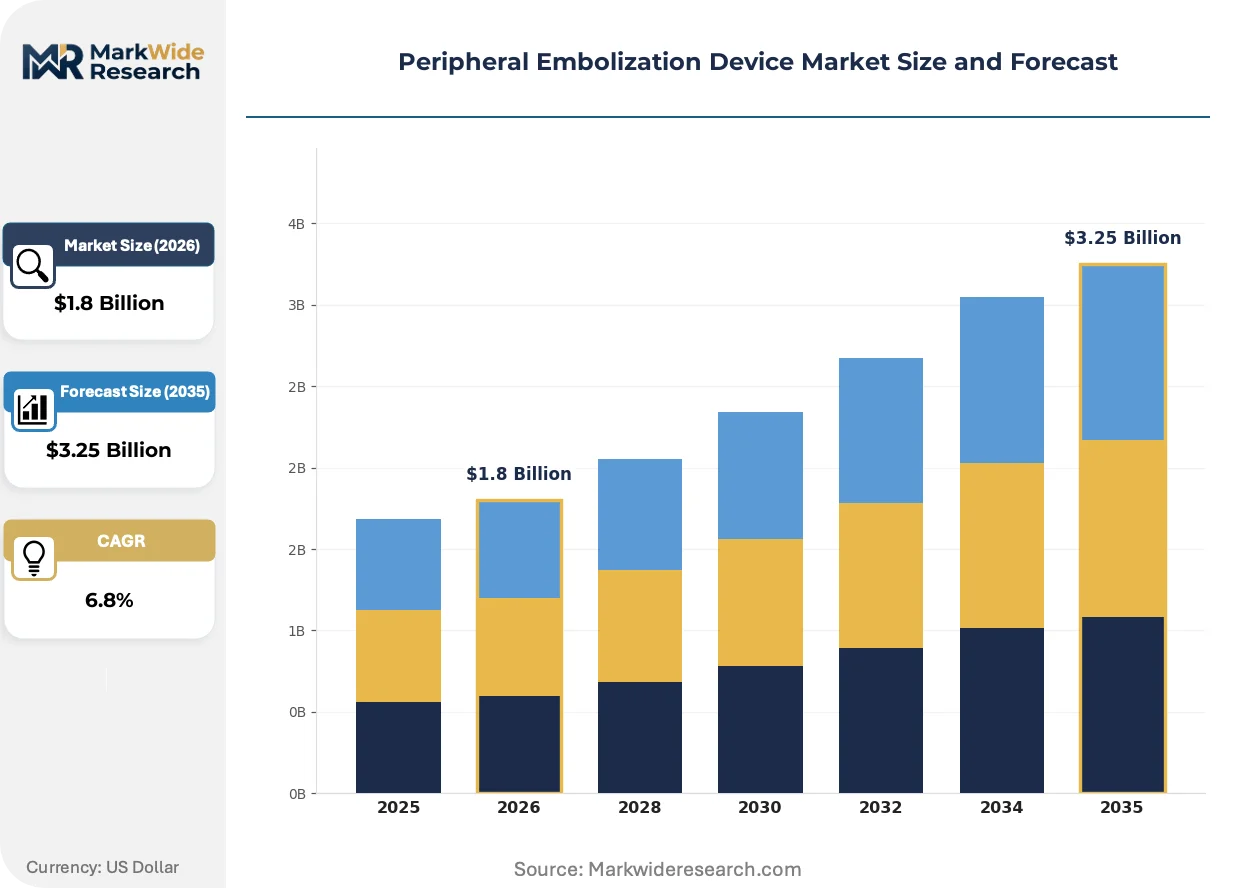
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
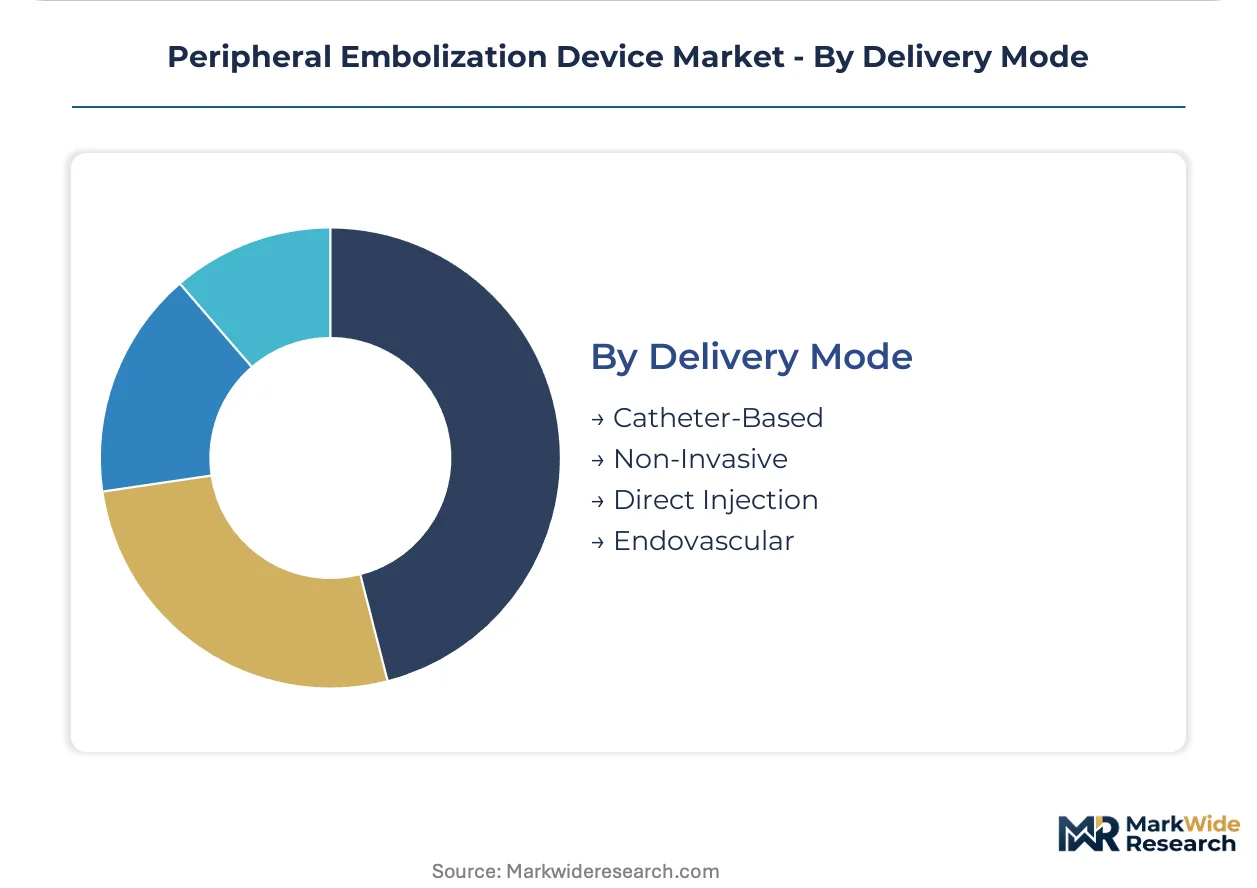
| Segmentation | Product Type: Coils, Particles, Gelatin, Liquid Embolic Agents Application: Vascular Malformations, Uterine Fibroids, Tumor Embolization, AVMs End User: Hospitals, Clinics, Ambulatory Surgical Centers, Imaging Centers Delivery Mode: Catheter-Based, Non-Invasive, Direct Injection, Endovascular |
| Companies Covered | Terumo Corporation, Stryker Corporation, Boston Scientific Corporation, Abbott Laboratories, Johnson & Johnson (DePuy Synthes), Medtronic, Penumbra, Merit Medical Systems, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Embolization Device Market Evolving Landscape
Digital twin technologies are virtualizing procedural planning workflows, compressing the gap between diagnostic imaging and therapeutic intervention while reshaping how embolization cases are prepared and executed across hospital systems.
Flow-diverting stent technology is virtualizing traditional coil-based aneurysm treatment paradigms by enabling parent vessel reconstruction without dense packing. Academic medical centers with advanced neurointerventional programs are adopting these platforms for complex posterior circulation aneurysms previously managed with open surgical clipping. The structural consequence is a procedural volume redistribution that is virtualizing the coil market's historical dominance in intracranial applications.
The FDA's enhanced premarket review pathways for permanent implantable devices are elevating clinical evidence standards across the device class. Manufacturers are responding by investing in prospective registry infrastructure and patient-level outcomes tracking systems. Liquid embolic agents without long-term implant surveillance data face the steepest compliance burden, compressing development timelines for novel formulations.
Hospital procurement consolidation is concentrating purchasing authority within integrated delivery network supply chain executives, displacing individual physician preference as the primary vendor selection mechanism. Device manufacturers are restructuring commercial organizations around enterprise contracting teams with data analytics capabilities. This behavioral shift is most visible in United States metropolitan markets where three-hospital-system mergers have created regional procurement monopolies.
Peripheral Embolization Device Market Segmentation
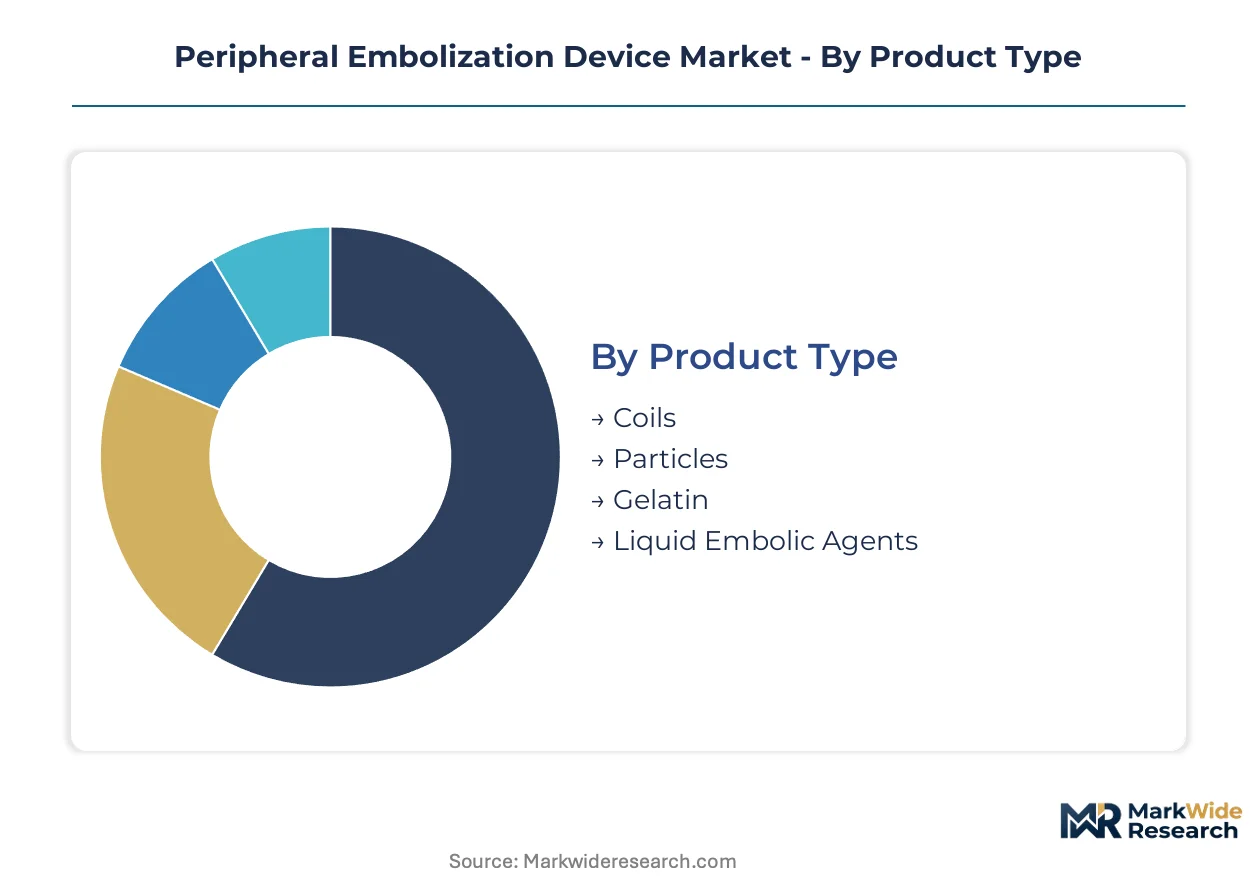
Peripheral embolization device segmentation reveals distinct procurement patterns across product categories, with after-sales service intensity varying sharply between permanent implants and consumable agents. Hospital supply chain executives prioritize vendor technical support for complex catheter-embolic system integration, while outpatient settings favor low-touch replenishment models.
Product Type:
After-sales service intensity peaks with coil systems requiring specialized technical field support for inventory management and procedural troubleshooting, while liquid embolic agents demand minimal ongoing vendor interaction beyond initial training certification.
- Coils:Platinum-tungsten alloy constructs deliver permanent mechanical occlusion through catheter deployment, with helical and complex framing configurations engineered for aneurysm neck bridging. Demand concentrates in United States academic medical centers where neurointerventional programs require 24/7 technical field coverage and consignment inventory programs. The FDA's Class III controls elevate service intensity through mandatory complaint handling and device retrieval protocols.
- Liquid Embolic Agents:N-butyl cyanoacrylate and ethylene vinyl alcohol copolymer formulations polymerize on vascular contact to achieve nidus penetration beyond coil reach. Demand is accelerating fastest in German and Japanese tertiary centers treating complex arteriovenous malformations previously deemed untreatable. Catheter compatibility requirements create sticky vendor relationships with intensive upfront training and lower ongoing service touchpoints.
- Particles:Polyvinyl alcohol and tris-acryl gelatin microspheres provide calibrated temporary occlusion for tumor devascularization and pre-operative embolization.
- Gelatin:Resorbable temporary occlusive agents serve trauma and pediatric applications requiring vessel recanalization.
By volume, coils lead. By growth pace, liquid embolic agents are ahead.
Application:
Cost tier stratification separates premium-priced tumor embolization from high-volume uterine fibroid procedures, with reimbursement differentials driving site-of-service decisions and device configuration preferences.
- Tumor Embolization:Hepatocellular carcinoma and renal cell carcinoma interventions command premium pricing through specialized microcatheter systems and calibrated particle sizing. Demand concentrates in United States hospital outpatient departments where CMS bundled payments reward same-day discharge protocols. Interventional radiology service line expansion at Mayo Clinic, MD Anderson, and Cleveland Clinic anchors procedural volume.
- Uterine Fibroids:Uterine artery embolization represents the largest outpatient volume driver, with procedure standardization enabling ambulatory surgical center migration. United States metropolitan markets with integrated delivery network consolidation show fastest adoption of same-day discharge protocols. Patient preference for fertility-preserving alternatives to hysterectomy sustains procedural growth.
- Vascular Malformations:Complex congenital and acquired anomalies require multidisciplinary management at specialized centers.
- AVMs:Arteriovenous malformation nidus embolization demands liquid agent expertise and extended procedural times.
By revenue contribution, tumor embolization leads. By procedure count, uterine fibroids are expanding most quickly.
End User:
Customer type determines procurement authority concentration, with integrated delivery networks centralizing purchasing decisions while individual physician preference persists in independent imaging centers.
- Hospitals:Academic medical centers and community hospitals capture high-complexity embolizations requiring overnight observation capabilities. United States hospital outpatient departments dominate coil-based aneurysm and trauma procedures through established reimbursement pathways. Enterprise-wide contracting with Terumo, Merit Medical, and Cook Medical displaces site-level vendor relationships.
- Ambulatory Surgical Centers:Freestanding facilities specialize in standardized uterine fibroid and select tumor embolizations with predictable recovery profiles. United States ASCs exploit site-of-service payment differentials under Medicare's Hospital Outpatient Prospective Payment System. Vendor-managed inventory platforms with automated consumption tracking reduce supply chain overhead.
- Clinics:Office-based settings handle diagnostic angiography and minor embolization procedures.
- Imaging Centers:Diagnostic facilities with interventional capabilities perform venous access and minor embolization services.
By capital equipment investment, hospitals lead. By volume growth rate, ambulatory surgical centers are climbing the fastest.
Delivery Mode:
Supply concentration in catheter manufacturing creates integration dependencies, with liquid embolic efficacy hinging on precise compatibility between delivery platform and embolic material viscosity profiles.
- Catheter-Based:Microcatheter and balloon catheter systems enable superselective vessel access for precise embolic deposition. Demand concentrates in German, Japanese, and United States centers with advanced neurointerventional programs. Terumo's interventional systems portfolio bundles catheter and embolic offerings to lock in hospital procurement contracts.
- Endovascular:Transfemoral and transradial access approaches dominate peripheral embolization, with radial adoption accelerating in East Asian markets for patient comfort advantages. Catheter-embolic system integration requirements complicate supply chain management and clinical training standardization across multi-site health systems.
- Direct Injection:Percutaneous needle access serves superficial vascular malformations and trauma applications.
- Non-Invasive:External beam and focused ultrasound alternatives compete for select vascular indications.
By procedural volume, catheter-based delivery leads. By technology trajectory, endovascular approaches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-Saint Paul logistics corridor anchors United States distribution for platinum-tungsten coil shipments to academic medical centers. German interventional radiology training networks extend reach across Central European tertiary centers through standardized fellowship curricula.
United States
Hospital outpatient departments capture the majority of high-complexity embolization procedures through established CMS reimbursement pathways. The FDA's Class II/III device controls govern permanent implantable coils and liquid embolic agents. Mayo Clinic in Rochester, Minnesota anchors procedural volume for tumor embolization with dedicated interventional radiology service lines.
Germany
Tertiary centers in Munich and Heidelberg drive liquid embolic agent adoption for complex arteriovenous malformation treatment. The EU MDR imposes strengthened clinical evidence requirements for embolic agents marketed in Europe. The Rhine-Main metropolitan cluster concentrates catheter manufacturing capabilities with integrated delivery system production.
Japan
Transradial access adoption accelerates in Tokyo and Osaka metropolitan markets for patient comfort advantages in peripheral procedures. The PMDA maintains stringent post-market surveillance for permanent implantable devices. The Kanto region's academic medical centers concentrate neurointerventional training capacity and high-volume AVM referral networks.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex embolization procedures at designated tertiary centers in London and Manchester. The MHRA aligns with EU MDR requirements for clinical evidence standards post-Brexit transition. The Oxford-Cambridge-London golden triangle anchors medical device regulatory consulting and clinical trial infrastructure.
China
Domestic catheter manufacturing scales in the Yangtze River Delta to serve hospital procurement consolidation across provincial health systems. The NMPA accelerates review pathways for innovative interventional devices through priority review channels. Shanghai's Ruijin Hospital and Beijing's Peking Union Medical College Hospital anchor interventional radiology training and high-complexity procedural volume.
Peripheral Embolization Device Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and catheter manufacturing. The market structures around three tiers: multinational conglomerates with interventional portfolios, mid-cap device specialists with focused embolic offerings, and regional manufacturers supplying standard coil configurations. Competitive positioning hinges on catheter-embolic system integration, enterprise contracting scale, and regulatory dossier depth. Consolidation pressures favor acquisition of liquid embolic technology platforms and catheter compatibility portfolios.
Among Japan-based platform integrators, Terumo Corporation occupies a position spanning catheter systems and embolic agents. Stryker Corporation and Boston Scientific Corporation exemplify the multinational conglomerate tier with broad interventional portfolios. Merit Medical Systems and Cook Medical represent the mid-cap specialist archetype with focused embolic configurations and direct hospital sales organizations.
| Leading Market Players |
|---|
| Terumo Corporation |
| Stryker Corporation |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Johnson & Johnson (DePuy Synthes) |
| Medtronic |
| Penumbra |
| Merit Medical Systems |
| Cook Medical |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta's catheter manufacturing cluster exerts outsized leverage over downstream device pricing through integrated production of microcatheter systems and embolic delivery platforms. Hospital procurement consolidation across United States integrated delivery networks has shifted bargaining power toward enterprise supply chain executives, compressing vendor margins on standard coil configurations while preserving premium pricing for complex liquid embolic systems.
Pricing Analysis
Volume-discount tiering structures dominate hospital system contracting, with platinum-tungsten coils commanding premium pricing through consignment inventory programs and 24/7 technical field support bundling. Price differentiation rests on FDA Class III certification status and catheter-embolic system integration depth. Cost compression in standard helical coil configurations is intensifying because integrated delivery networks are consolidating vendor contracts across multi-site footprints. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare site-of-service payment differentials, while academic medical centers prioritize technical service intensity over unit cost.
Supply Chain Analysis
Contract manufacturing concentration resides with East Asian metallurgical suppliers specializing in platinum-tungsten alloy refining and German precision catheter foundries serving neurointerventional platforms. Geographic supply concentration centers on China, Japan, and Germany for critical components. Raw material dependencies include platinum-group metals, polyvinyl alcohol polymers, and N-butyl cyanoacrylate monomers. Single-source vulnerability in specialized alloy supply exposes device makers to input cost volatility. Distribution runs through integrated delivery network vendor-managed inventory platforms with automated consumption tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where catheter-embolic system integration is displacing standalone component procurement across hospital systems. Interoperability lock-in between delivery platforms and embolic materials is restructuring competitive moats around ecosystem control rather than individual product performance.
For Market Incumbents: Build regulatory dossier depth as the primary moat by accelerating EU MDR technical documentation investment and real-world evidence generation infrastructure. Consolidate position through backward integration into platinum-tungsten alloy supply to mitigate East Asian refining concentration risk. Expand direct hospital sales teams covering outpatient and inpatient settings to capture enterprise contracting authority migration.
For New Entrants and Emerging Players: Bioresorbable embolic materials for trauma and pediatric applications represent the most penetrable entry point given programmable resorption timelines and absence of established incumbents. Liquid embolic agent formulations with novel polymerization kinetics targeting complex AVM nidus penetration offer second white-space opportunity. Pursue academic medical center partnership go-to-market model to secure training certification pathways and procedural volume anchoring.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because catheter-embolic system integration requirements favor platform breadth over point-solution depth. Acquisition target archetype: mid-cap liquid embolic technology platforms with catheter compatibility portfolios and established European notified body relationships. Monitor CMS outpatient procedure bundling decisions as inflection signal for site-of-service volume redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Class II/III premarket review pathways govern permanent implantable coils and liquid embolic agents. |
| CE Marking Pathway | EU MDR strengthened clinical evidence requirements elevate barriers for novel material introductions. |
| Hospital System Partnership | Enterprise-wide contracting with integrated delivery networks displaces site-level vendor relationships. |
| Software Companion Development | Digital twin technologies virtualize procedural planning workflows between diagnostic imaging and intervention. |
| Reimbursement Strategy | CMS site-of-service economics redirect uterine fibroid embolizations to hospital outpatient departments. |
Research Methodology
A spread of perspectives from interventional radiologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Demand-supply-balance framing shaped the forecast architecture, with procedural volume growth rates calibrated against interventional radiology fellowship pipeline capacity constraints and integrated delivery network service line expansion plans. Segmentation dimensions modeled include product type, application, end user, and delivery mode, with regional regulatory cluster effects layered across the projection horizon. CAGRs derived from procedure volume elasticity to reimbursement rate changes and technology substitution patterns.
Practitioners should monitor platinum-tungsten alloy spot price movements, EU notified body certification backlog duration, and CMS outpatient procedure bundling rulemaking for early signals of forecast revision. Forecasts reflect assumptions about interventional radiology workforce expansion and integrated delivery network consolidation trajectories. Quarterly review of hospital procurement contract announcements and MDR technical documentation approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
South Korea ECG Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
PET Injectors Market
Medical Devices
Global Pacemakers Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Critical Care Devices Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Contraceptive Rings Market
Medical Devices
Spinal Fusion Market
Medical Devices
Global Mobile C-Arm Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Double-Lumen Biliary Catheters Market