
 South Korea Drug Delivery Devices Market | 2026-2036
South Korea Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Drug Delivery Devices Market Analytics
Oncology and diabetes care is shifting toward self-administered biologics in South Korea, pulling device specifications toward higher precision and patient-controlled delivery. Baxter International anchors its position through captive supply of infusion pump platforms for hospital networks. Johnson & Johnson differentiates via R&D intensity in transdermal microneedle systems. Terumo Corporation leverages its geographic dominance in Seoul-based manufacturing to control regional distribution channels.
Drug delivery devices encompass engineered systems that administer therapeutic agents through controlled release kinetics, incorporating specifications such as flow-rate accuracy within five percent variance and biocompatible polymer construction for sustained-release formulations. These systems serve commercial purposes by enabling patient adherence, dose optimization, and reduction of healthcare facility utilization. Injectable delivery mode occupies the largest revenue pool given biologics penetration, while smart device technology represents the fastest-expanding segment as connectivity enables real-time dosing feedback and remote patient monitoring integration.
MFDS, the Ministry of Food and Drug Safety, mandates clinical evidence standards for combination products that blend drug and device functions, shaping product development timelines and market access requirements. The Korean Agency for Technology and Standards enforces electrical safety and electromagnetic compatibility for connected delivery systems, filtering entrants without in-house compliance capabilities. Stakeholders must monitor evolving software-as-medical-device classifications under MFDS guidance to anticipate regulatory scope expansion affecting smart inhalers and app-integrated pumps.
Market Dynamics
Biologics manufacturing expansion in South Korea is compressing device development cycles as pharmaceutical producers demand integrated combination products with accelerated regulatory pathways.
Growth Catalysts
- MFDS Accelerated Approval Pathways:The Ministry of Food and Drug Safety's streamlined review for combination products reduces commercialization timelines, incentivizing domestic pharmaceutical investment in advanced delivery systems.
- Seoul-Incheon Corridor Concentration:Contract development organizations cluster in this metropolitan zone, creating dense supplier networks that shorten prototype-to-production intervals for device manufacturers.
- Self-Administered Biologics Adoption:Oncology and diabetes therapeutic categories are shifting toward patient-controlled delivery, pulling specifications toward higher-precision flow-rate mechanisms and ergonomic designs.
Market Restraints
- Biocompatible Polymer Input Volatility:Specialized polymer feedstocks for sustained-release formulations face price instability due to concentrated global supply of medical-grade resins.
- Electromagnetic Compliance Burden:The Korean Agency for Technology and Standards enforces stringent electrical safety and EMC standards that filter entrants lacking in-house testing infrastructure.
- Software-as-Medical-Device Scope Expansion:Evolving MFDS guidance on connected device classifications creates regulatory friction for smart inhaler and app-integrated pump developers uncertain of compliance boundaries.
Strategic Opportunities
- Busan-Ulsan Manufacturing Belt:Underutilized industrial capacity in these southeastern port cities offers cost-advantaged production sites for device assembly and sterilization operations.
- Remote Patient Monitoring Convergence:Integration of real-time dosing feedback with hospital information systems creates white space for connectivity-enabled pump platforms in chronic disease management.
- Transdermal Microneedle Applications:Vaccine delivery and hormone replacement therapy segments present expansion vectors for minimally invasive delivery technologies beyond traditional injectable routes.
Industry Challenges
- Combination Product Talent Scarcity:Cross-functional expertise spanning pharmaceutical formulation and mechanical engineering remains concentrated among a small cohort of domestic specialists.
- Legacy Hospital System Integration:New connected devices must interface with established infusion pump networks and electronic health record architectures, complicating deployment workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Drug Delivery Devices Market |
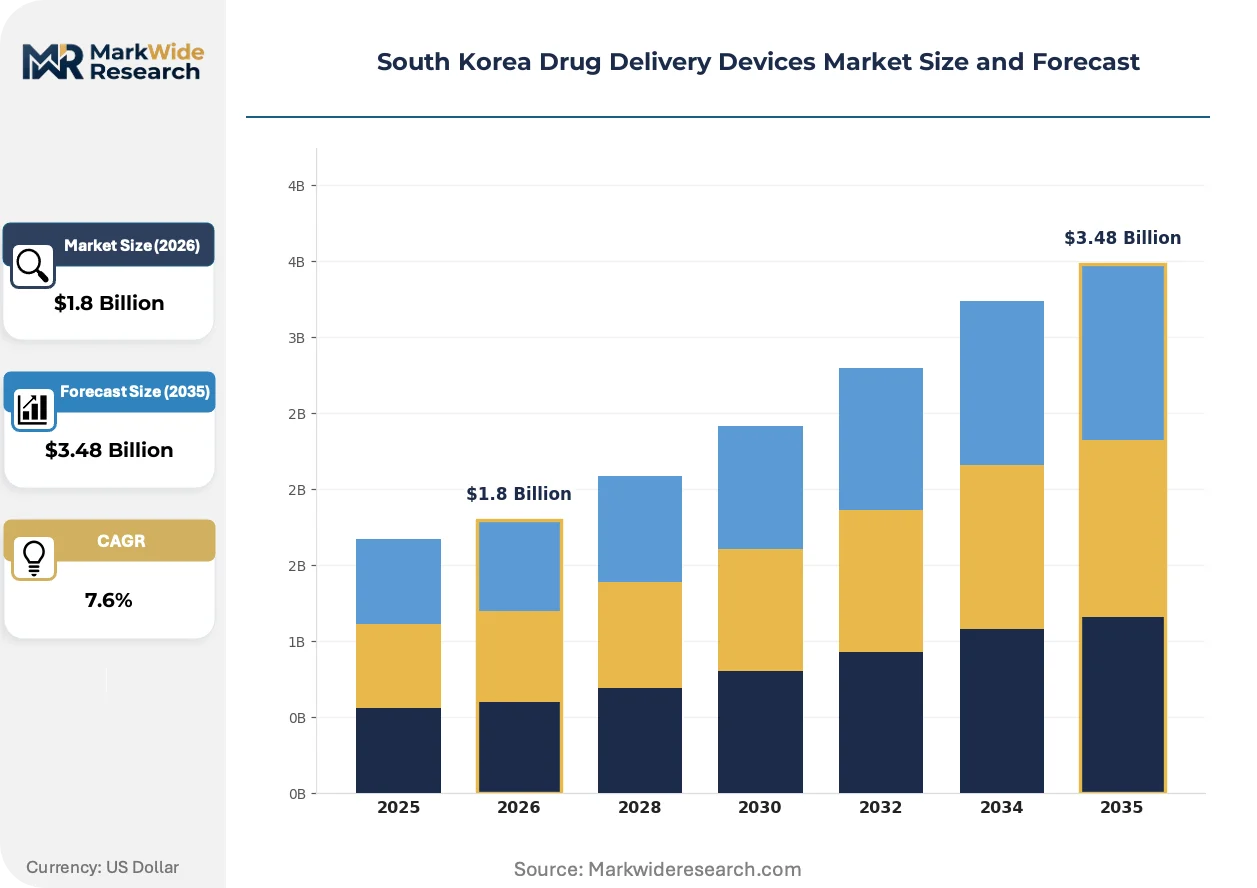
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Syringes, Inhalers, Infusion Pumps, Microneedles Delivery Mode: Injectable, Oral, Transdermal, Inhalation End User: Hospitals, Homecare, Clinics, Pharmacies Technology: Smart Devices, Nanotechnology, Biodegradable Systems, Conventional Devices |
| Companies Covered | Baxter International, Johnson & Johnson, Terumo Corporation, Becton, Dickinson and Company, Solventum, Medtronic, Roche Holding AG, Pfizer Inc., Novartis AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Drug Delivery Devices Market Evolving Landscape
Connectivity architectures and precision manufacturing methods are actively redefining device specifications as South Korean healthcare infrastructure digitizes and biologics portfolios expand.
Microneedle array technology is absorbing manufacturing investment from domestic pharmaceutical producers seeking alternatives to conventional hypodermic delivery for macromolecule therapeutics. Dermatology and vaccine development units at Seoul-based research hospitals are piloting ceramic and dissolvable polymer formulations. This absorption is compressing development timelines for transdermal platforms previously considered niche.
MFDS guidance on software-as-medical-device classifications is tightening evidentiary requirements for algorithm-driven dosing systems in connected inhalers and insulin pumps. Device manufacturers must now submit clinical validation data for embedded control software previously treated as ancillary. Smart pump developers in the Seoul metropolitan area are restructuring quality management systems to accommodate this scope expansion.
Hospital procurement committees are consolidating vendor relationships around full-service platform providers capable of supplying infusion systems, maintenance contracts, and training protocols through single-source agreements. This concentration displaces fragmented purchasing of disposable components from multiple suppliers. The shift is most visible in tertiary care networks within the Seoul-Incheon corridor where standardization reduces clinical training overhead.
South Korea Drug Delivery Devices Market Segmentation
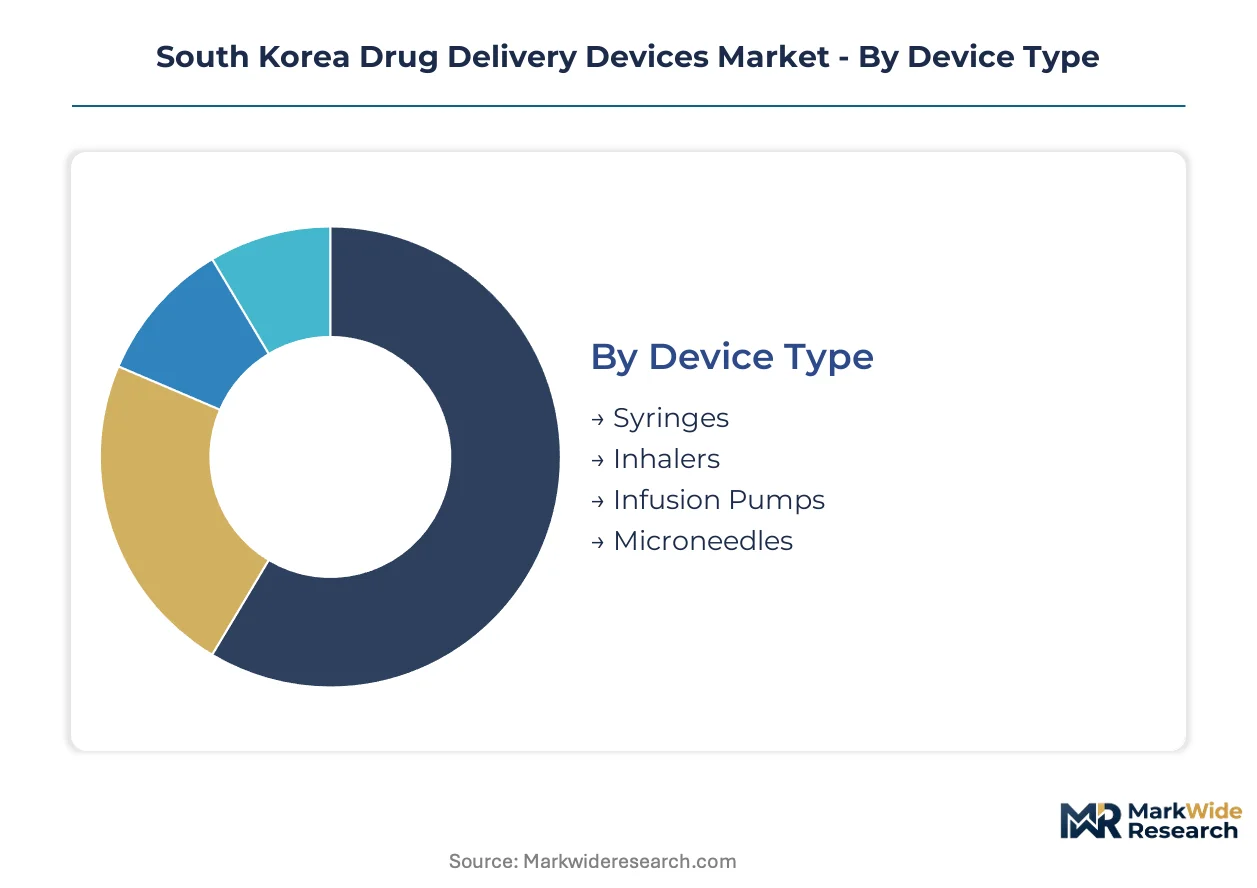
Segmentation in the South Korea drug delivery devices market reveals how biologics manufacturing priorities and MFDS regulatory pathways reshape procurement patterns across device categories. Understanding these divisions exposes where pharmaceutical producers concentrate investment and where compliance requirements filter market participation.
Device Type:
Infusion pumps command premium positioning through precision flow-rate specifications, while syringes dominate unit volume across hospital and homecare channels.
- Syringes:Glass and polymer-barrel configurations with Luer-lock compatibility serve as the foundational delivery mechanism for biologics administration. Demand concentrates in Seoul-Incheon hospital networks where standardization reduces clinical training overhead, though price pressure from centralized procurement limits margin expansion.
- Infusion Pumps:Electronic and elastomeric platforms deliver programmable flow rates with five-percent variance tolerance for oncology and diabetes therapeutics. Seoul-based tertiary care centers drive specification requirements toward connectivity-enabled models that integrate with hospital information systems, compressing replacement cycles for legacy equipment.
- Inhalers:Pressurized metered-dose and dry-powder devices administer respiratory therapeutics through pulmonary deposition mechanisms.
- Microneedles:Dissolvable polymer and ceramic arrays enable transdermal macromolecule delivery for vaccine and hormone applications.
Today's leader: Infusion pumps. Tomorrow's challenger: Microneedles.
Delivery Mode:
Injectable routes absorb the majority of biologics-focused investment, while transdermal platforms gain development attention from domestic pharmaceutical producers seeking patient adherence improvements.
- Injectable:Subcutaneous and intravenous administration via prefilled syringes and pen injectors remains the dominant commercial channel for monoclonal antibodies and insulin analogs. Contract development organizations in the Seoul-Incheon corridor concentrate prototype-to-production capacity here, shortening development timelines for combination products seeking MFDS accelerated approval.
- Transdermal:Microneedle arrays and iontophoretic systems bypass hepatic first-pass metabolism for macromolecule delivery previously limited to parenteral routes. Research hospitals in Seoul pilot ceramic formulations for vaccine applications, pulling manufacturing investment from conventional hypodermic suppliers.
- Oral:Enteric-coated and sustained-release formulations address small-molecule therapeutics with patient convenience advantages.
- Inhalation:Pulmonary deposition systems target respiratory and systemic delivery through alveolar absorption.
Injectable platforms anchor current revenue; transdermal technologies are climbing the fastest as domestic biologics producers diversify delivery portfolios.
End User:
Hospital procurement committees consolidate purchasing power, while homecare channels expand with self-administered biologics adoption in oncology and diabetes management.
- Hospitals:Tertiary care networks in Seoul, Busan, and Daegu drive demand for infusion pumps and connected delivery systems through single-source vendor agreements. MFDS electrical safety requirements filter supplier participation, concentrating relationships around full-service platform providers capable of maintenance contracts and clinical training protocols.
- Homecare:Patient-controlled delivery devices for insulin and biologics expand with aging demographics and chronic disease prevalence. Ergonomic design specifications and remote monitoring integration distinguish competitive offerings in this channel.
- Clinics:Outpatient facilities require portable and disposable delivery systems for intermittent therapeutic administration.
- Pharmacies:Retail channels distribute prefilled pen injectors and inhalers for prescription fulfillment and patient self-management.
Hospital networks currently dominate procurement volume; homecare represents the steepest expansion trajectory as therapeutic categories shift toward patient-controlled administration.
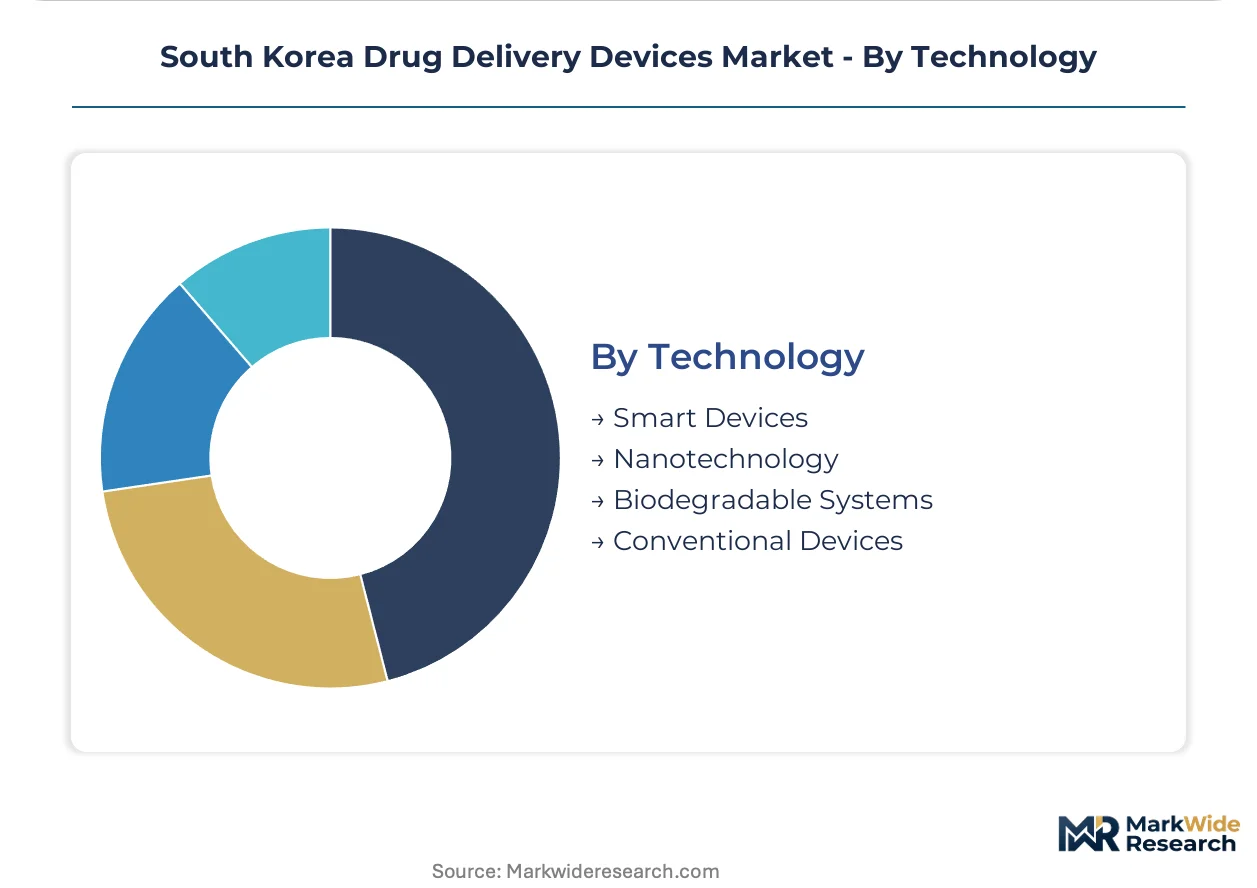
Technology:
Smart device architectures attract regulatory scrutiny under evolving MFDS software-as-medical-device guidance, while conventional platforms retain cost advantages in price-sensitive procurement segments.
- Smart Devices:Connectivity-enabled pumps and inhalers embed sensors, algorithms, and wireless transmission for real-time dosing feedback and remote patient monitoring. MFDS tightened evidentiary requirements for embedded control software, forcing Seoul metropolitan developers to restructure quality management systems and submit clinical validation data previously treated as ancillary.
- Biodegradable Systems:Dissolvable microneedles and polymer-based sustained-release depots eliminate retrieval procedures and improve patient compliance. Domestic pharmaceutical producers absorb manufacturing investment here as alternatives to conventional hypodermic delivery gain regulatory traction.
- Nanotechnology:Liposomal and polymeric nanoparticle carriers enhance bioavailability and targeted delivery for oncology applications.
- Conventional Devices:Mechanical pumps, standard syringes, and passive inhalers without electronic components serve cost-optimized procurement segments.
Conventional devices hold present volume leadership; smart platforms are gaining share fastest as hospital digitization and remote monitoring integration reshape purchasing criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as device manufacturers migrate toward jurisdictions offering streamlined compliance pathways and concentrated supplier networks. Cost-of-compliance gaps between mature and emerging manufacturing hubs are accelerating facility relocation decisions.
Seoul Capital Area
Biologics contract manufacturing and connected device R&D concentrate in the Seoul-Incheon corridor where MFDS accelerated approval pathways compress commercialization timelines. The Korean Agency for Technology and Standards enforces electrical safety standards that filter supplier participation, concentrating relationships around full-service platform providers. Samsung Medical Center and Seoul National University Hospital pilot smart pump integrations that reshape procurement specifications for tertiary care networks.
Busan-Ulsan Manufacturing Belt
Underutilized industrial capacity in these southeastern port cities attracts cost-advantaged assembly and sterilization operations from device producers seeking alternatives to Seoul-area overhead. The Korea Free Economic Zone Authority offers tax incentives for medical device manufacturing facilities locating in Busan. Ulsan's petrochemical infrastructure supplies specialized polymer feedstocks for sustained-release formulation components.
Daegu-Gyeongbuk
Textile and materials science expertise from the region's traditional industries transfers into biodegradable polymer development for microneedle applications. Kyungpook National University Hospital collaborates with domestic pharmaceutical producers on transdermal delivery pilots. The Daegu Medical Device Industry Cluster hosts sterilization and packaging operations serving Seoul-based device developers.
Daejeon-Sejong
Government research institutions including the Korea Institute of Science and Technology anchor preclinical testing capabilities for combination products. The Sejong administrative city hosts MFDS headquarters, creating proximity advantages for regulatory consultation and submission preparation. Device developers locate regulatory affairs functions here to accelerate pathway navigation.
Gwangju-Honam
Agricultural biotechnology expertise from the Honam region's research institutes transfers into biocompatible polymer sourcing for sustained-release applications. The Gwangju Institute of Science and Technology maintains active programs in biomaterials engineering. Regional producers supply medical-grade resins to device manufacturers in the Seoul corridor.
South Korea Drug Delivery Devices Market Competitive Landscape
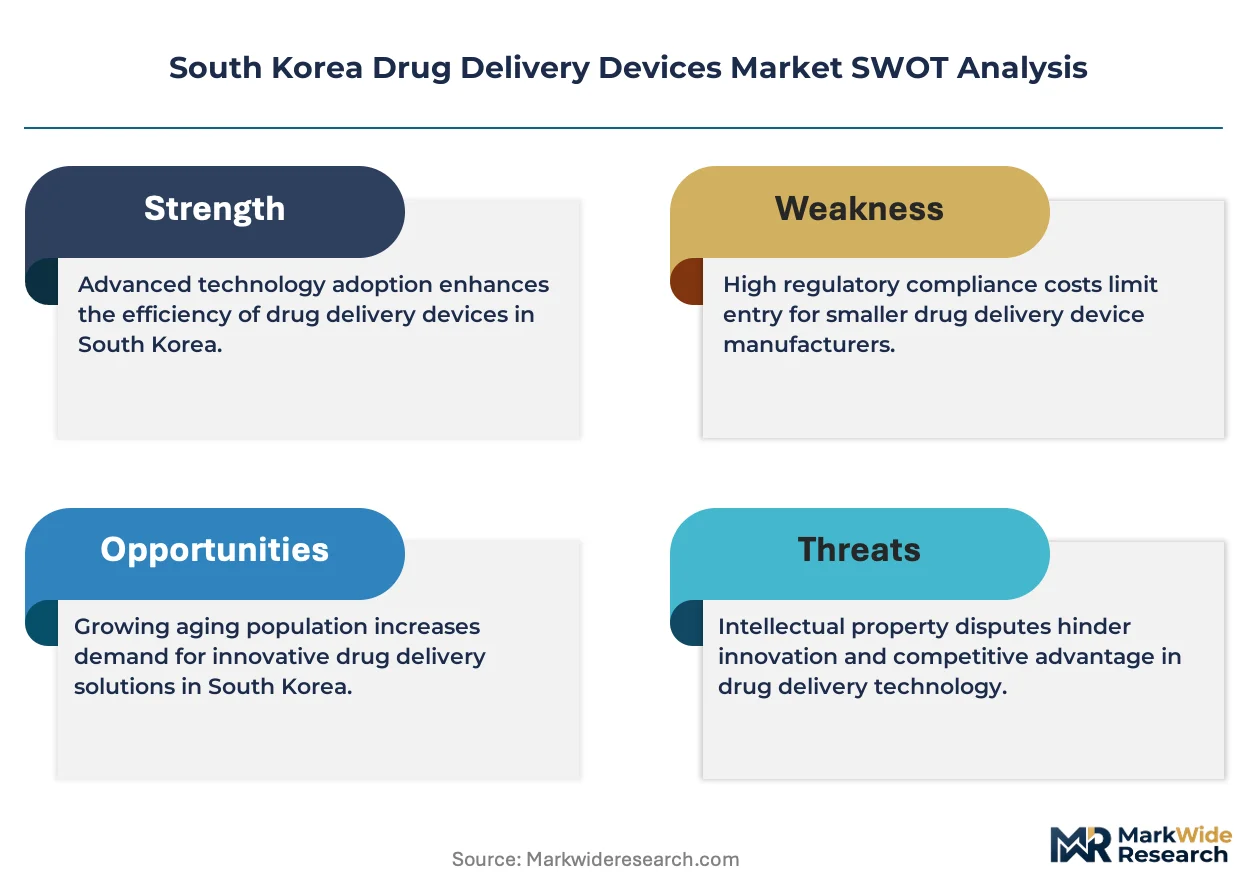
Strategic partnerships dominate the current landscape as device manufacturers align with biologics producers to secure combination product pipelines. The market structure consolidates around full-service platform providers capable of supplying infusion systems, maintenance contracts, and training protocols through single-source agreements. Three archetypes define participation: multinational medical technology conglomerates with captive hospital relationships, specialized infusion pump developers with connectivity expertise, and contract manufacturers serving domestic pharmaceutical producers. M&A activity and technology licensing agreements represent the primary competitive vectors as firms seek integrated capabilities spanning mechanical engineering and pharmaceutical formulation.
Among multinational medical technology conglomerates, Baxter International and Johnson & Johnson occupy positions exemplifying the full-service platform archetype, while Terumo Corporation represents geographic proximity advantages in Seoul-based manufacturing. These entities anchor procurement relationships with tertiary care networks through bundled offerings that combine hardware, software, and clinical training. Domestic contract manufacturers and emerging connectivity specialists sit within a fragmented tier below, competing on development cycle compression and MFDS pathway expertise rather than scale.
| Leading Market Players |
|---|
| Baxter International |
| Johnson & Johnson |
| Terumo Corporation |
| Becton, Dickinson and Company |
| Solventum |
| Medtronic |
| Roche Holding AG |
| Pfizer Inc. |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
Medical-grade polymer feedstocks move from Ulsan petrochemical complexes through Seoul-based compounders before reaching device manufacturers, with each transfer point layering cost premiums that stratify final pricing across hospital procurement tiers.
Pricing Analysis
Distributor margins compress as Seoul-Incheon hospital networks consolidate purchasing through single-source vendor agreements. Three-tier pricing structure across premium connectivity-enabled pumps, standard elastomeric platforms, and economy mechanical syringes reflects certification grade and after-sales service bundling. Pricing pressure stems from centralized GPO negotiations that demand multi-year maintenance contracts as table stakes. Homecare channels exhibit highest price sensitivity due to out-of-pocket patient exposure, while tertiary care networks prioritize total cost of ownership over unit price.
Supply Chain Analysis
Refurbishment flows for infusion pump electronics concentrate in the Seoul Capital Area, creating reverse-logistics hubs that extend equipment lifecycles and depress new-unit demand. Component sourcing draws from Japan for precision sensors, Germany for medical-grade polymers, and domestic Ulsan facilities for base resins. Single-source vulnerability sits with specialized ceramic microneedle substrates from limited Asian suppliers. Distribution runs through captive service networks maintained by Baxter, Johnson & Johnson, and Terumo rather than independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea drug delivery devices market functions as a geographic-arbitrage play where Busan-Ulsan assembly costs undercut Seoul-area production by fifteen to twenty percent before logistics, while MFDS proximity in Sejong accelerates regulatory timelines versus offshore submission routes.
For Market Incumbents: Deploy captive service network expansion to lock out emerging connectivity specialists before they achieve critical mass in hospital information system integrations. Consolidate maintenance contract portfolios across Seoul-Incheon tertiary networks to raise switching costs for procurement committees evaluating multi-vendor alternatives. Counter transdermic microneedle substitutes by accelerating biologics-compatible pump platform iterations through Seoul-based R&D partnerships. For New Entrants and Emerging Players: Regional hospital networks outside Seoul-Incheon present underserved buyer archetypes where incumbent service coverage remains thin and price sensitivity runs higher than tertiary centers. Penetrate Daegu-Gyeongbuk and Gwangju-Honam clusters through sterilization outsourcing partnerships that reduce capital requirements. Lead with software-as-medical-device compliance expertise to differentiate against legacy manufacturers restructuring quality systems under expanded MFDS guidance. For Investors and Strategic Acquirers: Consolidation pressure builds where combination product talent scarcity concentrates among domestic specialists capable of spanning pharmaceutical formulation and mechanical engineering disciplines. Long-term viability favors platform providers with integrated hardware-software-service stacks over component suppliers facing commoditization. Monitor MFDS software-as-medical-device enforcement patterns as inflection indicator for smart device valuation premiums versus conventional equipment.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Accelerated Approval Pathway | Compresses commercialization timelines for Seoul-based combination product developers seeking first-mover positioning. |
| Hospital System Partnership | Locks in multi-year single-source agreements with Seoul National University Hospital and Samsung Medical Center networks. |
| Software Companion Development | Enables real-time dosing feedback integration with hospital information systems under tightened MFDS evidentiary requirements. |
| Backward Integration into Polymer Compounding | Secures medical-grade resin supply from Ulsan petrochemical infrastructure against feedstock volatility. |
| Reimbursement Strategy | Aligns connected pump connectivity features with National Health Insurance Service coverage criteria for chronic disease management. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with device engineering directors, MFDS regulatory consultants, hospital biomedical equipment managers, and GPO contract administrators with secondary validation against MFDS submission databases, Korean Agency for Technology and Standards certification registries, and hospital procurement disclosure filings. Bottom-up device shipment estimates triangulated against top-down biologics production volume projections from Seoul-Incheon contract manufacturing organizations.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-acceleration digitization trends across the modeling period. Segmentation dimensions modeled include device type, delivery mode, end-user channel, and technology tier, with additional cross-cutting analysis by MFDS regulatory pathway cluster. CAGRs derived from spline interpolation between anchor points with industry-specific adjustments for biologics pipeline expansion rates and connected device adoption curves.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around pricing tier estimates. Forecasts reflect documented assumptions regarding MFDS guidance stability and biocompatible polymer supply continuity. Practitioners should monitor MFDS software-as-medical-device reclassification announcements and Busan-Ulsan industrial zone incentive modifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Australia Medtech Market
Medical Devices
Digital Intraoral Camera Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Global Electrophysiology Devices Market