
 3D and 4D Ultrasound Devices Market | 2026-2036
3D and 4D Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
3D and 4D Ultrasound Devices Market Analysis
Chinese ultrasound component manufacturing is shifting toward higher-end transducer arrays and FPGA-based beamforming chipsets. GE HealthCare leverages captive semiconductor sourcing to sustain margin control across its cart-based portfolio. Siemens Healthineers anchors European hospital procurement through integrated PACS connectivity. Koninklijke Philips N.V. competes on portable system battery density and wireless probe architectures.
3D and 4D ultrasound devices generate volumetric anatomical reconstructions from phased-array piezoelectric crystals operating at 2-15 MHz, with 4D adding real-time temporal rendering for fetal movement and cardiac valve analysis. Cart-based ultrasound systems occupy the dominant revenue position due to premium transducer channel counts and institutional procurement cycles. Portable ultrasound is gaining fastest among mobile imaging services and point-of-care emergency departments where maneuverability outweighs raw image resolution.
FDA 510(k) pathways govern software-as-medical-device upgrades for AI-assisted image segmentation, while CE marking under the EU MDR imposes stricter clinical evidence requirements on new 4D obstetric applications. The EPA and RoHS frameworks constrain piezoelectric material selection, particularly lead-based ceramics in transducer manufacturing. Stakeholders must monitor regulatory divergence between FDA's predicate-device approach and MDR's clinical performance benchmarks when planning multi-territory product rollouts.
Market Dynamics
Cart-based ultrasound systems face procurement pressure from hospital capital committees prioritizing AI-enhanced diagnostic workflows over hardware channel counts. This shift compresses upgrade cycles and reconfigures vendor relationships around software subscription economics rather than equipment replacement.
Growth Catalysts
- AI-assisted image segmentation:FDA 510(k) clearance pathways for software-as-medical-device upgrades accelerate feature deployment without full hardware recertification. Radiology departments integrate automated fetal biometry and cardiac valve tracking into existing cart-based installations.
- Obstetric imaging demand:Maternal-fetal medicine specialists in the United States specify 4D real-time temporal rendering for fetal movement assessment. Hospital procurement budgets favor premium 4D configurations over base 3D systems.
- FPGA-based beamforming:Chinese component manufacturing advances higher-end transducer arrays and programmable logic chipsets. Captive semiconductor sourcing sustains margin control for integrated device manufacturers.
Market Restraints
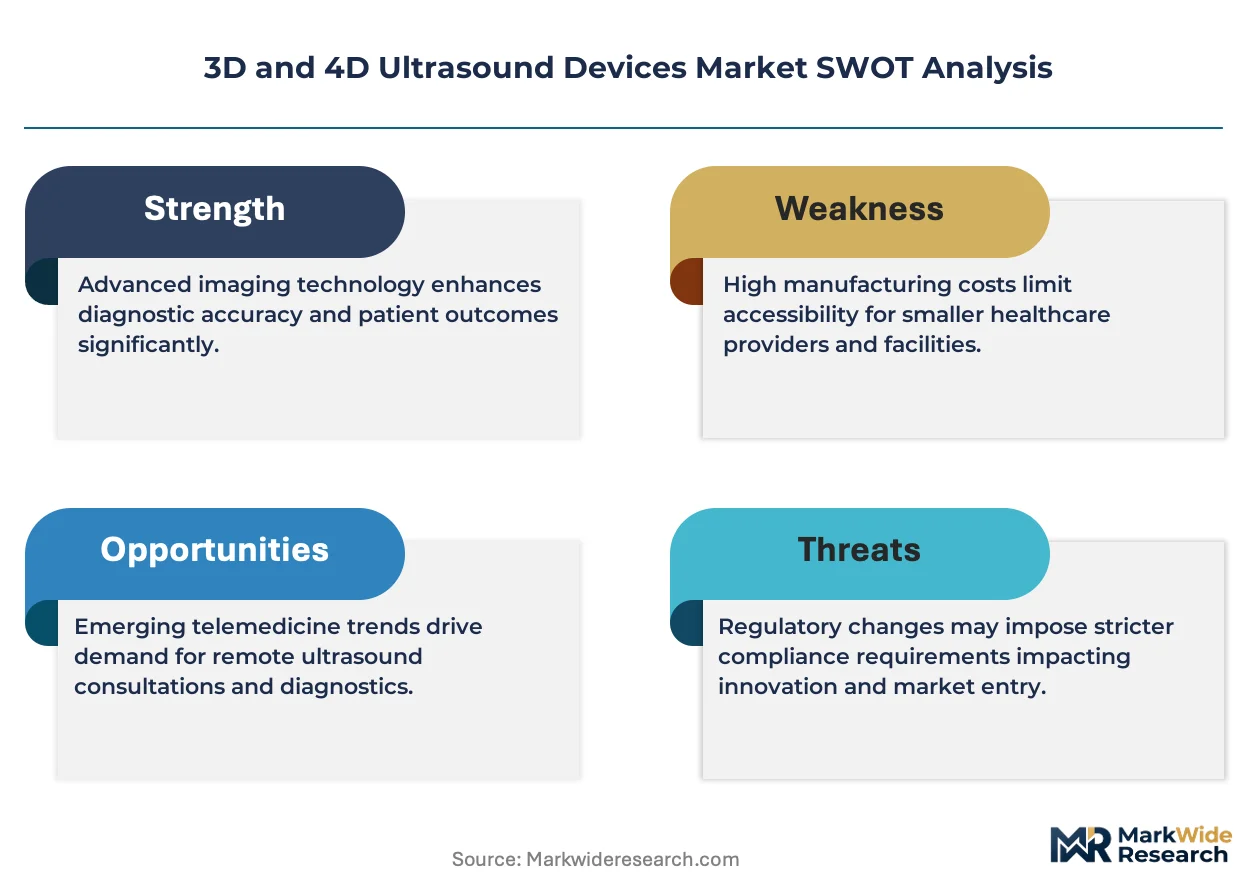
- Lead-based ceramic constraints:EPA and RoHS frameworks restrict piezoelectric material selection in transducer manufacturing. Alternative crystal formulations raise unit input costs without matching acoustic impedance performance.
- EU MDR clinical evidence requirements:CE marking imposes stricter performance benchmarks on new 4D obstetric applications than FDA predicate-device pathways. Multi-territory rollouts face timeline divergence and redundant trial expenditure.
- Portable resolution trade-offs:Battery density limitations in wireless probe architectures constrain channel counts versus cart-based systems. Mobile imaging services accept maneuverability gains at the cost of volumetric reconstruction fidelity.
Strategic Opportunities
- Emergency department point-of-care expansion:Underserved hospital departments seek rapid cardiac and trauma assessment without radiology queue delays. Wireless probe architectures penetrate acute care settings previously reserved for cart-based deployment.
- PACS connectivity integration:European hospital procurement favors vendors offering seamless DICOM routing and cloud storage handoffs. Siemens Healthineers anchors institutional contracts through embedded IT infrastructure compatibility.
- Battery chemistry advancement:Lithium-silicon anode development extends portable system operating duration beyond current lithium-ion limits. Philips competes on wireless probe uptime metrics in mobile diagnostic services.
Industry Challenges
- Regulatory divergence management:Stakeholders must reconcile FDA's predicate-device approach with MDR's clinical performance benchmarks. Quality assurance teams maintain parallel documentation systems for identical hardware configurations.
- Transducer array calibration complexity:Phased-array piezoelectric crystals operating at 2-15 MHz require precision alignment protocols. Field service engineers face extended training curves for volumetric reconstruction troubleshooting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D and 4D Ultrasound Devices Market |
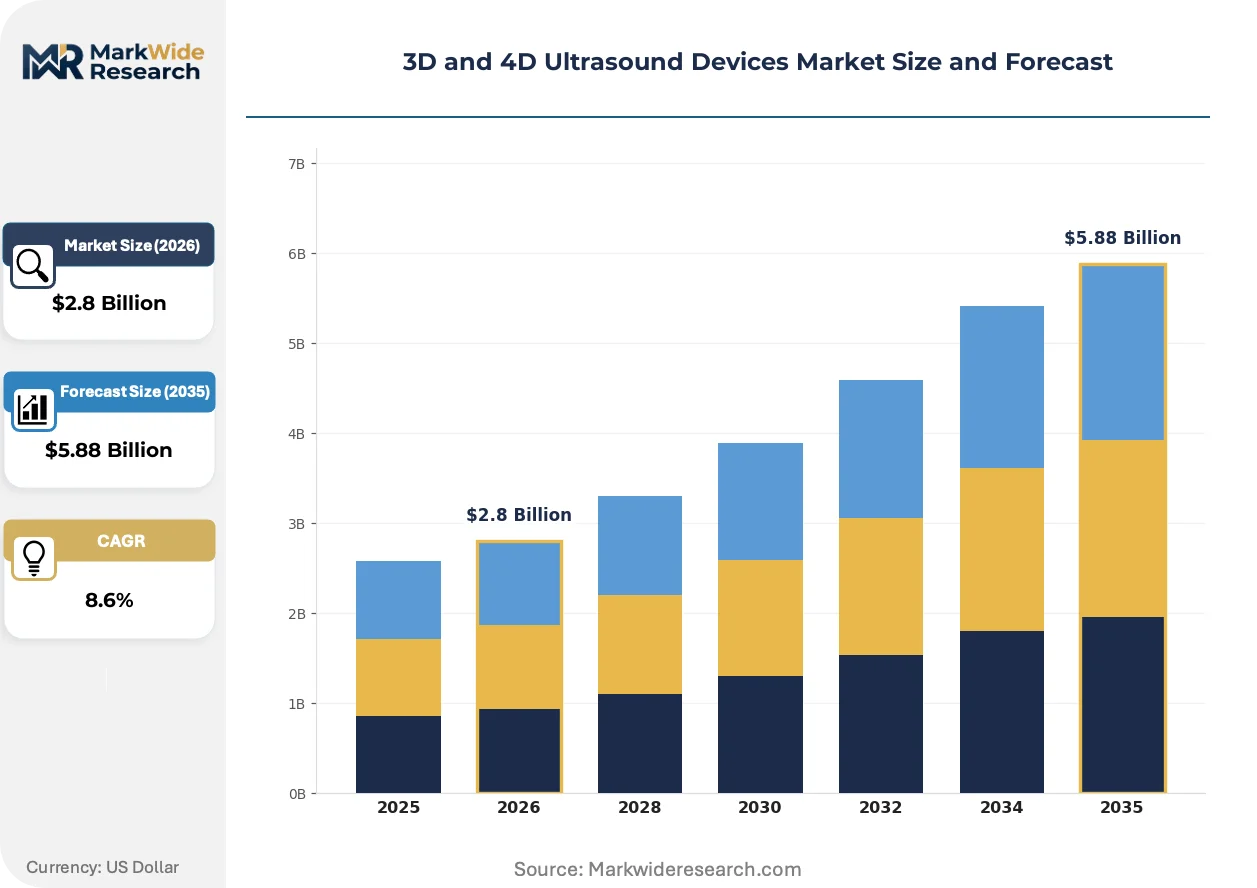
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Cart-based Ultrasound, Handheld Ultrasound, Transducers End User: Hospitals, Diagnostic Clinics, Mobile Imaging Services, Research Institutions Technology: Ultrasound Tomography, Harmonic Imaging, Doppler Imaging, Contrast-enhanced Ultrasound Application: Obstetrics, Cardiology, Urology, Abdominal Imaging |
| Companies Covered | Mindray Medical International Limited, Siemens Healthineers, GE HealthCare, Esaote S.p.A., Hitachi Medical Corporation, Koninklijke Philips N.V., FUJIFILM Corporation, Samsung Electronics, Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D and 4D Ultrasound Devices Market Emerging Trajectories
Real-time volumetric rendering and automated diagnostic assistance are compressing the skill gap between specialized sonographers and generalist practitioners. Hardware commoditization pushes competitive differentiation toward software-enabled clinical decision support.
Convolutional neural networks trained on fetal anatomical datasets are automating standard plane detection and biometric measurement extraction. Maternal-fetal medicine clinics in the United States deploy these tools to reduce examination time variability between operators. The technology is automating routine screening workflows and redirecting specialist attention toward complex anomaly cases.
MDR clinical evidence requirements for 4D obstetric applications impose prospective trial obligations absent from FDA predicate pathways. European notified bodies demand longitudinal safety data for real-time temporal rendering in first-trimester protocols. Manufacturers with existing FDA clearances face duplicate investment to access EU hospital procurement channels.
Hospital capital committees unbundle after-sales service contracts from equipment purchase agreements. Third-party technical service organizations compete for preventive maintenance and transducer replacement revenue previously captured by original equipment manufacturers. This pattern concentrates in the United States where health system consolidation creates centralized procurement leverage against vendor service pricing.
3D and 4D Ultrasound Devices Market Segmentation
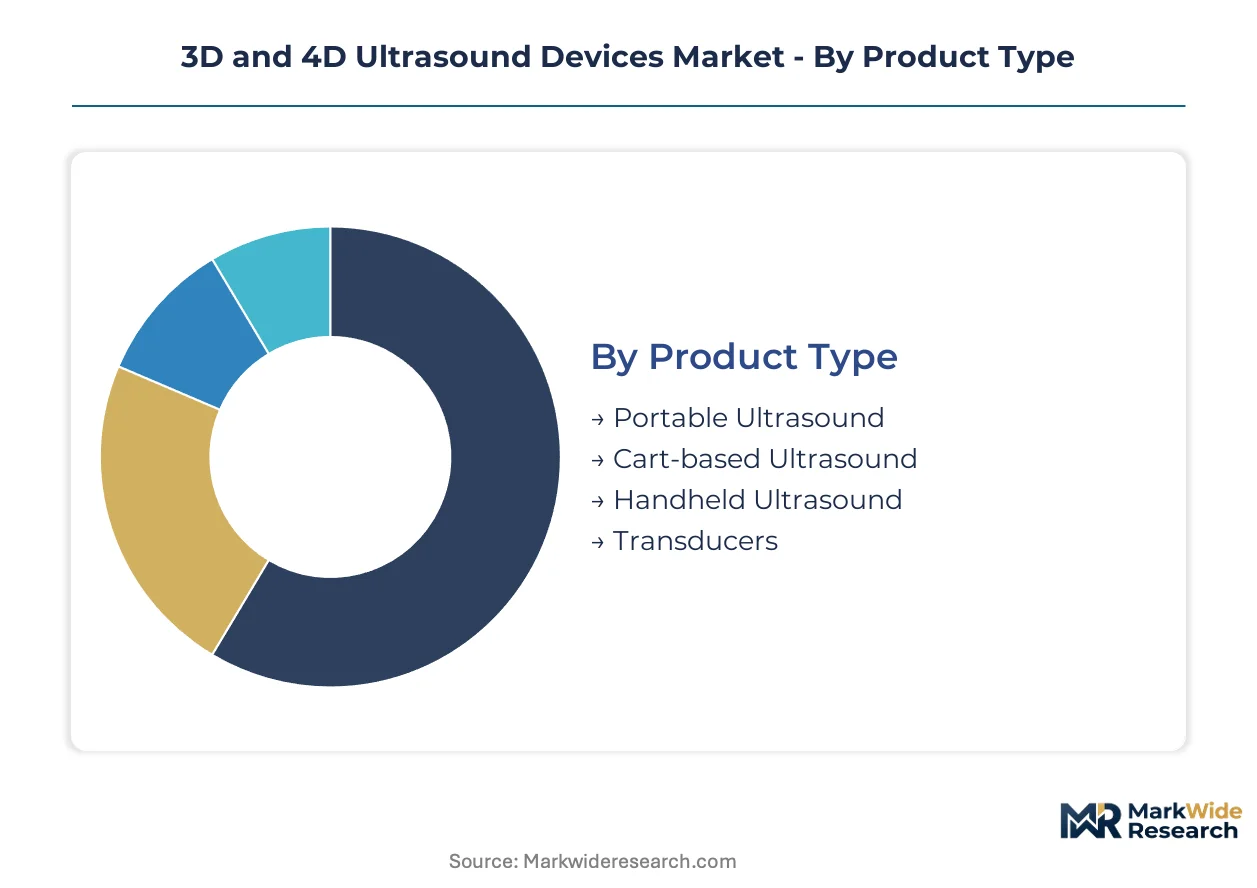
Segmentation in 3D and 4D ultrasound devices reveals divergent upgrade economics across hardware configurations and clinical settings. Procurement committees weight channel counts against AI-enabled software subscriptions differently by facility type, reshaping vendor pricing architecture.
Product Type:
Upgrade cycles compress where AI-enhanced diagnostics offset hardware replacement, favoring modular system architectures over full-platform swaps.
- Cart-based Ultrasound:Stationary systems integrate 128-512 channel transducer arrays with FPGA-based beamforming chipsets for volumetric reconstruction fidelity. United States hospital procurement budgets concentrate here for maternal-fetal medicine suites, prioritizing real-time 4D temporal rendering over portable maneuverability.
- Portable Ultrasound:Battery-powered units with lithium-silicon anode development extend operating duration for mobile diagnostic services. Emergency departments in acute care settings adopt these for rapid cardiac assessment without radiology queue delays, accepting resolution trade-offs for point-of-care speed.
- Handheld Ultrasound:Wireless probe architectures penetrate underserved hospital departments previously reserved for cart-based deployment.
- Transducers:Phased-array piezoelectric crystals at 2-15 MHz require precision calibration protocols and drive recurring replacement revenue.
Cart-based Ultrasound sits at the top of the volume ranking, with Portable Ultrasound climbing the fastest.
End User:
Customer concentration patterns follow capital availability and procedure reimbursement rates across facility tiers.
- Hospitals:Institutional procurement cycles favor premium 4D configurations with integrated PACS connectivity and DICOM routing. Maternal-fetal medicine specialists specify real-time fetal movement assessment capabilities, compressing upgrade timelines through software subscription economics.
- Diagnostic Clinics:Independent imaging centers prioritize throughput metrics and examination time variability reduction through automated biometry tools.
- Mobile Imaging Services:Maneuverability requirements drive wireless probe adoption for bedside and remote deployment.
- Research Institutions:Clinical trial obligations for EU MDR compliance generate demand for longitudinal safety data collection systems.
Hospitals capture the dominant procurement volume, while Mobile Imaging Services expand most quickly.
Technology:
Functional differentiation shifts competitive positioning toward algorithmic enhancement rather than raw acoustic specification.
- Doppler Imaging:Velocity measurement of blood flow and cardiac valve motion enables functional assessment beyond anatomical structure. Cardiology departments integrate automated valve tracking into existing installations, reducing operator-dependent variability.
- Harmonic Imaging:Frequency-domain signal processing improves tissue contrast resolution at depth, particularly for abdominal imaging protocols.
- Contrast-enhanced Ultrasound:Microbubble agent compatibility expands vascular and perfusion assessment applications.
- Ultrasound Tomography:Computed reconstruction algorithms generate cross-sectional anatomical datasets for research applications.
Doppler Imaging holds the widest installed base, with Harmonic Imaging gaining share fastest in premium system configurations.
Application:
Procedure reimbursement codes and clinical evidence requirements shape demand concentration across specialty areas.
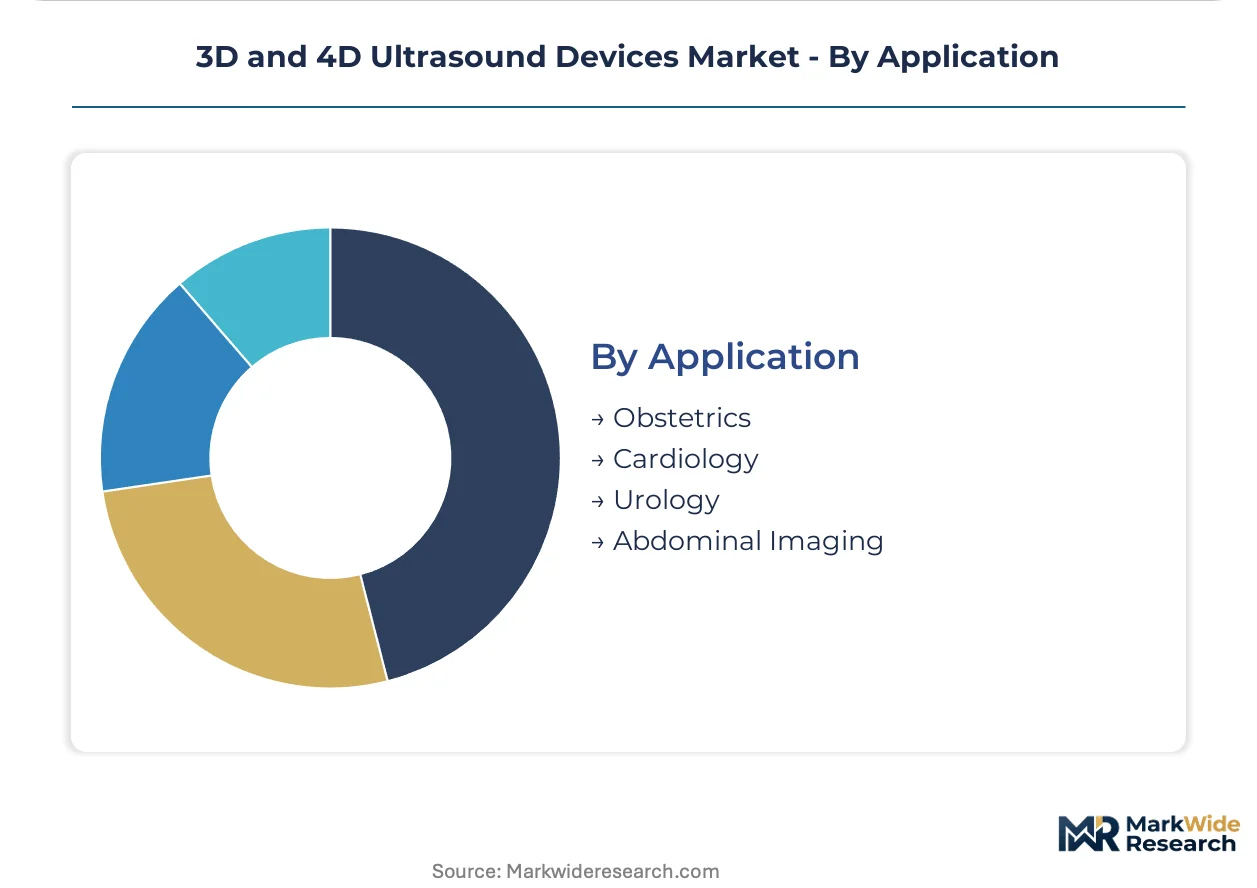
- Obstetrics:4D real-time temporal rendering for fetal movement assessment commands premium pricing in United States maternal-fetal medicine. FDA 510(k) pathways for AI-assisted fetal biometry accelerate feature deployment without full hardware recertification.
- Cardiology:Stress echocardiography and valve assessment protocols drive Doppler imaging specification in hospital cardiology departments.
- Abdominal Imaging:Liver, renal, and gastrointestinal applications leverage harmonic imaging for deep tissue penetration.
- Urology:Prostate and renal imaging applications concentrate in diagnostic clinic settings with focused procedure volumes.
Obstetrics leads application revenue, with Cardiology showing the steepest expansion trajectory on aging population cardiac monitoring demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EPA and RoHS constraints on lead-based ceramics drive component sourcing toward jurisdictions with harmonized environmental standards. Production migration follows cost-of-compliance gaps between FDA predicate pathways and EU MDR clinical evidence requirements.
United States
Maternal-fetal medicine specialists command premium 4D configurations for real-time fetal movement assessment. FDA 510(k) pathways compress software upgrade timelines without full hardware recertification. Hospital procurement in the Northeast Corridor favors integrated PACS connectivity and AI-enhanced diagnostic workflows.
Germany
European hospital procurement anchors on embedded IT infrastructure compatibility and seamless DICOM routing. CE marking under EU MDR imposes stricter clinical evidence benchmarks for 4D obstetric applications than FDA equivalents. The Baden-Württemberg medical technology cluster concentrates beamforming chipset development and transducer calibration expertise.
China
Domestic manufacturing shifts toward higher-end transducer arrays and FPGA-based beamforming chipsets. NMPA regulatory pathways accommodate faster iteration cycles for AI-enhanced ultrasound software. Shenzhen and Shanghai industrial zones house captive semiconductor sourcing operations sustaining margin control for integrated device manufacturers.
Japan
PMDA oversight maintains rigorous post-market surveillance for volumetric reconstruction devices. METI industrial policy supports lithium-silicon anode development extending portable system operating duration. The Nagoya-Chubu corridor concentrates precision alignment protocols for phased-array piezoelectric crystals.
India
Diagnostic clinic expansion drives demand for automated biometry tools reducing examination time variability. CDSCO regulatory frameworks are aligning with international standards for software-as-medical-device classifications. The Maharashtra-Gujarat pharmaceutical-industrial corridor attracts mobile imaging services targeting underserved hospital departments.
3D and 4D Ultrasound Devices Market Vendor Landscape
United States and European producers anchor the premium-tier cart-based segment; Chinese specialists hold component supply positions. The vendor structure concentrates around integrated device manufacturers with captive semiconductor sourcing and diversified conglomerates with imaging portfolios spanning multiple modalities. Three archetypes dominate: full-platform developers with software subscription economics, component specialists controlling transducer array manufacturing, and diversified electronics conglomerates leveraging display and battery technologies. Competitive moves center on M&A for AI software capabilities and strategic partnerships for PACS connectivity integration.
Among diversified health technology conglomerates, GE HealthCare and Siemens Healthineers exemplify the integrated-platform archetype with embedded IT infrastructure positioning. Koninklijke Philips N.V. occupies a distinct tier competing on portable system architectures and wireless probe uptime metrics. Chinese specialists including Mindray Medical International Limited represent the component-to-system vertical trajectory in higher-end transducer arrays.
| Leading Market Players |
|---|
| Mindray Medical International Limited |
| Siemens Healthineers |
| GE HealthCare |
| Esaote S.p.A. |
| Hitachi Medical Corporation |
| Koninklijke Philips N.V. |
| FUJIFILM Corporation |
| Samsung Electronics |
| Canon Medical Systems Corporation |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committees in the United States now unbundle after-sales service contracts from equipment purchase agreements, forcing original equipment manufacturers to compete with third-party technical service organizations for preventive maintenance and transducer replacement revenue. This buyer consolidation trend compresses vendor margin capture across the installed base and redirects pricing power toward centralized health system procurement leverage.
Pricing Analysis
Distributor margins in the cart-based ultrasound segment typically range from 15-22 percent for premium 4D configurations, while direct-to-hospital contracts for portable systems command steeper volume discounts. Pricing stratifies across premium, standard, and economy tiers based on transducer channel counts and AI software subscription bundling. Cost compression in the portable segment is intensifying because battery chemistry advancements and Chinese FPGA sourcing reduce hardware differentiation. Mobile imaging services exhibit the highest price sensitivity, whereas maternal-fetal medicine suites in academic medical centers prioritize real-time 4D temporal rendering capabilities over unit cost.
Supply Chain Analysis
Refurbishment flows for cart-based ultrasound systems extend equipment lifecycles through certified pre-owned programs, with remanufactured transducers capturing recurring replacement revenue streams. Manufacturing concentrates in China for higher-end transducer arrays and FPGA-based beamforming chipsets, in Germany for precision calibration equipment, and in Japan for lithium-silicon battery anode development. Raw material dependencies include lead-free piezoelectric ceramics, rare-earth elements for transducer crystals, and semiconductor-grade silicon for programmable logic devices. Single-source vulnerability in lead-free ceramic formulations creates supply risk as EPA and RoHS frameworks constrain traditional lead-based alternatives. Distribution runs through regional medical device distributors with GPO contracting relationships for hospital system penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D and 4D ultrasound devices market functions as a geographic-arbitrage play where manufacturers exploit the cost-of-compliance gap between FDA predicate-device pathways and EU MDR clinical evidence requirements. Production migration toward Chinese industrial zones with harmonized environmental standards captures margin relief from RoHS-constrained piezoelectric material sourcing.
For Market Incumbents: Deploy captive semiconductor sourcing to sustain margin control across cart-based portfolios as hospital procurement shifts toward AI-enhanced software subscriptions over hardware replacement cycles. Consolidate service contract capture through embedded PACS connectivity and DICOM routing integration that third-party technical organizations cannot replicate. Counter the threat of portable system displacement by accelerating lithium-silicon battery chemistry advancement for wireless probe uptime metrics. For New Entrants and Emerging Players: AI-assisted fetal biometry algorithms offer a technology-first wedge into maternal-fetal medicine clinics seeking examination time variability reduction. The emergency department point-of-care segment presents the most penetrable white-space target, with underserved hospital departments accepting resolution trade-offs for rapid cardiac assessment without radiology queue delays. Pursue go-to-market positioning through wireless probe architectures with battery density specifications exceeding current lithium-ion limits. For Investors and Strategic Acquirers: Asymmetric upside sits with component specialists controlling higher-end transducer array manufacturing and FPGA-based beamforming chipset development. Long-term viability across the analysis window favors integrated device manufacturers with backward integration into semiconductor sourcing rather than pure-play software vendors vulnerable to hardware commoditization. Monitor FDA 510(k) clearance velocity for AI-enhanced ultrasound software as an inflection indicator for feature deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements for 4D obstetric applications impose stricter performance benchmarks than FDA equivalents. |
| Hospital System Partnership | Siemens Healthineers anchors European procurement through embedded IT infrastructure and seamless DICOM routing compatibility. |
| Software Companion Development | Convolutional neural networks trained on fetal anatomical datasets automate standard plane detection and biometric measurement extraction. |
| Backward Integration | GE HealthCare leverages captive semiconductor sourcing to sustain margin control across cart-based portfolio configurations. |
| Reimbursement Strategy | Maternal-fetal medicine specialists in United States academic centers command premium 4D configurations for real-time fetal movement assessment. |
Methodological Framework
Multiple input streams — primary interviews with maternal-fetal medicine specialists and hospital purchasing committees, secondary validation through FDA 510(k) filings and EU MDR notified body documentation, and trade data on piezoelectric ceramic imports — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included biomedical engineers managing transducer calibration protocols, GPO contracts managers overseeing health system procurement consolidation, and regulatory affairs leads navigating predicate-device versus clinical performance benchmark divergence. Secondary sources encompassed hospital procurement databases tracking cart-based versus portable system specifications, CMS Medicare reimbursement code analysis for obstetric imaging procedures, and customs records of FPGA beamforming chipset trade flows.
Historical shipment data was cross-referenced against panel input from device manufacturers and component suppliers to anchor volume projections across the analysis window. Segmentation dimensions modeled include product type hierarchy, end-user facility tier, technology functional differentiation, and application specialty area with reimbursement code clustering. CAGRs were derived from weighted average growth contributions across these segments, with specific inputs from lithium-silicon battery chemistry advancement timelines and NMPA regulatory pathway iteration cycles for AI-enhanced software.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between FDA and EU MDR frameworks, lead-free piezoelectric ceramic formulation breakthroughs, and hospital capital committee prioritization shifts. Practitioners should monitor FDA 510(k) clearance velocity for AI-assisted image segmentation, EU notified body backlog for 4D obstetric application reviews, and health system consolidation announcements for centralized procurement leverage indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
Pleural Catheters Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Embolization Plugs Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Smart Bassinet Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Peripheral Micro Catheters Market