
 Japan Aesthetic Devices Market | 2026-2036
Japan Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Aesthetic Devices Market Foresight
JIS T 0601 certification for medical electrical equipment is bifurcating the competitive landscape between established domestic distributors and foreign manufacturers seeking Ministry of Health, Labour and Welfare clearance. AbbVie leverages its Allergan Aesthetics portfolio to sustain premium positioning in injectable platforms across Japan's major metropolitan clinics. Cynosure LLC competes through specialized laser systems designed for East Asian skin phototypes, while Alma Lasers anchors its presence with multi-technology platforms that integrate radiofrequency and light therapy modalities.
Japan aesthetic devices comprise electromechanical and energy-delivery systems engineered to modify skin, adipose tissue, or hair follicles through controlled thermal, optical, or mechanical action, typically operating at wavelengths between 532 nm and 10,600 nm or radiofrequencies in the 0.5–40 MHz range for tissue coagulation and collagen remodeling. These systems serve commercial medical aesthetics providers seeking outpatient alternatives to surgical intervention with reduced recovery intervals. Laser devices and radiofrequency platforms command the dominant installed base, while non-invasive technology adoption outpaces minimally invasive alternatives as Japanese consumers prioritize treatment sessions without anesthesia or downtime. Dermatology centers represent the fastest-growing end-user channel, capturing margin pools that spas and traditional beauty salons cannot access due to physician-supervision requirements.
PMDA's pharmaceutical and medical device review standards govern premarket approval timelines, while METI oversees industrial standards compliance and the Ministry of Health, Labour and Welfare sets reimbursement boundaries that determine which procedures clinics can profitably offer. These regulatory layers shape demand by restricting certain energy-based devices to physician-operated settings and creating certification cost barriers for smaller importers. Stakeholders must monitor PMDA's evolving guidance on software-controlled aesthetic platforms and METI's potential harmonization with IEC 60601 international standards to anticipate which product categories will face accelerated or delayed market entry.
Market Dynamics
METI's reimbursement recalibration is compressing clinic margins while simultaneously unlocking capital flows toward physician-supervised energy-based platforms, creating a bifurcation between high-throughput dermatology centers and constrained spa operators.
Growth Catalysts
- Aging Demographics:Japan's over-65 population density in Tokyo and Osaka metropolitan corridors sustains outpatient demand for skin tightening and adipose reduction without surgical recovery periods.
- PMDA Streamlining:The pharmaceutical and medical device agency's software-as-medical-device guidance is accelerating clearance timelines for algorithm-controlled aesthetic platforms.
- JIS T 0601 Harmonization:Convergence with IEC 60601 international electrical safety standards is reducing recertification costs for imported multi-technology systems.
Market Restraints
- Import Dependency:Critical optical components and RF generators concentrate among German and Israeli suppliers, exposing procurement to currency volatility and shipping friction.
- Physician Supervision Mandates:Ministry of Health, Labour and Welfare restrictions on laser operating privileges limit addressable clinic density and cap spa channel penetration.
- Capital Intensity:Energy-based platforms requiring 20-40 million yen per unit deployment strain independent dermatology practices against hospital-affiliated chains.
Strategic Opportunities
- Fukuoka Cluster Expansion:Kyushu's underpenetrated aesthetic device installed base offers first-mover positioning ahead of metropolitan saturation.
- Combination Therapy Convergence:Integrated platforms merging fractional laser with bipolar radiofrequency are capturing premium positioning in collagen remodeling protocols.
- Subscription Servitization:Per-treatment leasing models are displacing outright capital expenditure for mid-tier clinic operators seeking technology refresh flexibility.
Industry Challenges
- Technician Certification Bottlenecks:PMDA-mandated operator training hours for Class IV laser systems constrain workforce scalability across expanding clinic networks.
- Legacy System Integration:New energy-based platforms face interoperability friction with existing patient management software and electronic health record architectures.
- Patent Thicket Navigation:Dense intellectual property layering around fractional delivery mechanisms and cooling technologies complicates new entrant product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Aesthetic Devices Market |
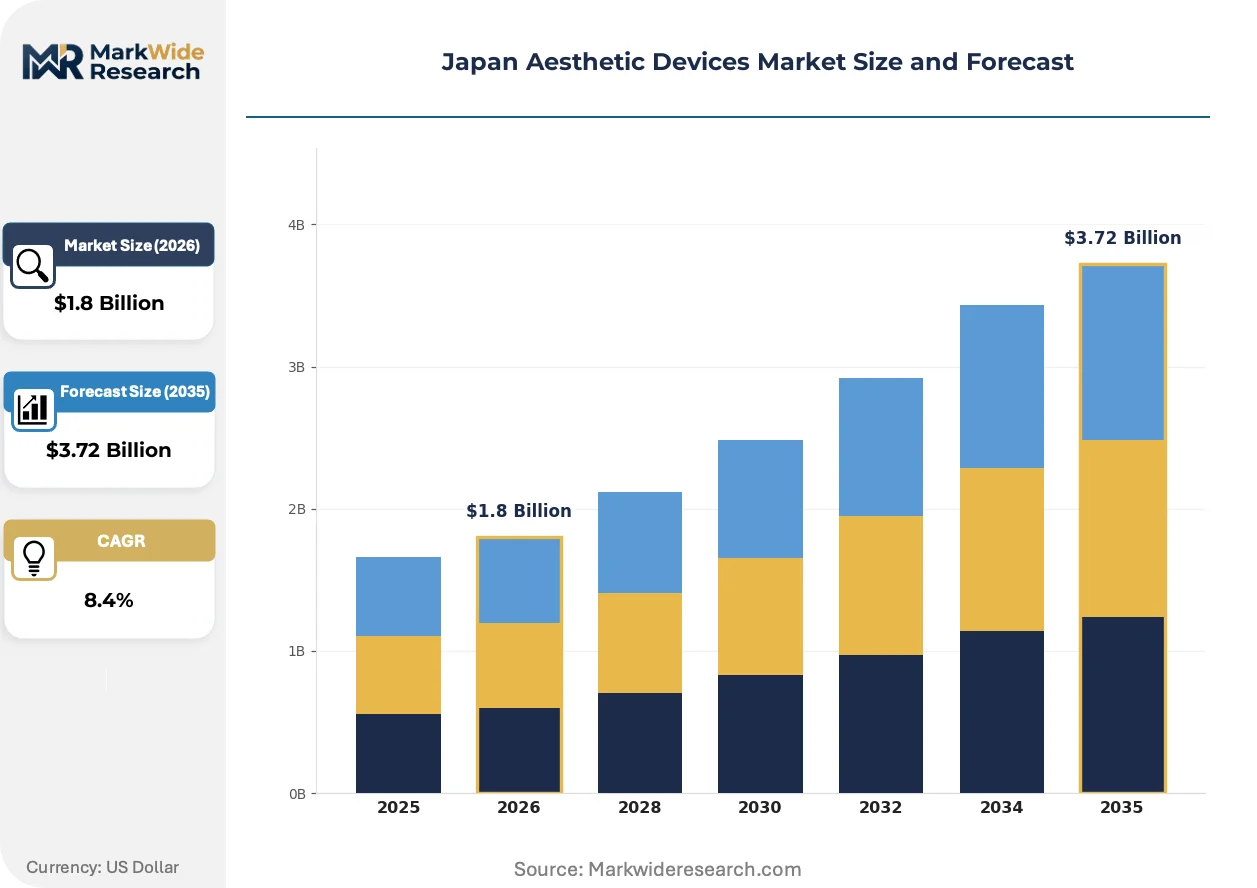
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Light Therapy Devices, Microdermabrasion Devices, Radiofrequency Devices Technology: Non-Invasive, Minimally Invasive, Energy-Based, Topical Delivery End User: Clinics, Spas, Hospitals, Dermatology Centers Application: Skin Rejuvenation, Hair Removal, Body Contouring, Acne Treatment |
| Companies Covered | AbbVie, Cynosure LLC, Bausch Health Companies Inc., Sciton Inc., Alma Lasers, Cutera Inc., Venus Concept, Hologic Inc., Lumenis Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Aesthetic Devices Market Shifts & Advancements
Device architecture is compressing toward portable form factors while regulatory frameworks and procurement logic simultaneously restructure competitive positioning across Japan's aesthetic medicine landscape.
Fractional radiofrequency microneedling systems are miniaturizing from cart-based hospital units to handheld tabletop configurations. Solo practitioners in Osaka and Nagoya are adopting these reduced-footprint platforms at twice the pace of institutional purchasers. This format shift is compressing the addressable market for legacy multi-module systems while expanding clinic density in constrained urban real estate.
PMDA's evolving guidance on artificial intelligence-enabled treatment planning software is mandating clinical validation datasets specific to East Asian skin phototypes. Device manufacturers must now submit supplementary safety evidence for algorithmic fluence recommendations. This regulatory layer most acutely affects imported platforms originally validated on Caucasian demographic data, forcing localization investments or partnership structures with domestic clinical research organizations.
Japanese consumers are compressing treatment intervals and unbundling after-sales service expectations from hardware procurement. Younger demographic segments in Tokyo's Shibuya and Ginza districts now prioritize per-session pricing transparency over long-term maintenance contracts. This behavioral pivot pressures distributors to restructure revenue models toward consumable attachment rates rather than upfront equipment margins.
Japan Aesthetic Devices Market Segmentation
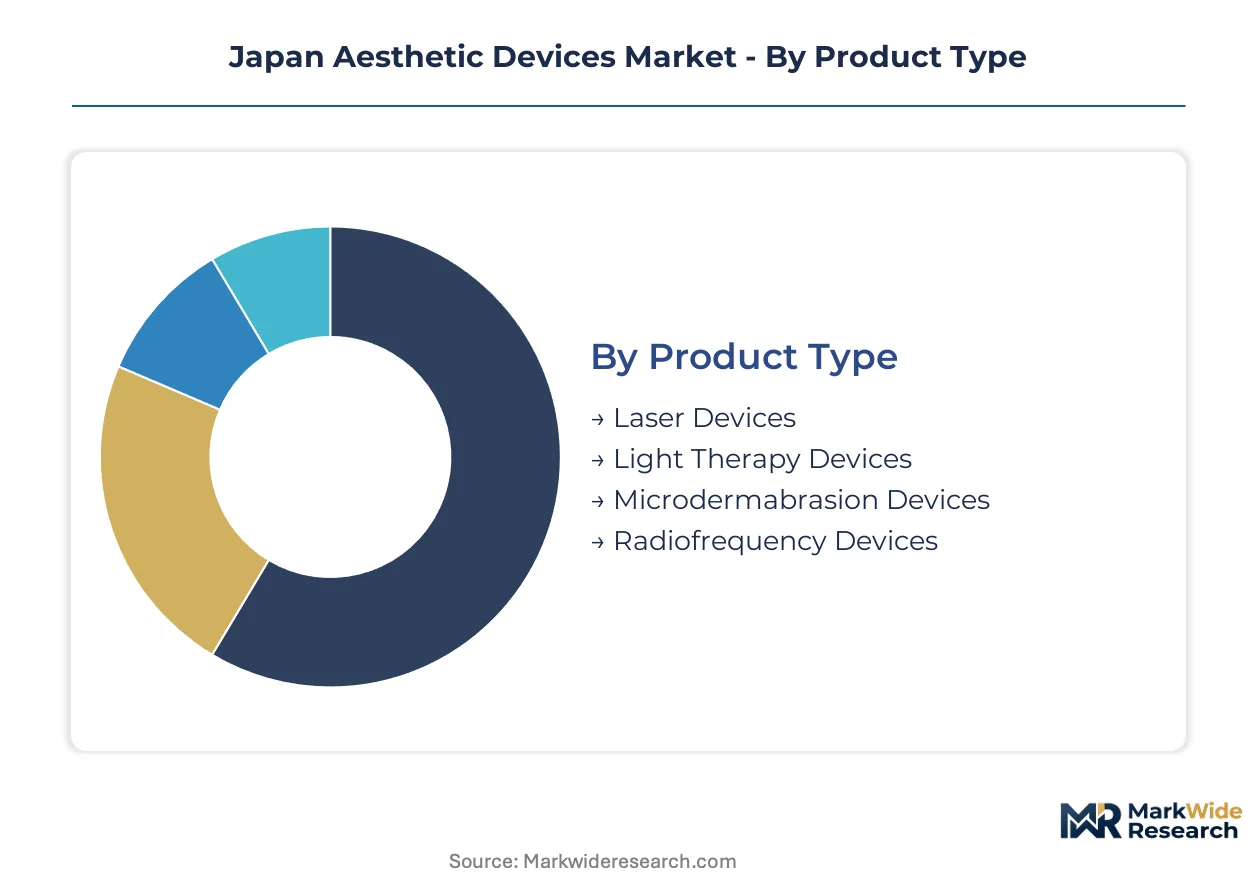
Segmentation in Japan's aesthetic devices market reveals how regulatory boundaries and procurement economics split demand across institutional channels. Each dimension—product, technology, end user, and application—carries distinct certification requirements and margin structures that determine competitive positioning.
Product Type:
Domestic demand concentrates in laser and radiofrequency platforms manufactured by Japanese precision optics suppliers, while light therapy and microdermabrasion devices rely heavily on Israeli and German import channels.
- Laser Devices:Solid-state and diode laser systems operating at 755 nm to 1,064 nm wavelengths deliver selective photothermolysis for hair removal and vascular lesions. Tokyo dermatology centers deploy these platforms for high-throughput outpatient procedures, though PMDA's Class IV laser operator certification requirements constrain workforce scalability.
- Radiofrequency Devices:Monopolar and bipolar RF systems generate dermal heating at 0.5–40 MHz for collagen remodeling and adipose tissue reduction. Osaka and Nagoya clinics favor these modalities for Japan's aging demographic seeking non-surgical skin tightening with minimal downtime.
- Light Therapy Devices:Intense pulsed light and LED-based systems target pigmentation and acne through broad-spectrum optical delivery.
- Microdermabrasion Devices:Crystal and diamond-tip mechanical exfoliation systems serve lower-acuity aesthetic maintenance protocols in spa settings.
Laser devices hold the largest share; momentum sits with radiofrequency platforms as combination therapy protocols gain adoption.
Technology:
Cost tier stratification separates premium energy-based platforms requiring physician supervision from accessible topical and non-invasive alternatives deployable in spa environments.
- Energy-Based:Laser, RF, and focused ultrasound platforms delivering controlled thermal injury for tissue remodeling command the highest equipment price points and require METI-certified electrical safety compliance. Dermatology centers in Fukuoka's expanding medical cluster prioritize these systems for margin capture unavailable to spa operators.
- Non-Invasive:Cryolipolysis, low-level light therapy, and external RF systems operate without epidermal breach. Younger consumers in Tokyo's Shibuya district drive demand for anesthesia-free treatment sessions with immediate return to daily activity.
- Minimally Invasive:Microneedling RF and fractional laser systems create controlled micro-injury requiring topical anesthetic but avoiding surgical recovery.
- Topical Delivery:Iontophoresis and sonophoresis devices enhance transdermal agent penetration for cosmetic rather than therapeutic claims.
Energy-based systems dominate revenue; non-invasive alternatives are climbing the fastest as consumer preference shifts toward zero-downtime protocols.
End User:
Volume concentration in hospital-affiliated chains contrasts with margin density in independent dermatology practices, while regulatory restrictions exclude spas from the highest-value procedure categories.
- Dermatology Centers:Physician-supervised facilities in Tokyo, Osaka, and Fukuoka metropolitan corridors deploy Class IV laser and combination RF platforms. METI's reimbursement recalibration favors these operators through procedural coding that spa channels cannot access.
- Clinics:Independent aesthetic medicine practices and small-chain operators balance equipment capital intensity against per-treatment leasing models.
- Hospitals:Academic medical centers and cosmetic surgery departments integrate aesthetic devices within broader plastic surgery service lines.
- Spas:Non-medical beauty salons face Ministry of Health, Labour and Welfare restrictions on laser operating privileges, limiting deployment to microdermabrasion and light therapy systems.
Dermatology centers capture the steepest expansion trajectory; clinics retain the largest installed base across Japan's prefectural markets.
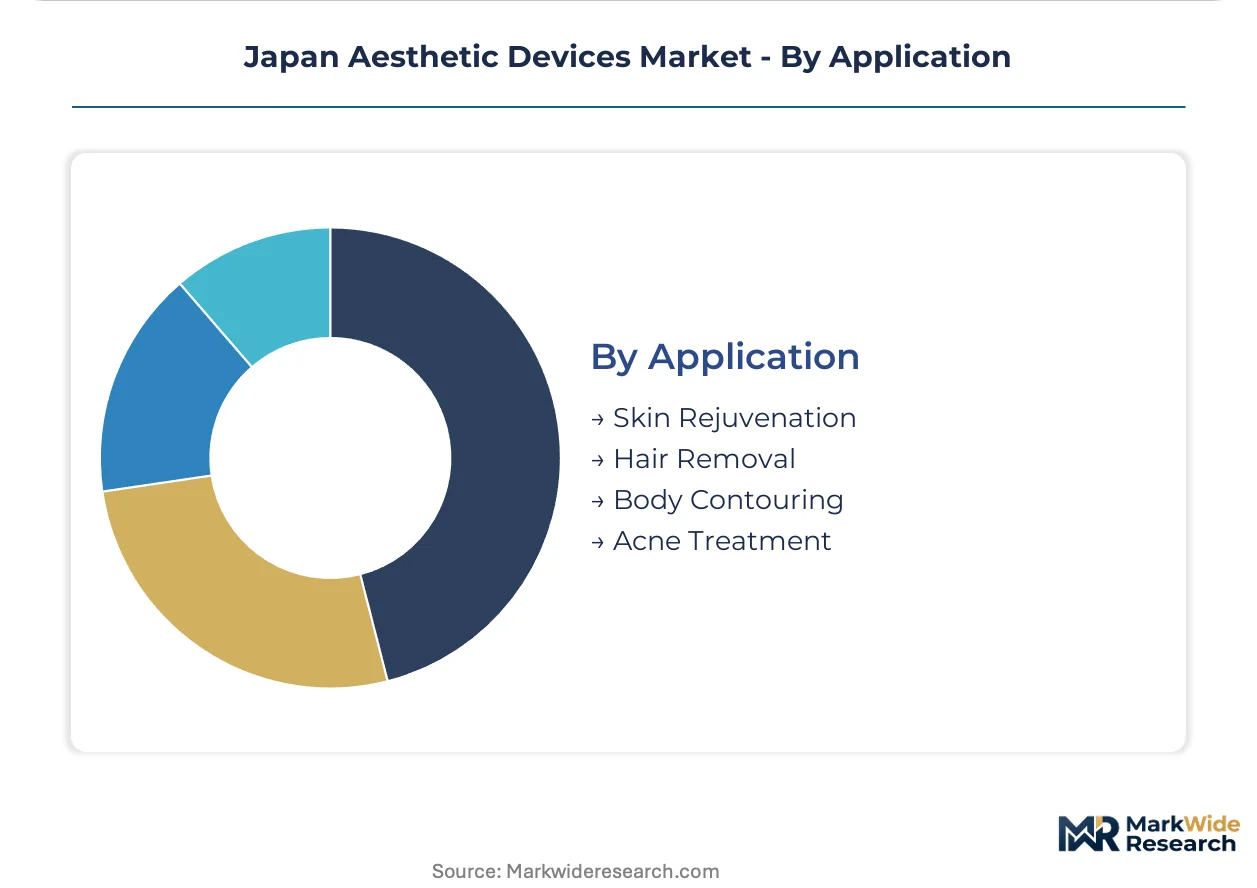
Application:
Customer type differentiation separates medical-grade therapeutic interventions from cosmetic maintenance, with age demographics driving distinct procedure preferences across metropolitan markets.
- Skin Rejuvenation:Fractional laser resurfacing, RF microneedling, and IPL photorejuvenation target photoaging, rhytides, and dyschromia. Japan's over-65 population density in urban corridors sustains outpatient demand for collagen remodeling without surgical recovery.
- Body Contouring:Cryolipolysis, non-invasive RF fat reduction, and high-intensity focused electromagnetic muscle toning address adipose tissue and body sculpting. Post-pandemic consumer behavior in Tokyo prioritizes these procedures for visible results without lifestyle interruption.
- Hair Removal:Alexandrite and diode laser systems deliver permanent hair reduction across multiple treatment sessions.
- Acne Treatment:Blue light therapy and photodynamic protocols target sebaceous gland activity and Cutibacterium acnes colonization.
Skin rejuvenation commands the largest procedure volume; body contouring is gaining share fastest as device miniaturization enables clinic network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan dermatology centers concentrate procurement authority across Japan's major urban corridors, with physician-supervised facilities in Tokyo, Osaka, and Fukuoka driving platform deployment decisions. Kanto and Kansai regions anchor installed base density, while Kyushu and Chubu present expansion vectors for energy-based system vendors.
Kanto/Tokyo
Tokyo's Shibuya and Ginza districts generate concentrated demand for non-invasive body contouring and skin rejuvenation protocols among affluent aging consumers. METI's reimbursement recalibration for physician-supervised energy-based procedures channels capital toward hospital-affiliated dermatology chains. The Tokyo metropolitan corridor hosts the nation's densest cluster of Class IV laser-certified operators.
Kansai/Osaka
Osaka's independent aesthetic medicine practices favor radiofrequency platforms for collagen remodeling among Japan's over-65 demographic seeking minimal-downtime interventions. PMDA's streamlined software-as-medical-device guidance accelerates clearance timelines for algorithm-controlled treatment planning systems. The Osaka-Nagoya corridor sustains robust per-treatment leasing model adoption.
Chubu/Nagoya
Nagoya's manufacturing-affluent consumer base drives demand for premium combination therapy platforms merging fractional laser with bipolar radiofrequency. JIS T 0601 harmonization with IEC 60601 standards reduces recertification friction for imported multi-technology systems. Solo practitioners in Aichi Prefecture adopt portable tabletop RF microneedling configurations at twice the rate of institutional purchasers.
Kyushu
Fukuoka's underpenetrated aesthetic device installed base offers first-mover positioning ahead of metropolitan saturation, with dermatology centers expanding procurement as patient volumes rise. Ministry of Health, Labour and Welfare reimbursement boundaries determine which procedures clinics can profitably offer. The Fukuoka medical cluster captures margin pools unavailable to spa operators through physician-supervision requirements.
Hokkaido
Sapporo's seasonal tourism economy creates episodic demand spikes for aesthetic maintenance protocols among domestic visitors. Capital intensity constraints strain independent dermatology practices against hospital-affiliated chains deploying 20-40 million yen energy-based platforms. Hokkaido's dispersed geography limits technician certification scalability for PMDA-mandated Class IV laser operator training.
Japan Aesthetic Devices Market Competitive Landscape
Player mix skews toward multinational precision optics specialists and domestic distributors with regulatory navigation capabilities. Market structure concentrates around established foreign manufacturers holding PMDA clearances and Japanese partners managing JIS T 0601 certification pathways. Three archetypes dominate: diversified pharmaceutical-aesthetic conglomerates, specialized laser and RF platform developers, and regional distributors with clinical research organization partnerships. Competitive dynamics center on technology licensing arrangements and per-treatment servitization models displacing outright capital sales.
Among diversified pharmaceutical-aesthetic conglomerates, AbbVie occupies a position exemplifying premium injectable platform positioning through legacy Allergan Aesthetics portfolio integration. Cynosure LLC and Alma Lasers represent specialized energy-based platform developers, with the former anchoring East Asian skin phototype optimization and the latter sitting within multi-technology integration archetypes spanning radiofrequency and light therapy modalities. These three companies illustrate the competitive tension between single-technology depth and platform breadth strategies.
| Leading Market Players |
|---|
| AbbVie |
| Cynosure LLC |
| Bausch Health Companies Inc. |
| Sciton Inc. |
| Alma Lasers |
| Cutera Inc. |
| Venus Concept |
| Hologic Inc. |
| Lumenis Ltd. |
| Others |
Supply & Pricing Matrix
JIS T 0601 certification gates both supplier qualification and price stratification across Japan's aesthetic device procurement landscape, forcing foreign manufacturers through costly electrical safety recertification while enabling domestic distributors to command premium positioning for METI-cleared platforms.
Pricing Analysis
Cost-plus contracts with yen-denominated indexation dominate equipment procurement between Japanese dermatology chains and German laser optics suppliers. Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised energy-based platforms from spa-deployable light therapy systems. Cost compression in mid-tier radiofrequency units is intensifying because Fukuoka clinic networks are consolidating purchasing volumes. Independent practitioners exhibit highest price sensitivity; hospital-affiliated chains absorb capital intensity through depreciation schedules.
Supply Chain Analysis
Inventory lead times for RF generators and solid-state laser cavities now stretch fourteen to eighteen months from German and Israeli component suppliers. Japan's device assembly draws from precision optics manufacturers in Germany, RF generator specialists in Israel, and semiconductor cooling systems from South Korea. Single-source vulnerability concentrates in alexandrite laser rod supply. Distribution runs through domestic distributors holding PMDA clearance relationships rather than direct manufacturer-to-clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's aesthetic device market fragments along regulatory boundaries, with METI's reimbursement recalibration and PMDA's software guidance creating distinct competitive niches for specialized platform developers.
For Market Incumbents: Shield installed base positions through backward integration into RF generator supply and accelerated JIS T 0601 recertification for next-generation platforms. Consolidate technician training infrastructure to constrain workforce scalability for emerging competitors. Channel control through exclusive leasing arrangements with Osaka clinic chains represents the priority defensive lever against portable tabletop entrants. For New Entrants and Emerging Players: Anchor in Fukuoka's underpenetrated dermatology corridor where physician-supervised energy-based platform demand outpaces metropolitan saturation. Target subscription servitization models for mid-tier clinics seeking technology refresh flexibility without capital expenditure. Combination therapy convergence—merging fractional laser with bipolar radiofrequency—offers the most penetrable white-space for differentiated positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable RF microneedling segments as miniaturization reduces per-unit deployment costs. Long-term viability over the coming decade hinges on software-as-medical-device clearance capabilities and East Asian skin phototype validation datasets. Acquisition targets should display domestic clinical research organization partnerships. The signal to monitor is PMDA's guidance evolution on algorithm-controlled fluence recommendations.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Accelerates market entry for AI-enabled treatment planning platforms validated on Japanese demographic data. |
| JIS T 0601 Harmonization Investment | Reduces recertification costs for imported multi-technology systems converging with IEC 60601 standards. |
| Domestic Clinical Research Organization Partnership | Enables supplementary safety evidence submission for algorithmic fluence recommendations on East Asian skin. |
| Per-Treatment Leasing Model Deployment | Captures mid-tier clinic operators seeking technology refresh flexibility without 20-40 million yen capital outlay. |
| Technician Certification Infrastructure Buildout | Constrains workforce scalability for competitors while securing operator loyalty to incumbent platform ecosystems. |
Research Methodology
Desk research of PMDA premarket approval filings, METI industrial standards documentation, and hospital procurement databases preceded structured interviews with dermatology clinic directors, biomedical equipment procurement managers, GPO contracts specialists, and regulatory affairs consultants at device distributors. Primary fieldwork across Tokyo, Osaka, and Fukuoka metropolitan corridors combined with secondary validation through JIS standard harmonization records and Ministry of Health, Labour and Welfare reimbursement schedules. Bottom-up installed base enumeration triangulated against top-down market size estimates from energy-based platform shipment data.
Variance decomposition across product type, technology tier, end-user channel, and application category shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include energy delivery modality, physician supervision requirement, and metropolitan versus prefectural market density. CAGRs derived from procedure volume growth trajectories and per-treatment equipment utilization rates. Forecast inputs incorporated aging demographic projections and reimbursement code expansion schedules.
Decision-makers should treat outputs as directional under assumptions of stable METI reimbursement boundaries and continued PMDA software guidance evolution; material deviation in regulatory timelines or import tariff structures would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Allografts Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Biologic Injectors Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Pen Injectors Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
United States Stair Lift Market
Medical Devices
Europe Organ-On-Chip Market