
 Global Angiography Catheters Market | 2026-2036
Global Angiography Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Angiography Catheters Market Foresight
The capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is reorganizing competitive tiers in angiography catheters. Medtronic leverages captive polymer compounding and in-house extrusion to sustain margin structures that pure-play distributors cannot replicate. Boston Scientific competes through concentrated R&D spending on hydrophilic coating chemistries. Terumo Medical Corporation anchors its position with dominant share in Japanese cardiac centers and selective European expansion.
Angiography catheters are thin-walled, radiopaque tubes engineered from polyurethane, nylon, or polyethylene with braided wire reinforcement to transmit torque during fluoroscopically guided vascular navigation. Their primary purpose is to deliver contrast media to target vessels while maintaining lumen patency for guidewire and device exchange. Diagnostic catheters retain the largest volume position due to universal deployment in baseline coronary assessments, yet microcatheters are capturing disproportionate value growth as neurovascular and chronic total occlusion procedures expand. Hydrophilic coating technology leads material differentiation by reducing friction coefficients during tortuous anatomy traversal, while non-coated alternatives occupy economy positioning in cost-constrained procurement environments.
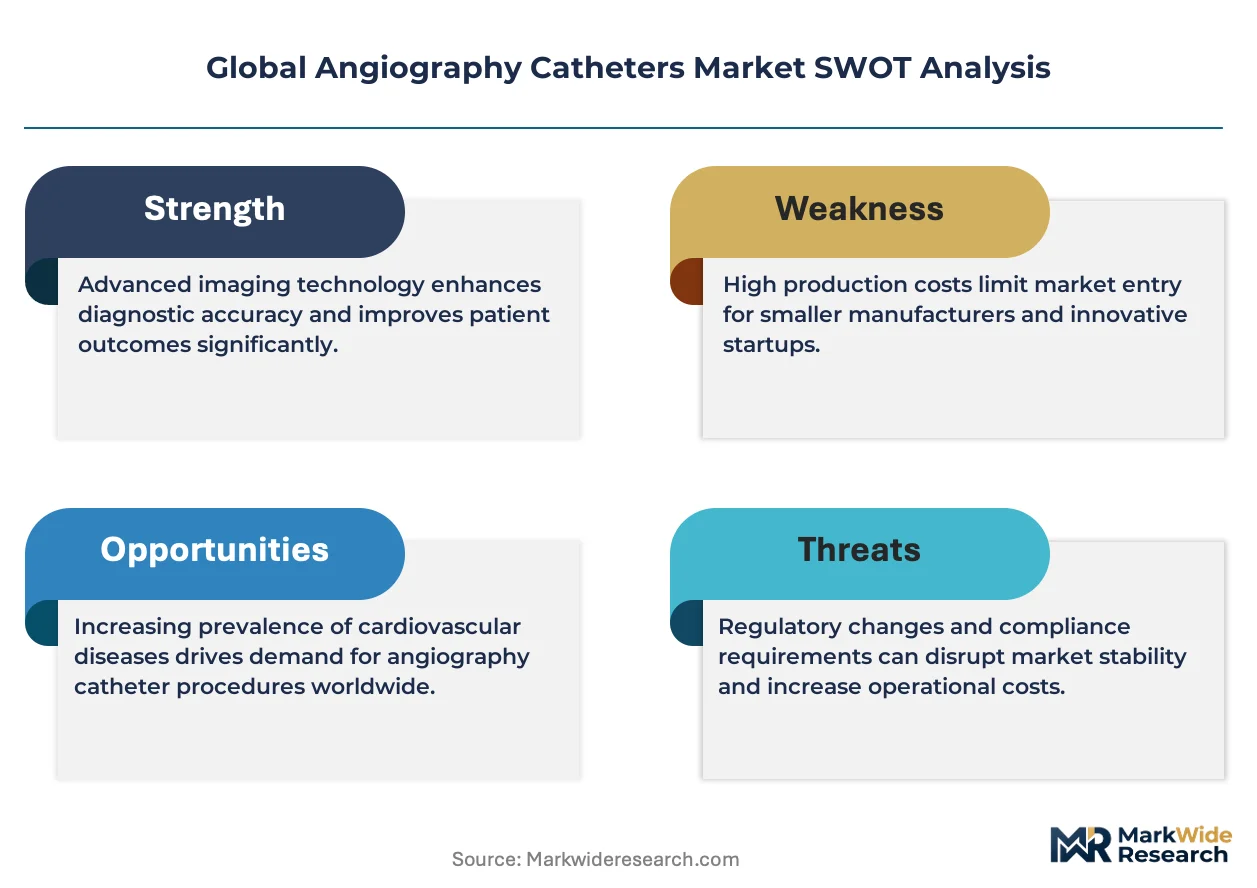
FDA premarket approval pathways, CE marking under the EU MDR, and Japan's PMDA quality management standards collectively shape product development timelines and clinical evidence requirements for market access. These frameworks favor incumbents with established regulatory infrastructure and predicate device libraries. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA breakthrough device designations that could compress competitive response windows for novel catheter geometries.
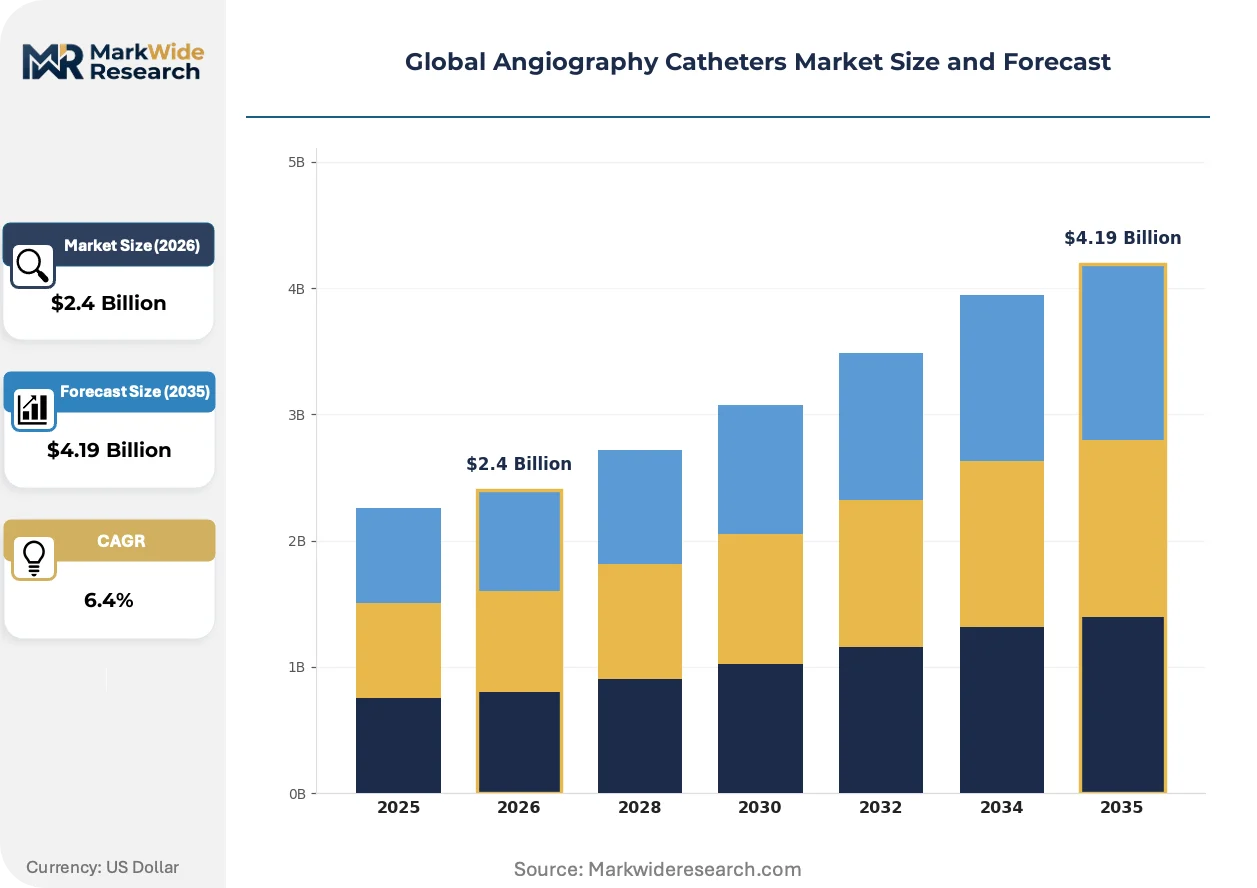
Market Dynamics
Regulatory escalation under the EU MDR and FDA premarket approval pathways is compressing product development timelines while elevating clinical evidence burdens, forcing manufacturers to front-load quality management investments before commercialization.
Growth Catalysts
- EU MDR Implementation:The Medical Device Regulation's enhanced clinical evaluation requirements are filtering out marginal competitors and consolidating procurement toward established suppliers with predicate device libraries.
- Neurovascular Procedure Expansion:Chronic total occlusion and intracranial interventions are driving disproportionate value capture in microcatheter subsegments across Japanese and German cardiac centers.
- Hydrophilic Coating Chemistry:Advanced polymer surface treatments are reducing friction coefficients in tortuous anatomy navigation, expanding addressable cases in peripheral vascular disease.
Market Restraints
- Nitinol Wire Volatility:Braided reinforcement materials face price instability from concentrated superelastic alloy suppliers, compressing margin structures for assembly-dependent manufacturers.
- Notified Body Bottlenecks:EU MDR designation capacity constraints are extending CE marking timelines by 12-18 months, delaying market access for novel catheter geometries.
- Reimbursement Compression:Diagnosis-related group payment bundling in US Medicare is narrowing separate device reimbursement codes for diagnostic catheters.
Strategic Opportunities
- Brazil ANVISA Pathway:Latin America's largest cardiac center network offers first-mover positioning for manufacturers with established FDA 510(k) predicates.
- AI-Fluoroscopy Integration:Machine learning-enabled navigation assistance is converging with catheter design to reduce contrast media volumes and radiation exposure.
- Direct Hospital Contracting:IDN procurement centralization is creating channel bypass opportunities for manufacturers with captive polymer compounding capabilities.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemistry expertise for radiopaque polyurethane blends is concentrated among a narrow cohort of medical device veterans.
- MDR Technical Documentation:The EU's expanded post-market surveillance and periodic safety update report requirements are consuming 25-30% of regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Angiography Catheters Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.19 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Catheters, Guiding Catheters, Balloon Catheters, Microcatheters, Others Technology: Hydrophilic Coating, Non-Coated, Polyurethane, Silicone, PTFE, Others Application: Coronary Artery Imaging, Peripheral Vessel Imaging, Neurovascular Diagnosis, Pulmonary Artery Visualization, Renal Artery Examination End User: Cardiac Centers, Radiology Clinics, Specialty Clinics, Diagnostic Laboratories, Outpatient Facilities |
| Companies Covered | Medtronic, Boston Scientific Corporation, Terumo Medical Corporation, Abbott, Merit Medical Systems, Inc., Cardinal Health, AngioDynamics, Cook Group, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Angiography Catheters Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization pressures are restructuring how angiography catheters are designed, validated, and procured across developed healthcare systems.
Microcatheter technology is decomposing the traditional diagnostic-interventional boundary in neurovascular access. Academic medical centers in Germany and Japan are adopting sub-2.0 French platforms for intracranial aneurysm coiling, collapsing the historical procedure volume split between standalone diagnostic runs and therapeutic interventions. This convergence is compressing the addressable market for conventional 5-6 French diagnostic catheters in cerebrovascular applications.
Japan's PMDA quality management standards are tightening biocompatibility testing protocols for long-dwell catheters. Manufacturers must now submit extended thrombogenicity and hemolysis data for devices exceeding 60 minutes indwell time, extending development cycles by 8-12 months. Cardiac centers in Osaka and Tokyo are responding by consolidating supplier lists toward vendors with established biological evaluation laboratories.
Hospital procurement departments are unbundling device sourcing from contrast media and capital equipment agreements. Integrated delivery networks in the United States are negotiating standalone catheter contracts with utilization guarantees, displacing the traditional bundled angiography suite purchasing model. This shift is most visible in Florida and Texas health systems where cardiac service line consolidation has concentrated buying power.
Global Angiography Catheters Market Segmentation
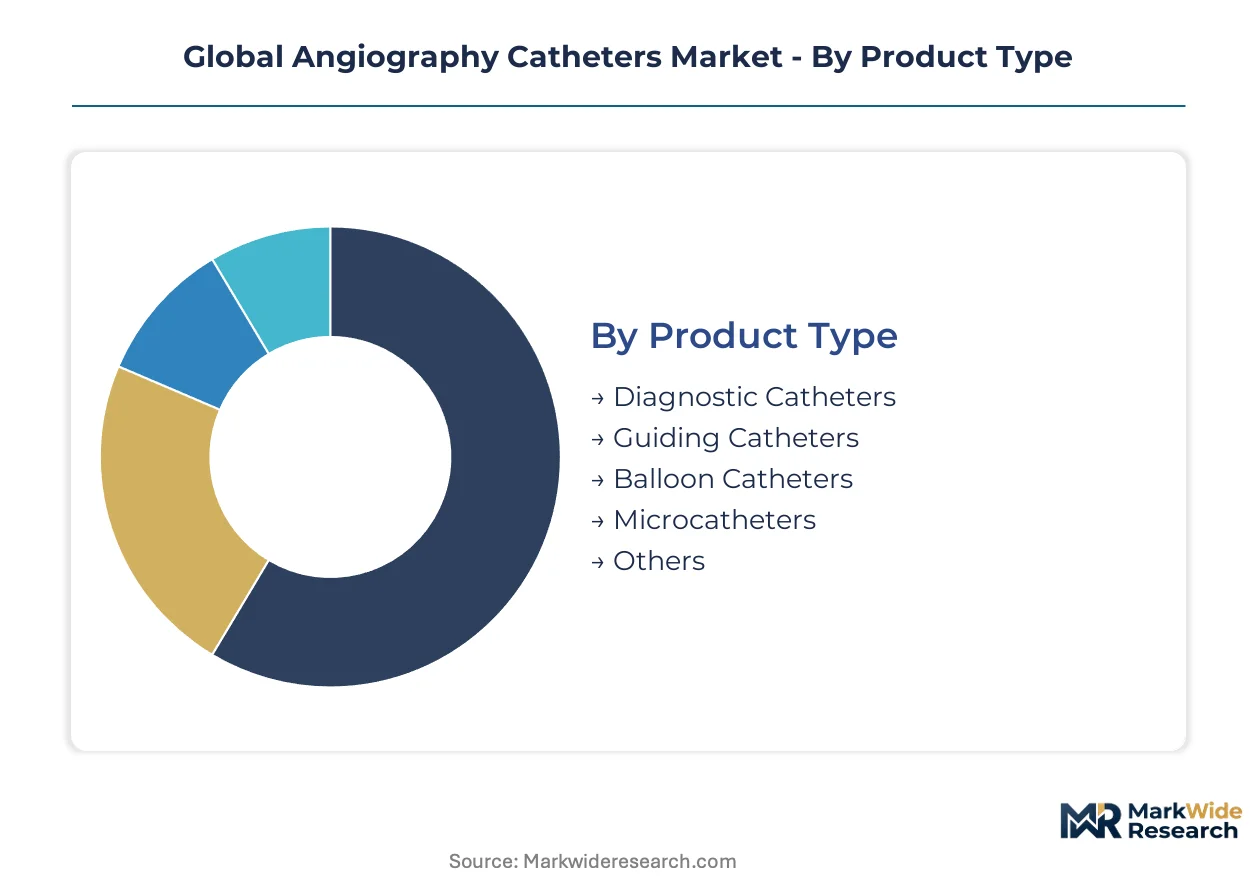
Segmentation in angiography catheters determines procurement pathways, with cardiac centers and radiology clinics operating distinct sourcing protocols. Product type and coating technology drive reimbursement coding and inventory management decisions across hospital systems.
Product Type:
Diagnostic catheters and guiding catheters move through GPO contracts with volume commitments, while microcatheters increasingly bypass traditional distribution through direct manufacturer agreements with academic medical centers.
- Diagnostic Catheters:Thin-walled radiopaque tubes in 5-6 French sizes serve universal deployment in baseline coronary assessments. Demand concentrates in United States cardiac centers where Medicare DRG bundling favors standardized procurement of high-volume SKUs.
- Microcatheters:Sub-2.0 French platforms with braided nitinol reinforcement enable intracranial aneurysm coiling and chronic total occlusion navigation. German and Japanese cardiac centers are consolidating supplier lists toward vendors with established biological evaluation laboratories for extended indwell protocols.
- Guiding Catheters:Large-lumen platforms for device delivery and contrast injection in interventional procedures.
- Balloon Catheters:Integrated inflation lumens for angioplasty and stent deployment applications.
- Others:Specialty configurations including aspiration and perfusion catheters for niche indications.
Diagnostic catheters dominate installed base. Microcatheters are where expansion concentrates.
Technology:
Coating chemistry stratifies pricing tiers and determines shelf-life requirements, with hydrophilic formulations commanding premium positioning in tortuous anatomy cases while non-coated alternatives serve cost-constrained procurement.
- Hydrophilic Coating:Advanced polymer surface treatments reduce friction coefficients during vascular navigation. Demand clusters in peripheral vascular disease procedures across Florida and Texas health systems where cardiac service line consolidation has concentrated buying power.
- Non-Coated:Economy positioning for high-volume diagnostic runs with shorter procedure times. Procurement departments in German outpatient facilities favor these for budget adherence under DRG-equivalent frameworks.
- Polyurethane:Radiopaque blends with Shore hardness optimization for torque response.
- Silicone:Biocompatible options for extended indwell applications requiring thromboresistance.
- PTFE:Low-friction liner materials for guidewire compatibility.
- Others:Emerging surface treatments including drug-eluting and antimicrobial coatings.
Non-coated platforms anchor volume procurement. Hydrophilic formulations are climbing the fastest.
Application:
Procedure complexity dictates catheter specification, with coronary applications driving standardization while neurovascular and peripheral cases require specialized geometries and coating profiles.
- Coronary Artery Imaging:Universal baseline assessment procedures using diagnostic catheters with Judkins or Amplatz curve configurations. United States cardiac centers generate procedure volume through established reimbursement codes.
- Neurovascular Diagnosis:Intracranial access for aneurysm evaluation and embolization planning. Japanese academic medical centers in Osaka and Tokyo are adopting sub-2.0 French platforms, collapsing the historical split between diagnostic runs and therapeutic interventions.
- Peripheral Vessel Imaging:Lower extremity and carotid access for atherosclerotic disease assessment.
- Pulmonary Artery Visualization:Right heart catheterization for pulmonary hypertension evaluation.
- Renal Artery Examination:Fibromuscular dysplasia and stenosis assessment in hypertension workups.
Coronary applications retain procedure volume leadership. Neurovascular diagnosis is gaining share fastest.
End User:
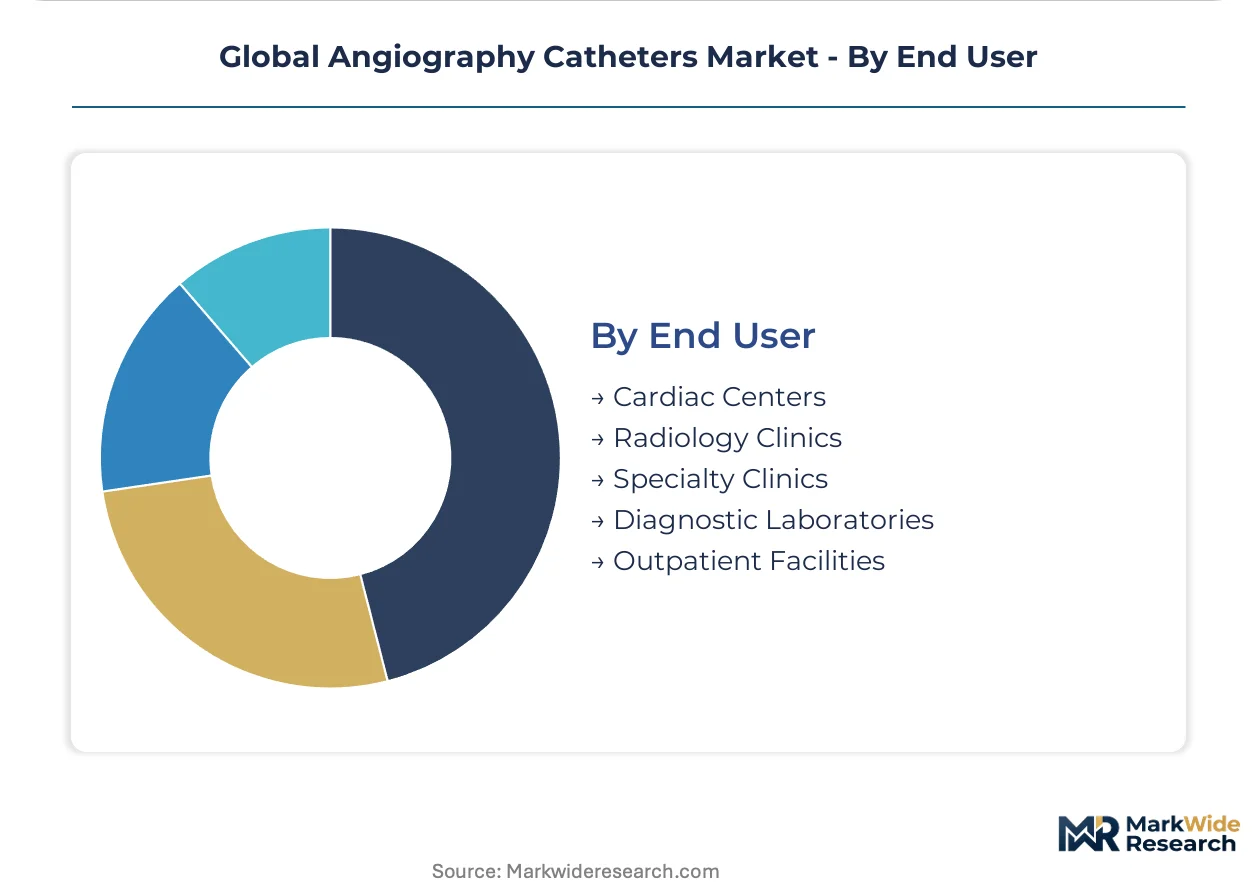
Site-of-care shifts are restructuring demand concentration, with outpatient migration and IDN consolidation rewriting contract negotiation dynamics.
- Cardiac Centers:High-volume interventional suites with captive polymer compounding partnerships. United States integrated delivery networks negotiate standalone catheter contracts with utilization guarantees.
- Radiology Clinics:Diagnostic imaging facilities with fluoroscopy capabilities for peripheral and carotid assessments. German outpatient radiology chains are consolidating purchasing toward vendors with CE marking under MDR predicates.
- Specialty Clinics:Vascular surgery and cardiology practices with limited procedure mixes.
- Diagnostic Laboratories:Standalone facilities with referral relationships to interventional centers.
- Outpatient Facilities:Ambulatory surgery centers capturing migration from inpatient settings.
Cardiac centers anchor current demand. Outpatient facilities are where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing premium hydrophilic-coated catheters under established reimbursement frameworks. Procurement teams in Brazil and India operate under severe budget constraints, favoring non-coated diagnostic platforms. The United States occupies a middle position where integrated delivery networks negotiate utilization-guaranteed contracts that trade volume commitments for moderate price concessions.
United States
Cardiac service line consolidation across Florida and Texas health systems has concentrated buying power among ten to fifteen integrated delivery networks. FDA premarket approval pathways for Class III devices elevate barrier-to-entry standards, filtering marginal competitors from commercialization. Cleveland Clinic and Mayo Clinic anchor procurement innovation through direct manufacturer agreements that bypass traditional group purchasing organizations.
Germany
Academic medical centers in Munich and Heidelberg drive disproportionate microcatheter adoption for chronic total occlusion and neurovascular interventions. CE marking under the EU MDR with its enhanced clinical evaluation requirements filters procurement toward established suppliers with predicate device libraries. The Baden-Württemberg cardiac center network exemplifies supplier consolidation toward vendors with dedicated biological evaluation laboratories.
Japan
Osaka and Tokyo cardiac centers are collapsing the historical procedure volume split between diagnostic runs and therapeutic interventions through sub-2.0 French platform adoption. PMDA quality management standards now mandate extended thrombogenicity data for catheters exceeding sixty minutes indwell time. Terumo Medical Corporation anchors dominant share through captive relationships with Japanese academic medical centers and selective European expansion.
Brazil
Latin America's largest cardiac center network offers first-mover positioning for manufacturers with established FDA 510(k) predicates seeking ANVISA pathway entry. Price sensitivity dominates procurement decisions across São Paulo and Rio de Janeiro public hospital systems. Private cardiac centers in the Southeast region demonstrate moderate elasticity for hydrophilic-coated platforms in complex peripheral interventions.
India
Cost-constrained procurement environments in Delhi and Mumbai favor non-coated diagnostic catheters for high-volume baseline coronary assessments. CDSCO medical device regulations are harmonizing toward ISO 13485 quality management standards, extending registration timelines for novel entrants. The Apollo and Fortis hospital networks in South India represent emerging demand concentration for premium-tier microcatheters in neurovascular applications.
Global Angiography Catheters Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure with limited overlap between premium innovators and assembly-dependent distributors. The vendor base concentrates around integrated manufacturers with captive polymer compounding capabilities and pure-play competitors dependent on outsourced nitinol wire and extrusion supply. Three archetypes dominate: vertically integrated multinationals with regulatory infrastructure depth, regional specialists with geographic anchoring advantages, and contract manufacturers serving private-label distributors. M&A activity targets regulatory predicate libraries and biological evaluation laboratory assets, while strategic partnerships concentrate on AI-fluoroscopy integration development.
Within the integrated multinational tier, Medtronic and Boston Scientific Corporation occupy positions defined by captive manufacturing depth and concentrated R&D allocation toward coating chemistry innovation. Terumo Medical Corporation exemplifies geographic anchoring through dominant Japanese cardiac center relationships. Among diversified healthcare conglomerates, Abbott and Cardinal Health represent portfolio breadth strategies that leverage catheter offerings within broader interventional device ecosystems. Merit Medical Systems, Inc. and AngioDynamics sit within the specialist tier focused on niche procedure segments.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Terumo Medical Corporation |
| Abbott |
| Merit Medical Systems, Inc. |
| Cardinal Health |
| AngioDynamics |
| Cook Group |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Captive polymer compounding scale at integrated manufacturers like Medtronic and Boston Scientific anchors price floors for hydrophilic-coated platforms, while assembly-dependent competitors absorb margin compression from outsourced nitinol wire and extrusion supply. This scale divergence stratifies procurement tiers across United States integrated delivery networks and German academic medical centers.
Pricing Analysis
After-sales service contracts and extended warranty bundles now drive lifetime value capture for catheter manufacturers. Three-tier pricing structure across premium hydrophilic-coated, standard polyurethane, and economy non-coated levels segments buyers by procedure complexity and reimbursement environment. Cost compression in economy tiers intensifies as Indian and Brazilian public hospital systems consolidate procurement toward high-volume SKUs. German and Japanese cardiac centers demonstrate lowest price elasticity, absorbing premium positioning under established DRG frameworks.
Supply Chain Analysis
Nitinol wire supply from concentrated superelastic alloy producers in Japan and the United States anchors braided reinforcement costs for torque-responsive catheter platforms. Polyurethane resin formulations and radiopaque additive blends draw from specialty chemical suppliers in Germany and Switzerland. Single-source vulnerability in nitinol wire creates exposure to price volatility and allocation constraints during demand surges. Distribution runs through group purchasing organizations in the United States and direct hospital contracting in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Angiography catheter procurement is shifting toward platform-economics logic as AI-fluoroscopy integration and software companion applications rewrite interoperability requirements between devices and imaging systems.
For Market Incumbents: Secure predicate device libraries under FDA and CE marking pathways to compress competitive response windows for novel catheter geometries. Deepen backward integration into polymer compounding to defend margin structures against nitinol wire volatility and assembly-dependent challengers. For New Entrants and Emerging Players: Lead with Brazil ANVISA pathway entry leveraging established FDA 510(k) predicates for first-mover positioning in Latin America's largest cardiac center network. Target cost-constrained procurement environments in Indian outpatient facilities with non-coated diagnostic platforms, bypassing premium-tier competition dominated by integrated multinationals. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive biological evaluation laboratories and regulatory infrastructure depth. Long-term viability hinges on MDR notified body capacity constraints and AI-fluoroscopy convergence timelines. Watch FDA breakthrough device designations as inflection signals for novel geometry commercialization windows.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR predicate libraries filter procurement toward established suppliers with clinical evidence depth. |
| Hospital System Partnership | Direct contracting with United States IDNs bypasses GPO intermediaries and captures utilization guarantees. |
| Backward Integration | Captive polymer compounding insulates margin structures from specialty chemical supplier concentration. |
| Software Companion Development | AI-fluoroscopy integration reduces contrast media volumes and anchors next-generation platform economics. |
| Reimbursement Strategy | Medicare DRG bundling navigation determines diagnostic catheter coding viability in United States cardiac centers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Across the analysis window, forecasts incorporated product type segmentation by diagnostic, microcatheter, and guiding catheter platforms; coating technology tiers; and end-user site-of-care migration patterns. CAGRs derived from procedure volume elasticity models against demographic aging trajectories and reimbursement framework stability. Hydrophilic coating adoption curves and neurovascular procedure expansion rates served as key demand-side inputs.
The analysis sits within stated boundaries; outcomes outside stable MDR notified body capacity, nitinol wire supply continuity, and Medicare DRG bundling parameters would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline trajectories and hospital consolidation momentum. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Liposuction Devices Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Neurovascular Devices Market
Medical Devices
North America C-Arms Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Hormonal Implants Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Global Acetabular Prostheses Market