
 Perfusion Imaging Market | 2026-2036
Perfusion Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Perfusion Imaging Market Outlook
AI-enhanced reconstruction algorithms is reconfiguring how perfusion imaging systems process raw acquisition data into quantitative parametric maps. Siemens Healthineers leverages proprietary compressed-sensing technology to accelerate scan times while preserving spatial resolution. Canon Medical Systems anchors its competitive stance through integrated CT perfusion platforms that unify acquisition and post-processing workflows.
Perfusion imaging measures regional blood flow, blood volume, and mean transit time using contrast-enhanced or arterial spin-labeling techniques, producing parametric maps that guide clinical decision-making in ischemia detection and tumor characterization. CT Perfusion dominates acute stroke protocols due to rapid acquisition and widespread scanner availability, while MRI Perfusion captures expanding share in oncology and neuro-oncology where blood-brain barrier permeability quantification drives treatment monitoring. Software Tools represent the fastest-expanding technology segment as vendors embed machine learning classifiers that automate lesion detection and reduce inter-reader variability.
FDA premarket notification requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence standards for perfusion imaging devices and contrast agents. The Environmental Protection Agency and REACH restrictions on iodinated contrast disposal are elevating capital requirements for hospital radiology departments. Stakeholders must monitor reimbursement decisions for quantitative perfusion biomarkers by Medicare and major European sickness funds, as coding recognition will determine whether advanced analysis platforms achieve routine deployment or remain confined to research settings.
Market Dynamics
AI-enhanced reconstruction algorithms are compressing scan times from minutes to seconds while preserving diagnostic accuracy, forcing hardware vendors to embed software capabilities directly into acquisition platforms rather than treating post-processing as an aftermarket add-on.
Growth Catalysts
- Compressed-sensing acquisition protocols:University hospitals in Germany are integrating quantitative perfusion analysis into routine stroke protocols, creating template workflows for European adoption.
- EU Medical Device Regulation streamlining:MDR harmonization is reducing redundant clinical evidence requirements across member states, accelerating multi-country product launches for perfusion software vendors.
- FDA premarket notification pathways:AI-enhanced perfusion analysis tools are securing 510(k) clearances under streamlined software-as-medical-device frameworks, shortening US commercialization timelines.
Market Restraints
- Iodinated contrast agent costs:Gadolinium and iodinated contrast pricing volatility is squeezing hospital radiology department operating margins, particularly affecting high-volume CT perfusion protocols.
- Scanner hardware concentration:CT and MRI system manufacturing concentrates among three dominant vendors, creating supply vulnerability for perfusion-compatible hardware upgrades.
- REACH disposal compliance:ECHA restrictions on contrast agent wastewater handling are elevating capital requirements for hospital radiology departments across European markets.
Strategic Opportunities
- Arterial spin-labeling MRI expansion:Contrast-free perfusion techniques are penetrating neuro-oncology monitoring protocols, opening reimbursement pathways in pediatric and renal-impaired patient populations.
- Quantitative biomarker standardization:ISO 13485-compliant software platforms are positioning for Medicare Category III CPT code recognition, enabling transition from research to routine clinical reimbursement.
- Cloud-native post-processing deployment:Hospital IT departments are adopting browser-based perfusion analysis tools, reducing on-premise workstation capital requirements and enabling remote radiologist access.
Industry Challenges
- Inter-reader variability reduction:Machine learning classifier training requires large, annotated perfusion datasets that remain fragmented across institutional silos, complicating algorithm generalization.
- Legacy PACS integration friction:Quantitative perfusion maps must interface with decade-old picture archiving systems, forcing vendors to maintain multiple data format compatibility layers.
- Specialized neuroradiologist scarcity:Advanced perfusion interpretation demands subspecialty training that academic medical centers struggle to staff, limiting protocol expansion at community hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfusion Imaging Market |
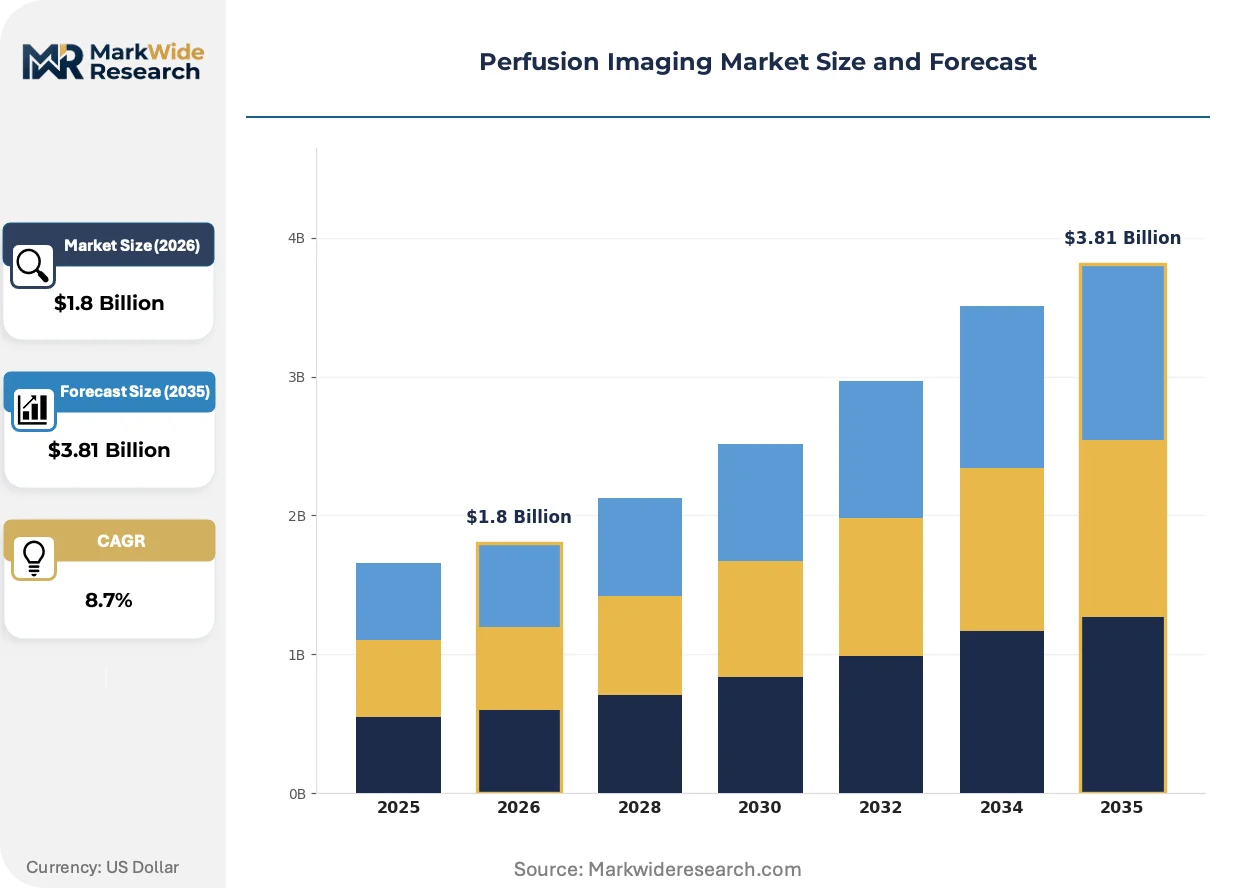
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Perfusion, MRI Perfusion, PET Perfusion, Ultrasound Perfusion End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Clinics Technology: Contrast Media, Software Tools, Imaging Devices, Data Analysis Platforms Application: Oncology, Neurology, Cardiovascular, Emergency Medicine |
| Companies Covered | Canon Medical Systems, Bracco Imaging, GE Healthcare, Bayer AG, Guerbet, Philips Healthcare, Fujifilm Holdings Corporation, Medtronic, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfusion Imaging Market Strategic Shifts
Computational reconstruction methods are displacing hardware-intensive acquisition approaches, compressing the traditional trade-off between image quality and scan duration that has governed perfusion imaging economics for two decades.
Compressed-sensing acquisition algorithms are collapsing the temporal resolution requirements for CT perfusion, enabling whole-brain coverage in sub-60-second scan windows. Academic stroke centers are adopting these protocols for emergency department triage, replacing conventional multi-slice dynamic acquisitions. This compression is eliminating the need for dedicated research-grade CT scanners in high-volume stroke networks.
EU AI Act risk classification frameworks are reshaping clinical decision-support software deployment requirements, mandating human-in-the-loop oversight for perfusion-derived treatment recommendations. Vendors are restructuring product architectures to segregate diagnostic display functions from automated lesion quantification. Neuro-oncology applications face the steepest compliance burden under these emerging conformity assessment pathways.
Radiology group purchasing organizations are consolidating vendor evaluation criteria around interoperability certifications, displacing standalone software procurement in favor of integrated platform contracts. Hospital systems are bundling perfusion analysis licenses with enterprise imaging agreements, compressing pricing leverage for point-solution vendors. This concentration is most visible in US integrated delivery networks exceeding 20-hospital scale.
Perfusion Imaging Market Segmentation
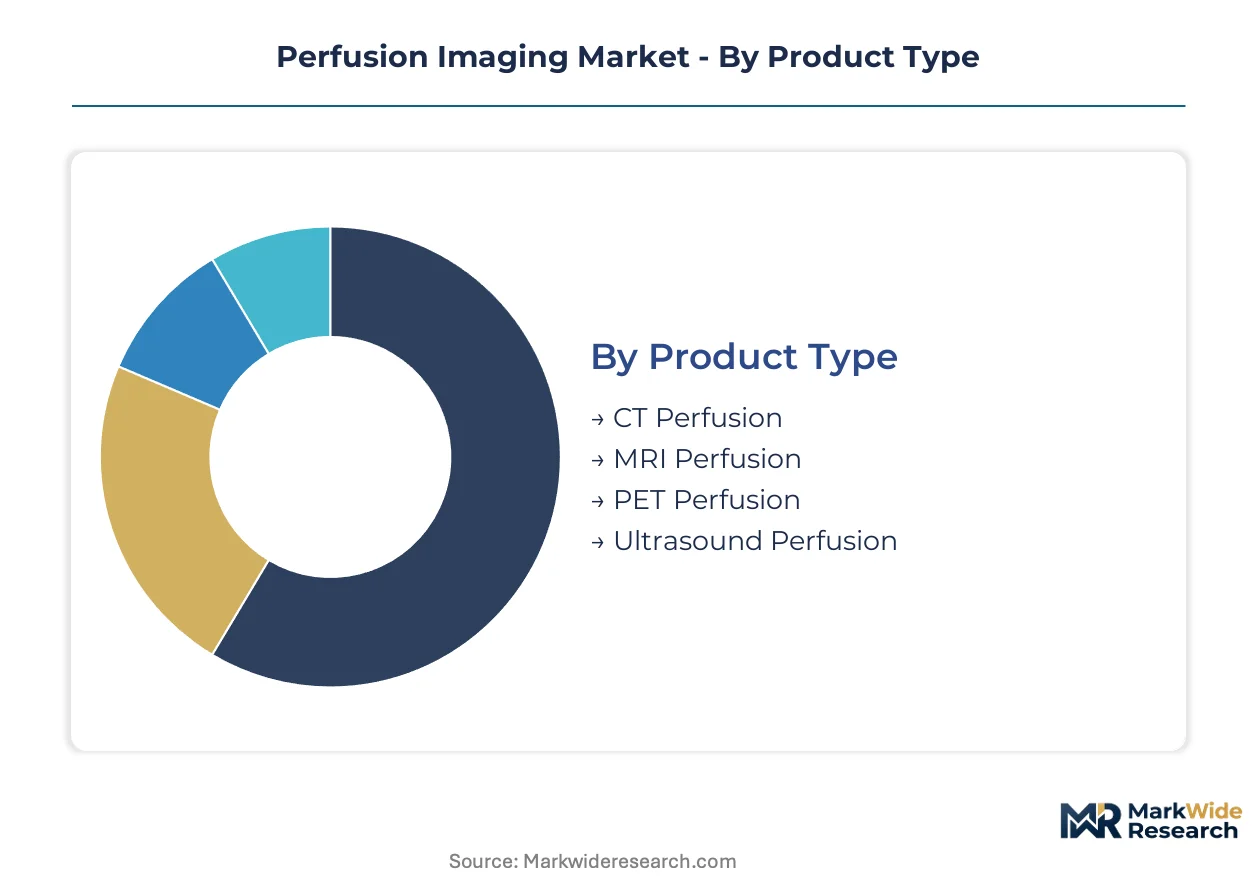
Perfusion imaging segmentation reveals how clinical workflows, capital deployment, and reimbursement pathways fragment demand across hardware, software, and consumable layers. Understanding these divisions exposes where procurement decisions concentrate purchasing power and where technology transitions disrupt incumbent positions.
Product Type:
Cost tier stratification separates emergency-ready hardware from capital-intensive specialized systems and emerging portable alternatives.
- CT Perfusion:Rapid acquisition protocols using iodinated contrast enable whole-brain coverage in under 60 seconds. Emergency departments at academic stroke centers in Germany and the United States are standardizing these workflows for triage decisions, though iodinated contrast pricing volatility squeezes operating margins.
- MRI Perfusion:Arterial spin-labeling techniques eliminate contrast requirements while quantifying blood-brain barrier permeability. University hospitals in Germany are embedding these protocols into neuro-oncology monitoring, opening reimbursement pathways for pediatric and renal-impaired populations where gadolinium retention risks constrain alternatives.
- PET Perfusion:Radiotracer-based quantification delivers metabolic-perfusion fusion imaging for myocardial viability assessment. Cardiac catheterization laboratories at tertiary centers deploy these systems for revascularization planning.
- Ultrasound Perfusion:Microbubble contrast agents enable bedside perfusion assessment without ionizing radiation. Outpatient cardiology clinics adopt these systems for stress testing where CT scanner access remains limited.
CT Perfusion holds installed capacity across emergency networks. MRI Perfusion is rotating up the share rankings as arterial spin-labeling protocols mature.
End User:
Customer type determines purchasing authority complexity, with integrated delivery networks consolidating procurement differently than independent diagnostic operators.
- Hospitals:Academic medical centers anchor advanced protocol development, embedding quantitative perfusion analysis into stroke and tumor boards. These institutions negotiate enterprise imaging agreements that bundle perfusion software licenses with PACS and RIS contracts.
- Diagnostic Centers:Independent imaging operators focus on high-volume CT perfusion for acute stroke referrals from regional emergency departments. Medicare reimbursement for quantitative perfusion biomarkers remains pending, constraining capital deployment for advanced analysis platforms.
- Research Institutes:Multi-center trial networks generate annotated perfusion datasets for machine learning classifier training. Fragmented data ownership across institutional silos complicates algorithm generalization efforts.
- Outpatient Clinics:Community cardiology practices deploy ultrasound perfusion for stress testing where hospital-based CT or MRI access requires patient transfer. Limited neuroradiologist availability restricts protocol complexity at this tier.
Hospitals command procurement volume through enterprise contracts. Diagnostic Centers are capturing referral flow as stroke networks regionalize.
Technology:
Margin concentration shifts from hardware toward software and consumables as reconstruction algorithms displace scanner-dependent acquisition advantages.
- Contrast Media:Iodinated and gadolinium-based agents face REACH disposal compliance costs and pricing volatility. ECHA wastewater handling restrictions elevate capital requirements for hospital radiology departments across European markets.
- Software Tools:Machine learning classifiers automate lesion detection and reduce inter-reader variability. FDA 510(k) clearance pathways under software-as-medical-device frameworks are shortening commercialization timelines for AI-enhanced perfusion analysis.
- Imaging Devices:CT and MRI system manufacturing concentrates among dominant vendors, creating supply vulnerability for perfusion-compatible hardware upgrades. Compressed-sensing acquisition protocols are collapsing temporal resolution requirements.
- Data Analysis Platforms:Cloud-native post-processing tools enable browser-based perfusion analysis, reducing on-premise workstation capital requirements. Hospital IT departments are adopting these deployments for remote radiologist access.
Imaging Devices represent the largest revenue base. Software Tools are climbing fastest as vendors embed capabilities directly into acquisition platforms.
Application:
Volume distribution across clinical domains reflects where quantitative perfusion biomarkers have achieved reimbursement recognition versus research-stage deployment.
- Oncology:MRI perfusion quantifies tumor angiogenesis and treatment response through blood volume and permeability mapping. Neuro-oncology applications face steepest EU AI Act compliance burden for clinical decision-support deployment.
- Neurology:Acute stroke protocols dominate CT perfusion volume, with automated mismatch detection guiding endovascular therapy selection. Compressed-sensing algorithms are eliminating dedicated research-grade scanner requirements.
- Cardiovascular:Myocardial perfusion imaging guides revascularization decisions in catheterization laboratories. PET perfusion fusion with metabolic imaging assesses viability in ischemic cardiomyopathy.
- Emergency Medicine:Whole-brain CT perfusion protocols compress triage timelines in emergency departments. Sub-60-second scan windows are replacing conventional multi-slice dynamic acquisitions.
Neurology anchors procedure volume through stroke protocols. Oncology is ascending as quantitative biomarker standardization progresses toward Medicare Category III CPT code recognition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in perfusion imaging equipment tilt toward net importing positions across advanced healthcare systems, with concentrated manufacturing in Germany, Japan, and the United States shaping regional availability of CT and MRI systems.
United States
FDA 510(k) clearance pathways for AI-enhanced perfusion software are accelerating commercialization timelines for software-as-medical-device frameworks. Medicare reimbursement decisions for quantitative perfusion biomarkers remain pending, constraining capital deployment at community hospitals. The Boston-Cambridge corridor anchors neuro-oncology protocol development at academic medical centers.
Germany
University hospitals across Bavaria and North Rhine-Westphalia are integrating quantitative perfusion analysis into routine stroke and tumor assessments, creating template workflows for European adoption. EU Medical Device Regulation harmonization reduces redundant clinical evidence requirements across member states. REACH restrictions on iodinated contrast disposal elevate capital requirements for radiology departments in the Eindhoven Region supply chain.
Japan
PMDA regulatory frameworks shape product development timelines for perfusion-compatible hardware upgrades. METI industrial policy supports domestic MRI system manufacturing, reducing import dependency for high-field scanners. The Kanto region around Tokyo concentrates tertiary stroke center deployment of compressed-sensing CT protocols.
China
NMPA approval pathways for imported perfusion software are extending commercialization timelines relative to domestic alternatives. Hospital procurement reforms under centralized volume-based purchasing compress pricing for iodinated contrast agents. The Yangtze River Delta region around Shanghai anchors deployment of AI-enhanced reconstruction algorithms in academic medical centers.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement access for advanced perfusion analysis platforms. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines for software-as-medical-device classifications. The London-Southeast corridor concentrates neuro-oncology trial networks generating annotated datasets for machine learning training.
Perfusion Imaging Market Competitive Environment
On the supply side, the industry is consolidating around integrated platform vendors that bundle hardware acquisition systems with embedded software capabilities, displacing standalone post-processing specialists. Three strategic archetypes dominate: diversified imaging conglomerates with full modality portfolios, contrast agent specialists with vertical integration into delivery systems, and AI-native software vendors seeking hardware partnerships. Competitive moves concentrate on enterprise imaging agreement bundling and cloud-native deployment architectures that reduce hospital IT capital requirements.
Among diversified imaging system manufacturers, Siemens Healthineers, GE Healthcare, and Canon Medical Systems exemplify the integrated platform archetype, each anchoring competitive positioning through proprietary reconstruction algorithms and compressed-sensing acquisition protocols. These vendors occupy positions where hardware-software integration determines procurement decisions at academic medical centers and integrated delivery networks.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Bracco Imaging |
| GE Healthcare |
| Bayer AG |
| Guerbet |
| Philips Healthcare |
| Fujifilm Holdings Corporation |
| Medtronic |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Iodinated contrast agent pricing volatility acts as the dominant risk vector, compressing margins across CT perfusion workflows while simultaneously reshaping procurement patterns toward multi-source supply agreements and contrast-free protocol alternatives. This input-cost instability determines both the spread between premium integrated-platform pricing and economy-tier standalone software, and the geographic reconfiguration of supply relationships as hospitals seek tariff-advantaged sourcing corridors.
Pricing Analysis
The generation-gap between compressed-sensing CT protocols, conventional multi-slice acquisitions, and emerging arterial spin-labeling MRI creates three distinct pricing tiers. Premium pricing attaches to integrated hardware-software bundles with embedded AI reconstruction, while standard tiers cover standalone post-processing licenses and economy positioning falls to legacy workstation-based analysis tools. Price differentiation hinges on FDA 510(k) clearance tier and enterprise imaging agreement bundling scale. Cost compression in the standard tier is intensifying because radiology group purchasing organizations are consolidating vendor evaluation criteria around interoperability certifications. Community hospitals exhibit highest price sensitivity due to pending Medicare reimbursement decisions, whereas academic medical centers demonstrate lowest sensitivity given research funding offsets.
Supply Chain Analysis
Contract manufacturing for CT and MRI system components concentrates among Siemens Healthineers' Forchheim facilities, GE Healthcare's Milwaukee operations, and Canon Medical Systems' Otawara production hubs. Geographic supply concentration centers on Germany, Japan, and the United States for high-field scanner assembly, with China and South Korea anchoring gradient coil and RF subsystem sourcing. Raw material dependencies encompass superconducting niobium-titanium wire, rare-earth permanent magnets, and iodinated contrast precursor chemicals. Single-source vulnerability persists for cryogenic cooling systems tethered to limited qualified suppliers. Distribution runs through direct sales forces for enterprise hospital contracts and specialized imaging distributors for mid-tier diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perfusion imaging market is crossing a platform-economics inflection where interoperability certifications and cloud-native deployment architectures are displacing standalone software procurement, rewarding vendors who embed capabilities into enterprise imaging ecosystems rather than point-solution positioning.
For Market Incumbents: Harden integrated platform defenses by accelerating compressed-sensing algorithm embedding directly into CT and MRI acquisition consoles, eliminating post-processing as a separable purchase decision. Deepen backward integration into contrast agent delivery systems to offset iodinated pricing volatility exposure. Priority certification investment should target ISO 13485-compliant software platforms positioning for Medicare Category III CPT code recognition, as reimbursement lock-in will determine whether advanced analysis achieves routine deployment or remains research-confined. For New Entrants and Emerging Players: Cloud-native browser-based perfusion analysis tools for remote radiologist access represent the most penetrable entry point, capitalizing on hospital IT departments' capital reduction imperatives. Pediatric and renal-impaired patient populations where gadolinium retention risks constrain alternatives offer a protected indication pathway for arterial spin-labeling MRI software specialization. Go-to-market execution should prioritize partnership with radiology group purchasing organizations consolidating vendor evaluation criteria, rather than direct hospital sales force buildout. For Investors and Strategic Acquirers: AI-native software vendors with FDA-cleared machine learning classifiers and established cloud deployment architectures present the most attractive acquisition target archetype, given their scarcity value in a consolidating integrated-platform landscape. Long-term viability across the analysis window hinges on whether quantitative perfusion biomarkers achieve reimbursement recognition or remain confined to research budgets. The signal to monitor is Medicare Category III CPT code advancement timelines, as coding recognition inflection will determine capital deployment velocity at community hospitals and diagnostic centers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | AI-enhanced perfusion software secures streamlined software-as-medical-device framework entry. |
| CE Marking Pathway | EU MDR harmonization reduces redundant clinical evidence requirements across member states. |
| Hospital System Partnership | Enterprise imaging agreements bundle perfusion licenses with PACS and RIS contracts. |
| Software Companion Development | Machine learning classifiers automate lesion detection and reduce inter-reader variability. |
| Reimbursement Strategy | Medicare Category III CPT code recognition enables transition from research to routine clinical deployment. |
Study Parameters
The analysis maps CT perfusion, MRI perfusion, PET perfusion, and ultrasound perfusion sub-sectors, each validated through neuroradiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers across primary interview programs. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement contract repositories. Bottom-up triangulation across equipment installation bases, procedure volume estimates, and software license deployment counts is reconciled with top-down market sizing derived from manufacturer revenue disclosures and trade flow analysis.
The forecast framework holds regulatory clearance timelines and reimbursement recognition schedules as fixed boundary conditions while varying technology adoption curves and hospital capital expenditure cycles across sensitivity scenarios. Segmentation dimensions modeled encompass product type, end user archetype, technology layer, and clinical application, with regional regulatory clusters capturing FDA, EMA, PMDA, and NMPA pathway differentiation. CAGRs are derived from logistic diffusion modeling of technology substitution patterns, with inputs including academic medical center protocol standardization rates and radiology group purchasing organization contract consolidation velocity.
Practitioners should monitor Medicare Category III CPT code advancement decisions, EU AI Act conformity assessment pathway finalization, and iodinated contrast pricing volatility indices for early signals of forecast revision. Forecasts reflect assumptions regarding reimbursement recognition timelines, regulatory harmonization progress, and technology substitution elasticity. Quarterly review of hospital capital expenditure surveys, GPO contract award announcements, and contrast agent manufacturer pricing disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
South America Mammography Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Breast Imaging Market