
 Rhinoplasty Implants Market | 2026-2036
Rhinoplasty Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Rhinoplasty Implants Market Analysis
Patient-specific 3D-printed implant modeling is fragmenting traditional manufacturing workflows across the rhinoplasty implants supply chain. Stryker leverages its orthopedic digital surgery infrastructure to extend design-to-implant workflows into facial aesthetics. Implantech anchors North American production with specialized silicone and Gore-Tex portfolios for revision rhinoplasty. GORE competes through expanded polytetrafluoroethylene formulations that dominate secondary dorsal augmentation procedures.
Rhinoplasty implants are biocompatible structural devices, typically fabricated from medical-grade silicone, porous high-density polyethylene, or expanded polytetrafluoroethylene, engineered to augment, reconstruct, or restore nasal dorsal and tip anatomy following trauma, congenital deformity, or aesthetic revision. Silicone implants retain the largest installed base due to decades of surgical familiarity and straightforward explantability, though Gore-Tex variants capture premium positioning where vascularized tissue integration reduces capsule contracture risk. Among end users, cosmetic surgeons and plastic surgeons command the highest procedure volumes, while ENT specialists increasingly share the reconstructive segment with craniomaxillofacial teams handling post-traumatic cases. The reconstructive surgery application segment exhibits faster expansion than pure aesthetic enhancement as trauma incidence and cancer reconstruction referrals rise in tertiary hospital networks.
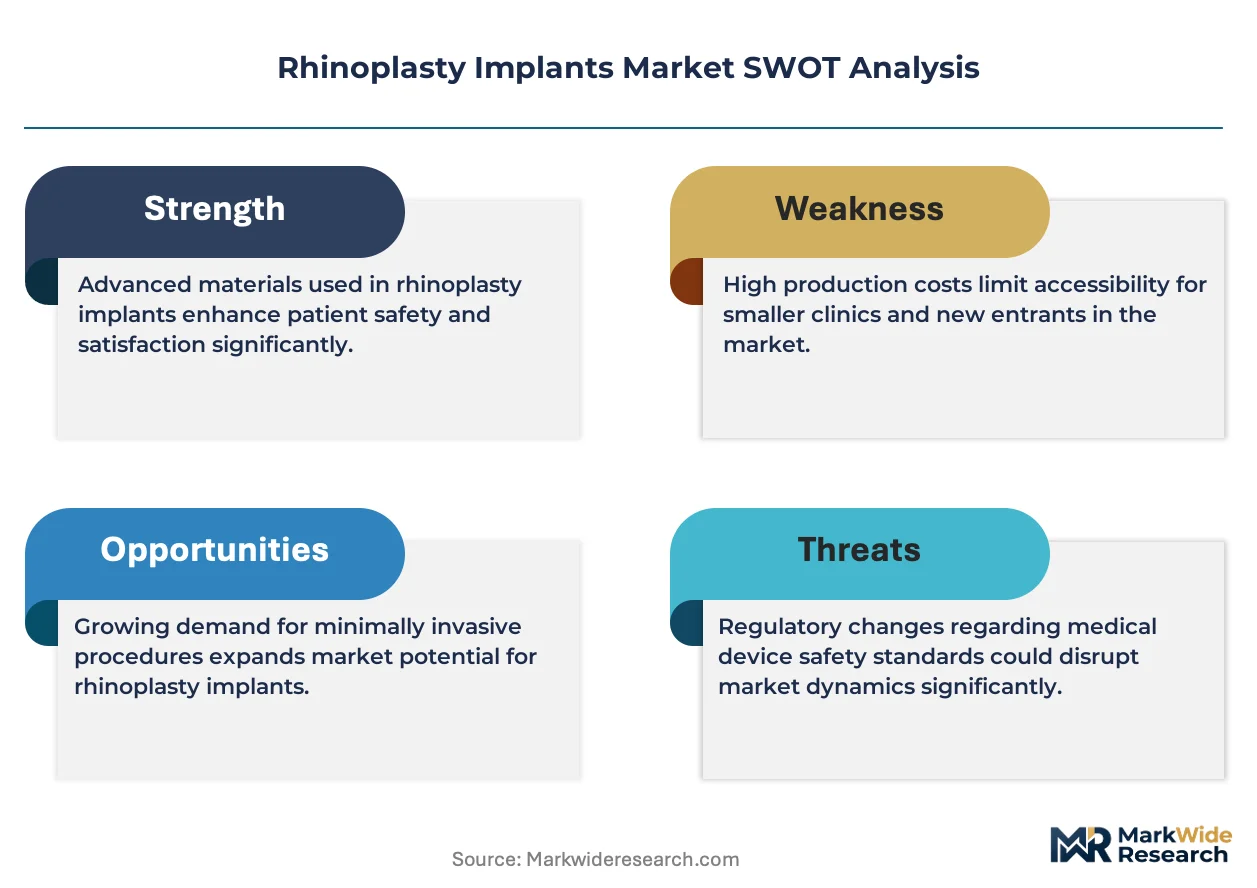
FDA 510(k) clearance pathways and the EU Medical Device Regulation impose distinct biocompatibility and clinical evidence thresholds that filter market entrants by testing capacity and notified body access. Japan's PMDA maintains stringent foreign body reaction documentation requirements that delay product registration for non-domestic manufacturers. Stakeholders must monitor evolving regulatory divergence between the FDA's streamlined predicate-based routes and the EU's intensified clinical evaluation demands, as this friction will determine which implant portfolios achieve multi-region commercialization without redundant trials.
Market Dynamics
Patient-specific 3D-printed implant modeling is fragmenting traditional manufacturing workflows across the rhinoplasty implants supply chain. This technological shift compresses design-to-implant timelines while elevating biocompatibility documentation burdens under evolving regulatory frameworks.
Growth Catalysts
- EU Medical Device Regulation (MDR):The intensified clinical evaluation demands filter weak market entrants and consolidate testing capacity among established manufacturers with notified body access.
- Revision rhinoplasty protocols:Minimally invasive revision procedures in South Korean aesthetic surgery clinics expand implant procurement volumes for secondary dorsal augmentation.
- Porous high-density polyethylene:This material captures reconstructive segment share where vascularized tissue integration reduces capsule contracture risk in post-traumatic cases.
Market Restraints
- Silicone raw material concentration:Supply chain vulnerability concentrates among specialty chemical producers in Germany and Japan, exposing manufacturers to input cost volatility and single-source dependency.
- PMDA foreign body reaction documentation:Japan's stringent registration requirements delay product entry for non-domestic manufacturers by 18-36 months versus FDA predicate pathways.
- Autologous cartilage harvesting:Surgeon preference for patient-derived tissue in primary rhinoplasty limits synthetic implant penetration in first-time aesthetic procedures.
Strategic Opportunities
- Brazil private cosmetic surgery sector:Rhinoplasty ranks among the most frequently performed aesthetic operations in this underpenetrated market for premium Gore-Tex formulations.
- Digital surgery infrastructure convergence:Integration of AI-driven anatomical mapping with 3D printing workflows enables same-day implant fabrication for revision cases.
- Reconstructive surgery expansion:Trauma incidence and cancer reconstruction referrals in tertiary hospital networks outpace pure aesthetic enhancement growth.
Industry Challenges
- Craniomaxillofacial surgeon training:The skill gap in complex nasal reconstruction limits adoption of advanced porous polyethylene implants in post-traumatic cases.
- Notified body capacity constraints:EU MDR implementation bottlenecks delay CE marking timelines and compress working capital cycles for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhinoplasty Implants Market |
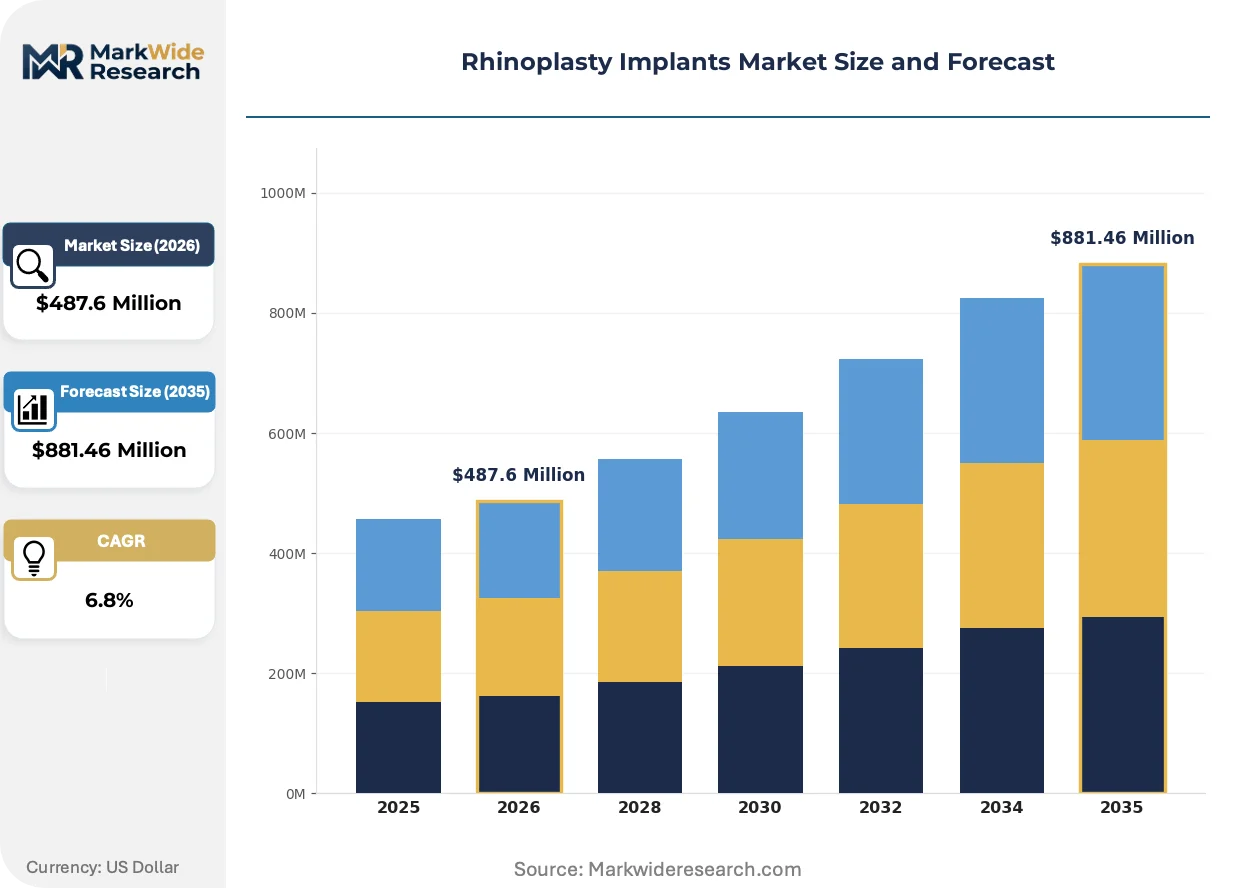
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Implants, Gore-Tex Implants, Medpor Implants, Autologous Grafts End User: Cosmetic Surgeons, Plastic Surgeons, ENT Specialists, Hospitals Material: Silicone, Polyethylene, Biological Tissue, Synthetic Material Application: Cosmetic Surgery, Reconstructive Surgery, Trauma Treatment, Aesthetic Enhancement |
| Companies Covered | Stryker, Implantech, Surgiform, Galderma, GORE, Acteon Medical, HANSON MEDICAL, Koken, Spectrum Designs Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhinoplasty Implants Market Emerging Trajectories
Digital fabrication technologies and regulatory recalibration are simultaneously compressing product development cycles and elevating clinical evidence thresholds. These forces reshape competitive positioning around design-to-implant speed and multi-region compliance infrastructure.
Patient-specific 3D-printed implant modeling is virtualizing the traditional silicone molding workflow that dominated rhinoplasty implant manufacturing for decades. Cosmetic surgery clinics in Seoul and São Paulo are adopting this technology fastest, driven by revision case volume and patient demand for anatomical precision. The structural consequence compresses inventory carrying costs while fragmenting production across distributed fabrication nodes rather than centralized molding facilities.
REACH substance restrictions and EU MDR biocompatibility benchmarks are tightening permissible additive profiles in medical-grade silicone formulations. Manufacturers must reformulate surface texturing chemistries to maintain CE marking, elevating R&D expenditure for European market access. The premium Gore-Tex segment faces less friction here, as expanded polytetrafluoroethylene formulations already satisfy the intensified purity documentation.
Surgeon procurement patterns are consolidating around integrated design-to-implant service contracts rather than discrete product purchasing. Aesthetic surgery clinics in South Korea now expect vendor-managed inventory with same-day custom fabrication, displacing the traditional distributor-held stock model. This behavioral shift concentrates purchasing power among vertically integrated manufacturers with captive digital surgery infrastructure.
Rhinoplasty Implants Market Segmentation
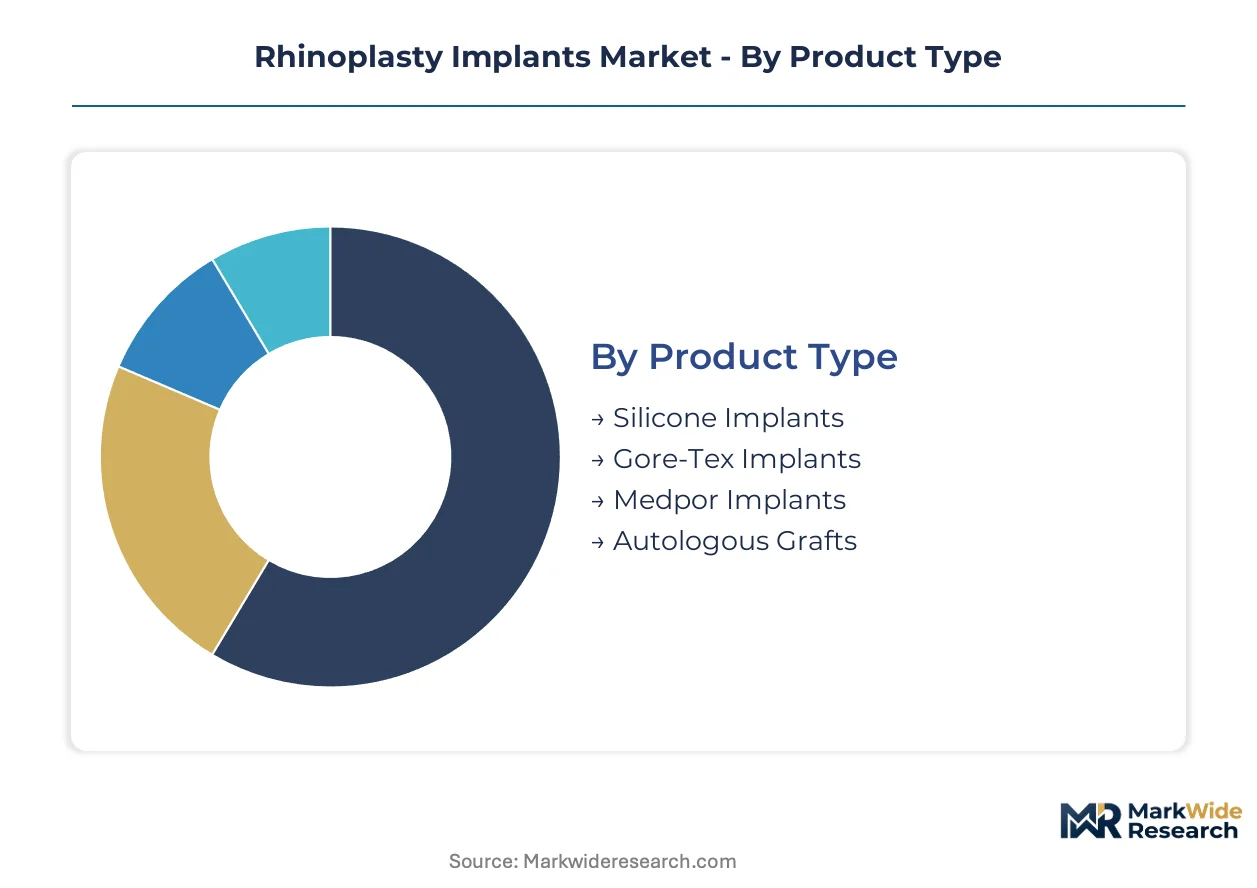
Implant selection in rhinoplasty hinges on tissue integration requirements, explantability risk, and revision complexity. Segmentation reveals how material science and surgical specialty reshape procurement patterns across primary and secondary procedures.
Product Type:
The use-case spectrum spans permanent synthetic augmentation to patient-derived reconstruction, with each option carrying distinct capsular contracture profiles and explantation protocols.
- Silicone Implants:Medical-grade solid silicone formulations dominate dorsal augmentation due to decades of surgical familiarity and straightforward explantability. South Korean aesthetic clinics procure these in highest volumes for minimally invasive revision protocols where implant exchange frequency runs elevated.
- Gore-Tex Implants:Expanded polytetrafluoroethylene structures permit vascularized tissue ingrowth that reduces capsule formation risk in secondary procedures. Brazil's private cosmetic surgery sector favors these for dorsal augmentation where patient demand for permanent integration outweighs cost sensitivity.
- Medpor Implants:Porous high-density polyethylene enables osseointegration in complex post-traumatic reconstruction.
- Autologous Grafts:Patient-derived cartilage from septal, conchal, or costal sources eliminates foreign body reaction risk entirely.
The dominant share belongs to Silicone Implants, while Gore-Tex Implants is closing the gap fastest.
End User:
Procurement authority concentrates differently across elective aesthetics versus trauma reconstruction, with each specialty commanding distinct implant specifications and volume scales.
- Cosmetic Surgeons:These practitioners drive aesthetic rhinoplasty volume in private clinic settings, with Seoul and São Paulo clusters representing concentrated demand pockets for same-day custom fabrication services.
- Plastic Surgeons:Board-certified plastic surgeons handle complex revision cases and combined facial procedures, often specifying Gore-Tex for dorsal augmentation where prior silicone failure occurred.
- ENT Specialists:Otolaryngologists share reconstructive segment demand with craniomaxillofacial teams, particularly in tertiary hospital networks managing post-traumatic nasal defects.
- Hospitals:Institutional procurement channels serve cancer reconstruction and trauma referrals, with porous polyethylene implants preferred for structural restoration.
Cosmetic Surgeons command the highest procedure volumes, while ENT Specialists are expanding their implant procurement fastest through reconstructive case referrals.
Material:
Supply chain configuration determines availability and regulatory pathway complexity, with synthetic formulations facing REACH substance restrictions while biological sources encounter harvesting variability.
- Silicone:Specialty chemical producers in Germany and Japan supply medical-grade formulations subject to EU MDR biocompatibility intensification.
- Polyethylene:Porous high-density polyethylene structures from Implantech and Stryker anchor reconstructive applications requiring tissue integration.
- Biological Tissue:Autologous cartilage and processed allografts eliminate foreign body risk but introduce harvest site morbidity and supply inconsistency.
- Synthetic Material:Engineered polymers beyond silicone and PTFE occupy niche positions where specific mechanical properties or surface chemistries are required.
Silicone retains installed base dominance, though Biological Tissue is gaining share fastest as surgeon training in cartilage harvesting expands.
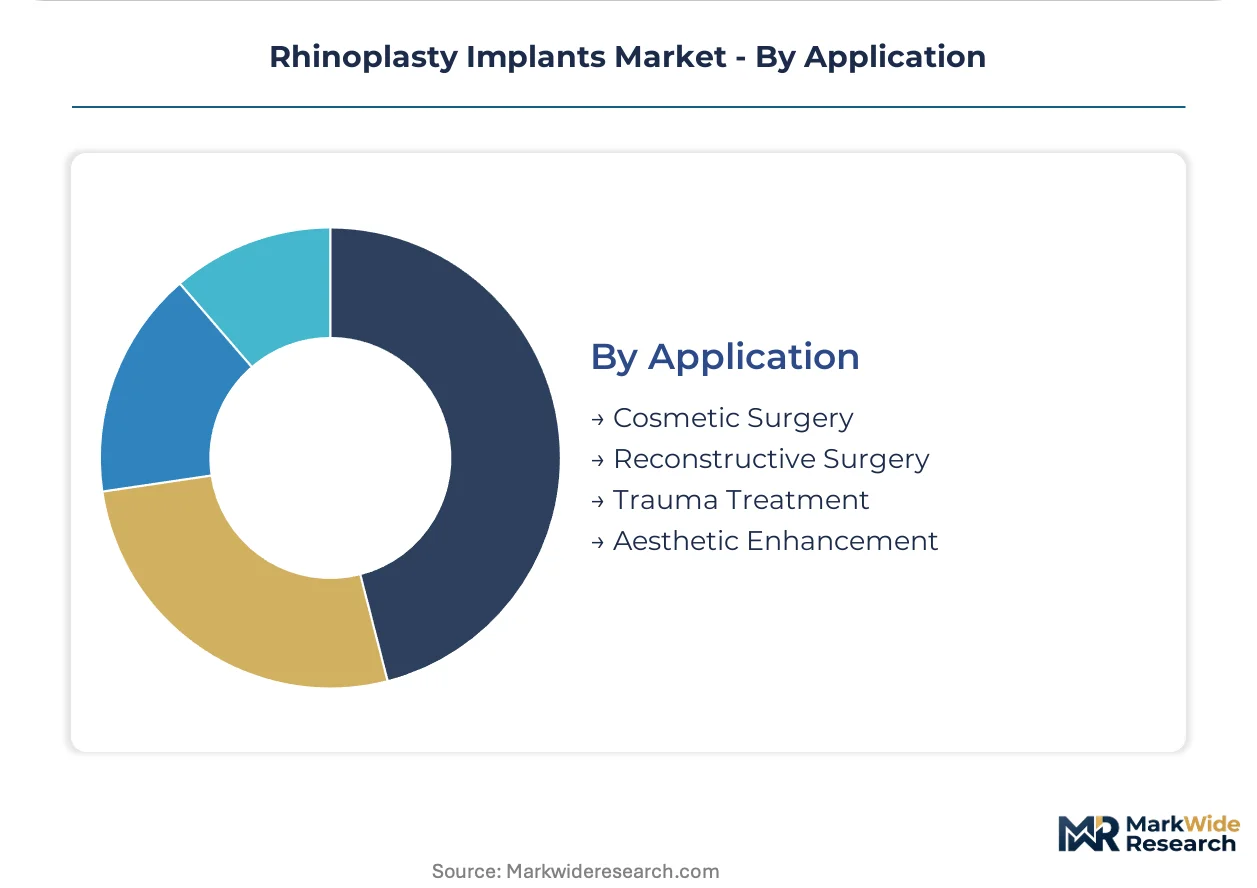
Application:
Procedure intent separates elective aesthetic modification from functional restoration, with each application carrying distinct reimbursement pathways and outcome documentation requirements.
- Cosmetic Surgery:Elective nasal reshaping procedures in private pay settings generate the highest absolute implant consumption, particularly in Brazil where rhinoplasty ranks among the most frequently performed aesthetic operations.
- Reconstructive Surgery:Post-cancer and congenital defect correction drives faster expansion than pure aesthetics, with tertiary hospital networks in South Korea and the United States referring complex cases to craniomaxillofacial teams.
- Trauma Treatment:Acute nasal fracture management and delayed post-traumatic reconstruction require implants with structural rigidity and infection resistance.
- Aesthetic Enhancement:Subtle refinement procedures distinct from primary cosmetic surgery often employ smaller profile implants or injectable augmentation alternatives.
Cosmetic Surgery holds the dominant share, while Reconstructive Surgery is expanding most quickly through rising trauma incidence and cancer reconstruction referrals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical producers export medical-grade silicone formulations to aesthetic surgery clinics in Seoul and São Paulo, establishing the primary trade-flow corridor for rhinoplasty implant raw materials.
United States
FDA 510(k) clearance pathways enable faster predicate-based product registration than European routes, attracting revision rhinoplasty device submissions. The agency's streamlined biocompatibility documentation supports silicone implant manufacturers targeting secondary dorsal augmentation procedures. Craniomaxillofacial surgical clusters in Greater Boston and the Pacific Northwest drive demand for porous polyethylene implants in post-traumatic reconstruction.
South Korea
MFDS maintains stringent foreign body reaction documentation that shapes domestic manufacturing standards while Seoul's Gangnam aesthetic surgery district procures elevated volumes of silicone implants for minimally invasive revision protocols. The capital's design-to-implant service contracts now require same-day custom fabrication capabilities from vendor partners.
Brazil
ANVISA regulates medical device registration for the private cosmetic surgery sector where rhinoplasty ranks among the most frequently performed aesthetic operations. São Paulo's private clinic networks favor Gore-Tex formulations for dorsal augmentation where patient demand for permanent tissue integration outweighs cost sensitivity.
Japan
PMDA foreign body reaction documentation requirements delay product entry for non-domestic manufacturers by 18-36 months versus FDA pathways, protecting domestic suppliers. Tokyo's tertiary hospital networks refer complex cancer reconstruction cases to craniomaxillofacial teams preferring porous high-density polyethylene for structural nasal restoration.
Germany
EU Medical Device Regulation biocompatibility benchmarks and REACH substance restrictions tighten permissible additive profiles in medical-grade silicone formulations. Specialty chemical producers in Bavaria and North Rhine-Westphalia supply raw material inputs to implant fabricators across Europe, exposing the supply chain to single-source concentration risk.
Rhinoplasty Implants Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement hierarchies. The vendor base concentrates around three strategic archetypes: diversified orthopedic conglomerates extending digital surgery infrastructure, dedicated facial implant fabricators with specialized silicone and polymer portfolios, and materials science specialists dominating premium porous polyethylene segments. Dominant competitive moves include backward integration into raw material supply and strategic partnerships with aesthetic surgery clinic networks for vendor-managed inventory contracts.
Among North American-based manufacturers, Stryker and Implantech occupy distinct positioning archetypes. Stryker exemplifies the diversified orthopedic conglomerate model, leveraging scale advantages in digital surgery infrastructure. Implantech represents the dedicated facial implant fabricator archetype with specialized production focus. Gore sits within the materials science specialist tier, its expanded polytetrafluoroethylene formulations anchoring premium positioning in secondary dorsal augmentation where tissue integration requirements elevate product specifications.
| Leading Market Players |
|---|
| Stryker |
| Implantech |
| Surgiform |
| Galderma |
| GORE |
| Acteon Medical |
| HANSON MEDICAL |
| Koken |
| Spectrum Designs Medical |
| Others |
Supply Flow & Price Mechanics
Freight corridors connecting German specialty chemical producers to Seoul and São Paulo aesthetic surgery clinics transmit input cost volatility into downstream price stratification, compressing margins for centralized molding facilities while elevating premiums for distributed 3D-printed fabrication nodes.
Pricing Analysis
Technology-generation pricing gaps separate legacy silicone molding workflows from emerging patient-specific 3D-printed fabrication and next-generation AI-integrated design platforms. Pricing stratifies across premium, standard, and economy tiers where Gore-Tex formulations command brand premiums for vascularized tissue integration, while silicone variants compete on volume scale and explantability. Pricing pressure stems from REACH substance restrictions forcing reformulation R&D expenditure for European market access. Academic medical centers exhibit highest price sensitivity due to institutional procurement constraints, whereas private aesthetic surgery clinics in South Korea demonstrate lowest sensitivity for same-day custom fabrication services.
Supply Chain Analysis
Upstream medical-grade silicone feedstock concentrates among specialty chemical producers in Germany and Japan, with porous high-density polyethylene resins drawing from North American petrochemical complexes. Raw material dependencies center on organosilicon precursors, PTFE polymerization feedstocks, and precision milling equipment for porous polyethylene structuring. Single-source vulnerability in German silicone additive suppliers exposes manufacturers to regulatory-driven formulation disruptions. Distribution runs through vendor-managed inventory contracts displacing traditional distributor-held stock models, with integrated design-to-implant service providers capturing direct clinic relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as patient-specific 3D-printed implant modeling fragments traditional manufacturing workflows, creating specialized niches for digital surgery infrastructure providers and regional fabrication specialists.
For Market Incumbents: Pre-empt entrant disruption by backward integration into medical-grade silicone raw material supply and captive acquisition of notified body relationships for EU MDR compliance. Consolidate testing capacity advantages to filter mid-tier competitors facing CE marking bottlenecks. Anchor procurement relationships through vendor-managed inventory contracts with same-day fabrication capabilities. For New Entrants and Emerging Players: Mid-market porous polyethylene implants for post-traumatic reconstruction in tertiary hospital networks represent the most penetrable entry point, given craniomaxillofacial surgeon training gaps limiting incumbent penetration. Brazil's private cosmetic surgery sector offers secondary opportunity where Gore-Tex supply constraints create availability windows. Pursue GPO contracting pathways with hospital purchasing committees rather than direct clinic sales models. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates seeking to divest non-core facial aesthetic portfolios lacking digital surgery infrastructure integration. Long-term viability favors vertically integrated manufacturers with captive 3D printing workflows and multi-region regulatory filings. Watch FDA 510(k) clearance velocity versus EU MDR notified body queue lengths as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership | CE marking pathway acceleration under EU MDR compresses working capital cycles for mid-tier manufacturers. |
| Digital Surgery Platform Integration | AI-driven anatomical mapping with 3D printing workflows enables same-day implant fabrication for revision cases. |
| Raw Material Backward Integration | In-house production of medical-grade silicone formulations insulates against REACH-driven additive reformulation costs. |
| Hospital System Partnership | GPO contracts with tertiary networks capture reconstructive surgery expansion outpacing pure aesthetic growth. |
| Reimbursement Strategy Development | Coding alignment with cancer reconstruction and trauma treatment pathways unlocks institutional procurement channels. |
Methodological Framework
A spread of perspectives from plastic surgeons, cosmetic surgery clinic procurement directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underpinning volume and value estimates. Primary interviews with ENT specialists and craniomaxillofacial teams combined with secondary validation against FDA 510(k) filings, EU MDR notified body databases, MFDS registration records, and hospital procurement databases. Bottom-up implant shipment estimates triangulated with top-down aesthetic and reconstructive procedure counts across the analysis window.
Demand-supply-balance framing anchored the analytical framework across product type, material formulation, end-user specialty, and application intent segmentation dimensions. CAGRs derived from procedure volume elasticity to demographic shifts and material substitution dynamics. Industry-specific forecast inputs incorporated PMDA foreign body reaction documentation timelines and South Korean minimally invasive revision protocol adoption curves.
Macroeconomic conditions sit as an overlay; deviation in private healthcare expenditure cycles and medical tourism flows would shift the trajectory. Forecasts reflect documented assumptions around regulatory pathway efficiency and surgeon training expansion rates. Material shifts in EU MDR biocompatibility benchmark stringency or PMDA documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electrophysiology Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Cervical Retractors Market
Medical Devices
Pleural Catheters Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Knee Braces Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Human Augmentation in Healthcare Market