
 High Frequency Trading Server Market | 2026-2036
High Frequency Trading Server Market Size, Share, and Industry Trends Forecast 2026-2036
High Frequency Trading Server Market Intelligence
Proprietary trading firms is consolidating share of server procurement as hedge funds trim infrastructure budgets. Super Micro Computer, Inc. leverages modular designs to capture colocation deployments. Dell Inc. sustains enterprise-grade reliability for investment bank data centers. Hewlett Packard Enterprise Development LP anchors high-density cooling architectures in exchange-adjacent facilities.
A high frequency trading server is a purpose-built compute platform engineered for sub-microsecond order execution, typically incorporating FPGA acceleration cards, kernel-bypass networking stacks, and liquid-cooled processors operating at sustained turbo frequencies. Its primary commercial function is to minimize tick-to-trade latency for algorithmic strategies where nanosecond advantages determine profitability. Dedicated servers retain the dominant margin pool due to deterministic performance requirements, though cloud-based solutions are gaining traction among retail-facing brokerages seeking elastic capacity. FPGA technology leads deployment in latency-arbitrage applications, while software optimization captures cost-sensitive volume segments.
The SEC and FINRA govern order handling and market access rules that directly shape server placement and audit trail capabilities. CFTC regulations on automated trading further mandate risk controls that influence hardware redundancy specifications. Stakeholders must monitor evolving exchange co-location fee structures and cross-border data residency requirements as these factors increasingly determine total cost of ownership for trading infrastructure.
Market Dynamics
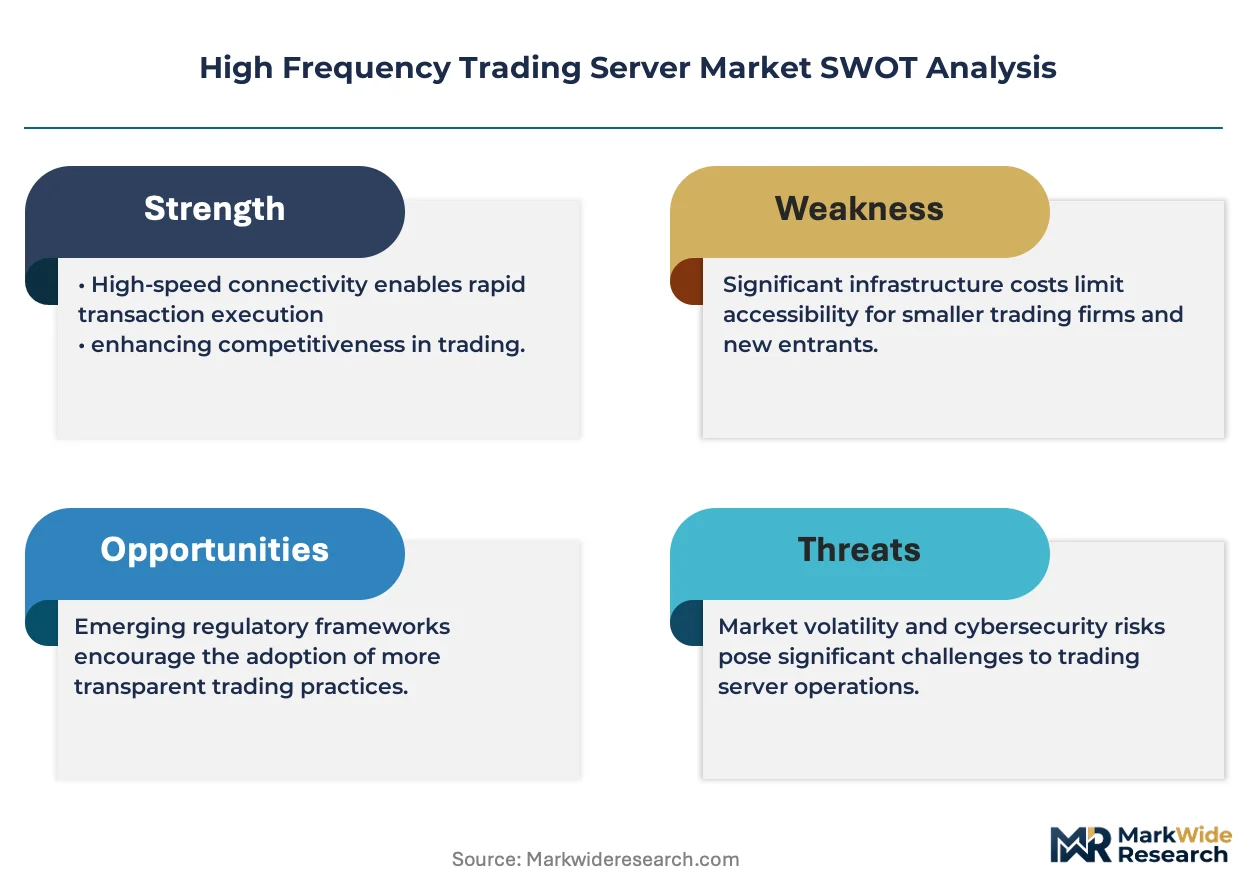
The migration of proprietary trading firms from hedge fund infrastructure to direct server ownership is compressing procurement cycles and tightening latency specifications across exchange-adjacent data centers.
Growth Catalysts
- FPGA Acceleration Adoption:Field-programmable gate arrays now dominate tick-to-trade pipelines, enabling sub-microsecond execution for latency-arbitrage strategies in New Jersey and Chicago clusters.
- SEC Market Access Rule Compliance:Pre-trade risk control mandates under Regulation SCI are forcing infrastructure upgrades that favor purpose-built hardware over general-purpose cloud instances.
- Colocation Proximity Requirements:Exchange-matched data center expansion in the United States is driving rack-density investments and liquid-cooled server deployments.
Market Restraints
- Copper and Silicon Supply Concentration:Taiwan-based foundry capacity constraints for advanced networking chips create six-month lead time volatility for kernel-bypass NIC procurement.
- CFTC Automated Trading Risk Controls:Hardware redundancy specifications mandated for derivatives market access inflate capital expenditure floors for smaller proprietary shops.
- Cloud Substitution Pressure:Retail-facing brokerages are migrating latency-tolerant workloads to elastic compute, eroding the addressable market for dedicated bare-metal deployments.
Strategic Opportunities
- Secondary Exchange Expansion:IEX and MEMX matching engine deployments in New Jersey are creating new colocation demand from market makers seeking alternative liquidity pools.
- EU MiFID II Best Execution Mandates:European regulatory pressure on execution quality is opening procurement channels for timestamp-harmonized server infrastructure in Frankfurt and London.
- AI-Infused Market Making Convergence:Machine learning inference accelerators are merging with traditional FPGA stacks, creating hybrid architecture demand among quantitative funds.
Industry Challenges
- Kernel-Bypass Engineering Talent Scarcity:DPDK and RDMA specialization commands premium compensation, constraining deployment velocity for mid-tier trading firms.
- Exchange Certification Timelines:FIX protocol conformance testing and order gateway validation create three-to-six month integration delays for new hardware rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Frequency Trading Server Market |
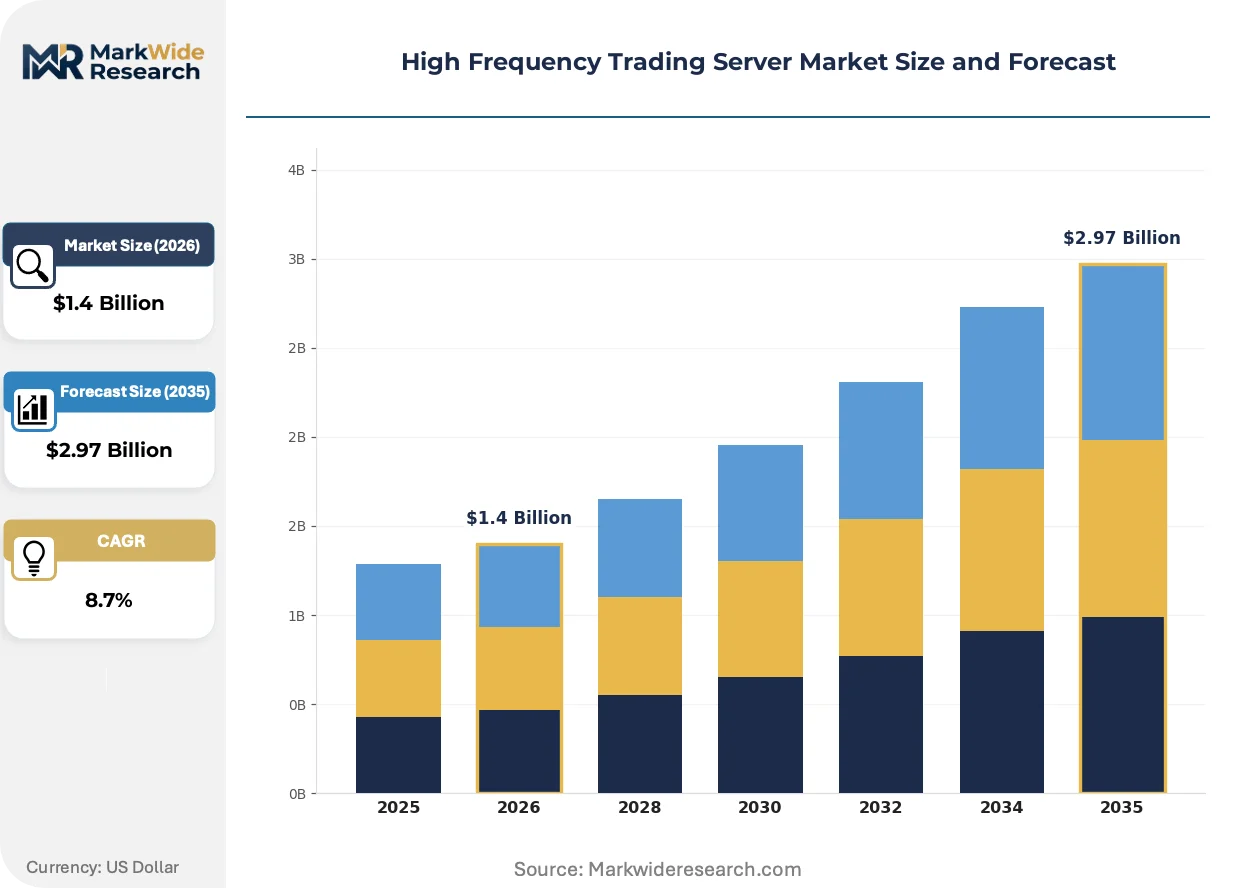
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Server Type: Dedicated Servers, Cloud-Based Solutions, Virtual Machines, Hybrid Systems Technology: FPGA, ASIC, Software Optimization, Low-Latency Networking End User: Investment Banks, Hedge Funds, Proprietary Trading Firms, Retail Traders Deployment Model: On-Premises, Colocation Services, Public Cloud, Private Cloud |
| Companies Covered | Super Micro Computer, Inc., Dell Inc., Hewlett Packard Enterprise Development LP, Lenovo, Hypertec Group Inc., HyperShark Technologies Corp., ASA Computers, Inc., SMART Global Holdings, Inc., Exacta Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Frequency Trading Server Market Strategic Shifts & Innovations
Hardware-software co-design is collapsing the traditional separation between network interface cards and compute silicon, reshaping how trading firms architect execution stacks.
SmartNICs with embedded ARM cores is decentralizing packet processing from host CPUs, allowing proprietary trading firms to offload order validation and risk checks directly to network hardware. Firms deploying these architectures in Chicago's Aurora data center cluster are reporting measurable latency reductions in their market-making engines. The technology is decentralizing the traditional server hierarchy and compressing the physical footprint required for high-performance trading.
FINRA's Consolidated Audit Trail mandate is forcing timestamp granularity upgrades across broker-dealer infrastructure, with microsecond synchronization requirements now extending to co-located server farms. The regulation is driving investment in precision time protocol hardware and GPS-disciplined oscillators. Smaller proprietary shops in New Jersey are responding by pooling calibration resources through third-party timing-as-a-service providers.
Buy-side infrastructure teams are unbundling hardware procurement from managed colocation contracts, negotiating direct server purchases while retaining rack-space leases. This pattern is displacing the traditional bundled pricing model that dominated exchange-adjacent facilities for the past decade. The shift is most visible among quantitative hedge funds in the United States seeking depreciation tax advantages and hardware refresh autonomy.
High Frequency Trading Server Market Segmentation
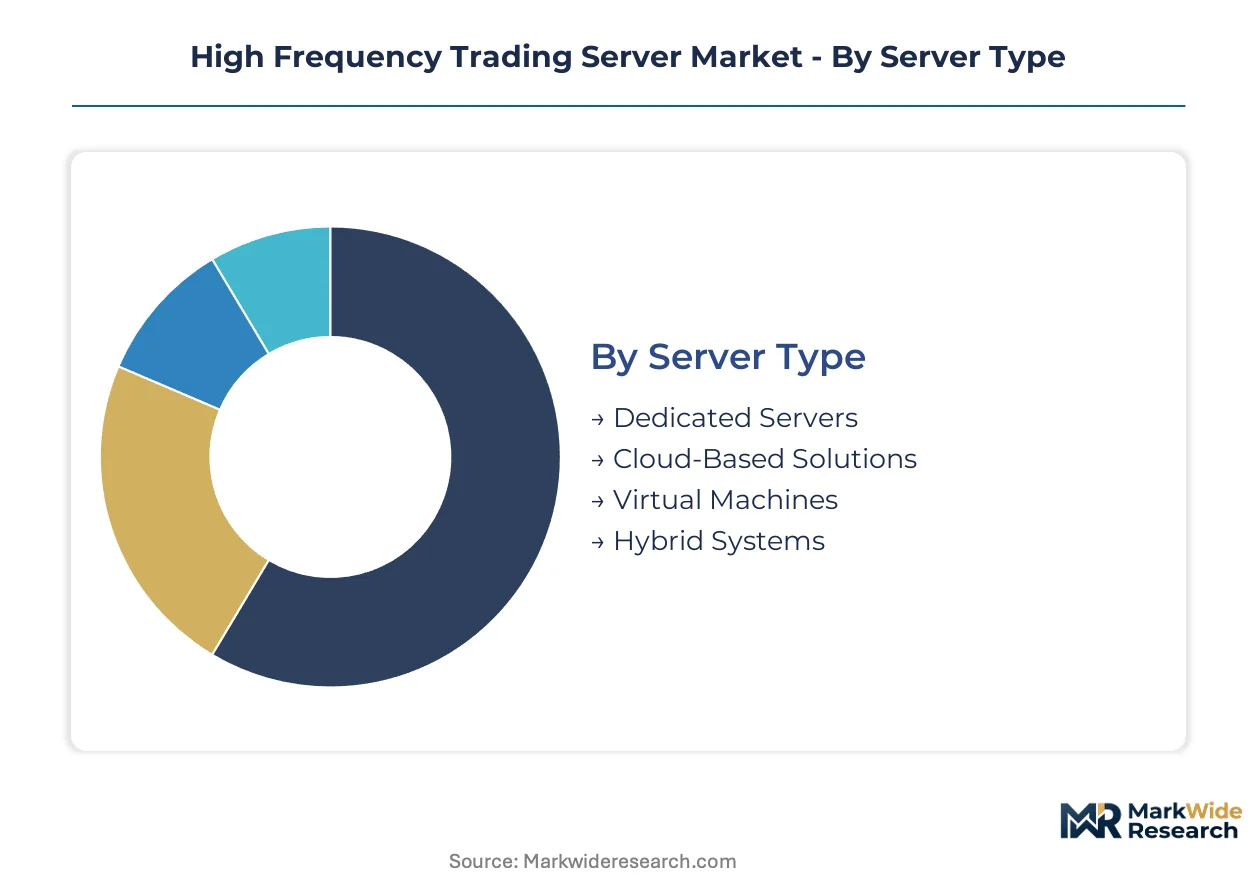
Trading infrastructure procurement splits sharply between latency-sensitive and cost-sensitive buyers, with deployment architecture and acceleration technology determining competitive viability. Segment boundaries are hardening as proprietary trading firms consolidate server ownership while retail-facing operations migrate to elastic compute.
Server Type:
Dedicated servers command premium budgets from firms where deterministic performance separates profitable strategies from losses, while cloud elasticity attracts capital-constrained entrants.
- Dedicated Servers:Bare-metal platforms with FPGA acceleration cards and kernel-bypass networking stacks deliver sub-microsecond tick-to-trade latency. Proprietary trading firms in New Jersey and Chicago clusters drive procurement as latency-arbitrage strategies expand.
- Cloud-Based Solutions:Elastic compute instances with pay-per-use pricing enable rapid strategy deployment without capital commitment. Retail brokerages seeking variable capacity represent the core demand pool.
- Virtual Machines:Partitioned compute resources running on shared hardware sacrifice determinism for cost efficiency. Smaller quantitative shops use these for backtesting and non-critical workloads.
- Hybrid Systems:Architectures blending bare-metal execution engines with cloud-based analytics layers. Mid-tier hedge funds deploy these to balance latency requirements against infrastructure flexibility.
Dedicated servers lead volumes today; cloud-based solutions are gaining share fastest.
Technology:
Acceleration method selection separates firms competing on nanosecond advantages from those optimizing total cost per trade.
- FPGA:Reconfigurable logic gates executing order validation and risk checks in hardware rather than software. Latency-arbitrage specialists in exchange-adjacent facilities require these for tick-to-trade pipelines.
- ASIC:Custom silicon delivering fixed-function acceleration with lower power consumption than programmable alternatives. High-volume market makers justify NRE costs through operational efficiency at scale.
- Software Optimization:Kernel-bypass networking stacks and cache-conscious algorithms on standard x86 processors. Cost-sensitive volume traders accept microsecond penalties for capital efficiency.
- Low-Latency Networking:Specialized NICs with RDMA and DPDK offloads minimizing host CPU involvement in packet processing. Colocation providers bundle these into premium rack offerings.
FPGA deployments dominate latency-sensitive applications; software optimization is climbing the fastest as mid-tier firms prioritize capital efficiency.
End User:
Buyer type determines procurement cycle length, latency specification stringency, and willingness to absorb infrastructure capital intensity.
- Investment Banks:Enterprise-grade reliability requirements with redundant hardware configurations and comprehensive audit trails. These institutions sustain demand for vendor-managed deployments with SLA guarantees.
- Hedge Funds:Quantitative strategy shops unbundling hardware procurement from colocation contracts to capture depreciation benefits. Infrastructure autonomy is displacing bundled service agreements.
- Proprietary Trading Firms:Latency-obsessed operators owning servers directly and optimizing for nanosecond advantages. These buyers compress procurement cycles and drive specification tightening across the supply base.
- Retail Traders:Individual and small-firm participants accessing markets through broker-hosted platforms. Cloud-based execution dominates this price-sensitive segment.
Proprietary trading firms lead volumes today; hedge funds are expanding share fastest through infrastructure autonomy initiatives.
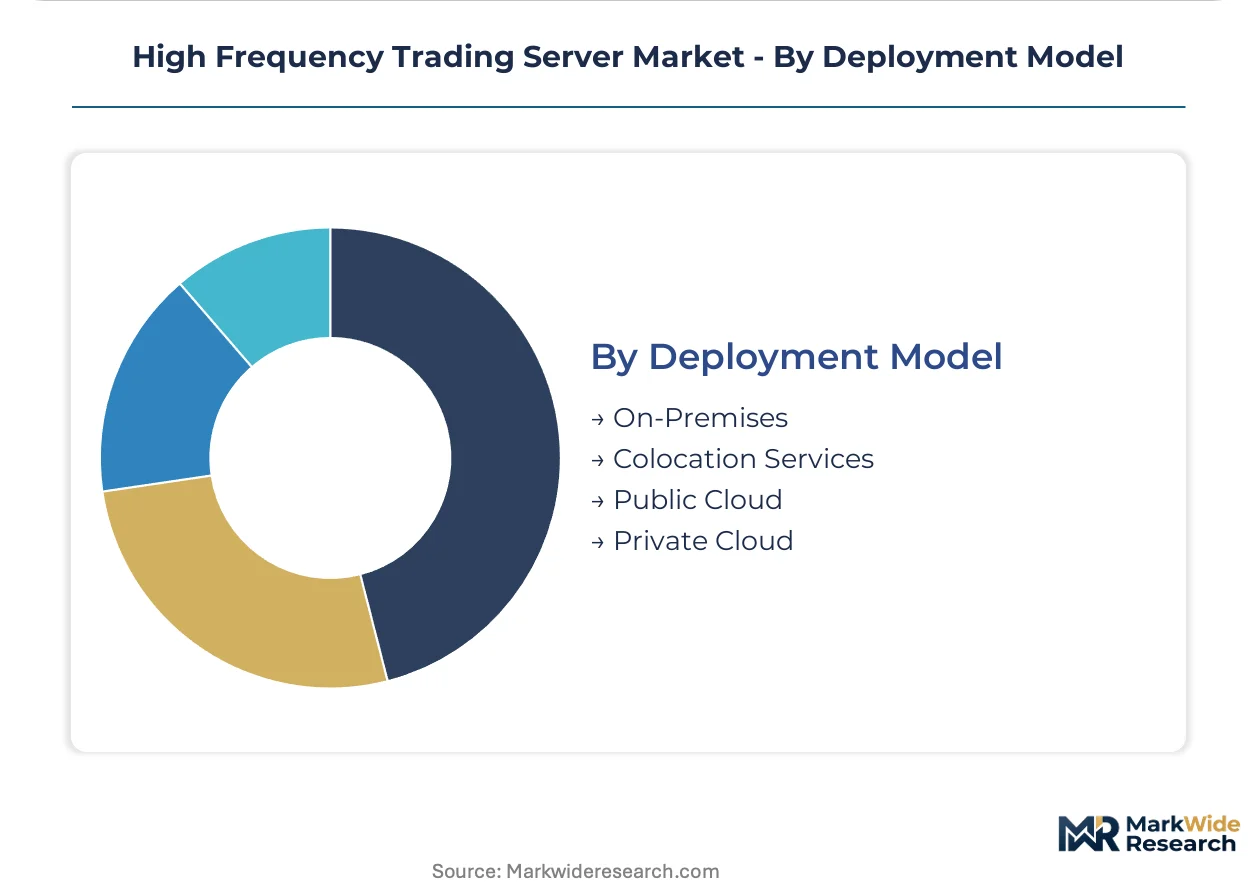
Deployment Model:
Physical proximity to matching engines and control over hardware refresh cadence define deployment architecture selection.
- On-Premises:Self-managed data centers with full hardware control and customized cooling infrastructure. Large proprietary shops with established facilities maintain this model for complete autonomy.
- Colocation Services:Rack space leased within exchange-matched facilities minimizing fiber distance to matching engines. The dominant deployment pattern for latency-sensitive strategies in United States clusters.
- Public Cloud:Shared infrastructure with geographic distribution and elastic scaling capabilities. Retail brokerages and latency-tolerant strategies utilize these for variable demand patterns.
- Private Cloud:Dedicated cloud environments with guaranteed resource isolation and custom networking configurations. Mid-tier quantitative funds adopt these for hybrid flexibility.
Colocation services lead volumes today; private cloud is gaining share fastest among mid-tier funds seeking hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping server procurement geography as compliance cost differentials between jurisdictions drive infrastructure placement decisions. Trading firms migrate hardware investments toward regions offering streamlined exchange access rules and favorable colocation fee structures. The United States retains dominant positioning due to matching engine density, though European and Asian financial centers are capturing incremental share through regulatory harmonization initiatives.
United States
SEC Regulation SCI and FINRA audit trail mandates are accelerating hardware refresh cycles among broker-dealers. CFTC automated trading risk controls specify hardware redundancy requirements that inflate capital expenditure floors. Exchange-matched data center clusters in New Jersey's Secaucus corridor and Chicago's Aurora facility anchor continental infrastructure investment.
United Kingdom
MiFID II best execution mandates are driving timestamp-harmonization investments across London-based trading infrastructure. The Financial Conduct Authority's market abuse surveillance requirements influence server logging and data retention specifications. The City of London and Docklands colocation facilities concentrate deployment for European equity and derivatives market access.
Germany
BaFin's high-frequency trading licensing regime imposes minimum latency disclosure standards that shape hardware procurement decisions. Eurex exchange proximity requirements in Frankfurt's Ostend district are tightening rack-density specifications. Deutsche Börse's co-location services in Eschborn and Frankfurt anchor Central European infrastructure deployment.
Singapore
Monetary Authority of Singapore's regulatory sandbox framework enables experimental trading infrastructure deployment with streamlined compliance pathways. Cross-border data residency requirements with ASEAN trading venues are influencing server placement decisions. The Marina Bay and Tanjong Koj data center districts concentrate matching engine proximity investments for Asia-Pacific market access.
Japan
Japan Exchange Group's co-location fee restructuring is altering total cost-of-ownership calculations for domestic trading firms. Financial Services Agency market surveillance upgrades are mandating enhanced timestamp granularity across broker-dealer infrastructure. The Tokyo-Otemachi and Osaka financial districts anchor domestic server deployment for derivatives and equity trading.
High Frequency Trading Server Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with dedicated server procurement favoring established hardware vendors while cloud-adjacent deployments opening channels for specialized integrators. Market structure concentrates around three tiers: enterprise-grade systems houses serving investment banks, modular specialists capturing proprietary trading firm demand, and regional assemblers addressing cost-sensitive volume segments. Dominant competitive moves include vertical integration into liquid-cooled chassis manufacturing and strategic partnerships with FPGA acceleration card suppliers.
Among California-based systems specialists, Super Micro Computer, Inc. exemplifies modular design architectures optimized for exchange-adjacent colocation density. Dell Inc. and Hewlett Packard Enterprise Development LP occupy positions within the enterprise reliability tier, serving investment bank data centers with comprehensive service level agreements. These three entities anchor the vendor landscape through differentiated approaches to latency-optimized hardware deployment.
| Leading Market Players |
|---|
| Super Micro Computer, Inc. |
| Dell Inc. |
| Hewlett Packard Enterprise Development LP |
| Lenovo |
| Hypertec Group Inc. |
| HyperShark Technologies Corp. |
| ASA Computers, Inc. |
| SMART Global Holdings, Inc. |
| Exacta Technologies |
| Others |
Cost & Logistics Intelligence
Kernel-bypass engineering talent concentration in New Jersey and Chicago widens pricing spreads between premium FPGA-accelerated tiers and software-optimized alternatives, as proprietary trading firms absorb labor-cost premiums while retail-facing brokerages drive standard-tier commoditization.
Pricing Analysis
Distributor margins on FPGA acceleration cards compress direct-to-OEM pricing for volume buyers, while colocation providers bundle premium rack space with liquid-cooled chassis at tiered performance levels. Price differentiation hinges on nanosecond-latency certification and geographic proximity to matching engines. Pricing pressure stems from cloud substitution among latency-tolerant workloads. Proprietary trading firms show least price sensitivity; retail brokerages demand economy-tier elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale proprietary firm demand, while value-added resellers serve mid-tier hedge funds with bundled deployment services. Taiwan, South Korea, and the United States concentrate advanced networking chip fabrication. Supply chains draw from copper interconnects, silicon wafers, and precision timing oscillators. Single-source vulnerability in Taiwan-based foundry capacity creates procurement volatility. Distribution runs through exchange-certified system integrators with FIX protocol validation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as proprietary trading firms consolidate server ownership and demand sub-microsecond deterministic performance regardless of capital intensity.
For Market Incumbents: Lock in FPGA acceleration card supply agreements with Taiwan-based foundries to defend against kernel-bypass NIC lead time volatility. Deepen backward integration into liquid-cooled chassis manufacturing to capture colocation density premiums and offset cloud substitution pressure in retail-facing segments. For New Entrants and Emerging Players: MiFID II best execution mandates in the United Kingdom open a window for timestamp-harmonized server infrastructure targeting European quantitative funds. Target Frankfurt and London colocation clusters with precision time protocol hardware offerings, leveraging third-party timing-as-a-service partnerships to bypass capital-intensive calibration investments. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking bare-metal capabilities to bridge latency gaps in hybrid trading architectures. Focus on mid-tier modular specialists with exchange-certified deployment track records. Watch for CFTC automated trading rule expansions as a signal for hardware redundancy specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Acceleration Partnership | Sub-microsecond execution pipelines in New Jersey and Chicago clusters capture latency-arbitrage profitability. |
| Liquid-Cooled Chassis Integration | Exchange-adjacent rack density investments meet sustained turbo frequency requirements for kernel-bypass networking. |
| Precision Timing Hardware Deployment | FINRA Consolidated Audit Trail compliance drives GPS-disciplined oscillator procurement across broker-dealer infrastructure. |
| Colocation Proximity Expansion | Secondary exchange matching engines in Secaucus corridor create alternative liquidity pool access for market makers. |
| Hybrid Cloud Architecture Development | Mid-tier hedge funds balance bare-metal execution engines with cloud analytics layers for infrastructure flexibility. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with proprietary trading firm infrastructure heads, hedge fund CTOs, colocation facility operators, FPGA acceleration card suppliers, and exchange technology officers with secondary validation against SEC filings, CFTC regulatory dockets, exchange co-location fee schedules, and customs import records for networking equipment. Bottom-up server deployment counts and top-down infrastructure spending estimates were triangulated.
Segment-weighting applied technology acceleration type, server deployment model, end-user category, and geographic colocation cluster as core dimensions across the modeling period. CAGRs derived from historical procurement cycle analysis and forward-looking latency specification tightening trends. Forecast inputs incorporated exchange-matched data center expansion timelines and regulatory mandate implementation schedules.
Revisions become necessary when foundry capacity constraints intensify, exchange certification timelines extend, or cloud substitution accelerates beyond latency-tolerant workload boundaries. Forecasts reflect documented assumptions on proprietary trading firm capital commitment levels and co-location fee trajectory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Nigeria Data Center Power Market