
 Data Center Life Cycle Services Market | 2026-2036
Data Center Life Cycle Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Life Cycle Services Market Analysis
A widening capability gap between hyperscale operators and regional service providers is redrawing competitive boundaries in data center life cycle services. IBM Corporation leverages deep consulting heritage across design and decommissioning phases. Schneider Electric anchors its position through integrated power and cooling infrastructure control. Tata Consultancy Services competes on cost-optimized delivery models across emerging Asian markets.
Data center life cycle services encompass the full spectrum of technical and operational support from initial site selection through final equipment retirement, typically governed by uptime tier classifications and power density specifications measured in kilowatts per rack. These services ensure continuous availability of compute, storage, and network infrastructure for enterprise and cloud workloads. Implementation services currently capture the largest share of value as rack densities exceed 30kW in AI training facilities. Maintenance services represent the fastest-expanding margin pool as thermal management complexity rises with liquid cooling adoption. Design and planning services concentrate among specialized engineering firms serving hyperscale builds exceeding 100 megawatts.
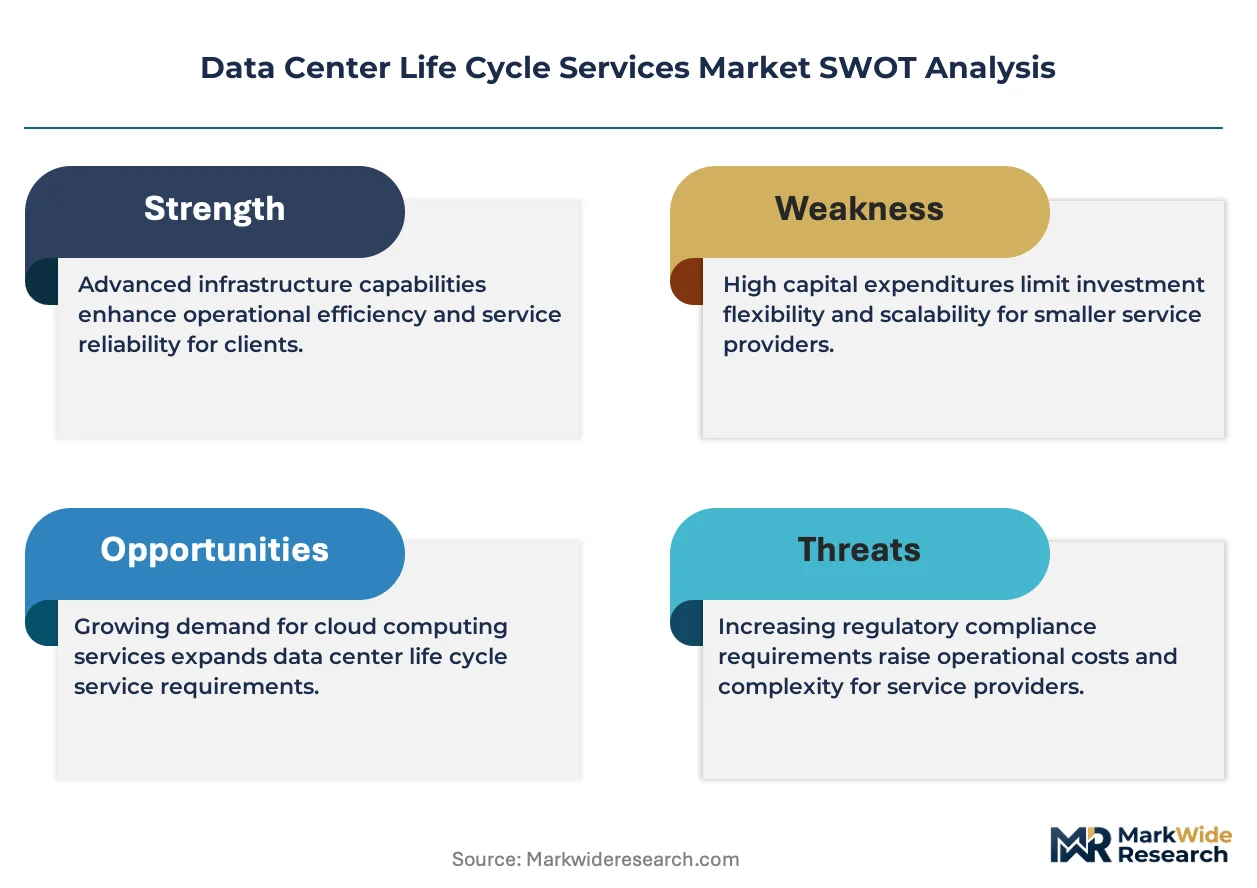
ISO 27001 and SOC 2 Type II frameworks govern information security assurance across multi-tenant facilities, while the EU Energy Efficiency Directive mandates power usage effectiveness reporting for new data center deployments in member states. India's Ministry of Electronics and Information Technology enforces data localization requirements that stimulate domestic facility construction and associated life cycle service demand. Stakeholders must evaluate thermal design power trajectories against regional electricity grid constraints before committing capital to new service delivery footprints.
Market Dynamics
AI training clusters exceeding 100 megawatts are compressing design-to-commissioning cycles from 24 months to 14 months, forcing life cycle service providers to restructure project delivery methodologies around modular prefabrication and parallel workstreams.
Growth Catalysts
- Liquid cooling infrastructure mandates:Thermal design power thresholds above 30kW per rack in AI facilities are accelerating demand for specialized commissioning and maintenance services. Rack density specifications now require continuous coolant monitoring protocols.
- India's data localization framework:The Ministry of Electronics and Information Technology enforces domestic storage requirements for financial and health data, stimulating facility construction and associated life cycle service procurement.
- EU Energy Efficiency Directive:Power usage effectiveness reporting requirements for new deployments in member states are expanding the addressable market for design-phase energy optimization consulting.
Market Restraints
- Copper and electrical steel price volatility:Transformer and busbar material costs fluctuate with commodity markets, compressing margins on fixed-price infrastructure contracts.
- Specialized technician scarcity:Certification requirements for fluorinated gas handling under EU F-Gas Regulation limit the available labor pool for cooling system maintenance.
- Grid interconnection queues:Utility approval timelines exceeding 18 months in high-demand clusters delay project revenue recognition for construction-phase service providers.
Strategic Opportunities
- Decommissioning and ITAD services:First-generation cloud facilities reaching end-of-life create asset recovery and secure destruction revenue streams.
- Southeast Asian expansion corridors:Hyperscale operators are prioritizing Johor, Singapore, and Batam for new footprints, opening localization requirements for regional service partnerships.
- Digital twin convergence:Building information modeling and operational technology data integration enable predictive maintenance contracts with multi-year recurring revenue structures.
Industry Challenges
- Commissioning engineer shortages:Uptime Institute certification pathways produce fewer qualified professionals than facility completion schedules demand.
- Multi-vendor integration complexity:Disaggregated supply chains for power distribution, cooling, and software control layers extend system acceptance testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Life Cycle Services Market |
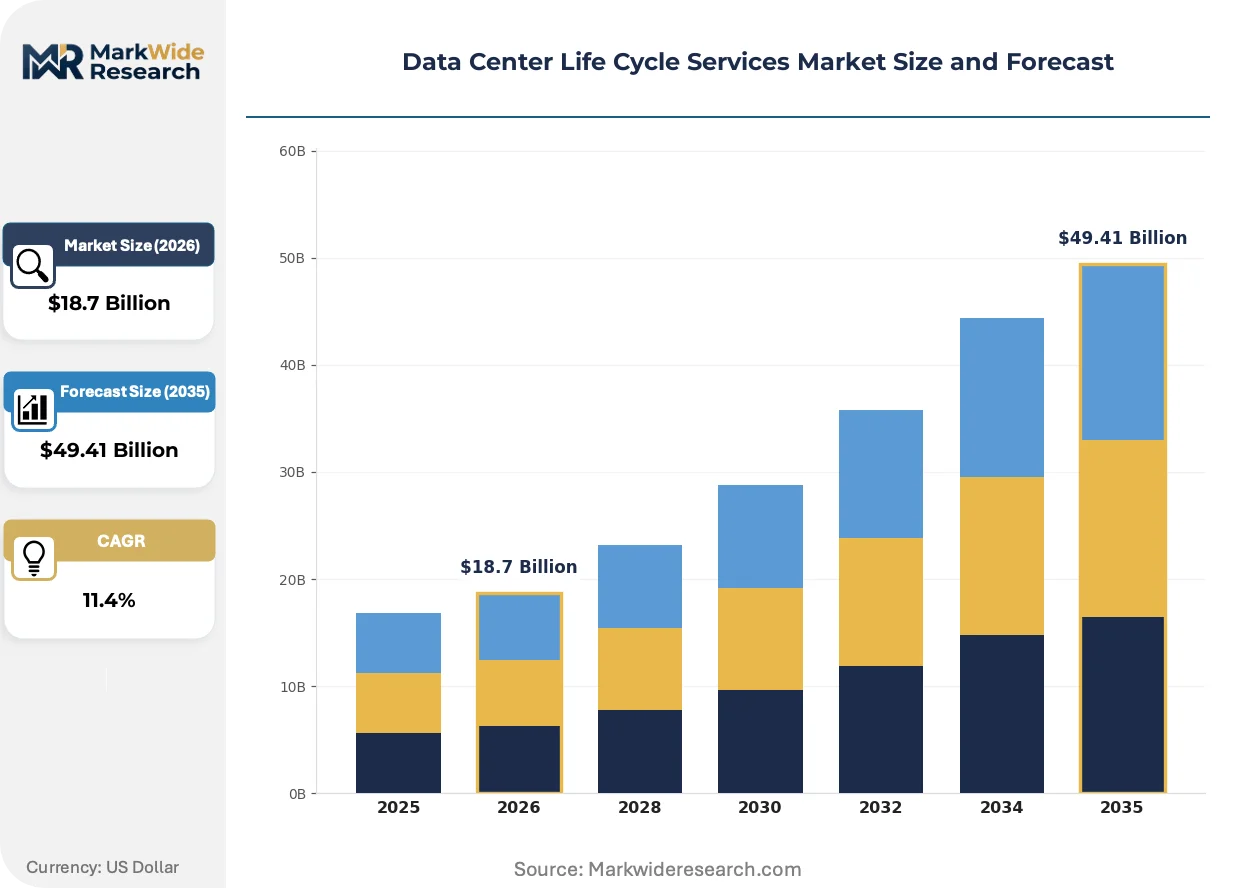
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design & Planning, Implementation, Maintenance, Decommissioning Deployment Model: On-Premises, Colocation, Hybrid, Managed Cloud End User: Enterprise, SMEs, Government, Educational Institutions Technology: Virtualization, Cooling Solutions, Security Solutions, Monitoring Tools |
| Companies Covered | IBM Corporation, Microsoft, Amazon Web Services, Cognizant, Tata Consultancy Services, Hewlett Packard Enterprise, Dell Technologies, Schneider Electric, Vertiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Life Cycle Services Market Emerging Trajectories
Computational intensity thresholds are restructuring how facilities are designed, operated, and retired. Service providers must now orchestrate across thermal, electrical, and software domains simultaneously.
Direct liquid cooling is fragmenting traditional air-cooled infrastructure specifications. Hyperscale operators deploying NVIDIA H100 clusters are specifying coolant distribution units as standard rack infrastructure. This technology is fragmenting the mechanical contractor landscape into specialized thermal-fluid specialists and legacy HVAC generalists.
The EU AI Act establishes risk classification frameworks for high-impact AI systems with corresponding infrastructure audit requirements. Data center operators hosting frontier model training must document environmental impact and energy sourcing. European facility operators are responding by procuring design-phase compliance consulting as a mandatory workstream.
Enterprise buyers are unbundling life cycle service contracts that were previously bundled with colocation agreements. Financial services firms with dedicated cloud requirements now separately procure design advisory, commissioning oversight, and ongoing maintenance. This pattern is most visible in Singapore's Marina Bay and Changi facility clusters where domestic banks operate captive infrastructure.
Data Center Life Cycle Services Market Segmentation
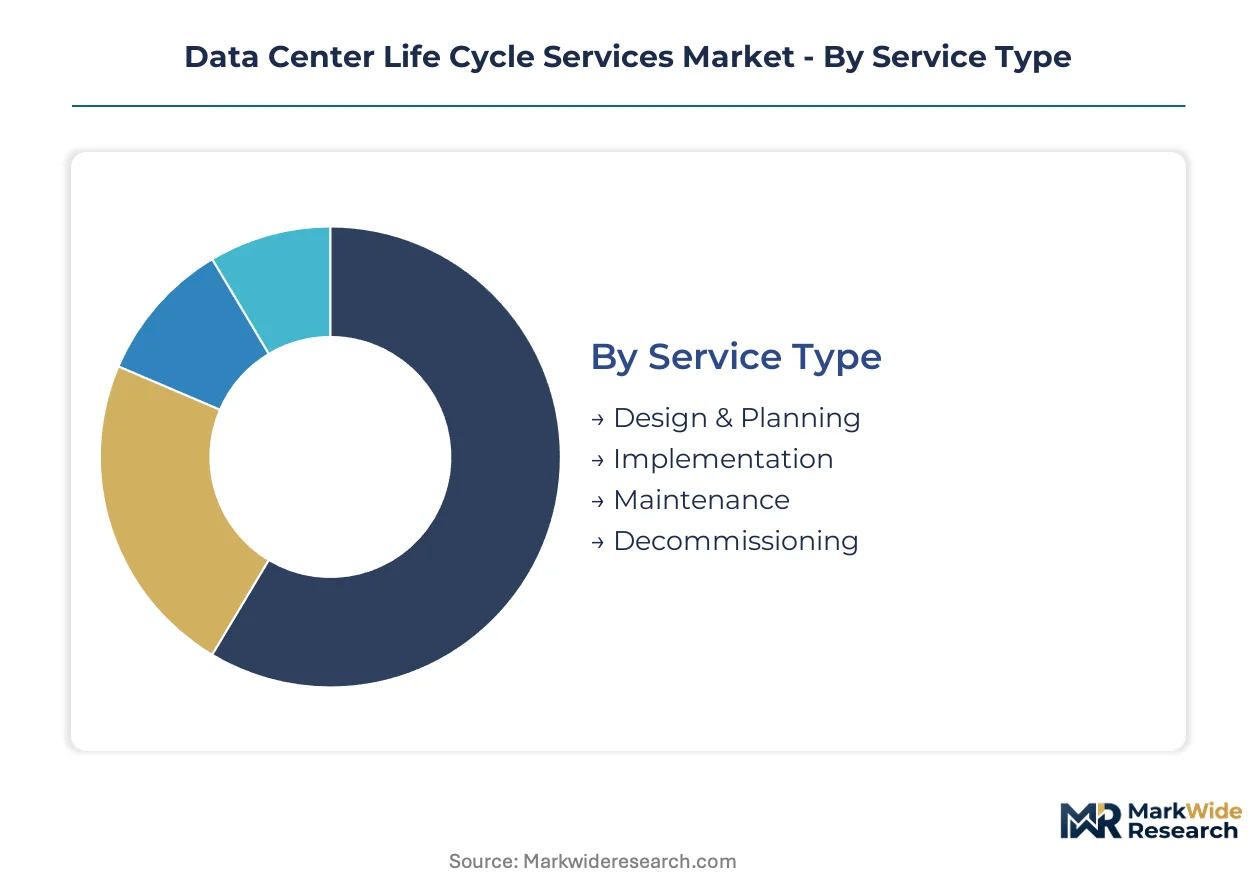
Segmentation in data center life cycle services reveals distinct procurement patterns across service types, deployment models, and technology layers. Understanding these divisions enables providers to align capability investments with where buyer budgets are concentrating.
Service Type:
Implementation services face the strongest substitution pressure as hyperscale operators internalize modular construction expertise and bypass third-party project management.
- Design & Planning:Engineering advisory spanning site selection, power density modeling, and cooling architecture specification. Demand concentrates among hyperscale builds exceeding 100 megawatts in India and Southeast Asia, driven by domestic data localization mandates and compressed commissioning timelines.
- Implementation:Physical construction, equipment installation, and system integration across electrical, mechanical, and software layers. Rack densities exceeding 30kW in AI training facilities are expanding specialized commissioning requirements in Singapore, Johor, and Batam clusters.
- Maintenance:Preventive and corrective services ensuring continuous availability. Thermal management complexity with liquid cooling adoption is expanding recurring revenue opportunities.
- Decommissioning:Asset recovery, secure data destruction, and environmental disposal of end-of-life infrastructure. First-generation cloud facilities reaching retirement age are stimulating ITAD service procurement.
Implementation retains volume leadership; Maintenance holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates enterprise buyers with captive infrastructure from mid-market adopters seeking operational expenditure flexibility.
- On-Premises:Enterprise-owned and operated facilities with full life cycle service procurement. Financial services firms in Singapore's Marina Bay and Changi clusters are unbundling design advisory, commissioning, and maintenance into separate contracts.
- Colocation:Third-party facility leasing with bundled or unbundled operational services. Hybrid cloud strategies are expanding multi-tenant facility construction across Indian metropolitan markets.
- Hybrid:Integrated on-premises and cloud infrastructure with orchestrated life cycle management. Regulatory compliance requirements under the EU AI Act are mandating infrastructure audit documentation for frontier model hosting.
- Managed Cloud:Fully outsourced infrastructure with provider-managed life cycle services. SME adoption is accelerating in Southeast Asian expansion corridors.
Colocation captures the largest addressable base; Hybrid deployment is climbing the fastest.
End User:
Application intensity varies sharply between latency-sensitive financial workloads and batch-processing government systems.
- Enterprise:Large organizations with dedicated infrastructure requirements spanning multiple facility generations. India's Ministry of Electronics and Information Technology data localization rules are stimulating domestic facility construction and associated service procurement.
- SMEs:Mid-sized organizations prioritizing operational flexibility over capital ownership. Managed cloud adoption is reducing barriers to Tier III equivalent reliability.
- Government:Public sector entities with sovereign data requirements and extended procurement cycles. EU Energy Efficiency Directive compliance is mandating power usage effectiveness optimization in new deployments.
- Educational Institutions:Research universities operating high-performance computing clusters with specialized cooling and power density needs.
Enterprise dominates current spending; Government procurement is gaining share fastest.
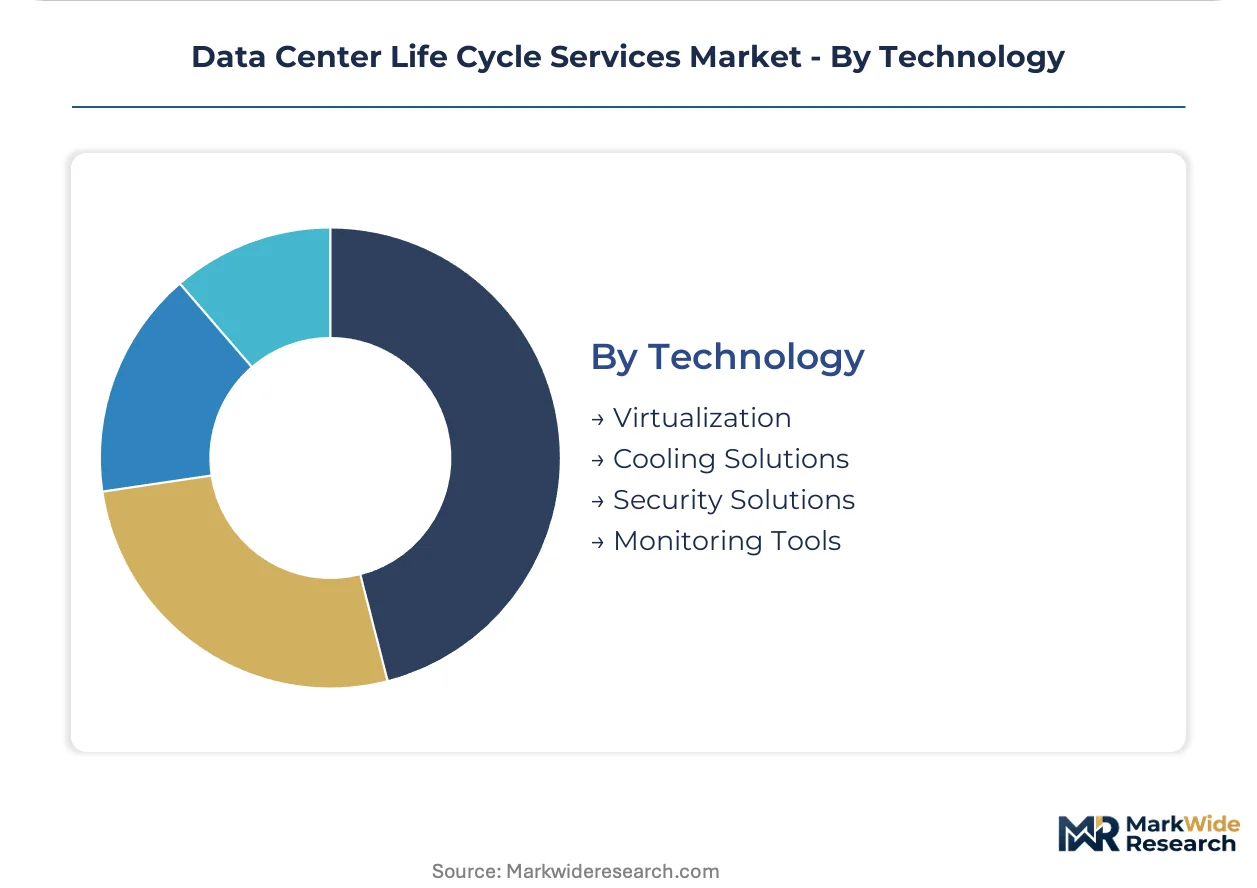
Technology:
Supply concentration in cooling equipment is forcing service providers to develop specialized thermal-fluid competencies distinct from legacy HVAC capabilities.
- Virtualization:Software-defined compute, storage, and network abstraction layers. Multi-vendor integration complexity is extending system acceptance testing timelines.
- Cooling Solutions:Air-cooled, liquid-cooled, and hybrid thermal management systems. Direct liquid cooling for NVIDIA H100 clusters is fragmenting the mechanical contractor landscape.
- Security Solutions:Physical access control, cybersecurity frameworks, and compliance documentation. ISO 27001 and SOC 2 Type II certifications govern multi-tenant facility assurance.
- Monitoring Tools:Operational technology platforms for predictive maintenance and digital twin convergence. Building information modeling integration is enabling multi-year recurring revenue contracts.
Cooling Solutions anchor capital deployment; Monitoring Tools show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Singapore and Johor commands premiums 40% above Indian metropolitan markets for equivalent commissioning services. This asymmetry reflects divergent regulatory stringency and land scarcity rather than capability differentiation. Service providers arbitrage the gap through modular prefabrication shipped from lower-cost manufacturing bases.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth are compressing design-to-commissioning cycles below 18 months for AI training clusters. FERC interconnection queues extending beyond 24 months delay project revenue recognition. Phoenix and Reno clusters concentrate liquid cooling deployment for thermal loads exceeding 30kW per rack.
India
Data localization mandates from the Ministry of Electronics and Information Technology stimulate facility construction across Mumbai, Chennai, and Hyderabad. Domestic banks and healthcare operators drive Tier III certification requirements. Navi Mumbai and Bengaluru suburbs concentrate greenfield builds exceeding 50 megawatts.
Germany
EU Energy Efficiency Directive power usage effectiveness reporting requirements expand design-phase consulting procurement. Frankfurt's DE-CIX proximity sustains financial services demand for low-latency infrastructure. Bavaria and North Rhine-Westphalia host carbon-neutral facility commitments under national dual carbon alignment.
Singapore
Marina Bay and Changi financial district operators unbundle life cycle contracts previously bundled with colocation agreements. Tropical climate constraints mandate specialized thermal-fluid engineering for liquid cooling acceptance. Government moratoriums on new data center power allocations intensify competition for existing facility expansion rights.
Japan
METI carbon neutrality targets for 2050 reshape facility design specifications in Tokyo and Osaka metropolitan areas. Earthquake resilience codes extend commissioning timelines relative to other developed markets. Fukuoka and Hokkaido regions attract hyperscale investment for seismic stability and cooler ambient temperatures.
Data Center Life Cycle Services Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive boundaries across the value chain. Integrated infrastructure manufacturers compete on thermal and electrical system control, while IT services firms compete on labor arbitrage and consulting depth. Three archetypes dominate: diversified technology conglomerates with captive hardware supply, pure-play engineering specialists with Uptime Institute certification density, and regional system integrators with government relationship advantages. Consolidation pressure concentrates in commissioning and maintenance segments where certified technician scarcity creates acquisition targets. Strategic partnerships between cooling equipment manufacturers and software control vendors displace single-source procurement patterns.
Within the diversified technology tier, IBM Corporation and Microsoft exemplify consulting-led positioning across design and decommissioning phases. Tata Consultancy Services anchors cost-optimized delivery models for emerging Asian markets. Schneider Electric occupies a position bridging infrastructure hardware control with life cycle service orchestration.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft |
| Amazon Web Services |
| Cognizant |
| Tata Consultancy Services |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Schneider Electric |
| Vertiv |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates above 85 percent in Singapore's Marina Bay and Changi clusters compress commissioning margins while elevating price floors for liquid-cooled infrastructure acceptance. This scale concentration forces regional service providers to absorb logistics premiums or cede share to modular prefabrication specialists operating from Johor and Batam manufacturing bases.
Pricing Analysis
The customization-premium spread between standard commissioning services and configured-to-order liquid cooling acceptance runs widest in AI training facilities exceeding 30kW per rack. Project-based pricing dominates implementation phases, while maintenance contracts shift toward subscription structures tied to uptime guarantees. Price differentiation rests on Uptime Institute certification density and after-sales thermal-fluid engineering support. Cost compression in standard air-cooled commissioning is intensifying as hyperscale operators internalize modular construction expertise. Enterprise financial services firms in Singapore demonstrate lowest price sensitivity, prioritizing tier certification over procurement cost.
Supply Chain Analysis
Inbound logistics costs through Singapore's port congestion and container availability constraints on the Shanghai-Singapore-Batam trade lane elevate landed costs for transformer and busbar components. Supply concentrates in China for electrical steel and copper busbar fabrication, Germany for precision cooling equipment, and Japan for seismic-rated switchgear. Raw material dependencies span copper cathodes, electrical steel laminations, and fluorinated refrigerants governed by EU F-Gas Regulation restrictions. Single-source vulnerability in specialized coolant distribution units creates procurement risk for liquid cooling deployments. Distribution runs through EPC contractors and direct OEM channels to facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as enterprise buyers unbundle life cycle contracts previously consolidated under colocation agreements, creating specialized niches for design advisory and commissioning oversight independent of facility operation.
For Market Incumbents: Compound certification density advantages by acquiring Uptime Institute-credentialed commissioning engineers in India and Southeast Asia where labor scarcity outpaces facility completion schedules. Deepen backward integration into modular prefabrication to defend margin position against commodity cost volatility in copper and electrical steel. Prioritize digital twin platform investments to lock in multi-year predictive maintenance contracts before software-native competitors establish presence. For New Entrants and Emerging Players: Liquid cooling maintenance capacity gaps in Johor, Batam, and Navi Mumbai clusters offer immediate service-layer entry points where incumbent HVAC generalists lack thermal-fluid competencies. Target decommissioning and ITAD services for first-generation cloud facilities reaching end-of-life in Northern Virginia and Frankfurt, where asset recovery demand exceeds qualified provider supply. Lead with compliance-documentation capabilities under EU AI Act infrastructure audit requirements to differentiate from commodity maintenance offerings. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play engineering specialists with Uptime Institute certification density over diversified conglomerates where data center services compete for capital allocation. Long-term viability hinges on recurring revenue mix and regional exposure to data localization mandates rather than project-dependent implementation volumes. Acquisition targets should demonstrate captive relationships with hyperscale operators expanding in Southeast Asia. Monitor FERC interconnection queue clearance rates as inflection indicator for construction-phase service demand recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Scale-Up | Compresses design-to-commissioning cycles from 24 months to 14 months for AI clusters in Singapore. |
| Liquid Cooling Competency Acquisition | Addresses technician scarcity under EU F-Gas Regulation for thermal loads exceeding 30kW per rack. |
| Digital Twin Platform Integration | Enables predictive maintenance contracts with multi-year recurring revenue in Marina Bay financial district. |
| India Localization Partnership | Captures procurement from domestic banks and healthcare operators under Ministry of Electronics and Information Technology mandates. |
| Decommissioning Service Expansion | Targets first-generation cloud facilities reaching retirement age in Northern Virginia and Frankfurt clusters. |
Methodological Framework
A spread of perspectives from data center facility operators, commissioning engineers, EPC contractors, and hyperscale cloud procurement officers converged on the working assumptions governing market sizing and growth trajectories. Primary fieldwork combined structured interviews with secondary validation against SEC filings from infrastructure manufacturers, Uptime Institute certification databases, and FERC interconnection queue records. Bottom-up facility construction tracking across Mumbai, Chennai, Hyderabad, Singapore, Johor, and Batam clusters was triangulated with top-down hyperscaler capex disclosure analysis.
Segmentation dimensions modeled span service type, deployment model, end user category, and technology layer across the projection horizon. The analytical framework incorporates rack density specifications, thermal design power trajectories, and regional electricity grid constraint assessments. CAGRs were derived from facility completion schedules, localization mandate implementation timelines, and liquid cooling adoption curves. Forecast inputs include hyperscale operator expansion commitments in Southeast Asia and EU Energy Efficiency Directive compliance deadlines.
Forecasts assume regulatory continuity in EU member states, India, and Singapore; material policy shifts in data localization requirements or power allocation moratoriums would require re-modeling. Practitioners should keep alternative scenarios live as FERC interconnection queue dynamics and copper price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
China Data Center Physical Security Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Asia-Pacific Hosting Infrastructure Services Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market