
 Europe Hyperscale Data Center Market | 2026-2036
Europe Hyperscale Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hyperscale Data Center Market Analytics
Data center engineering talent is collapsing across Northern Europe, forcing operators to raise compensation and extend project timelines. Microsoft leverages its existing cloud engineering pipelines in Ireland to sustain buildout velocity despite labor scarcity. Vantage Data Centers competes by anchoring its European headquarters in Frankfurt, where local technical universities feed specialized workforce pools. Equinix differentiates through its interconnection fabric expertise, occupying a niche that generic colocation providers cannot replicate.
Europe hyperscale data centers are mission-critical facilities exceeding 15 megawatts of IT capacity, designed with N+1 or 2N redundancy in power and cooling architecture to support continuous operations for cloud and AI workloads. Their primary commercial purpose is to deliver scalable compute, storage, and network services to enterprises offloading infrastructure ownership. Modular data centers lead capital deployment because prefabricated power and cooling modules compress construction schedules by 30-40% versus traditional stick-built approaches. Edge data centers represent the fastest-expanding structural category as latency-sensitive applications in manufacturing and autonomous systems require distributed presence beyond core hubs.
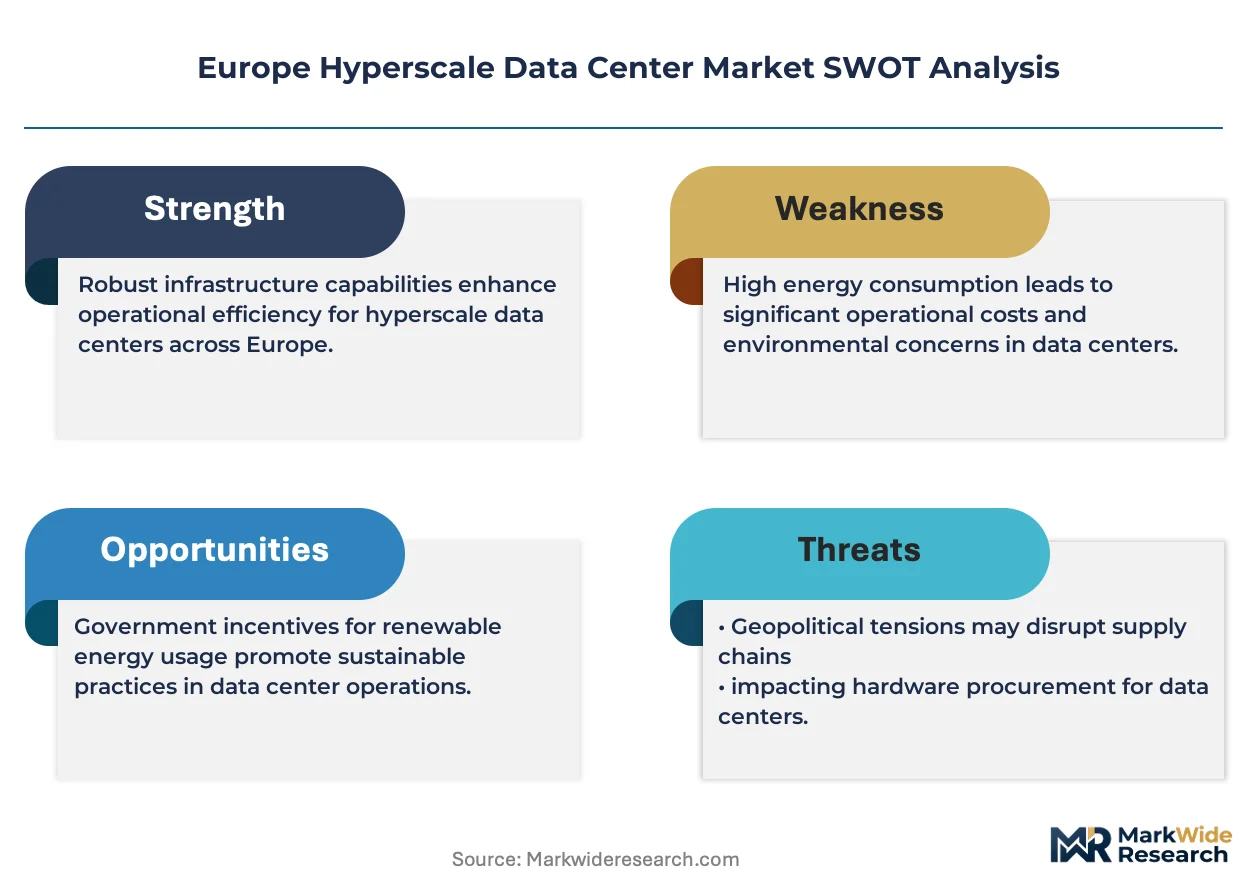
The EU Green Deal and F-Gas Regulation constrain refrigerant choices and mandate progressive carbon disclosure, pushing operators toward liquid cooling and heat recovery architectures. ECHA's chemical restrictions and national building codes in Germany, France, and the Netherlands add compliance layers that favor established developers with regulatory affairs capacity. Stakeholders must monitor how the EU AI Act's transparency requirements reshape data residency and processing location decisions for model training workloads.
Market Dynamics
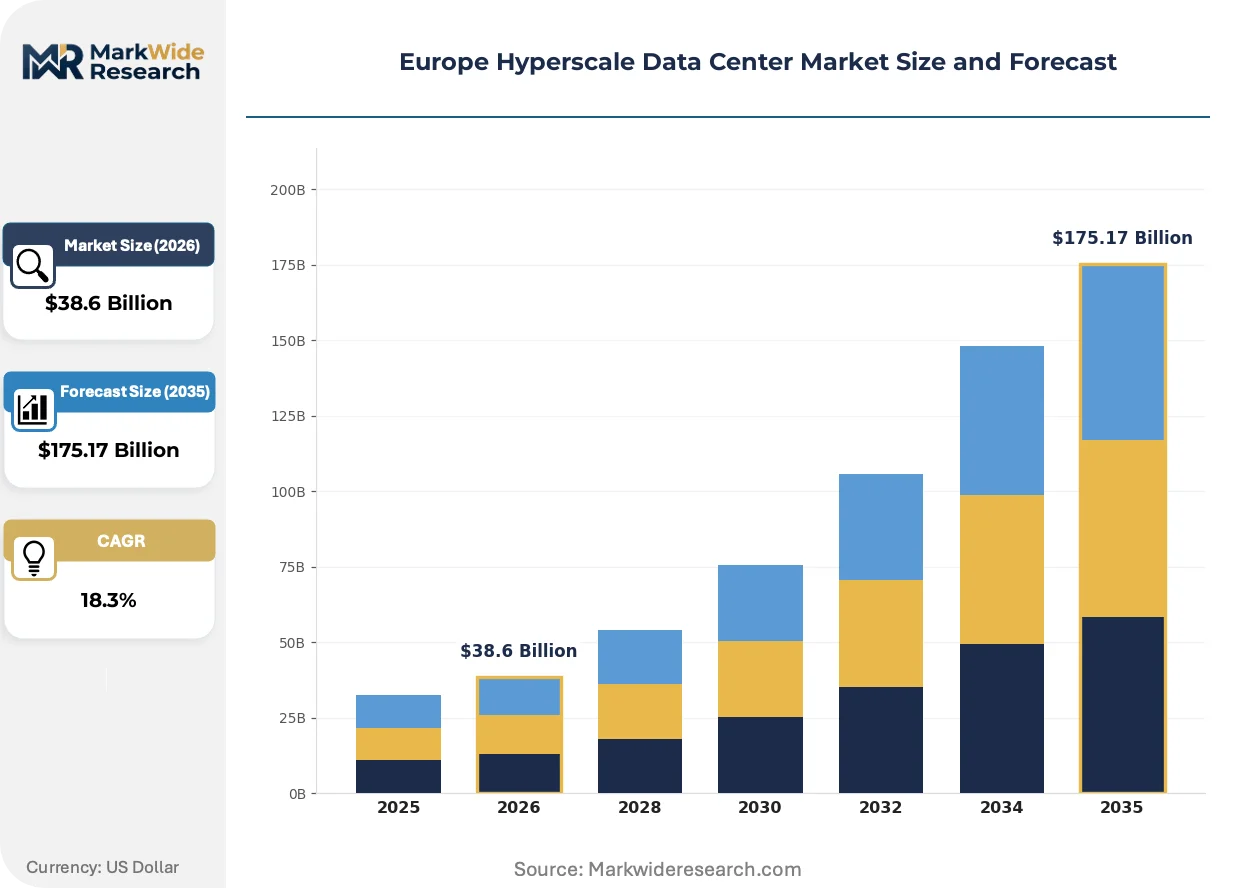
The EU Green Deal's carbon-neutrality mandates are forcing facility operators to reengineer power and cooling architectures, compressing project timelines and raising capital intensity for every new buildout across the continent.
Growth Catalysts
- EU AI Act compliance requirements:Transparency and data residency rules for model training workloads are pushing enterprises toward dedicated hyperscale facilities with verifiable sovereignty controls.
- Cloud adoption by BFSI institutions:Financial services firms are offloading core infrastructure, generating sustained demand for fault-tolerant capacity with sub-millisecond latency to trading venues.
- Frankfurt's fiber density:The city's interconnection richness and available land parcels attract successive international operator investments, concentrating European buildout activity.
Market Restraints
- ECHA refrigerant restrictions:F-Gas Regulation constraints eliminate conventional cooling chemistries, forcing costly liquid cooling retrofits and specialized engineering.
- Engineering talent scarcity:Northern Europe's collapsing data center construction workforce extends commissioning schedules and inflates labor costs for specialized electrical and mechanical roles.
- Grid interconnection queues:Utility approval timelines for 100+ megawatt connections stretch 24-36 months in Germany and the Netherlands, throttling deployment velocity.
Strategic Opportunities
- Spain and Portugal expansion:Iberian solar resource abundance and submarine cable landing points offer low-carbon power arbitrage for latency-tolerant workloads.
- Waste heat recovery monetization:District heating network integration in Nordic cities transforms cooling loads into revenue streams, improving project economics.
- Modular prefabrication convergence:Factory-built power and cooling modules compress construction schedules by 30-40% versus stick-built approaches, enabling faster market entry.
Industry Challenges
- Electrical commissioning expertise gap:Qualified medium-voltage switchgear technicians and commissioning engineers command premium wages, constraining parallel project execution.
- Legacy facility interoperability:Brownfield expansions must integrate with existing building management systems and power distribution architectures, complicating automation deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hyperscale Data Center Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $175.17 Billion |
| CAGR (2026 – 2036) | 18.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Containerized Solutions, Traditional Data Centers, Edge Data Centers Deployment Model: On-Premises, Cloud, Hybrid, Colocation End User: Telecommunications, BFSI, IT Services, E-Commerce Energy Source: Renewable Energy, Grid Power, Backup Generators, Solar |
| Companies Covered | Microsoft, Vantage Data Centers, Equinix, Evroc, NTT DATA, Digital Realty, Google Cloud, Meta Platforms, AWS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hyperscale Data Center Market Evolving Landscape
Liquid cooling architectures, regulatory disclosure mandates, and procurement model evolution are restructuring how hyperscale capacity gets financed, engineered, and contracted across European markets.
Immersion and direct-to-chip liquid cooling is fragmenting the thermal management landscape as power densities exceed 50 kilowatts per rack. AI training clusters and high-performance computing buyers are specifying liquid-cooled designs for nearly all new deployments. This technology is fragmenting vendor ecosystems, splitting market share between incumbent HVAC specialists and emerging fluid systems providers.
The EU Green Deal's progressive carbon disclosure requirements are mandating granular emissions reporting from facility operators. Industrial consequence includes mandatory third-party verification of Scope 2 electricity claims and embodied carbon in construction materials. German and French operators are responding fastest, embedding lifecycle assessment tools into procurement workflows ahead of 2027 compliance deadlines.
Power purchase agreement structures are displacing traditional utility tariffs as the dominant energy contracting mechanism. Large cloud buyers are negotiating 10-15 year renewable energy contracts directly with offshore wind and solar developers, bypassing incumbent utilities. This shift is most visible in Denmark and the Netherlands, where offshore wind lease rounds have attracted hyperscale offtake commitments.
Europe Hyperscale Data Center Market Segmentation
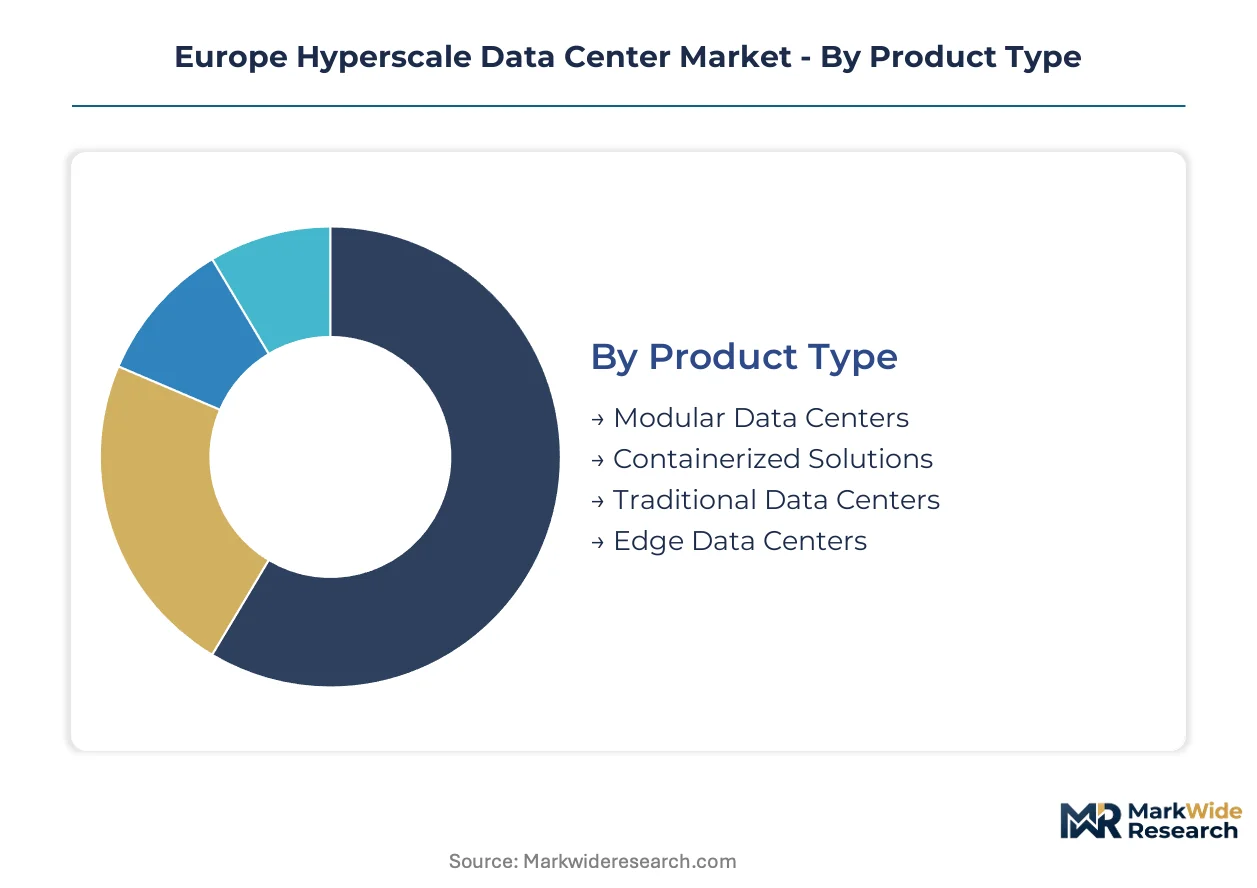
Segmentation reveals how EU Green Deal compliance costs and F-Gas refrigerant restrictions fragment procurement strategies across facility architectures and energy sourcing models. Buyers now segment investments by regulatory exposure rather than pure capacity economics.
Product Type:
ECHA chemical restrictions and national building codes in Germany, France, and the Netherlands create divergent compliance burdens across structural approaches.
- Modular Data Centers:Factory-built power and cooling modules compress construction schedules by 30-40% versus stick-built alternatives. Demand concentrates in Frankfurt's successive buildouts where land availability and fiber density attract international operators needing rapid commissioning despite labor scarcity.
- Edge Data Centers:Distributed sub-10 megawatt facilities positioned for latency-sensitive manufacturing and autonomous systems workloads. Germany's automotive corridor and Nordic industrial zones drive deployment as EU AI Act data residency rules push processing closer to source data.
- Containerized Solutions:Standardized shipping-container form factors enable rapid redeployment across Iberian solar sites.
- Traditional Data Centers:Stick-built concrete and steel structures face extended grid interconnection queues in the Netherlands.
Modular Data Centers handles the majority of throughput; Edge Data Centers is gaining share fastest as latency requirements harden.
Deployment Model:
Cost tier differentiation separates sovereign-controlled infrastructure from utility-priced alternatives.
- Colocation:Third-party operated facilities where enterprises lease rack space and cross-connect to cloud on-ramps. Frankfurt's interconnection richness sustains premium pricing for financial services firms requiring sub-millisecond latency to trading venues.
- Cloud:Hyperscale-operated facilities with standardized APIs and global backbone integration. Ireland's existing cloud engineering pipelines sustain buildout velocity despite Northern Europe's collapsing data center workforce.
- Hybrid:Split workloads across owned and leased capacity with unified orchestration layers.
- On-Premises:Enterprise-owned facilities retained for compliance-sensitive workloads under EU AI Act sovereignty controls.
Colocation commands the revenue base; Cloud is expanding most quickly as BFSI institutions complete core infrastructure offloading.
End User:
Application-specific reliability requirements drive divergent redundancy specifications across buyer categories.
- BFSI:Banking and insurance institutions mandating 2N electrical redundancy and fault-tolerant cooling for core transaction processing. Frankfurt's fiber density and land availability attract successive international operator investments concentrated in this segment.
- IT Services:Managed service providers and systems integrators aggregating enterprise workloads onto shared hyperscale infrastructure. Demand intensifies across Germany where local technical universities feed specialized workforce pools.
- Telecommunications:Carrier-neutral facilities supporting 5G core network functions and edge computing.
- E-Commerce:Retail platforms with flash-traffic patterns requiring elastic burst capacity.
BFSI anchors capacity commitments; IT Services is climbing the fastest as multi-tenant outsourcing accelerates.
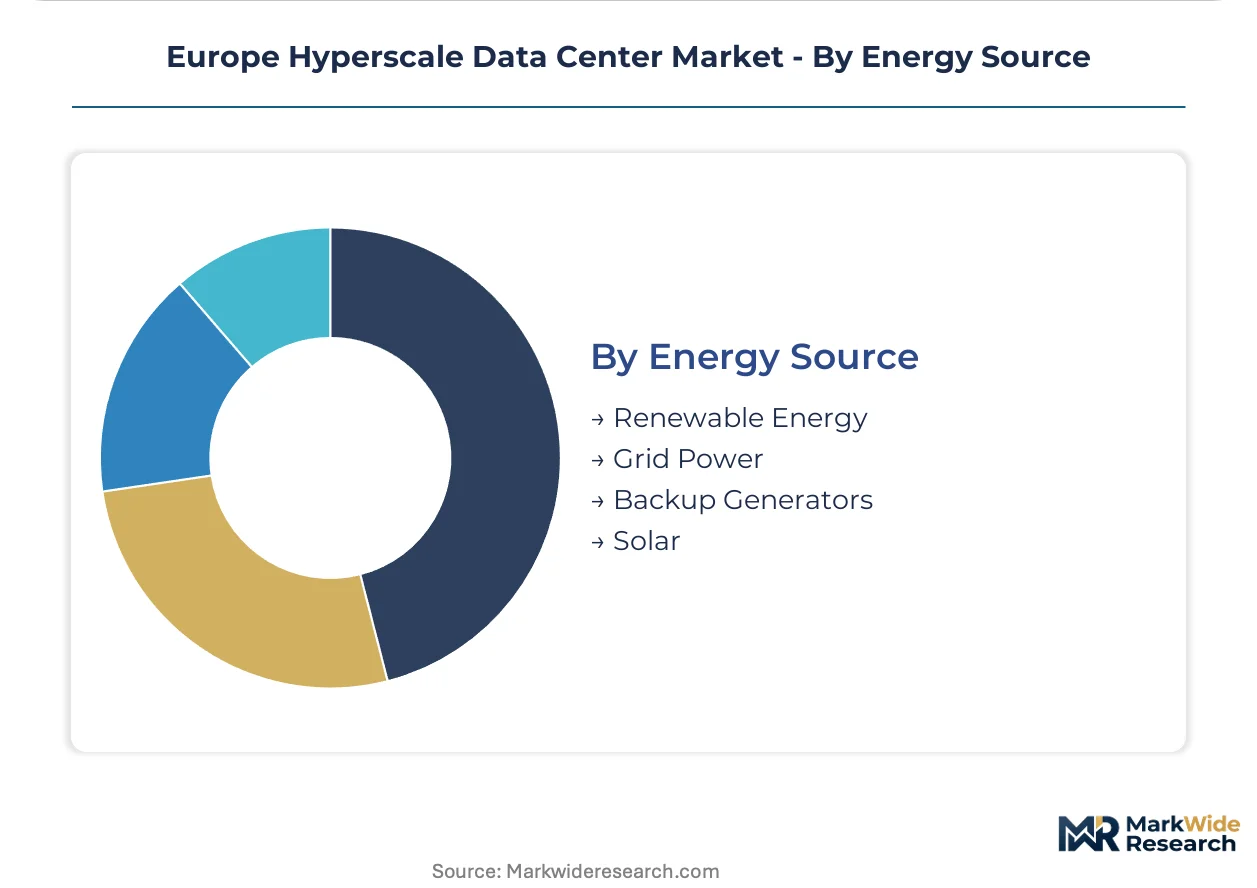
Energy Source:
Margin structures diverge sharply between long-term contracted renewables and volatile grid-exposed alternatives.
- Renewable Energy:Power purchase agreements with offshore wind and solar developers locking 10-15 year pricing. Denmark and the Netherlands attract hyperscale offtake commitments through offshore wind lease rounds.
- Solar:On-site or adjacent photovoltaic arrays with battery buffering for diurnal load shaping. Iberian resource abundance offers low-carbon power arbitrage for latency-tolerant workloads in Spain and Portugal.
- Grid Power:Conventional utility supply exposed to wholesale price volatility and carbon intensity disclosure requirements.
- Backup Generators:Diesel or HVO-fueled emergency systems constrained by EU Green Deal progressive carbon disclosure mandates.
Renewable Energy underpins the bulk of new capacity; Solar is seeing the steepest expansion trajectory as PPA structures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes hyperscale capacity differently than Iberia, prioritizing financial services latency over solar arbitrage. The Netherlands structures procurement around renewable power purchase agreements rather than grid exposure. France segments demand between sovereign AI workloads and commercial cloud offloading.
Germany
Frankfurt's fiber density and land availability attract successive international operator buildouts for BFSI latency requirements. The EU Green Deal's carbon-neutrality mandates force power and cooling reengineering across Hesse and North Rhine-Westphalia. Berlin-Brandenburg hosts sovereign cloud clusters serving federal AI workloads under strict data residency controls.
Netherlands
Amsterdam's interconnection hub sustains premium colocation demand from trading firms requiring sub-millisecond latency. Grid interconnection queues for 100+ megawatt connections stretch 24-36 months, throttling deployment velocity. ECHA F-Gas Regulation constraints eliminate conventional cooling chemistries, forcing liquid cooling retrofits in Randstad facilities.
France
Paris anchors financial services cloud migration with 2N redundancy specifications for core transaction processing. The EU AI Act's transparency requirements reshape data residency decisions for model training workloads in Île-de-France. Auvergne-Rhône-Alpes attracts heat recovery deployments integrating with district heating networks.
Ireland
Dublin's existing cloud engineering pipelines sustain Microsoft buildout velocity despite Northern Europe's collapsing data center workforce. The country's corporate tax framework concentrates hyperscale operator regional headquarters. Local technical universities feed specialized workforce pools for electrical and mechanical commissioning roles.
Spain and Portugal
Iberian solar resource abundance offers low-carbon power arbitrage for latency-tolerant workloads. Submarine cable landing points in Lisbon and Barcelona attract international operators seeking renewable energy contract structures. Madrid and Catalonia host containerized rapid-deployment facilities serving burst capacity requirements.
Europe Hyperscale Data Center Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud operators controlling capacity expansion timelines while colocation providers compete on interconnection density. The market structures around three archetypes: vertically integrated cloud builders with captive energy procurement, interconnection-centric colocation platforms, and modular infrastructure specialists compressing construction schedules. Competitive moves concentrate on renewable power purchase agreement negotiations and workforce pipeline development through technical university partnerships.
Within the integrated cloud tier, Microsoft and AWS exemplify operators leveraging existing engineering pipelines to sustain buildout velocity. Vantage Data Centers occupies a position among modular specialists anchoring European headquarters in Frankfurt to access local technical workforce pools. Equinix represents the interconnection-centric archetype, differentiating through fabric expertise that generic colocation providers cannot replicate.
| Leading Market Players |
|---|
| Microsoft |
| Vantage Data Centers |
| Equinix |
| Evroc |
| NTT DATA |
| Digital Realty |
| Google Cloud |
| Meta Platforms |
| AWS |
| Others |
Value Network & Pricing Analysis
Megawatt-scale capacity utilization at 85-90% in Frankfurt and Amsterdam creates natural scale economies that compress unit costs and establish price floors for regional competitors. This concentration of operational scale simultaneously shapes supply chain sourcing patterns, as tier-one electrical and mechanical contractors prioritize relationships with high-volume operators capable of absorbing prefabricated module output at scale.
Pricing Analysis
Long-term power purchase agreements dominate hyperscale contracting, with 10-15 year renewable energy offtake structures locking in electricity costs below volatile grid-exposed alternatives. Price differentiation separates sovereign-controlled facilities with EU AI Act compliance premiums from standard commercial cloud capacity. Pricing pressure stems from Iberian solar arbitrage opportunities pulling latency-tolerant workloads away from premium Frankfurt and Amsterdam hubs. Financial services firms demonstrate lowest price sensitivity due to sub-millisecond latency requirements, while manufacturing and backup workloads show highest elasticity.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for prefabricated power modules sourced from Asian manufacturing clusters. Supply concentration centers on Germany, the Netherlands, and China for medium-voltage switchgear, precision cooling components, and lithium-ion battery systems. Raw material dependencies include copper busbar, fluorinated fluids for liquid cooling, and rare earth elements for power conditioning equipment. Single-source vulnerability runs through Taiwanese semiconductor fabrication for data center control systems. Distribution runs through direct OEM relationships with Schneider Electric, Vertiv, and Huawei, bypassing traditional distribution channels for megawatt-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale data center economics are shifting toward platform-based interconnection ecosystems where cross-connect density and cloud on-ramp availability determine tenant stickiness. This interoperability inflection favors operators with existing fiber-rich positions and complicates greenfield entry for asset-light competitors.
For Market Incumbents: Compound interconnection density advantages in Frankfurt and Amsterdam by securing additional cross-connect capacity before grid interconnection queues lengthen further. Defend against modular specialists compressing construction schedules by embedding prefabrication partnerships into procurement workflows. Prioritize vertical integration into renewable energy development to lock in PPA pricing ahead of offshore wind lease competition intensifying in the North Sea. For New Entrants and Emerging Players: Differentiate on heat recovery integration and district heating network partnerships in Nordic cities where waste heat monetization improves project economics. Target Spain and Portugal expansion where solar resource abundance and submarine cable landing points offer low-carbon power arbitrage for latency-tolerant workloads. Pursue sovereign cloud certifications under EU AI Act data residency requirements as the primary go-to-market wedge against established commercial operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among interconnection-centric colocation platforms with financial services tenant concentrations and long-term lease structures. Five-to-ten year viability hinges on regulatory affairs capacity navigating ECHA chemical restrictions and EU Green Deal disclosure mandates. Target acquisition archetypes include modular infrastructure specialists with factory-built power and cooling module capabilities. Watch for inflection in grid interconnection approval timelines as the signal for deployment velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Negotiation | Direct 10-15 year renewable contracts with Danish and Dutch offshore wind developers bypass utility margins. |
| Modular Prefabrication Partnership | Factory-built power modules compress Frankfurt construction schedules by 30-40% versus stick-built alternatives. |
| Heat Recovery Infrastructure Deployment | District heating integration in Nordic cities transforms cooling loads into revenue streams improving project returns. |
| Liquid Cooling Retrofit Program | ECHA F-Gas Regulation compliance requires specialized engineering for refrigerant-constrained facilities in Randstad. |
| Technical University Pipeline Development | Frankfurt and Dublin partnerships address Northern Europe's collapsing data center engineering workforce scarcity. |
Research Methodology
A spread of perspectives from hyperscale facility operators, electrical commissioning contractors, utility interconnection planners, and cloud procurement officers converged on the working assumptions for capacity expansion timelines. Primary fieldwork combined structured interviews with secondary validation against SEC capex disclosures, EIA electricity generation data, EU Green Deal regulatory filings, and offshore wind lease round documentation. Bottom-up project pipeline analysis triangulated against top-down utility interconnection queue data across Germany, the Netherlands, and Ireland.
Segmentation dimensions modeled include facility architecture type, deployment model, end-use industry, and energy sourcing structure across the projection horizon. CAGRs were derived from capacity utilization trajectories, power density evolution, and renewable energy penetration curves. Industry-specific forecast inputs incorporated ECHA chemical restriction implementation timelines and EU AI Act compliance cost assumptions for sovereign cloud deployments.
The analysis sits within stated boundaries; outcomes outside sustained grid interconnection approval, stable offshore wind development costs, or unaltered EU Green Deal carbon-neutrality mandates would require recalibration. Forecasts reflect documented assumptions about labor scarcity persistence and liquid cooling technology maturation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Bengaluru Data Center Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
France Data Center Market