
 Data Center UPS Market | 2026-2036
Data Center UPS Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center UPS Market Analysis
Capital-intensity divergence between transformer-based legacy architectures and silicon carbide-enabled platforms is rotating competitive advantage toward modular topology specialists. Schneider Electric leverages its integrated power distribution software stack to sustain design-win rates in hyperscale bids. Eaton Corporation anchors North American enterprise retrofit cycles through service-contract bundling. Huawei Technologies competes on vertically integrated semiconductor sourcing, though geopolitical licensing constraints limit certain market access.
A data center uninterruptible power supply is an electrical apparatus providing emergency power through battery arrays, flywheel kinetic storage, or hybrid electrochemical systems when input mains power fails, with double-conversion topologies achieving output voltage regulation within two percent deviation. The equipment's primary purpose is eliminating downtime in server environments where power anomalies corrupt transactional data or trigger cascading cooling failures. Double conversion technology leads installed base value due to zero transfer time requirements in Tier III and Tier IV facilities, while modular installation types capture fastest deployment velocity as operators phase capacity additions to match server rack densities. Rack-mounted units below 20 kVA occupy the volume-driven replacement segment where price competition compresses margin pools.
The U.S. EPA Energy Star program and DOE efficiency standards shape minimum power-factor thresholds for qualifying equipment, while the EU Ecodesign Directive through delegated regulation 2019/1782 mandates standby-loss ceilings that filter out transformer-based legacy designs. China's GB/T 7260 national standard and MIIT certification requirements for data center infrastructure create parallel compliance tracks for domestic and export-oriented manufacturers. Stakeholders must monitor how battery chemistry transitions from valve-regulated lead-acid to lithium-ion architectures reshape fire-safety codes and insurance underwriting criteria across jurisdictions.
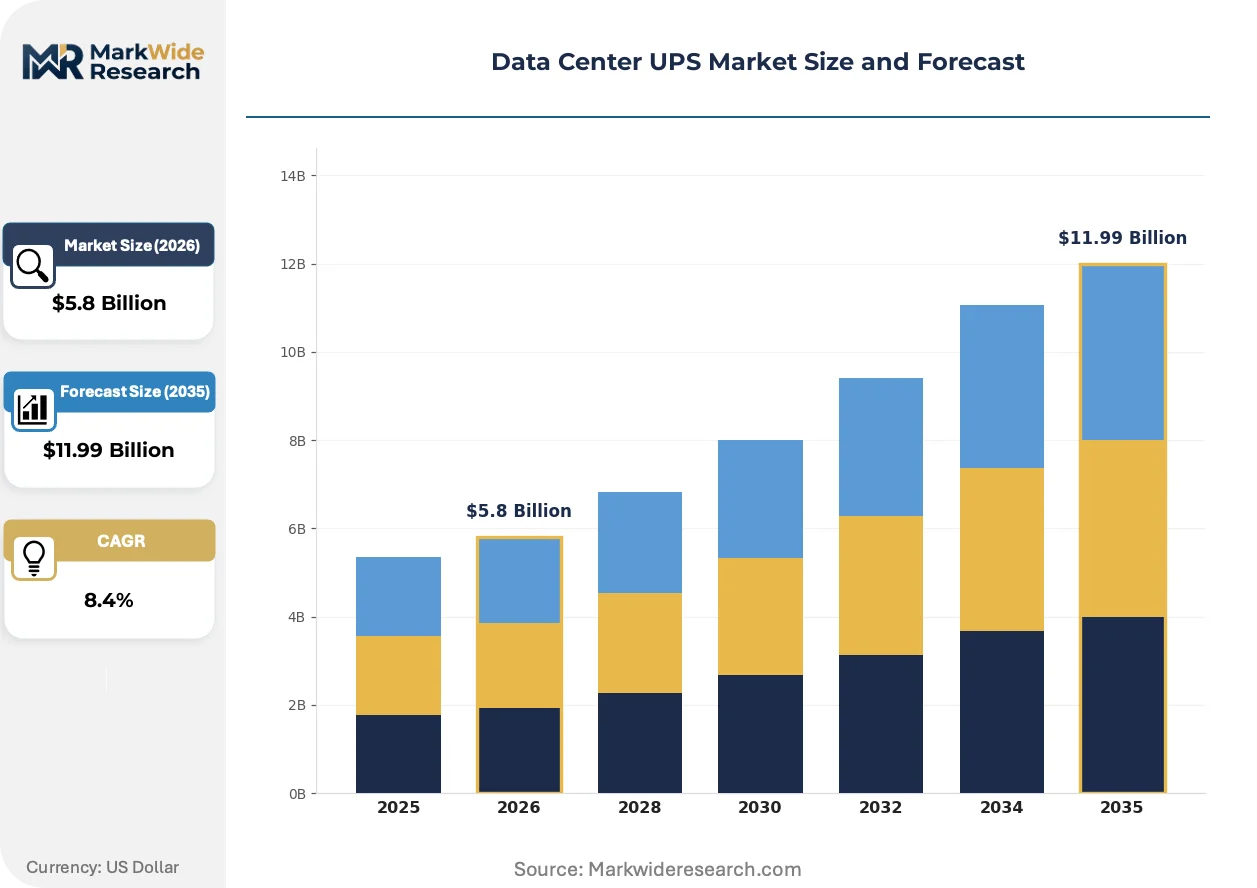
Market Dynamics
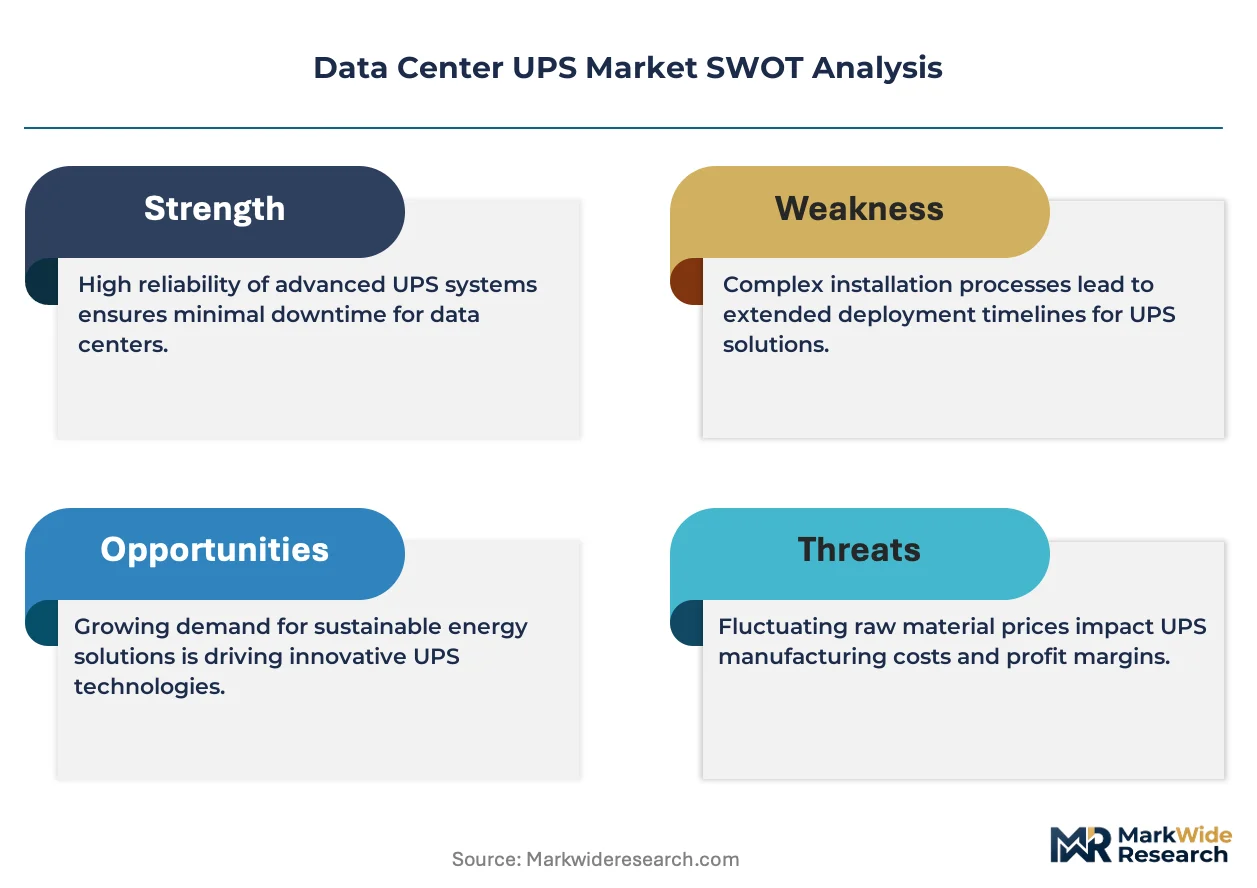
Silicon carbide power semiconductors are compressing converter losses below three percent, forcing incumbent manufacturers to abandon transformer-based architectures or surrender hyperscale design wins to modular topology specialists. This materials transition redistributes value capture from legacy electrical component suppliers toward semiconductor-integrated system architects.
Growth Catalysts
- Hyperscale facility construction:Cloud operators in Northern Virginia, Frankfurt, and Singapore are deploying redundant power architectures requiring double-conversion UPS density above 500 kW per rack row.
- EU Ecodesign Directive:Delegated regulation 2019/1782 mandates standby-loss ceilings that filter transformer-based legacy designs from European procurement lists.
- Lithium-ion battery chemistry:Energy density improvements enable 40% footprint reduction versus valve-regulated lead-acid, accelerating retrofit cycles in space-constrained urban data centers.
Market Restraints
- Semiconductor supply concentration:Silicon carbide substrate fabrication concentrates among Japanese and U.S. wafer suppliers, creating input bottlenecks for European and Chinese UPS manufacturers.
- Fire-safety code lag:NFPA 855 and local jurisdictional amendments impose thermal runaway containment costs that offset lithium-ion capital savings in certain North American municipalities.
- Skilled commissioning technician scarcity:Modular parallel system startup requires factory-certified field engineers, with qualified personnel concentrated among OEM direct service organizations.
Strategic Opportunities
- Edge computing facility buildout:Distributed micro data centers below 1 MW capacity lack dedicated power engineering staff, creating attach opportunities for managed power-as-a-service contracts.
- India PLI scheme:Production-linked incentives for electronic components manufacturing reduce landed cost for domestic UPS assembly serving South Asian hyperscale demand.
- Hybrid electrochemical storage:Flywheel-lithium-ion combinations address cycling durability gaps in high-temperature Middle Eastern installations where battery-only economics fail.
Industry Challenges
- Legacy SCADA integration complexity:Proprietary communication protocols in fifteen-year-old power distribution software block seamless telemetry extraction for predictive maintenance algorithms.
- Certification timeline compression:UL 1973 second-edition testing for lithium-ion energy storage systems extends product launch schedules by eight to fourteen months versus lead-acid equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center UPS Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: 1 kVA, 5 kVA, 10 kVA, 20 kVA Installation Type: Rack-mounted, Tower, Modular, Portable End User: Telecom, Colocation, Enterprise, Cloud Provider Technology: Double Conversion, Line Interactive, Offline, Flywheel |
| Companies Covered | ABB, Delta Electronics, Schneider Electric, Legrand, Mitsubishi Electric, Vertiv Holdings, Huawei Technologies, General Electric, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center UPS Market Emerging Trajectories
Power conversion architectures are bifurcating between silicon carbide-enabled modular platforms and legacy transformer-based systems, with regulatory efficiency mandates accelerating the transition timeline. This technological divergence is reshaping competitive positioning across installation types and end-use verticals.
Silicon carbide MOSFETs enable switching frequencies above 50 kHz, reducing magnetic component mass by sixty percent versus insulated-gate bipolar transistor designs. Hyperscale operators in Singapore and Frankfurt are specifying SiC-based units for all new Tier IV builds, accepting fifteen-to-twenty percent capital premiums for footprint recovery. Transformer-based legacy architectures are supplanting modular silicon carbide platforms only in price-sensitive retrofit segments where existing electrical rooms cannot accommodate DC bus reconfiguration.
The U.S. Department of Energy's efficiency mandates for critical infrastructure equipment are tightening power-factor correction thresholds above 0.99 at partial load. Equipment failing to demonstrate compliance through third-party certification loses eligibility for federal data center construction tax incentives. Double-conversion topologies above 500 kVA face the steepest redesign burden, as silicon-controlled rectifier legacy designs cannot meet harmonic distortion limits without complete power stage replacement.
Cloud procurement teams are unbundling fifteen-year service contracts from initial capital purchase, forcing OEMs to compete on levelized cost of power protection rather than equipment margin alone. This purchasing pattern shift concentrates volume among manufacturers with captive service networks in Northern Virginia, Frankfurt, and Singapore. Financially constrained colocation operators in secondary U.S. markets retain bundled procurement models, creating a two-tier supplier engagement structure.
Data Center UPS Market Segmentation
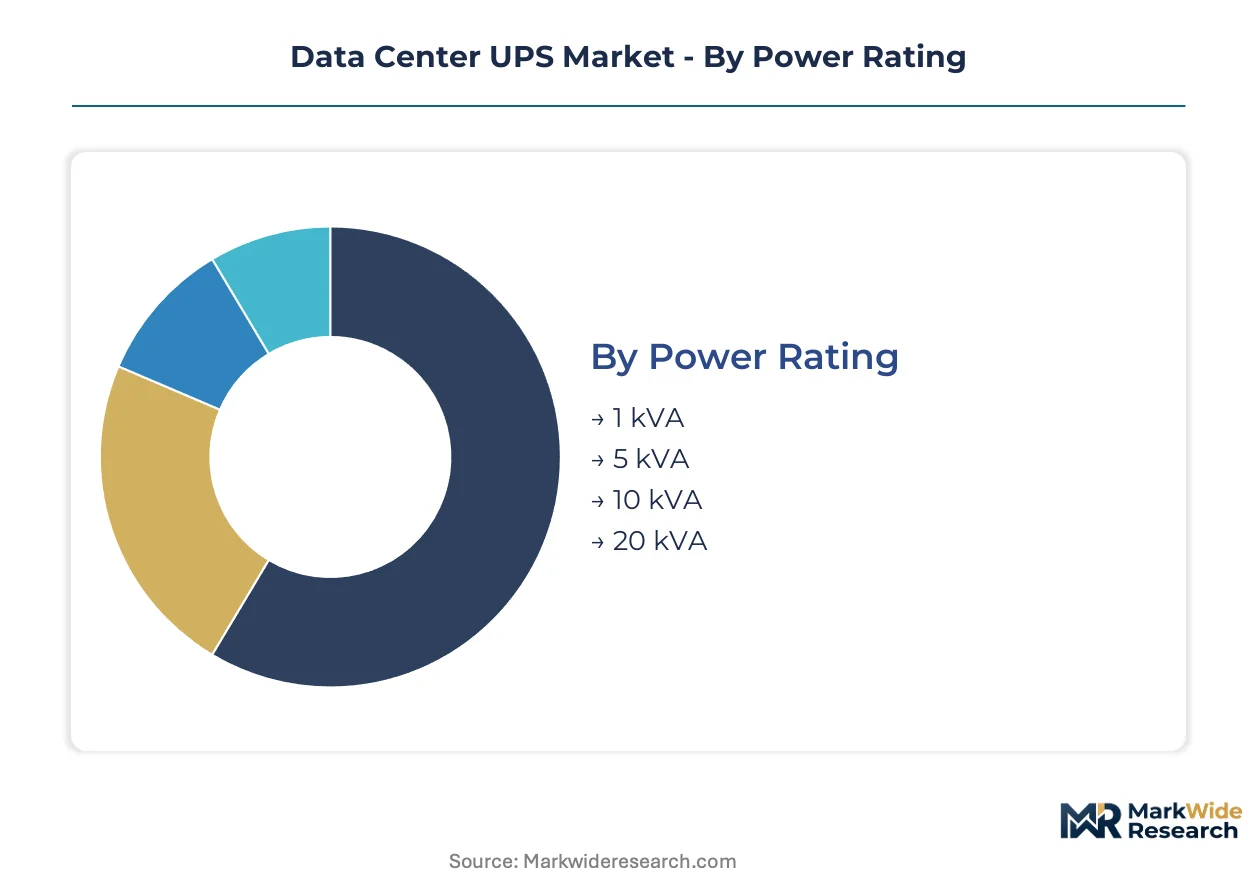
UPS segmentation reveals divergent substitution pressures across power architectures. Silicon carbide-enabled modular systems displace transformer-based alternatives in hyperscale bids, while legacy installations persist in price-sensitive retrofit cycles where electrical room constraints block DC bus reconfiguration.
Power Rating:
Substitution pressure intensifies at the high-kVA threshold where lithium-ion energy density enables footprint compression against valve-regulated lead-acid equivalents.
- 1 kVA:Compact units serve edge computing nodes and network closets where space constraints override efficiency optimization. Demand concentrates in distributed micro data centers across Singapore and Frankfurt lacking dedicated power engineering staff.
- 5 kVA:Mid-range systems anchor small enterprise server rooms. Procurement in Northern Virginia tilts toward rack-mounted configurations to match phased server rack density additions.
- 10 kVA:Standardized platforms for departmental data centers face margin compression from modular parallel alternatives that reduce stranded capacity risk.
- 20 kVA:Upper threshold for single-unit installations before modular architectures achieve superior levelized cost of power protection through hot-swappable increments.
1 kVA retains volume leadership; 20 kVA holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates premium modular architectures from economy tower formats, with rack-mounted units occupying the contested mid-market where hyperscale procurement teams unbundle service contracts.
- Rack-mounted:Units below 20 kVA integrate directly into server cabinet rows, eliminating separate electrical room requirements. Cloud providers in Northern Virginia specify these for rapid deployment velocity matching server rack densities.
- Modular:Parallel-capable frames enable capacity scaling from 50 kW to 2 MW through hot-swappable power modules. Silicon carbide MOSFET switching above 50 kHz reduces magnetic component mass sixty percent versus insulated-gate bipolar transistor designs.
- Tower:Freestanding enclosures persist in enterprise retrofit cycles where existing electrical infrastructure cannot accommodate DC bus reconfiguration.
- Portable:Mobile units address temporary power protection for disaster recovery operations and construction-phase data center commissioning.
Modular captures premium pricing; rack-mounted dominates unit volume.
End User:
Application-specific requirements drive technology selection, with Tier III and Tier IV facility classifications mandating zero transfer time architectures that filter out line-interactive alternatives.
- Cloud Provider:Hyperscale operators deploy redundant power architectures above 500 kW per rack row, accepting fifteen-to-twenty percent capital premiums for silicon carbide-enabled footprint recovery in Singapore and Frankfurt Tier IV builds.
- Colocation:Multi-tenant facilities balance capital constraints against SLA penalties, driving attach rates for managed power-as-a-service contracts in secondary U.S. markets.
- Enterprise:Corporate data centers face retrofit pressure from EU Ecodesign Directive standby-loss ceilings that disqualify transformer-based legacy designs from European procurement lists.
- Telecom:Central office and 5G edge installations prioritize battery runtime over conversion efficiency, sustaining demand for line-interactive topologies in price-sensitive network infrastructure.
Cloud Provider leads capital deployment; Enterprise shows the fastest retrofit conversion rate.
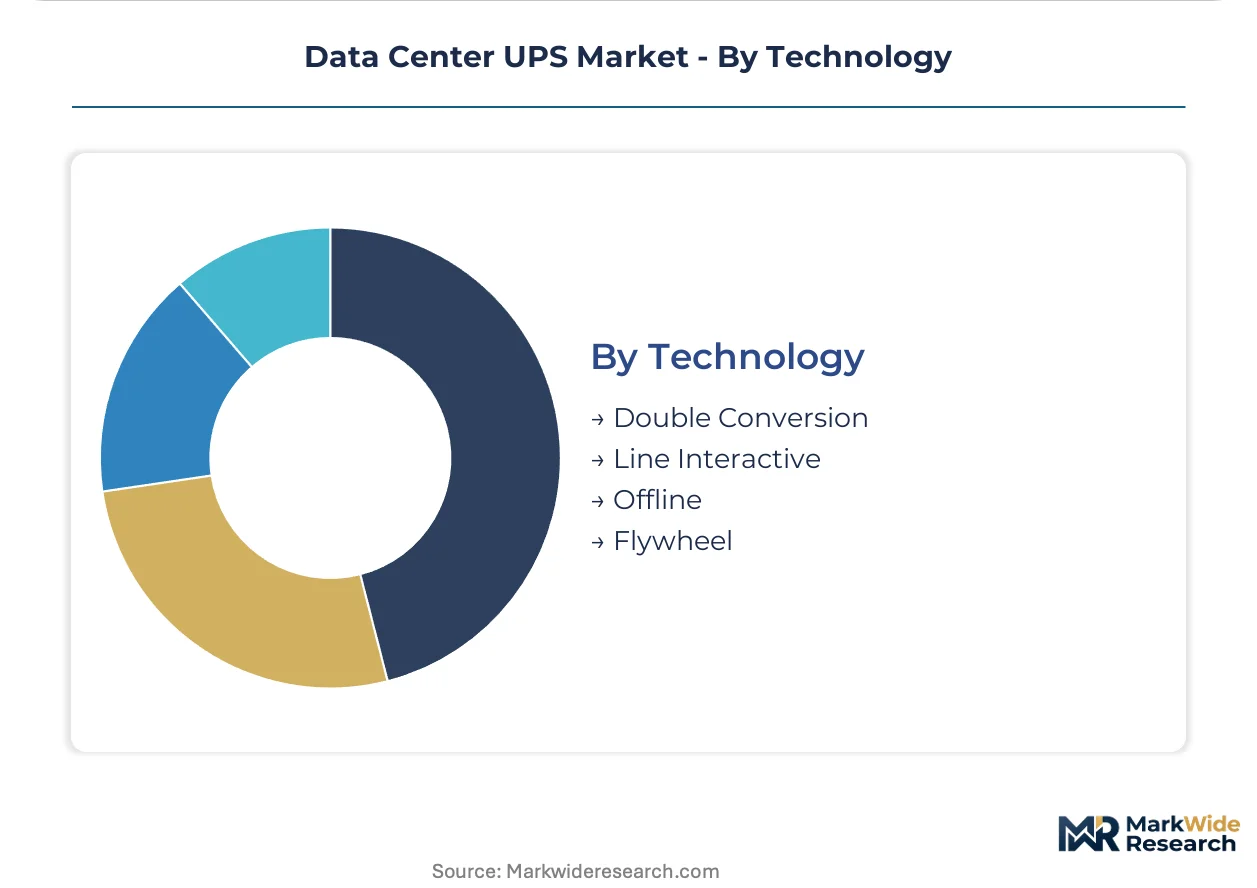
Technology:
Maturity gradients separate established double-conversion architectures from emerging flywheel hybrids, with efficiency mandates accelerating transitions toward silicon carbide-enabled platforms.
- Double Conversion:AC-to-DC-to-AC topology achieves output voltage regulation within two percent deviation through continuous inverter operation. Tier III and Tier IV facilities mandate this architecture for zero transfer time requirements.
- Flywheel:Kinetic energy storage eliminates battery replacement cycles and thermal runaway risks. Hybrid flywheel-lithium-ion combinations address cycling durability gaps in high-temperature Middle Eastern installations.
- Line Interactive:Buck-boost voltage regulation with battery backup serves price-sensitive applications where transfer time tolerance exceeds ten milliseconds.
- Offline:Standby topology engages inverter only during mains failure, limiting deployment to non-critical loads with relaxed power quality requirements.
Double Conversion maintains installed base dominance; Flywheel gains share fastest in high-temperature climates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Cloud operators in Northern Virginia prioritize redundant power density above 500 kW per rack row, while European facilities emphasize standby-loss compliance under delegated regulation 2019/1782. Asian markets split between hyperscale efficiency mandates and space-constrained urban retrofits.
United States
Hyperscale construction in Northern Virginia and Dallas-Fort Worth drives double-conversion UPS demand above 500 kVA. The U.S. Department of Energy's efficiency mandates tighten power-factor correction thresholds above 0.99 at partial load. Tax incentive eligibility hinges on third-party certification, filtering non-compliant equipment from federal data center construction bids.
Germany
Frankfurt's Tier IV facility cluster accepts fifteen-to-twenty percent capital premiums for silicon carbide-enabled footprint recovery. The EU Ecodesign Directive through delegated regulation 2019/1782 mandates standby-loss ceilings that disqualify transformer-based legacy designs. German colocation operators balance SLA penalties against capital constraints, driving attach rates for managed power-as-a-service contracts.
Singapore
Land scarcity forces 40% footprint reduction targets through lithium-ion battery chemistry versus valve-regulated lead-acid equivalents. Singapore's national standards for data center infrastructure create parallel compliance tracks for domestic and export-oriented manufacturers. The city-state's hyperscale operators specify SiC-based units for all new Tier IV builds, prioritizing magnetic component mass reduction.
China
GB/T 7260 national standards and MIIT certification requirements reshape procurement for domestic manufacturers. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate hyperscale demand, though geopolitical licensing constraints limit certain market access for foreign suppliers. Local OEMs compete on vertically integrated semiconductor sourcing for modular topology platforms.
India
The PLI scheme for electronic components manufacturing reduces landed cost for domestic UPS assembly serving South Asian hyperscale demand. Mumbai and Bangalore data center corridors face skilled commissioning technician scarcity, with qualified personnel concentrated among OEM direct service organizations. Edge computing facility buildout below 1 MW capacity creates attach opportunities for managed power-as-a-service contracts.
Data Center UPS Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Data Center UPS Market. The upper tier commands hyperscale design wins through captive service networks and silicon carbide-enabled modular platforms. Mid-tier specialists compete on price-sensitive retrofit cycles and regional certification agility. Dominant competitive moves include unbundling fifteen-year service contracts from capital purchase and backward integration into semiconductor sourcing.
Within the integrated systems tier, Schneider Electric and Eaton Corporation exemplify divergent geographic anchoring strategies. Schneider leverages integrated power distribution software stacks to sustain design-win rates in European and Asian hyperscale bids. Eaton anchors North American enterprise retrofit cycles through service-contract bundling in secondary U.S. markets. Huawei Technologies occupies a position shaped by vertically integrated semiconductor sourcing advantages, though geopolitical licensing constraints limit certain market access. Vertiv Holdings and Delta Electronics represent the specialist tier, with naming conventions suggesting U.S. and Taiwan-based origins respectively.
| Leading Market Players |
|---|
| ABB |
| Delta Electronics |
| Schneider Electric |
| Legrand |
| Mitsubishi Electric |
| Vertiv Holdings |
| Huawei Technologies |
| General Electric |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day silicon carbide wafer lead times concentrate pricing power with Japanese and U.S. substrate suppliers, forcing European and Chinese UPS manufacturers to absorb input cost volatility or surrender hyperscale design wins to integrated system architects with captive semiconductor sourcing.
Pricing Analysis
Long-term service contracts unbundled from capital purchase dominate hyperscale procurement, with cloud operators in Northern Virginia and Frankfurt evaluating suppliers on levelized cost of power protection rather than equipment margin alone. Three-tier pricing structure across premium silicon carbide modular platforms, standard rack-mounted configurations, and economy tower retrofits reflects certification grade and after-sales bundling differentiation. Cost compression in the tower segment intensifies as price-sensitive colocation operators in secondary U.S. markets retain bundled procurement models. Telecom and enterprise retrofit buyers exhibit highest price sensitivity; Tier IV hyperscale operators accept capital premiums for footprint recovery.
Supply Chain Analysis
Strategic stockpiling of silicon carbide substrates and lithium-ion battery cells characterizes tier-one OEM procurement, mitigating single-source vulnerability from concentrated Japanese and U.S. wafer fabrication. Raw material dependencies center on silicon carbide substrates, lithium iron phosphate cathodes, and copper busbar components. Distribution runs through OEM direct service organizations concentrated in Northern Virginia, Frankfurt, and Singapore, with qualified commissioning technicians scarce outside captive networks. Tariff exposure on Chinese battery cells and semiconductor components threatens margin stability for non-integrated assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-certified commissioning engineer scarcity constrains modular parallel system deployment velocity, creating asymmetric advantage for OEMs with captive field service networks versus third-party assemblers dependent on scarce qualified personnel.
For Market Incumbents: Secure hyperscale design-win retention by deepening backward integration into silicon carbide semiconductor sourcing and expanding captive service network density in Northern Virginia, Frankfurt, and Singapore. Anchor enterprise retrofit cycles through fifteen-year service contract bundling to defend against modular topology specialists displacing transformer-based legacy architectures under EU Ecodesign Directive compliance pressure. For New Entrants and Emerging Players: Differentiate on managed power-as-a-service contracts targeting edge computing facilities below 1 MW capacity lacking dedicated power engineering staff. Penetrate India's PLI scheme-subsidized domestic assembly corridor serving South Asian hyperscale demand, where skilled technician scarcity creates attach opportunities for remote monitoring and predictive maintenance platforms. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor-integrated system architect play because silicon carbide power stage redesign cycles concentrate value capture with OEMs controlling upstream substrate supply. Target acquisition profiles emphasize modular topology specialists with UL 1973 second-edition lithium-ion certification progress and established hyperscale reference installations. Watch silicon carbide substrate capacity expansion announcements as inflection indicator for input cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Semiconductor Sourcing | Captive substrate supply insulates margin pressure from Japanese and U.S. wafer supplier concentration. |
| Managed Power-as-a-Service Contract Expansion | Remote monitoring platforms address commissioning technician scarcity in edge computing deployments. |
| UL 1973 Second-Edition Certification Investment | Lithium-ion energy storage system approval accelerates product launch schedules versus lead-acid equivalents. |
| Captive Service Network Density Buildout | Factory-certified field engineer concentration secures hyperscale design-win rates in Northern Virginia and Frankfurt. |
| Hybrid Electrochemical Storage Development | Flywheel-lithium-ion combinations penetrate high-temperature Middle Eastern installations where battery-only economics fail. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA Energy Star certification databases, DOE efficiency standard filings, EU Ecodesign Directive delegated regulations, and hyperscaler capital expenditure disclosures. Primary interviews encompassed data center engineering directors, OEM product management executives, colocation procurement leads, and lithium-ion battery system integrators. Secondary validation drew from UL certification registries, MIIT infrastructure filings, and customs trade data for power semiconductor imports. Bottom-up unit shipment analysis triangulated against top-down facility construction pipeline estimates.
Segmentation dimensions modeled span power rating tiers, installation type architectures, end-user verticals, and technology topology categories across the analysis window. CAGRs derived from facility construction pipeline tracking, server rack density evolution curves, and battery chemistry substitution elasticity. Industry-specific forecast inputs incorporated silicon carbide MOSFET adoption curves and EU Ecodesign Directive compliance phase-in schedules.
Material uncertainties — silicon carbide substrate supply disruptions, NFPA 855 thermal runaway code amendments, and geopolitical licensing constraint expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding lithium-ion cost parity achievement and modular topology acceptance velocity. Revision becomes warranted when silicon carbide wafer lead time compression or battery chemistry fire-safety code harmonization crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
Data Center Blocks Market