
 Artificial Intelligence in Trading Market | 2026-2036
Artificial Intelligence in Trading Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Trading Market Analysis
North America is reconfiguring the competitive map for AI trading infrastructure through cloud capacity expansions in Virginia and Texas. NVIDIA dominates GPU supply for training financial models, while Palantir leverages government-adjacent data architectures to serve institutional clients. Microsoft anchors enterprise distribution through Azure's financial services cloud, and Alphabet Inc. competes on natural language processing for sentiment-driven strategies.
Artificial intelligence in trading encompasses machine learning systems that process market data, news flows, and alternative datasets to generate predictive signals or execute orders with minimal human intervention. These platforms typically operate on sub-millisecond latency thresholds and rely on neural network architectures trained on historical price action and fundamental indicators. Algorithmic trading solutions capture the largest share of current deployment spending, while predictive analytics is expanding fastest among hedge funds seeking non-traditional data edges. Cloud-based deployment is displacing on-premises installations as latency differentials narrow and regulatory scrutiny of vendor resilience intensifies.
The SEC enforces transparency requirements for AI-driven investment advice under evolving fiduciary standards, while the EU AI Act imposes risk-classification obligations on automated decision systems deployed in European capital markets. FINRA's sweep examinations of member firms' model governance practices are reshaping vendor selection criteria toward explainable architectures. Stakeholders must weigh compliance investment against model performance gains as supervisory frameworks harden on both sides of the Atlantic.
Market Dynamics
Latency arbitrage is compressing as cloud infrastructure narrows the gap between co-located and distributed execution, forcing vendors to compete on model sophistication rather than raw speed.
Growth Catalysts
- EU AI Act risk-classification mandates:European capital markets face mandatory algorithmic transparency requirements, creating demand for explainable AI architectures that audit decision trails.
- Alternative data ingestion:Satellite imagery, credit card aggregates, and social sentiment streams are expanding signal diversity beyond traditional price and volume metrics.
- Hedge fund alpha compression:Crowded traditional strategies are pushing systematic managers toward machine learning to extract non-linear patterns from unstructured datasets.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in training hardware creates single-source vulnerability for model development pipelines, with lead times extending during demand surges.
- Data licensing fragmentation:Proprietary alternative datasets carry escalating subscription costs and restrictive usage terms that erode strategy margins.
- Model decay velocity:Alpha-generating signals exhibit shortening half-lives as competitive adoption accelerates, demanding continuous retraining investment.
Strategic Opportunities
- India's SEBI-regulated market infrastructure:The country's exchange modernization and retail participation surge create whitespace for retail-facing robo-advisory deployment.
- Reinforcement learning convergence with NLP:Large language models processing central bank communications are hybridizing with execution algorithms to anticipate policy-induced volatility.
- Cloud-native platform distribution:Financial services clouds are emerging as primary channels for vendor distribution, reducing client-side infrastructure overhead.
Industry Challenges
- Quantitative researcher scarcity:The intersection of financial domain expertise and advanced machine learning engineering remains thinly staffed across buy-side institutions.
- FINRA model governance examinations:Regulatory scrutiny of documentation standards and backtesting protocols is extending vendor onboarding timelines.
- Legacy order management integration:Established trading infrastructures require substantial middleware development to accommodate neural network outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Trading Market |
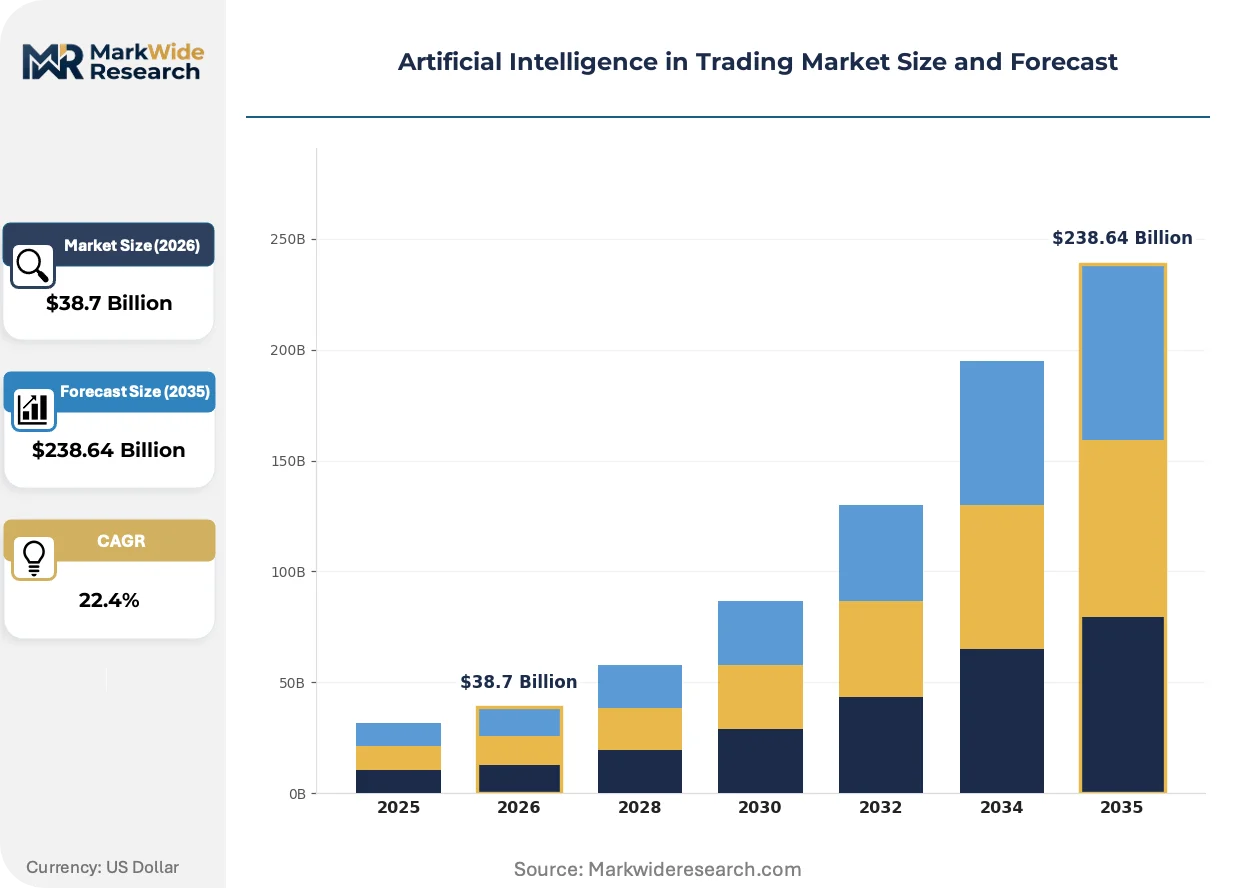
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $238.64 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Algorithmic Trading, Predictive Analytics, Risk Management, Portfolio Optimization End User: Investment Firms, Hedge Funds, Retail Traders, Institutional Investors Technology: Machine Learning, Natural Language Processing, Neural Networks, Deep Learning Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | MLQ.ai, Kavout, Precision Alpha, Trade Ideas, Numerai, Palantir, NVIDIA, Alphabet Inc., Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Trading Market Emerging Trajectories
Execution infrastructure is pivoting from speed-centric hardware toward intelligence-centric software stacks, with model architecture becoming the primary competitive differentiator.
Transformer-based natural language processing is hybridizing with time-series forecasting to parse earnings calls, regulatory filings, and news flows into tradable signals. Multi-manager platforms are deploying these architectures to synthesize sentiment shifts across thousands of concurrent sources. The convergence is compressing the window between information release and price adjustment, redistributing alpha toward fastest-inference systems.
The EU AI Act's risk-tier framework is mandating human oversight interfaces for high-frequency autonomous decisions in European venues. Asset managers are restructuring algorithmic workflows to embed circuit-breakers and audit trails that satisfy supervisory review. Continental hedge funds are absorbing compliance engineering costs that Anglo-American competitors currently avoid.
Buy-side procurement is consolidating vendor relationships around integrated data-model-execution bundles rather than point solutions. Chief investment officers are demanding unified platforms that span ingestion through settlement, displacing fragmented best-of-breed stacks. This preference shift is most pronounced among North American asset managers managing over ten billion dollars in systematic strategies.
Artificial Intelligence in Trading Market Segmentation
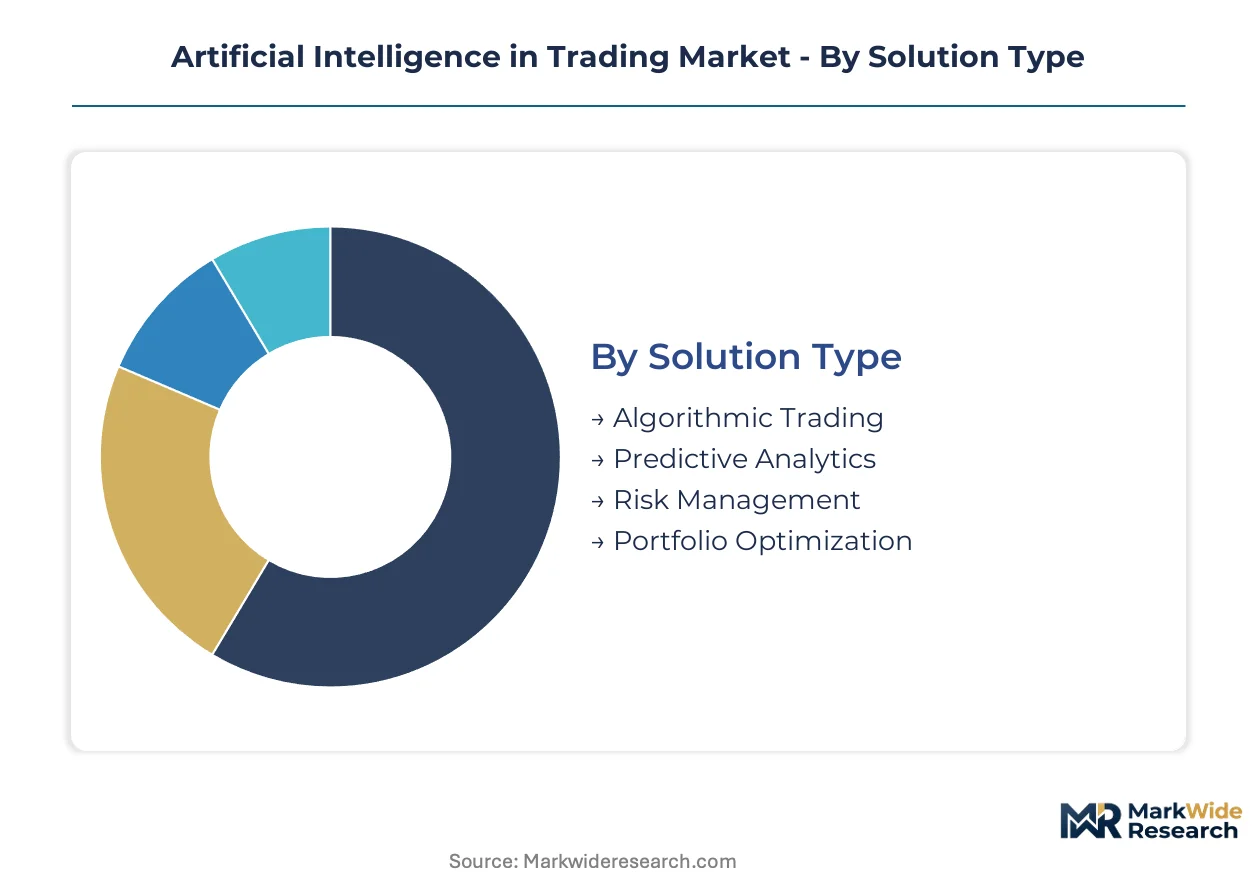
Segmentation in AI trading reveals distinct procurement cycles and capability requirements across solution architectures and user types. Investment firms prioritize explainability for regulatory defense, while hedge funds chase signal decay velocity. Understanding these divergent selection criteria clarifies vendor positioning and R&D allocation priorities.
Solution Type:
Cycle times vary dramatically: execution systems refresh quarterly while risk infrastructure spans multi-year depreciation schedules.
- Algorithmic Trading:These systems execute orders across fragmented venues using latency-optimized decision trees and reinforcement learning agents. Demand concentrates among Chicago and New York prop shops where microsecond advantages still justify hardware spend. Regulatory scrutiny from FINRA and the SEC around market manipulation detection is extending vendor due diligence timelines.
- Predictive Analytics:Platforms synthesize alternative data streams—satellite imagery, credit card aggregates, earnings call sentiment—into directional signals. Hedge funds in Connecticut and London deploy these tools to extract non-linear patterns from unstructured datasets as traditional factor exposures decay.
- Risk Management:Real-time portfolio stress testing and counterparty exposure monitoring using Monte Carlo simulations and copula models. Banks in Frankfurt and Singapore prioritize these systems for regulatory capital optimization under Basel frameworks.
- Portfolio Optimization:Mean-variance and Black-Litterman implementations enhanced with Bayesian machine learning for robust parameter estimation. Family offices in Switzerland and Boston adopt these for tax-aware rebalancing across multi-asset mandates.
Algorithmic Trading anchors the volume base while Predictive Analytics gains share at the steepest rate.
End User:
Customer sophistication tiers separate self-service API consumers from fully outsourced managed solutions.
- Investment Firms:Asset managers with systematic mandates require model explainability for fiduciary documentation and client reporting. Firms in Boston and San Francisco dominate procurement, prioritizing platforms with embedded audit trails for SEC examination readiness.
- Hedge Funds:Systematic and quantitative managers deploy proprietary architectures on co-located infrastructure. Funds in Greenwich and London represent the most demanding segment for raw signal alpha and sub-millisecond execution latency.
- Retail Traders:Mobile-first platforms with pre-built strategy templates and social copying features. India's SEBI-regulated market and Brazil's B3 exchange are seeing surge adoption among dematerialized account holders.
- Institutional Investors:Pension funds and sovereign wealth funds emphasize governance overlays and long-horizon risk-adjusted returns. Canada's CPP Investments and Australia's Future Fund exemplify procurement focused on vendor operational resilience.
Institutional Investors anchor the volume base while Retail Traders expand most quickly in emerging market jurisdictions.
Technology:
Computational intensity and data requirements create sharp capability boundaries between statistical and deep learning approaches.
- Machine Learning:Gradient-boosted trees and random forests dominate structured data applications with interpretable feature importance. Random forests trained on fundamental factors remain standard for equity long-short funds in London and New York seeking defensible investment processes.
- Natural Language Processing:Transformer architectures parse central bank communications, earnings transcripts, and regulatory filings for sentiment extraction. Funds in Washington DC and Frankfurt deploy these to anticipate policy-induced volatility before price adjustments.
- Neural Networks:Feedforward and recurrent architectures for pattern recognition in time-series data. Japanese quantitative houses in Tokyo apply LSTM networks to foreign exchange microstructure prediction.
- Deep Learning:Multi-layer architectures requiring GPU clusters for training on petabyte-scale alternative datasets. Silicon Valley hedge funds and Shanghai quantitative teams lead deployment for image-based satellite analysis and audio sentiment extraction.
Machine Learning anchors the volume base while Deep Learning climbs the fastest despite infrastructure barriers.
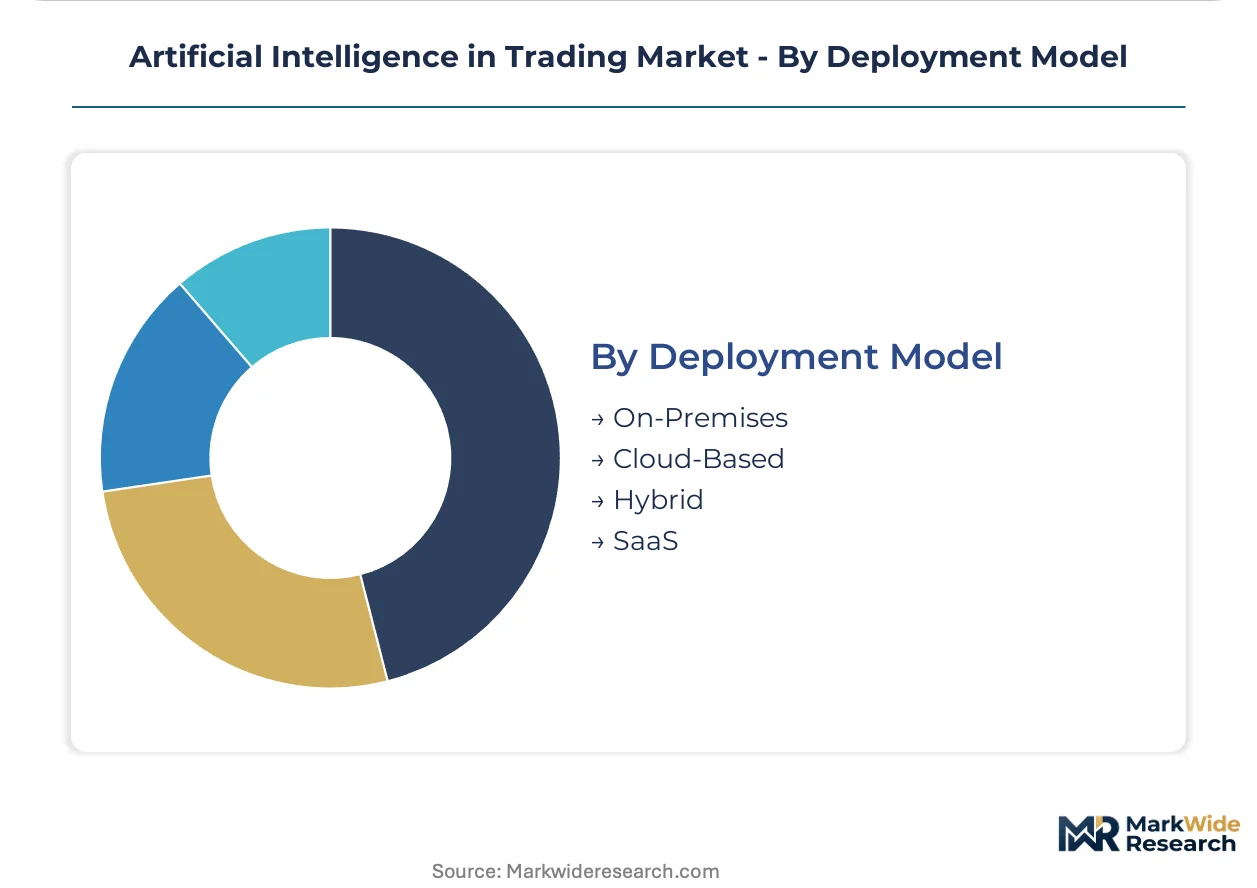
Deployment Model:
Latency requirements and data sovereignty concerns drive divergent infrastructure commitments across user profiles.
- On-Premises:Dedicated hardware in exchange co-location facilities or private data centers. High-frequency traders in Mahwah and Cermak maintain these deployments for deterministic latency despite capital intensity.
- Cloud-Based:Elastic compute on financial services-specialized cloud regions with proximity to matching engines. Asset managers in Chicago and Toronto migrate here as network latency differentials compress below 50 microseconds.
- Hybrid:Sensitive model training on private infrastructure with inference distributed to cloud edge nodes. European funds under GDPR and EU AI Act constraints favor this architecture for data residency compliance.
- SaaS:Fully managed platforms with strategy builders and pre-trained models accessible via web interfaces. Registered investment advisors across Texas and Florida adopt these for cost-efficient systematic exposure.
On-Premises anchors the volume base while Cloud-Based deployment shows the steepest expansion trajectory among mid-size systematic managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CME Group's Aurora data center in Illinois anchors North American trading infrastructure, while the London Stock Exchange's Turquoise platform underwrites European liquidity aggregation. Submarine cable landings at Virginia Beach and Bude, Cornwall compress transatlantic latency windows for cross-border arbitrage strategies.
United States
SEC examination readiness and fiduciary documentation requirements drive demand for explainable AI architectures among Boston and San Francisco asset managers. FINRA's model governance sweep examinations mandate granular backtesting protocols and decision audit trails. The Chicago-Mahwah corridor maintains dedicated co-location facilities where proprietary trading firms deploy reinforcement learning agents for microsecond execution advantages.
United Kingdom
FCA supervisory scrutiny of algorithmic trading conduct rules compels London hedge funds to embed circuit-breakers and human oversight interfaces. The EU AI Act's extraterritorial reach affects UK-domiciled funds accessing European venues through equivalence arrangements. The Square Mile and Canary Wharf clusters host systematic managers hybridizing transformer-based NLP with execution algorithms for earnings call sentiment extraction.
Germany
BaFin's high-frequency trading licensing requirements and market abuse surveillance obligations shape vendor selection toward transparent model architectures. Deutsche Börse's proximity hosting services in Frankfurt attract latency-sensitive systematic strategies from quantitative funds. The Rhine-Main metropolitan region concentrates compliance engineering investment as continental managers absorb EU AI Act implementation costs.
Singapore
MAS technology risk management guidelines and sandbox licensing frameworks encourage cloud-native AI trading platform deployment among regional wealth managers. The Equinix SG1 facility and submarine cable landings at Tanah Merah compress Asia-Pacific latency differentials. The Marina Bay financial district hosts family offices adopting machine learning for multi-asset portfolio optimization across ASEAN equity markets.
India
SEBI's algorithmic trading audit trail mandates and co-location fee structures democratize systematic strategy access for domestic brokerages. The National Stock Exchange's colocation facility in Mumbai and BSE's infrastructure support retail-facing robo-advisory proliferation. Bangalore's technology corridor supplies quantitative engineering talent to global hedge funds establishing captive development centers.
Artificial Intelligence in Trading Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying inference hardware and data infrastructure. The vendor base stratifies between full-stack execution platforms and point-solution providers for sentiment analysis or risk modeling. Three archetypes dominate: cloud hyperscalers distributing through financial services verticals, GPU hardware suppliers capturing training compute margins, and alternative data aggregators monetizing proprietary signal streams. Competitive dynamics center on strategic partnerships between infrastructure and application layers, alongside vertical integration moves to capture data-model-execution value chains.
Within the infrastructure tier, NVIDIA and Microsoft exemplify contrasting approaches to market positioning. NVIDIA's dominance in training hardware creates single-source vulnerability that competitors exploit through specialized inference chips. Microsoft anchors enterprise distribution through Azure's financial services cloud, leveraging existing institutional relationships to displace on-premises installations. Palantir occupies a distinct position serving government-adjacent data architectures to institutional clients seeking alternative dataset integration. These three companies collectively represent the hardware, cloud, and data integration vectors shaping procurement decisions among systematic managers.
| Leading Market Players |
|---|
| MLQ.ai |
| Kavout |
| Precision Alpha |
| Trade Ideas |
| Numerai |
| Palantir |
| NVIDIA |
| Alphabet Inc. |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
NVIDIA's chokehold on GPU training hardware concentrates upstream margin capture in Santa Clara, while downstream pricing power fragments across cloud hyperscalers, boutique AI vendors, and institutional clients negotiating volume discounts. This asymmetry forces systematic trading platforms to absorb hardware cost inflation through SaaS-tiered subscription models rather than pass-through pricing.
Pricing Analysis
The EU AI Act dictates the pricing tier structure by mandating explainable AI architectures that audit decision trails, forcing vendors to embed compliance engineering costs into premium service tiers. Pricing stratifies across enterprise-grade platforms with embedded regulatory documentation, mid-market solutions with standardized model governance, and entry-level SaaS tools for retail-facing robo-advisory. Cost compression in the mid-tier is intensifying because GPU supply constraints extend lead times during demand surges, squeezing vendor margins. Retail brokerages in India and Brazil exhibit highest price sensitivity, while Greenwich hedge funds prioritize signal alpha over subscription costs.
Supply Chain Analysis
Extended payment terms from cloud hyperscalers now anchor supplier financing for AI trading infrastructure vendors, compressing working capital cycles for component specialists. Hardware fabrication concentrates in Taiwan and South Korea, with final assembly and cloud provisioning centered in Virginia and Texas. The supply chain draws from NVIDIA's GPU silicon, high-bandwidth memory modules from SK Hynix, and specialized networking gear from Arista. Single-source vulnerability in training hardware creates structural risk if export controls tighten. Distribution runs through financial services cloud regions on Azure, AWS, and GCP, with hybrid deployments growing among EU funds facing data residency mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial intelligence in trading market represents a high-growth disruption as transformer-based NLP converges with execution algorithms, while the EU AI Act's risk-tier framework restructures competitive economics around compliance engineering.
For Market Incumbents: Harden model governance documentation to withstand FINRA examination scrutiny, embedding granular backtesting protocols and decision audit trails that satisfy supervisory review. Deepen backward integration into alternative data sourcing through exclusive satellite imagery partnerships or credit card aggregate licensing, reducing exposure to escalating third-party subscription costs. Priority lever: captive supply of proprietary signal streams that decay more slowly than commoditized price-volume factors. For New Entrants and Emerging Players: India's SEBI-regulated retail brokerage market represents the most penetrable entry point, where dematerialized account growth and co-location fee democratization create whitespace for mobile-first robo-advisory platforms. Reinforcement learning convergence with central bank NLP parsing offers a second white-space target among Washington DC and Frankfurt funds seeking policy-induced volatility anticipation. Go-to-market angle: cloud-native distribution through regional wealth manager partnerships rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with embedded regulatory compliance architectures that satisfy EU AI Act mandates without Anglo-American competitors' cost absorption. Long-term viability hinges on data-model-execution integration that captures value chain margin rather than point-solution commoditization. Signal to watch: consolidation velocity among mid-size systematic managers seeking unified platforms over fragmented best-of-breed stacks.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Architecture Investment | EU AI Act compliance mandates embed audit trails that defend against supervisory scrutiny in Frankfurt and London venues. |
| Alternative Data Licensing Partnership | Exclusive satellite imagery or credit card aggregate access extends signal half-life beyond commoditized price-volume factors. |
| Cloud-Native Platform Integration | Azure and AWS financial services regions reduce client infrastructure overhead while capturing mid-size asset manager procurement. |
| Regulatory Sandbox Certification | MAS and SEBI sandbox frameworks accelerate retail-facing robo-advisory deployment across Singapore and Mumbai markets. |
| GPU Supply Diversification | AMD and specialized inference chip adoption mitigates NVIDIA single-source vulnerability in model development pipelines. |
Methodological Framework
Initial hypotheses were tested against primary input from quantitative researchers at Greenwich hedge funds, compliance officers at Boston asset managers, cloud procurement leads at Chicago systematic shops, and SEBI-regulated brokerage technology heads in Mumbai, then refined through secondary validation. SEC examination guidelines, EU AI Act implementation drafts, FINRA model governance notices, and hyperscaler financial services cloud disclosures anchored quantitative triangulation. Bottom-up vendor revenue estimates and top-down capital markets technology spend allocations were reconciled across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling deployment model transitions, solution type procurement cycles, end-user sophistication tiers, and regional regulatory cluster adoption patterns. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included GPU supply lead time dynamics, alternative data licensing cost trajectories, and cloud latency compression curves affecting co-location versus distributed execution economics.
Practitioners should monitor EU AI Act enforcement intensity, NVIDIA supply allocation shifts, and alternative data provider consolidation for early signals of forecast deviation. The analysis reflects assumptions about regulatory implementation timelines, hardware supply normalization, and cloud adoption velocity. Macroeconomic liquidity contraction, geopolitical export control expansion, or breakthrough quantum computing advancement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market