
 Nigeria Data Center Power Market | 2026-2036
Nigeria Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Data Center Power Market Insights
Project finance and power purchase agreements is tilting competitive dynamics toward operators with long-term offtake contracts. Schneider Electric SE leverages its integrated electrical infrastructure portfolio to anchor large-scale deployments. Cummins Inc. sustains generator set supply relationships with build-to-suit developers. Vertiv Group Corp. differentiates through thermal management tied to power density requirements.
Nigeria data center power encompasses electrical infrastructure engineered to deliver conditioned, uninterrupted electricity with specified availability tiers, typically incorporating diesel rotary uninterruptible power supply systems, battery energy storage, and automatic transfer switches rated for sub-cycle switching. This infrastructure ensures continuous operations for server racks, storage arrays, and network equipment where downtime carries quantified financial penalties. Generators dominate capital allocation given grid reliability constraints, while uninterruptible power supply systems command attention for bridging startup intervals. Cloud services application segment leads deployment scale as hyperscale and local operators expand capacity.
Nigeria's central bank prudential guidelines on electronic banking infrastructure and the Nigerian Communications Commission data center licensing framework shape equipment redundancy standards and facility certification requirements. The country's national electricity regulator mandates backup power provisions for critical infrastructure, directly influencing generator sizing and fuel storage specifications. Stakeholders must monitor how diesel cost volatility and renewable hybrid pilot programs reshape total cost of ownership calculations for power architecture decisions.
Market Dynamics
Grid instability across Nigerian urban centers is forcing data center operators to overbuild generator capacity and fuel storage beyond Tier III baseline requirements, creating capital allocation distortions that favor established players with project finance access.
Growth Catalysts
- NITDA Data Localization Mandate:Nigeria's National Information Technology Development Agency guidelines compel financial institutions and government agencies to host data within national borders, directly stimulating certified facility construction with redundant power architectures.
- Submarine Cable Landings:Lagos hosts multiple international submarine cable termination points including MainOne and Glo-1, concentrating enterprise demand and justifying hyperscale power infrastructure investments in the metropolitan corridor.
- CBN Electronic Banking Guidelines:Nigeria's central bank prudential standards mandate uninterrupted power for core banking infrastructure, elevating generator and UPS specifications for Tier III certification compliance.
Market Restraints
- Diesel Price Volatility:Generator-dependent operators face margin compression from fluctuating automotive gas oil costs, which constitute 35-45% of operational expenditure for facilities running 18-20 hours daily on backup systems.
- Grid Reliability Deficits:Nigerian Electricity Regulatory Commission data indicates average grid availability below 40% in major urban centers, forcing excessive capital deployment into redundant power stacks that strain project returns.
- Skilled Technician Scarcity:Certified power systems engineers capable of maintaining rotary UPS and paralleling switchgear remain concentrated in Lagos and Abuja, constraining facility expansion into secondary markets.
Strategic Opportunities
- Solar-Diesel Hybrid Pilots:NERC renewable integration frameworks enable behind-the-meter solar plus battery configurations that reduce generator runtime and diesel logistics exposure for edge facilities.
- Kano-Kaduna Corridor:Northern Nigeria's underserved enterprise base presents first-mover potential for modular data centers with containerized power systems targeting agricultural commodity trading platforms.
- Build-to-Suit Leasing Models:Power infrastructure as a service arrangements allow operators to monetize electrical assets separately from white space, attracting capital from infrastructure funds seeking yield-bearing energy assets.
Industry Challenges
- Tier Certification Timelines:Uptime Institute and TIA-942 certification processes for Nigerian facilities face 8-14 month delays due to auditor availability and documentation gaps, extending revenue recognition timelines.
- Fuel Supply Chain Security:Diesel storage regulations from the Department of Petroleum Resources mandate on-site reserves exceeding 48 hours, requiring capital-intensive tank farms and complicating site selection in dense urban zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Data Center Power Market |
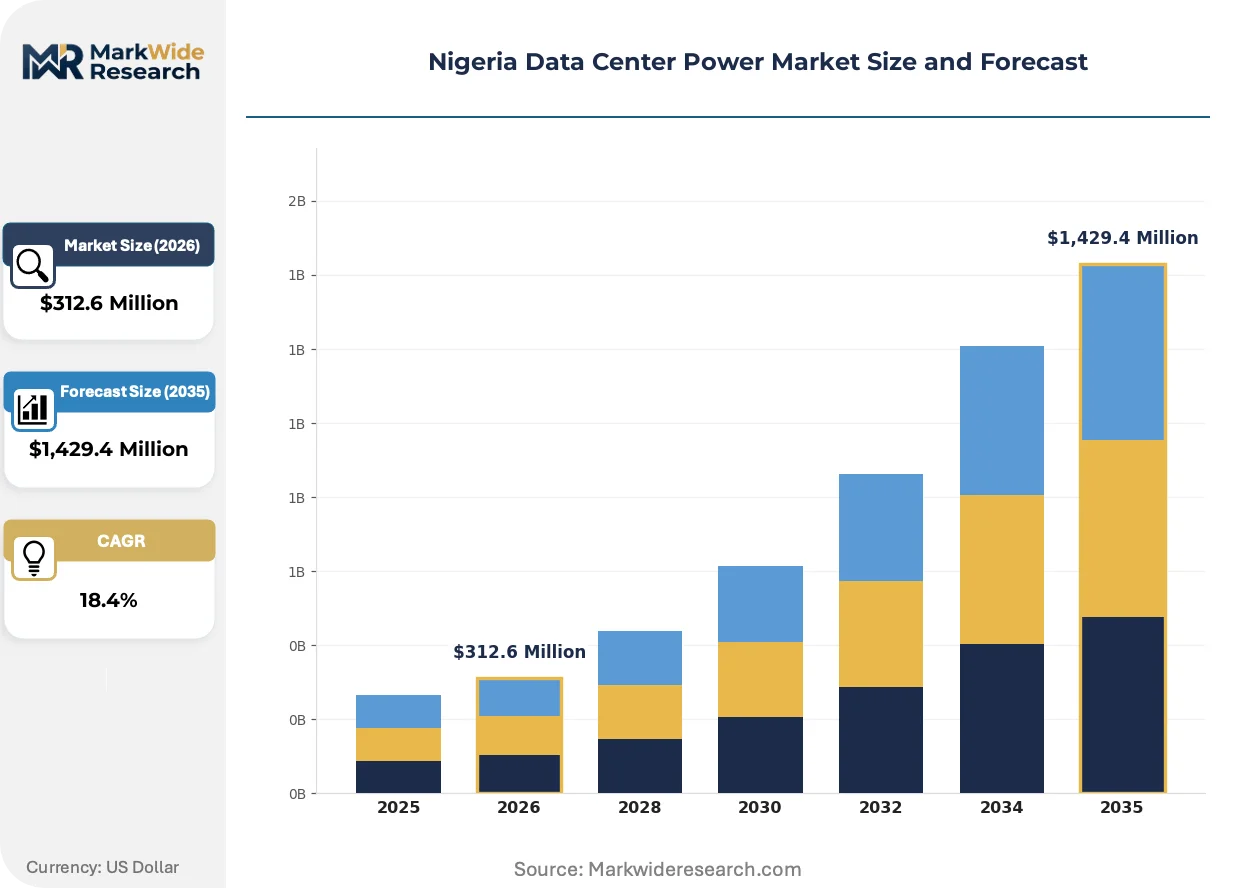
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,429.4 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uninterruptible Power Supply, Generators, Power Distribution Units, Cooling Systems Technology: Cloud Computing, Edge Computing, Virtualization, High-Performance Computing Application: Cloud Services, Data Storage, Disaster Recovery, Colocation End User: Telecommunications, Financial Services, E-Commerce, Healthcare |
| Companies Covered | ABB Ltd, Schneider Electric SE, Vertiv Group Corp., Eaton Corp. plc, Caterpillar Inc., Cummins Inc., Rolls-Royce PLC, Legrand Group, Rittal GmbH and Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Data Center Power Market Trends and Innovations
Intelligent power management systems are compressing operational decision cycles for Nigerian operators managing multi-source electrical architectures. Three developments are restructuring competitive requirements.
Lithium-ion battery energy storage systems are digitizing backup power orchestration for Lagos-based hyperscale facilities. Local cloud operators deploying 500kW+ modular UPS configurations now sequence generator startup and battery discharge through centralized software platforms. This convergence is digitizing maintenance scheduling and load forecasting, reducing human intervention in failover events.
Nigerian Communications Commission data center licensing frameworks now embed power redundancy specifications into operating permits. The 2023 licensing circular mandates dual-feed electrical paths and N+1 generator configurations for Tier II facilities and above. Financial services deployments in Victoria Island and Lekki are absorbing compliance costs fastest, converting certification into competitive differentiation.
Power purchase agreements with embedded generation developers are displacing captive diesel ownership among enterprise colocation customers. Large banking and fintech tenants now procure conditioned power as a metered utility rather than capitalizing generator assets. This preference shift concentrates in Lagos Island and Ikoyi districts where land scarcity prevents on-site fuel storage expansion.
Nigeria Data Center Power Market Segmentation
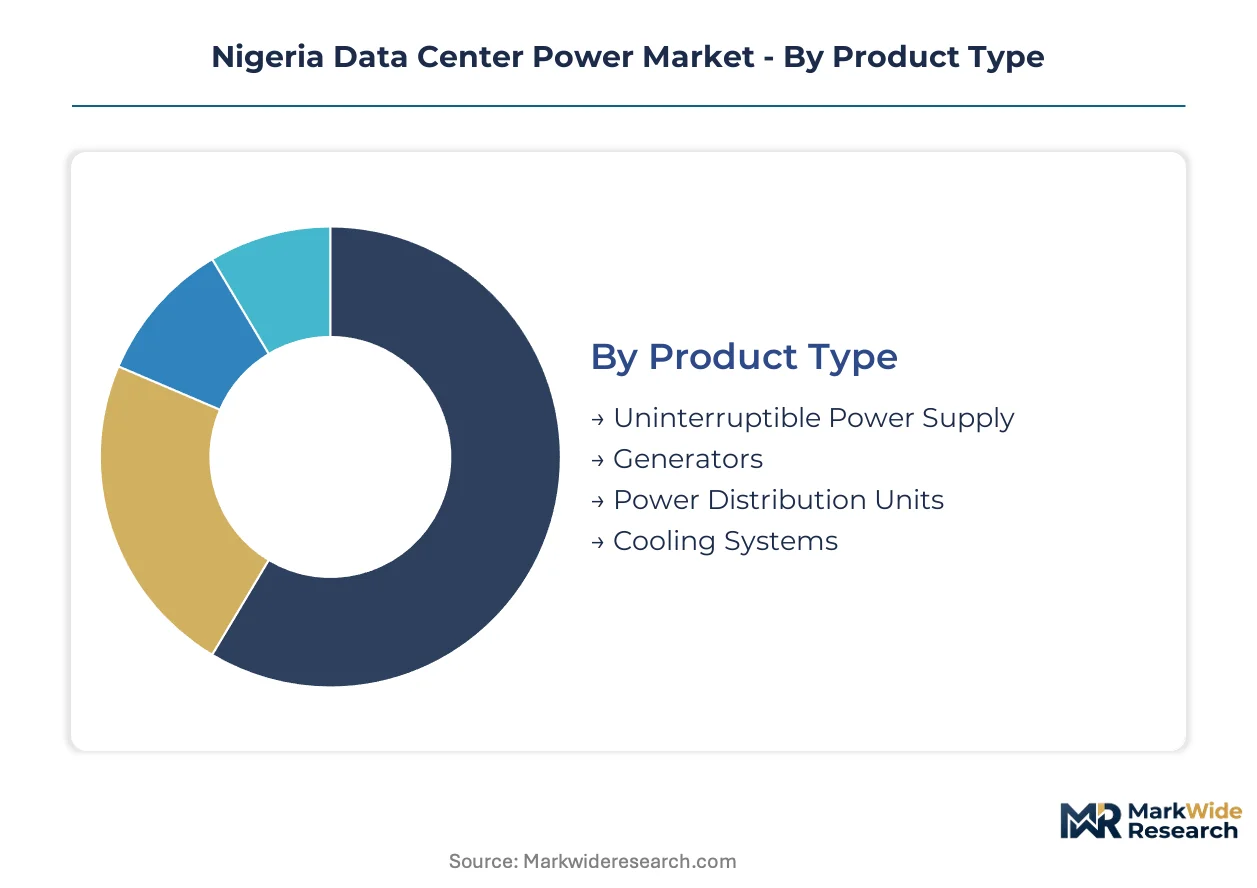
Power infrastructure procurement in Nigeria's data center sector fragments across equipment categories, deployment models, and customer verticals. Each segment carries distinct service requirements, certification standards, and financing structures that shape vendor engagement models.
Product Type:
After-sales service intensity varies dramatically across electrical infrastructure categories, with rotating equipment demanding dedicated technician contracts and battery systems requiring predictive replacement programs.
- Uninterruptible Power Supply:Battery energy storage and rotary UPS configurations bridge generator startup intervals during grid failures. Lagos-based hyperscale facilities prioritize lithium-ion systems with 10-15 minute autonomy windows for controlled shutdown sequencing. Schneider Electric and Vertiv dominate service contract penetration in Victoria Island clusters.
- Generators:Diesel and gas-powered generator sets constitute the capital backbone of Nigerian data center power architecture, sized for 100% load carry during extended grid outages. Fuel logistics and preventive maintenance contracts concentrate vendor relationships with Cummins and MTU Onsite Energy for Tier III facilities in Lekki and Ikoyi.
- Power Distribution Units:Rack-level and floor-mounted PDUs manage conditioned power delivery to server loads with remote monitoring capabilities.
- Cooling Systems:Precision air conditioning and chilled water infrastructure dissipates heat from dense compute environments, with thermal management increasingly integrated into power orchestration platforms.
Generators hold the largest share; momentum sits with UPS systems as battery costs decline and runtime requirements compress.
Technology:
Deployment architecture determines power density requirements, with edge configurations favoring containerized electrical packages against hyperscale demands for modular substations.
- Cloud Computing:Hyperscale and local cloud operators drive the highest power density requirements, with Lagos facilities deploying 10-15MW blocks demanding N+1 generator redundancy and dual-feed utility paths. MainOne and Glo-1 cable landings anchor demand concentration in metropolitan corridors.
- Edge Computing:Distributed micro-data centers across Kano, Port Harcourt, and Abuja prioritize rapid-deployment containerized power systems with 48-hour fuel autonomy. Agricultural trading platforms and retail banking branches absorb modular UPS and generator skid configurations.
- Virtualization:Software-defined infrastructure consolidates compute loads, reducing per-rack power variance but increasing aggregate facility demand predictability.
- High-Performance Computing:GPU-intensive workloads for fintech analytics and oil reservoir modeling push rack densities above 30kW, demanding liquid cooling integration with power delivery.
Cloud computing dominates deployment scale; edge computing gains share fastest as NITDA localization mandates extend beyond Lagos.
Application:
Service level agreements and uptime penalties vary by workload criticality, with financial transaction processing commanding the most stringent power availability terms.
- Cloud Services:Public and private cloud infrastructure requires Tier III certification minimum, with CBN electronic banking guidelines mandating uninterrupted power for core banking platforms hosted in certified facilities. Tier certification timelines of 8-14 months extend revenue recognition for power infrastructure investments.
- Data Storage:Archive and primary storage arrays tolerate brief power transitions but demand conditioned voltage for disk integrity, favoring online double-conversion UPS topologies.
- Disaster Recovery:Secondary site requirements under NITDA guidelines stimulate redundant facility construction with mirrored power architectures, often in secondary cities to satisfy geographic separation mandates.
- Colocation:Multi-tenant facilities amortize power infrastructure across diverse customer loads, with metered power agreements displacing captive generator ownership among enterprise tenants.
Cloud services command the largest facility footprint; disaster recovery shows steepest expansion trajectory as regulatory compliance tightens.
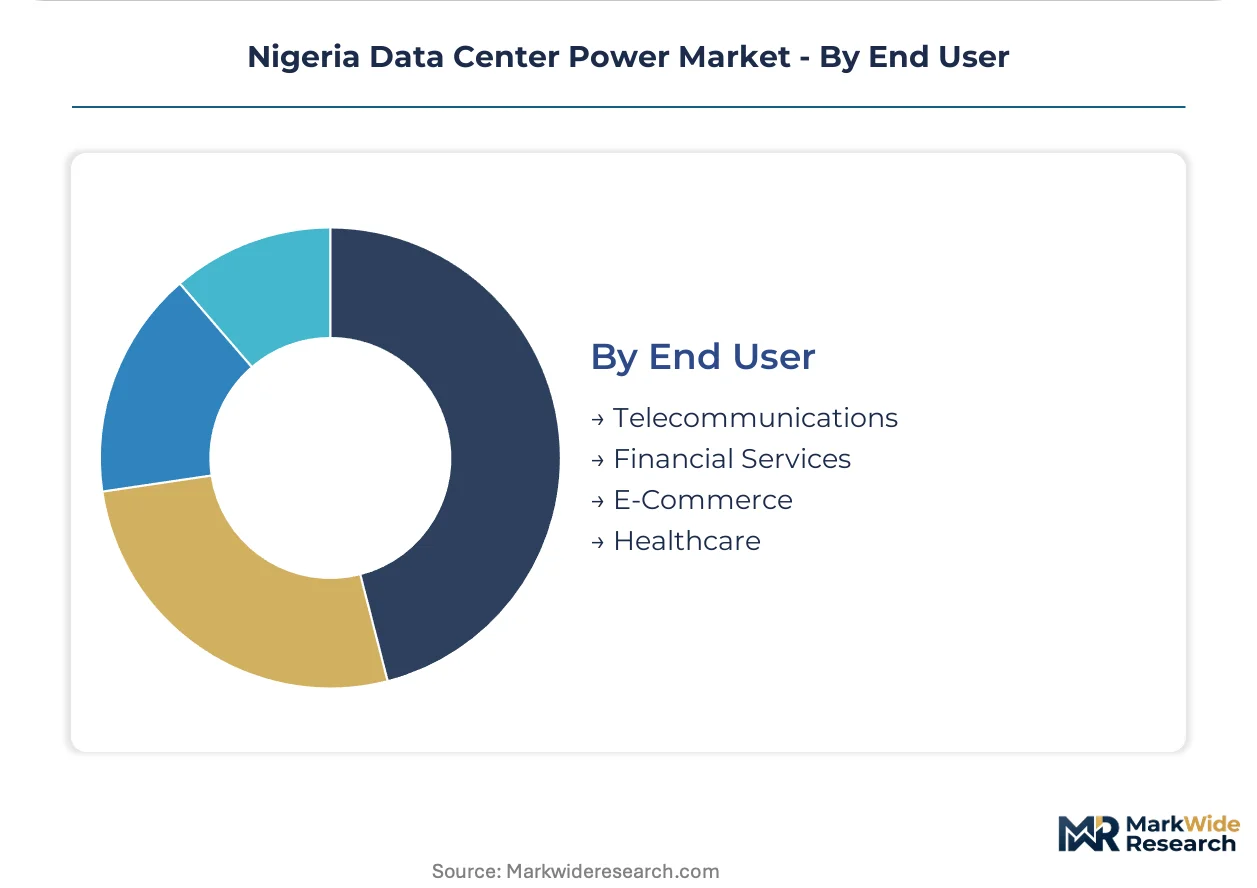
End User:
Vertical-specific risk tolerance and regulatory exposure shape power redundancy investment, with financial penalties for downtime varying by sector.
- Telecommunications:Mobile network operators and internet exchange points require 99.999% availability for signaling infrastructure, with MTN and Airtel data centers in Lagos deploying 2N power architectures. Nigerian Communications Commission licensing frameworks embed generator and UPS specifications into operating permits.
- Financial Services:Commercial banks, fintech platforms, and payment processors face CBN prudential standards mandating uninterrupted power for electronic banking infrastructure. Tier III certification compliance costs concentrate in Victoria Island and Ikoyi districts where land scarcity prevents fuel storage expansion.
- E-Commerce:Online retail platforms and logistics aggregators prioritize power reliability for transaction processing during peak demand windows.
- Healthcare:Hospital information systems and health insurance platforms require power continuity for patient data integrity under emerging data protection frameworks.
Financial services absorb the highest per-megawatt power infrastructure investment; e-commerce is climbing the fastest as digital payment penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services institutions and cloud operators concentrate procurement decisions in specific Nigerian metropolitan corridors, with submarine cable landings and regulatory mandates dictating facility placement.
Lagos
MainOne and Glo-1 submarine cable terminations anchor Nigeria's densest data center cluster, with Victoria Island and Ikoyi districts absorbing Tier III-certified facilities. Nigerian Communications Commission licensing frameworks mandate dual-feed power paths for operating permits in this corridor. Hyperscale operators deploy 10-15MW power blocks with N+1 generator redundancy to serve banking and fintech tenants.
Abuja
Federal government data localization requirements under NITDA guidelines stimulate certified facility construction in the Federal Capital Territory. Central bank prudential standards for electronic banking infrastructure elevate generator and UPS specifications for disaster recovery sites. Jabi and Maitama districts concentrate enterprise colocation investments targeting public sector contracts.
Kano
Agricultural commodity trading platforms and Islamic banking institutions drive demand for edge data centers in northern Nigeria's commercial capital. Diesel logistics constraints favor solar-diesel hybrid pilots under NERC renewable integration frameworks. Dawanau and Sabon Gari industrial zones attract modular power system deployments with 48-hour fuel autonomy specifications.
Port Harcourt
Oil and gas sector data residency requirements stimulate facility construction in Rivers State's energy hub. International oil company IT infrastructure mandates push operators toward Tier II certification minimums with rotary UPS configurations. Trans Amadi industrial layout hosts containerized power systems targeting upstream exploration data processing.
Ibadan
Secondary city positioning offers geographic separation for disaster recovery architectures under NITDA guidelines. Lower land costs enable compliant fuel storage expansion beyond Lagos constraints. Ring Road and Moniya industrial corridors attract build-to-suit developers offering power infrastructure as a service to southwestern enterprises.
Nigeria Data Center Power Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Nigeria's data center power market, creating a tiered structure where integrated electrical infrastructure vendors hold procurement influence over standalone equipment suppliers. The competitive terrain segments into three archetypes: full-stack power infrastructure integrators, rotating equipment specialists, and thermal-electrical convergence providers. Capacity expansion into Lagos hyperscale corridors and strategic partnerships with build-to-suit developers represent the dominant competitive moves reshaping vendor positioning.
Within the integrated infrastructure tier, Schneider Electric SE and Vertiv Group Corp. exemplify channel-controlling strategies that bundle electrical distribution with thermal management. Cummins Inc. occupies a specialist position anchored in generator set supply relationships with Tier III facility developers. These three companies represent distinct archetypes: the French-headquartered conglomerate with end-to-end data center infrastructure portfolios, the American power and cooling convergence specialist, and the American engine manufacturer with deep relationships in Nigerian diesel generator deployment.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corp. plc |
| Caterpillar Inc. |
| Cummins Inc. |
| Rolls-Royce PLC |
| Legrand Group |
| Rittal GmbH and Co. KG |
| Others |
Pricing and Supply Chain Analysis
Diesel price volatility exposure determines both pricing tier spreads and supply chain shape across Nigeria's data center power market. Generator-dependent operators absorb automotive gas oil indexation clauses that compress margins for facilities without long-term offtake contracts, while fuel logistics constraints force capital-intensive tank farm investments that reshape site selection economics.
Pricing Analysis
Cost-plus contracts with automotive gas oil indexation dominate procurement structures for Nigerian data center operators. Pricing stratifies across Tier III-certified facilities, Tier II-compliant installations, and uncertified edge deployments, with certification grade and generator redundancy level driving differentiation. Cost compression in the uncertified tier intensifies because diesel logistics absorb disproportionate operational expenditure. Cloud services and financial services tenants show least price sensitivity, while agricultural trading platforms and retail banking branches exhibit highest elasticity.
Supply Chain Analysis
Upstream diesel feedstock and lithium-ion battery cell production anchor supply dependencies for Nigerian data center power infrastructure. Generator sets draw from manufacturing concentrations in the United States, Germany, and China, while battery energy storage systems source from South Korea and Japan. Diesel supply hinges on Nigerian petroleum product import infrastructure and Department of Petroleum Resources storage mandates. Single-source vulnerability concentrates in rotary UPS switchgear and paralleling controls. Distribution runs through Lagos-based electrical infrastructure distributors with direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's data center power market sits in a cyclical upswing driven by NITDA data localization mandates compelling certified facility construction. Infrastructure funds and strategic operators should position before Tier III certification scarcity hardens competitive moats.
For Market Incumbents: Harden generator service contract penetration in Victoria Island and Ikoyi corridors to lock out modular competitors. Secure exclusive relationships with build-to-suit developers before captive power purchase agreements displace equipment ownership models. Diesel cost pass-through mechanisms and fuel logistics integration represent the critical defensive lever against solar-diesel hybrid entrants. For New Entrants and Emerging Players: Northern Nigeria's Kano-Kaduna corridor with its underserved agricultural commodity trading platforms represents the most penetrable entry point for containerized power systems. Solar-diesel hybrid configurations under NERC renewable integration frameworks offer regulatory-aligned differentiation against incumbent diesel-only architectures. Target first-mover positioning with 48-hour fuel autonomy specifications before established players extend generator service networks. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors power infrastructure as a service platforms over captive equipment ownership models. Long-term viability rests on monetizing electrical assets separately from white space through yield-bearing energy structures. Watch diesel-automotive gas oil price spreads as the inflection signal for hybrid technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Enables infrastructure funds to acquire yield-bearing energy assets separate from facility operations. |
| Tier III Certification Investment | Nigerian Communications Commission licensing mandates embed N+1 generator specifications into operating permits. |
| Solar-Diesel Hybrid Deployment | NERC renewable integration frameworks reduce generator runtime exposure for edge facilities in secondary cities. |
| Generator Service Contract Expansion | Cummins and MTU Onsite Energy relationships anchor recurring revenue in Lagos hyperscale corridors. |
| Build-to-Suit Developer Partnership | Schneider Electric and Vertiv bundle electrical infrastructure with thermal management for integrated deployments. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with data center operators, generator service technicians, and Nigerian Communications Commission licensing officers; and secondary validation through NERC regulatory filings, CBN prudential guidelines, submarine cable landing documentation, and vendor technical specifications. Facility development databases and diesel logistics operator records provided installation and operational cost benchmarks. Bottom-up facility counts triangulated against top-down power infrastructure procurement estimates.
Forecast inputs considered equipment category deployment rates, certification tier adoption curves, and regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, application workload criticality, and end-user vertical. CAGRs derived from facility pipeline analysis and power density requirements per megawatt installed. Diesel price trajectory assumptions and renewable hybrid pilot scalability informed scenario-weighted outputs.
Macroeconomic conditions sit as an overlay; deviation in naira exchange rates, automotive gas oil import costs, or central bank monetary policy would shift the trajectory. Forecasts reflect documented assumptions regarding grid reliability deficits and NITDA enforcement consistency. Cross-checking against Uptime Institute certification databases and NERC renewable integration filing rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Ireland Data Center Market